
 Gunshot Injuries Treatment Market | 2026-2036
Gunshot Injuries Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Gunshot Injuries Treatment Market Outlook
Military Medical Units is collapsing the traditional hospital-centric procurement model for gunshot injury products. Stryker Corporation leverages its orthopedic trauma portfolio to dominate battlefield-adapted surgical kits. Zhejiang Haichuang Medical Device Co., Ltd. anchors cost-efficient wound dressing production for emerging defense budgets. RevMedx specializes in hemostatic device innovation that competes directly with conventional gauze protocols.
Gunshot injuries treatment encompasses immediate hemorrhage control, surgical intervention, infection prevention, and long-term rehabilitation of ballistic trauma wounds, typically requiring hemostatic agents with clot activation times under three minutes. The primary purpose spans civilian emergency departments, military theaters, and tactical law enforcement medicine where delayed intervention elevates mortality. Wound Dressings leads product type revenue due to recurrent battlefield and urban trauma consumption, while Surgical Kits captures premium margins from integrated hemorrhage control systems. Emergency Medicine dominates therapy area demand through Level I trauma center throughput, though Rehabilitation shows structural expansion from rising survival rates requiring post-traumatic functional restoration.
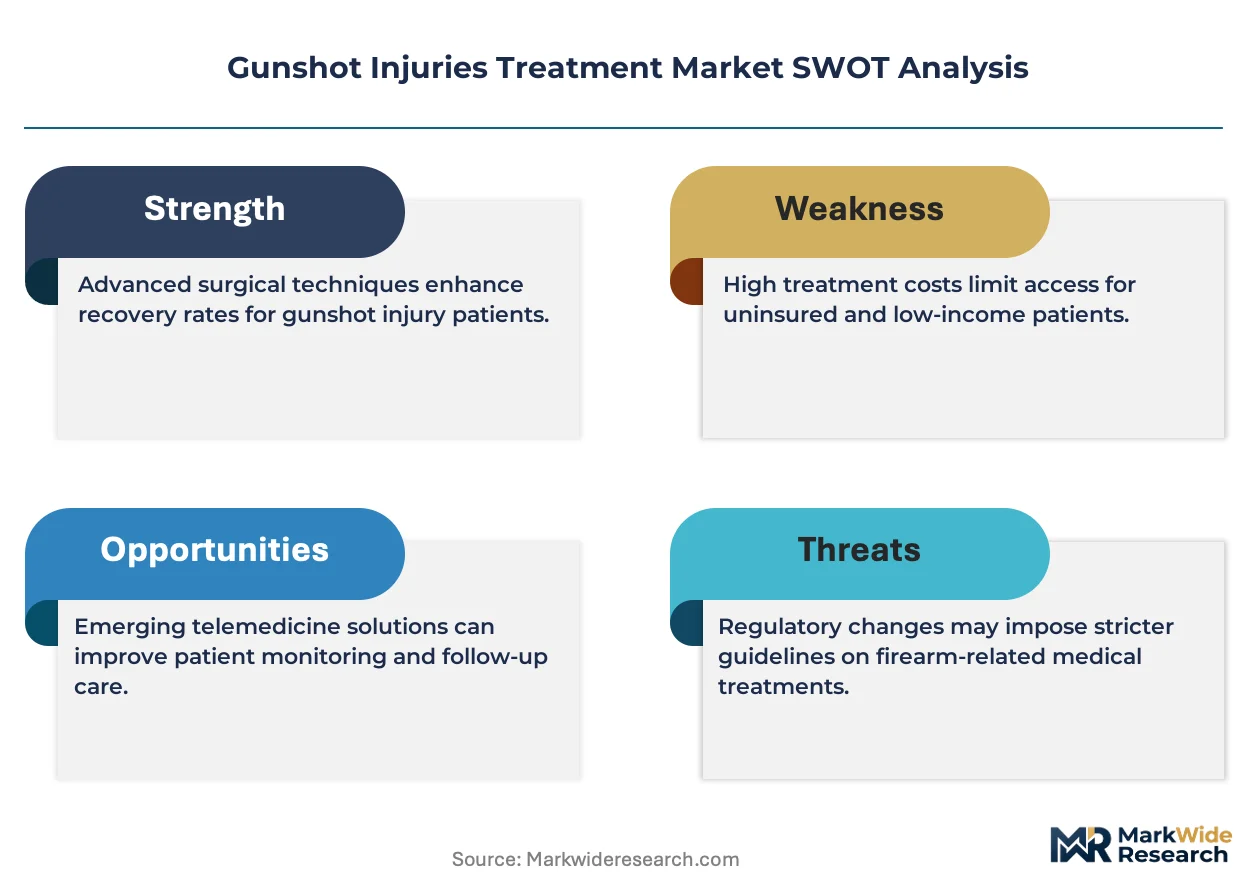
The FDA regulates hemostatic devices as Class II medical devices with 510(k) premarket notification requirements, while the EU MDR imposes stricter clinical evidence standards for implantable trauma products that reshape market access timelines. Military procurement operates under FDA Emergency Use Authorization pathways and NATO standardization agreements that compress validation cycles for deployed forces. Stakeholders must monitor evolving battlefield medicine doctrine and civilian active shooter response protocols to align R&D investment with shifting intervention timelines.
Market Dynamics
The FDA's 21st Century Cures Act framework accelerates breakthrough device designations, compressing validation cycles for hemostatic trauma interventions and reshaping competitive entry timelines across military and civilian procurement channels.
Growth Catalysts
- Expedited FDA Pathways:The 21st Century Cures Act breakthrough device designation compresses premarket review timelines for hemostatic agents, enabling faster deployment of clot-activation technologies under three minutes.
- Military Theater Procurement:NATO standardization agreements for battlefield medicine drive recurrent volume commitments for wound closure systems across deployed medical units.
- Level I Trauma Center Expansion:Urban trauma center throughput requirements in the United States sustain demand for integrated hemorrhage control surgical kits.
Market Restraints
- Chitosan Supply Concentration:Raw material sourcing for advanced hemostatic dressings concentrates in Southeast Asian processing facilities, exposing producers to input volatility.
- EU MDR Clinical Evidence Burden:Stricter post-market surveillance requirements for implantable trauma products extend market access timelines by 18-24 months compared to 510(k) pathways.
- Conventional Gauze Substitution:Low-cost cotton-based protocols retain preference in budget-constrained emergency medical services, limiting premium hemostatic penetration.
Strategic Opportunities
- Tactical Law Enforcement Medicine:Active shooter response protocol standardization across municipal police departments creates demand for portable hemorrhage control kits.
- Rehabilitation Services Integration:Rising survival rates from ballistic trauma expand post-traumatic functional restoration requirements beyond acute care settings.
- India Defense Modernization:Emerging defense budgets in South Asia support cost-efficient wound dressing procurement for military medical infrastructure.
Industry Challenges
- Biocompatibility Certification Complexity:ISO 10993 testing requirements for hemostatic implantables demand 12-18 month validation cycles before regulatory submission.
- Battlefield Doctrine Synchronization:Military medical units require continuous protocol alignment between deployed forces and domestic trauma centers, complicating product configuration standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gunshot Injuries Treatment Market |
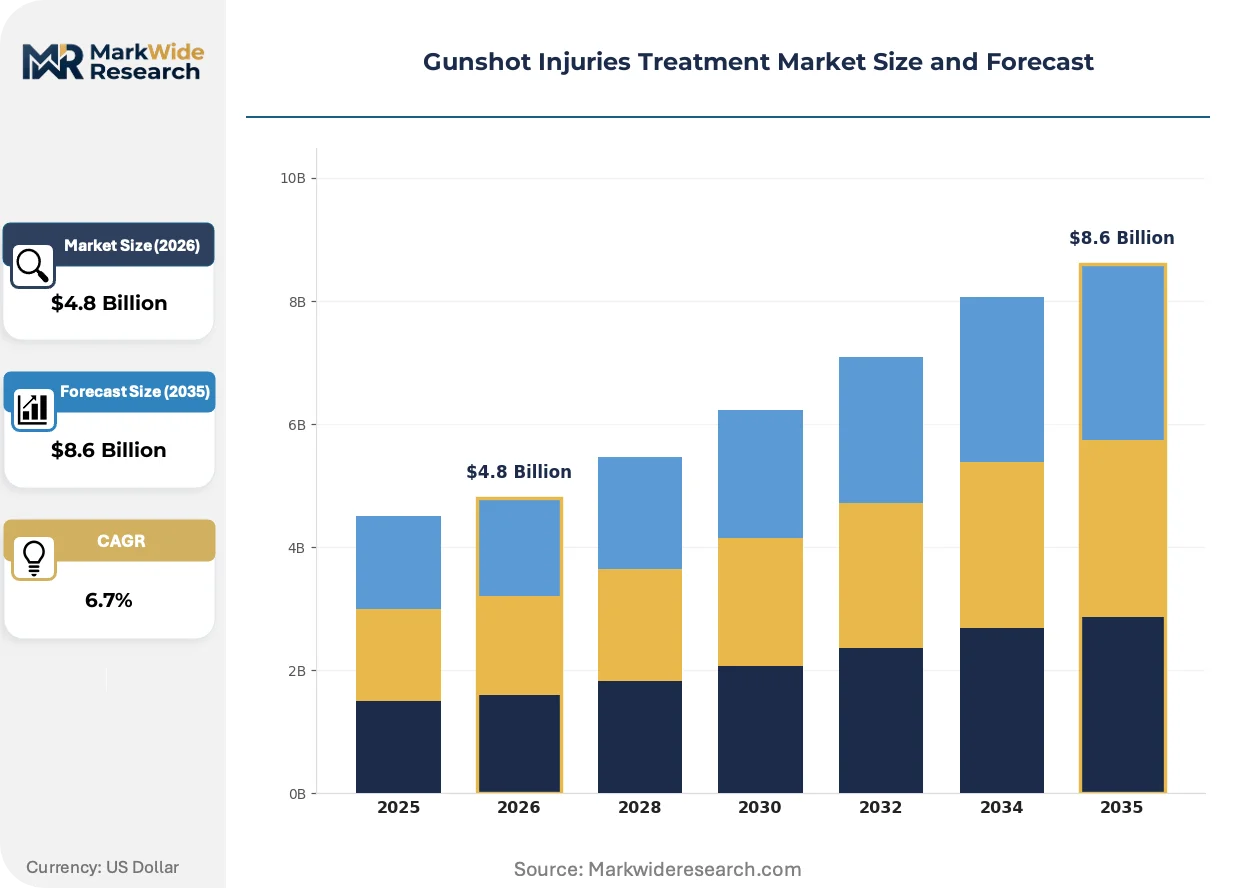
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wound Dressings, Surgical Kits, Antiseptics, Implants Therapy Area: Emergency Medicine, Trauma Care, Pain Management, Rehabilitation End User: Hospitals, Trauma Centers, Outpatient Facilities, Military Medical Units Delivery Mode: Intravenous, Oral, Topical, Surgical |
| Companies Covered | Stryker Corporation, RevMedx, Medtrade Products Ltd, Zhejiang Haichuang Medical Device Co., Ltd., Baxter Healthcare Corporation, RescueMed, TraumaTech, Hemostat Solutions, BioHeal Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gunshot Injuries Treatment Market Strategic Shifts
Trauma intervention technologies are converging around speed-to-clot performance metrics, with regulatory frameworks and procurement models adapting to prioritize hemorrhage control efficacy over incremental cost considerations.
Resorbable hemostatic sponges engineered from oxidized regenerated cellulose deliver active clotting without manual pressure application. Tactical combat casualty care protocols in military medical units adopt these systems for junctional wound sites where tourniquets fail. This material is supplanting layered gauze protocols in pre-hospital settings, compressing intervention training requirements while elevating survival metrics for extremity and torso trauma.
The EU Medical Device Regulation imposes annual safety update reporting and post-market clinical follow-up for implantable trauma products. Manufacturers must maintain European Authorized Representatives and updated technical documentation across product lifecycles. Surgical kit assemblers with CE-marked portfolios face compressed margin structures from notified body audit frequency increases, driving consolidation among mid-tier European suppliers.
Integrated service contracts now bundle device supply with training certification and inventory management for civilian trauma centers. Traditional distributor relationships fragment as hospital systems negotiate direct procurement agreements with hemostatic device manufacturers. This pattern concentrates in the United States, where health system consolidation creates purchasing leverage for standardized wound closure protocols across multi-facility networks.
Gunshot Injuries Treatment Market Segmentation
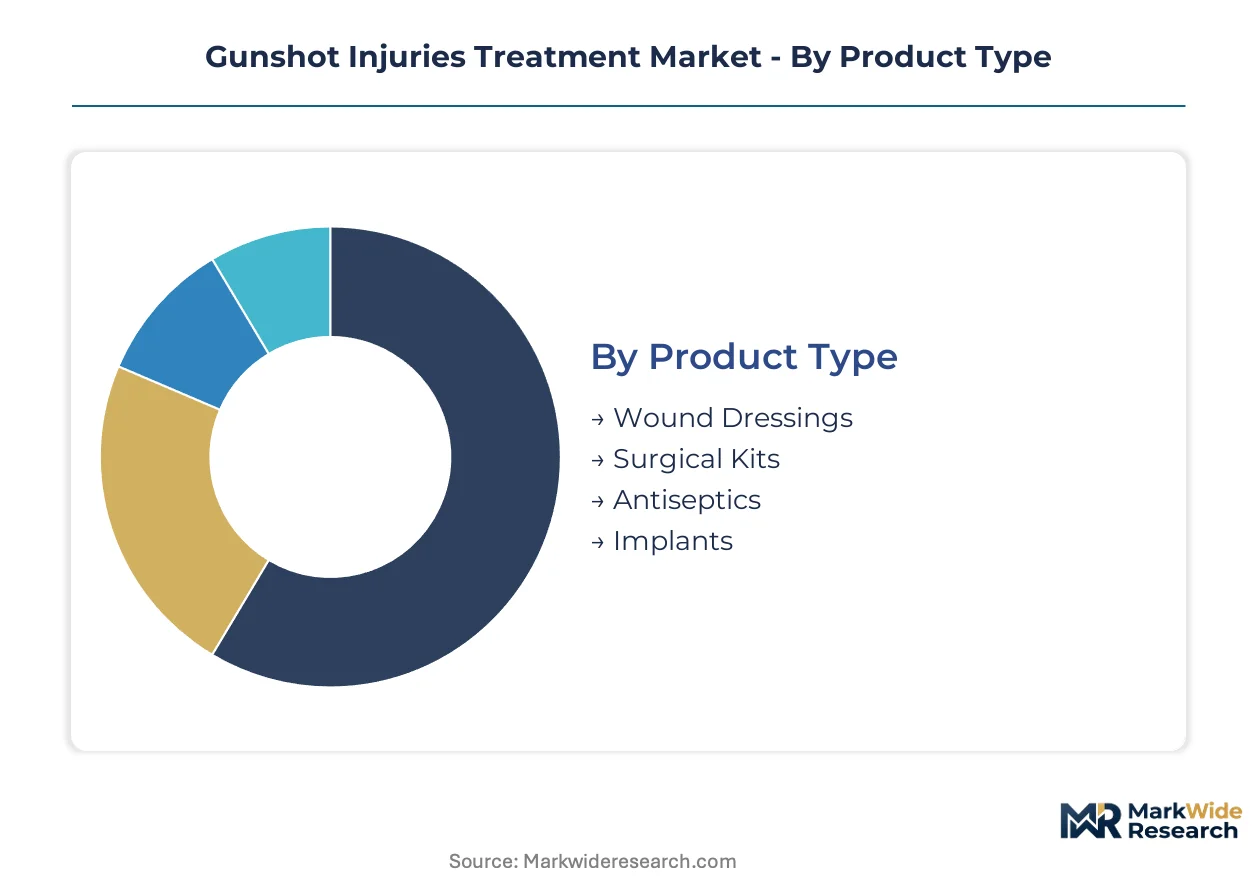
Segmentation in gunshot injuries treatment reveals distinct procurement patterns across military and civilian channels. Each dimension exposes divergent regulatory pathways, pricing tolerances, and technology adoption speeds that reshape competitive positioning.
Product Type:
Wound Dressings concentrate domestic manufacturing in the United States and Western Europe, while Surgical Kits face export-led procurement from NATO defense ministries. Antiseptics flow through global pharmaceutical distributors. Implants remain concentrated in specialized orthopedic device hubs.
- Wound Dressings:Oxidized regenerated cellulose and chitosan-based hemostatic layers activate clotting without manual pressure. Demand clusters in Level I trauma centers across Texas, California, and Florida, driven by urban violence response protocols and mass casualty preparedness mandates.
- Surgical Kits:Integrated hemorrhage control systems bundle tourniquets, hemostatic gauze, and junctional wound devices in standardized configurations. Military Medical Units in the United States, United Kingdom, and Germany drive volume through NATO standardization agreements that compress vendor qualification cycles.
- Antiseptics:Iodine and chlorhexidine formulations for ballistic wound irrigation distribute through hospital pharmacy networks and field medical supplies.
- Implants:Resorbable fixation plates and trauma screws for cranial and facial ballistic reconstruction require ISO 10993 biocompatibility certification before regulatory submission.
Wound Dressings commands the established base. The steepest expansion runs through Surgical Kits.
Therapy Area:
Emergency Medicine absorbs premium pricing for speed-critical interventions. Trauma Care segments across civilian hospital networks and deployed military facilities. Pain Management and Rehabilitation follow distinct reimbursement pathways with longer sales cycles.
- Emergency Medicine:Pre-hospital hemorrhage control and immediate trauma bay interventions prioritize clot-activation speed under three minutes. United States urban trauma centers in Chicago, Philadelphia, and Houston concentrate demand through active shooter response training mandates.
- Trauma Care:Definitive surgical management of ballistic injuries spans damage control surgery through reconstructive phases. Military theater hospitals in Poland and Romania expand capacity under NATO forward medical presence initiatives.
- Pain Management:Regional anesthesia and multimodal analgesia protocols for ballistic trauma integrate into civilian and military treatment algorithms.
- Rehabilitation:Post-traumatic functional restoration for extremity and spinal ballistic injuries extends care episodes beyond acute hospitalization.
Emergency Medicine captures volume leadership. Rehabilitation is climbing the fastest as survival rates from previously fatal wounds improve.
End User:
Hospitals and Trauma Centers dominate domestic procurement within national health systems. Military Medical Units operate through defense ministry tenders with distinct technical specifications. Outpatient Facilities represent emerging channels for follow-on wound care.
- Hospitals:General acute care facilities maintain emergency department hemorrhage control supplies under Joint Commission readiness standards. United States community hospitals in Ohio, Michigan, and Pennsylvania upgrade capabilities through state trauma system grants.
- Trauma Centers:American College of Surgeons-verified Level I and II centers mandate specific hemostatic device inventories. California's trauma network spanning Los Angeles, San Diego, and Sacramento regions standardizes procurement across public and private facilities.
- Outpatient Facilities:Wound care clinics and ambulatory surgery centers manage post-acute ballistic injury follow-up.
- Military Medical Units:Deployed and garrison medical elements operate under FDA Emergency Use Authorization pathways and combat casualty care doctrine.
Hospitals anchor procurement volume. Military Medical Units are gaining share fastest through accelerated modernization cycles.
Delivery Mode:
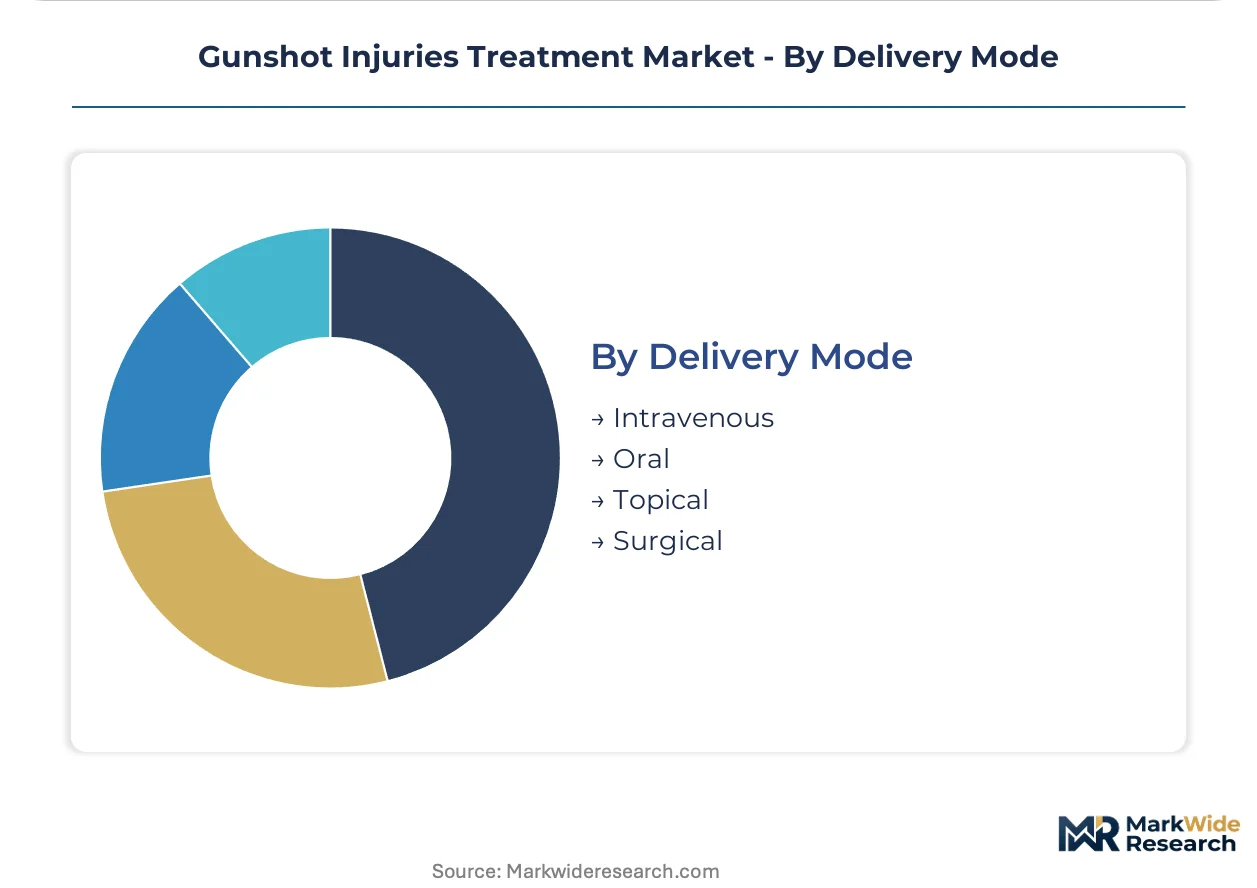
Topical and Surgical delivery concentrate in trauma intervention settings with immediate efficacy requirements. Intravenous routes support adjunctive care. Oral delivery remains limited to extended recovery phases.
- Topical:Direct application of hemostatic powders, dressings, and sealants to bleeding wound surfaces. Tactical combat casualty care protocols in United States Army and Marine Corps units prioritize this route for junctional and non-compressible torso hemorrhage.
- Surgical:Intraoperative hemostasis through resorbable sponges, flowable agents, and energy devices. Civilian trauma centers in Baltimore, Atlanta, and Seattle integrate these systems into damage control laparotomy and thoracotomy workflows.
- Intravenous:Systemic hemostatic agents and blood product administration in resuscitation bays.
- Oral:Extended antibiotic prophylaxis and analgesia for outpatient ballistic wound management.
Surgical delivery holds the revenue base. Topical application shows the steepest trajectory as pre-hospital protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hemostatic device manufacturing clusters in the United States, Germany, China, and India, with regulatory pathways and defense procurement cycles dictating market access speed across each jurisdiction.
United States
FDA breakthrough device designations under the 21st Century Cures Act compress premarket timelines for clot-activation technologies. Level I trauma centers in Chicago, Philadelphia, and Houston mandate specific hemostatic inventories under active shooter response protocols. Military medical units operate through Emergency Use Authorization pathways that accelerate battlefield deployment cycles.
Germany
NATO standardization agreements drive recurrent procurement commitments from the Bundeswehr medical service. EU MDR post-market surveillance requirements extend validation timelines for implantable trauma products by 18-24 months. The medical technology cluster around Tübingen and Stuttgart anchors surgical kit assembly for European defense ministries.
United Kingdom
Ministry of Defence tenders for battlefield medicine systems prioritize interoperability with allied medical units. MHRA recognition of FDA Emergency Use Authorizations streamlines parallel regulatory pathways for deployed forces. The Cambridge-Oxford corridor concentrates hemostatic research translation into commercial trauma products.
China
NMPA Class II medical device registrations govern hemostatic dressing market entry with 12-18 month review cycles. Defense modernization programs under the 14th Five-Year Plan expand military medical infrastructure procurement. Zhejiang province anchors cost-efficient wound dressing production for domestic and export defense budgets.
India
CDSCO medical device rules impose import licensing requirements on hemostatic products with biocompatibility documentation. Defense capital acquisition programs modernize military medical units under the Atmanirbhar Bharat initiative. The Pune-Bengaluru corridor develops domestic surgical kit assembly capabilities for army hospital networks.
Gunshot Injuries Treatment Market Competitive Environment
Concentration sits with diversified medical technology conglomerates and specialized hemostatic device developers. The vendor base spans three tiers: integrated orthopedic-trauma portfolios, dedicated hemorrhage control specialists, and cost-optimized wound dressing fabricators. Strategic archetypes include battlefield-adapted surgical kit assemblers, chitosan-based hemostatic innovators, and resorbable sponge developers. Competitive moves center on NATO qualification certifications and direct procurement contracts with consolidated US health systems.
Among US-based diversified manufacturers, Stryker Corporation exemplifies the integrated trauma portfolio archetype. RevMedx occupies a position within the dedicated hemostatic innovation tier. Zhejiang Haichuang Medical Device Co., Ltd. anchors the cost-efficient production segment for emerging defense markets.
| Leading Market Players |
|---|
| Stryker Corporation |
| RevMedx |
| Medtrade Products Ltd |
| Zhejiang Haichuang Medical Device Co., Ltd. |
| Baxter Healthcare Corporation |
| RescueMed |
| TraumaTech |
| Hemostat Solutions |
| BioHeal Inc. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Southeast Asian chitosan processing facilities shapes both supply concentration and price floors for advanced hemostatic dressings. Scale economies in oxidized regenerated cellulose production anchor premium tier pricing, while smaller batch manufacturers serving emerging defense budgets operate at higher per-unit cost structures.
Pricing Analysis
Volume-discount tiering structures separate NATO-standard surgical kits from civilian trauma center procurement and emerging market defense budgets. Three-tier pricing stratifies across premium hemostatic sponges with sub-three-minute clot activation, standard chitosan-based gauze protocols, and economy cotton dressings for budget-constrained emergency medical services. Cost compression in the economy tier intensifies because conventional gauze substitution limits premium penetration. Military Medical Units demonstrate the least price sensitivity due to operational urgency mandates, while municipal police departments show highest sensitivity for tactical law enforcement medicine kits.
Supply Chain Analysis
Port congestion at Shanghai and Ningbo elevates inbound logistics costs for chitosan raw material shipments from Southeast Asian processing facilities. Manufacturing concentrates in the United States, Germany, and China for hemostatic devices, with India developing domestic surgical kit assembly capabilities. Raw material sourcing draws from Southeast Asian chitosan processors, US-based oxidized regenerated cellulose producers, and European biocompatibility testing laboratories. Single-source vulnerability concentrates in chitosan supply given limited qualified processing facilities. Distribution runs through defense ministry tenders for military procurement and direct hospital system agreements for civilian trauma centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gunshot injuries treatment market represents a high-growth disruption propelled by FDA breakthrough device designations compressing validation cycles for hemostatic interventions. This regulatory inflection accelerates competitive entry timelines and reshapes procurement patterns across military and civilian channels.
For Market Incumbents: Secure NATO qualification certifications ahead of defense ministry modernization cycles to lock out emerging competitors. Secure direct procurement contracts with consolidated US health systems through integrated service bundling of device supply with training certification and inventory management. Capacity addition in Zhejiang province addresses cost-efficient wound dressing demand from emerging defense budgets. For New Entrants and Emerging Players: Lead with tactical law enforcement medicine as the most penetrable segment given active shooter response protocol standardization across municipal police departments. Lead with portable hemorrhage control kits differentiated for junctional wound sites where tourniquets fail. Lead with reimbursement strategy development targeting outpatient wound care clinics for post-acute ballistic injury follow-up. For Investors and Strategic Acquirers: Dedicated hemorrhage control specialists with FDA Emergency Use Authorization pathways and combat casualty care doctrine alignment represent priority acquisition targets. Long-term viability centers on regulatory moat sustainability and military procurement relationship durability. Watch FDA breakthrough device designation velocity as the inflection indicator for competitive entry timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review timelines for sub-three-minute clot-activation technologies under 21st Century Cures Act framework. |
| NATO Standardization Agreement Compliance | Compresses vendor qualification cycles for military medical units across United States, United Kingdom, and Germany procurement. |
| Direct Hospital System Partnership | Replaces fragmented distributor relationships with consolidated purchasing leverage across multi-facility trauma networks. |
| Chitosan Supply Backward Integration | Reduces input volatility exposure from Southeast Asian processing facility concentration. |
| Rehabilitation Services Integration | Captures extended care episode value from rising ballistic trauma survival rates requiring functional restoration. |
Study Parameters
The analysis maps hemostatic devices, surgical kits, wound dressings, and rehabilitation services, each validated through trauma surgeons, hospital purchasing committee directors, and defense ministry procurement officers. Primary interviews with biomedical engineers and GPO contracts managers combine with secondary validation against FDA 510(k) filings, EU MDR notified body records, NATO standardization agreements, and hospital procurement databases. Bottom-up and top-down triangulation cross-checks segment-level demand against aggregate market sizing.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, therapy area, end user, and delivery mode segmentation alongside clot-activation speed performance tiers. CAGRs derive from regression analysis of historical procurement trajectories and forward-looking defense budget allocations. Military theater deployment cycles and civilian trauma center throughput requirements anchor demand-side inputs.
Forecasts assume regulatory continuity in FDA breakthrough device pathways and EU MDR post-market surveillance regimes; material policy shifts would require re-modeling. Specific risk factors include chitosan supply disruption, EU MDR clinical evidence burden extensions, and conventional gauze substitution pressure in budget-constrained segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Scabies Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Infertility Treatment Market