
 Global Uterine Fibroids Treatment Market | 2026-2036
Global Uterine Fibroids Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Uterine Fibroids Treatment Market Foresight
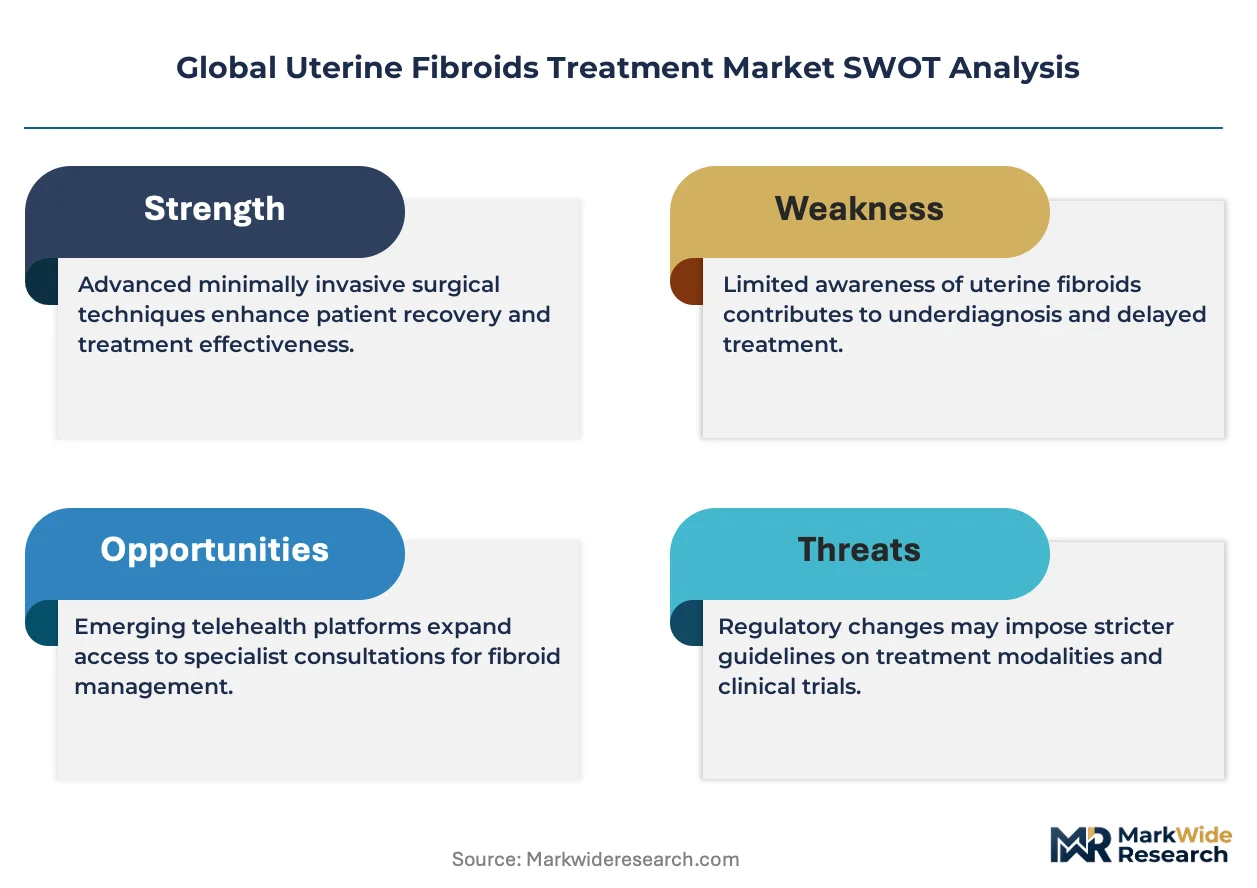
Hospital procurement channels for uterine fibroids treatment devices is fragmenting as specialized gynecologic centers gain direct purchasing authority. Medtronic leverages its integrated surgical portfolio to anchor high-volume accounts in minimally invasive myomectomy. Boston Scientific Corporation competes through radiofrequency ablation systems that occupy the outpatient clinic segment.
Uterine fibroids treatment encompasses pharmacologic, surgical, and non-invasive modalities targeting benign smooth muscle tumors of the myometrium, with procedures ranging from laparoscopic radiofrequency ablation to MRI-guided focused ultrasound thermal coagulation. Hormonal therapy sustains first-line medical management for symptomatic patients, while surgical devices command premium pricing in cases refractory to pharmacologic intervention. Non-invasive therapies represent the fastest-growing delivery mode as INSIGHTEC's focused ultrasound platforms expand reimbursable indications across European hospital networks.
The FDA breakthrough device program and EMA's adaptive pathways framework both compress timelines for uterine-sparing innovations, while Japan's PMDA accelerates reviews for devices demonstrating preservation of fertility outcomes. Stakeholders must monitor reimbursement parity between hysterectomy alternatives and emerging non-invasive modalities as payer cost-effectiveness thresholds tighten across Germany, France, and the United Kingdom.
Market Dynamics
Magnetic resonance-guided focused ultrasound systems are compressing hysterectomy volumes as gynecologic centers acquire direct capital equipment authority outside traditional hospital procurement hierarchies.
Growth Catalysts
- FDA Breakthrough Device Pathway:The accelerated review framework for uterine-sparing technologies shortens commercialization timelines from 36 months to 18 months for eligible devices.
- German Statutory Reimbursement Expansion:Outpatient hysteroscopic myomectomy procedures now carry full reimbursement parity with inpatient alternatives, driving procedural volume in ambulatory settings.
- Fertility Preservation Demand:Women aged 30-40 increasingly reject hysterectomy in favor of myomectomy and ablative techniques that preserve uterine function for future conception.
Market Restraints
- Capital Equipment Intensity:MRI-guided focused ultrasound platforms require $2.5-4.5 million upfront investment plus specialized suite construction, limiting deployment to academic medical centers.
- Reimbursement Asymmetry:United States commercial payers often classify non-invasive ablation as experimental, forcing patients toward surgical alternatives with established CPT codes.
- Substitute Procedure Availability:Uterine artery embolization performed by interventional radiologists competes directly for symptomatic fibroid patients seeking organ-sparing solutions.
Strategic Opportunities
- Japan Fertility Outcome Incentives:PMDA's expedited review track for devices demonstrating post-procedure pregnancy rates creates regulatory arbitrage for manufacturers with robust clinical data.
- Office-Based Radiofrequency Ablation:Compact bipolar RF systems enable gynecologists to perform fibroid ablation in ambulatory surgical centers without hospital admission infrastructure.
- EMA Adaptive Pathways Convergence:Conditional approval frameworks allow real-world evidence collection during commercial rollout, compressing total development timelines for European market entry.
Industry Challenges
- Interventional Radiology-Gynecology Coordination:MRI-guided procedures require synchronized scheduling between imaging suites and procedural teams, creating operational friction and underutilized equipment.
- Longitudinal Outcome Documentation:Recurrence monitoring for ablative techniques demands 5-year follow-up registries that most centers lack infrastructure to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Uterine Fibroids Treatment Market |
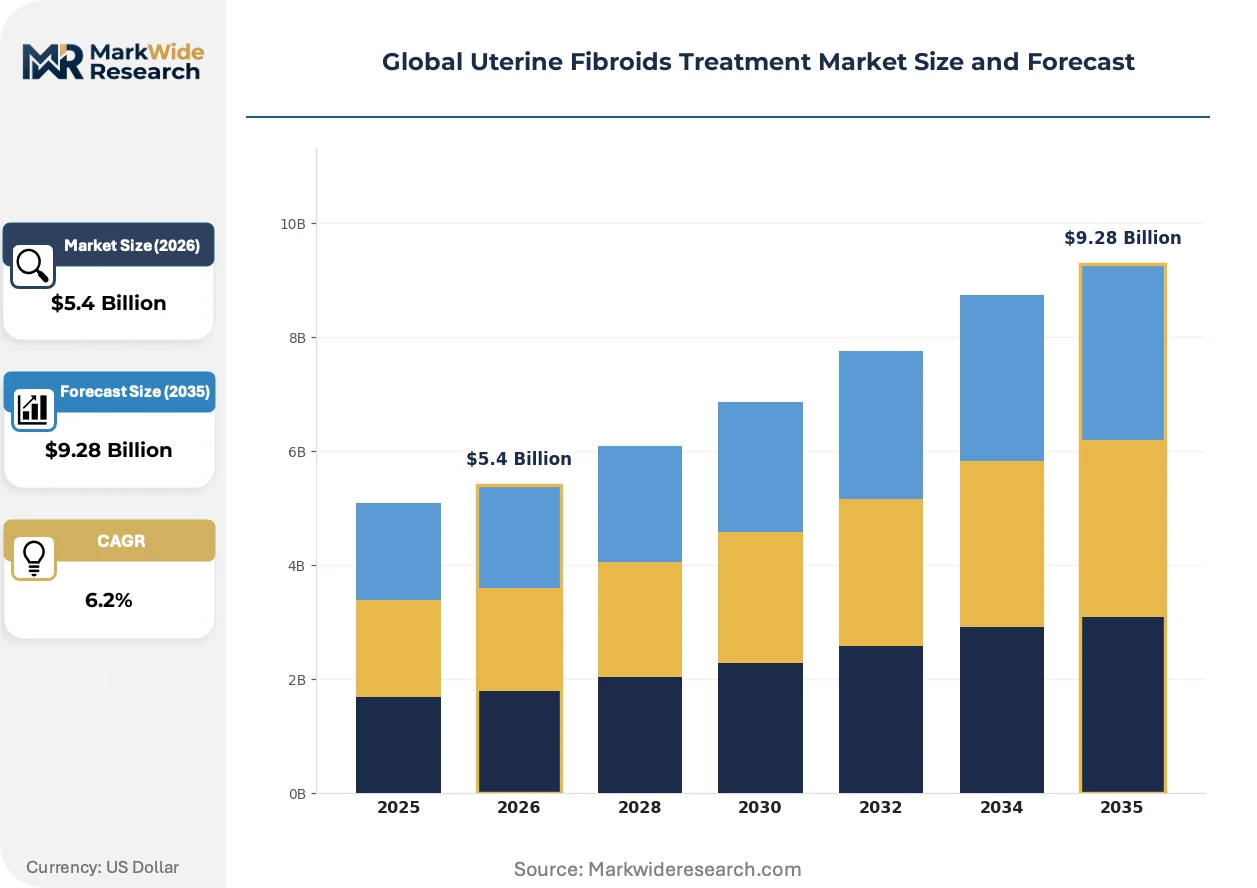
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Surgical Devices, Non-Invasive Therapies, Embolization Agents Therapy Area: Symptomatic Fibroids, Asymptomatic Fibroids, Menorrhagia Management, Pain Relief End User: Hospitals, Outpatient Clinics, Specialized Gynecologic Centers, Diagnostic Laboratories Delivery Mode: Oral, Injectable, Minimally Invasive Procedures, Intrauterine Devices |
| Companies Covered | Medtronic, Boston Scientific Corporation, Hologic, AbbVie Inc., Pfizer Inc., AstraZeneca, Myovant Sciences, Stryker Corporation, INSIGHTEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Uterine Fibroids Treatment Market Shifts & Advancements
Non-invasive thermal ablation modalities are displacing surgical resection as first-line intervention for symptomatic fibroids, compressing the traditional treatment algorithm that positioned hysterectomy as definitive therapy.
Focused ultrasound thermal coagulation is migrating from academic tertiary centers to community gynecologic networks as INSIGHTEC and competing platforms secure expanded CE mark indications across European hospital networks. Community hospitals in France and the Netherlands now deploy these systems for same-day outpatient procedures. The technology is migrating from niche fertility-preservation cases toward standard-of-care status for premenopausal women with submucosal and intramural fibroids.
EMA's Medical Device Regulation (MDR) implementation is forcing retrospective clinical evidence generation for legacy hysteroscopic morcellators and resectoscopes already in commercial distribution. Manufacturers must compile post-market surveillance data or withdraw devices from European markets. Class III device reclassification for powered morcellation systems is driving consolidation among smaller European surgical instrument suppliers unable to absorb notified body audit costs.
Direct-to-employer contracting for bundled fibroid care episodes is emerging in United States metropolitan markets where large self-insured employers negotiate fixed-price packages covering diagnosis through 90-day post-procedure follow-up. Employers in Texas and California pilot these arrangements with integrated delivery networks. The model bypasses traditional fee-for-service reimbursement and shifts volume toward high-efficiency centers meeting quality benchmarks.
Global Uterine Fibroids Treatment Market Segmentation
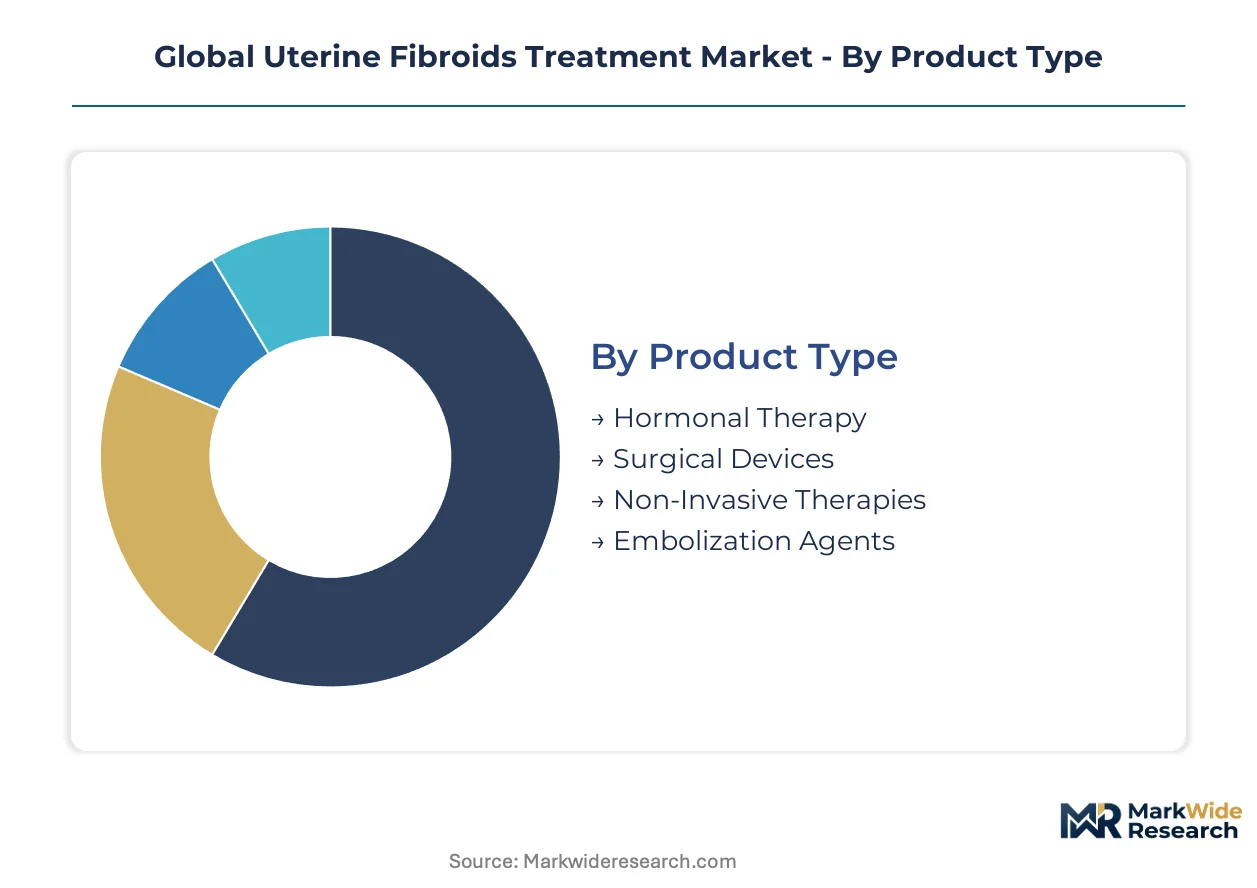
Treatment modality selection in uterine fibroids care follows a severity-escalation pathway where hormonal suppression precedes device-based intervention. Segmentation reveals how reimbursement frameworks and fertility-preservation priorities reshape volume distribution across delivery settings.
Product Type:
Use-case spectrum spans chronic symptom suppression through definitive tissue removal, with capital intensity and reimbursement status determining site-of-care placement.
- Hormonal Therapy:GnRH agonists and selective progesterone receptor modulators constitute first-line pharmacologic management for symptomatic patients. Demand concentrates in outpatient prescription channels across Germany and France, where statutory reimbursement for long-term suppression therapy delays surgical referral.
- Surgical Devices:Hysteroscopic morcellators, laparoscopic power morcellators, and radiofrequency ablation systems command premium pricing in cases refractory to medical management. Hospitals in the United States and academic centers in Japan anchor procurement volume for myomectomy platforms.
- Non-Invasive Therapies:MRI-guided focused ultrasound thermal coagulation systems enable same-day outpatient procedures without incision. INSIGHTEC platforms are gaining reimbursable indications across European hospital networks.
- Embolization Agents:Polyvinyl alcohol particles and tris-acryl gelatin microspheres deployed by interventional radiologists for uterine artery embolization procedures.
Established volume favors surgical devices; emerging adoption favors non-invasive therapies.
Therapy Area:
Cost tier stratification separates chronic management regimens from single-intervention definitive procedures, with fertility status determining algorithm placement.
- Symptomatic Fibroids:Heavy menstrual bleeding, pelvic pressure, and reproductive dysfunction drive intervention demand. Gynecologic centers in the United Kingdom and the Netherlands report highest procedural density for bulk symptom presentations.
- Asymptomatic Fibroids:Incidentally detected myomas during imaging for unrelated indications create surveillance and elective intervention decisions. Diagnostic laboratories in Japan and South Korea generate substantial incidental detection volume through routine pelvic ultrasound screening protocols.
- Menorrhagia Management:Heavy menstrual bleeding as primary complaint favors hormonal suppression and endometrial ablation over myomectomy in perimenopausal cohorts.
- Pain Relief:Dysmenorrhea and chronic pelvic pain indications support NSAID-refractory progression to procedural intervention pathways.
Symptomatic presentations dominate revenue contribution; asymptomatic detection is expanding the addressable patient pool fastest.
End User:
Customer type evolution shows procurement authority migrating from centralized hospital supply chains toward specialized gynecologic centers with direct capital equipment acquisition rights.
- Hospitals:Academic medical centers and community hospital systems maintain high-volume surgical myomectomy and hysterectomy capabilities. Facilities in Texas and California pilot direct-to-employer bundled care contracts bypassing traditional fee-for-service structures.
- Outpatient Clinics:Ambulatory surgical centers in Germany leverage statutory reimbursement parity for hysteroscopic procedures performed outside inpatient admission. Radiofrequency ablation systems enable office-based fibroid treatment without hospital infrastructure.
- Specialized Gynecologic Centers:Dedicated fibroid clinics in France and the Netherlands deploy focused ultrasound platforms for same-day thermal coagulation. Direct purchasing authority outside traditional procurement hierarchies accelerates technology adoption.
- Diagnostic Laboratories:Imaging centers and pathology services support detection, staging, and post-treatment monitoring workflows.
Hospitals retain hysterectomy and complex myomectomy volume; specialized gynecologic centers are capturing non-invasive ablation growth.
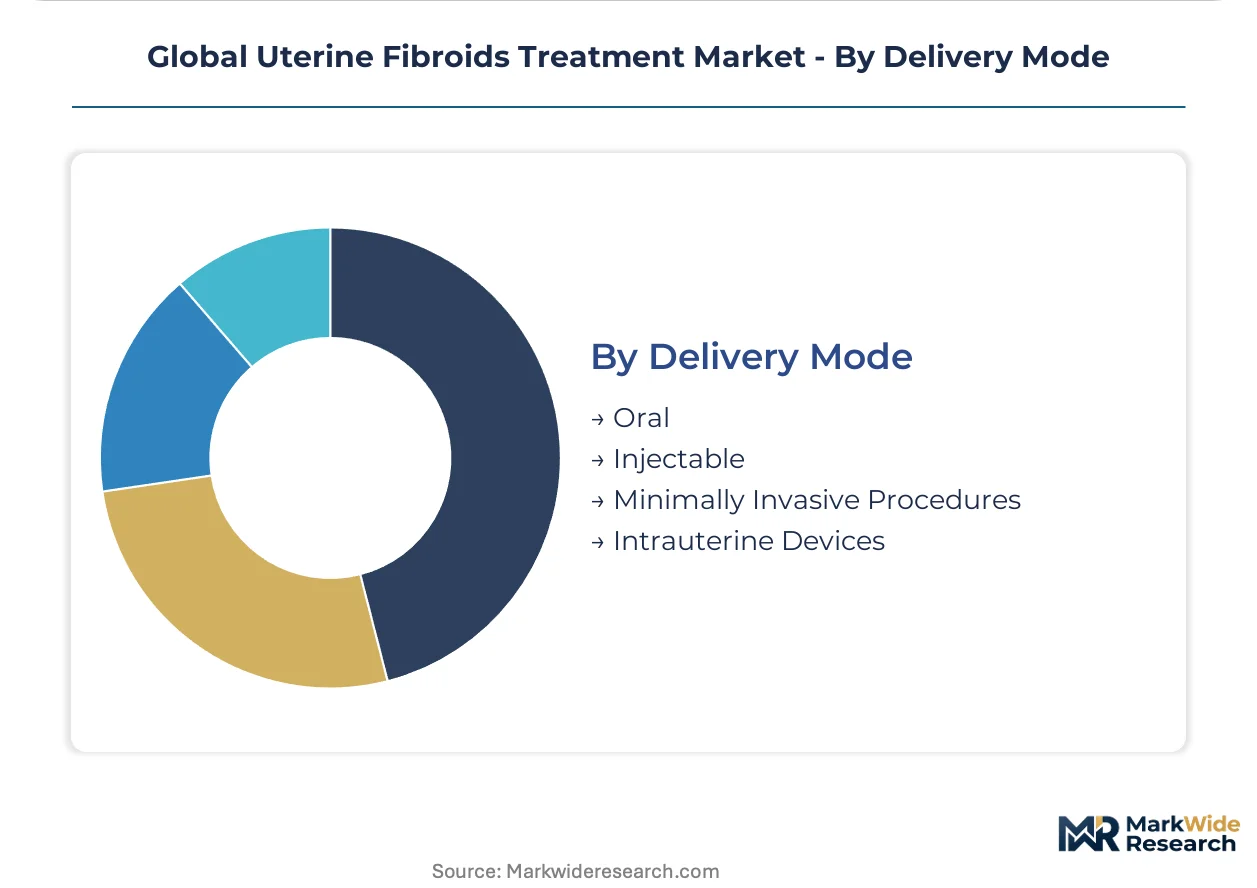
Delivery Mode:
Maturity gradient separates decades-established oral and injectable routes from procedure-based alternatives requiring capital equipment and specialized training.
- Oral:Selective progesterone receptor modulators and combination hormonal contraceptives enable patient-administered chronic symptom suppression. Primary care prescription channels in France and Spain drive volume for ulipristal acetate and similar agents.
- Injectable:Depot leuprolide and GnRH antagonist formulations provide monthly or quarterly administration for patients preferring compliance assurance over daily regimens.
- Minimally Invasive Procedures:Laparoscopic radiofrequency ablation, hysteroscopic resection, and laparoscopic myomectomy balance tissue preservation with definitive intervention. Outpatient migration of these procedures is reshaping site-of-care economics across European markets.
- Intrauterine Devices:Levonorgestrel-releasing systems deliver localized hormonal suppression for menorrhagia-dominant presentations without systemic exposure.
Oral delivery maintains patient-initiated access advantages; minimally invasive procedures are climbing the fastest as fertility-preservation demand reshapes treatment algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics hub underwrites continental distribution for hormonal therapies across Western Europe. This infrastructure asset anchors transatlantic supply chains for GnRH agonists and selective progesterone receptor modulators.
United States
Academic medical centers in Boston and Houston anchor MRI-guided focused ultrasound adoption. The FDA breakthrough device designation compresses commercialization timelines for uterine-sparing technologies. Gynecologic centers in Texas pilot direct-to-employer bundled care contracts that bypass traditional fee-for-service structures.
Germany
Statutory health insurance reimbursement parity for outpatient hysteroscopic procedures drives ambulatory procedural volume. The EMA Medical Device Regulation forces retrospective clinical evidence generation for legacy hysteroscopic morcellators. Specialized gynecologic centers in Bavaria and North Rhine-Westphalia deploy focused ultrasound platforms for same-day thermal coagulation.
Japan
PMDA's expedited review track for devices demonstrating post-procedure pregnancy rates creates regulatory arbitrage for fertility-preservation innovations. Diagnostic laboratories in Tokyo and Osaka generate substantial incidental fibroid detection volume through routine pelvic ultrasound screening protocols. Kanto region hospitals anchor procurement for myomectomy platforms.
France
Community hospitals in Île-de-France and Provence-Alpes-Côte d'Azur deploy focused ultrasound systems for same-day outpatient procedures. ANSM oversight of medical device vigilance shapes post-market surveillance requirements for thermal ablation platforms. Paris-based gynecologic centers capture non-invasive ablation growth outside traditional hospital procurement hierarchies.
United Kingdom
Gynecologic centers in London and the Midlands report highest procedural density for bulk symptom presentations. NHS England's cost-effectiveness thresholds tighten reimbursement parity between hysterectomy alternatives and emerging non-invasive modalities. Integrated care systems in Greater Manchester pilot outcome-based contracting for fibroid care episodes.
Global Uterine Fibroids Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain for radiofrequency ablation electrodes and embolization particles. The vendor base stratifies across three tiers: multinational surgical conglomerates with integrated portfolios, mid-cap device specialists with focused gynecologic franchises, and emerging players in non-invasive thermal modalities. Strategic moves concentrate on regulatory pathway optimization and site-of-care expansion into ambulatory settings.
Among platform integrators, Medtronic anchors high-volume accounts through its integrated surgical portfolio, while Boston Scientific Corporation occupies the outpatient clinic segment with radiofrequency ablation systems. INSIGHTEC exemplifies the non-invasive modality archetype with focused ultrasound platforms gaining reimbursable indications across European hospital networks.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Hologic |
| AbbVie Inc. |
| Pfizer Inc. |
| AstraZeneca |
| Myovant Sciences |
| Stryker Corporation |
| INSIGHTEC |
| Others |
Supply & Pricing Matrix
Rotterdam's pharmaceutical logistics hub anchors continental distribution for hormonal therapies, concentrating upstream supply power among GnRH agonist and selective progesterone receptor modulator manufacturers serving Western European outpatient channels. This geographic chokepoint translates into pricing leverage for incumbent suppliers negotiating with hospital procurement committees and specialized gynecologic centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MRI-guided focused ultrasound platforms from radiofrequency ablation systems and generic hormonal therapies. Premium tiers command position through FDA breakthrough device designation and fertility outcome data, while standard surgical devices compete on procedural volume discounts to hospital systems. Price erosion runs through the hormonal therapy segment as patent expirations for GnRH agonists expand generic substitution. Outpatient clinics exhibit highest price sensitivity due to capital constraints, whereas academic medical centers prioritize clinical efficacy metrics over unit cost.
Supply Chain Analysis
Export control regimes for high-intensity focused ultrasound transducers and superconducting magnet components limit technology transfer to certified medical device manufacturers in Germany, Japan, and the United States. Component sourcing draws from specialized suppliers in the Netherlands for radiofrequency electrodes, Switzerland for precision surgical instruments, and Ireland for pharmaceutical active ingredients. Single-source vulnerability concentrates in superconducting wire supply for MRI-guided systems. Distribution runs through hospital procurement hierarchies for capital equipment and direct-to-clinic channels for disposable ablation electrodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as interoperability between imaging systems and thermal ablation devices creates ecosystem lock-in effects favoring integrated solution providers.
For Market Incumbents: Build switching-cost moats through proprietary training certification programs for gynecologic center staff operating focused ultrasound platforms. Deepen backward integration into radiofrequency electrode manufacturing to capture margin from outpatient clinic volume expansion. Consolidate position against emerging entrants by securing exclusive GPO contracts with hospital systems in Texas and California piloting bundled care episodes. For New Entrants and Emerging Players: Southeast Asian diagnostic laboratory networks present underpenetrated white space for compact radiofrequency ablation systems targeting incidental fibroid detection protocols. Office-based gynecology practices in Spain and Italy offer secondary entry points with lower capital barriers than hospital procurement channels. Pursue regulatory arbitrage through Japan's PMDA fertility outcome incentive track to accelerate market access against entrenched surgical device portfolios. For Investors and Strategic Acquirers: Long-term, this sits as a procedure-migration play because volume gravity shifts from inpatient hysterectomy toward outpatient thermal ablation across European and North American markets. Target acquisition candidates with focused ultrasound platforms demonstrating post-procedure pregnancy registry data. Monitor reimbursement parity decisions by Germany's statutory health insurance as the inflection signal for non-invasive modality adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance enables continued European distribution for thermal ablation platforms. |
| Hospital System Partnership | Integrated delivery networks in Texas anchor bundled care contract volume for fibroid treatment episodes. |
| Reimbursement Strategy | CPT code establishment for MRI-guided procedures unlocks United States commercial payer coverage expansion. |
| Software Companion Development | Real-time thermal monitoring algorithms differentiate next-generation focused ultrasound platforms from legacy systems. |
| Regulatory Approval Pathway | FDA breakthrough device designation compresses review timelines for uterine-sparing innovations. |
Research Methodology
Desk research of FDA 510(k) filings, EMA medical device registration databases, and hospital procurement contract records preceded structured interviews with gynecologic surgeons, biomedical engineers, GPO contracts managers, and payer formulary directors. Secondary validation drew from CMS Medicare claims data, statutory health insurance reimbursement schedules in Germany and France, and clinical trial registries. Bottom-up procedure volume estimates triangulated against top-down market sizing from capital equipment installation records.
Assumptions held reimbursement parity evolution and fertility preservation demand growth as fixed parameters while varying capital equipment deployment rates and regulatory approval timelines across the projection horizon. Segmentation modeling spanned treatment modality, therapy area severity, end-user facility type, and delivery mode complexity. CAGRs derived from logistic adoption curves fitted to historical procedure volume trajectories in comparable minimally invasive surgical categories. Forecast inputs incorporated PMDA review track utilization rates and outpatient hysteroscopic procedure reimbursement decisions.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or statutory insurance budget constraints would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement expansion velocity. Material shifts in FDA breakthrough device eligibility criteria or EMA MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market