
 Kidney Stones Management Market | 2026-2036
Kidney Stones Management Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Stones Management Market Analysis
Aftermarket service revenue for lithotripter maintenance and laser fiber replacement is tilting toward original equipment manufacturers as hospital capital budgets tighten. Boston Scientific Corporation leverages its integrated urology portfolio to capture recurring consumable sales alongside capital placements. Olympus Corporation sustains dominance in flexible ureteroscope refurbishment programs that extend device lifecycles. KARL STORZ SE & Co. KG anchors European demand through rigid endoscope manufacturing scale and specialized training infrastructure.
Kidney stones management encompasses the clinical and surgical interventions used to fragment, extract, or pass renal and ureteral calculi, with extracorporeal shock wave lithotripsy employing electromagnetic or electrohydraulic generators producing shock waves at 18-24 kV to fragment stones into passable particles less than 4 mm. The primary purpose spans symptomatic relief, prevention of renal obstruction, and reduction of recurrent stone formation through combined procedural and pharmacological protocols. Laser lithotripters command premium positioning within device type segmentation as holmium and thulium fiber platforms displace pneumatic ballistic systems in complex stone burdens. Ureteroscopy represents the fastest-growing treatment type as single-use scopes eliminate reprocessing liability and cross-contamination risk. Dietary management remains the most mature segment with limited reimbursement but expanding digital health integration for metabolic evaluation.
FDA 510(k) pathways govern laser lithotripter and retrieval device approvals in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for endoscope reprocessing validation. Japan's PMDA maintains distinct technical standards for electromagnetic shock wave generators that delay multinational product harmonization. Stakeholders must monitor reimbursement divergence between inpatient percutaneous nephrolithotomy and outpatient ureteroscopy as site-of-service policies reshape capital allocation across hospital and ambulatory settings.
Market Dynamics
Single-use ureteroscope commercialization is compressing capital equipment cycles while fragmenting aftermarket service revenue streams across ambulatory networks. This technology shift is redistributing value capture from reprocessing-dependent incumbents toward disposable manufacturers with fiber laser integration capabilities.
Growth Catalysts
- EU MDR Article 120 transition:Extended legacy device marketing periods are accelerating hospital procurement of validated single-use endoscopes ahead of 2028 certificate expiration deadlines.
- Holmium laser fiber platforms:Thulium fiber laser miniaturization is enabling office-based stone fragmentation in urology clinics previously restricted to hospital settings.
- Metabolic stone prevention protocols:Digital health integration with 24-hour urine analysis is expanding reimbursable nephrology consultations in United States integrated delivery networks.
Market Restraints
- Reimbursement compression:CMS site-of-service payment differentials between hospital outpatient departments and ambulatory surgical centers are constraining capital allocation for multi-scope facilities.
- Laser fiber supply concentration:Rare-earth dopant processing for holmium and thulium gain media concentrates among Chinese rare earth refiners, creating input cost volatility.
- Shock wave generator technical limitations:Electrohydraulic electrode degradation at 18-24 kV operating voltages limits device reliability below pneumatic lithotripter benchmarks in hard stone compositions.
Strategic Opportunities
- Office-based lithotripsy expansion:United States urology group practices are retrofitting procedure rooms for laser ureteroscopy, bypassing hospital facility fees entirely.
- Japan PMDA electromagnetic standards:Divergent technical requirements for shock wave focal zone characterization create first-mover advantages for localized regulatory submission strategies.
- Stone retrieval basket-digital imaging convergence:Integrated nitinol basket designs with real-time stone sizing algorithms are enabling same-session complete stone clearance protocols.
Industry Challenges
- Laser safety certification timelines:IEC 60601-2-22 third-edition compliance for fiber laser systems extends FDA 510(k) review cycles by eight to fourteen months.
- Flexible ureteroscope repair technician scarcity:Deflection mechanism micro-welding expertise concentrates among German and Japanese OEM service centers, limiting third-party refurbishment competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Stones Management Market |
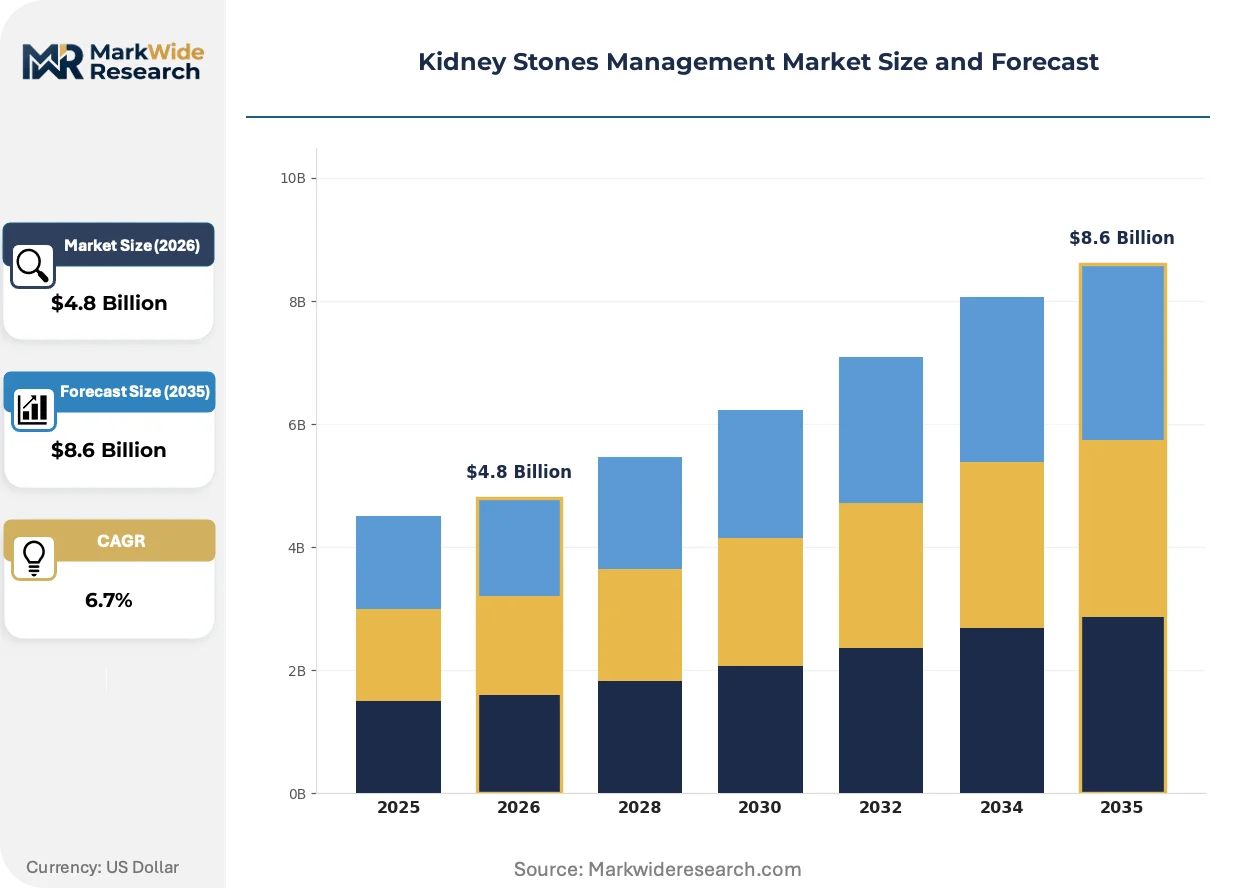
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Extracorporeal Shock Wave Lithotripsy, Ureteroscopy, Percutaneous Nephrolithotomy, Dietary Management Device Type: Laser Lithotripters, Stents, Endoscopes, Kidney Stone Retrieval Devices End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Healthcare Medication Type: Thiazide Diuretics, Potassium Citrate, Allopurinol, Others |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, KARL STORZ SE & Co. KG, Richard Wolf GmbH, Cook Medical, BD, EDAP TMS, Allengers Medical Systems Ltd., Dornier MedTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Stones Management Market Emerging Trajectories
Stone management workflows are fragmenting across care settings as disposable technology economics override capital depreciation models. This transformation is compressing device lifecycle expectations while elevating consumable revenue predictability.
Digital stone analysis platforms integrating spectral CT imaging with artificial intelligence classification are digitizing pre-procedural planning across United States academic medical centers. Urologists are adopting these systems to predict stone composition and laser parameter selection before scope insertion. This capability is digitizing operative time allocation and reducing anesthesia exposure in outpatient protocols.
FDA 510(k) substantial equivalence determinations for laser lithotripters are tightening predicate device requirements following electromagnetic compatibility incidents in 2023. Manufacturers are responding with expanded clinical validation datasets spanning multiple stone compositions and patient BMI ranges. United States market entrants face extended pre-submission timelines and predicate device substantiation costs.
Ambulatory surgical center buyers are consolidating procurement authority through group purchasing organizations, displacing hospital-centric distributor relationships. This concentration is forcing device manufacturers to restructure sales compensation and inventory consignment models. The shift is most visible in southeastern United States markets where urology practice consolidation has exceeded national averages.
Kidney Stones Management Market Segmentation
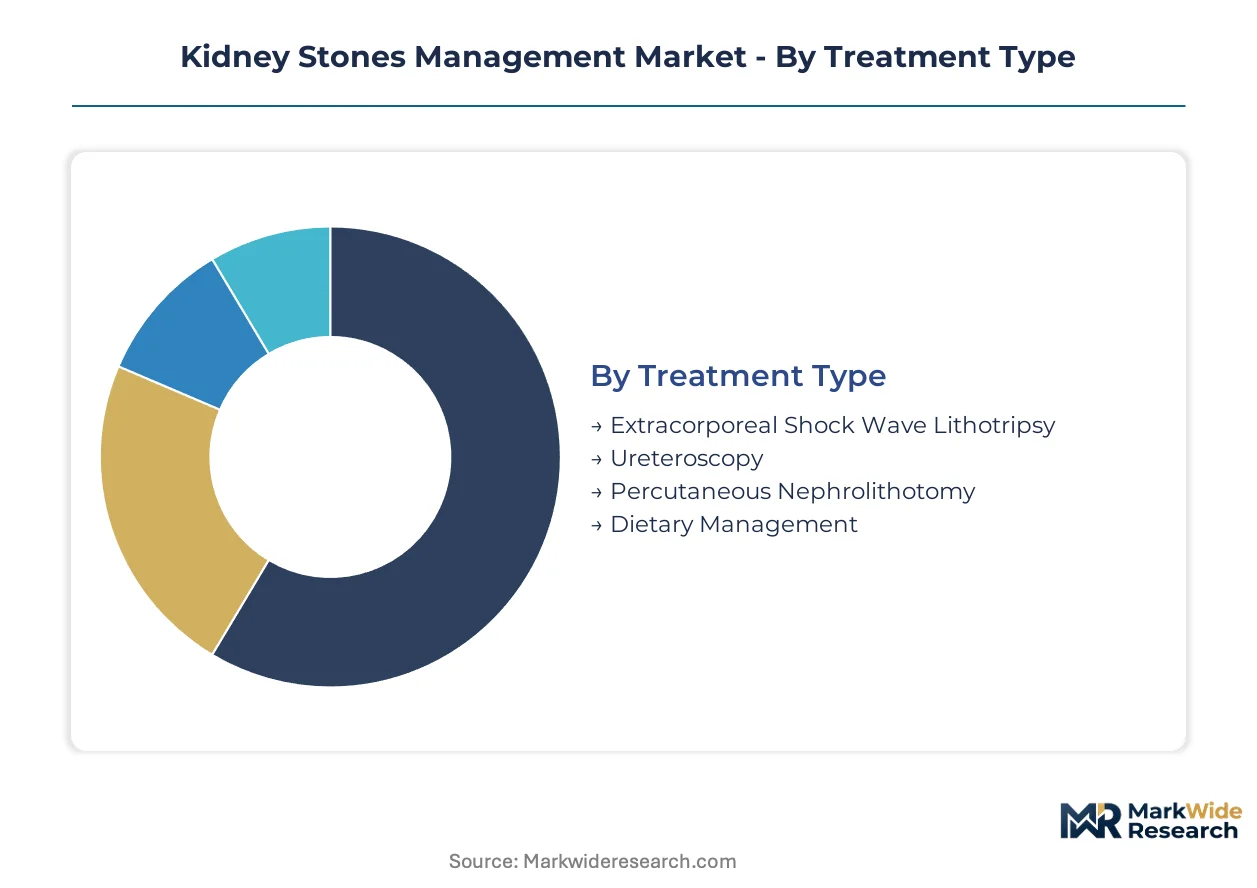
Stone management workflows fragment across procedural intensity, device capital requirements, and care setting economics. Each segmentation axis reveals distinct margin profiles and regulatory exposure that reshape manufacturer positioning.
Treatment Type:
The use-case spectrum spans non-invasive fragmentation through metabolic prevention, with reimbursement intensity inversely correlating with procedural invasiveness.
- Ureteroscopy:Flexible and rigid endoscope insertion enables direct stone visualization and laser fragmentation within the urinary tract. United States ambulatory surgical centers are driving procedural volume as single-use scopes eliminate reprocessing liability and facility overhead.
- Extracorporeal Shock Wave Lithotripsy:Electromagnetic or electrohydraulic generators deliver focused shock waves at 18-24 kV to fragment stones into passable particles under 4 mm. Demand concentrates in European hospital systems where capital equipment depreciation cycles favor mature platform utilization.
- Percutaneous Nephrolithotomy:Percutaneous tract creation and nephroscope insertion for large or complex stone burdens requiring direct renal access.
- Dietary Management:Metabolic evaluation and fluid intake protocols with limited reimbursement but expanding digital health integration.
The dominant share belongs to Extracorporeal Shock Wave Lithotripsy, while Ureteroscopy is closing the gap fastest.
Device Type:
Capital intensity and consumable attachment rates differentiate margin profiles across the hardware spectrum.
- Laser Lithotripters:Holmium and thulium fiber platforms deliver precise stone fragmentation with adjustable pulse energy and frequency settings. United States urology group practices are retrofitting procedure rooms for office-based deployment, bypassing hospital facility fees entirely.
- Endoscopes:Flexible ureteroscopes with active deflection mechanisms and integrated irrigation channels enable upper tract navigation. EU MDR Article 120 transition deadlines are accelerating hospital procurement of validated single-use alternatives ahead of certificate expirations.
- Kidney Stone Retrieval Devices:Nitinol basket designs with tipless and helical configurations for stone capture and extraction.
- Stents:Double-J and externalized stent designs for ureteral patency maintenance post-procedure.
Laser Lithotripters capture premium positioning, while Endoscopes are expanding most quickly through disposable substitution.
End User:
Site-of-service economics and capital budget autonomy segment procurement authority across care settings.
- Ambulatory Surgical Centers:Outpatient facilities with dedicated procedure rooms and streamlined anesthesia protocols for same-day discharge. Southeastern United States markets show pronounced consolidation through group purchasing organizations displacing hospital-centric distributor relationships.
- Hospitals:Integrated health networks with hybrid operating room infrastructure and inpatient capability for complex stone burdens. CMS site-of-service payment differentials are constraining capital allocation for multi-scope facilities.
- Clinics:Office-based urology practices with limited procedure room retrofit capability.
- Home Healthcare:Post-procedural stent management and metabolic monitoring through remote patient engagement platforms.
Hospitals retain installed base dominance, though Ambulatory Surgical Centers are gaining share fastest through procedural migration.
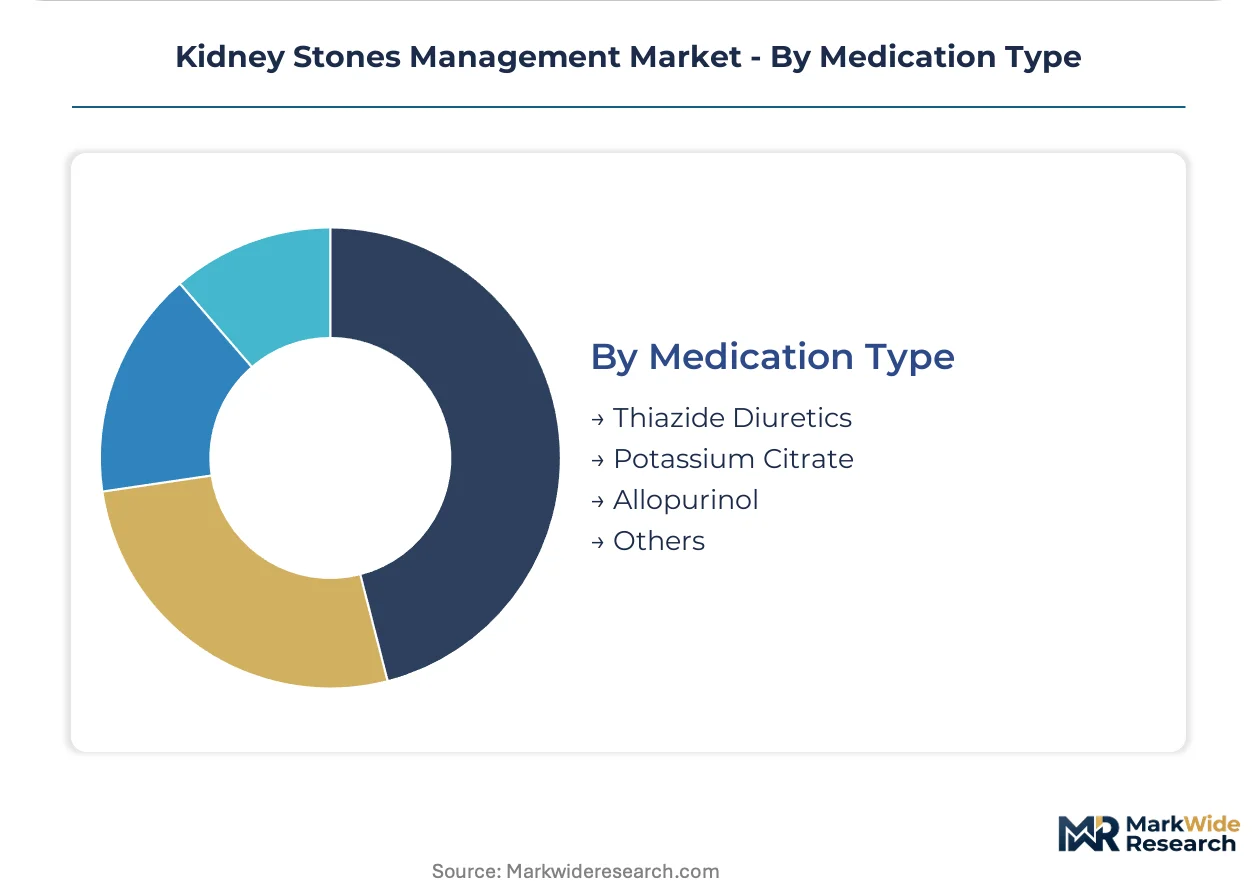
Medication Type:
Pharmacological prevention targets specific stone chemistries with distinct reimbursement and adherence profiles.
- Thiazide Diuretics:Hydrochlorothiazide and indapamide for calcium stone prevention through urinary calcium reduction. United States integrated delivery networks are expanding reimbursable nephrology consultations through digital health integration with 24-hour urine analysis.
- Potassium Citrate:Urinary alkalinization therapy for uric acid and cystine stone prevention. Rare-earth supply concentration for citrate synthesis precursors creates input cost volatility from Chinese refiner dominance.
- Allopurinol:Xanthine oxidase inhibition for hyperuricosuric calcium oxalate stone prevention.
- Others:Alpha-blockers for distal ureteral stone passage and antibiotics for struvite stone management.
Thiazide Diuretics anchor prescription volume, while Potassium Citrate is climbing the fastest on metabolic protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for disposable ureteroscopes, while Chinese procurement prioritizes refurbished capital equipment and domestic laser fiber alternatives.
United States
Integrated health networks in Texas and Florida drive ambulatory surgical center consolidation through group purchasing organizations. FDA 510(k) pathways for laser lithotripters compress approval timelines for manufacturers targeting office-based urology practices. The Southeast corridor from Atlanta to Miami shows the fastest procedural migration away from hospital outpatient departments.
Germany
Rigid endoscope manufacturing clusters in Tuttlingen and Berlin sustain European supply chains for reusable ureteroscopy platforms. EU MDR Article 120 transition deadlines accelerate hospital procurement of validated single-use alternatives ahead of 2028 certificate expirations. Bavarian academic medical centers pilot AI-integrated stone composition analysis for pre-procedural planning.
Japan
PMDA electromagnetic standards for shock wave focal zone characterization delay multinational product harmonization and protect domestic generator manufacturers. Tokyo and Osaka urology clinics adopt thulium fiber laser miniaturization for office-based fragmentation previously restricted to hospital settings. METI funding supports domestic rare-earth dopant processing to reduce import dependence for holmium gain media.
China
Rare-earth refiner concentration in Jiangxi and Inner Mongolia controls holmium and thulium gain media supply for global laser fiber production. NMPA regulatory harmonization with international standards accelerates approval of domestically manufactured retrieval devices. Shanghai and Beijing hospitals balance cost constraints with procurement of imported flexible ureteroscopes for complex stone burdens.
India
CDSCO streamlined pathways for Class B and C medical devices attract multinational lithotripter manufacturers seeking emerging market expansion. Maharashtra and Karnataka host the fastest-growing ambulatory urology networks adopting pneumatic ballistic systems as cost-effective laser alternatives. Government hospital procurement favors electrohydraulic shock wave platforms with established maintenance infrastructure.
Kidney Stones Management Market Vendor Landscape
Integrated urology portfolio holders and specialized endoscope manufacturers split the market into distinct competitive spheres. Consolidation pressure concentrates among disposable technology entrants challenging reprocessing-dependent incumbents. Three archetypes dominate: diversified medtech conglomerates with recurring consumable strategies, precision endoscope specialists with refurbishment ecosystems, and regional equipment fabricators with price-competitive pneumatic platforms. M&A activity targets single-use scope technology acquisitions, while geographic expansion focuses on ambulatory surgical center procurement authority consolidation.
Within the integrated portfolio tier, Boston Scientific Corporation exemplifies recurring revenue capture through consumable attachment to capital placements. Olympus Corporation and KARL STORZ SE & Co. KG occupy positions at opposite ends of the reusable-disposable spectrum, with the former anchoring refurbishment program dominance and the latter representing European manufacturing scale in rigid endoscope platforms. These three entities collectively illustrate how service revenue models and regulatory compliance capabilities differentiate competitive positioning across divergent technology transitions.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| KARL STORZ SE & Co. KG |
| Richard Wolf GmbH |
| Cook Medical |
| BD |
| EDAP TMS |
| Allengers Medical Systems Ltd. |
| Dornier MedTech |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit rare-earth dopant cost volatility directly into laser lithotripter pricing tiers, amplifying the margin compression that Chinese refiner concentration already imposes on fiber gain media procurement across ambulatory surgical center networks.
Pricing Analysis
Aftermarket service contracts and laser fiber replacement programs anchor lifetime value capture for original equipment manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Cost compression in consumable tiers is intensifying because ambulatory surgical center group purchasing organizations consolidate procurement authority. Price-sensitive independent urology clinics in emerging markets absorb economy-tier pneumatic systems, while integrated United States health networks absorb premium-tier disposable ureteroscope premiums.
Supply Chain Analysis
Extended payment terms from Chinese rare-earth refiners in Jiangxi and Inner Mongolia stabilize working capital for laser fiber manufacturers facing downstream pricing pressure. Holmium and thulium gain media sourcing centers on China, with secondary concentration in Japanese METI-funded domestic processing facilities. Nitinol wire feedstock for retrieval baskets draws from United States and European specialty alloy producers. Single-source vulnerability in rare-earth dopant refining creates exposure to export restriction shocks. Distribution runs through regional medical device distributors with hospital-centric relationships giving way to ambulatory surgical center group purchasing organization direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ambulatory surgical center consolidation through southeastern United States group purchasing organizations has shifted procurement leverage toward buyers, fragmenting manufacturer pricing power across fragmented urology practice networks.
For Market Incumbents: Pre-empt single-use ureteroscope entrants by accelerating in-house fiber laser integration capabilities before 510(k) review cycles tighten further. Secure backward integration into rare-earth dopant processing through offtake agreements with Chinese refiners, insulating input cost volatility that threatens consumable margin stability. Defend refurbishment program dominance against disposable substitution by extending flexible ureteroscope lifecycle guarantees. For New Entrants and Emerging Players: Office-based urology practices in Japan's Tokyo-Osaka corridor present underpenetrated deployment terrain for thulium fiber laser miniaturization platforms. Target India's Maharashtra and Karnataka ambulatory networks with pneumatic ballistic systems as cost-effective laser alternatives. Bypass hospital distributor relationships entirely through direct group purchasing organization engagement in consolidated southeastern United States markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to divest non-core urology portfolios amid disposable technology transition pressures. Five-to-ten year viability hinges on consumable attachment rate sustainability rather than capital equipment placement volume. Monitor FDA 510(k) predicate device substantiation cost escalation as an inflection indicator for regulatory barrier height and incumbent protection strength.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Laser Platform Miniaturization | Thulium systems enable office-based fragmentation outside hospital settings. |
| Single-Use Endoscope Regulatory Submission | EU MDR Article 120 deadlines accelerate validated disposable procurement. |
| Group Purchasing Organization Partnership | Direct ambulatory surgical center contracts displace hospital distributor relationships. |
| Rare-Earth Dopant Supply Agreement | Offtake contracts with Chinese refiners stabilize laser fiber input costs. |
| AI-Integrated Stone Composition Platform | Spectral CT classification reduces operative time in outpatient protocols. |
Methodological Framework
Cross-validation between primary interviews with urologists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body certification data. Bottom-up procedure volume modeling triangulates with top-down device shipment aggregation.
Calibration against historical laser lithotripter placement cycles and ureteroscopy procedural migration patterns informs the analytical framework across the projection horizon. Segmentation dimensions span treatment type, device capital intensity, end-user site-of-service economics, and regional regulatory cluster. CAGRs derive from installed base depreciation schedules and consumable attachment rate trajectories. Forecast inputs incorporate ambulatory surgical center construction pipelines and rare-earth refiner capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by single-use disposable entrants or Chinese rare-earth export restriction enforcers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market