
 Global Enteral Feeding Tubes Market | 2026-2036
Global Enteral Feeding Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enteral Feeding Tubes Market Foresight
Aftermarket service revenue for enteral feeding tube maintenance and replacement cycles is tilting toward home healthcare channels as hospital length-of-stay contracts. Fresenius Kabi leverages its vertically integrated nutrition platform to control both formula and delivery device supply chains. Cardinal Health sustains broad distribution reach across acute and post-acute settings through its medical segment infrastructure. Avanos Medical specializes in enteral access technologies, competing primarily on low-profile gastrostomy device design.
Enteral feeding tubes are flexible polymer or silicone catheters inserted through nasal, oral, or percutaneous routes to deliver liquid nutrition directly into the gastrointestinal tract, with diameters typically measured in French units and radiopaque lines enabling fluoroscopic placement verification. Gastrostomy tubes occupy the largest installed base among product types due to their suitability for long-term enteral access in neurological disorder patients. Polyurethane material formulations are capturing disproportionate growth share because their thin-wall construction permits larger inner lumens at smaller outer diameters, reducing patient discomfort while maintaining flow rates. Home healthcare end users represent the fastest-expanding demand channel as reimbursement frameworks shift toward outpatient nutrition management.
The FDA enforces medical device quality system regulation and biocompatibility testing under ISO 10993 standards, while the EU Medical Device Regulation requires notified body certification for enteral access devices sold in European markets. Japan's PMDA mandates clinical evidence submissions for novel percutaneous endoscopic gastrostomy kits, creating differentiated market access timelines across jurisdictions. Stakeholders must monitor evolving reimbursement codes for home-based enteral nutrition in the United States, Germany, and Japan to anticipate volume shifts between acute and post-acute settings.
Market Dynamics
Home healthcare reimbursement expansion is compressing acute-care enteral feeding tube volumes while accelerating replacement cycle frequency in outpatient settings. Polyurethane thin-wall technology is simultaneously reducing patient discomfort thresholds and enabling longer dwell times outside institutional monitoring.
Growth Catalysts
- Japan's PMDA clinical evidence pathway:Novel percutaneous endoscopic gastrostomy kits gain accelerated market access through streamlined submission protocols for elderly neurological patients.
- Polyurethane material substitution:Thin-wall polymer construction permits larger inner lumens at reduced outer diameters, improving flow rates while minimizing nasal and gastric tissue irritation.
- Germany's outpatient reimbursement expansion:Statutory health insurance frameworks now cover home-based enteral nutrition therapy, shifting device procurement from hospital purchasing to durable medical equipment channels.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains cluster in East Asian polymer manufacturing clusters, exposing device producers to input cost volatility and logistics disruption.
- FDA biocompatibility testing timelines:ISO 10993 compliance requirements extend product development cycles for novel polymer formulations seeking 510(k) clearance.
- PEG kit technical limitations:Percutaneous endoscopic gastrostomy placement requires fluoroscopic verification infrastructure unavailable in many home healthcare settings, restricting adoption to institutional environments.
Strategic Opportunities
- United States home healthcare channel:Reimbursement code expansion for outpatient enteral nutrition creates white space for low-profile gastrostomy device distribution through durable medical equipment suppliers.
- Anti-microbial coating convergence:Silver-ion and chlorhexidine-impregnated polymer technologies combine with radiopaque line integration to reduce biofilm formation and replacement frequency.
- Telehealth-integrated feeding monitoring:Remote flow-rate sensing and occlusion alert systems enable clinical oversight of home-based patients without routine institutional visits.
Industry Challenges
- Interventional radiology skill scarcity:Fluoroscopic-guided tube placement requires specialized physician training that concentrates in tertiary academic medical centers, limiting service expansion.
- Legacy electronic health record integration:Home healthcare documentation systems lack standardized interoperability with hospital-based enteral nutrition order sets, complicating care transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enteral Feeding Tubes Market |
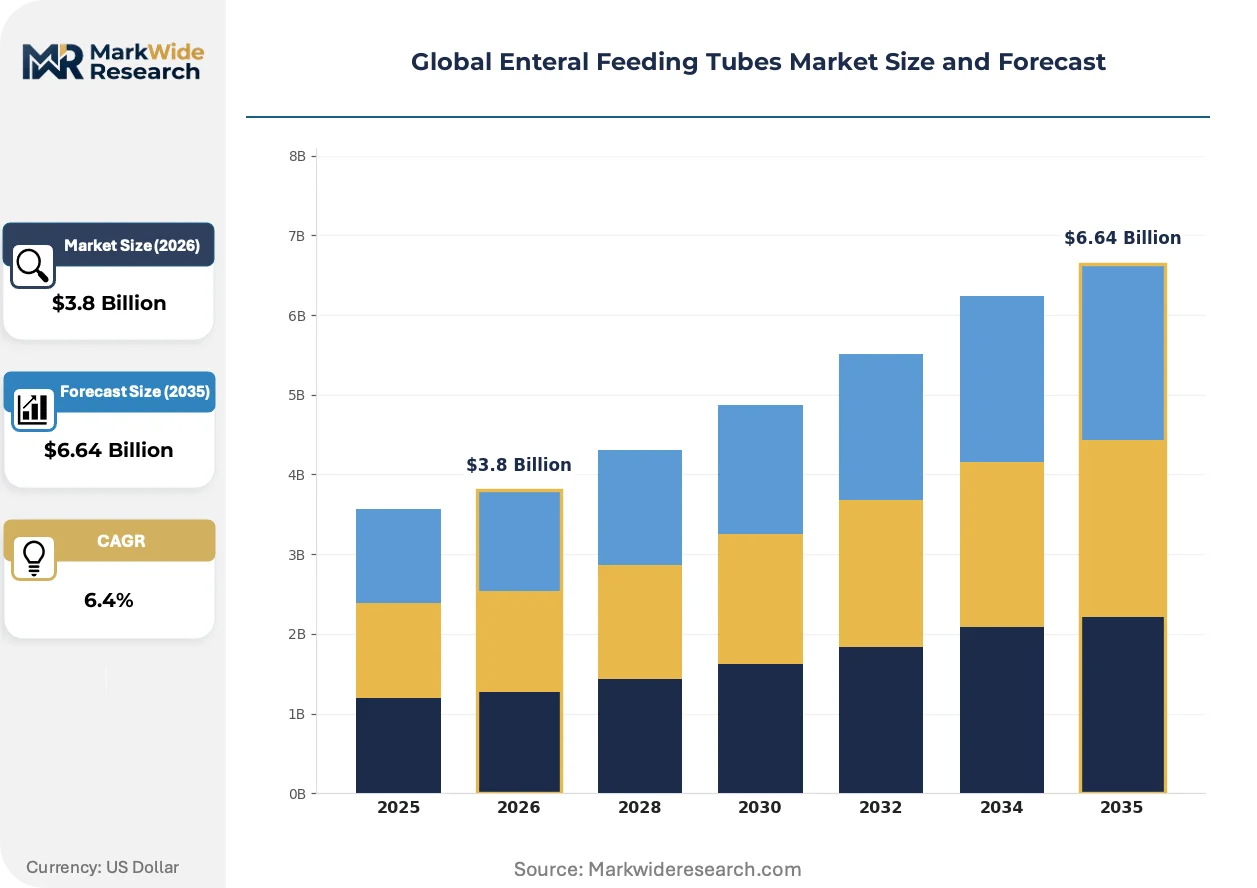
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasoenteric Tubes, Gastrostomy Tubes, Jejunostomy Tubes, Oroenteric Tubes Material: Polyurethane, Silicone, Polyvinyl Chloride, Latex Application: Malnutrition Management, Dysphagia, Neurological Disorders, Oncology Nutrition Support End User: Hospitals, Home Healthcare, Long-Term Care Facilities, Ambulatory Surgical Centers |
| Companies Covered | Fresenius Kabi, Cardinal Health, Avanos Medical, B. Braun, Boston Scientific, Cook Medical, Applied Medical Technology, Amsino International, ALCOR Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enteral Feeding Tubes Market Shifts & Advancements
Digital connectivity and material science advances are restructuring how enteral feeding tubes are monitored, replaced, and reimbursed across care settings. Three developments are compressing traditional procurement and clinical workflows.
Smart enteral feeding systems with embedded flow sensors and wireless transmission modules are virtualizing the traditional bedside monitoring infrastructure. Home healthcare agencies in the United States are piloting these connected devices to reduce nursing visit frequency for stable neurological patients. This virtualization is collapsing the distinction between acute and post-acute oversight models, enabling reimbursement codes previously restricted to institutional settings.
The EU Medical Device Regulation's notified body certification requirements for enteral access devices are extending market access timelines for non-European manufacturers. European hospital purchasing committees now prioritize suppliers with established CE-marked polymer traceability documentation. German and French procurement frameworks are responding by consolidating vendor panels around vertically integrated device-nutrition platforms.
Aftermarket service unbundling is separating device replacement cycles from formula supply contracts in United States home healthcare channels. Durable medical equipment suppliers are capturing maintenance revenue previously retained by hospital outpatient departments. This behavioral shift concentrates most visibly in Medicare Advantage plans expanding supplemental home health benefits for dysphagia management.
Global Enteral Feeding Tubes Market Segmentation
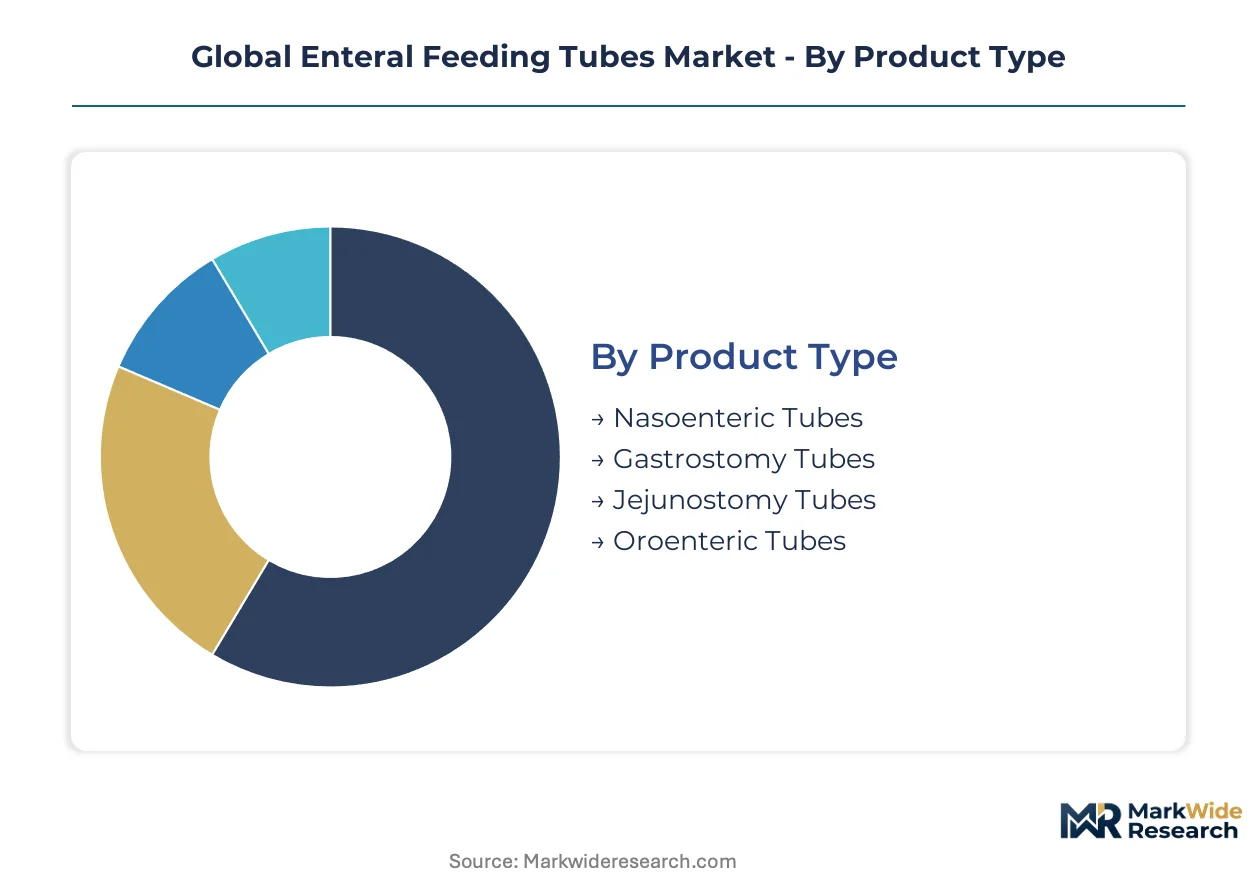
Enteral feeding tube procurement varies sharply across clinical settings, with replacement cycles, material specifications, and reimbursement pathways creating distinct commercial profiles for each segment. Understanding these dimensional splits enables suppliers to align manufacturing capacity with channel-specific demand patterns.
Product Type:
After-sales-service intensity diverges dramatically across tube categories, with percutaneous devices requiring scheduled replacement protocols and nasoenteric products demanding frequent nursing intervention for occlusion management.
- Gastrostomy Tubes:Percutaneous devices inserted through the abdominal wall into the stomach for long-term enteral access, typically featuring low-profile balloon or bumper retention mechanisms. Demand concentrates in United States home healthcare channels as Medicare Advantage plans expand supplemental benefits for neurological disorder patients requiring durable feeding access.
- Nasoenteric Tubes:Flexible catheters advanced through the nasal cavity into the stomach or small intestine, constructed with radiopaque lines for fluoroscopic placement verification. Germany's statutory health insurance frameworks now reimburse these devices for outpatient malnutrition management, shifting procurement from hospital purchasing to durable medical equipment suppliers.
- Jejunostomy Tubes:Surgical or endoscopically placed devices accessing the jejunum directly, bypassing gastric motility dysfunction.
- Oroenteric Tubes:Oral-route insertion devices for short-term enteral access when nasal passage is contraindicated.
Gastrostomy tubes hold the largest share; momentum sits with nasoenteric devices as home healthcare reimbursement expands.
Material:
Cost tier stratification separates premium polymer formulations from commodity alternatives, with thin-wall construction commanding price premiums proportional to flow-rate performance gains.
- Polyurethane:Thermoplastic elastomer enabling thin-wall construction with larger inner lumens at reduced outer diameters, minimizing tissue irritation while maintaining nutritional flow rates. Japan's PMDA has streamlined clinical evidence pathways for polyurethane PEG kits targeting elderly neurological populations, accelerating regulatory clearance timelines.
- Silicone:Platinum-cured elastomer offering superior biocompatibility and extended dwell times for long-term gastrostomy patients. Supply concentration in East Asian polymer manufacturing clusters exposes device producers to input cost volatility and logistics disruption risks.
- Polyvinyl Chloride:Rigid thermoplastic for short-term nasoenteric applications where cost sensitivity dominates procurement decisions.
- Latex:Natural rubber compound with limited contemporary use due to hypersensitivity concerns in institutional settings.
Silicone maintains the dominant installed base; polyurethane is climbing the fastest as thin-wall technology penetrates outpatient channels.
Application:
Volume concentration aligns with chronic disease prevalence and reimbursement generosity, creating divergent growth trajectories across therapeutic indications.
- Neurological Disorders:Enteral access for stroke, Parkinson's disease, and amyotrophic lateral sclerosis patients with progressive dysphagia. United States durable medical equipment channels are capturing replacement revenue for this population as hospital length-of-stay contracts compress.
- Dysphagia:Swallowing dysfunction management across acute and post-acute settings, spanning both temporary and permanent feeding access needs. German outpatient reimbursement expansion has shifted device procurement toward home healthcare suppliers serving stable patients outside institutional monitoring.
- Malnutrition Management:General nutritional support for patients with inadequate oral intake due to metabolic or gastrointestinal conditions.
- Oncology Nutrition Support:Specialized enteral access for head and neck cancer patients undergoing chemoradiation with treatment-induced mucositis.
Neurological disorders command the greatest volume; dysphagia applications show the steepest expansion trajectory as home healthcare infrastructure matures.
End User:
Customer type determines procurement methodology, with institutional purchasing committees negotiating volume contracts while home healthcare channels prioritize logistics reliability and patient training support.
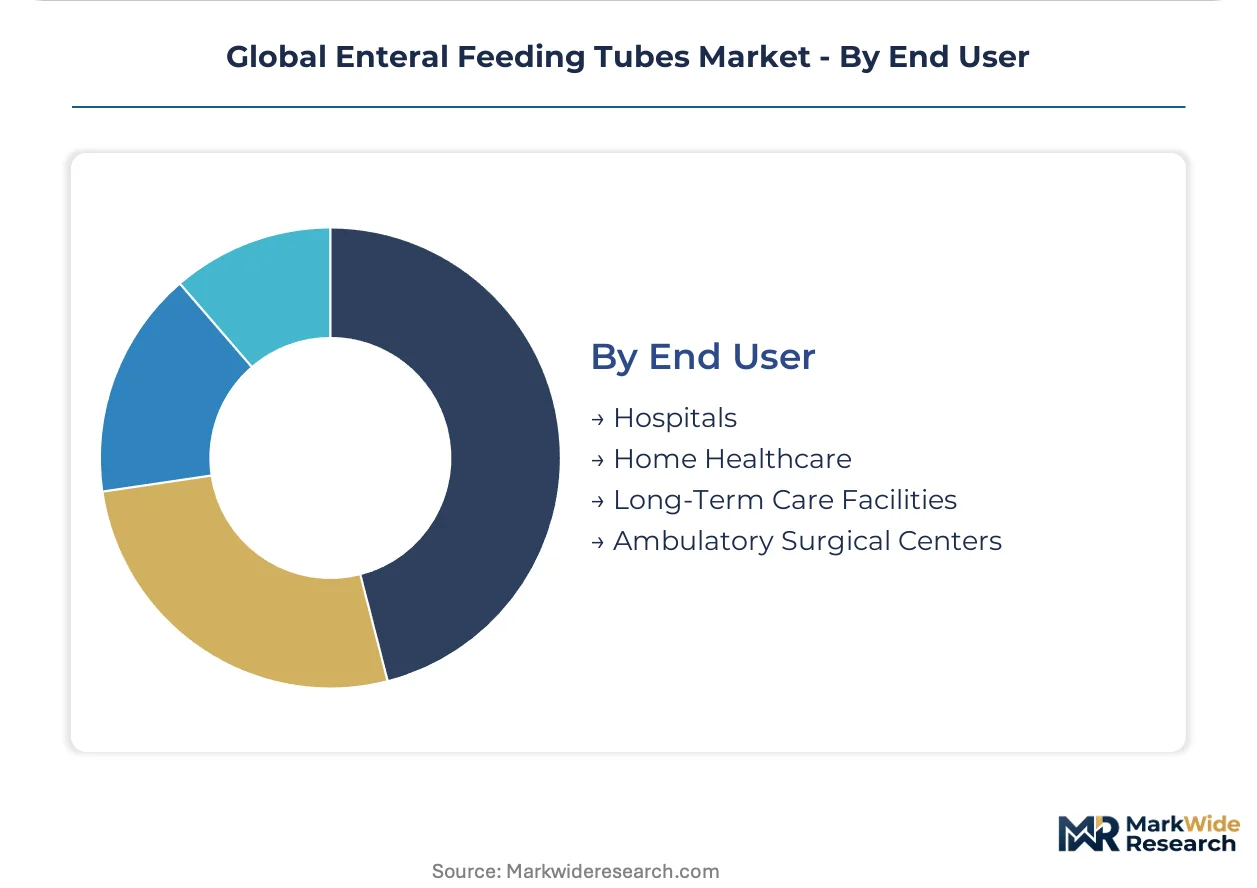
- Home Healthcare:Outpatient enteral nutrition services delivered through durable medical equipment suppliers and visiting nurse agencies. United States reimbursement code expansion for home-based enteral therapy is accelerating replacement cycle frequency outside institutional settings.
- Hospitals:Acute-care facilities performing initial tube placement and managing inpatient nutritional support. Japan's tertiary academic medical centers concentrate interventional radiology expertise for fluoroscopic-guided placement, limiting service expansion to these institutional hubs.
- Long-Term Care Facilities:Skilled nursing facilities managing stable enteral patients with established feeding protocols.
- Ambulatory Surgical Centers:Outpatient surgical settings performing elective percutaneous endoscopic gastrostomy procedures.
Hospitals retain the largest procurement volume; home healthcare is gaining share fastest as reimbursement frameworks shift toward outpatient nutrition management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers prioritize reimbursement reliability over unit cost, while German procurement committees negotiate aggressively on polymer specifications. Japanese purchasers accept premium pricing for PMDA-validated devices.
United States
Medicare Advantage plans are expanding supplemental home health benefits for dysphagia patients, accelerating replacement cycle frequency outside hospitals. The FDA enforces ISO 10993 biocompatibility testing and medical device quality system regulations for polymer traceability. Device distribution concentrates in durable medical equipment channels across the Southeast and Midwest, where hospital length-of-stay compression is most pronounced.
Germany
Statutory health insurance frameworks now reimburse home-based enteral nutrition therapy, shifting procurement from hospital purchasing committees to outpatient suppliers. The EU Medical Device Regulation requires notified body certification for enteral access devices sold in European markets. Manufacturing and distribution clusters in North Rhine-Westphalia and Bavaria are consolidating vendor panels around vertically integrated device-nutrition platforms.
Japan
Elderly neurological populations are driving demand for percutaneous endoscopic gastrostomy kits with streamlined regulatory pathways. The PMDA mandates clinical evidence submissions for novel PEG devices, creating differentiated market access timelines. Tertiary academic medical centers in Tokyo and Osaka concentrate interventional radiology expertise for fluoroscopic-guided placement, limiting service expansion to these institutional hubs.
China
Domestic manufacturers are capturing share in short-term nasoenteric segments where cost sensitivity dominates procurement decisions. The NMPA enforces medical device registration and quality management system requirements for polymer-based feeding tubes. Production gravity centers on Yangtze River Delta polymer manufacturing clusters, exposing device producers to input cost volatility and logistics disruption risks.
United Kingdom
NHS procurement frameworks are unbundling device replacement cycles from formula supply contracts in home healthcare channels. The MHRA operates under retained EU MDR alignment for medical device market authorization. Distribution infrastructure in London and the Southeast is capturing maintenance revenue previously retained by hospital outpatient departments.
Global Enteral Feeding Tubes Market Competitive Landscape
Vertically integrated nutrition platforms and specialized enteral access technology developers split the market between formula-device bundling and standalone device innovation. The vendor base concentrates around three strategic archetypes: diversified healthcare conglomerates with nutrition portfolios, pure-play enteral device specialists, and regional polymer fabrication houses. Dominant competitive moves include backward integration into medical-grade silicone supply chains and technology licensing partnerships for anti-microbial coating convergence.
Within the diversified healthcare tier, Fresenius Kabi and Cardinal Health exemplify archetypes of formula-device vertical integration and broad distribution infrastructure respectively. Avanos Medical occupies a specialist position in low-profile gastrostomy device design. These three anchors illustrate how competitive positioning diverges between controlling upstream nutrition supply chains versus capturing downstream home healthcare channel access.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Cardinal Health |
| Avanos Medical |
| B. Braun |
| Boston Scientific |
| Cook Medical |
| Applied Medical Technology |
| Amsino International |
| ALCOR Scientific |
| Others |
Supply & Pricing Matrix
Yangtze River Delta polymer manufacturing clusters concentrate medical-grade silicone and polyurethane resin capacity, translating upstream feedstock scarcity into asymmetric pricing power for device producers serving United States and German hospital purchasing committees. This geographic concentration forces downstream buyers into long-term offtake contracts with limited spot-market alternatives, embedding cost volatility into durable medical equipment channel procurement.
Pricing Analysis
Aftermarket service revenue from scheduled replacement cycles and occlusion management protocols drives lifetime value capture beyond initial device placement. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and after-sales bundling intensity. Pricing pressure stems from Medicare Advantage plan reimbursement compression in United States home healthcare channels. Hospital purchasing committees exhibit lowest price sensitivity due to bundled formula-device contracts, while durable medical equipment suppliers face acute margin compression from unbundled procurement frameworks.
Supply Chain Analysis
Medical-grade silicone and thermoplastic polyurethane feedstock production clusters in China, South Korea, and Japan, with platinum-cured elastomer processing concentrated in East Asian polymer fabrication facilities. Device assembly draws from radiopaque line suppliers in Germany, polymer extrusion equipment in Italy, and sterilization packaging from United States medical film producers. Single-source vulnerability in East Asian silicone resin supply exposes producers to logistics disruption from regional port congestion. Distribution runs through hospital purchasing committees for acute placement, durable medical equipment suppliers for outpatient replacement, and long-term care facility group purchasing organizations for institutional maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in home healthcare channel expansion as reimbursement unbundling separates device replacement from formula supply, creating niche entry points for specialized enteral access technology developers.
For Market Incumbents: Insulate market position through backward integration into medical-grade silicone supply chains and captive production of thin-wall polyurethane formulations. Threat from emerging anti-microbial coating specialists demands accelerated R&D investment in silver-ion polymer integration. Priority lever sits with hospital system partnership consolidation to lock in placement volume before durable medical equipment channel capture accelerates. For New Entrants and Emerging Players: United Kingdom NHS procurement unbundling offers the most penetrable white space for standalone device distribution without formula bundling requirements. Target telehealth-integrated flow monitoring systems for neurological disorder patients in Medicare Advantage plans as the fastest-expanding application segment. Go-to-market angle should emphasize nursing visit reduction metrics to align with home healthcare agency cost-containment priorities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized enteral access developers with PMDA-validated polyurethane PEG kits over diversified nutrition platforms facing margin compression. Long-term viability window favors acquisition targets with established CE-marked polymer traceability documentation under EU MDR requirements. Signal to watch is Japan PMDA accelerated pathway expansion for elderly neurological indications as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Anti-Microbial Coating Convergence | Silver-ion polymer integration reduces biofilm formation and extends replacement intervals for home healthcare patients. |
| Telehealth-Integrated Monitoring Development | Wireless flow-rate sensing enables CMS reimbursement code capture previously restricted to institutional settings. |
| EU MDR Certification Investment | Notified body polymer traceability documentation secures German and French hospital purchasing committee inclusion. |
| Home Healthcare Channel Partnership | Durable medical equipment supplier alliances capture replacement revenue from hospital outpatient department unbundling. |
| Thin-Wall Polyurethane Scale-Up | Japanese PMDA streamlined pathways accelerate market access for elderly neurological population targeting. |
Research Methodology
The analysis maps enteral access device categories, material formulation tiers, and reimbursement channel pathways, each validated through hospital purchasing committee directors, home healthcare agency procurement managers, biomedical engineers, and GPO contracts specialists. Primary interview intelligence combined with FDA 510(k) filings, EU MDR notified body certification databases, CMS Medicare reimbursement code schedules, and Japanese PMDA clinical evidence submission records. Bottom-up volume triangulation across product type, material, application, and end user segments cross-checked against top-down market sizing from polymer feedstock demand modeling.
Assumption sets held reimbursement framework evolution and regulatory pathway timelines as fixed boundary conditions while varying home healthcare penetration rates and replacement cycle frequency parameters across the projection horizon. Segmentation dimensions modeled include product type, material formulation, therapeutic application, and end user channel, with regional regulatory cluster effects embedded as interaction terms. CAGRs derived from installed base growth plus replacement cycle velocity, incorporating PMDA pathway acceleration effects and Medicare Advantage benefit expansion as industry-specific demand drivers.
Practitioners should monitor FDA biocompatibility testing timeline extensions and East Asian polymer logistics disruption indices for early signals of forecast revision. Cross-checking against Japanese Ministry of Health enteral nutrition reimbursement statistics and German statutory health insurance outpatient coverage expansion reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Mexico Ophthalmic Devices Market
Medical Devices
Jet Nebulizers Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Global Medical Sensor Market
Medical Devices
Global Nebuliser Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Capnography Devices Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
India Static Compression Therapy Market