
 Myotonic Dystrophy Treatment Market | 2026-2036
Myotonic Dystrophy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Myotonic Dystrophy Treatment Market Foresight
Buyer concentration among academic medical centers and neuromuscular specialty clinics is repositioning procurement patterns toward integrated care contracts rather than standalone drug purchasing. Sun Pharma leverages its generic manufacturing scale to supply cost-conscious hospital systems across multiple continents. Avidity Biosciences anchors its competitive stance through antibody-oligonucleotide conjugate technology purpose-built for muscle tissue delivery. Dyne Therapeutics differentiates via its FORCE platform designed to overcome myotonic dystrophy type 1 cellular trafficking barriers.
Myotonic dystrophy treatment encompasses therapeutic interventions targeting the autosomal dominant multisystem disorder characterized by CTG trinucleotide repeat expansion in the DMPK gene, with modalities spanning small molecules that modulate alternative splicing, antisense oligonucleotides that sequester toxic RNA, and emerging gene editing approaches intended to correct the underlying genetic defect. The primary purpose across all modalities remains the restoration of normal muscle function and mitigation of cardiac, respiratory, and central nervous system complications. Small molecules currently dominate commercial revenue due to established manufacturing infrastructure and oral bioavailability, while antisense oligonucleotides represent the fastest-expanding development category driven by clinical proof-of-concept in splice correction. Gene therapy occupies a pre-commercial position with substantial margin potential contingent on durable expression in skeletal and cardiac muscle tissues.
The FDA orphan drug program and EMA's Committee for Orphan Medicinal Products collectively shape development incentives through tax credits, protocol assistance, and market exclusivity provisions that reduce financial risk for sponsors targeting myotonic dystrophy's limited patient population. REACH compliance in Europe and ongoing EPA oversight of oligonucleotide manufacturing waste streams further constrain production geography and facility investment decisions. Stakeholders must monitor regulatory divergence between FDA accelerated approval pathways and EMA conditional marketing authorization requirements when designing pivotal trial strategies.
Market Dynamics
RNA-targeted therapeutic platforms are restructuring competitive boundaries by enabling direct intervention against toxic repeat expansions, forcing established small-molecule developers to accelerate splice-modulator pipelines or risk displacement in inherited myopathy care.
Growth Catalysts
- Orphan Drug Incentives:The FDA's tax credit and protocol assistance provisions reduce clinical trial cost burdens for sponsors targeting myotonic dystrophy's limited patient population. Sponsors leverage this framework to advance first-in-class antisense candidates through accelerated timelines.
- Academic Medical Center Concentration:United States-based neuromuscular specialty clinics are expanding dedicated myotonic dystrophy programs, creating concentrated demand nodes that attract therapeutic developers. These centers generate natural history data essential for regulatory submissions.
- Antibody-Oligonucleotide Conjugation:Muscle-targeted delivery technology is resolving prior biodistribution limitations that constrained systemic antisense efficacy. Developers are achieving functional splice correction in skeletal tissue at lower dose exposures.
Market Restraints
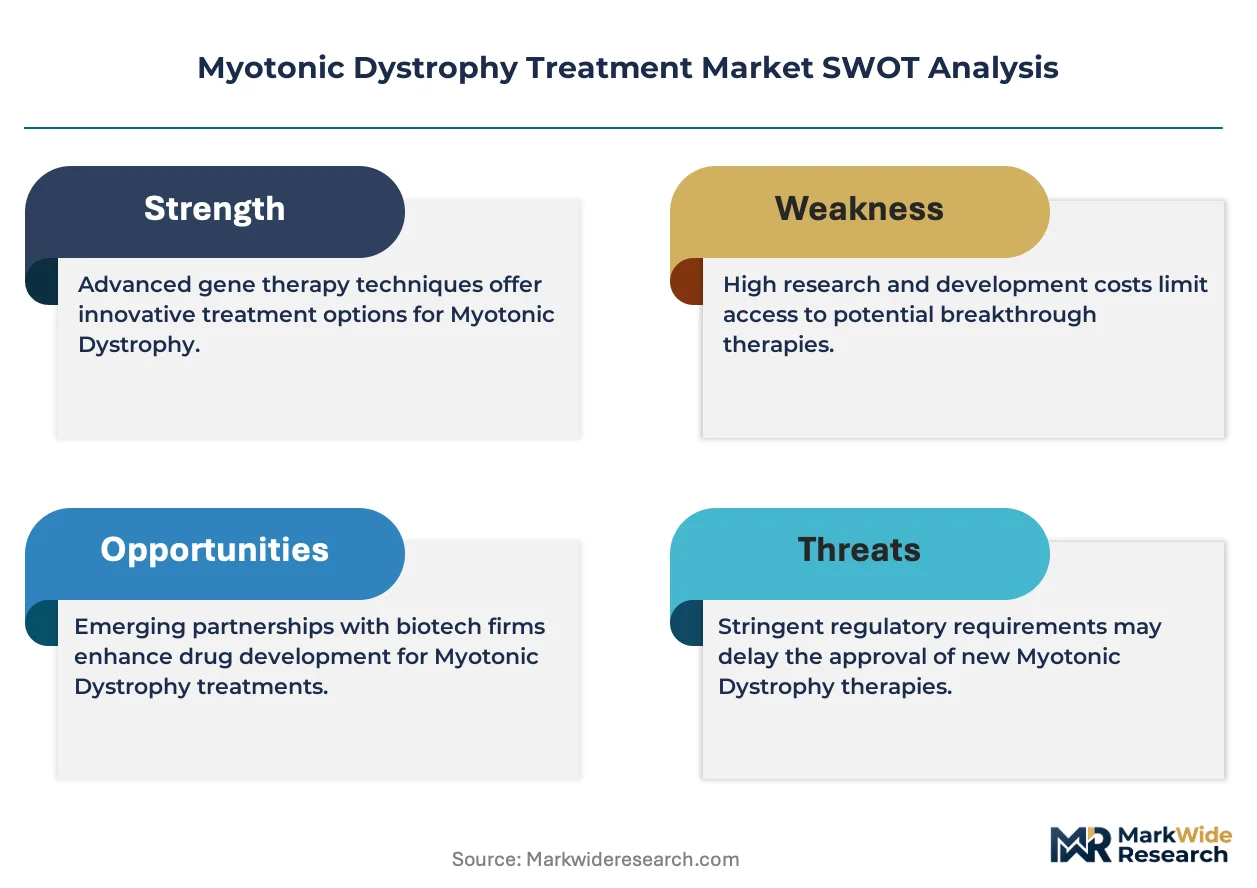
- Oligonucleotide Manufacturing Concentration:Commercial-scale synthesis capacity for phosphorothioate backbones concentrates among a limited supplier base in North America and Europe. Capacity constraints extend lead times for clinical-grade material.
- EPA Waste Stream Oversight:Oligonucleotide production generates acetonitrile and phosphorus-containing waste streams subject to federal environmental enforcement. Facility siting decisions must incorporate tertiary treatment infrastructure costs.
- Diagnostic Latency:Mean time from symptom onset to genetic confirmation exceeds five years in non-specialist care settings. Delayed identification compresses the addressable treated population and extends trial recruitment cycles.
Strategic Opportunities
- Cardiac Phenotype Addressability:Arrhythmia and conduction system complications represent an emerging application with limited current therapeutic options. Developers targeting cardiac muscle delivery could capture differentiated positioning.
- EMA Conditional Marketing Authorization:European regulators permit approval based on surrogate endpoints in ultra-rare indications. Sponsors can secure revenue-generating market access prior to completion of long-term functional outcome studies.
- Integrated Care Contracting:Neuromuscular specialty clinics are consolidating procurement through multi-year agreements spanning genetic testing, therapeutic administration, and monitoring. Manufacturers can secure volume commitments through outcome-linked pricing structures.
Industry Challenges
- Biomarker Qualification:Regulatory acceptance of splice biomarkers as surrogate endpoints requires extensive natural history validation. Sponsors face extended timelines to establish biomarker-disease progression correlations acceptable to FDA and EMA reviewers.
- Cross-Functional Talent Scarcity:Development teams require integration of oligonucleotide chemistry, muscle biology, and rare disease clinical operations. Competition for experienced translational scientists intensifies as multiple platforms advance simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myotonic Dystrophy Treatment Market |
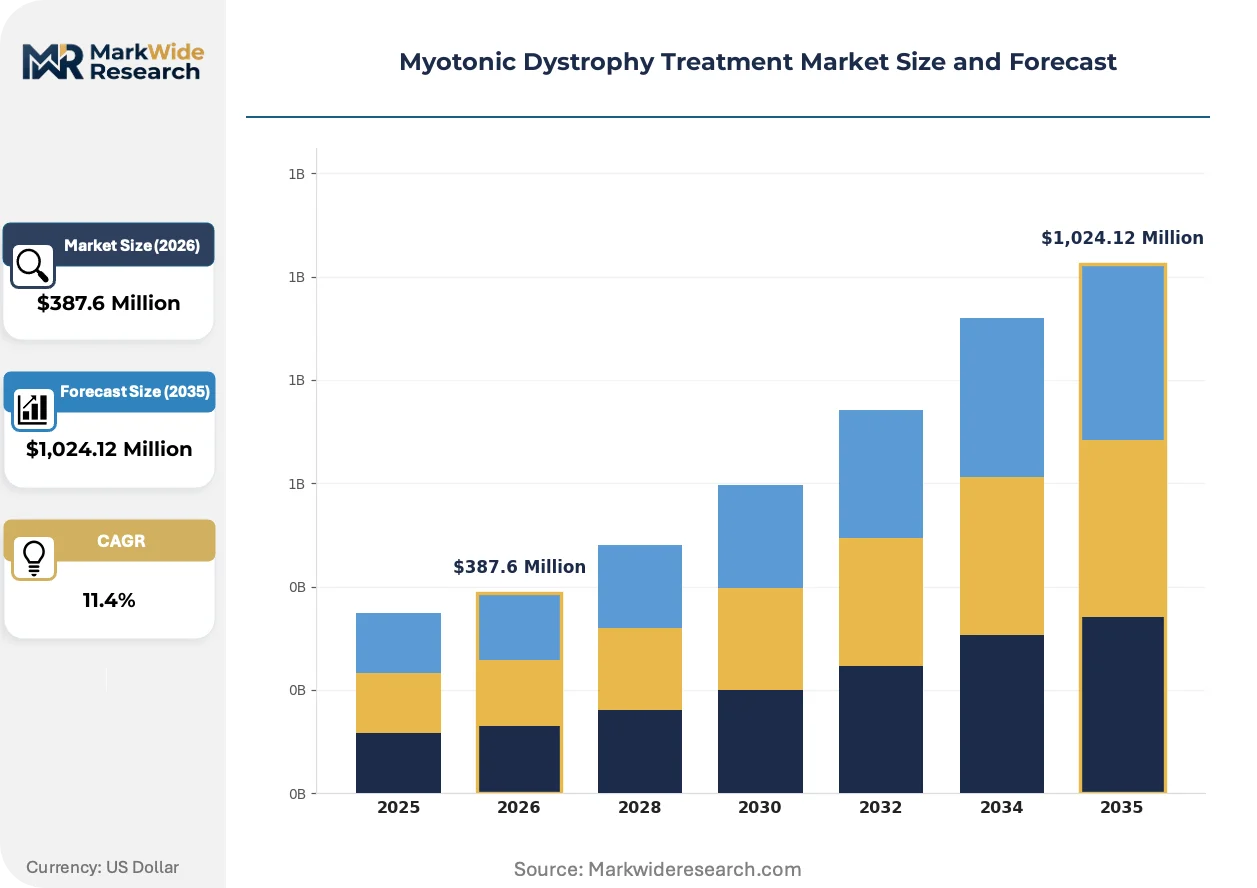
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Gene Therapy, Antisense Oligonucleotides, RNA Modulators Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Homecare Settings, Research Institutions Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Specialty Pharmacy |
| Companies Covered | Sun Pharma, Mylan, Lupin, Avidity Biosciences, Mallinckrodt, Teva Pharmaceutical Industries Ltd., ANI Pharmaceuticals, Dyne Therapeutics, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myotonic Dystrophy Treatment Market Shifts & Advancements
Antisense oligonucleotide platforms are displacing small-molecule splice modulators as the dominant development modality, while regulatory frameworks adapt to accommodate gene-targeted therapeutics and procurement patterns consolidate around specialized care networks.
Antibody-oligonucleotide conjugate technology is consolidating delivery precision for muscle tissue targeting. Neuromuscular specialty clinics in the United States are prioritizing these platforms for their expanded patient intake programs. The technology is consolidating competitive advantage around tissue-specific biodistribution that reduces systemic exposure requirements.
REACH compliance in Europe is mandating substitution assessments for hazardous substances in oligonucleotide manufacturing processes. European production facilities are retrofitting solvent recovery systems to meet ECHA registration thresholds. Contract manufacturers with integrated waste treatment capabilities are capturing preferential positioning for EMA-bound supply chains.
Hospital systems are unbundling after-sales monitoring from therapeutic procurement, creating separate contracting streams for genetic counseling and cardiac surveillance. Neuromuscular specialty clinics in Germany and France are piloting this separation to optimize reimbursement capture. Academic medical centers in the United States are following this model to align with value-based care mandates.
Myotonic Dystrophy Treatment Market Segmentation
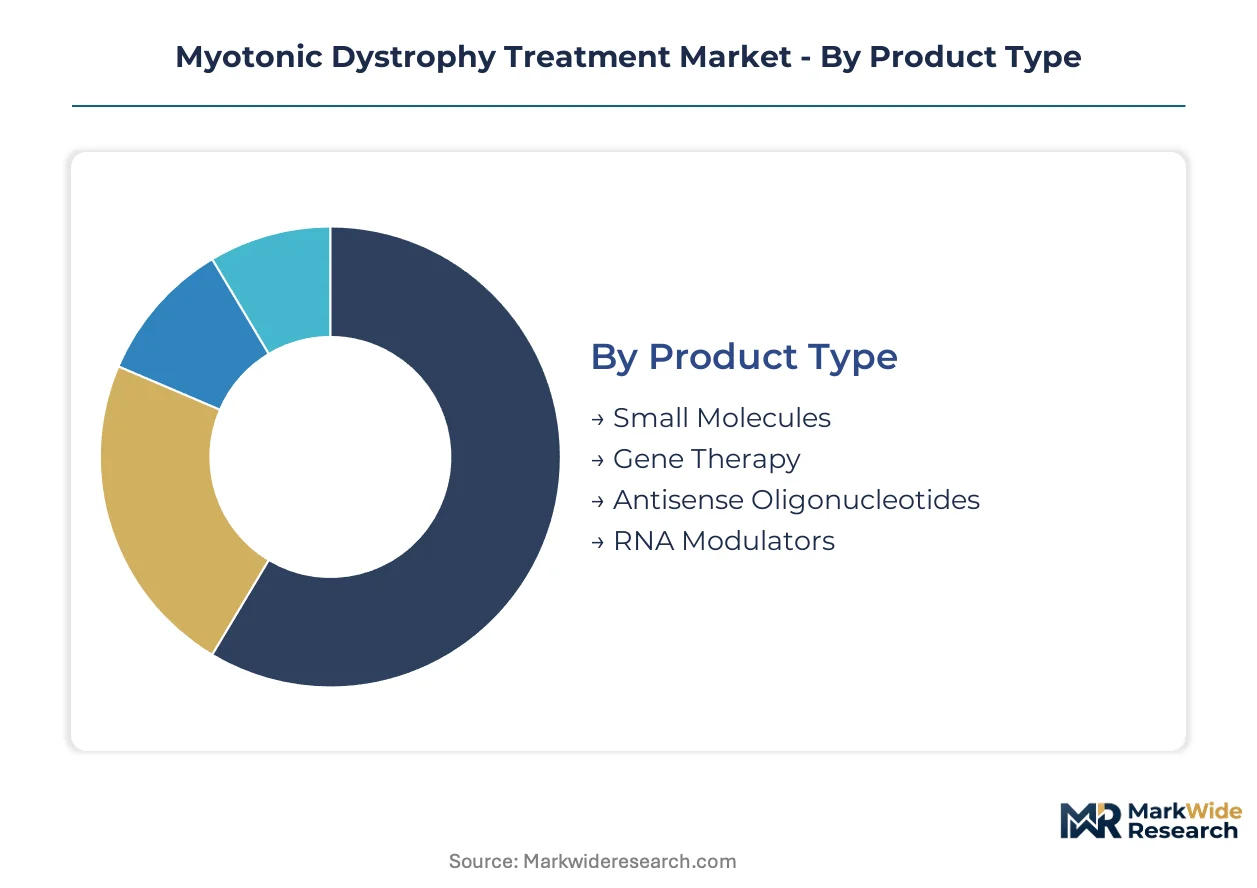
Segmentation in myotonic dystrophy treatment reveals how therapeutic modality, delivery mechanism, and care setting interact to determine commercial viability. Each dimension carries distinct regulatory, reimbursement, and operational implications for developers and healthcare providers.
Product Type:
Standalone therapeutic platforms operate independently of companion diagnostics, while emerging modalities require integrated genetic testing infrastructure to identify eligible patients.
- Small Molecules:Oral bioavailability and established manufacturing infrastructure position these agents as the current revenue foundation. Demand concentrates in United States hospital systems seeking cost-effective maintenance therapy for cardiac and respiratory symptoms.
- Antisense Oligonucleotides:Phosphorothioate-modified sequences sequester toxic CUG repeat RNA to restore normal splicing patterns. United States academic medical centers with dedicated myotonic dystrophy programs are prioritizing these candidates for their expanded patient intake initiatives.
- Gene Therapy:Viral vector delivery of corrected DMPK sequences remains pre-commercial with substantial margin potential contingent on durable expression.
- RNA Modulators:Small-molecule approaches targeting RNA structure offer oral administration with splice-correcting mechanism.
Small molecules lead volumes today; antisense oligonucleotides are gaining share fastest.
Administration Route:
Route selection determines site-of-care requirements, with hospital-based infusion carrying higher reimbursement capture versus self-administered alternatives.
- Oral:Self-administered small molecules and RNA modulators enable home-based management without specialized infusion infrastructure.
- Intravenous:Systemic delivery of antisense constructs requires hospital or infusion center presence with cardiac monitoring capability.
- Subcutaneous:Antibody-oligonucleotide conjugates with enhanced tissue penetration are shifting toward subcutaneous administration to reduce site-of-care burden.
- Intramuscular:Direct injection into affected muscle groups targets localized gene expression with limited systemic exposure.
Intravenous administration dominates current clinical practice; subcutaneous delivery is climbing the fastest as conjugate technology matures.
End User:
Care setting segmentation tracks the consolidation of myotonic dystrophy management into specialized centers versus distributed community practice.
- Hospitals:Academic medical centers with neuromuscular specialty programs generate natural history data and serve as trial recruitment hubs.
- Clinics:Dedicated neuromuscular specialty clinics in Germany and France are piloting unbundled contracting for genetic counseling and therapeutic administration.
- Homecare Settings:Remote monitoring infrastructure enables cardiac surveillance and respiratory support outside institutional settings.
- Research Institutions:Sponsored investigation sites concentrate in United States locations with FDA orphan drug protocol assistance relationships.
Hospitals anchor current therapeutic volumes; clinics are expanding most quickly through integrated care contracting.
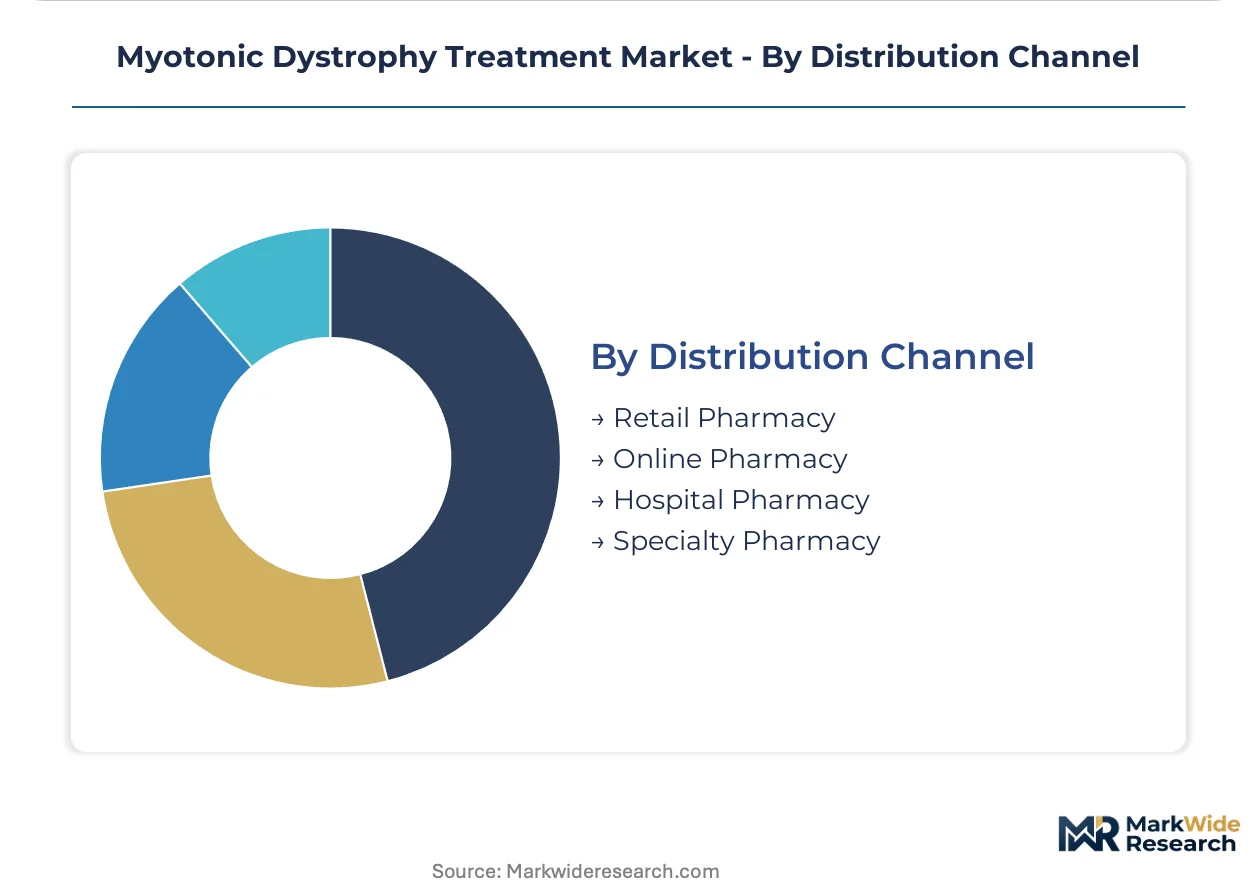
Distribution Channel:
Channel structure reflects the intersection of specialty handling requirements for oligonucleotides with patient access convenience demands.
- Specialty Pharmacy:Temperature-controlled logistics and patient support programs for complex parenteral therapies concentrate distribution through limited networks.
- Hospital Pharmacy:In-house procurement for infusion-administered antisense agents captures institutional reimbursement margins.
- Retail Pharmacy:Oral small molecules distribute through standard community pharmacy networks with limited specialty service requirements.
- Online Pharmacy:Direct-to-patient delivery models are emerging for stable oral formulations with established safety profiles.
Specialty pharmacy leads channel volumes today; hospital pharmacy is advancing fastest through integrated care contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates more neuromuscular specialty capacity than any other single country, while Germany builds comparable clinical infrastructure through university hospital networks. Patient identification rates and regulatory pathway sophistication create divergent commercial timelines across major markets.
United States
Academic medical centers in Boston, Baltimore, and Rochester maintain dedicated myotonic dystrophy programs that generate natural history data for regulatory submissions. FDA orphan drug tax credits reduce clinical trial cost burdens for sponsors targeting the limited patient population. The National Institutes of Health supports research consortia at institutions including the University of Florida and University of Rochester.
Germany
University hospitals in Munich and Heidelberg operate integrated neuromuscular centers with genetic counseling and cardiac surveillance capabilities. REACH compliance mandates substitution assessments for hazardous substances in oligonucleotide manufacturing processes. The Charité hospital network in Berlin coordinates multi-site natural history studies essential for EMA submissions.
France
Reference centers for neuromuscular diseases in Paris and Lyon consolidate patient intake through the FILNEMUS network. ANSM provides protocol assistance for ultra-rare indication trials under the EMA framework. The Institut de Myologie in Paris anchors translational research partnerships with commercial developers.
United Kingdom
NHS England's specialized commissioning framework routes myotonic dystrophy patients to designated neuromuscular centers in London, Oxford, and Newcastle. The MHRA operates aligned with EMA conditional marketing authorization pathways for surrogate endpoint approvals. The Newcastle upon Tyne Hospitals NHS Foundation Trust maintains longitudinal patient registries.
Switzerland
University hospitals in Zurich and Geneva serve as referral hubs for alpine-region patients with complex cardiac phenotypes. Swissmedic coordinates with EMA procedures while maintaining distinct national authorization timelines. The Swiss Neuromuscular Research Network links clinical centers in Basel and Lausanne to academic research programs.
Myotonic Dystrophy Treatment Market Competitive Landscape
United States-based biotechnology firms anchor the novel therapeutic tier; Indian and Israeli pharmaceutical manufacturers hold established positions in cost-conscious supply. The competitive structure stratifies across three tiers: large-cap diversified pharmaceutical companies with neuromuscular portfolios, mid-cap specialists advancing RNA-targeted platforms, and generic manufacturers supplying symptomatic management agents. Strategic moves concentrate on antibody-oligonucleotide conjugation partnerships and integrated care contracting with academic medical centers.
Within the RNA-targeted specialist tier, Avidity Biosciences and Dyne Therapeutics exemplify platform-driven competitive positioning. Sun Pharma occupies a position among generic manufacturers supplying hospital systems across multiple continents. These three companies represent distinct archetypes: conjugate technology developers, force-platform specialists, and scale-driven generic suppliers respectively.
| Leading Market Players |
|---|
| Sun Pharma |
| Mylan |
| Lupin |
| Avidity Biosciences |
| Mallinckrodt |
| Teva Pharmaceutical Industries Ltd. |
| ANI Pharmaceuticals |
| Dyne Therapeutics |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Phosphorothioate chemistry specialists in Switzerland and Massachusetts command wage premiums that widen spreads between clinical-grade antisense tiers and commoditized small-molecule alternatives. Labor-cost differentials between European contract manufacturers and Indian generic suppliers translate into three-tier pricing structure across premium, standard, and economy levels for myotonic dystrophy therapeutics.
Pricing Analysis
Capacity additions in South Korea and Singapore are reshaping price floors for phosphoramidite reagents used in antisense backbone synthesis. Pricing stratifies across premium, standard, and economy tiers based on cGMP certification level and volume commitment scale. Cost compression in the standard tier is intensifying because hospital systems are consolidating procurement through multi-year integrated care contracts. Academic medical centers in the United States demonstrate the least price sensitivity due to orphan drug reimbursement carve-outs, while community hospital systems in emerging markets exhibit highest sensitivity to per-dose acquisition costs.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA reviewers mandate multi-supplier qualification for critical oligonucleotide starting materials. Manufacturing concentrates in Switzerland, Germany, and the United States for clinical-grade phosphorothioate synthesis, while India and China anchor supply of small-molecule intermediates. Raw material dependencies center on acetonitrile solvents, phosphorus pentasulfide, and nucleoside phosphoramidites. Single-source vulnerability persists for rare modified nucleosides protected by process patents. Distribution runs through specialty pharmacy networks with cold-chain logistics for parenteral antisense formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in myotonic dystrophy therapeutics rests on manufacturing scale-down in oligonucleotide synthesis and premium-tier capture through antibody-oligonucleotide conjugate positioning.
For Market Incumbents: Anchor market position through backward integration into phosphoramidite manufacturing and exclusive supply agreements with United States academic medical centers. RNA-targeted platforms from Avidity Biosciences and Dyne Therapeutics threaten displacement of small-molecule maintenance therapies. Capacity addition in Singapore or South Korea offers cost-down leverage against European manufacturing premiums. For New Entrants and Emerging Players: Launch via subcutaneous delivery partnerships with German university hospital networks seeking to reduce infusion center burden. Cardiac phenotype addressability represents the most penetrable application white-space, with limited current therapeutic options for arrhythmia management. Target EMA conditional marketing authorization pathway to secure revenue-generating European market access ahead of long-term functional outcome completion. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap RNA-targeted specialists with validated muscle delivery platforms but pre-revenue clinical assets. Long-term viability over the next decade hinges on biomarker qualification success and durable splice correction demonstration. Watch FDA acceptance of splice biomarkers as surrogate endpoints as the inflection signal for accelerated approval timelines and valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Antibody-Oligonucleotide Conjugate Partnership | Muscle-targeted delivery resolves prior biodistribution limitations for antisense efficacy in skeletal tissue. |
| EMA Conditional Marketing Authorization Pursuit | Surrogate endpoint approval enables European revenue generation prior to long-term functional studies completion. |
| Integrated Care Contracting with Academic Centers | Multi-year agreements spanning genetic testing and therapeutic administration secure volume commitments. |
| Phosphoramidite Manufacturing Scale-Up | In-house production of oligonucleotide starting materials reduces dependency on limited European supplier base. |
| Cardiac Delivery Platform Development | Arrhythmia and conduction system complications offer differentiated positioning with limited current options. |
Research Methodology
Bottom-up neuromuscular specialty clinic modeling reconciled against top-down oligonucleotide manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads at FDA and EMA, hospital procurement managers, and payer access specialists were validated against secondary sources including FDA orphan drug filings, EMA submission documents, ClinicalTrials.gov records, and hospital formulary databases. Triangulation between demand-side patient intake projections and supply-side synthesis capacity constraints ensures consistency across the analysis window.
Input-output matrices mapped therapeutic modality adoption against administration route preferences and care setting consolidation patterns. Segmentation dimensions modeled include treatment line, administration route, end-user setting, and regional regulatory cluster. CAGRs were derived from patient population growth, diagnostic latency reduction assumptions, and therapy penetration curves across academic versus community care settings. Forecast inputs incorporated FDA protocol assistance timelines, EMA conditional authorization pathways, and specialty pharmacy distribution capacity expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence between FDA accelerated approval and EMA conditional marketing authorization requirements. Forecasts reflect assumptions regarding biomarker qualification timelines, manufacturing scale-up success, and integrated care contract adoption rates. Deviation in splice biomarker regulatory acceptance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Single Dose Radiotherapy Services Market