
 Global Image-Guided Radiation Therapy (IGRT) Market | 2026-2036
Global Image-Guided Radiation Therapy (IGRT) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Image-Guided Radiation Therapy (IGRT) Market Foresight
The divergence between premium MRI-guided units and commodity X-ray based devices is hardening as reimbursement thresholds tighten. Siemens Healthineers leverages its installed base of linear accelerators to bundle imaging upgrades. Elekta sustains R&D intensity in adaptive delivery software. Accuray differentiates through compact gantry designs that reduce vault construction costs.
Image-guided radiation therapy integrates real-time anatomical imaging with beam delivery to correct for patient motion and tumor deformation during treatment sessions, typically achieving sub-millimeter positioning accuracy through stereoscopic X-ray or volumetric MRI verification. CT-based systems occupy the largest installed base due to lower capital requirements and faster workflow integration, while MRI-guided units represent the fastest-growing product category as soft-tissue contrast enables online adaptive planning for abdominal and pelvic malignancies. Among application areas, prostate cancer commands the deepest margin pools because fractionation protocols favor daily imaging, whereas lung cancer segments expand with motion-management protocols for stereotactic body radiation therapy.
FDA premarket notification requirements and EU MDR technical documentation obligations shape hardware validation timelines and software algorithm lockdowns, while IEC 60601-2-68 standards govern electromagnetic compatibility for imaging-beam integration. Japan's PMDA enforces distinct clinical evidence thresholds for adaptive therapy claims that delay entry for non-domestic manufacturers. Stakeholders must monitor whether CMS reimbursement codes for adaptive planning will expand beyond proton centers to photon-based MRI-guided installations.
Market Dynamics
Adaptive planning workflows are compressing treatment margins and forcing hardware vendors to bundle software subscriptions with linear accelerator sales, restructuring how procurement committees evaluate total cost of ownership across fifteen-year equipment lifecycles.
Growth Catalysts
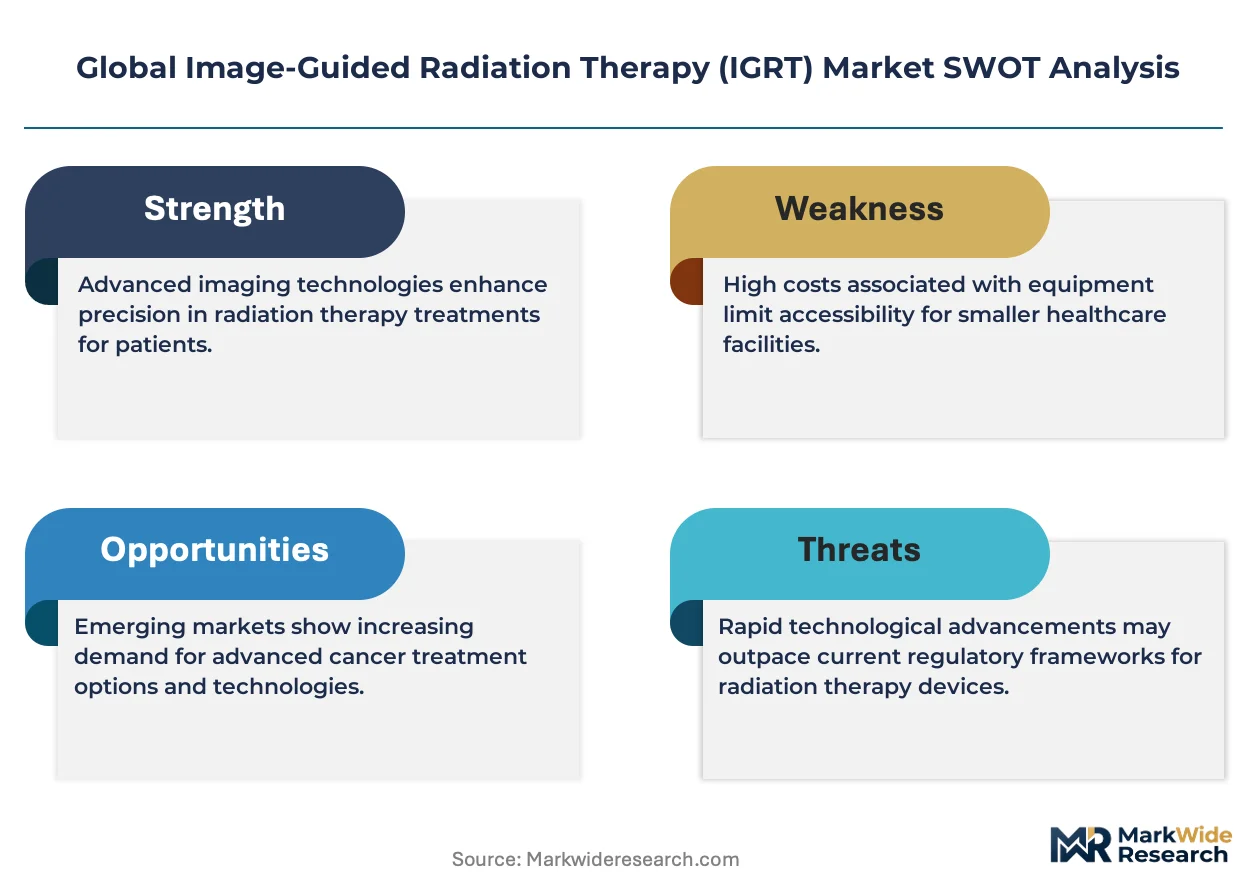
- EU MDR certification pathways:Streamlined technical documentation for MRI-guided systems accelerates hospital procurement cycles in Germany and France, reducing validation timelines for integrated imaging-beam platforms.
- Prostate cancer fractionation protocols:Daily imaging mandates in curative regimens sustain replacement demand for aging CT-based units at academic medical centers in the United States.
- Vault construction cost reduction:Compact gantry designs shrink shielding requirements, enabling installation in repurposed clinical spaces previously unsuitable for radiation oncology.
Market Restraints
- Superconducting magnet supply concentration:Cryogenic component fabrication concentrates among Japanese and European specialty suppliers, exposing OEMs to helium price volatility and export license delays.
- IEC 60601-2-68 electromagnetic compatibility testing:Validation protocols for imaging-beam integration extend development cycles and lock software algorithms months before commercial release.
- Proton therapy substitution threat:Bragg peak physics enables margin reduction without daily imaging, diverting capital budgets from photon-based IGRT at premium cancer centers.
Strategic Opportunities
- India's hospital infrastructure expansion:Private oncology chains in Mumbai and Delhi seek refurbished linear accelerators with retrofit imaging kits, creating aftermarket service revenue pools.
- Japan's PMDA adaptive therapy pathway:Domestic clinical evidence requirements delay foreign entrants, rewarding early investment in localized trial networks for real-time planning software.
- AI-enabled auto-contouring convergence:Machine learning segmentation integrated with MRI-linac workflows compresses planning time from hours to minutes, enabling same-day adaptive treatments.
Industry Challenges
- Medical physics workforce scarcity:Specialized training for MRI-guided commissioning and quality assurance lags installation growth, extending site readiness timelines.
- Legacy LINAC integration complexity:Retrofit imaging upgrades on decade-old accelerators require custom mechanical adapters and software bridges, fragmenting vendor support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Image-Guided Radiation Therapy (IGRT) Market |
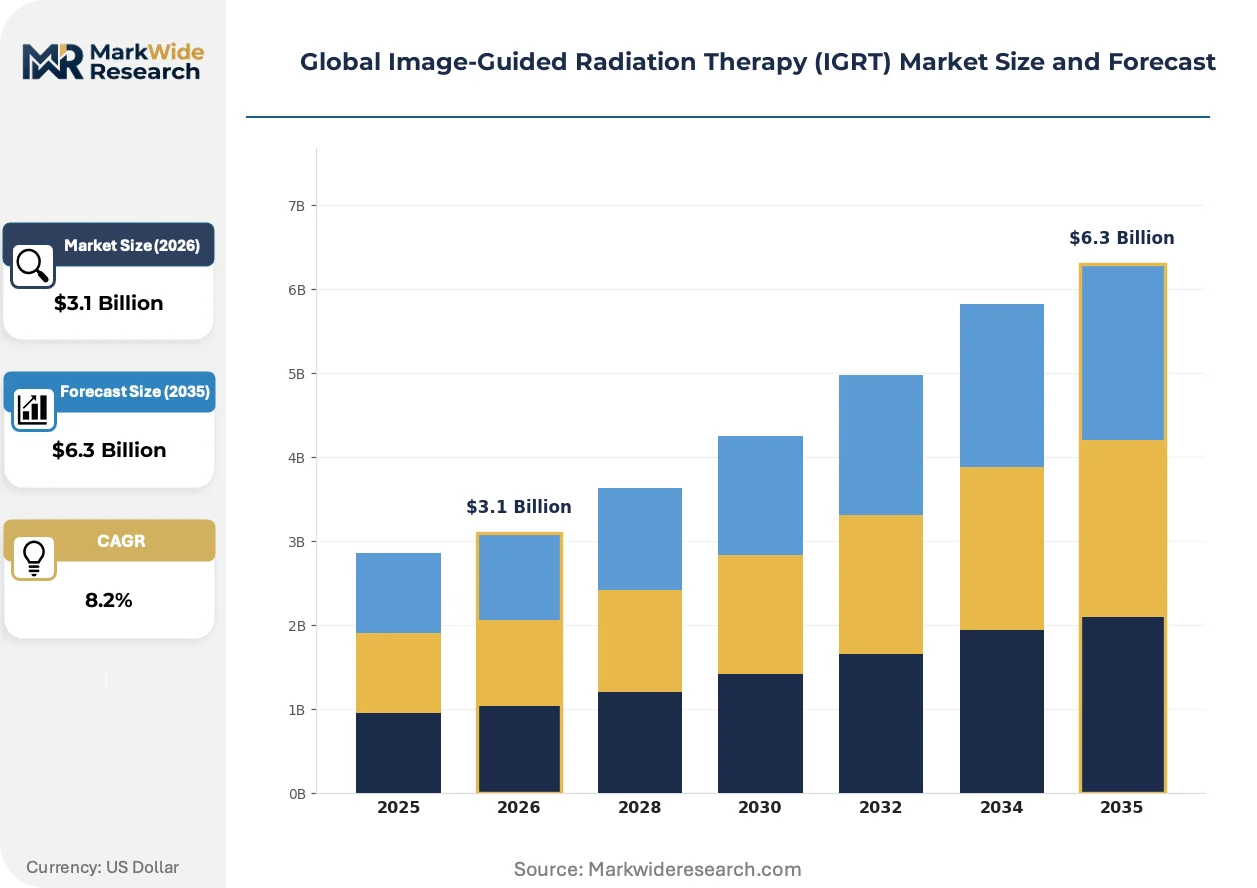
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.3 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT-Based Systems, MRI-Guided Units, Ultrasound-Guided Systems, X-Ray Based Devices, Surface Guided Radiation Therapy, Optical Tracking Systems Application Area: Prostate Cancer, Lung Cancer, Head & Neck Tumors, Breast Tumors, Brain Tumors, Gynecological Malignancies End User: Oncology Centers, Diagnostic Imaging Labs, Cancer Research Institutes, Ambulatory Surgical Facilities, Academic Medical Centers, Specialized Clinics Deployment Model: In-House Installations, Mobile Radiation Units, Integrated Hospital Systems, Standalone Clinics, Tele-Radiotherapy Networks |
| Companies Covered | Siemens Healthineers AG (Varian Medical Systems), Elekta AB, Accuray Incorporated, GE HealthCare, Koninklijke Philips N.V., ViewRay Technologies, Hitachi Medical Systems, IBA Worldwide, Vision RT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Image-Guided Radiation Therapy (IGRT) Market Shifts & Advancements
Real-time anatomical tracking is displacing static positioning verification, compressing the gap between diagnostic imaging and therapeutic delivery into continuous closed-loop systems that redefine clinical workflow boundaries.
MR-linac technology is unifying soft-tissue visualization with megavoltage beam delivery through integrated 1.5 Tesla scanners mounted directly on accelerator gantries. Academic medical centers in the United States and Germany are adopting these platforms for abdominal and pelvic malignancies where daily anatomical deformation demands online plan adaptation. This unification collapses the traditional separation between simulation and treatment rooms, forcing facility designers to consolidate capital budgets into single-vendor integrated systems rather than discrete imaging and therapy purchases.
Japan's PMDA maintains distinct clinical evidence thresholds for adaptive therapy claims that require domestic patient cohorts and localized imaging protocols. Non-domestic manufacturers face eighteen-to-twenty-four month delays while establishing in-country trial infrastructure, compressing first-mover advantages for early entrants. South Korean and Australian regulators are observing PMDA's evidentiary framework, potentially harmonizing Asia-Pacific adaptive therapy approval standards around Japanese precedents.
Hospital procurement committees are unbundling equipment financing from software subscriptions and service contracts, treating imaging upgrades as separate capital events from linear accelerator replacements. United States academic centers increasingly lease adaptive planning modules on annual terms rather than embedding perpetual licenses in initial hardware purchases. This behavioral shift concentrates vendor risk in renewal rates and forces pricing transparency across multi-year total cost of ownership calculations.
Global Image-Guided Radiation Therapy (IGRT) Market Segmentation
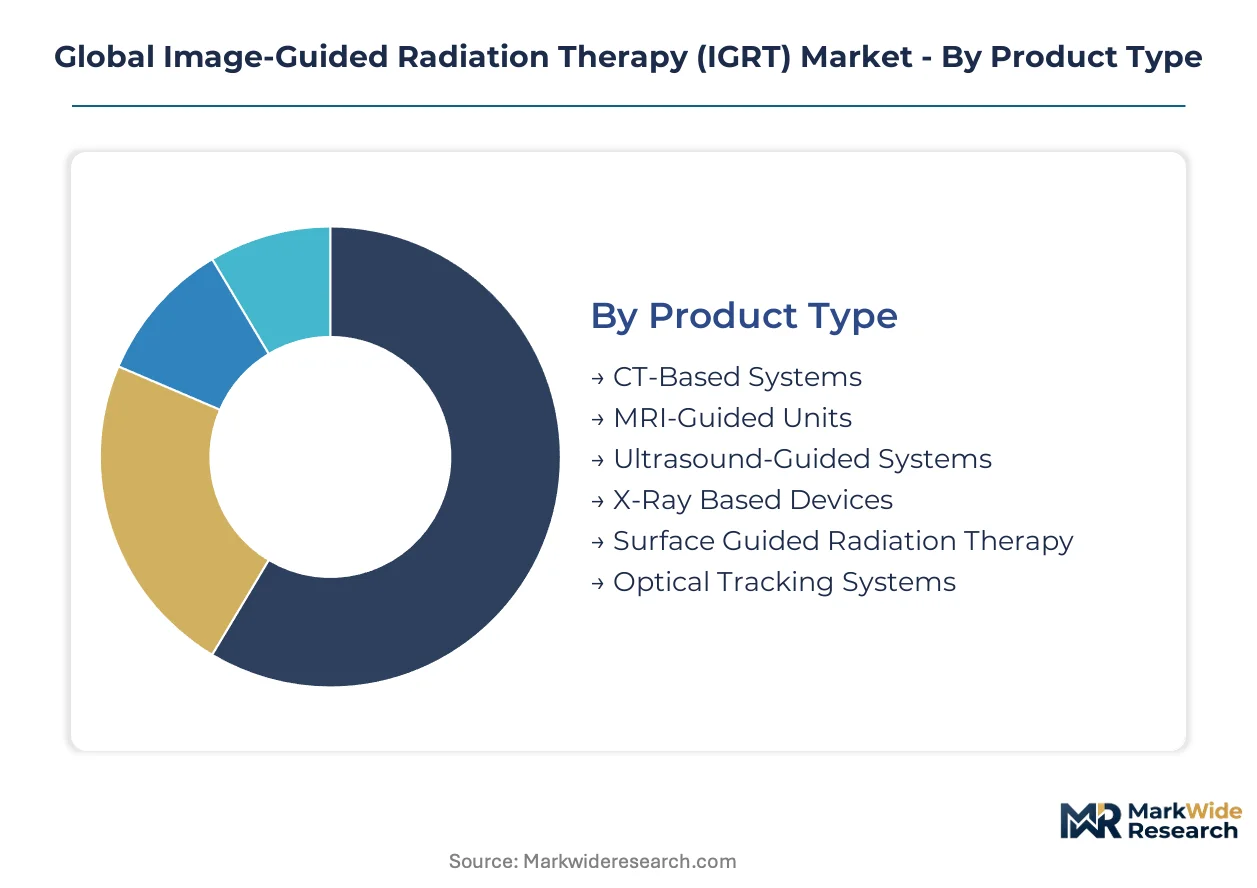
IGRT market segmentation reveals how imaging modality, clinical application, and facility infrastructure interact to determine procurement priorities. Understanding these intersections helps vendors align hardware specifications with reimbursement pathways and site readiness constraints.
Product Type:
Integration depth varies sharply across imaging modalities, with some platforms operating as standalone verification tools while others embed directly into beam delivery architecture.
- CT-Based Systems:Fan-beam or cone-beam CT scanners mounted on linear accelerator gantries provide bony anatomy verification with sub-millimeter spatial resolution. Demand concentrates in community oncology centers across the United States where capital budgets prioritize workflow speed over soft-tissue visualization, constrained by reimbursement codes that favor fractionated treatment throughput.
- MRI-Guided Units:Integrated 1.5 Tesla superconducting magnets combined with linear accelerators enable real-time soft-tissue tracking during beam delivery. Academic medical centers in Germany and the United States drive adoption as EU MDR certification streamlines procurement validation, though helium supply volatility extends delivery timelines for cryogenic components.
- Ultrasound-Guided Systems:Transabdominal or transrectal probes provide prostate positioning verification without ionizing radiation exposure.
- X-Ray Based Devices:Stereoscopic kV imaging pairs deliver rapid bony landmark registration for daily patient setup.
- Surface Guided Radiation Therapy:Optical surface scanning monitors patient position through external markerless tracking.
- Optical Tracking Systems:Infrared camera arrays track reflective markers affixed to patient immobilization devices.
CT-Based Systems lead volumes today; MRI-Guided Units is gaining share fastest.
Application Area:
Margin reduction potential and fractionation intensity determine which anatomical sites justify premium imaging investment versus commodity verification approaches.
- Prostate Cancer:Daily imaging mandates in hypofractionated curative regimens sustain replacement cycles for aging CT-based units, with fractionation protocols requiring sub-millimeter positioning repeatability over forty or fewer sessions. Academic medical centers in the United States anchor demand as Medicare reimbursement rates reward high-dose-per-fraction delivery with image verification.
- Lung Cancer:Stereotactic body radiation therapy for early-stage lesions demands motion management through 4D-CT or real-time tracking, with tumor displacement during respiration exceeding treatment margins without continuous monitoring. German cancer centers expand installation of integrated gating systems under EU MDR streamlined pathways.
- Head & Neck Tumors:Bony landmark proximity to soft-tissue targets favors CT verification over MRI guidance.
- Breast Tumors:Deep inspiration breath-hold protocols drive surface-guided positioning adoption.
- Brain Tumors:Frameless stereotaxy using optical tracking dominates functional preservation cases.
- Gynecological Malignancies:Daily anatomical deformation from bladder and rectum filling pushes adaptive planning adoption.
Prostate Cancer commands the deepest margin pools; Lung Cancer shows the steepest expansion trajectory.
End User:
Capital allocation authority and patient volume scale create distinct purchasing behaviors across facility types, from centralized academic procurement to distributed ambulatory decisions.
- Oncology Centers:Dedicated radiation therapy facilities with multiple linear accelerators prioritize vendor consolidation for service efficiency, bundling imaging upgrades across aging installed bases through fifteen-year replacement cycles. Mumbai and Delhi private chains drive refurbished equipment demand with retrofit imaging kits.
- Academic Medical Centers:Research mission requirements and resident training obligations sustain investment in MRI-guided platforms and adaptive planning software, with procurement committees separating hardware financing from annual software subscriptions. United States institutions increasingly lease planning modules rather than embedding perpetual licenses.
- Diagnostic Imaging Labs:Pre-treatment simulation focus limits therapeutic imaging investment to CT-based systems.
- Cancer Research Institutes:Grant-funded adaptive therapy trials concentrate in PMDA-compliant Japanese networks.
- Ambulatory Surgical Facilities:Lower throughput favors mobile radiation unit partnerships over capital installation.
- Specialized Clinics:Single-modality focus permits streamlined X-ray based verification workflows.
Oncology Centers lead volumes today; Academic Medical Centers is gaining share fastest.
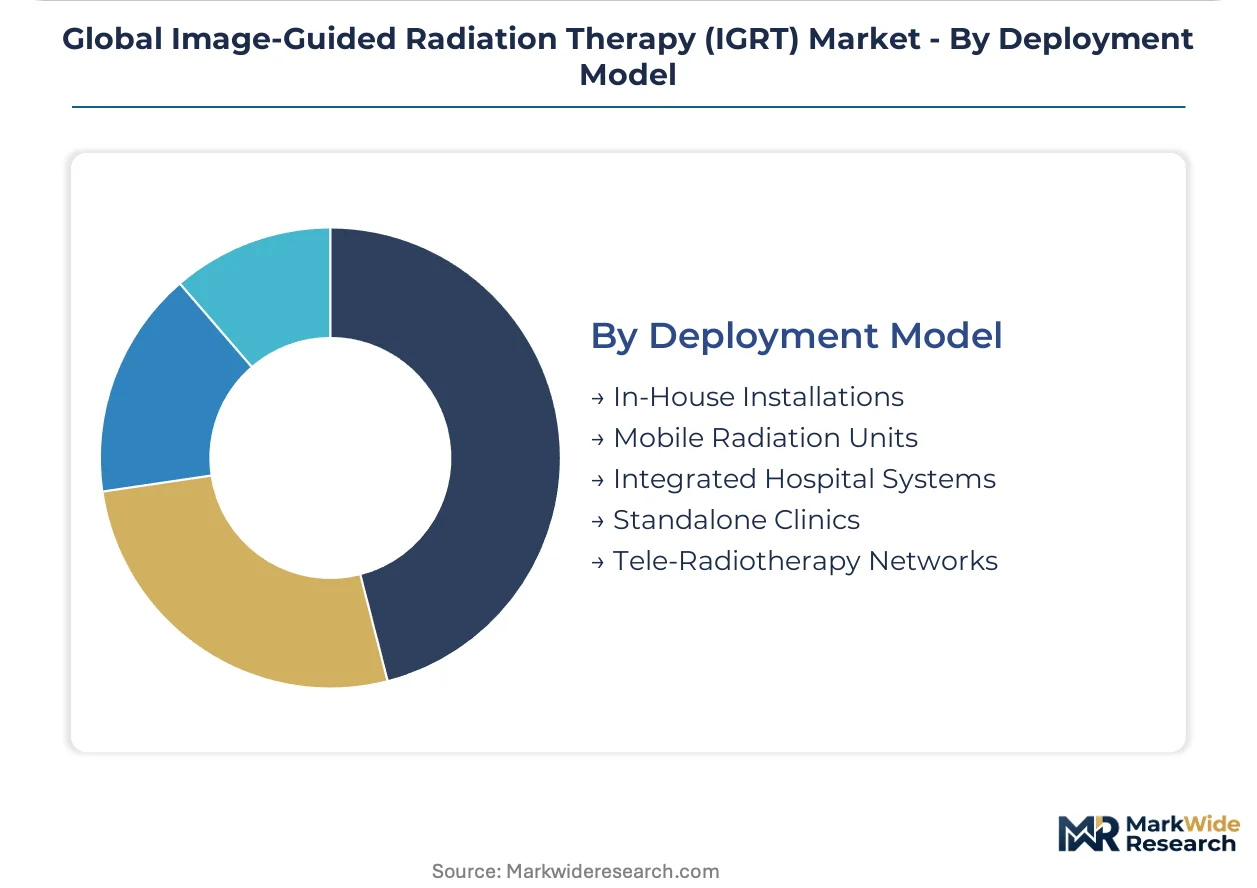
Deployment Model:
Physical infrastructure requirements and regulatory jurisdiction shape whether facilities pursue fixed installation, mobile service, or distributed network architectures.
- In-House Installations:Fixed vault-based linear accelerators with integrated imaging represent the traditional capital deployment model, requiring dedicated shielding construction and medical physics commissioning that extends site readiness timelines. Compact gantry designs from specialized vendors reduce vault footprint requirements, enabling repurposed clinical space conversion.
- Integrated Hospital Systems:Enterprise-wide procurement committees consolidate imaging and therapy capital budgets into single-vendor platforms, collapsing historical separation between simulation and treatment room infrastructure. United States health systems favor this model for fifteen-year total cost of ownership optimization.
- Mobile Radiation Units:Truck-mounted linear accelerators serve rural or temporary demand clusters without permanent construction.
- Standalone Clinics:Independent practice ownership sustains CT-based system replacement demand.
- Tele-Radiotherapy Networks:Remote planning and quality assurance hub models concentrate physics expertise across distributed delivery sites.
In-House Installations lead volumes today; Integrated Hospital Systems is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany streamlines MRI-guided system procurement through EU MDR certification pathways, while the United States concentrates replacement demand at academic medical centers with aging CT-based installed bases.
United States
Academic medical centers anchor demand for integrated hospital systems as Medicare reimbursement rates reward high-dose-per-fraction delivery with image verification. FDA premarket notification requirements shape hardware validation timelines and software algorithm lockdowns. The Greater Boston cluster sustains research mission investment in adaptive planning software.
Germany
Cancer treatment centers expand adoption of MRI-guided units under streamlined EU MDR technical documentation obligations. IEC 60601-2-68 standards govern electromagnetic compatibility for imaging-beam integration. The Baden-Württemberg region concentrates vendor consolidation for service efficiency across fifteen-year replacement cycles.
Japan
PMDA enforces distinct clinical evidence thresholds for adaptive therapy claims that delay entry for non-domestic manufacturers. Domestic clinical evidence requirements compress first-mover advantages for early entrants. The Kanto region around Tokyo anchors grant-funded adaptive therapy trials requiring localized imaging protocols.
India
Private oncology chains in Mumbai and Delhi seek refurbished linear accelerators with retrofit imaging kits, creating aftermarket service revenue pools. The country's national pharmaceutical regulator oversees device import licensing for radiation therapy platforms. The Maharashtra-Gujarat corridor drives capital deployment in repurposed clinical spaces.
Australia
Regulators observe PMDA's evidentiary framework, potentially harmonizing Asia-Pacific adaptive therapy approval standards around Japanese precedents. TGA compliance pathways influence procurement timelines for real-time planning software. The New South Wales-Victoria corridor concentrates tele-radiotherapy network development.
Global Image-Guided Radiation Therapy (IGRT) Market Competitive Landscape
Top-tier vendors anchor integrated MRI-linac platforms, while mid-tier specialists concentrate on compact gantry designs and retrofit imaging kits. Siemens Healthineers leverages its installed base of linear accelerators to bundle imaging upgrades. Elekta sustains R&D intensity in adaptive delivery software. Accuray differentiates through compact gantry designs that reduce vault construction costs. Strategic consolidation centers on software subscription bundling and fifteen-year total cost of ownership optimization.
Within the integrated-system tier, Siemens Healthineers AG, Elekta AB, and Accuray Incorporated represent the dominant archetypes. Siemens Healthineers occupies a position exemplifying installed-base leverage for imaging upgrade bundling. Elekta anchors the adaptive software specialization vector. Accuray exemplifies compact-hardware differentiation. These three entities collectively represent the competitive structure driving procurement committee evaluation criteria across academic and community oncology centers.
| Leading Market Players |
|---|
| Siemens Healthineers AG (Varian Medical Systems) |
| Elekta AB |
| Accuray Incorporated |
| GE HealthCare |
| Koninklijke Philips N.V. |
| ViewRay Technologies |
| Hitachi Medical Systems |
| IBA Worldwide |
| Vision RT |
| Others |
Supply & Pricing Matrix
Captive production of superconducting magnets by Japanese and European specialty suppliers anchors both supply security and pricing power for MRI-guided system OEMs, while helium price volatility feeds directly into equipment cost structures and procurement committee negotiations.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for EU MDR-certified MRI-guided platforms as streamlined validation compresses procurement timelines. Three-tier pricing structure across premium MRI-linac, standard CT-based, and economy retrofit configurations separates academic medical centers from community oncology sites. Cost compression in the standard tier intensifies because Siemens Healthineers and Elekta bundle software subscriptions with hardware, shifting margin pressure to renewal rates. Community oncology centers in the United States exhibit highest price sensitivity, while German academic centers prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Medical physics workforce scarcity in Japan and the United States extends commissioning timelines for MRI-guided installations, forcing OEMs to pre-position trained specialists at manufacturing sites. Cryogenic component fabrication concentrates in Japan and Germany, while linear accelerator vacuum tubes draw from specialized suppliers in the United States and Sweden. Single-source vulnerability around helium-3 isotope supply from Russian extraction facilities exposes superconducting magnet production to export license delays. Distribution runs through direct OEM-hospital contracting with fifteen-year service agreements, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IGRT equipment procurement operates as a geographic-arbitrage play where EU MDR certification timelines in Germany run twelve to eighteen months shorter than PMDA adaptive therapy pathways in Japan, compressing first-mover returns for early entrants into European academic medical centers.
For Market Incumbents: Acquire adaptive planning software assets to counter proton therapy substitution threats at premium cancer centers. Siemens Healthineers should deepen backward integration into cryogenic component supply to insulate margins from helium price spikes. Elekta must lock hospital system procurement committees into fifteen-year service contracts before compact gantry competitors reduce vault construction cost advantages. For New Entrants and Emerging Players: Private oncology chains in Mumbai and Delhi represent the most penetrable segment, seeking refurbished linear accelerators with retrofit imaging kits at forty percent below OEM list pricing. AI-enabled auto-contouring modules offer a direct go-to-market angle, compressing planning time from hours to minutes for same-day adaptive treatments. Avoid Japan's PMDA pathway until localized trial infrastructure matures. For Investors and Strategic Acquirers: Consolidation pressure builds where software subscription bundling fragments vendor support obligations across decade-old accelerator installed bases. Five-to-ten year viability favors platforms with demonstrated EU MDR certification and CMS reimbursement code expansion into photon-based MRI-guided installations. Watch CMS adaptive planning reimbursement decisions as the primary inflection indicator for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Streamlined technical documentation accelerates hospital procurement cycles in Germany and France. |
| Software Subscription Bundling | Annual licensing models shift vendor risk to renewal rates across fifteen-year equipment lifecycles. |
| Compact Gantry Design | Reduced vault footprint enables installation in repurposed clinical spaces previously unsuitable for radiation oncology. |
| AI-Enabled Auto-Contouring | Machine learning segmentation compresses planning time from hours to minutes for same-day adaptive treatments. |
| Aftermarket Service Expansion | Refurbished linear accelerators with retrofit imaging kits capture revenue pools in India's private oncology chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with radiation oncologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement code records, and hospital procurement databases. Bottom-up installation tracking and top-down vendor revenue triangulation anchored market sizing across imaging modality segments.
Historical reference periods anchored the projection horizon through installed base depreciation curves and replacement cycle analysis across fifteen-year linear accelerator lifecycles. The analytical framework modeled segmentation dimensions including imaging modality, clinical application, facility infrastructure type, and regional regulatory cluster. CAGRs derived from vendor shipment disclosures and hospital capital budget surveys, with helium price volatility and medical physics workforce growth rates as industry-specific forecast inputs.
Revisions become necessary when EU MDR certification timelines extend, PMDA adaptive therapy evidence thresholds shift, or CMS reimbursement codes for photon-based MRI-guided installations materialize differently than modeled assumptions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Germany Digital Pathology Market