
 Facial Spasm Treatment Market | 2026-2036
Facial Spasm Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Spasm Treatment Market Analytics
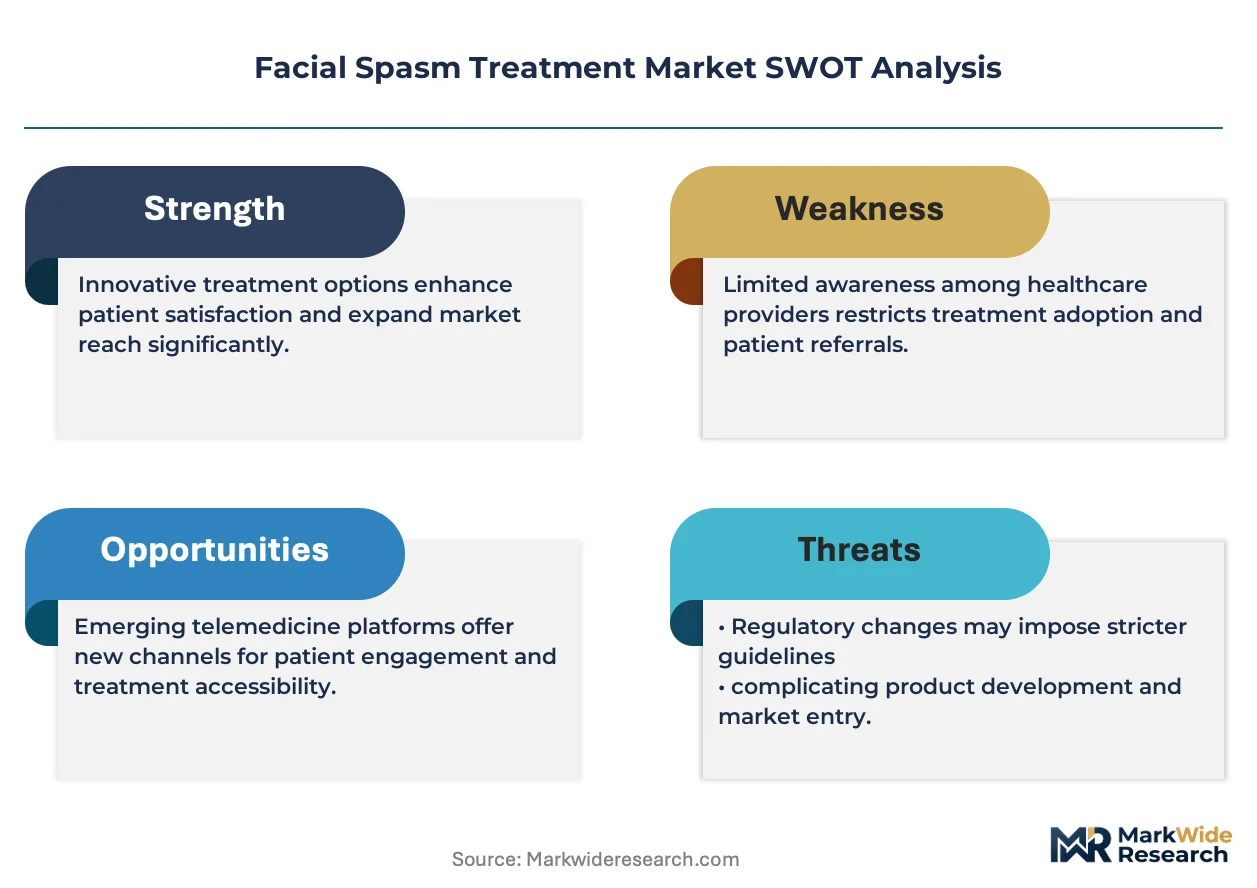
Modular dosing configurations for botulinum toxin is shifting how physicians customize per-patient protocols across hemifacial spasm and blepharospasm indications. Merz Pharmaceuticals anchors its European presence through concentrated toxin formulations designed for precise neuromuscular targeting. Revance Therapeutics differentiates via peptide-enhanced delivery platforms that extend duration of therapeutic effect. Ipsen Biopharmaceuticals competes through specialized manufacturing scale that supports consistent batch potency for injectable neurotoxins.
Facial spasm treatment encompasses pharmacological and interventional modalities targeting involuntary contractions of orbicularis oculi, orbicularis oris, and associated mimetic muscles, with botulinum toxin serotype A functioning through SNAP-25 cleavage to inhibit acetylcholine release at the neuromuscular junction. The primary purpose is restoring facial symmetry, reducing functional impairment, and preventing secondary corneal exposure or visual obstruction. Botulinum toxin commands the dominant margin pool due to recurring injection cycles and established reimbursement, while surgical procedures including microvascular decompression retain niche positioning for refractory cases. Neurology clinics represent the fastest-growing application channel as outpatient settings consolidate diagnosis and injection administration under specialist supervision.
FDA oversight of biologic potency testing and lot release standards governs injectable neurotoxin commercialization, while the EMA's biosimilar framework shapes competitive entry pathways in European markets. The EU MDR's strengthened clinical evidence requirements for high-risk devices affects surgical instrument and implantable neurostimulator market access timelines. Stakeholders must monitor evolving FDA guidance on long-duration toxin formulations and CMS reimbursement decisions for office-based injection procedures to align portfolio development with payer and regulatory expectations.
Market Dynamics
Modular botulinum toxin dosing configurations are restructuring physician-patient matching protocols across hemifacial spasm and blepharospasm indications, compressing trial-and-error cycles and consolidating protocol standardization around precision-targeted neuromuscular interventions.
Growth Catalysts
- Orphan Drug Incentives:The FDA's accelerated approval pathways and tax credits for rare disease therapies are redirecting R&D investment toward novel injectable formulations for refractory facial spasm subtypes.
- Neurology Clinic Consolidation:Outpatient movement disorder centers in the United States are integrating diagnosis and injection administration under single-specialist supervision, streamlining patient throughput and reimbursement capture.
- Peptide-Enhanced Delivery:Extended-duration toxin platforms are reducing injection frequency burdens for chronic patients, improving adherence curves and lifetime value metrics for payers.
Market Restraints
- Batch Potency Volatility:Biologic manufacturing inconsistencies in neurotoxin production create lot-to-lot efficacy variation, complicating physician dosing confidence and adverse event profiling.
- European Regulatory Friction:The EU MDR's strengthened clinical evidence requirements for high-risk devices are elongating market access timelines for surgical instruments and implantable neurostimulators.
- Surgical Substitution Ceiling:Microvascular decompression retains niche positioning only for pharmacologically refractory cases, limiting addressable expansion beyond toxin-dependent patient pools.
Strategic Opportunities
- Underpenetrated European Markets:France and Germany exhibit lower specialist injection density per capita relative to the United States, creating whitespace for concentrated toxin formulation launches.
- Office-Based Procedure Reimbursement:CMS coverage clarity for injection administration in non-hospital settings is enabling neurology clinic network expansion and capital-light service models.
- Neurostimulator-Toxin Convergence:Combined device-biologic protocols for refractory cases are opening hybrid intervention categories not captured by either monotherapy alone.
Industry Challenges
- Specialist Injection Training Bottlenecks:Precise orbicularis oculi and oris targeting demands fellowship-level anatomical expertise, constraining scalable workforce deployment.
- Reimbursement Documentation Burden:Prior authorization requirements for botulinum toxin therapies consume administrative bandwidth in movement disorder centers, delaying treatment initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Spasm Treatment Market |
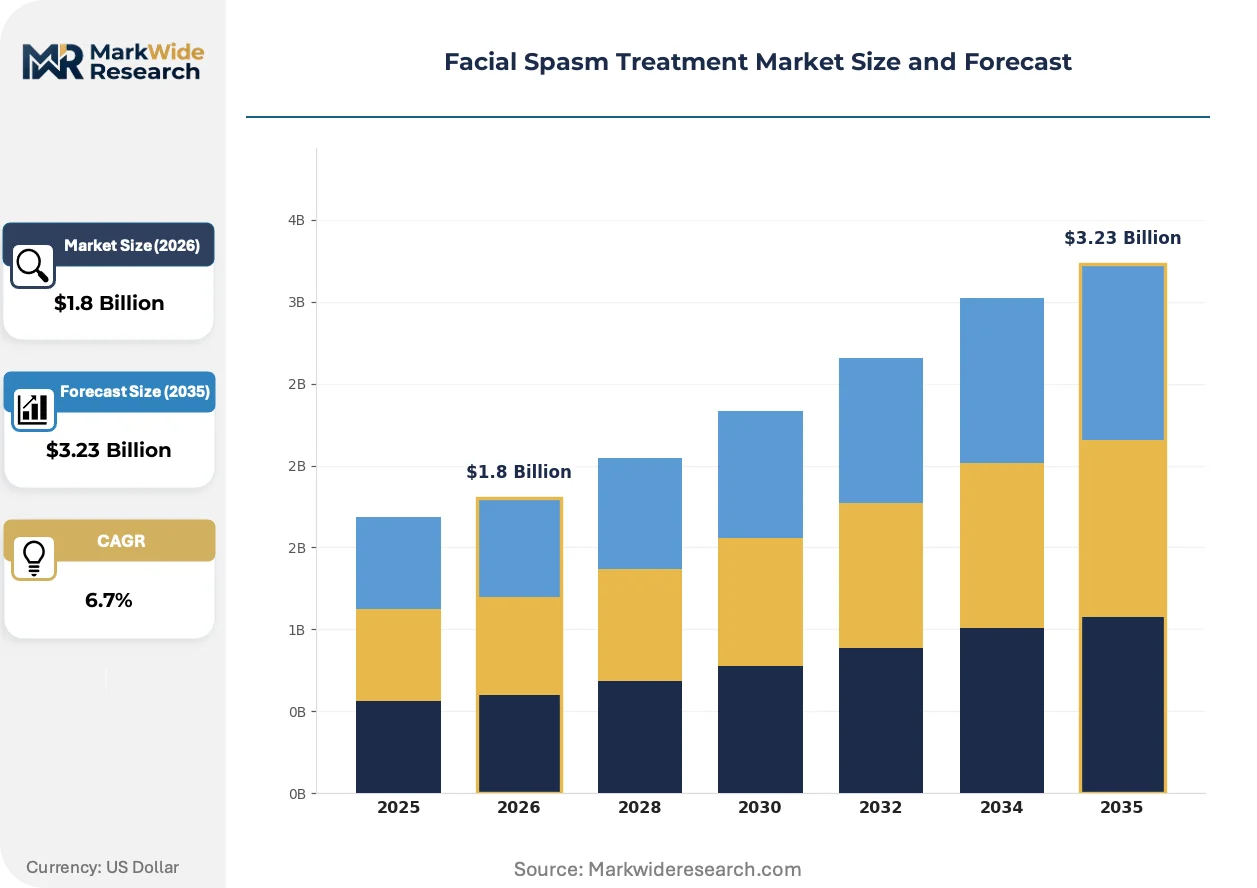
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
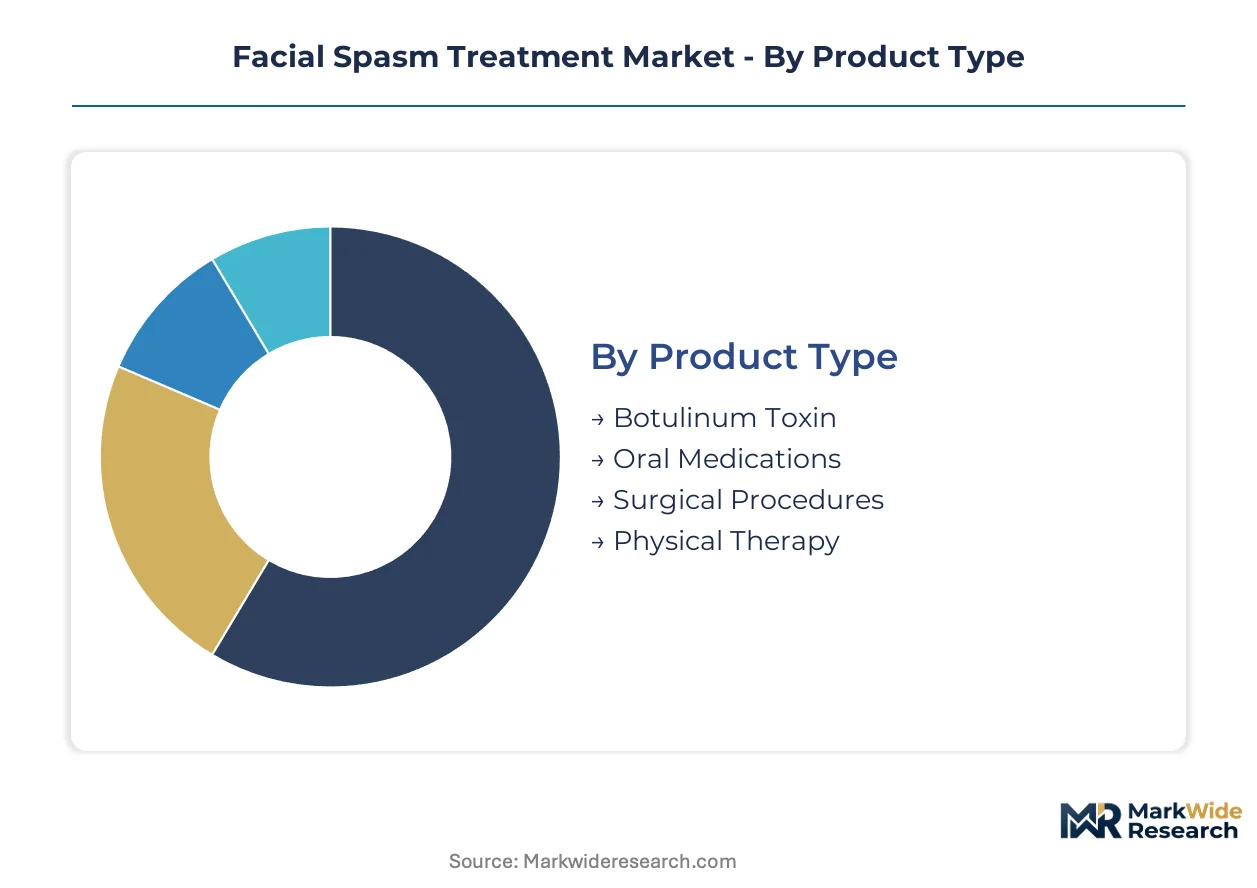
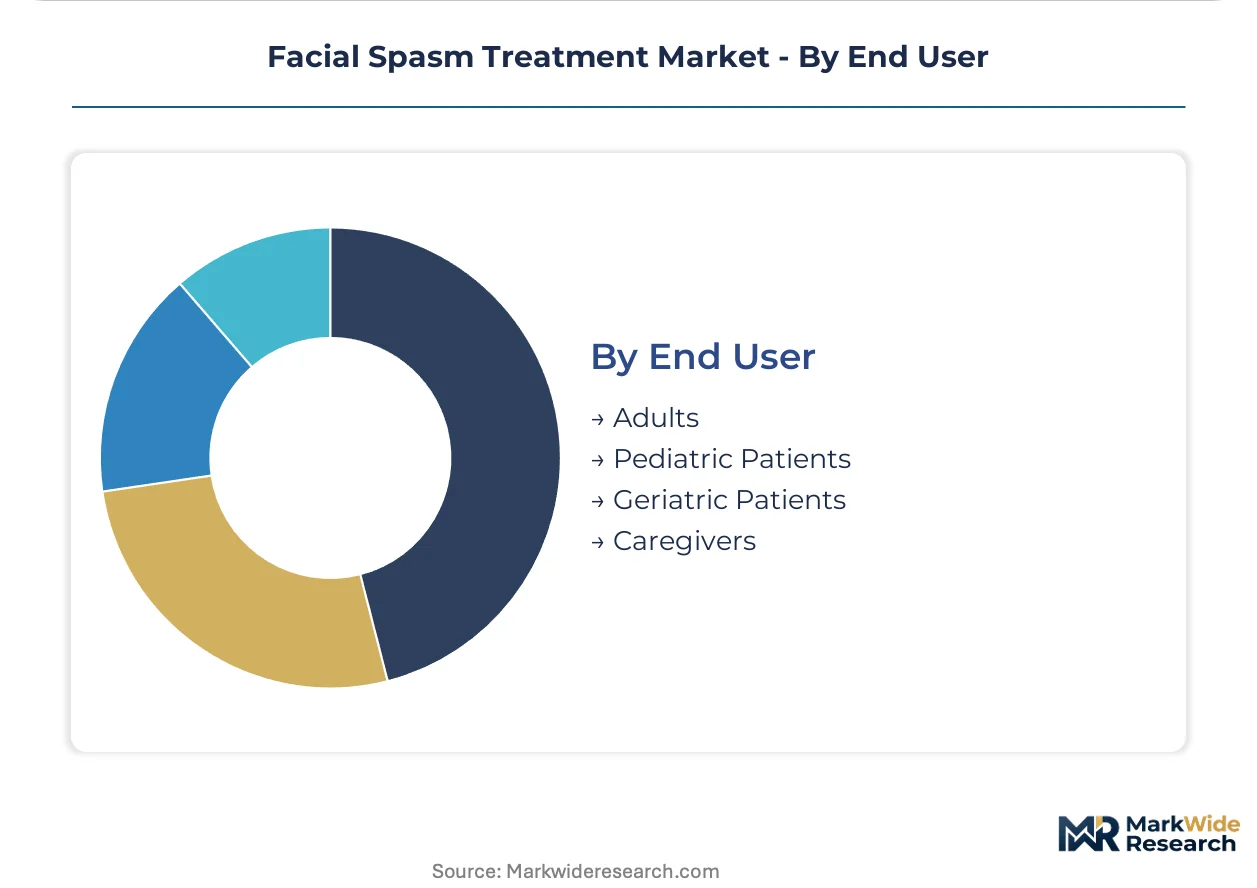
| Segmentation | Product Type: Botulinum Toxin, Oral Medications, Surgical Procedures, Physical Therapy Application: Neurology Clinics, Hospitals, Rehabilitation Centers, Home Care Delivery Mode: Injectables, Oral, Intravenous, Topical End User: Adults, Pediatric Patients, Geriatric Patients, Caregivers |
| Companies Covered | Merz Pharmaceuticals, Revance Therapeutics, Allergan (AbbVie), Ipsen Biopharmaceuticals, Medtronic, Boston Scientific, Stryker, Galderma, Medytox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Spasm Treatment Market Evolving Landscape
Duration-extension technologies and precision delivery mechanisms are displacing conventional toxin administration paradigms, while regulatory frameworks on both sides of the Atlantic recalibrate evidence standards for biologic potency claims.
Peptide-enhanced neurotoxin formulations are overtaking standard serotype A preparations in physician preference hierarchies. These platforms extend therapeutic intervals from twelve to sixteen weeks in hemifacial spasm cohorts. Movement disorder specialists in academic medical centers are adopting them fastest, compressing revenue per patient visit while capturing lifetime adherence gains.
The EU MDR's post-market surveillance mandates are reshaping surgical instrument commercialization pathways. Manufacturers must now submit periodic safety update reports for implantable neurostimulators used in refractory spasm cases. German and French notified bodies are enforcing these requirements most stringently, delaying competitive entry for device-only players.
Direct-to-specialist sampling programs are displacing traditional pharmaceutical rep-detailing models in the United States. Neurology clinics now receive modular dosing kits prior to formulary commitment, reducing switching friction. This pattern concentrates in the Northeast and West Coast hospital systems where movement disorder center density supports peer-to-peer protocol diffusion.
Facial Spasm Treatment Market Segmentation
Facial spasm treatment segmentation reveals how regulatory pathways and reimbursement structures concentrate commercial value across delivery mechanisms and care settings. Understanding these divisions clarifies where FDA lot-release standards, CMS coverage decisions, and specialist training requirements create barriers or opportunities for market entry.
Product Type:
FDA biologic potency testing and EMA batch certification requirements vary sharply across this category, with injectable neurotoxins facing the most stringent manufacturing oversight while oral formulations navigate abbreviated approval pathways.
- Botulinum Toxin:Serotype A preparations function through SNAP-25 cleavage to inhibit acetylcholine release at the neuromuscular junction. Demand concentrates in United States movement disorder centers where reimbursement clarity supports recurring injection cycles, though batch potency volatility complicates physician dosing confidence.
- Surgical Procedures:Microvascular decompression addresses pharmacologically refractory hemifacial spasm through neurovascular conflict resolution. Volumes cluster at academic medical centers in Germany and France where specialized neurosurgical expertise supports favorable outcome documentation required under EU MDR post-market surveillance mandates.
- Oral Medications:Anticonvulsant and muscle relaxant compounds serve as first-line therapy for mild cases, with prescribing concentrated among general neurologists lacking injection training.
- Physical Therapy:Biofeedback and facial muscle retraining protocols support adjunctive care, with uptake limited by evidence requirements for insurance reimbursement.
Leading the category by volume: Botulinum Toxin. Growing fastest: Surgical Procedures.
Application:
Capital intensity and specialist density determine margin structures across settings, with outpatient consolidation favoring lower-overhead models.
- Neurology Clinics:Outpatient movement disorder centers integrate diagnosis and injection administration under single-specialist supervision. These settings capture the steepest expansion trajectory as CMS reimbursement clarity enables capital-light network growth across United States metropolitan clusters.
- Hospitals:Inpatient and outpatient surgical departments handle refractory cases requiring microvascular decompression or complex comorbidity management. Volumes concentrate at tertiary centers in Boston, Cleveland, and Baltimore where fellowship-trained specialists support academic referral networks.
- Rehabilitation Centers:Post-surgical recovery and adjunctive therapy delivery occurs in these settings, with physical therapy integration driving modest utilization.
- Home Care:Caregiver-administered oral medications and monitoring support chronic management, limited by injection therapy exclusion from non-clinical settings.
Dominant by patient throughput: Neurology Clinics. Highest revenue per procedure: Hospitals.
Delivery Mode:
Pharmacokinetic profiles and administration requirements segment this category by training burden and patient adherence patterns.
- Injectables:Botulinum toxin intramuscular delivery demands precise orbicularis oculi and oris targeting. United States specialist injection density per capita exceeds French and German levels, creating whitespace for concentrated formulation launches in European markets.
- Oral:Systemic absorption enables self-administration but requires higher dosing for neuromuscular penetration, with compliance challenges in geriatric populations.
- Intravenous:Hospital-restricted administration for acute spasm episodes or perioperative management, with limited chronic utilization.
- Topical:Transdermal penetration limitations constrain efficacy for deep mimetic muscle targets, relegating this mode to investigational or adjunctive status.
Standard of care by efficacy: Injectables. Lowest adherence barrier: Oral.
End User:
Disease etiology and functional impairment severity vary across demographic groups, shaping treatment selection and outcome measurement priorities.
- Adults:Primary hemifacial spasm and blepharospasm onset typically occurs in middle age, with botulinum toxin injection frequency and surgical candidacy determined by vocational and social functional requirements.
- Geriatric Patients:Secondary spasm forms related to cerebrovascular events or neurodegenerative conditions drive demand in this segment, with comorbidity profiles complicating anesthesia risk for surgical intervention.
- Pediatric Patients:Congenital or early-onset movement disorders represent rare disease indications qualifying for FDA orphan drug incentives and accelerated approval pathways.
- Caregivers:Treatment decision proxy and adherence support role, with reimbursement documentation burden falling heavily on this group in home care settings.
Largest addressable population: Adults. Fastest-expanding eligibility: Geriatric Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized movement disorder centers cluster in United States metropolitan tax-incentive zones where CMS reimbursement clarity supports higher procedure volumes. FDA orphan drug incentives and accelerated approval pathways are redirecting development investment toward novel injectable formulations.
United States
Movement disorder centers in Boston, Cleveland, and Baltimore anchor academic referral networks for microvascular decompression procedures. FDA biologic potency testing and lot release standards govern commercialization of injectable neurotoxins. Neurology clinics in Northeast and West Coast hospital systems receive modular dosing kits through direct-to-specialist sampling programs.
Germany
Specialized neurosurgical expertise at academic medical centers supports favorable outcome documentation for refractory hemifacial spasm cases. EU MDR post-market surveillance mandates elongate market access timelines for implantable neurostimulators. German notified bodies enforce strengthened clinical evidence requirements most stringently.
France
Lower specialist injection density per capita relative to United States levels creates whitespace for concentrated toxin formulation launches. ANSM oversight shapes biologic commercialization pathways alongside EMA batch certification requirements. Parisian academic centers concentrate surgical volumes for pharmacologically refractory cases.
Japan
PMDA regulatory frameworks govern botulinum toxin approval pathways with distinct serotype evaluation protocols. METI industrial policy supports domestic manufacturing scale for consistent batch potency. Tokyo and Osaka metropolitan areas concentrate movement disorder specialist training programs.
United Kingdom
NHS reimbursement structures for office-based injection procedures influence neurology clinic network expansion decisions. MHRA post-Brexit regulatory autonomy recalibrates biologic potency testing alignment with EMA standards. London teaching hospitals anchor fellowship-level anatomical expertise training for precise orbicularis targeting.
Facial Spasm Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the facial spasm treatment ecosystem. The market structure concentrates around established neurotoxin manufacturers with recurring revenue models from injection cycles. Three archetypes dominate: biologic potency specialists, peptide-enhanced delivery innovators, and surgical instrument manufacturers. Competitive moves center on modular dosing configuration launches and neurology clinic network partnerships.
Among European toxin manufacturers, Merz Pharmaceuticals and Ipsen Biopharmaceuticals occupy positions emphasizing concentrated formulation expertise and manufacturing scale respectively. Revance Therapeutics represents the peptide-enhanced delivery archetype within United States-based innovators. These three companies exemplify how platform differentiation around duration extension and precision targeting is restructuring physician-patient matching protocols.
| Leading Market Players |
|---|
| Merz Pharmaceuticals |
| Revance Therapeutics |
| Allergan (AbbVie) |
| Ipsen Biopharmaceuticals |
| Medtronic |
| Boston Scientific |
| Stryker |
| Galderma |
| Medytox |
| Others |
Value Network & Pricing Analysis
Clostridium botulinum fermentation media costs cascade through batch certification requirements into final per-unit pricing tiers for movement disorder centers and hospital systems. United States neurology clinics absorb premium positioning for peptide-enhanced formulations, while European markets stratify around EMA batch potency tiers and domestic manufacturing scale.
Pricing Analysis
Margin tightening in standard serotype A formulations reflects biosimilar entry pressures and CMS reimbursement compression for office-based injection procedures. Three-tier pricing structure across premium peptide-enhanced, standard serotype A, and economy oral medication levels separates academic medical center procurement from community neurology clinic purchasing. Cost-down pressure on surgical instrumentation accelerates because EU MDR compliance investments elongate amortization schedules for microvascular decompression device manufacturers. Geriatric patient segments demonstrate highest price sensitivity due to fixed-income constraints and Medicare Part D coverage gaps, while pediatric rare disease indications command least sensitivity through orphan drug pricing protections.
Supply Chain Analysis
Domestic-content mandates in Japan's METI industrial policy and the United States' Buy American provisions for federal healthcare procurement reshape active pharmaceutical ingredient sourcing toward local fermentation capacity. Biologic manufacturing concentrates in the United States, Ireland, and Japan for clostridial toxin production, with South Korea emerging for fill-finish operations. Raw material dependencies center on yeast extract, casein hydrolysate, and specialized cell culture media for upstream fermentation. Single-source vulnerability permeates the peptide-enhanced delivery platform segment where proprietary excipient supply rests on limited qualified vendors. Distribution runs through cold-chain logistics networks terminating at hospital pharmacy and neurology clinic direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peptide-enhanced neurotoxin platforms are displacing conventional serotype A preparations as the dominant therapeutic modality, compressing revenue per visit while extending patient lifetime value through reduced injection frequency.
For Market Incumbents: Deepen backward integration into clostridial strain banks and fermentation capacity to defend against biosimilar margin erosion. Secure EMA batch certification redundancy across multiple manufacturing sites to mitigate EU MDR inspection disruption risks. Prioritize neurology clinic network partnerships in underpenetrated French and German metropolitan clusters where specialist injection density lags United States benchmarks. For New Entrants and Emerging Players: Begin with concentrated toxin formulation launches targeting the whitespace between standard serotype A and premium peptide-enhanced segments. France and Germany offer the most penetrable geographic entry points given lower per-capita specialist density and ANSM regulatory pathways that parallel FDA accelerated approval structures. Deploy direct-to-specialist sampling programs to compress formulary adoption cycles before establishing traditional pharmaceutical rep-detailing infrastructure. For Investors and Strategic Acquirers: FDA orphan drug designation awards for pediatric hemifacial spasm indications are the leading indicator that duration-extension platform technologies have achieved clinical validation thresholds suitable for platform expansion. Five-to-ten year viability favors acquisition targets with proprietary peptide delivery intellectual property and established EMA batch release relationships. Monitor CMS reimbursement decisions for office-based injection procedures as the primary inflection signal for neurology clinic network valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide-Enhanced Formulation Development | Extends therapeutic intervals from twelve to sixteen weeks in hemifacial spasm cohorts. |
| EU MDR Batch Certification Pathway | Accelerates market access timelines for concentrated toxin launches in German and French markets. |
| Neurology Clinic Network Partnership | Captures patient throughput consolidation as CMS reimbursement clarity enables capital-light expansion. |
| Orphan Drug Designation Pursuit | Unlocks FDA tax credits and accelerated approval pathways for pediatric facial spasm indications. |
| Direct-to-Specialist Sampling Program | Reduces switching friction in Northeast and West Coast hospital system formulary committees. |
Research Methodology
FDA 510(k) filings, EMA marketing authorization applications, and ClinicalTrials.gov protocol registries formed the secondary backbone for neurotoxin efficacy and safety profiling. Primary interviews with movement disorder specialists, hospital pharmacy directors, payer access specialists, and regulatory affairs leads at biologic manufacturers validated dosing protocol evolution and reimbursement capture strategies. Bottom-up and top-down triangulation reconciled neurology clinic procedure volumes with national health claims databases.
Bottom-up modeling aggregated injection cycle frequencies across hemifacial spasm and blepharospasm patient populations, while top-down analysis calibrated against CMS Medicare Part B spending patterns for botulinum toxin procedures. Segmentation dimensions spanned product type, application setting, delivery mode, and end-user demographic across the projection horizon. CAGRs derived from historical procedure growth rates adjusted for EU MDR implementation delays and FDA orphan drug incentive expansion. Forecast inputs incorporated specialist training pipeline constraints and batch potency volatility assumptions.
Underlying measurement precision varies by segment; neurology clinic procedure volumes carry tighter precision than home care oral medication utilization due to claims data availability. Forecasts reflect assumptions around CMS reimbursement stability and EMA batch certification throughput capacity. Regulatory pathway delays, biosimilar entry acceleration, or manufacturing contamination events could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Global Medication Management Market