
 Thyroid Gland Disorders Treatment Market | 2026-2036
Thyroid Gland Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Thyroid Gland Disorders Treatment Market Analysis
Market Context with Strategic Players
Hospital end-use is pivoting toward ambulatory surgical centers for elective thyroid procedures, reducing inpatient stays while expanding same-day surgery capacity. AbbVie Inc. leverages its immunology infrastructure to cross-sell diagnostic workflows into endocrinology practices. Novartis AG anchors European distribution of radioactive iodine therapies through specialized radiopharmacy networks. Pfizer Inc. competes in the oral levothyroxine segment with mature manufacturing scale and pharmacy benefit manager access.
Technical Definition and Structural Segments
Thyroid Gland Disorders Treatment encompasses pharmacological, surgical, and radiotherapeutic interventions targeting hypothyroidism, hyperthyroidism, thyroid nodules, and differentiated carcinomas, with hormone replacement therapy relying on synthetic levothyroxine sodium formulations calibrated to narrow therapeutic indices. The primary commercial purpose centers on restoring euthyroid metabolic status while preventing cardiovascular, reproductive, and neuropsychiatric sequelae. Hormone replacement therapy occupies the largest revenue pool given chronic daily dosing requirements across millions of diagnosed patients, while genetic testing within the technology segment shows the fastest structural ascent as next-generation sequencing panels identify hereditary medullary carcinoma risk. Radioactive iodine maintains concentrated margins due to isotope supply chain constraints and specialized handling protocols.
Regulatory Frame and Forward-Looking Close
FDA bioequivalence guidelines for narrow therapeutic index drugs constrain generic substitution of levothyroxine products, while EMA's REACH framework governs isotope handling and waste disposal across European radiopharmacy networks. Japan's PMDA maintains distinct pharmacovigilance reporting for antithyroid drug-induced agranulocytosis, shaping prescriber education and monitoring protocols. Stakeholders must monitor evolving pharmacogenomic reimbursement policies that could segment hormone dosing from one-size-fits-all protocols toward TSH genotype-guided titration models.
Market Dynamics
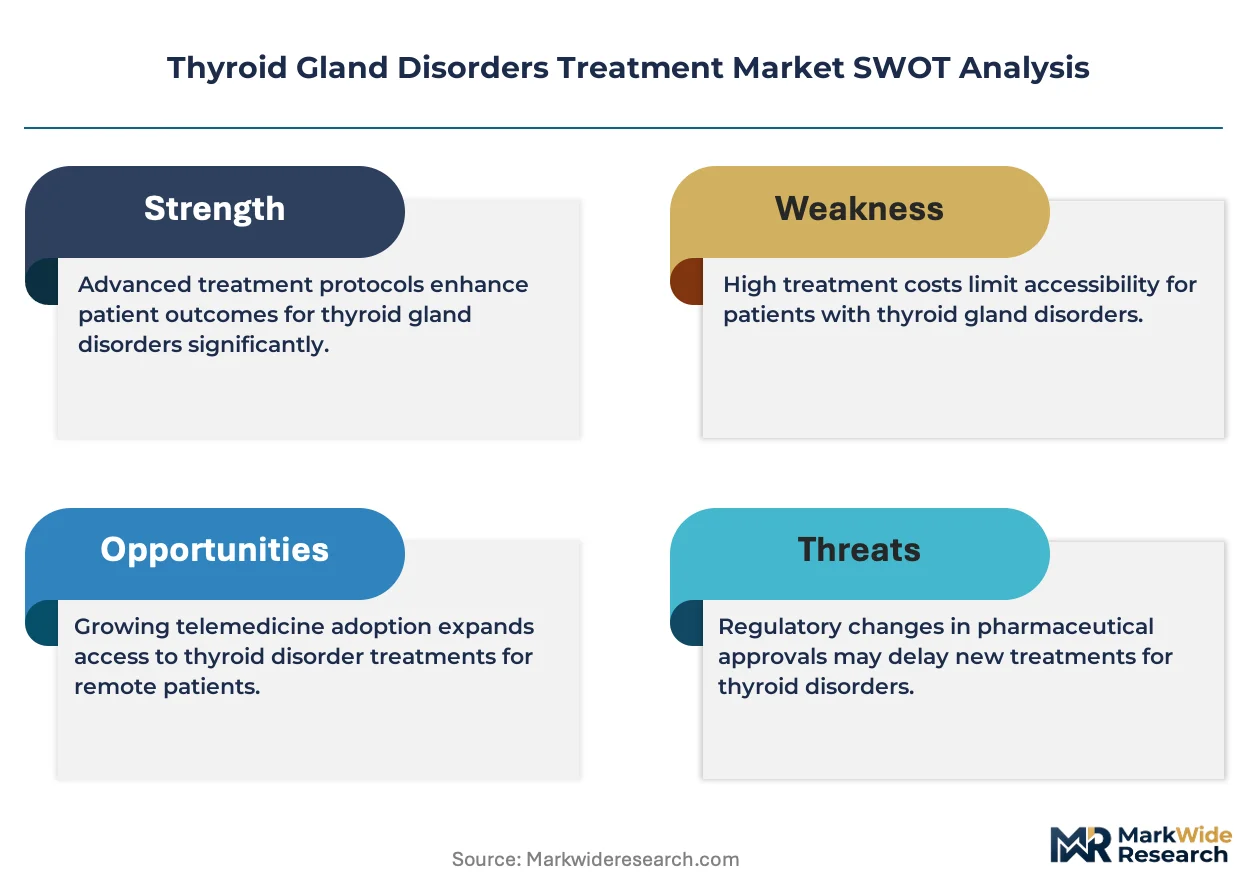
Levothyroxine manufacturing concentration among a handful of API suppliers creates supply vulnerability, while FDA bioequivalence tightening for narrow therapeutic index drugs forces reformulation investments across generic portfolios.
Growth Catalysts
- Aging diagnostic volume:Japan's super-aged population drives thyroid function testing at rates exceeding younger demographics, expanding the chronic patient pool requiring daily hormone replacement.
- EMA REACH framework:Standardized isotope handling protocols across European radiopharmacy networks enable cross-border radioactive iodine distribution, reducing regional supply fragmentation.
- Next-generation sequencing panels:Genetic testing for hereditary medullary carcinoma risk is accelerating preventive thyroidectomy decisions among mutation-positive families.
Market Restraints
- API supply concentration:Synthetic levothyroxine sodium production clusters among three dominant Chinese and Indian manufacturers, exposing formulators to geopolitical trade friction.
- Isotope supply chain rigidity:Molybdenum-99 decay chains depend on aging research reactors in Canada and the Netherlands, constraining radioactive iodine therapy availability.
- FDA bioequivalence constraints:Narrow therapeutic index classification prevents automatic generic substitution, limiting pharmacy benefit manager leverage on pricing.
Strategic Opportunities
- Pharmacogenomic reimbursement expansion:Germany's G-BA is piloting TSH genotype-guided levothyroxine dosing protocols, creating a pathway for personalized hormone titration models.
- Ambulatory surgical center migration:Elective thyroidectomy volume is shifting from inpatient hospital settings to specialized same-day surgery facilities in the United States.
- Remote patient monitoring integration:Connected devices for home TSH tracking are converging with telemedicine platforms to reduce endocrinology clinic visit frequency.
Industry Challenges
- Radiopharmacy technician scarcity:Specialized handling certification for radioactive iodine requires training programs that lack capacity expansion funding.
- Legacy EMR integration:Endocrinology practices face workflow friction embedding pharmacogenomic decision support into established electronic medical record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyroid Gland Disorders Treatment Market |
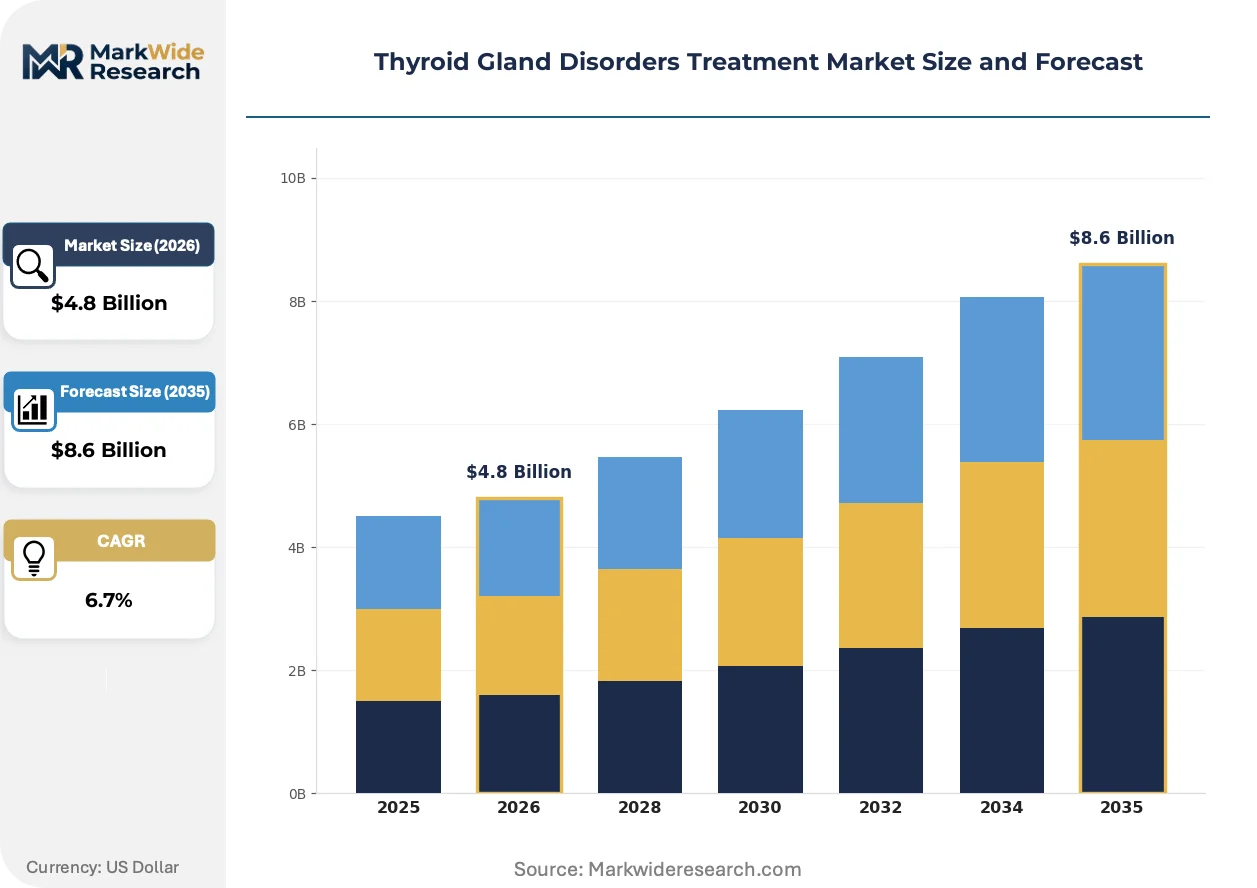
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormone Replacement Therapy, Antithyroid Drugs, Radioactive Iodine, Surgery End User: Hospitals, Clinics, Homecare Settings, Ambulatory Surgical Centers Technology: Genetic Testing, Imaging Techniques, Radioisotopes, Hormonal Assays Delivery Mode: Oral Medication, Injectable Therapy, Topical Applications, Infusion Therapy |
| Companies Covered | Exelixis Inc., Amgen Inc., AbbVie Inc., GSK plc, Novartis AG, Merck KGaA, Viatris Inc., Takeda Pharmaceutical Company Limited, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyroid Gland Disorders Treatment Market Emerging Trajectories
Diagnostic and therapeutic modalities are fragmenting across care settings, with technology enabling point-of-care decision-making that previously required centralized laboratory infrastructure.
Continuous glucose monitoring hardware adapted for thyroid hormone tracking is decentralizing metabolic status surveillance from hospital laboratories into patient homes. Endocrinology practices in Germany and Japan are piloting these devices for post-thyroidectomy patients requiring rapid levothyroxine titration. This shift is decentralizing revenue capture from reference labs toward device manufacturers and remote monitoring platforms.
EMA's Medical Device Regulation is reclassifying software-based diagnostic aids for thyroid nodule risk stratification, triggering conformity assessment requirements that delay market entry. Algorithm developers must now compile clinical validation dossiers previously unnecessary for decision-support tools. European ultrasound equipment vendors are responding by acquiring AI startups to internalize regulatory expertise.
Self-administered capillary blood sampling for TSH measurement is compressing the interval between thyroid function testing and medication adjustment. Direct-to-consumer laboratory channels in the United States are displacing traditional physician-ordered panels for stable hypothyroidism patients. This behavioral shift is most visible among employed insured populations seeking to minimize clinic absenteeism.
Thyroid Gland Disorders Treatment Market Segmentation
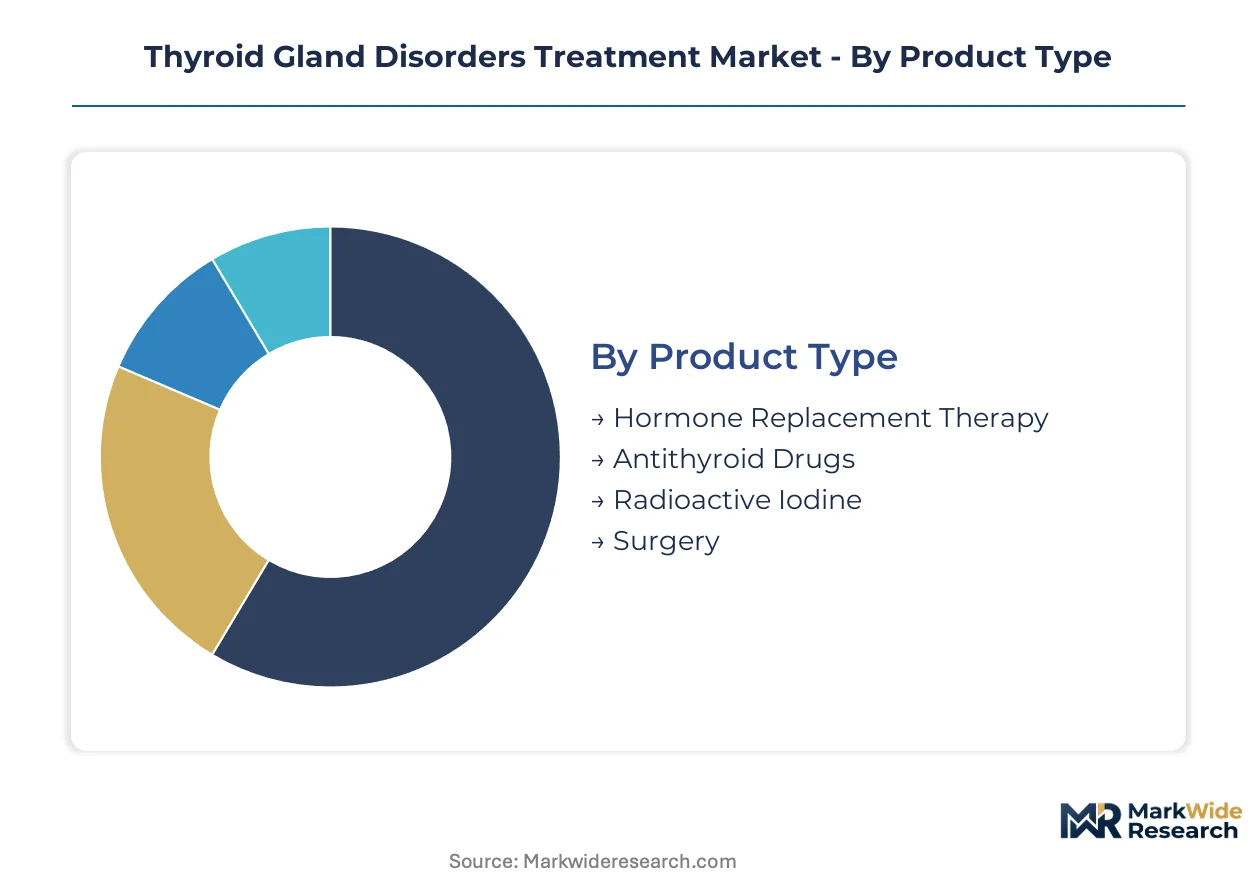
Thyroid disorder treatment modalities fragment across pharmacological, surgical, and radiotherapeutic domains, each carrying distinct reimbursement pathways and supply chain vulnerabilities. Segmentation reveals where chronic daily dosing requirements concentrate revenue versus where procedural interventions generate episodic high-value claims.
Product Type:
Replacement-cycle dynamics favor oral formulations with decades of clinical validation over capital-intensive surgical and radiotherapeutic alternatives that require infrastructure renewal.
- Hormone Replacement Therapy:Synthetic levothyroxine sodium formulations dominate prescription volume through narrow therapeutic index protocols requiring lifelong daily administration. Demand concentrates in United States retail pharmacy channels where pharmacy benefit managers negotiate formulary placement for chronic patient pools.
- Antithyroid Drugs:Methimazole and propylthiouracil tablets suppress thyroid hormone synthesis in hyperthyroidism through thionamide mechanisms. Japan's PMDA maintains distinct pharmacovigilance reporting for agranulocytosis, shaping prescriber monitoring protocols and limiting first-line use in elderly populations.
- Radioactive Iodine:Iodine-131 therapies ablate hyperfunctioning tissue and residual carcinoma through beta particle emission. EMA REACH frameworks govern isotope handling across European radiopharmacy networks.
- Surgery:Thyroidectomy addresses nodules, goiter, and malignancy through partial or total gland removal. Ambulatory surgical centers in Germany and the United States are expanding same-day capacity for elective procedures.
Volume placements concentrate in Hormone Replacement Therapy; the faster expansion belongs to Radioactive Iodine as diagnostic sensitivity improves carcinoma detection rates.
End User:
Cost-tier stratification separates high-acuity inpatient settings from lower-overhead outpatient venues competing on episode-based reimbursement efficiency.
- Hospitals:Academic medical centers manage complex thyroid carcinoma cases requiring multidisciplinary oncology coordination and inpatient radioactive iodine isolation protocols. Germany's university hospitals anchor European referral networks for medullary carcinoma subtypes.
- Clinics:Endocrinology practices titrate levothyroxine dosing through TSH monitoring and manage stable hypothyroidism without surgical intervention. United States clinic networks leverage telemedicine platforms to reduce visit frequency for chronic patients.
- Homecare Settings:Self-administered oral levothyroxine and capillary blood sampling devices shift metabolic surveillance from clinical laboratories to patient residences. Direct-to-consumer laboratory channels displace physician-ordered panels among employed insured populations.
- Ambulatory Surgical Centers:Specialized same-day facilities perform thyroidectomy for benign nodules and low-risk differentiated carcinomas. United States Medicare reimbursement policies favor site-of-service migration from inpatient hospitals.
Patient traffic concentrates in Hospitals; the steepest expansion trajectory belongs to Ambulatory Surgical Centers as payer incentives accelerate site migration.
Technology:
Application-specific value creation separates diagnostic modalities that enable preventive intervention from monitoring tools that optimize chronic management.
- Genetic Testing:Next-generation sequencing panels identify RET proto-oncogene mutations conferring hereditary medullary carcinoma risk. Germany's G-BA pilots reimbursement for genotype-guided preventive thyroidectomy decisions among mutation-positive families.
- Imaging Techniques:High-resolution ultrasound with elastography characterizes nodule malignancy risk without invasive biopsy. EMA Medical Device Regulation reclassifies AI-based risk stratification software, triggering conformity assessment delays.
- Radioisotopes:Diagnostic iodine-123 and therapeutic iodine-131 depend on molybdenum-99 decay chains from aging research reactors in Canada and the Netherlands. Supply rigidity constrains therapy availability during reactor maintenance cycles.
- Hormonal Assays:Third-generation TSH immunoassays enable subclinical dysfunction detection and precise levothyroxine titration. Reference laboratories in Japan and the United States compete on turnaround time for routine monitoring panels.
Test volume concentrates in Hormonal Assays; the fastest share gain belongs to Genetic Testing as hereditary risk stratification expands preventive surgical eligibility.
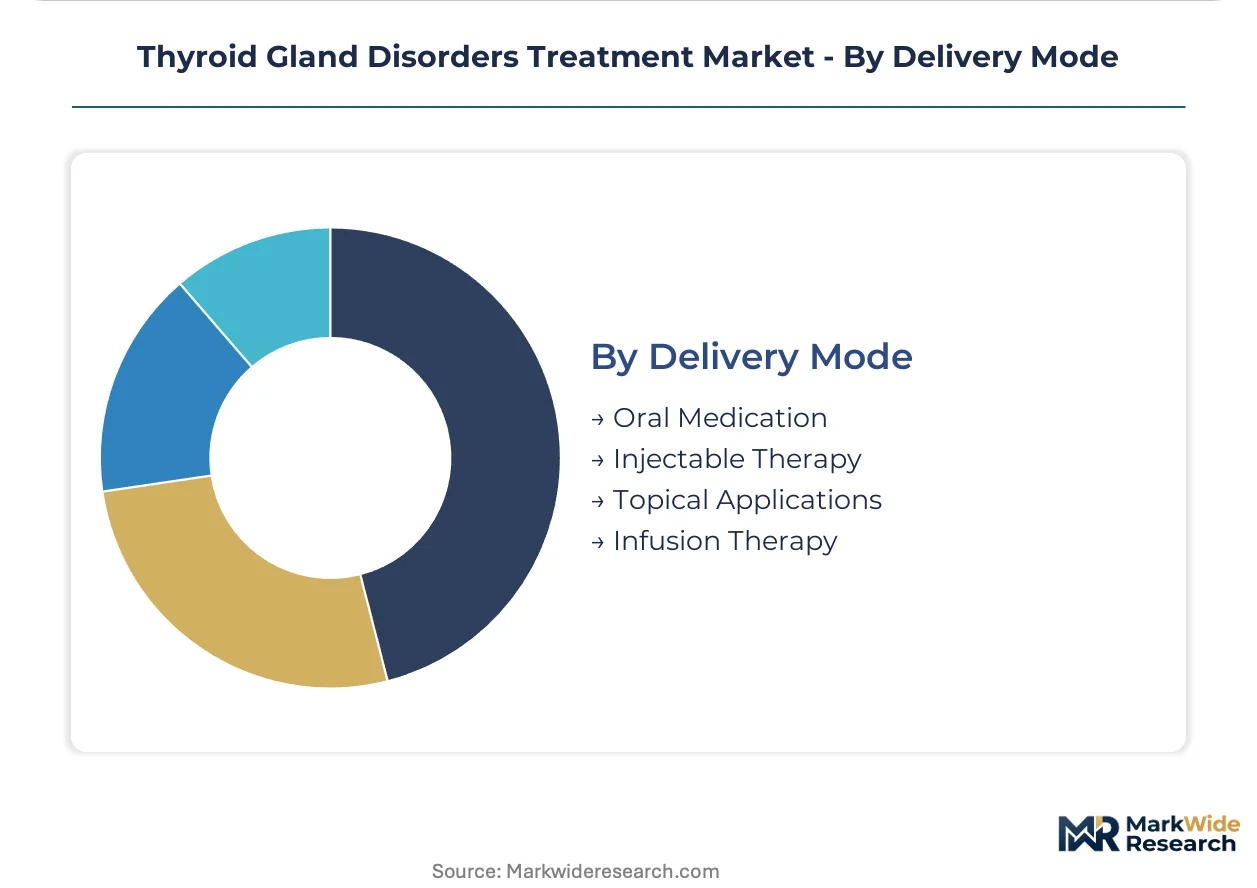
Delivery Mode:
Customer-type preferences segment between patients seeking minimal intervention disruption and those requiring rapid metabolic correction through intensive administration.
- Oral Medication:Levothyroxine tablets and antithyroid drugs accommodate self-administration without clinical supervision. Pharmacy benefit manager formularies in the United States prioritize generic substitution despite FDA narrow therapeutic index constraints.
- Injectable Therapy:Intravenous levothyroxine addresses malabsorption syndromes and perioperative patients unable to tolerate enteral administration. Hospital pharmacy compounds prepare patient-specific doses under USP standards.
- Topical Applications:Transdermal hormone delivery remains investigational for patients with gastrointestinal intolerance. Limited commercial availability restricts adoption to clinical trial settings.
- Infusion Therapy:Continuous intravenous antithyroid administration manages thyroid storm in intensive care units. High-acuity hospital settings concentrate utilization for life-threatening hyperthyroid decompensation.
Dose administrations concentrate in Oral Medication; the most rapid volume expansion belongs to Injectable Therapy as perioperative protocols standardize parenteral alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for synthetic levothyroxine concentrates in Chinese and Indian chemical hubs, while consumption gravity pulls toward aging populations in the United States, Germany, and Japan where diagnostic intensity drives chronic patient pools.
United States
Medicare reimbursement policies favor site-of-service migration from inpatient hospitals to ambulatory surgical centers for elective thyroidectomy. FDA bioequivalence guidelines constrain automatic generic substitution of narrow therapeutic index levothyroxine products. Endocrinology practices in Texas and Florida leverage telemedicine platforms to reduce clinic visit frequency for stable hypothyroidism patients.
Germany
The G-BA pilots reimbursement for TSH genotype-guided levothyroxine dosing protocols among mutation-positive families. EMA REACH frameworks standardize isotope handling across Bavarian and North Rhine-Westphalian radiopharmacy networks. University hospitals in Munich and Heidelberg anchor European referral networks for medullary carcinoma subtypes.
Japan
Super-aged demographics drive thyroid function testing at rates exceeding younger populations, expanding the chronic patient pool requiring daily hormone replacement. PMDA maintains distinct pharmacovigilance reporting for antithyroid drug-induced agranulocytosis. Tokyo and Osaka metropolitan areas concentrate endocrinology specialist density and genetic counseling capacity for hereditary risk stratification.
India
Domestic API production of synthetic levothyroxine sodium serves global formulators from manufacturing clusters in Gujarat and Maharashtra. CDSCO regulatory pathways align with ICH guidelines for abbreviated new drug applications. Hyderabad and Ahmedabad house contract research organizations supporting bioequivalence studies for export markets.
United Kingdom
NICE technology appraisals influence commissioning decisions for next-generation sequencing panels in hereditary medullary carcinoma screening. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards for radiopharmaceutical handling. London and Manchester academic medical centers participate in multicenter pharmacogenomic dosing trials.
Thyroid Gland Disorders Treatment Market Vendor Landscape
Top-tier vendors anchor hormone replacement therapy through mature manufacturing scale and pharmacy benefit manager access, while mid-tier specialists compete on radiopharmaceutical distribution and genetic testing services. The competitive terrain separates chronic oral medication incumbents from procedural and diagnostic innovators. Three archetypes dominate: diversified pharmaceutical conglomerates with endocrinology cross-selling infrastructure, radiopharmacy network operators with isotope handling specialization, and precision medicine platforms with next-generation sequencing capabilities. Consolidation pressure manifests through M&A targeting genetic testing assets and strategic partnerships securing API supply continuity.
Within the diversified pharmaceutical tier, AbbVie Inc. and Pfizer Inc. occupy positions exemplifying immunology-to-endocrinology workflow integration and mature levothyroxine manufacturing scale respectively. Novartis AG anchors European radiopharmaceutical distribution through specialized pharmacy networks. These three entities represent distinct competitive vectors: cross-selling infrastructure, manufacturing efficiency, and isotope supply chain control.
| Leading Market Players |
|---|
| Exelixis Inc. |
| Amgen Inc. |
| AbbVie Inc. |
| GSK plc |
| Novartis AG |
| Merck KGaA |
| Viatris Inc. |
| Takeda Pharmaceutical Company Limited |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up radiopharmacy specialists in the United States and Germany have consolidated isotope handling infrastructure, creating captive supply networks that insulate pricing from spot-market volatility while extracting premium margins through specialized handling certifications. This ownership pattern concentrates pricing power among operators with EMA REACH compliance and FDA cGMP radiopharmacy licensing, forcing independent formulators toward contract manufacturing arrangements with less favorable terms.
Pricing Analysis
Price erosion across oral levothyroxine tiers traces to pharmacy benefit manager consolidation in the United States, where three dominant PBMs negotiate formulary placement for chronic patient pools. Three-tier pricing structure across branded narrow-therapeutic-index, authorized generic, and commodity generic levels separates patients with absorption sensitivities from cost-optimized stable populations. Cost-down pressure on antithyroid drugs accelerates because Japanese PMDA agranulocytosis monitoring requirements elevate compliance costs for methimazole suppliers. Clinic networks exhibit highest price sensitivity for routine TSH monitoring panels, while academic medical centers absorb premium pricing for radioactive iodine therapies due to isolated inpatient protocols.
Supply Chain Analysis
Returns of unused iodine-131 vials from radiopharmacy networks to centralized reprocessing facilities in Belgium and the Netherlands recover valuable isotope for redispensing, reducing waste disposal costs under EMA REACH frameworks. Synthetic levothyroxine sodium API production clusters in Gujarat and Maharashtra, India, and Shandong Province, China, drawing from thyroid hormone precursor chemical streams. Molybdenum-99 decay chains for diagnostic and therapeutic isotopes rest on aging research reactors at Chalk River, Canada, and Petten, Netherlands, creating single-source vulnerability during maintenance cycles. Distribution runs through specialized radiopharmacy networks with cold-chain logistics rather than general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA bioequivalence tightening for narrow therapeutic index drugs erects a compliance moat that rewards incumbent manufacturers with validated pharmacokinetic dossiers while raising capital barriers for generic entrants. This cost-of-compliance dynamic concentrates market power among established players with decades of clinical data accumulation.
For Market Incumbents: Anchor manufacturing scale through backward integration into API supply from Indian and Chinese chemical hubs, securing volume commitments that preempt competitor access. Invest in pharmacogenomic decision-support modules for electronic medical record integration, defending against precision-medicine entrants targeting TSH genotype-guided dosing protocols. Monitor Germany's G-BA reimbursement pilots for preventive thyroidectomy in mutation-positive families as a demand inflection signal. For New Entrants and Emerging Players: EMA's Medical Device Regulation reclassification of AI-based thyroid nodule risk stratification software opens a window for algorithm developers with clinical validation dossiers to capture ultrasound equipment vendor partnerships. Target ambulatory surgical center networks in the United States seeking same-day thyroidectomy capacity expansion under Medicare site-of-service incentives. Pursue direct-to-consumer laboratory channel partnerships for capillary blood sampling devices, bypassing entrenched clinic networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-medicine platforms with next-generation sequencing capabilities in Germany and Japan, where hereditary medullary carcinoma screening reimbursement is expanding. Long-term viability centers on pharmacogenomic service models that displace one-size-fits-all hormone dosing. Watch for FDA bioequivalence study failure announcements among second-tier generic levothyroxine manufacturers as acquisition trigger signals.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Reimbursement Strategy | Germany's G-BA pilots create first-mover advantage in genotype-guided dosing protocols. |
| Radiopharmacy Network Expansion | EMA REACH compliance enables cross-border isotope distribution across European markets. |
| Ambulatory Surgical Center Partnership | Medicare site-of-service migration accelerates same-day thyroidectomy volume capture. |
| API Supply Backward Integration | Indian and Chinese manufacturing clusters offer captive supply security against trade friction. |
| Remote Patient Monitoring Platform | Connected TSH tracking devices reduce endocrinology clinic visit frequency for stable patients. |
Methodological Framework
Independent corroboration across endocrinology practice administrators, radiopharmacy operations managers, and formulary directors at United States pharmacy benefit managers underwrites the qualitative findings on pricing dynamics and site-of-service migration. Secondary validation draws from FDA bioequivalence guidance documents, EMA REACH implementation reports, and Japan PMDA pharmacovigilance databases. Bottom-up patient volume estimates by treatment modality triangulate against top-down pharmaceutical shipment data from Indian and Chinese customs records.
Rate-of-change decomposition across hormone replacement therapy, antithyroid drugs, radioactive iodine, and surgery segments isolates volume drivers from price effects throughout the projection horizon. Modeling incorporates treatment line progression, dosage form preferences, administration route feasibility, and regional regulatory cluster stringency. CAGRs derive from patient pool expansion by age demographic, diagnostic intensity trends, and reimbursement policy shifts rather than extrapolated historical growth.
Caveats apply where reactor maintenance cycles at Canadian and Dutch isotope facilities or geopolitical trade friction affecting Indian and Chinese API exports could materially shift the outlook. Practitioners should monitor FDA bioequivalence study outcomes and Germany G-BA pharmacogenomic reimbursement decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Chagas Disease Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Cervical Cancer Treatment Market