
 Radiation Proctitis Treatment Market | 2026-2036
Radiation Proctitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Proctitis Treatment Market Intelligence
Hyaluronic acid-based rectal barriers are restructuring product economics in radiation proctitis prevention, displacing older petroleum-based formulations across outpatient oncology settings. Ferring Pharmaceuticals leverages its gastroenterology franchise to sustain formulary access in European hospital systems. Boston Scientific anchors its position through endoscopic intervention devices for hemorrhagic proctitis cases. Cook Medical specializes in balloon catheter systems that compete on procedural efficiency metrics.
Radiation proctitis encompasses mucosal and vascular injury to the rectal wall resulting from ionizing radiation exposure during pelvic malignancy treatment, with severity graded by the RTOG/EORTC late toxicity scoring system. The condition demands intervention across inflammatory, fibrotic, and ischemic pathophysiological stages to preserve bowel function and quality of life. Medications occupy the largest revenue pool among product types due to chronic management requirements, while biologics represent the fastest-expanding category driven by anti-TNF and stem cell therapy investigations. Hospitals dominate end-user value capture through integrated radiation oncology and gastroenterology service lines, though home care administration routes are gaining traction as oral and rectal formulations improve patient compliance profiles.
FDA oversight of rectal barrier devices under the 510(k) pathway shapes product development timelines and clinical evidence requirements for market entrants. EMA's Medical Device Regulation and REACH compliance for hydrogel components constrain formulation choices for manufacturers serving European clinics. NCCN guideline revisions and ASTRO clinical practice statements directly influence payer coverage determinations and physician prescribing patterns across United States oncology networks. Stakeholders must monitor real-world evidence generation from proton therapy centers and evolving biosimilar competition in anti-inflammatory biologics to anticipate shifts in treatment algorithms and reimbursement landscapes.
Market Dynamics
Rectal-sparing radiation protocols are compressing prophitis incidence rates while simultaneously elevating the acuity of cases requiring intervention, forcing treatment paradigms toward salvage biologics and interventional endoscopy.
Growth Catalysts
- Proton therapy infrastructure:United States oncology centers are installing particle beam systems that demand specialized proctitis management protocols, creating parallel service line expansion.
- EMA MDR compliance pathways:Streamlined CE marking for hydrogel barrier devices is accelerating product registration timelines across German and French hospital procurement systems.
- Stem cell therapy pipelines:Mesenchymal stromal cell investigations for refractory hemorrhagic proctitis are attracting investigator-initiated trial funding from academic medical centers.
Market Restraints
- Biologic manufacturing concentration:Anti-TNF production for off-label proctitis use depends on concentrated mammalian cell culture capacity in Irish and Belgian contract facilities.
- REACH hydrogel precursor costs:Cross-linked hyaluronic acid raw material pricing fluctuates with agricultural fermentation feedstock availability.
- Reimbursement compression:Germany's KBA-equivalent assessment bodies are narrowing indication coverage for premium barrier formulations.
Strategic Opportunities
- Home care administration channels:Rectal foam and suppository formulations are penetrating direct-to-patient distribution models previously dominated by infusion centers.
- Real-world evidence mandates:FDA 21st Century Cures Act provisions incentivize post-market surveillance data collection from proton therapy centers.
- Anti-inflammatory biosimilar entry:Adalimumab biosimilar availability is expanding formulary access for chronic proctitis maintenance in United States managed care networks.
Industry Challenges
- Interventional gastroenterology training gaps:Balloon catheter deployment for radiation-induced strictures requires specialized endoscopic skills concentrated in tertiary referral centers.
- 510(k) clinical evidence timelines:FDA predicate device matching for novel barrier formulations extends development cycles beyond typical pharmaceutical comparators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Proctitis Treatment Market |
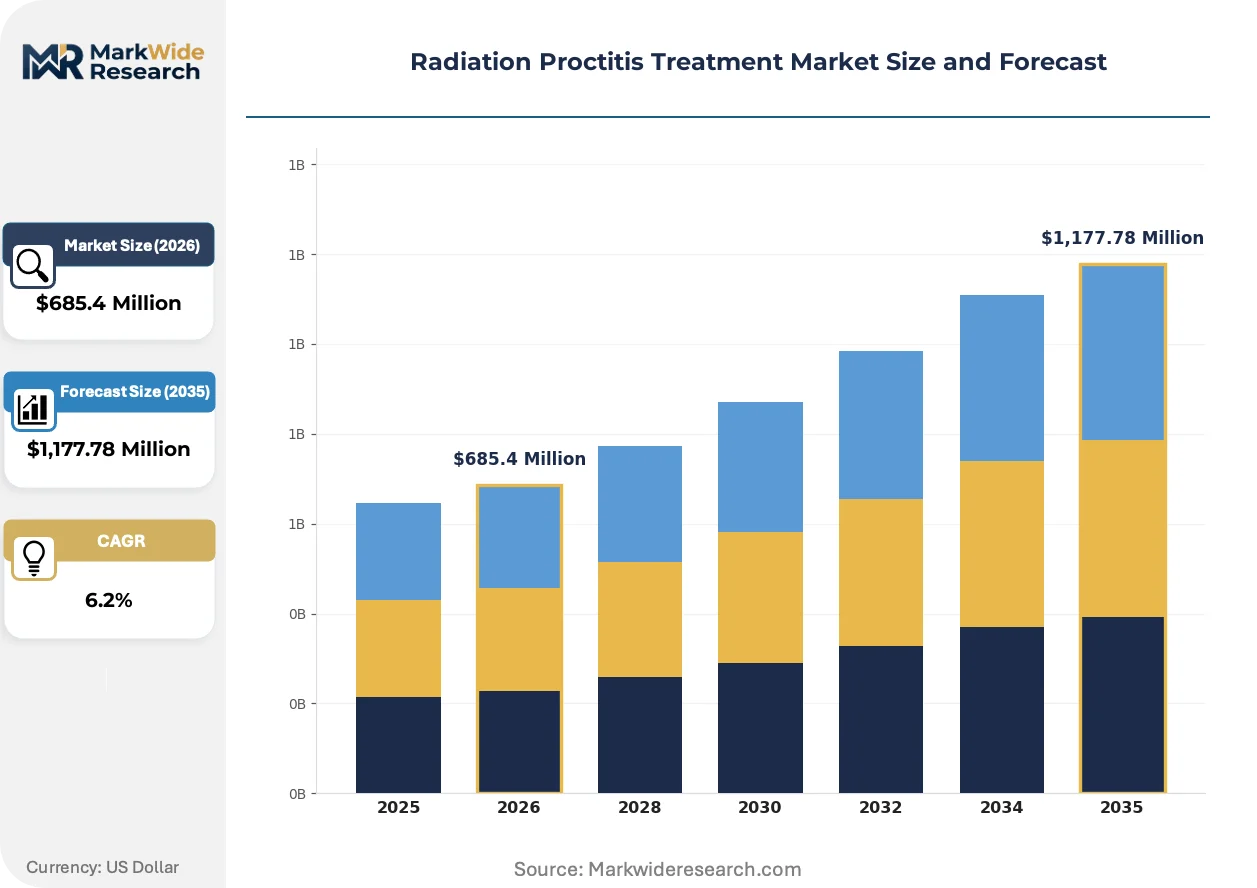
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Suppositories, Devices, Biologics End User: Clinics, Hospitals, Home Care, Long-term Care Facilities Treatment Modality: Conservative, Surgical, Pharmacological, Nutritional Administration Route: Oral, Rectal, Parenteral, Topical |
| Companies Covered | Ferring Pharmaceuticals, Chugai Pharmaceutical, Boston Scientific, Dr. Reddy Laboratories, Sun Pharmaceutical Industries, Cook Medical, GlaxoSmithKline, Allergan, Salix Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Proctitis Treatment Market Strategic Shifts & Innovations
Hyaluronic acid-based formulations are displacing petroleum-derived barriers across outpatient oncology settings, while regulatory frameworks and procurement models simultaneously restructure competitive access.
Polymeric rectal barriers containing cross-linked hyaluronic acid are rewriting prevention economics in pelvic radiation protocols. Outpatient oncology clinics in the United States are standardizing these formulations as first-line prophylaxis. The shift is compressing revenue per patient while expanding addressable procedure volumes.
REACH compliance requirements for hydrogel precursor chemicals are constraining formulation flexibility for manufacturers serving European clinics. EMA's Medical Device Regulation enforcement is extending technical documentation timelines. German hospital procurement consortia are responding by consolidating supplier panels to reduce qualification burden.
Integrated radiation oncology-gastroenterology service lines are consolidating purchasing authority within United States health systems. Independent physician practices are losing direct contracting access as hospital-employed specialists capture referral flows. This concentration is most pronounced in proton therapy hub markets across Texas, Florida, and California.
Radiation Proctitis Treatment Market Segmentation
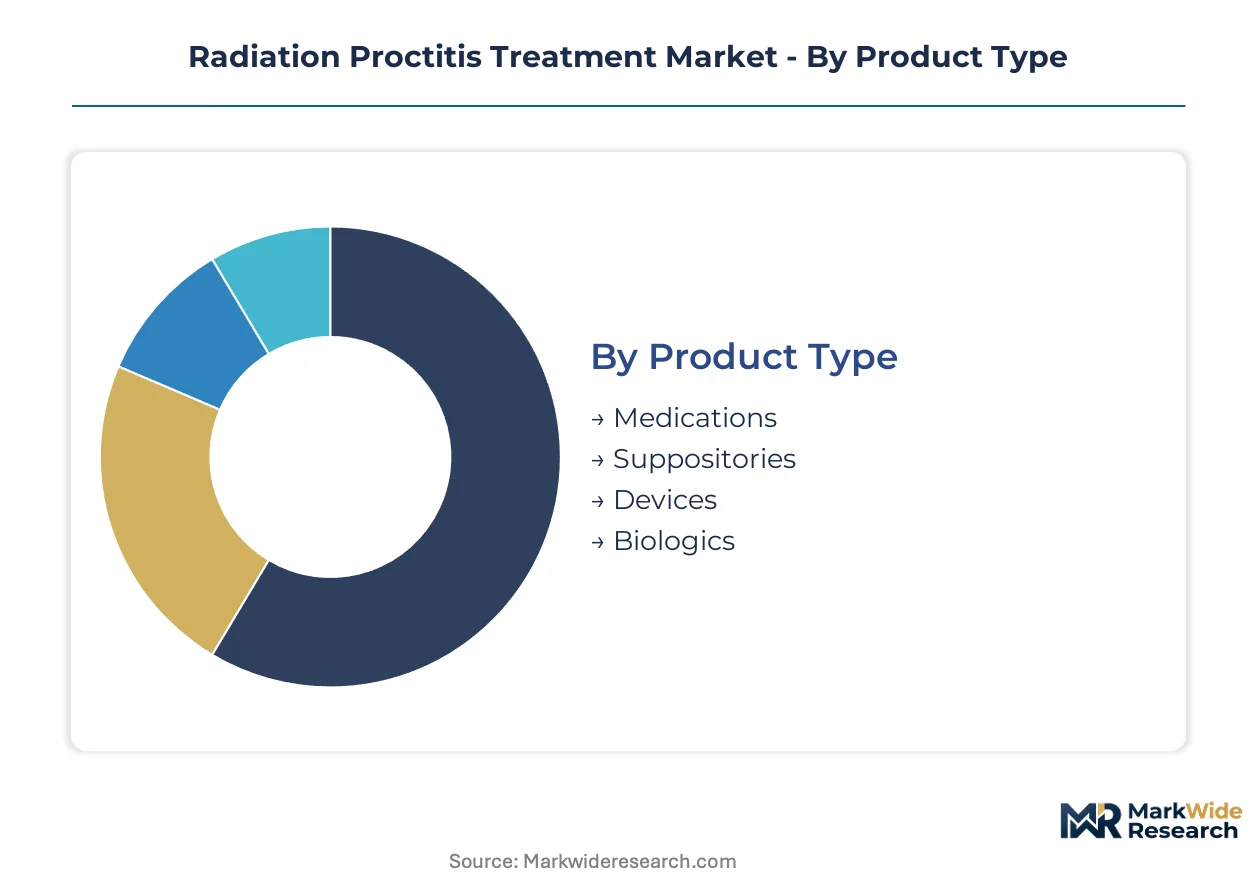
Treatment modality and product type splits reveal where capital equipment investments concentrate versus where recurring pharmaceutical revenues accumulate. Understanding these segment boundaries clarifies which stakeholders control purchasing decisions across acute intervention versus chronic management pathways.
Product Type:
Manufacturing capacity clusters differently across each product category, with sterile device production requiring distinct facility certifications from biologic fermentation or small-molecule compounding.
- Medications:Oral anti-inflammatory agents and topical corticosteroids dominate prescription volumes through outpatient oncology pharmacies. Demand concentrates in United States integrated delivery networks where prior authorization workflows favor formulary-maintenance drugs over novel alternatives.
- Biologics:Anti-TNF therapies and investigational mesenchymal stromal cell preparations command premium positioning for refractory hemorrhagic cases. United States academic medical centers with stem cell processing facilities are driving investigator-initiated trial enrollment fastest.
- Suppositories:Hydrocortisone and mesalamine rectal formulations serve bridging therapy between acute flares and maintenance protocols.
- Devices:Balloon catheters and endoscopic deployment systems require interventional gastroenterology service line investment.
Today's leader: Medications. Tomorrow's challenger: Biologics.
End User:
Procurement authority is migrating toward hospital-employed specialists as independent practice consolidation accelerates across major United States oncology markets.
- Hospitals:Integrated radiation oncology-gastroenterology service lines capture the highest-acuity cases requiring salvage biologics or interventional endoscopy. United States proton therapy hubs in Texas, Florida, and California concentrate tertiary referral volumes and associated proctitis management protocols.
- Home Care:Rectal foam and suppository formulations are penetrating direct-to-patient distribution channels as oral bioavailability improvements reduce infusion center dependency. United States specialty pharmacy networks are expanding home administration support for chronic maintenance regimens.
- Clinics:Community oncology practices handle stable patients on established maintenance protocols.
- Long-term Care Facilities:Skilled nursing settings manage delayed-onset radiation injury in elderly pelvic cancer survivors.
Procurement gravity centers on Hospitals. Home Care represents the steepest expansion trajectory as administration routes diversify.
Treatment Modality:
Clinical practice guidelines from NCCN and ASTRO stratify patients across intervention intensity tiers based on RTOG/EORTC toxicity grading.
- Pharmacological:Systemic and topical agents form the first-line intervention backbone across all severity grades. United States managed care networks leverage adalimumab biosimilar availability to expand formulary access for chronic maintenance.
- Conservative:Dietary modification, stool softeners, and observation protocols manage low-grade toxicity without escalating intervention costs.
- Surgical:Diverting colostomy and strictureplasty remain reserved for refractory fibrotic complications.
- Nutritional:Enteral support and micronutrient supplementation address malabsorption secondary to mucosal injury.
Pharmacological approaches dominate current prescribing. Conservative management is gaining protocol inclusion as rectal-sparing radiation techniques reduce baseline incidence.
Administration Route:
Formulation development investment is shifting toward patient-directed administration as healthcare labor costs rise and reimbursement compresses facility fees.
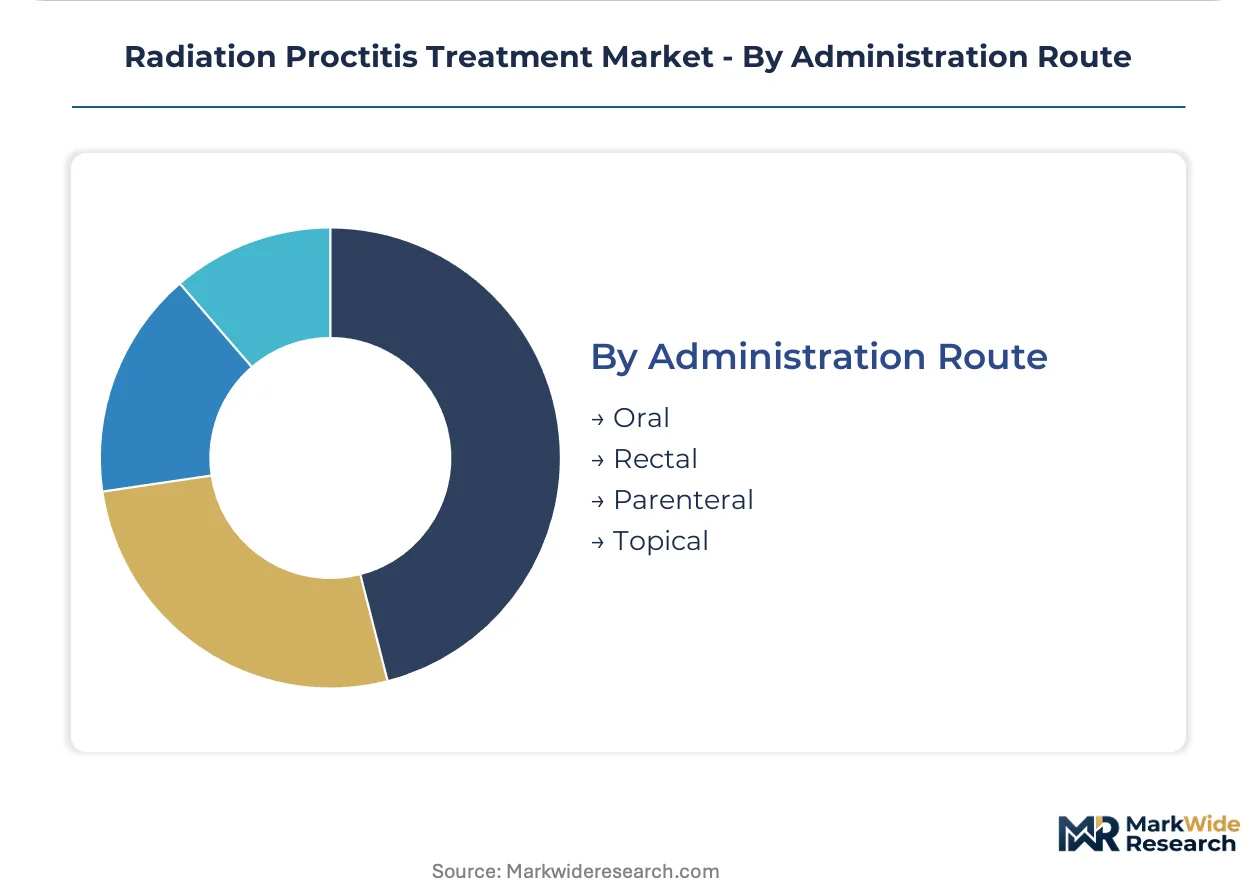
- Rectal:Suppositories, enemas, and hydrogel barriers deliver targeted mucosal drug concentrations with minimal systemic exposure. United States outpatient oncology clinics are standardizing hyaluronic acid-based barriers as first-line prophylaxis.
- Oral:Extended-release formulations and improved bioavailability are displacing parenteral alternatives for maintenance therapy. United States specialty pharmacies report rising dispense volumes for oral 5-ASA compounds.
- Parenteral:Infusion center administration persists for biologic loading doses and acute severe flares.
- Topical:Perianal creams address dermatologic complications of radiation exposure.
Rectal delivery commands the largest addressable procedure volume. Oral routes are climbing fastest as formulation science closes efficacy gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proton therapy hubs in Texas, Florida, and California concentrate the highest-acuity radiation proctitis case volumes and associated specialized treatment protocols. United States integrated delivery networks anchor global demand for salvage biologics and interventional endoscopy services. Regulatory frameworks and reimbursement structures diverge sharply across national boundaries.
United States
Proton therapy installations at MD Anderson Cancer Center, Mayo Clinic Florida, and California Protons are driving parallel proctitis management service line expansion. FDA 510(k) pathway oversight for rectal barrier devices shapes product development timelines and clinical evidence requirements. Texas Medical Center in Houston concentrates tertiary referral volumes for refractory hemorrhagic cases requiring salvage biologics.
Germany
EMA Medical Device Regulation enforcement extends technical documentation timelines for hydrogel barrier manufacturers. KBA-equivalent health technology assessment bodies are narrowing indication coverage for premium barrier formulations. Heidelberg University Hospital anchors European proton therapy capacity and associated proctitis research protocols.
Japan
PMDA regulatory pathways for mesenchymal stromal cell therapies are attracting investigator-initiated trial funding from academic medical centers. METI industrial policy supports domestic biologic fermentation capacity expansion. Osaka University Hospital concentrates stem cell processing facilities for refractory proctitis investigations.
United Kingdom
NHS England specialized commissioning frameworks are consolidating purchasing authority for biologic therapies within tertiary referral networks. MHRA post-Brexit regulatory autonomy is diverging from EMA device approval pathways. London's Royal Marsden Hospital anchors national proton therapy capacity and associated proctitis management expertise.
India
CDSCO accelerated approval pathways for biosimilar anti-TNF therapies are expanding formulary access for chronic proctitis maintenance. Apollo Hospitals and Tata Memorial Centre in Mumbai concentrate private and public proton therapy capacity respectively. Domestic pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad supply oral 5-ASA compounds across South Asian markets.
Radiation Proctitis Treatment Market Key Industry Players
Portfolio diversification dominates the current landscape as gastroenterology-focused pharmaceutical houses and interventional device manufacturers compete for integrated service line contracts. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with gastroenterology franchises, specialized interventional device manufacturers, and regional generic pharmaceutical suppliers. Two strategic archetypes predominate: rectal barrier formulators competing on hydrogel chemistry differentiation, and endoscopic intervention specialists competing on procedural efficiency metrics. M&A activity and strategic partnerships concentrate purchasing power within United States health systems.
Among pharmaceutical specialists, Ferring Pharmaceuticals exemplifies the gastroenterology franchise archetype through its sustained formulary access in European hospital systems. Boston Scientific anchors the interventional device tier with endoscopic deployment systems for hemorrhagic proctitis cases. Cook Medical occupies a position within balloon catheter specialists competing on procedural efficiency metrics for radiation-induced strictures.
| Leading Market Players |
|---|
| Ferring Pharmaceuticals |
| Chugai Pharmaceutical |
| Boston Scientific |
| Dr. Reddy Laboratories |
| Sun Pharmaceutical Industries |
| Cook Medical |
| GlaxoSmithKline |
| Allergan |
| Salix Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
United States integrated delivery networks concentrate purchasing authority for radiation proctitis therapies, anchoring a contract-based procurement model where formulary access determines pricing tiers. Hospital-employed specialists in proton therapy hubs negotiate bundled service agreements that compress unit economics for barrier devices while expanding volume commitments.
Pricing Analysis
Cross-linked hyaluronic acid precursor costs pass through directly to barrier device pricing, with REACH-compliant European feedstock commanding premiums over petroleum-derived alternatives. Three-tier pricing structure across premium hydrogel formulations, standard petroleum barriers, and economy generic suppositories reflects certification grade and procedural efficiency differentiation. Cost compression in the economy tier intensifies as Indian and Chinese manufacturers expand oral 5-ASA compound supply. Community oncology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
FDA 510(k) and EMA MDR certification requirements gate supplier qualification, extending onboarding timelines for novel hydrogel formulators. Manufacturing capacity clusters in Ireland and Belgium for anti-TNF biologics, Germany and Switzerland for precision device components, and India and China for oral pharmaceutical compounds. Supply chain vulnerability rests on concentrated mammalian cell culture capacity for biologic production. Distribution runs through hospital procurement consortia in Europe and GPO-contracted networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiation proctitis treatment has entered a late-cycle quality phase where hyaluronic acid barrier efficacy specifications now dominate procurement scoring over unit cost. This shift rewards manufacturers with validated clinical evidence packages and punishes commodity suppliers.
For Market Incumbents: Anticipate biosimilar adalimumab entry by securing exclusive formulary contracts with United States proton therapy hubs before patent cliffs accelerate. Deepen backward integration into hyaluronic acid fermentation capacity to insulate margin structures from agricultural feedstock volatility. Prioritize real-world evidence generation through FDA 21st Century Cures Act post-market surveillance pathways. For New Entrants and Emerging Players: Begin with home care administration channels where direct-to-patient distribution models remain underdeveloped relative to infusion center saturation. Target specialty pharmacy networks in Texas and Florida proton therapy corridors with rectal foam formulations that reduce facility fee dependency. Lead with patient compliance metrics and reimbursement support services rather than clinical efficacy claims alone. For Investors and Strategic Acquirers: Gastroenterology-focused pharmaceutical houses are the most active acquirer in this space, seeking device-biologic combination portfolios. Long-term viability hinges on exposure to stem cell therapy pipelines and proton therapy service line integration. Monitor FDA breakthrough device designations for novel barrier technologies as the inflection signal for valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Generation | FDA 21st Century Cures Act provisions incentivize post-market data collection from proton therapy centers. |
| CE Marking Pathway Optimization | Streamlined EMA MDR technical documentation accelerates hydrogel barrier registration across German hospital procurement systems. |
| Hospital System Partnership | Integrated radiation oncology-gastroenterology service lines in Texas and California consolidate purchasing authority for salvage biologics. |
| Backward Integration into Fermentation | In-house hyaluronic acid production insulates margin structures from REACH precursor cost volatility. |
| Reimbursement Strategy Development | NCCN guideline alignment determines payer coverage for premium barrier formulations in United States managed care networks. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down biologic manufacturing capacity tracking forms the analytical core of this study. Primary interviews with radiation oncology department heads, gastroenterology service line directors, hospital formulary committees, GPO contracts managers, and specialty pharmacy dispensing operations informed demand-side assumptions. Secondary validation drew from FDA 510(k) device filings, EMA MDR technical documentation, ClinicalTrials.gov stem cell therapy registrations, and CMS Medicare reimbursement databases. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of proton therapy installation patterns and biologic prescription volumes established baseline growth trajectories. The analytical framework segmented across treatment modality, product type, administration route, end-user setting, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to radiation oncology capacity expansion and pricing dynamics tied to biosimilar entry timelines. Forecast inputs incorporated RTOG/EORTC toxicity grading protocol adoption and rectal-sparing radiation technique diffusion rates.
Caveats apply where NCCN guideline revisions or KBA-equivalent reimbursement determinations could materially shift the outlook. Forecasts reflect assumptions about proton therapy hub construction schedules and anti-TNF biosimilar formulary penetration rates. A model refresh is warranted upon material change in FDA breakthrough device designations for novel barrier technologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Microwave Ablation Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Chagas Disease Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Brain Tumor Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Tetanus Treatment Market