
 Chile Endoscopy Devices Market | 2026-2036
Chile Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Endoscopy Devices Market Outlook
Single-use polymers are restructuring cost dynamics in flexible endoscope supply chains. Olympus Corporation leverages its established service infrastructure across Santiago to sustain recurring revenue from reprocessing contracts. Boston Scientific Corporation competes through specialized interventional platforms for biliary and pulmonary access. Karl Storz anchors the rigid endoscope segment with integrated camera-head systems favored by Chilean laparoscopic surgery departments.
Endoscopy devices encompass visualization instruments with insertion tubes ranging from 2.8 mm to 13 mm diameter, incorporating fiber-optic or digital image sensors for internal cavity examination, primarily enabling diagnostic biopsy and therapeutic intervention without open surgery. Flexible endoscopes command the largest installed base in Chilean gastroenterology suites, while robotic-assisted technology represents the fastest-expanding capability category as hospitals seek precision in complex polypectomy procedures. HD imaging systems capture dominant margin pools due to recurring purchases of proprietary processors and light-source upgrades.
Chile's Instituto de Salud Pública enforces medical device registration under Decreto Supremo 825, creating compliance barriers that favor established multinationals with dedicated regulatory affairs teams. The Ministry of Health's HTA unit evaluates endoscopy technology for Fonasa reimbursement, directly shaping hospital procurement priorities. Stakeholders must monitor how Chile's proposed new medical device liability framework alters distributor risk exposure and service-contract structuring.
Market Dynamics
Single-use polymer endoscopes are compressing reprocessing economics across Chilean gastroenterology suites, forcing incumbents with established service infrastructure to restructure recurring revenue models around disposable supply contracts rather than maintenance agreements.
Growth Catalysts
- Decreto Supremo 825 Streamlining:Chile's Ministry of Health registration pathway accelerates import clearance for advanced visualization systems, reducing time-to-market for HD imaging platforms in tertiary care centers.
- Metropolitan Region Hospital Expansion:Public procurement programs in Santiago and Valparaíso are adding minimally invasive surgical capacity, creating installed base demand for flexible endoscope systems.
- Robotic-Assisted Polypectomy:Precision requirements in complex colorectal procedures are pulling capital investment toward integrated surgical platforms in Chile's largest teaching hospitals.
Market Restraints
- Import Dependency for Optical Components:Chile lacks domestic manufacturing of CMOS image sensors and fiber-optic bundles, concentrating supply risk with East Asian component suppliers.
- Fonasa Reimbursement Lag:Chile's HTA unit evaluates endoscopy technology slowly, creating a 12-18 month gap between device registration and public hospital budget allocation.
- Single-Use Cost Premium:Disposable endoscope per-procedure economics remain unfavorable versus reprocessed flexible systems for high-volume screening programs.
Strategic Opportunities
- Antofagasta and Biobío Regional Penetration:Secondary cities outside Santiago show underdeveloped endoscopy capacity relative to disease burden, offering first-mover positioning for mobile screening units.
- AI-Assisted Pathology Integration:Convergence of real-time computer vision with endoscopic imaging enables automated polyp detection that reduces specialist dependency in resource-constrained settings.
- Leasing-Based Equipment Access:Alternative financing structures bypass Fonasa capital budget constraints, accelerating adoption in mid-tier private clinics.
Industry Challenges
- Gastroenterologist Training Pipeline:Chile produces insufficient advanced endoscopists to match equipment deployment, creating utilization gaps in newly equipped facilities.
- Decreto Supremo 825 Compliance Complexity:Registration dossier requirements for software-upgradable systems strain distributor technical documentation capabilities.
- Legacy Processor Integration:HD imaging upgrades require proprietary light-source compatibility, locking hospitals into vendor-specific upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Endoscopy Devices Market |
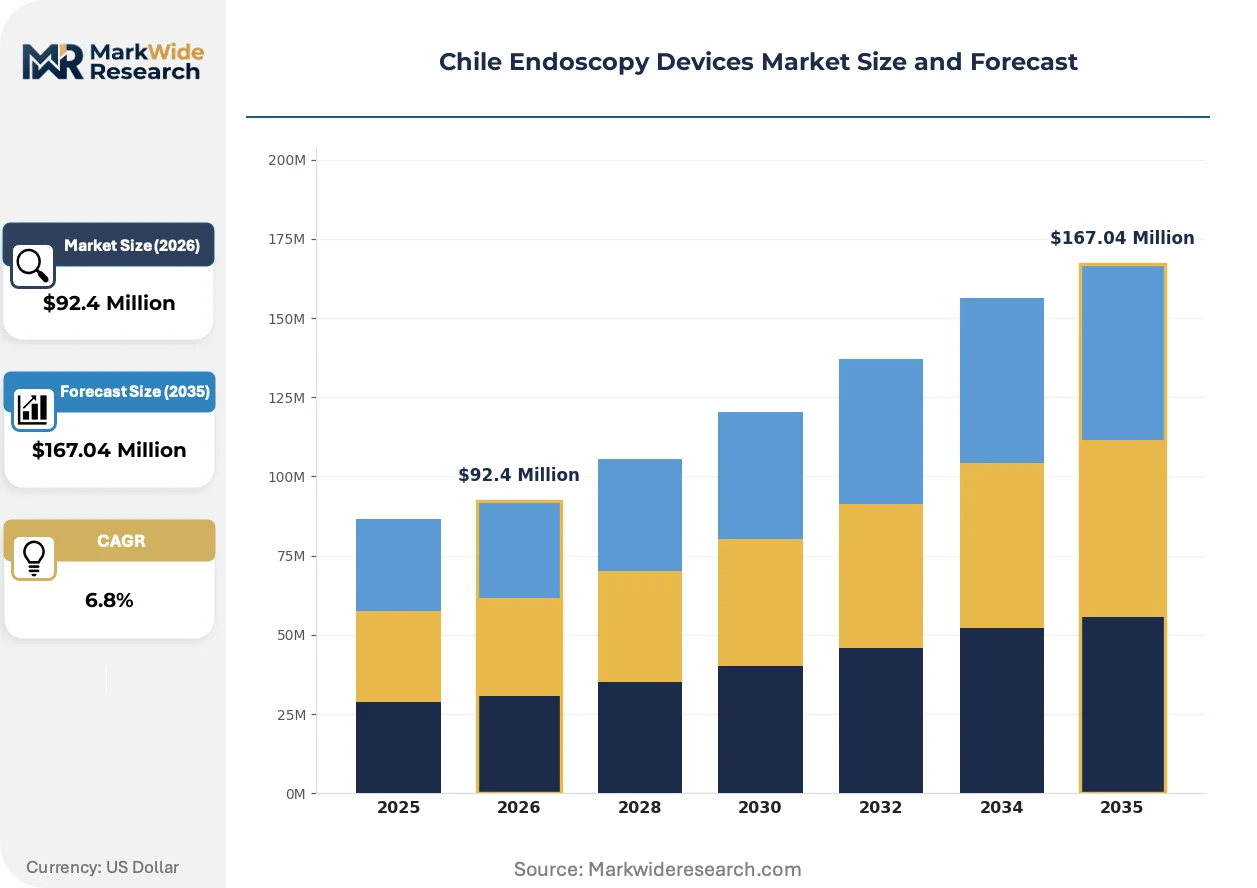
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $167.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Video Endoscopes, Rigid Endoscopes, Flexible Endoscopes, Ultrasound Endoscopes Application: Gastroenterology, Urology, Pulmonology, Gynecology End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Laboratories Technology: HD Imaging, Robotic-assisted, Wireless Endoscopy, Augmented Reality |
| Companies Covered | Johnson & Johnson, Pentax Medical, Boston Scientific Corporation, Fujifilm Holdings Corporation, Richard Wolf GmbH, Medtronic, Karl Storz, CONMED Corporation, Olympus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Endoscopy Devices Market Strategic Shifts
Digital image sensor technology is restructuring competitive advantage around software-defined imaging capabilities rather than optical hardware craftsmanship, compressing traditional differentiation strategies in the Chilean market.
CMOS-based digital endoscopes is electrifying the transition from fiber-optic visualization in Chilean gastroenterology departments. Santiago's largest public hospitals are adopting these platforms at replacement-cycle pace. The technology is electrifying margin compression for service-dependent incumbents while enabling new entrants to bypass established reprocessing infrastructure.
Chile's Instituto de Salud Pública enforces Decreto Supremo 825 registration requirements with increasing scrutiny on software-as-medical-device functionality. This regulatory posture elevates compliance costs for AI-enabled diagnostic features. HD imaging systems with embedded analytics face extended review timelines, favoring simpler hardware-only configurations in initial registrations.
Hospital procurement teams in the Metropolitan Region are unbundling after-sales service from equipment purchase, separating maintenance contracts from capital acquisition decisions. This behavioral shift disrupts traditional vendor lock-in strategies. Private clinic chains in Santiago's eastern districts demonstrate the most aggressive unbundling, driving competitive pressure on service pricing.
Chile Endoscopy Devices Market Segmentation
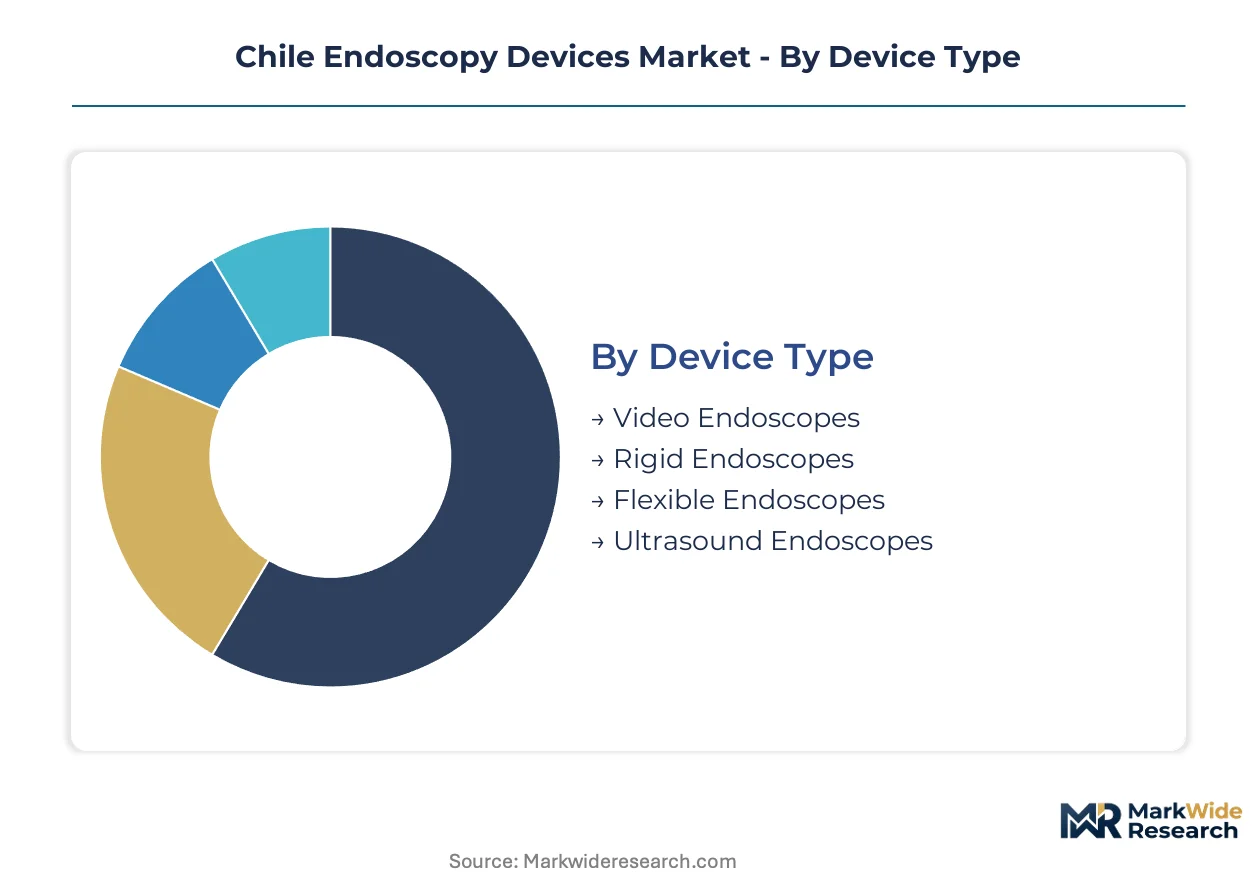
Endoscopy device segmentation in Chile reflects divergent procurement logics across public hospital systems and private clinic chains. Understanding how purchasing criteria vary by device category, clinical application, and technology tier enables vendors to align their Santiago-based service infrastructure with regional expansion priorities.
Device Type:
Hospital procurement committees weight total cost of ownership differently depending on reprocessing capabilities and procedure volume economics.
- Flexible Endoscopes:Fiber-optic and digital insertion systems with 2.8-13 mm diameters dominate Chilean gastroenterology suites. Santiago's tertiary centers prioritize HD-compatible platforms for complex therapeutic procedures, while regional hospitals favor reprocessable models to amortize capital investment across high screening volumes.
- Video Endoscopes:Integrated camera-processor systems with CMOS sensors are displacing fiber-optic visualization in Metropolitan Region teaching hospitals. Procurement teams unbundle service contracts from hardware acquisition, compressing margins for vendors dependent on recurring maintenance revenue.
- Rigid Endoscopes:Laparoscopic and arthroscopic systems with rod-lens optics serve Chilean surgical departments requiring durable instrumentation for repeated sterilization cycles.
- Ultrasound Endoscopes:EUS platforms combining endoscopic access with radial or linear ultrasound imaging enable fine-needle aspiration in pancreatic and biliary diagnostics.
Volume sits with flexible systems; growth tilts toward video endoscopes with embedded digital sensors.
Application:
Clinical specialization determines equipment specification requirements and reimbursement pathways through Fonasa's HTA evaluation process.
- Gastroenterology:Colonoscopy and upper GI platforms constitute the largest installed base across Chilean healthcare facilities. The Ministry of Health's cancer screening programs in Santiago and Valparaíso drive demand for reliable, high-throughput systems capable of polypectomy and mucosal resection.
- Pulmonology:Bronchoscopy systems with narrow-band imaging and electromagnetic navigation support lung cancer staging in Chile's largest respiratory centers. Interventional pulmonology expansion in Biobío Region creates demand for advanced tissue sampling capabilities.
- Urology:Cystoscopy and ureteroscopy platforms serve Chilean urology departments managing benign prostatic hyperplasia and upper tract urothelial carcinoma.
- Gynecology:Hysteroscopy systems enable diagnostic and operative procedures in Chilean obstetrics and gynecology units, with fertility clinics driving specialized demand.
Procedure volume concentrates in gastroenterology; capability investment flows fastest into pulmonology interventional platforms.
End User:
Facility type shapes capital acquisition constraints, with Fonasa reimbursement timelines and private financing availability creating divergent purchasing rhythms.
- Hospitals:Public tertiary centers in Metropolitan Region anchor equipment procurement through centralized Ministry of Health programs. Decreto Supremo 825 registration requirements favor established vendors with dedicated regulatory affairs capacity in Santiago.
- Clinics:Private outpatient facilities in Santiago's eastern districts demonstrate aggressive unbundling of service contracts from capital purchases, driving competitive pressure on maintenance pricing.
- Ambulatory Surgical Centers:Same-day procedure facilities require compact, mobile endoscopy platforms with rapid turnover capabilities.
- Research Laboratories:University-affiliated centers in Chile demand experimental platforms for clinical trial protocols and advanced imaging research.
Capital deployment concentrates in hospitals; facility expansion moves fastest among ambulatory surgical centers seeking lease-based equipment access.
Technology:
Software-defined capabilities are restructuring competitive advantage away from optical hardware craftsmanship toward algorithmic imaging enhancement.
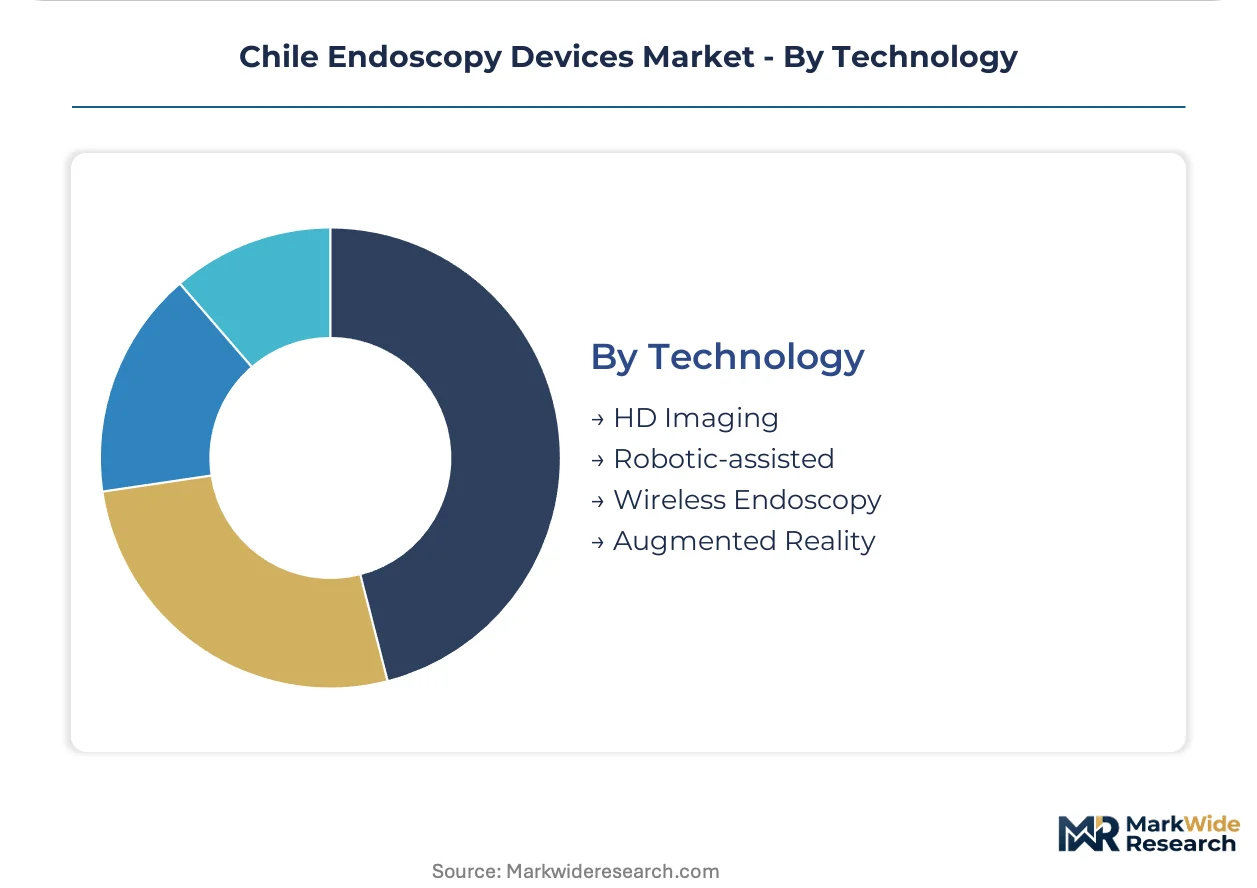
- HD Imaging:High-definition visualization systems with 1080p or 4K resolution capture dominant margin pools through recurring processor and light-source upgrades. Santiago's largest public hospitals adopt these platforms at replacement-cycle pace.
- Robotic-assisted:Integrated surgical platforms enable precision in complex polypectomy procedures, with Chile's teaching hospitals pulling capital investment toward computer-assisted navigation and instrument stabilization.
- Wireless Endoscopy:Capsule-based systems with ingestible cameras serve diagnostic indications where conventional endoscope insertion carries elevated risk.
- Augmented Reality:Overlay systems projecting anatomical guidance onto live endoscopic views remain early-stage in Chilean facilities, constrained by software-as-medical-device registration complexity under Instituto de Salud Pública scrutiny.
Revenue concentrates in HD imaging; capability adoption expands most quickly in robotic-assisted platforms for complex therapeutic procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for endoscopy devices in Chile concentrates in tertiary care centers across the Metropolitan Region, with Santiago and Valparaíso anchoring procurement volume through centralized Ministry of Health programs. Regional expansion into secondary cities is reshaping distribution priorities.
Metropolitan Region
Santiago's public hospital networks drive installed base growth through Decreto Supremo 825 procurement pathways. The Ministry of Health's HTA unit evaluates visualization systems for Fonasa reimbursement, creating 12-18 month budget allocation cycles. Clinical complexes in Providencia and Las Condes deploy HD imaging platforms at replacement-cycle pace.
Valparaíso Region
Port-city healthcare clusters require flexible endoscope systems for high-throughput screening programs targeting colorectal cancer. Regional health authorities coordinate equipment standardization across Viña del Mar and Valparaíso metropolitan hospitals. The area's teaching institutions pull capital investment toward integrated surgical platforms.
Biobío Region
Concepción's expanding gastroenterology departments generate demand for reprocessable flexible systems that amortize capital across procedure volume. Regional health service procurement favors established vendors with Santiago-based regulatory affairs capacity. Interventional pulmonology expansion creates secondary demand for advanced tissue sampling capabilities.
Antofagasta Region
Mining-centric population centers exhibit underdeveloped endoscopy capacity relative to occupational health disease burden. Mobile screening units present first-mover positioning opportunities outside metropolitan procurement hierarchies. Private clinic chains in Antofagasta city demonstrate lease-based equipment access preferences.
Chile Endoscopy Devices Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents restructure around disposable supply contracts. The vendor base organizes into three tiers: multinationals with dedicated regulatory affairs teams in Santiago, regional distributors with service infrastructure, and emerging entrants leveraging CMOS-based digital platforms. Strategic archetypes include reprocessing-dependent incumbents, single-use polymer specialists, and integrated surgical platform providers. Competitive moves center on unbundling service contracts from capital sales and accelerating software-as-medical-device registrations under Instituto de Salud Pública scrutiny.
Among Japan-based multinationals, Olympus Corporation and Fujifilm Holdings Corporation occupy positions anchored by established service infrastructure across Santiago. Boston Scientific Corporation exemplifies the interventional platform specialist archetype, while Karl Storz represents the rigid endoscope incumbent with integrated camera-head systems favored by Chilean laparoscopic surgery departments. Johnson & Johnson, Medtronic, and Pentax Medical sit within the diversified medical technology tier competing through broad portfolio breadth.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pentax Medical |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| Richard Wolf GmbH |
| Medtronic |
| Karl Storz |
| CONMED Corporation |
| Olympus Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive service infrastructure across Santiago anchors pricing power for established multinationals while compressing margin capture for distributors lacking proprietary reprocessing capabilities. This integration pattern separates vendors who bundle maintenance contracts from those competing on disposable supply economics, with Decreto Supremo 825 compliance costs further stratifying market access tiers.
Pricing Analysis
Volume concentrates in reprocessable flexible endoscopes while margins flow to HD imaging platforms with proprietary processor upgrades. Three-tier pricing structure across premium, standard, and economy levels differentiates by after-sales bundling and certification grade under Instituto de Salud Pública pathways. Cost compression in the mid-tier intensifies because procurement committees unbundle service from hardware acquisition. Public hospital systems exhibit highest price sensitivity; private clinic chains in Santiago's eastern districts demonstrate lowest sensitivity due to lease-based financing access.
Supply Chain Analysis
Regional distribution centers in Santiago's Providencia and Las Condes districts operate hub-and-spoke patterns reaching secondary cities with 48-72 hour replenishment cycles. Component manufacturing concentrates in Japan, Germany, and the United States for CMOS image sensors, fiber-optic bundles, and precision optical elements. Chilean distributors draw from East Asian assembly facilities for insertion tube polymers and light-source modules. Single-source vulnerability around CMOS sensor suppliers creates procurement risk concentration. Distribution runs through Ministry of Health centralized procurement channels for public tertiary centers, with private clinics accessing direct importer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's endoscopy device sector sits in a fiber-optic-to-digital transition phase, with CMOS-based video endoscopes displacing legacy fiber-optic visualization in Metropolitan Region teaching hospitals. This technology replacement cycle restructures competitive advantage around software-defined imaging rather than optical hardware craftsmanship.
For Market Incumbents:Anchoring recurring revenue through reprocessing service contracts defends against single-use polymer entrants compressing per-procedure economics. Incumbents should deepen backward integration into Santiago-based technical support infrastructure to offset unbundling pressure from procurement committees. Regulatory affairs capacity under Decreto Supremo 825 pathways remains the critical lever for maintaining hospital system access against emerging CMOS-platform competitors.
For New Entrants and Emerging Players:Enter via mobile screening unit deployments in Antofagasta and Biobío regions where endoscopy capacity lags disease burden and established service infrastructure is sparse. The most penetrable segment comprises mid-tier private clinics seeking lease-based equipment access outside Fonasa capital constraints. A software-as-medical-device registration strategy targeting simpler hardware-only initial configurations accelerates time-to-market under Instituto de Salud Pública review timelines.
For Investors and Strategic Acquirers:Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking Santiago-based regulatory affairs capacity and established hospital system relationships. Long-term viability hinges on positioning within the digital imaging transition rather than legacy fiber-optic platforms. Acquisition target archetypes include regional distributors with unbundled service contract expertise and CMOS-platform specialists with software-defined imaging capabilities. The signal to watch is Fonasa HTA unit acceleration of reimbursement evaluations for AI-assisted diagnostic features, which would validate premium pricing for algorithmic imaging enhancement.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Registration | Accelerates Instituto de Salud Pública clearance for AI-enabled imaging platforms in Santiago teaching hospitals. |
| Hospital System Partnership | Secures installed base demand through Ministry of Health centralized procurement programs in Metropolitan Region. |
| Reimbursement Strategy | Aligns HTA evaluation timelines with Fonasa budget allocation cycles for public hospital capital deployment. |
| Service Contract Unbundling | Responds to procurement committee behavior separating maintenance from hardware acquisition in private clinics. |
| Geographic Expansion | Captures first-mover positioning in Antofagasta and Biobío regional markets outside Santiago procurement hierarchies. |
Study Parameters
Hospital procurement databases, GPO contracts, and Instituto de Salud Pública registration filings formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at Santiago-based distributors triangulated against secondary validation. Bottom-up equipment installation tracking across Metropolitan Region tertiary centers combined with top-down Ministry of Health budget allocation analysis to anchor volume estimates.
Historical trendline analysis of replacement cycle timing and technology transition patterns informed projection modeling across the analysis window. Segmentation dimensions included device type, clinical application, end-user facility tier, and technology sophistication level. CAGRs derived from procedure volume growth assumptions tied to cancer screening program expansion and minimally invasive surgical capacity additions. Forecast inputs incorporated Fonasa HTA evaluation pipeline visibility and Decreto Supremo 825 regulatory pathway efficiency estimates.
Revisions become necessary when Fonasa reimbursement timelines extend beyond current 12-18 month cycles, when Instituto de Salud Pública intensifies software-as-medical-device scrutiny, or when single-use polymer cost economics shift materially against reprocessing models. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
Bronchoscopy Market
Endoscopy
Colonic Stents Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market