
 Tetanus Treatment Market | 2026-2036
Tetanus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tetanus Treatment Market Outlook
The WHO Expanded Programme on Immunization is realigning procurement priorities for tetanus prophylaxis across national health systems. GlaxoSmithKline leverages its established toxoid manufacturing infrastructure to sustain supply contracts with multilateral vaccine procurement bodies. Serum Institute of India anchors regional access through high-volume, cost-competitive production of tetanus-diphtheria combinations for public health programs.
Tetanus treatment encompasses pharmaceutical and biological interventions designed to neutralize Clostridium tetani exotoxins, prevent toxin binding to neural tissue, and manage autonomic dysfunction and muscle spasticity in infected patients; tetanus immune globulin provides immediate passive immunity through antitoxin antibodies, while tetanus toxoid vaccines stimulate active immunity via formalin-inactivated toxin administered in aluminum salt adjuvant suspensions. Tetanus toxoid products occupy the largest revenue share within product type segmentation due to decades of inclusion in routine pediatric and adult booster schedules. Immune globulin represents the fastest-expanding segment, driven by emergency department protocols mandating immediate post-exposure prophylaxis for wound cases with unknown or incomplete vaccination history.
The FDA regulates tetanus biologics under stringent lot-release testing and cGMP manufacturing requirements that shape product approval timelines and facility investment decisions. India's CDSCO enforces parallel standards for domestically manufactured toxoids through its Central Drugs Laboratory certification process, while the WHO prequalification program governs access to international procurement channels for low-income country distribution. Stakeholders must monitor evolving regulatory convergence between national regulators and WHO prequalification benchmarks to anticipate qualification barriers and optimize facility certification strategies.
Market Dynamics
The WHO Expanded Programme on Immunization is compressing procurement cycles for tetanus prophylaxis across national health systems. This multilateral framework is reshaping how governments prioritize toxoid and immune globulin allocation, forcing manufacturers to align production schedules with centralized tender timelines rather than fragmented commercial orders.
Growth Catalysts
- Emergency department protocols:Hospital trauma units now mandate immediate post-exposure prophylaxis for wound cases with unknown vaccination history, expanding immune globulin utilization.
- India's Universal Immunization Programme:Government-funded drives for tetanus-diphtheria boosters generate sustained procurement volume for domestic manufacturers.
- Formalin-inactivated toxoid adjuvant technology:Aluminum salt suspension formulations enable extended shelf stability, reducing cold chain burden for tropical distribution.
Market Restraints
- Equine serum supply concentration:Tetanus immune globulin production depends on hyperimmunized horse herds concentrated in limited geographies, creating biological input vulnerability.
- Lot-release testing timelines:FDA cGMP requirements extend certification cycles for new manufacturing facilities, delaying market entry for emerging suppliers.
- Recombinant antitoxin substitutes:Monoclonal antibody platforms for clostridial neutralization threaten displacement of plasma-derived immune globulin in prophylaxis protocols.
Strategic Opportunities
- Sub-Saharan Africa immunization gaps:Underpenetrated routine vaccination coverage creates procurement white space for WHO prequalified toxoid suppliers.
- Combination vaccine convergence:Tetanus-diphtheria-pertussis-poliomyelitis quadravalent formulations streamline national schedule compliance and reduce injection burden.
- Direct government contracting channels:Bypassing multilateral procurement bodies enables faster tender fulfillment and stronger price negotiation leverage for established manufacturers.
Industry Challenges
- Antitoxin potency standardization:International Unit calibration discrepancies between national control laboratories complicate cross-border product equivalence claims.
- Legacy fill-finish equipment retrofitting:Existing toxoid production lines require substantial capital reinvestment to meet evolving WHO prequalification environmental monitoring standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetanus Treatment Market |
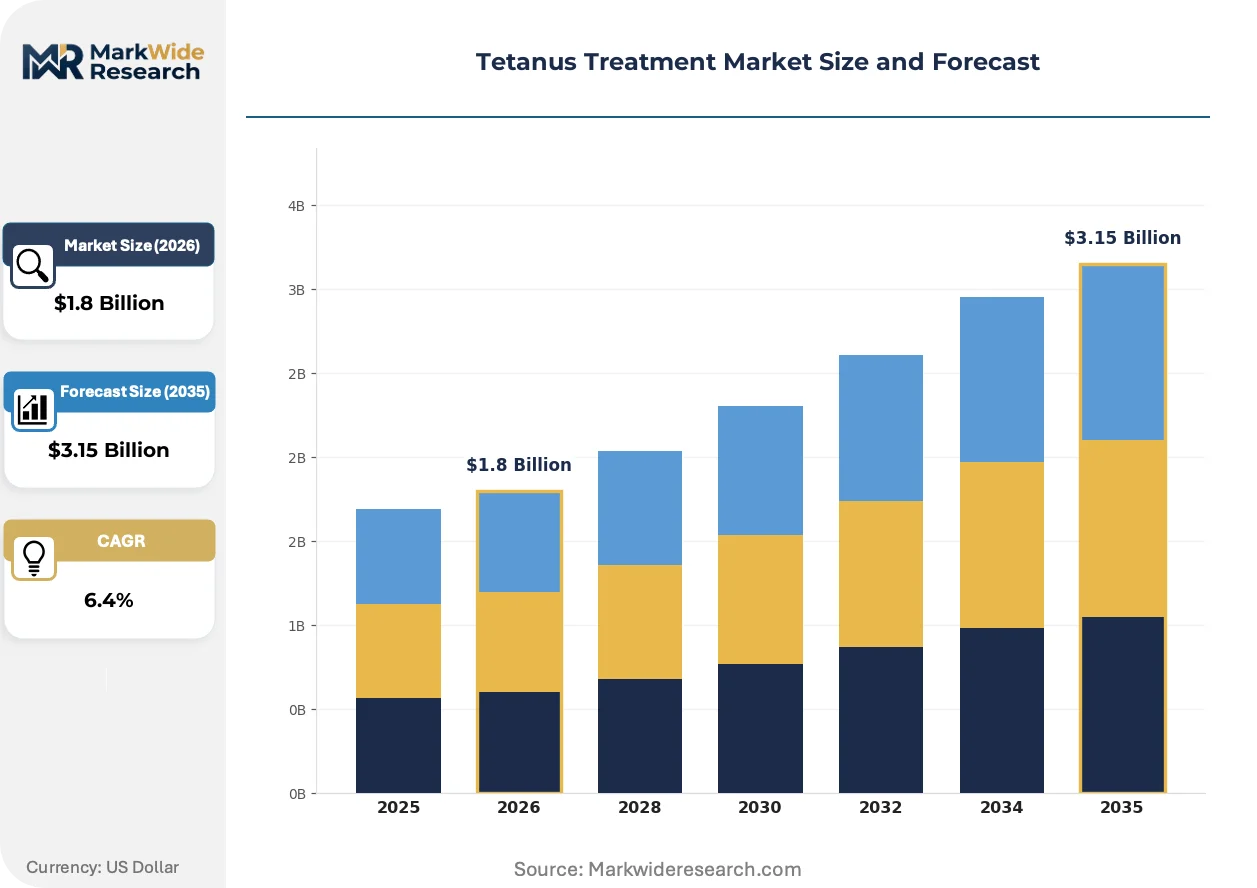
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tetanus Toxoid, Immune Globulin, Antibiotics, Supportive Care Delivery Mode: Intramuscular Injection, Subcutaneous Injection, Intravenous Infusion, Oral Administration End User: Hospitals, Clinics, Emergency Care Centers, Home Care Application: First Aid, Preventive Care, Emergency Treatment, Post-Exposure Prophylaxis |
| Companies Covered | Sanofi, GlaxoSmithKline, Merck & Co., Inc., Serum Institute of India, PT Bio Farma, Biological E, Pfizer Inc., Bharat Biotech, Emergent BioSolutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetanus Treatment Market Strategic Shifts
Biomanufacturing automation and regulatory harmonization are compressing development timelines for tetanus biologics. These forces are enabling faster response to outbreak-driven demand surges while reducing facility-dependent quality variation.
Single-use bioreactor systems for tetanus toxoid fermentation are unifying upstream production workflows across multi-product vaccine facilities. Serum Institute of India and comparable high-volume manufacturers are adopting disposable vessel technology to accelerate changeover between toxoid and combination vaccine campaigns. This shift is unifying quality assurance protocols across product lines, reducing batch failure rates and enabling faster response to government tender deadlines.
India's CDSCO has tightened Central Drugs Laboratory certification requirements for tetanus toxoid potency testing, mandating parallel mouse bioassay and in vitro alternatives for lot release. Domestic manufacturers must now maintain dual validation capability, extending facility qualification timelines by several months. Small and mid-scale suppliers are responding by consolidating testing services through third-party contract laboratories in Hyderabad and Pune.
Hospital procurement departments are consolidating tetanus biologics purchasing through centralized pharmacy and therapeutics committees, displacing fragmented emergency department stock-keeping. This concentration shifts bargaining power toward group purchasing organizations and away from individual facility buyers. The pattern is most visible in India's corporate hospital chains, where standardized wound management protocols now specify preferred immune globulin and toxoid brands across multi-site networks.
Tetanus Treatment Market Segmentation
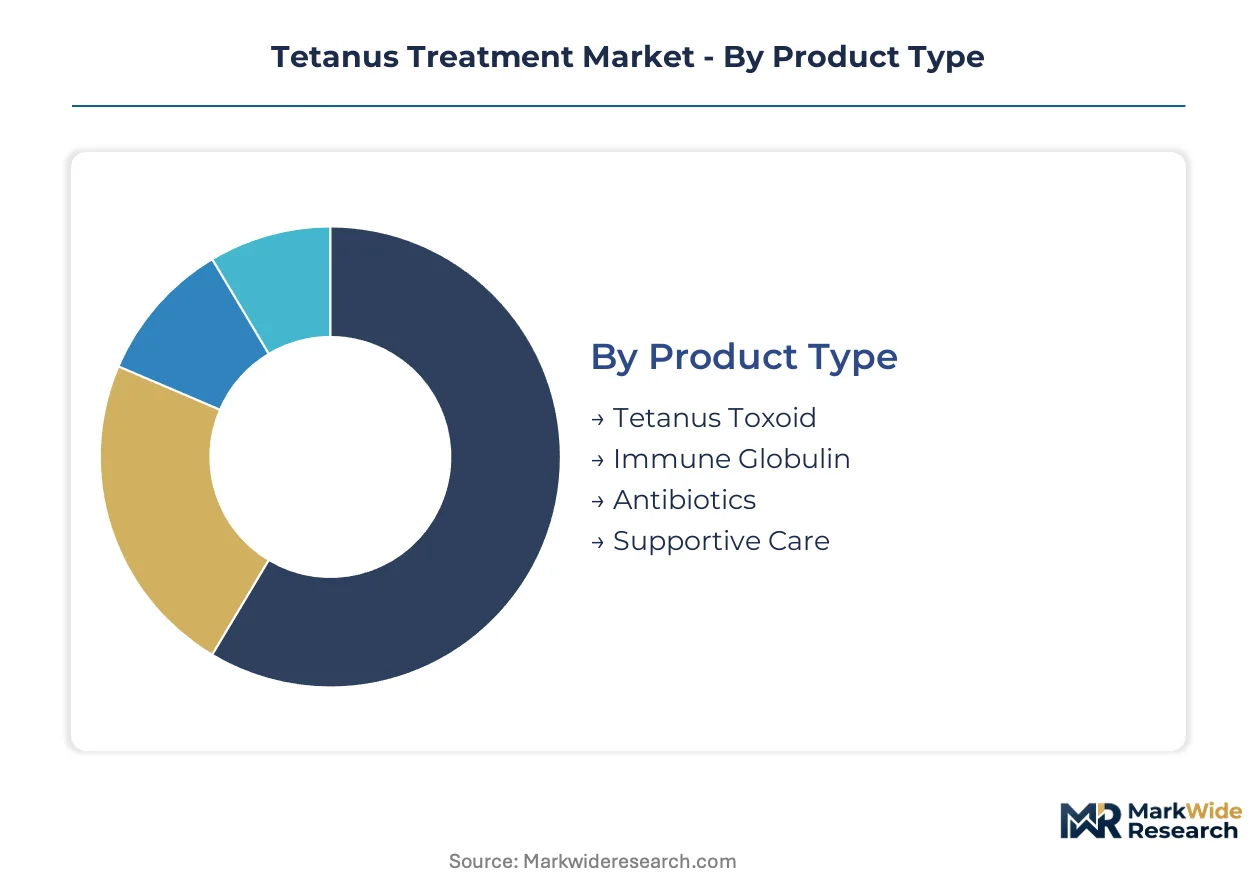
Tetanus treatment segmentation reflects divergent clinical pathways: routine immunization infrastructure versus acute emergency intervention. Product type and delivery mode choices cascade through procurement channels, reimbursement codes, and regulatory filing requirements. Understanding these segment boundaries enables suppliers to align manufacturing capacity with the distinct velocity and volume patterns of each demand pool.
Product Type:
Standardization dominates toxoid manufacturing through WHO prequalification protocols, while immune globulin retains customization through potency-tiered dosing and equine source variation.
- Tetanus Toxoid:Formalin-inactivated toxin suspended in aluminum salt adjuvant, administered in scheduled pediatric and adult booster regimens. India's Universal Immunization Programme generates concentrated procurement volume through government tender consolidation. WHO prequalification mandates compress supplier qualification timelines and favor established multi-product vaccine facilities.
- Immune Globulin:Plasma-derived or equine-sourced antitoxin antibodies providing immediate passive immunity for wound management. Emergency departments in Indian corporate hospital chains now mandate standardized post-exposure protocols, expanding utilization for trauma cases with unknown vaccination history. Equine serum supply concentration in limited geographies constrains production scalability.
- Antibiotics:Adjunctive agents targeting Clostridium tetani bacterial load in established infections. Metronidazole and penicillin G dominate institutional formularies through cost-competitive generic availability.
- Supportive Care:Muscle relaxants, sedatives, and autonomic stabilizers managing tetanus symptomatology in intensive care settings. ICU sedation protocols vary across facility tiers, creating fragmented demand.
Leading the category by volume: Tetanus Toxoid. Expanding most quickly: Immune Globulin.
Delivery Mode:
Route selection maps directly to clinical setting infrastructure and urgency gradients across the treatment continuum.
- Intramuscular Injection:Dominant administration route for toxoid boosters and immune globulin prophylaxis. India's cold chain distribution networks prioritize intramuscular formulations for rural immunization outreach. Aluminum adjuvant suspensions require deep deltoid or gluteal deposition to minimize local reactogenicity.
- Subcutaneous Injection:Alternative route for specific combination vaccines and patients with contraindications to intramuscular delivery. Limited utilization in mass vaccination campaigns due to slower absorption kinetics.
- Intravenous Infusion:Required for severe tetanus cases requiring continuous antitoxin administration and ICU-based supportive therapy. Indian tertiary hospitals maintain dedicated infusion capacity for neurotoxic emergency management.
- Oral Administration:Restricted to adjunctive antibiotics and supportive medications in stable patients. No primary tetanus-specific biologics utilize oral bioavailability.
Intramuscular Injection captures the largest procurement volume. Intravenous Infusion shows steepest expansion trajectory driven by ICU protocol standardization.
End User:
Facility type determines procurement velocity, with emergency care demanding immediate availability against scheduled immunization predictability.
- Hospitals:Primary locus for severe tetanus treatment and complex wound management. India's corporate hospital chains consolidate biologics purchasing through centralized pharmacy committees, displacing fragmented site-level procurement.
- Clinics:Outpatient settings handling routine booster administration and minor wound prophylaxis. Government-funded primary health centers in India anchor rural toxoid access through the Universal Immunization Programme.
- Emergency Care Centers:Rapid-response facilities requiring immediate immune globulin availability for trauma cases. Protocol standardization across networks is compressing brand selection discretion.
- Home Care:Limited to stable post-ICU patients requiring continued supportive medication administration. Negligible biologics utilization due to parenteral administration requirements.
Hospitals dominate absolute volume. Emergency Care Centers are gaining share fastest through trauma protocol expansion.
Application:
Prophylactic versus therapeutic intent splits demand across scheduled procurement and surge-responsive supply chains.
- First Aid:Immediate wound cleaning and preliminary antiseptic intervention at point of injury. Community health workers in India distribute basic first aid supplies through rural outreach programs.
- Preventive Care:Scheduled toxoid boosters maintaining active immunity in pediatric and adult populations. WHO Expanded Programme on Immunization shapes national schedule alignment across developing economies.
- Emergency Treatment:Active tetanus infection management requiring intensive care hospitalization and multimodal therapy. Specialized ICU capacity constraints limit treatment access in resource-limited settings.
- Post-Exposure Prophylaxis:Immediate immune globulin and toxoid administration following contaminated wound exposure. Emergency department protocols now mandate standardized administration for unknown vaccination history cases.
Preventive Care leads by volume. Post-Exposure Prophylaxis climbs fastest through emergency protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune anchors tetanus biologics manufacturing through Serum Institute of India's high-volume toxoid production campus and the surrounding contract testing laboratory cluster in Maharashtra state.
United States
Emergency department protocols mandating immediate post-exposure prophylaxis drive immune globulin procurement across hospital networks. FDA lot-release testing and cGMP manufacturing requirements shape facility investment decisions and extend certification timelines for new suppliers. The Maryland-Virginia corridor concentrates plasma fractionation capacity for antitoxin production.
India
Government-funded Universal Immunization Programme generates sustained procurement volume for tetanus-diphtheria combinations through centralized tender consolidation. CDSCO enforces tightened Central Drugs Laboratory certification requirements for toxoid potency testing, mandating dual validation capability. Hyderabad and Pune host consolidated third-party contract laboratories serving domestic manufacturers.
Germany
EMA regulatory frameworks govern tetanus biologics distribution across EU member states through centralized marketing authorization procedures. The country's national pharmaceutical regulator enforces stringent environmental monitoring standards for vaccine fill-finish operations. Bavaria's biomanufacturing corridor maintains multi-product vaccine facilities with toxoid changeover capability.
Brazil
ANVISA oversees parallel standards for imported and domestically manufactured toxoids, aligning with WHO prequalification benchmarks for regional procurement access. Routine immunization schedule gaps in northern states create demand for expanded cold chain distribution. São Paulo's pharmaceutical manufacturing cluster supports regional supply consolidation for Latin American markets.
China
NMPA regulates tetanus biologics under domestic lot-release testing protocols that diverge from WHO prequalification timelines, creating separate qualification pathways for national versus international supply. Provincial immunization programs drive volume procurement for pediatric toxoid schedules. The Yangtze River Delta concentrates fermentation capacity for formalin-inactivated toxin production.
Tetanus Treatment Market Competitive Environment
The competitive structure tilts toward established multi-product vaccine facilities with prequalified manufacturing infrastructure. Market concentration favors suppliers capable of synchronized production across toxoid and combination vaccine campaigns. Three archetypes dominate: high-volume public health suppliers, plasma fractionation specialists, and diversified pharmaceutical conglomerates. Capacity expansion and regulatory harmonization represent the primary competitive moves as manufacturers align with WHO tender timelines.
Within the high-volume public health supplier tier, Serum Institute of India and PT Bio Farma exemplify cost-competitive production models anchored in developing economy immunization programs. GlaxoSmithKline occupies a position among diversified pharmaceutical conglomerates leveraging established toxoid manufacturing infrastructure for multilateral procurement contracts. These three entities represent distinct geographic and operational archetypes spanning Indian, Indonesian, and UK-based manufacturing origins.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline |
| Merck & Co., Inc. |
| Serum Institute of India |
| PT Bio Farma |
| Biological E |
| Pfizer Inc. |
| Bharat Biotech |
| Emergent BioSolutions |
| Others |
Value Chain & Pricing Dynamics
Single-use bioreactor adoption across tetanus toxoid fermentation is simultaneously compressing per-batch production costs and concentrating manufacturing capability among high-volume facilities with disposable vessel infrastructure. This technology transition favors suppliers capable of rapid campaign changeover between toxoid and combination vaccine production, creating procurement leverage for buyers with consolidated tender volumes.
Pricing Analysis
Value-based pricing anchors on immunization coverage outcomes and cold chain reliability rather than unit cost alone. Pricing stratifies across WHO-prequalified, domestic-regulatory, and non-certified tiers based on potency testing rigor and aluminum adjuvant formulation standards. Cost compression in the non-certified tier intensifies as Indian manufacturers consolidate testing services through third-party laboratories in Hyderabad and Pune. Government procurement bodies demonstrate lowest price sensitivity due to schedule compliance mandates, while private hospital chains negotiate hardest on immune globulin contracts.
Supply Chain Analysis
Dual-sourcing requirements for tetanus immune globulin now mandate equine serum qualification from at least two geographic origins to mitigate biological input vulnerability. Manufacturing concentrates in India, Indonesia, and the United Kingdom through Serum Institute of India, PT Bio Farma, and GlaxoSmithKline respectively. Production rests on hyperimmunized horse herds, formalin supply for toxin inactivation, and aluminum salt adjuvant inputs. Single-source vulnerability in equine serum collection creates exposure to veterinary disease outbreaks. Distribution runs through government immunization cold chains and hospital pharmacy committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monoclonal antibody platforms for clostridial neutralization are displacing plasma-derived immune globulin in prophylaxis protocols, compressing the technology transition window for legacy suppliers.
For Market Incumbents: Anchor toxoid manufacturing capacity through backward integration into aluminum salt adjuvant production and captive fill-finish lines. Consolidate testing capability in-house to avoid CDSCO-mandated dual validation delays. Defend against monoclonal antibody substitutes by accelerating combination vaccine convergence into quadravalent formulations. For New Entrants and Emerging Players: The price-point gap between premium WHO-prequalified toxoids and economy domestic-grade products creates procurement white space for mid-tier suppliers. Target sub-Saharan African immunization gaps through direct government contracting channels bypassing multilateral tender bodies. Enter via contract manufacturing partnerships with established fill-finish facilities to circumvent FDA cGMP certification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with plasma fractionation specialists given equine serum supply concentration and limited geographic alternatives. Long-term viability hinges on five-to-ten year immunization schedule persistence against recombinant substitute threat. Monitor monoclonal antibody clinical trial progression as inflection indicator for immune globulin demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks access to UNICEF and Gavi procurement channels for low-income country distribution. |
| Combination Vaccine Convergence | Streamlines national schedule compliance and reduces injection burden for immunization programs. |
| Manufacturing Scale-Up | Aligns production schedules with centralized government tender timelines rather than fragmented orders. |
| Backward Integration | Captive aluminum salt adjuvant production reduces input cost volatility and lot-release delays. |
| Direct Government Contracting | Bypasses multilateral procurement bodies for faster tender fulfillment and stronger price negotiation leverage. |
Study Parameters
Independent corroboration across regulatory filings, procurement databases, and manufacturing facility disclosures underwrites the qualitative findings. Primary interviews with vaccine development executives, CDSCO regulatory affairs leads, hospital pharmacy procurement managers, and WHO immunization program officers combined with secondary validation from FDA biologics license applications, EMA centralized marketing authorization procedures, ClinicalTrials.gov antibody platform trials, and Indian government tender records. Bottom-up and top-down triangulation anchored volume estimates to actual production capacity and immunization schedule coverage data.
Comparable-period anchoring tied the projection horizon to historical procurement cycle patterns and regulatory approval timelines observed across prior vaccine prequalification waves. The analytical framework modeled segmentation across product type, delivery mode, end user facility tier, and application intent throughout the forecast period. CAGRs derived from regression against immunization coverage expansion targets and emergency department protocol adoption curves. Forecast inputs incorporated aluminum adjuvant supply constraints and equine serum collection capacity as industry-specific variables.
Inputs from CDSCO certification records and WHO prequalification databases were available through the study window; gaps in proprietary equine serum herd health data introduce uncertainty bands around immune globulin production capacity assumptions. Forecasts reflect documented assumptions regarding monoclonal antibody platform progression and national immunization program budget continuity. Deviation in recombinant antitoxin clinical trial outcomes or WHO Expanded Programme on Immunization funding levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market