
 Chagas Disease Treatment Market | 2026-2036
Chagas Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chagas Disease Treatment Market Analysis
Results-based financing for neglected tropical disease programs is reconfiguring how pharmaceutical suppliers participate in Chagas disease markets. Bayer AG leverages its manufacturing scale to maintain stable antiparasitic production volumes across endemic zones. Novartis AG anchors its position through sustained R&D investment in tropical disease therapeutics. F. Hoffmann-La Roche Ltd differentiates via diagnostic-test bundling that complements drug distribution networks.
Chagas disease treatment encompasses antiparasitic chemotherapy targeting Trypanosoma cruzi infection, with benznidazole and nifurtimox serving as first-line nitroheterocyclic compounds that disrupt parasite DNA and cellular metabolism during acute and chronic phases. These therapies aim to eliminate circulating parasites, halt cardiomyopathy progression, and reduce gastrointestinal megasyndrome risk in infected populations. Benznidazole dominates current product type demand due to established efficacy profiles and preferential WHO Essential Medicines List status, while combination therapy represents the fastest-growing segment as researchers evaluate synergistic protocols against resistant strains. Oral delivery mode leads volume distribution because of outpatient suitability in resource-limited settings, though intravenous formulations retain importance for severe acute cases requiring hospitalization.
FDA review pathways for tropical disease priority vouchers and EMA orphan drug incentives shape competitive entry timelines for new Chagas therapies. Brazil's ANVISA and Argentina's ANMAT enforce bioequivalence standards for generic benznidazole that determine market access for local manufacturers like Laboratorio Elea Phoenix. Stakeholders must monitor WHO prequalification status changes and national procurement tender structures to anticipate volume shifts between originator and generic supply sources.
Market Dynamics
Results-based financing mechanisms are restructuring pharmaceutical supplier relationships across endemic zones, concentrating procurement power in national health ministries while fragmenting diagnostic-test distribution among regional laboratories.
Growth Catalysts
- WHO Neglected Tropical Disease Roadmap:The 2021-2030 targets mandate expanded screening access in Bolivia and Paraguay, channeling development assistance into benznidazole procurement pipelines.
- Vector Control Investments:Brazil's Ministry of Health directs insecticide spraying programs toward Triatoma infestans habitats, reducing reinfection rates and sustaining treatment demand in chronic-phase patients.
- Point-of-Care Diagnostics:Rapid serological test deployment in rural Argentine clinics accelerates case detection and links infected populations to antiparasitic therapy enrollment.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for nitroheterocyclic compounds clusters in Indian and Chinese contract manufacturers, exposing formulators to cross-border logistics disruptions.
- Toxicity Profile Limitations:Benznidazole's adverse event spectrum restricts treatment eligibility in pregnant women and severe hepatic impairment patients, narrowing addressable populations.
- Substitution Pressure:Posaconazole and other azole antifungals demonstrate in vitro activity against Trypanosoma cruzi amastigotes, diverting research investment from first-line antiparasitic optimization.
Strategic Opportunities
- Underpenetrated Amazon Basins:Colombia's Putumayo and Caquetá departments maintain limited diagnostic coverage despite established triatomine transmission, creating whitespace for mobile screening units.
- Pediatric Formulation Gaps:Dissolvable benznidazole tablets for low-weight children remain inadequately supplied, opening formulation partnerships with regional compounding pharmacies.
- EMA Orphan Drug Incentives:Protocol assistance and fee waivers for Chagas-specific indications attract mid-cap developers toward chronic-phase therapeutic candidates.
Industry Challenges
- Clinical Trial Enrollment:Prolonged cardiac endpoint studies in chronic Chagas cardiomyopathy require decade-long follow-up, straining sponsor retention of investigator sites across dispersed Latin American populations.
- Biomarker Validation:Parasite clearance surrogates lack regulatory acceptance at FDA and EMA, forcing reliance on seroconversion endpoints that delay approval timelines.
- Cold Chain Fragmentation:Temperature-controlled distribution networks in rural Bolivia and Ecuador remain underdeveloped, compromising nifurtimox stability during last-mile delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chagas Disease Treatment Market |
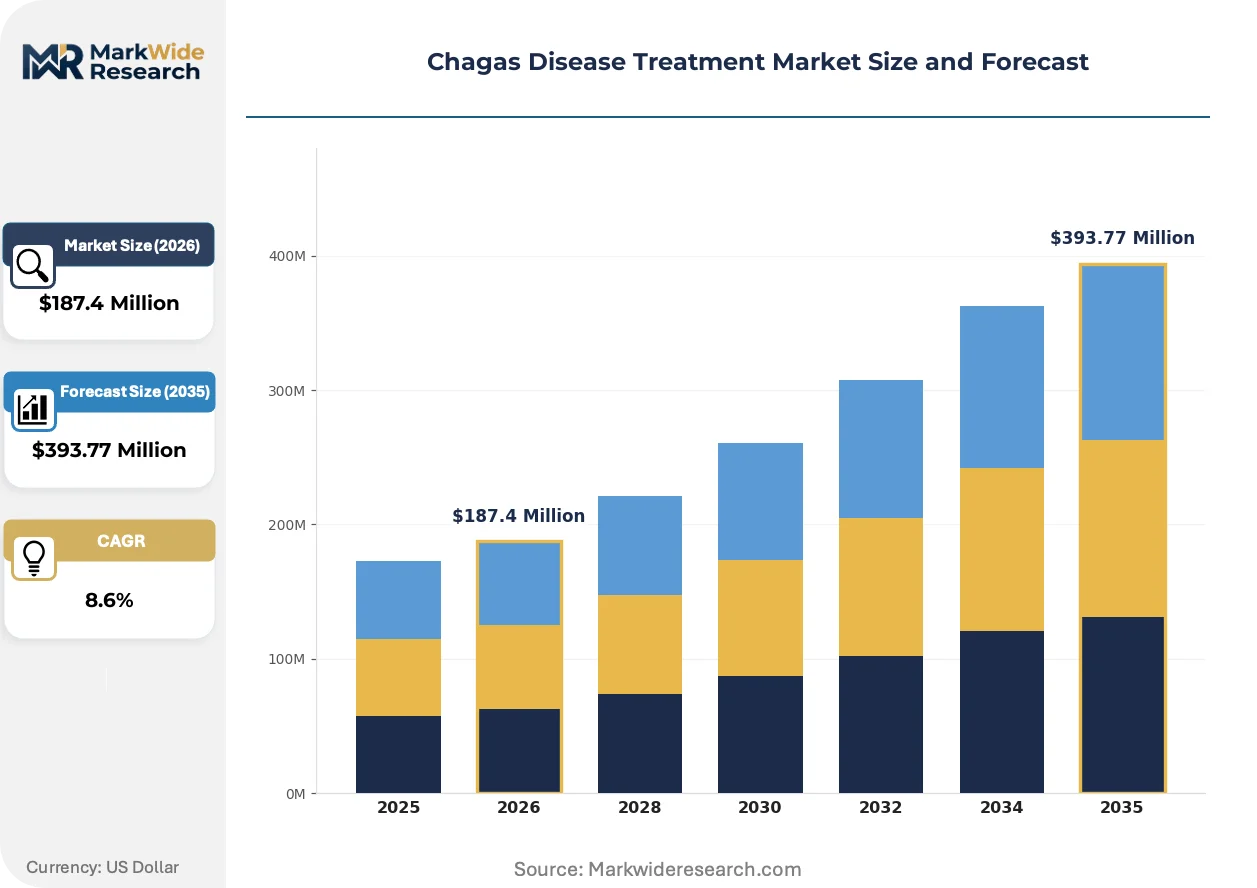
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benznidazole, Nifurtimox, Combination Therapy, Supportive Care Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare, Research Institutions Therapy Area: Infectious Diseases, Cardiovascular, Gastrointestinal, Neurological |
| Companies Covered | Bayer AG, Novartis AG, Laboratorio Elea Phoenix, Maprimed, Nortec Quimica SA, Eisai Co., GlaxoSmithKline, F. Hoffmann-La Roche Ltd, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chagas Disease Treatment Market Emerging Trajectories
Antiparasitic development pipelines are pivoting toward host-directed therapies and combination regimens, while diagnostic platforms integrate molecular confirmation with field-deployable serology.
Long-acting injectable formulations are migrating from experimental preclinical models toward phase I evaluation, with sustained-release depots targeting parasite reservoirs in adipose and cardiac tissue. Research institutes in Argentina and Brazil sponsor pharmacokinetic studies comparing monthly dosing intervals against standard twice-daily oral regimens. This technology is compressing adherence barriers in remote populations where supervised daily therapy proves impractical.
EMA's Orphan Regulation and FDA Tropical Disease Priority Voucher programs are accelerating sponsor engagement with Chagas indications, compressing regulatory review timelines for novel chemical entities. The industrial consequence manifests in expanded protocol assistance meetings and rolling submission pathways for benznidazole-nifurtimox combination trials. Pediatric indication expansions and chronic-phase cardiac endpoints attract the majority of voucher-seeking sponsors, with Argentine and Colombian sites enrolling disproportionate patient volumes.
Decentralized diagnostic procurement is fragmenting traditional centralized laboratory contracts, with municipal health departments in Brazil's Minas Gerais and São Paulo states purchasing rapid test kits directly from manufacturers. This pattern displaces state-level tender consolidation that previously favored high-volume reference laboratory networks. The shift is most visible in urban periphery zones where point-of-care serology enables same-day treatment initiation.
Chagas Disease Treatment Market Segmentation
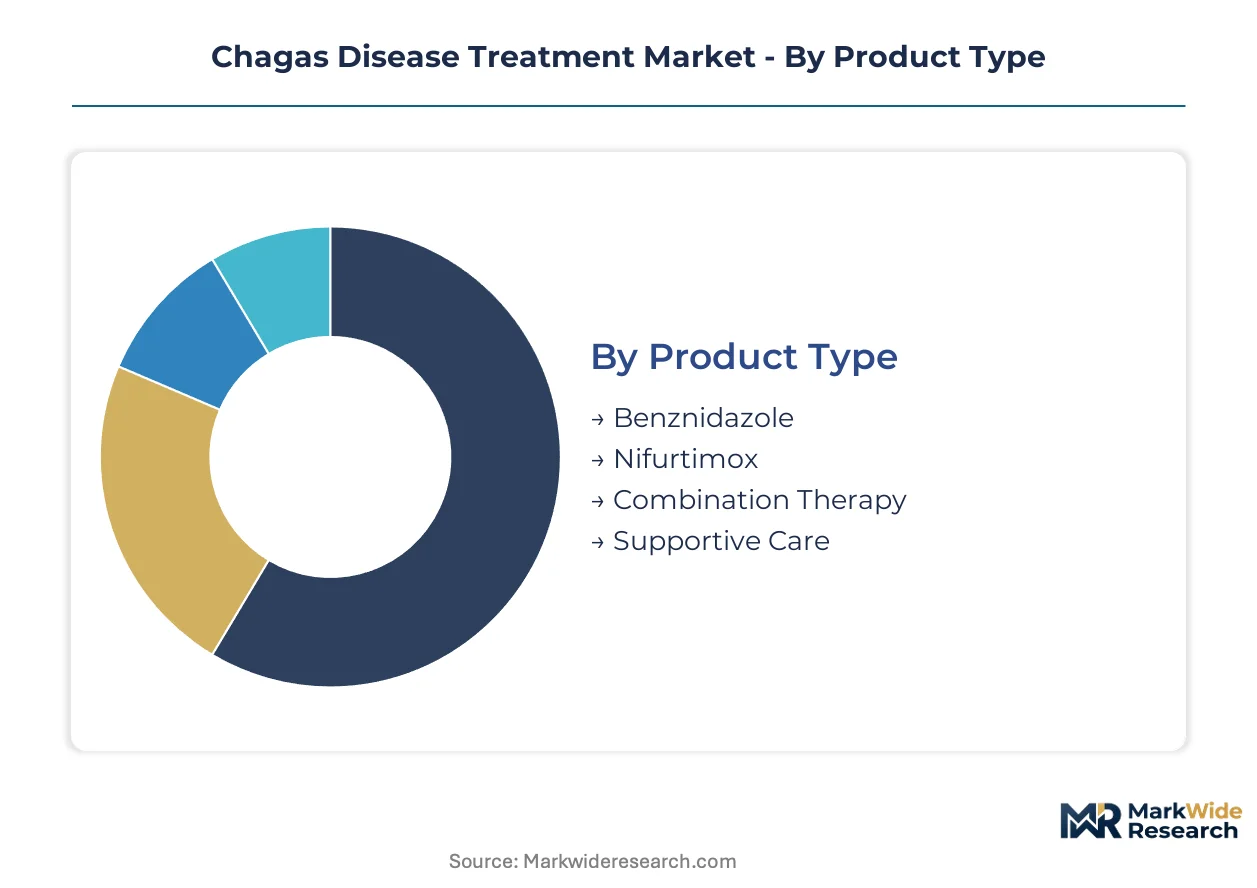
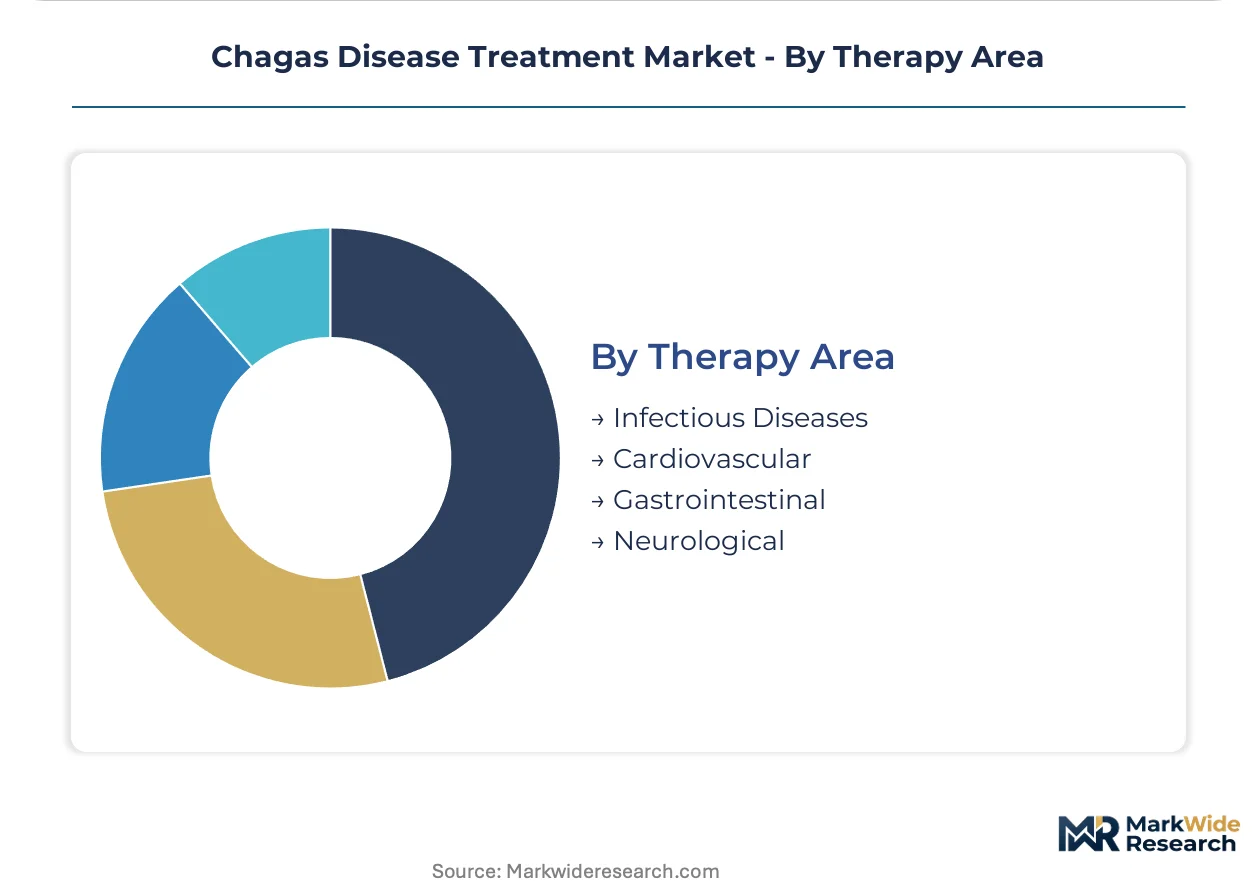
Chagas disease treatment segmentation reflects distinct clinical workflows across acute infection management, chronic cardiomyopathy intervention, and vector control integration. Each dimension captures specific procurement patterns, regulatory pathways, and patient access constraints that determine commercial viability in endemic Latin American markets.
Product Type:
Use-case spectrum spans curative antiparasitic elimination through symptomatic chronic disease management, with each compound class serving distinct therapeutic objectives and regulatory approval statuses.
- Benznidazole:Nitroimidazole derivative disrupts Trypanosoma cruzi DNA synthesis through free radical generation. Demand concentrates in Argentina's public hospital networks and Brazil's SUS procurement channels, driven by WHO Essential Medicines List preferential status and established pediatric dosing protocols.
- Nifurtimox:Nitrofuran compound metabolizes into reactive intermediates that damage parasite cellular proteins and nucleic acids. Bolivia's Ministry of Health and Paraguay's national programs anchor volume, constrained by shorter stability profiles and stricter cold chain requirements during rural distribution.
- Combination Therapy:Benznidazole-nifurtimox protocols and azole adjuncts target resistant parasite strains.
- Supportive Care:Beta-blockers, ACE inhibitors, and antiarrhythmics manage chronic Chagas cardiomyopathy progression.
Established volume favors benznidazole; emerging adoption favors combination therapy.
Delivery Mode:
Cost tier differentiation separates outpatient-scalable oral formats from resource-intensive parenteral administration requiring clinical infrastructure.
- Oral:Tablet and suspension formulations enable community-based treatment in remote Amazon basin settlements. Argentina's Misiones province and Colombia's Caquetá department deploy mobile oral therapy units to circumvent hospital access barriers.
- Intravenous:Hospital-based infusion protocols serve severe acute Chagas cases with myocarditis or meningoencephalitis complications. Brazilian tertiary cardiac centers in São Paulo and Minas Gerais states retain this capacity for hemodynamically unstable patients.
- Subcutaneous:Experimental depot formulations in early clinical evaluation for adherence improvement.
- Topical:Limited current application; exploratory research for cutaneous parasite reservoir targeting.
Oral administration commands procurement volume; intravenous retains premium positioning in acute care settings.
End User:
Customer type fragmentation mirrors healthcare system stratification across urban reference centers, municipal clinics, and decentralized home-based care programs.
- Hospitals:Tertiary institutions manage acute-phase diagnosis, cardiac complication staging, and severe adverse event monitoring. Brazil's INCOR and Argentina's Hospital de Clínicas anchor specialist referral networks for chronic cardiomyopathy surgical intervention.
- Clinics:Primary health posts in Bolivia's Santa Cruz department and Ecuador's Manabí province conduct serological screening and treatment initiation. Rapid diagnostic integration enables same-day benznidazole dispensing without centralized laboratory confirmation.
- Homecare:Family-supported oral therapy completion for chronic-phase patients with stable cardiac function.
- Research Institutions:Fiocruz in Brazil and CONICET-affiliated centers in Argentina host clinical trial enrollment and biomarker validation studies.
Clinic networks are expanding fastest; hospitals retain complex case concentration.
Therapy Area:
Application focus determines reimbursement coding, specialist prescriber access, and outcome measurement frameworks across infectious disease and organ-specific complications.
- Infectious Diseases:Antiparasitic chemotherapy targeting active Trypanosoma cruzi replication in acute and early chronic phases. Brazil's Ministry of Health protocols and Argentina's national Chagas program structure procurement around parasitological cure endpoints.
- Cardiovascular:Chronic Chagas cardiomyopathy management encompasses arrhythmia control, heart failure therapy, and transplant evaluation. Colombian and Venezuelan cardiac societies publish specific guidelines distinguishing Chagas etiology from ischemic dilated cardiomyopathy.
- Gastrointestinal:Megacolon and megaesophagus surgical intervention and motility disorder management.
- Neurological:Stroke prevention in Chagas-related cardiogenic embolism and rare meningoencephalitis cases.
Infectious disease anchors public program budgets; cardiovascular claims specialist reimbursement premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chagas disease treatment flows concentrate in Latin American endemic zones where domestic production of benznidazole and nifurtimox meets most regional demand, with limited cross-border trade in active pharmaceutical ingredients from Asian contract manufacturers.
Brazil
Brazil's Ministry of Health operates the world's largest Chagas treatment program through the Sistema Único de Saúde, procuring benznidazole for acute and chronic phase patients. ANVISA enforces bioequivalence standards for generic antiparasitic formulations that determine market access for local manufacturers. São Paulo and Minas Gerais states anchor diagnostic and treatment capacity, with Fiocruz research institutes in Rio de Janeiro driving clinical trial enrollment for combination therapy protocols.
Argentina
Argentina's national Chagas program maintains universal treatment access through public hospital networks concentrated in northern endemic provinces. ANMAT regulates nitroheterocyclic compound imports and domestic production quality standards for benznidazole tablets. The Misiones province bordering Paraguay deploys mobile oral therapy units to rural settlements, while Hospital de Clínicas in Buenos Aires manages complex chronic cardiomyopathy surgical referrals.
Bolivia
Bolivia's Santa Cruz and Cochabamba departments record the highest triatomine transmission rates in South America, channeling development assistance into nifurtimox procurement through the Ministry of Health. The country's national pharmaceutical regulator oversees cold chain requirements for antiparasitic distribution to highland communities. Rural health posts in the Gran Chaco region struggle with temperature-controlled logistics, compromising drug stability during last-mile delivery to dispersed indigenous populations.
Colombia
Colombia's Putumayo and Caquetá departments in the Amazon basin represent underpenetrated screening territories despite established vector transmission, creating demand for mobile diagnostic units. The national health regulator enforces import licensing for benznidazole while supporting local production scale-up. Cardiac centers in Bogotá and Medellín specialize in Chagas cardiomyopathy differentiation from ischemic heart disease, anchoring specialist reimbursement for chronic-phase management.
Paraguay
Paraguay's Chagas program targets the Paraguayan Chaco region where Triatoma infestans infestations persist in rural housing. The Ministry of Public Health coordinates with PAHO for antiparasitic supply security under WHO neglected tropical disease roadmap commitments. Asunción-based reference laboratories confirm serological diagnoses while municipal clinics in Concepción and Pedro Juan Caballero initiate same-day treatment protocols.
Chagas Disease Treatment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in API synthesis and generic formulation. The supplier base concentrates around established pharmaceutical manufacturers with tropical disease portfolios, while regional laboratories fragment diagnostic-test distribution. Three archetypes dominate: originator multinationals with essential medicines list status, mid-cap regional formulators with ANVISA and ANMAT approvals, and Indian and Chinese contract manufacturers supplying nitroheterocyclic active ingredients. Competitive moves center on pediatric formulation partnerships and diagnostic bundling to secure national procurement tenders.
Among originator-tier multinationals, Bayer AG and Novartis AG occupy positions anchored by decades of antiparasitic manufacturing scale and sustained R&D investment in tropical disease therapeutics. F. Hoffmann-La Roche Ltd exemplifies the diagnostic-platform archetype, with test bundling strategies that complement drug distribution networks in endemic Latin American markets. These three entities represent distinct competitive approaches: manufacturing scale, research continuity, and integrated diagnostic-therapeutic positioning.
| Leading Market Players |
|---|
| Bayer AG |
| Novartis AG |
| Laboratorio Elea Phoenix |
| Maprimed |
| Nortec Quimica SA |
| Eisai Co. |
| GlaxoSmithKline |
| F. Hoffmann-La Roche Ltd |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply Flow & Price Mechanics
API supply concentration in Indian and Chinese contract manufacturers determines both the pricing tier spreads between originator and generic benznidazole and the elongated supply chain shape that fragments procurement power across Latin American health ministries. This single-source dependency for nitroheterocyclic active ingredients exposes formulators to cross-border logistics disruptions that compress margins in the standard tier while sustaining premium positioning for vertically integrated suppliers.
Pricing Analysis
Public health ministries anchor a contract-based long-term offtake structure where tender consolidation favors high-volume reference laboratory networks. Price differentiation separates WHO prequalified originator products from ANVISA-certified generic tiers, with brand premiums reflecting pediatric formulation availability and cold chain reliability. Cost compression in the economy tier is intensifying because municipal health departments in Brazil's Minas Gerais and São Paulo states now purchase rapid diagnostic kits directly from manufacturers, bypassing state-level procurement. Clinic networks in Bolivia's Santa Cruz department demonstrate the highest price sensitivity due to constrained development assistance budgets, while Brazil's SUS procurement channels retain leverage through volume scale.
Supply Chain Analysis
Tariff exposure between India and Brazil dominates supply chain risk planning for nitroheterocyclic compound formulators. Active pharmaceutical ingredient production clusters in India, China, and selected European specialist manufacturers, with Brazilian and Argentine domestic facilities drawing from Asian contract manufacturers for raw material inputs. Single-source vulnerability persists for nifurtimox precursors, where regulatory restrictions on nitrofuran chemistry limit qualified supplier pools. Distribution runs through national health ministry central warehouses to state-level cold storage facilities, with last-mile fragmentation to rural health posts in Ecuador's Manabí province and Bolivia's Gran Chaco region compromising temperature-controlled integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diagnostic-test bundling represents a service-attach opportunity expanding faster than antiparasitic drug volume, as same-day serology-to-treatment protocols in Argentine municipal clinics demonstrate higher patient retention than standalone drug distribution.
For Market Incumbents: Pre-empt substitution pressure from azole antifungals by accelerating chronic-phase cardiac endpoint studies that establish superior long-term outcomes against posaconazole comparators. Consolidate position through backward integration into pediatric formulation capabilities, securing partnerships with regional compounding pharmacies in Colombia's underpenetrated Amazon departments. Channel control through diagnostic-platform bundling with Fiocruz-affiliated laboratories in Brazil anchors tender retention against mid-cap regional formulators. For New Entrants and Emerging Players: Colombia's Putumayo and Caquetá departments offer whitespace for mobile screening units where diagnostic coverage remains limited despite established triatomine transmission. Pediatric dissolvable tablet gaps in Bolivia's highland communities present the most penetrable segment, with formulation partnerships requiring minimal manufacturing infrastructure. A go-to-market angle anchored to PAHO supply security commitments under WHO neglected tropical disease roadmap targets unlocks development assistance procurement channels without competing against established SUS volume. For Investors and Strategic Acquirers: EMA Orphan Drug fee waivers and protocol assistance reshape the acquisition landscape by compressing regulatory timelines for chronic-phase therapeutic candidates. Long-term viability across the analysis window favors mid-cap developers with Argentine and Colombian clinical trial site networks already enrolled in combination therapy protocols. The signal to watch is WHO prequalification status changes for generic benznidazole, which would trigger volume shifts from originator to regional supply sources and revalue ANMAT-approved manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Partnership | ANMAT-approved compounding pharmacies in Argentina capture low-weight patient segments inaccessible to standard tablets. |
| Diagnostic-Test Bundling | Roche's serology platforms integrated with benznidazole distribution displace standalone drug tenders in Brazilian municipal clinics. |
| EMA Orphan Drug Pathway | Fee waivers and protocol assistance attract sponsors toward chronic-phase cardiomyopathy endpoints with decade-long follow-up requirements. |
| API Supply Diversification | Dual-sourcing from Indian and Chinese contract manufacturers mitigates tariff exposure for Brazilian ANVISA registrants. |
| Mobile Screening Unit Deployment | Same-day treatment initiation in Colombia's Caquetá department converts underpenetrated transmission zones into addressable patient populations. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads at ANVISA and ANMAT, hospital procurement managers in Brazil's SUS network, and formulary directors at Colombian cardiac centers; alongside secondary validation through FDA tropical disease priority voucher filings, EMA orphan drug designations, ClinicalTrials.gov enrollment records, and PAHO procurement databases. Bottom-up patient volume estimates from endemic Latin American countries triangulated against top-down pharmaceutical spending flows from national health ministry budget disclosures.
Forecast inputs encompassed treatment line segmentation across acute and chronic phases, dosage form differentiation between oral tablets and experimental depot formulations, administration route stratification, and regional regulatory clusters reflecting WHO prequalification status. Modeled CAGRs derived from epidemiological prevalence projections, vector control investment trajectories from Brazil's Ministry of Health, and development assistance disbursement patterns through the analysis window. Industry-specific inputs included biomarker validation timelines at FDA and EMA, cold chain infrastructure development in rural Bolivia and Ecuador, and pediatric indication expansion protocols.
Practitioners should monitor regulatory prequalification decisions, API supply disruptions at Indian contract manufacturers, and vector control program funding levels for early signals requiring forecast revision. Assumptions reflect documented procurement tender structures, clinical trial enrollment retention rates, and temperature-controlled distribution capacity constraints. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Ascites Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Malaria Treatment Market