
 Mesotherapy Market | 2026-2036
Mesotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Mesotherapy Market Intelligence
Asset-light leasing models for mesogun and electroporation equipment is fragmenting competitive access across mid-tier aesthetic centers. Toskani Cosmetics leverages direct-to-clinic training programs to sustain brand loyalty in Southern Europe. Koru Pharma Co., Ltd. anchors its position through in-house production of hyaluronic acid formulations. Institute BCN differentiates via broad-spectrum peptide portfolios that compete on protocol versatility rather than device dependency.
Mesotherapy denotes minimally invasive intradermal or subcutaneous administration of pharmaceutical compounds, vitamins, amino acids, and hyaluronic acid via fine-gauge needles or needle-free systems, typically at 1-4 mm depth for localized tissue response. The technique serves primary commercial purposes in aesthetic medicine for collagen induction, lipolysis, and follicular stimulation. Injectable formulations occupy the dominant margin pool due to recurring consumable demand, while needle-free devices represent the fastest-expanding segment as clinics in Germany and Spain adopt electroporation to reduce patient anxiety and bruising downtime. Skin rejuvenation applications lead volume, though hair loss treatment commands premium pricing per session across Middle Eastern aesthetic chains.
FDA oversight of mesotherapy injectables as off-label compounded drugs creates compliance complexity for US importers, while the EU MDR and CE marking requirements under Notified Body supervision extend registration timelines for mechanical mesoguns. Brazil's ANVISA maintains distinct phytotherapeutic compound rules that affect botanical ingredient sourcing for topical preparations. Stakeholders must monitor evolving national pharmacovigilance reporting obligations as mesotherapy transitions from salon-administered wellness service to regulated medical procedure in multiple jurisdictions.
Market Dynamics
The EU Medical Device Regulation is compressing product registration timelines while needle-free electroporation systems fragment competitive access across mid-tier aesthetic clinics in Germany and Spain.
Growth Catalysts
- EU MDR compliance acceleration:The Medical Device Regulation's stricter clinical evidence requirements are consolidating demand toward established manufacturers with Notified Body relationships, favoring device suppliers with pre-certified quality management systems.
- Hair loss protocol expansion:Middle Eastern aesthetic chains are deploying mesotherapy for androgenetic alopecia at premium per-session pricing, creating recurring revenue streams that offset capital equipment amortization.
- Hyaluronic acid formulation advances:Cross-linked and low-molecular-weight variants are extending treatment intervals from 2-3 weeks to 4-6 weeks, improving patient retention and clinic scheduling efficiency.
Market Restraints
- FDA off-label enforcement:The agency's oversight of compounded mesotherapy injectables as unapproved drugs creates import compliance complexity for US distributors sourcing European formulations.
- Single-source needle supply concentration:Fine-gauge 30-32G mesotherapy needles rely on Japanese and South Korean precision manufacturing, exposing clinics to supply disruption risks from regional logistics constraints.
- Substitution by oral nutraceuticals:High-dose biotin and collagen peptide supplements compete for budget-conscious patients seeking hair and skin improvement without procedural downtime.
Strategic Opportunities
- Brazil's phytotherapeutic regulatory pathway:ANVISA's distinct rules for botanical topical preparations enable differentiated product positioning for clinics seeking natural-ingredient protocols.
- Electroporation-laser convergence:Combination devices integrating electroporation with fractional laser pre-treatment are opening premium service tiers for collagen induction protocols.
- Direct-to-clinic training certification:Manufacturers bypassing traditional distributor networks with proprietary education programs capture higher-margin consumable attachment rates.
Industry Challenges
- Clinician certification timeline compression:Aesthetic medicine training infrastructure in France and South Korea cannot match the pace of clinic expansion, creating treatment quality inconsistency risks.
- Pharmacovigilance reporting obligations:National regulators in multiple jurisdictions are transitioning mesotherapy from wellness service to regulated medical procedure, imposing adverse event documentation burdens on solo practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesotherapy Market |
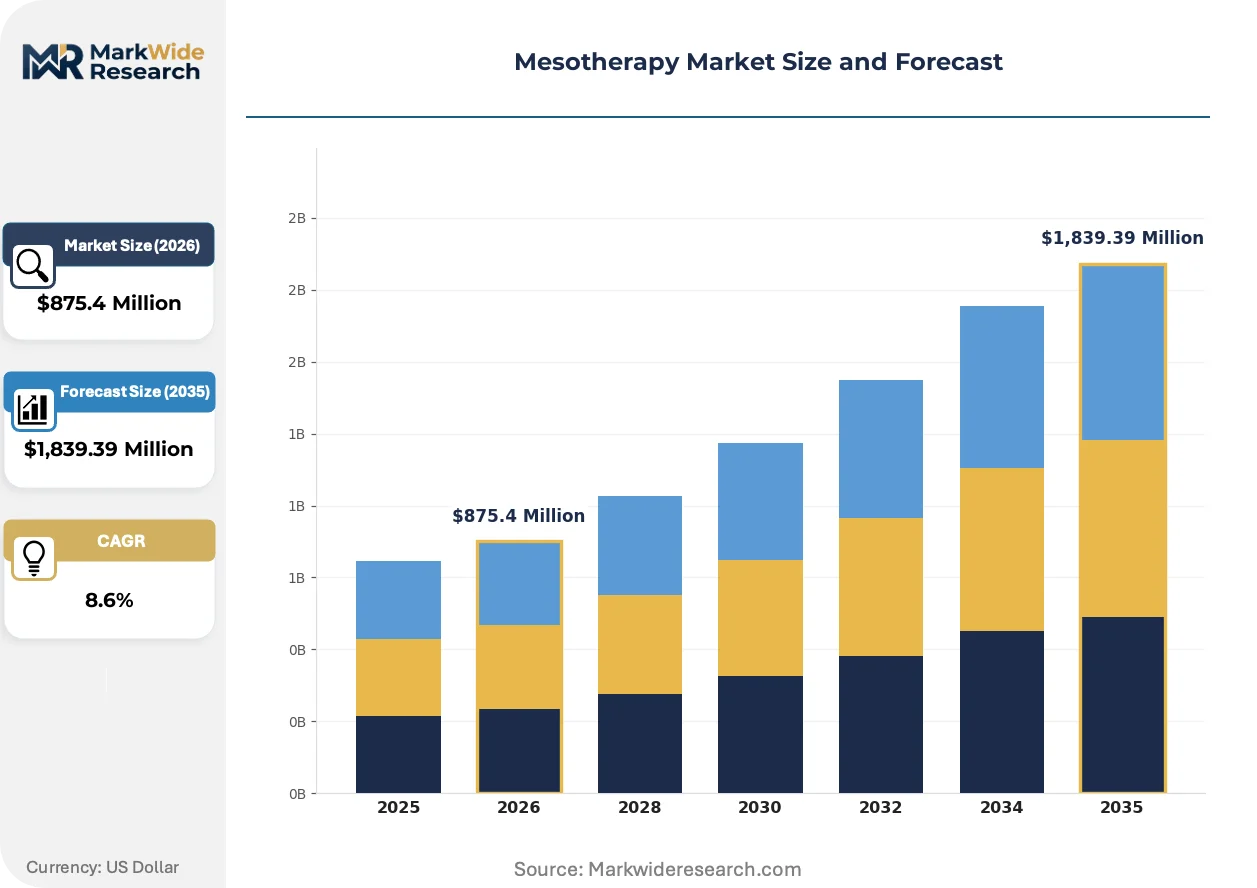
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,839.39 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Equipment, Needle-Free Devices, Injectable Formulations, Topical Preparations, Mesoguns Application: Fat Reduction, Skin Rejuvenation, Hair Loss Treatment, Pain Management, Cellulite Reduction End User: Dermatology Clinics, Aesthetic Centers, Beauty Salons, Cosmetic Surgeons, Wellness Spas Delivery Mode: Manual Injection, Mechanical Injection, Needle-Free Injection, Electroporation, Mesoporation |
| Companies Covered | Toskani Cosmetics, Mesoskinline, Filorga, Mesotech S.r.l., Dermaqual, Koru Pharma Co., Ltd., Institute BCN, Revitacare, Fusion Meso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesotherapy Market Strategic Shifts & Innovations
Active ingredient delivery mechanisms and regulatory classification frameworks are simultaneously evolving, reshaping how manufacturers position formulations against device-centric competitors.
Needle-free electroporation technology is migrating from experimental positioning to standard protocol in German and Spanish dermatology clinics. The technology uses pulsed electrical fields to transiently permeabilize cell membranes, enabling macromolecule penetration without mechanical trauma. Mid-tier aesthetic centers adopt these systems to reduce patient anxiety and bruising downtime, compressing the addressable market for traditional mesogun devices.
The EU Medical Device Regulation's 2021 implementation deadline forced mechanical mesogun manufacturers to resubmit technical documentation under stricter clinical evidence standards. This regulatory friction extended CE marking timelines by 12-18 months for smaller device suppliers. French and Italian clinics now prioritize suppliers with MDR-certified quality management systems, consolidating procurement toward established European manufacturers.
Patient preference for minimal-downtime procedures is rotating demand toward lunchtime treatment protocols. South Korean clinic chains unbundle after-care services into remote monitoring apps, replacing traditional in-person follow-up visits. This behavioral shift concentrates volume in urban centers with dense professional populations where schedule compression commands premium pricing.
Mesotherapy Market Segmentation
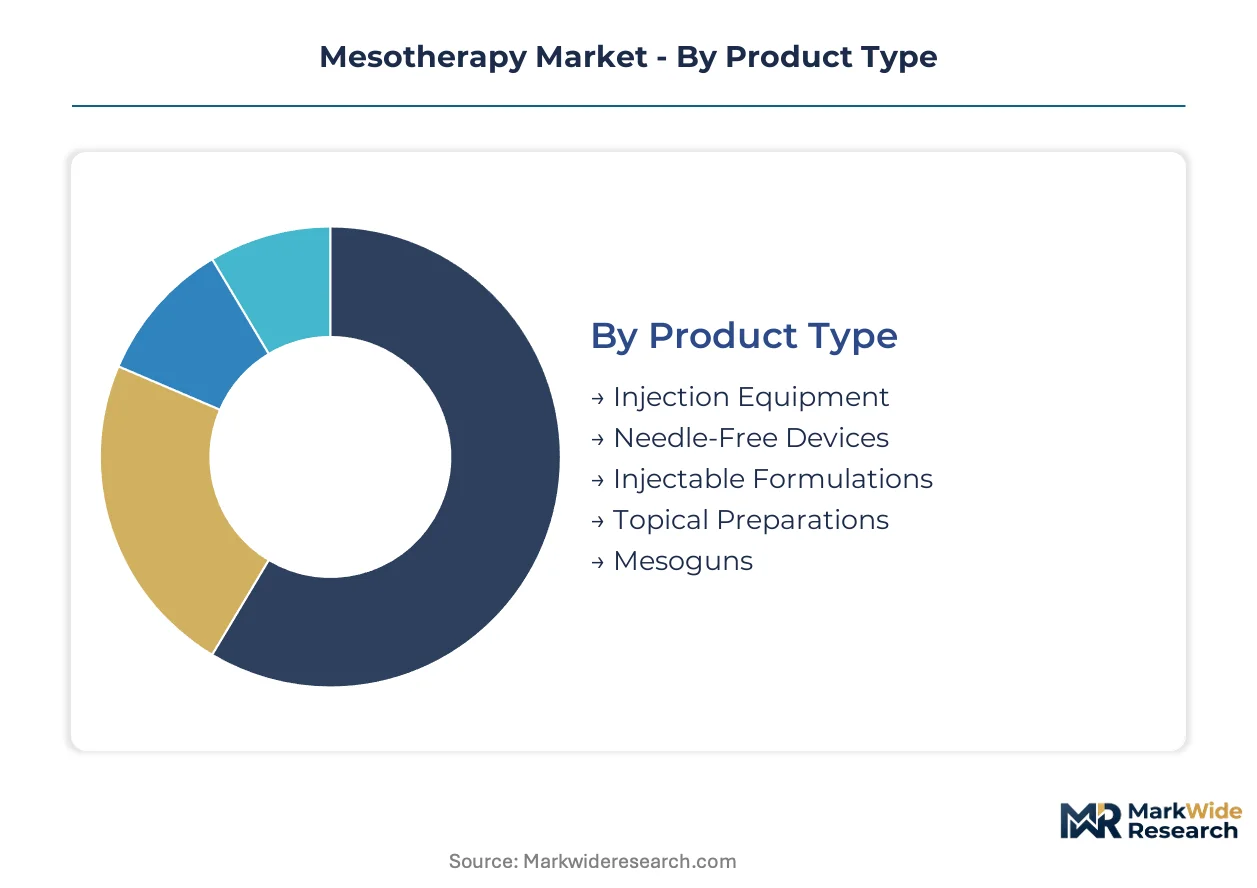
Mesotherapy market segmentation reveals divergent margin profiles across product categories. Service intensity varies dramatically between device-dependent revenue streams and consumable-driven recurring purchases.
Product Type:
After-sales service intensity defines competitive positioning across product categories, with electroporation systems requiring firmware updates and calibration protocols that deepen manufacturer-clinic relationships.
- Injectable Formulations:Pharmaceutical compounds, vitamins, amino acids, and hyaluronic acid delivered via fine-gauge needles at 1-4 mm depth. Demand concentrates in French and South Korean dermatology clinics where recurring consumable purchases generate predictable revenue streams and justify premium pricing for cross-linked hyaluronic acid variants.
- Needle-Free Devices:Electroporation and mesoporation systems using pulsed electrical fields to permeabilize cell membranes without mechanical trauma. German and Spanish mid-tier aesthetic centers are adopting these systems to reduce patient anxiety and bruising downtime, fragmenting competitive access away from traditional mesogun suppliers.
- Injection Equipment:Syringes, needles, and disposable administration kits for manual protocols.
- Topical Preparations:Botanical and phytotherapeutic creams for pre- and post-treatment application.
- Mesoguns:Mechanical injection devices for automated depth-controlled delivery.
By volume, injectable formulations lead. By growth pace, needle-free devices are ahead.
Application:
Cost tier stratification separates premium-priced hair restoration protocols from commoditized cellulite services.
- Skin Rejuvenation:Collagen induction and anti-aging protocols targeting facial and décolletage areas. Seoul and Milan clinic chains are expanding service menus for these protocols, with South Korean operators unbundling after-care into remote monitoring apps to compress treatment cycles.
- Hair Loss Treatment:Androgenetic alopecia protocols using growth factor cocktails and minoxidil combinations. Middle Eastern aesthetic chains command premium per-session pricing for these treatments, creating recurring revenue streams that offset capital equipment amortization.
- Fat Reduction:Lipolytic injections for localized adipose tissue dissolution.
- Pain Management:Anti-inflammatory and analgesic compound delivery for musculoskeletal conditions.
- Cellulite Reduction:Connective tissue remodeling protocols targeting subcutaneous fat architecture.
By patient volume, skin rejuvenation dominates. By revenue per session, hair loss treatment commands the highest position.
End User:
Customer type determines procurement sophistication, with dermatology clinics demanding clinical evidence packages that beauty salons bypass.
- Dermatology Clinics:Physician-supervised facilities with full medical licensing. São Paulo and Seoul operators are expanding service menus fastest, though France and South Korea face training infrastructure bottlenecks that create treatment quality inconsistency risks.
- Aesthetic Centers:Mid-tier facilities combining medical oversight with scaled service delivery.
- Cosmetic Surgeons:Hospital-affiliated or independent surgical practices integrating mesotherapy into pre- and post-operative protocols.
- Beauty Salons:Non-medical wellness venues where regulatory transitions from service to medical procedure are imposing compliance burdens.
- Wellness Spas:Hospitality-integrated facilities targeting tourist and leisure segments.
By procedure volume, dermatology clinics lead. By expansion velocity, aesthetic centers are climbing the fastest.
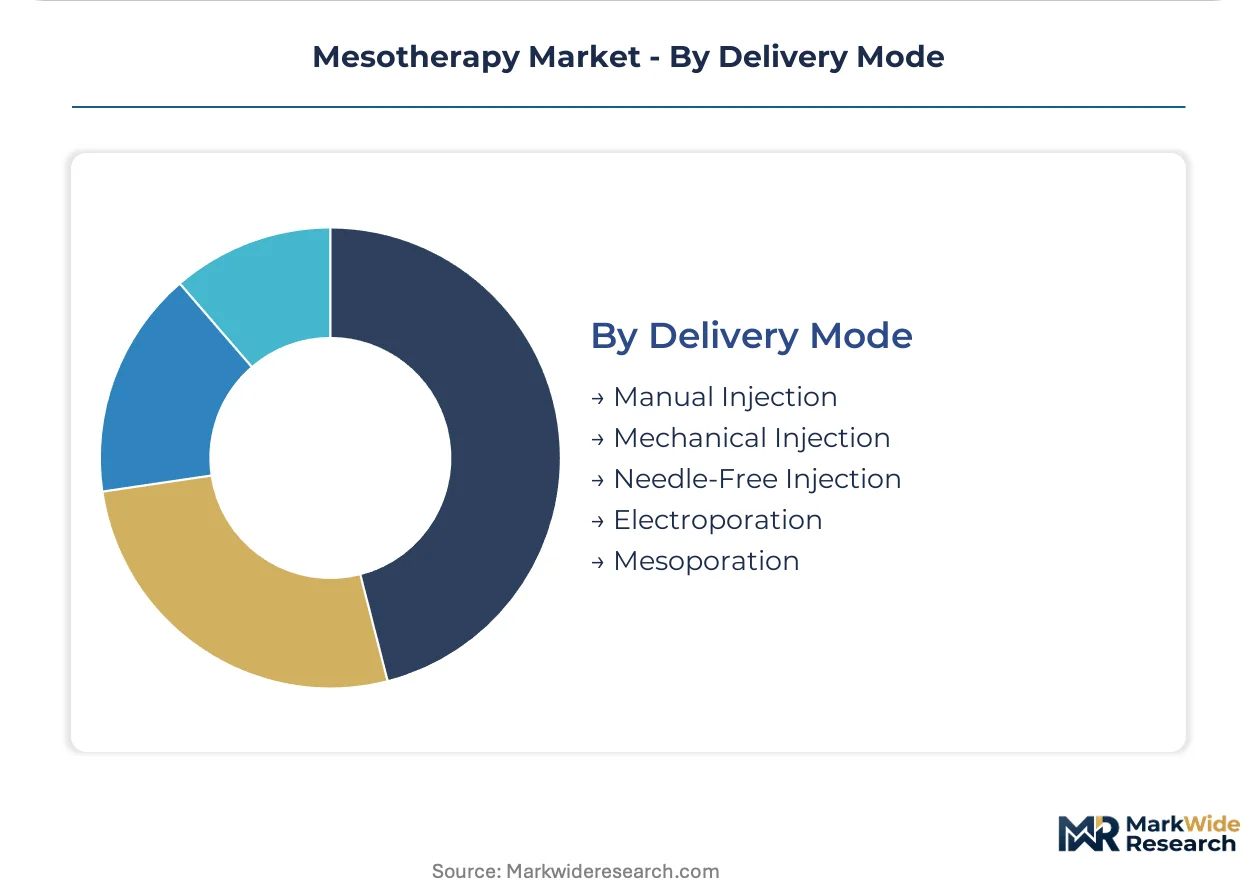
Delivery Mode:
Maturity gradients separate established manual techniques from emerging electroporation platforms still seeking reimbursement clarity.
- Electroporation:Pulsed electrical field technology enabling macromolecule penetration without needle trauma. German clinics are migrating this from experimental positioning to standard protocol, compressing addressable market for mechanical alternatives.
- Mechanical Injection:Automated mesogun systems with programmable depth and dosage control. EU MDR compliance has extended CE marking timelines for smaller device suppliers, consolidating procurement toward established European manufacturers with Notified Body relationships.
- Manual Injection:Syringe-based administration by trained clinicians.
- Needle-Free Injection:Pressure-based systems for subcutaneous delivery without piercing.
- Mesoporation:Combined mechanical and electrical permeabilization techniques.
By installed base, mechanical injection leads. By adoption momentum, electroporation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU MDR compliance acceleration is consolidating procurement toward established European manufacturers, while South Korea's MFDS oversight and Brazil's ANVISA phytotherapeutic pathways are creating distinct regulatory moats that favor localized formulation strategies.
France
Dermatology clinic expansion in Paris and Lyon is outpacing aesthetic medicine training capacity, creating treatment quality variance risks. ANSM pharmacovigilance reporting obligations are transitioning mesotherapy from wellness service to regulated medical procedure. The Île-de-France cluster concentrates demand for cross-linked hyaluronic acid formulations with extended treatment intervals.
South Korea
Seoul clinic chains are unbundling after-care into remote monitoring apps to compress treatment cycles for professional demographics. MFDS oversight of needle-free electroporation devices is accelerating CE-MDR parallel registration strategies for export-oriented manufacturers. The Seoul Capital Area dominates volume for collagen induction protocols with premium pricing power.
Germany
Mid-tier aesthetic centers in Munich and Hamburg are adopting electroporation systems to reduce patient anxiety and bruising downtime. BfArM's implementation of EU MDR through Notified Body supervision has extended device registration timelines by 12-18 months for smaller suppliers. Bavaria's dermatology networks prioritize MDR-certified quality management systems in procurement decisions.
Brazil
São Paulo clinic chains are expanding service menus fastest across Latin America, though ANVISA's distinct phytotherapeutic compound rules constrain botanical ingredient sourcing. The regulatory pathway enables differentiated positioning for natural-ingredient protocols targeting wellness-oriented demographics. Southeast Brazil concentrates capital equipment deployment for hair loss treatment at premium per-session pricing.
United States
FDA oversight of compounded mesotherapy injectables as unapproved drugs creates import compliance complexity for distributors sourcing European formulations. New York and Los Angeles dermatology practices navigate off-label enforcement variability across district offices. The Northeast and West Coast clusters drive demand for lunchtime treatment protocols with minimal downtime positioning.
Mesotherapy Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: European formulation houses with Notified Body relationships, Asian device manufacturers with captive consumable production, and regional training-centric distributors. Established players defend position through MDR certification maintenance and direct-to-clinic education programs, while mid-tier entrants pursue electroporation-laser convergence to access premium service tiers. Portfolio diversification into hair loss protocols and remote after-care platforms represents the dominant competitive vector.
Among European formulation specialists, Toskani Cosmetics and Institute BCN exemplify divergent archetypes within the consumable-driven tier. Toskani's Southern European positioning anchors a training-centric model, while Institute BCN occupies the protocol versatility vector through peptide portfolio breadth. Koru Pharma Co., Ltd. represents the Asian integrated manufacturer archetype with in-house hyaluronic acid production capabilities. These three entities collectively illustrate how geographic origin and captive supply integration determine competitive positioning against device-centric alternatives.
| Leading Market Players |
|---|
| Toskani Cosmetics |
| Mesoskinline |
| Filorga |
| Mesotech S.r.l. |
| Dermaqual |
| Koru Pharma Co., Ltd. |
| Institute BCN |
| Revitacare |
| Fusion Meso |
| Others |
Cost & Logistics Intelligence
Single-source needle supply concentration from Japanese and South Korean precision manufacturers determines both pricing tier spreads and supply chain shape, exposing mid-tier aesthetic clinics to disruption risks while compressing margins for device-dependent procurement models.
Pricing Analysis
Certification level (CE-MDR/FDA-grade) creates the primary spread across three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to Notified Body-certified mesoguns with cross-linked hyaluronic acid consumables, while economy positioning targets manual injection kits for price-sensitive beauty salons. Pricing pressure stems from electroporation device commoditization in German and Spanish markets. Dermatology clinics demonstrate lowest price sensitivity; wellness spas exhibit highest.
Supply Chain Analysis
Upstream hyaluronic acid feedstock draws from South Korean bioreactor facilities and Chinese fermentation plants, with peptide synthesis concentrated in French and Italian pharmaceutical corridors. Fine-gauge 30-32G needles hinge on precision manufacturing from Osaka and Seoul. Single-source vulnerability runs through Japanese needle suppliers exposed to regional logistics constraints. Distribution runs through direct-to-clinic manufacturer relationships bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mesotherapy sits at an early-cycle expansion story where needle-free electroporation adoption in European mid-tier clinics creates whitespace for protocol standardization before market maturation compresses differentiation.
For Market Incumbents: Insulate consumable revenue streams through in-house hyaluronic acid production and MDR certification maintenance. Koru Pharma's captive supply model demonstrates defensive positioning against formulation commoditization. Direct-to-clinic training programs deepen switching costs for aesthetic centers evaluating supplier alternatives. For New Entrants and Emerging Players: Mid-tier aesthetic centers in São Paulo and Mexico City represent the most penetrable entry point given ANVISA pathway familiarity and phytotherapeutic protocol demand. Electroporation-laser combination devices open premium service tiers without competing against established mesogun installed bases. Partner with regional training institutes to bypass distributor channel development timelines. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors formulation specialists with Notified Body relationships over device-centric hardware plays. Acquisition targets should demonstrate recurring consumable attachment rates above industry baseline. Watch electroporation reimbursement clarity in German statutory health insurance as inflection signal for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Parallel Registration | Accelerates EU market access while satisfying MFDS export requirements for Seoul-based manufacturers. |
| Direct-to-Clinic Training Certification | Bypasses distributor networks to capture higher-margin consumable attachment rates in Southern Europe. |
| Phytotherapeutic Formulation Development | Exploits ANVISA's distinct botanical rules for differentiated positioning in Brazilian wellness segments. |
| Electroporation-Laser Convergence | Opens premium collagen induction protocols competing on patient downtime reduction rather than device price. |
| Remote After-Care Platform Deployment | Compresses treatment cycles for professional demographics in dense urban centers like Seoul and Milan. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU MDR technical documentation, ANVISA registration filings, and MFDS device approval databases. Interviews with dermatology clinic operators, biomedical equipment procurement managers, aesthetic medicine training directors, and pharmaceutical formulation specialists informed demand-side assumptions. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Forecast inputs incorporate product type segmentation across injectable formulations, needle-free devices, and mechanical mesoguns; application splits between skin rejuvenation, hair loss treatment, and fat reduction; and delivery mode differentiation spanning electroporation, mechanical injection, and manual protocols. CAGRs derived from fitted growth curves adjusted for regulatory timeline compression and technology substitution elasticities. Hyaluronic acid raw material cost trajectories and clinician certification pipeline constraints fed scenario-weighted projections.
Practitioners should monitor EU MDR enforcement variance across Notified Bodies and electroporation reimbursement decisions in German statutory health insurance for early signals of competitive restructuring. Forecasts reflect assumptions about regulatory pathway stability and technology adoption curves. Cross-checking against hospital procurement database trends and GPO contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Transplantation Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Urea Cycle Disorders Treatment Market