
 Global Systemic Lupus Erythematosus Treatment Market | 2026-2036
Global Systemic Lupus Erythematosus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Systemic Lupus Erythematosus Treatment Market Foresight
EMA's evolving MDR framework is decoupling clinical evidence requirements from traditional trial designs for autoimmune biologics. GSK plc leverages its belimumab franchise to sustain dominance in systemic lupus biologics across European and North American prescribing networks. AstraZeneca anchors its position through anifrolumab's interferon receptor blockade mechanism, competing directly in the biologic agents segment. F. Hoffmann-La Roche Ltd differentiates through deep immunology R&D pipelines targeting refractory lupus populations.
Systemic lupus erythematosus treatment encompasses pharmaceutical and biological interventions designed to modulate autoimmune-mediated tissue inflammation, prevent organ damage progression, and manage disease flares through immunosuppression, cytokine inhibition, or complement pathway regulation. The therapeutic arsenal spans small-molecule immunosuppressants, monoclonal antibodies, corticosteroid tapering protocols, and antimalarial maintenance regimens, all calibrated to disease severity indices and organ-specific involvement patterns. Biologic agents command the highest margin pools as physician adoption shifts toward targeted B-cell and interferon pathway modulation, while immunosuppressants retain volume leadership in emerging markets where cost constraints dominate formulary decisions. Lupus nephritis represents the fastest-growing therapy area as renal involvement drives aggressive intervention and repeat treatment cycles.
FDA, EMA, and PMDA each enforce distinct evidentiary standards for lupus therapeutics, with FDA's accelerated approval pathway and EMA's MDR convergence creating divergent market access timelines that shape regional launch sequencing. The WHO's inclusion of systemic lupus erythematosus in its priority noncommunicable disease framework elevates national reimbursement negotiations and public procurement visibility. Stakeholders must monitor how evolving payer evidence requirements for real-world effectiveness data reshape post-approval commercialization investments and physician education priorities.
Market Dynamics
FDA's accelerated approval pathway for autoimmune therapies is compressing development timelines and forcing portfolio rebalancing across biopharma pipelines. This regulatory velocity is concentrating investment around biomarker-defined patient subsets and real-world evidence generation capabilities.
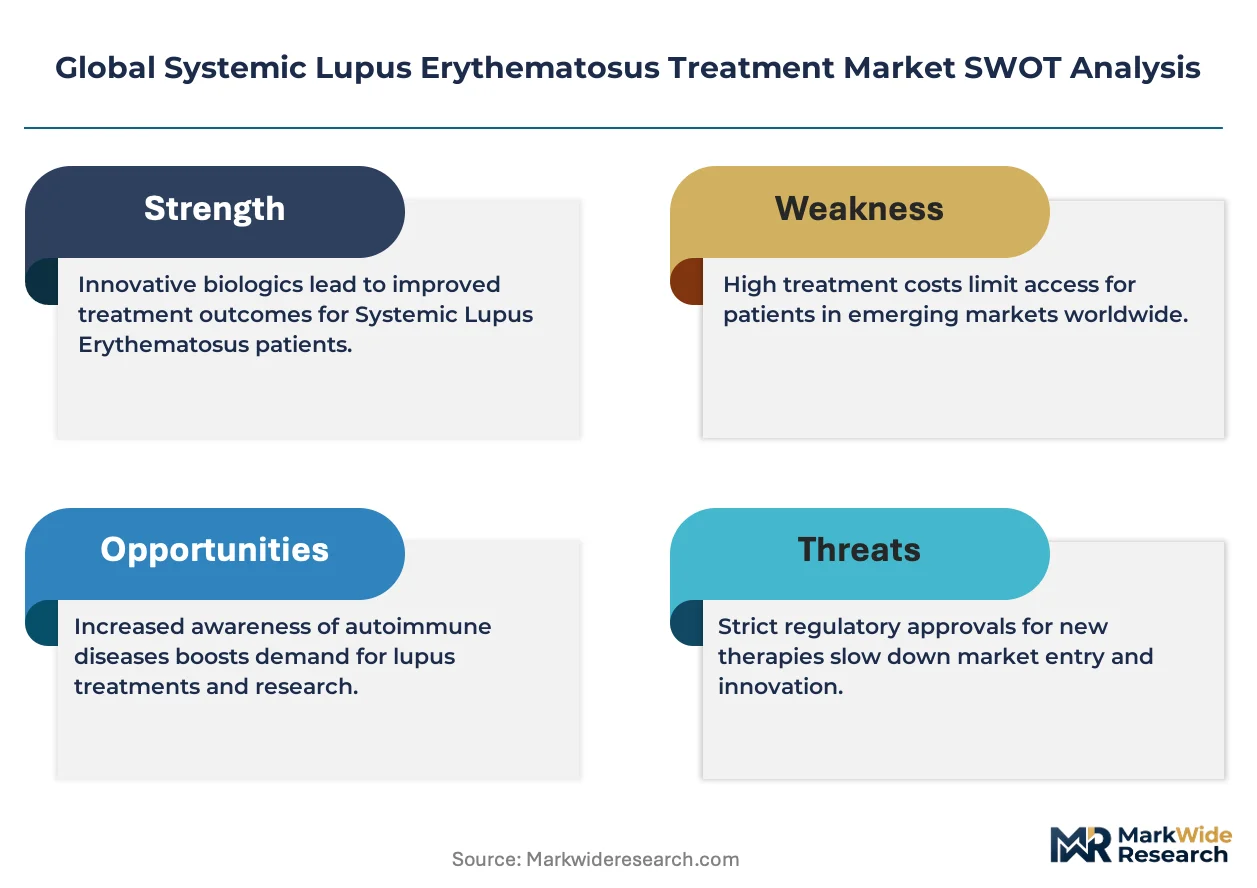
Growth Catalysts
- Accelerated Approval Pathway:FDA's streamlined evidentiary requirements for serious autoimmune conditions reduce Phase III duration. Biologic developers now prioritize surrogate endpoints in lupus nephritis trials.
- Rheumatology Center Expansion:Specialized infusion clinics in the United States and Germany are expanding biologic administration capacity. These centers drive physician familiarity with B-cell and interferon pathway modulators.
- Complement Inhibition Science:Advances in C5a receptor antagonism are opening new mechanistic territory beyond B-cell depletion. Pipeline candidates target refractory cutaneous and renal manifestations.
Market Restraints
- Biologic Manufacturing Concentration:Contract manufacturing for monoclonal antibodies concentrates among three global CDMO networks. Single-source dependencies create vulnerability in fill-finish capacity.
- EMA MDR Transition Friction:Europe's Medical Device Regulation convergence with pharmaceutical frameworks is extending review timelines for combination products. Device-enabled drug delivery systems face dual jurisdiction complexity.
- Corticosteroid Substitution Persistence:Generics prednisone remains the default induction therapy in cost-constrained markets. Payer step-therapy protocols delay biologic access by six to eighteen months in emerging economies.
Strategic Opportunities
- Pediatric Lupus Indications:Unmet need in adolescent-onset systemic lupus erythematosus creates first-mover potential. Regulatory exclusivity incentives align with mechanistic differentiation in this orphan subset.
- Japan's PMDA Sakigake Designation:Japan's priority review framework for innovative autoimmune therapies offers accelerated access. Companies with biomarker-enriched trial designs can compress launch sequencing.
- Telemedicine-Enabled Monitoring:Remote disease activity index scoring is displacing quarterly clinic visits for stable maintenance patients. Virtual care platforms enable rural patient retention and real-world data capture.
Industry Challenges
- Biomarker Validation Talent Scarcity:Interferon signature assay standardization requires specialized immunology and bioinformatics expertise. Competition for translational medicine talent intensifies across autoimmune pipelines.
- Real-World Evidence Infrastructure:Post-approval commitment studies demand patient registry integration across fragmented healthcare systems. Data interoperability gaps between academic medical centers and community rheumatology practices complicate evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Systemic Lupus Erythematosus Treatment Market |
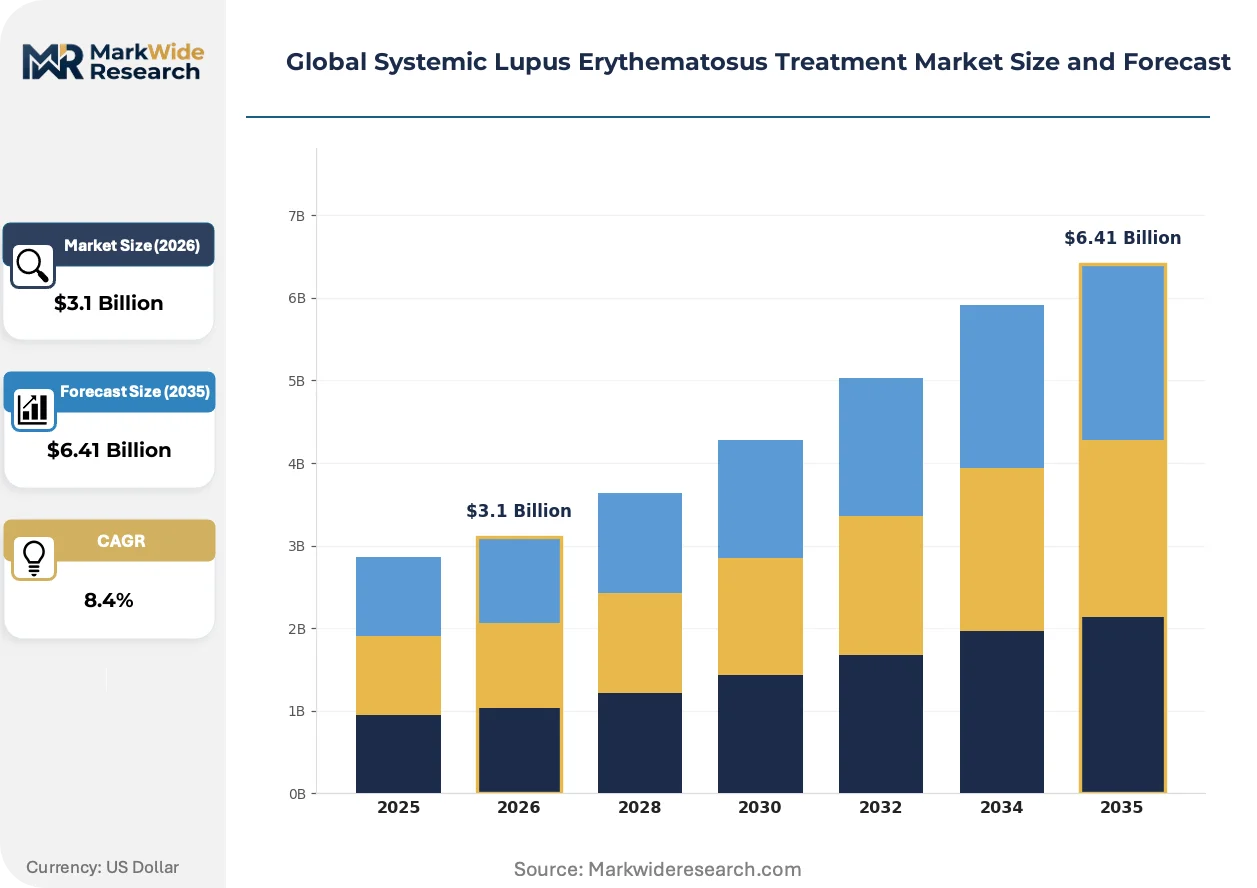
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Antimalarials, Corticosteroids, Biologic Agents, NSAIDs Therapy Area: Cutaneous Lupus, Lupus Nephritis, Neuropsychiatric Lupus, Cardiopulmonary Lupus, Hematologic Lupus End User: Specialty Clinics, Rheumatology Centers, Research Institutes, Diagnostic Laboratories Delivery Mode: Oral, Injectable, Intravenous, Topical |
| Companies Covered | GSK plc, AstraZeneca, F. Hoffmann-La Roche Ltd, Novartis AG, Bristol-Myers Squibb Company, Sanofi, Pfizer Inc., Eli Lilly and Company, Aurinia Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Systemic Lupus Erythematosus Treatment Market Shifts & Advancements
Targeted immunomodulation is displacing broad immunosuppression as the therapeutic standard, with mechanism-specific biomarkers guiding patient selection and trial enrichment strategies across development programs.
Bispecific antibody constructs engaging both B-cell and T-cell targets are consolidating the next-generation pipeline. Roche and smaller biotechs are advancing these formats into Phase II for refractory lupus populations. The technology is consolidating investment away from single-target monoclonals toward dual-mechanism candidates that promise deeper remission rates.
EMA's evolving MDR framework is decoupling clinical evidence requirements from traditional randomized trial designs for autoimmune biologics. Manufacturers can now leverage registry data and external control arms for post-market commitments. European rheumatology societies are adapting treatment guidelines to incorporate these expanded evidentiary sources.
Specialty pharmacy distribution is displacing traditional wholesale channels for infused biologics. United States payers now mandate white-bag or buy-and-bill alternatives that shift inventory risk to physician practices. This channel compression is most visible in lupus nephritis protocols where site-of-care economics determine formulary placement.
Global Systemic Lupus Erythematosus Treatment Market Segmentation
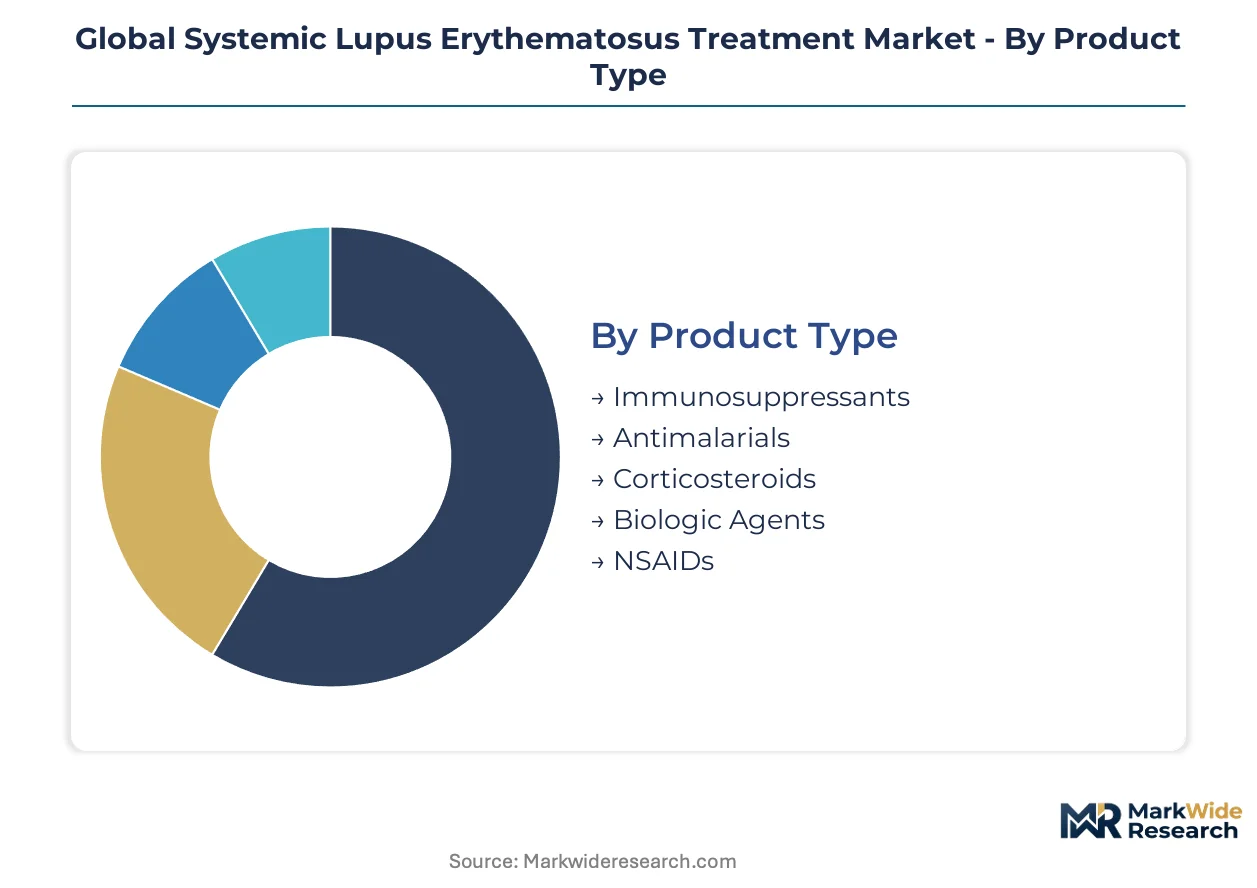
Treatment selection for systemic lupus erythematosus hinges on organ involvement patterns, severity indices, and payer reimbursement tiers. Segmentation reveals how biologic premium pricing concentrates in rheumatology centers while oral generics dominate maintenance protocols in cost-sensitive settings.
Product Type:
Prescribing economics drive category selection, with biologic agents commanding reimbursement premiums and corticosteroids serving as default induction therapy where formulary constraints apply.
- Biologic Agents:Monoclonal antibodies targeting B-cell and interferon pathways deliver targeted immunomodulation with reduced corticosteroid burden. United States rheumatology centers prioritize these agents for lupus nephritis induction, though prior authorization requirements delay initiation by four to eight weeks.
- Immunosuppressants:Small-molecule agents including mycophenolate mofetil and azathioprine form the backbone of maintenance regimens. Germany's statutory health insurance funds favor these as first-line steroid-sparing options, driving volume concentration across European outpatient networks.
- Corticosteroids:Prednisone and methylprednisolone remain the universal induction standard due to immediate anti-inflammatory efficacy and minimal acquisition cost.
- Antimalarials:Hydroxychloroquine serves as the foundational maintenance therapy across all disease severities.
- NSAIDs:Symptomatic management for arthralgia and serositis without disease-modifying properties.
Immunosuppressants lead on scale; biologic agents lead on momentum.
Therapy Area:
Organ-specific involvement patterns determine treatment intensity, with renal and neuropsychiatric manifestations driving the most aggressive intervention protocols and repeat treatment cycles.
- Lupus Nephritis:Renal involvement mandates combination immunosuppression with biologic or calcineurin inhibitor add-ons to prevent end-stage renal disease. United States nephrology-rheumatology co-management models concentrate high-value prescribing in academic medical centers.
- Cutaneous Lupus:Skin-limited disease spans topical corticosteroids through systemic antimalarials to biologic intervention for refractory discoid lesions. France's dermatology-rheumatology referral networks prioritize topical-first protocols before systemic escalation.
- Neuropsychiatric Lupus:Central nervous system involvement requires high-dose corticosteroid pulses and cyclophosphamide for severe presentations.
- Cardiopulmonary Lupus:Pericarditis, myocarditis, and interstitial lung disease drive immunosuppressive intensity calibrated to hemodynamic compromise.
- Hematologic Lupus:Autoimmune cytopenias respond variably to standard immunosuppression, with refractory cases requiring splenectomy or thrombopoietin agonists.
Lupus nephritis claims the steepest expansion trajectory as renal biopsy protocols expand and repeat induction cycles multiply; cutaneous lupus maintains the broadest patient base.
End User:
Site-of-care economics and infusion infrastructure determine channel access for parenteral biologics, fragmenting prescribing authority between community and academic settings.
- Rheumatology Centers:Dedicated infusion suites and biomarker testing capabilities enable biologic patient selection and monitoring. United States payers increasingly mandate these centers for buy-and-bill reimbursement of intravenous belimumab and anifrolumab.
- Specialty Clinics:Community-based lupus-focused practices manage stable maintenance patients with oral regimens and telemedicine follow-up. Japan's clinic-based rheumatology model concentrates stable patient volumes outside hospital settings.
- Research Institutes:Academic medical centers host clinical trials and refractory patient referral networks.
- Diagnostic Laboratories:Complement levels, anti-dsDNA titers, and interferon signature assays guide treatment decisions.
Rheumatology centers lead on biologic revenue concentration; specialty clinics lead on patient volume throughput.
Delivery Mode:
Route selection balances bioavailability requirements against patient adherence patterns, with subcutaneous formulations gaining share for maintenance biologics.
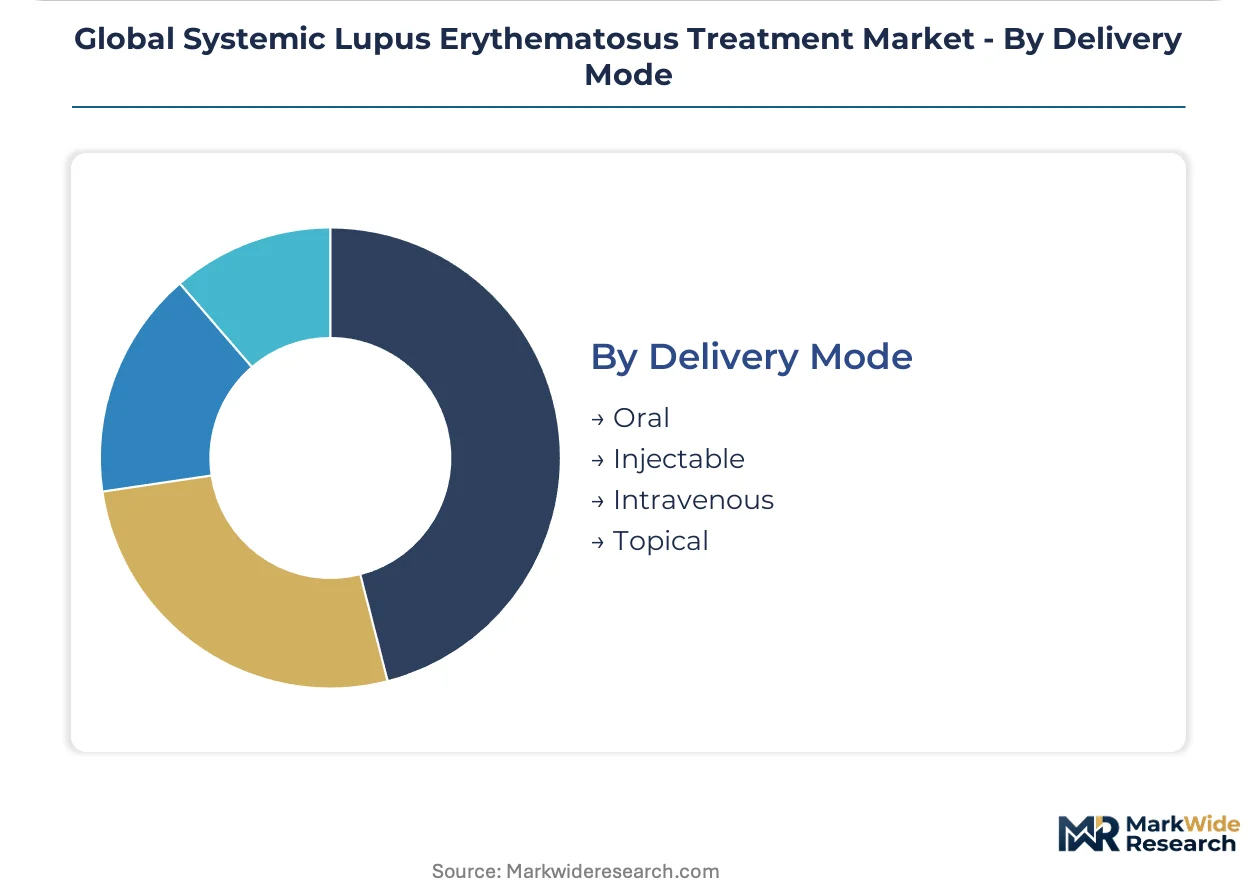
- Intravenous:Hospital and infusion center administration ensures compliance for high-cost biologics requiring monitoring. Germany's outpatient infusion reimbursement framework sustains channel preference for belimumab despite subcutaneous alternatives.
- Injectable:Subcutaneous biologics and self-administered immunosuppressants enable home-based maintenance. United States specialty pharmacy distribution of subcutaneous belimumab is displacing some infusion volume.
- Oral:Antimalarials, corticosteroids, and small-molecule immunosuppressants dominate daily maintenance regimens.
- Topical:Limited to cutaneous lupus manifestations with minimal systemic absorption.
Oral delivery leads on prescription volume; intravenous leads on revenue per patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheumatology specialist density concentrates prescribing authority in urban medical centers across major markets. Training pipeline constraints limit biologic administration capacity outside tertiary hubs. Regulatory divergence between FDA, EMA, and PMDA shapes divergent launch sequencing and evidence requirements.
United States
Lupus nephritis protocols drive biologic demand at academic medical centers in Boston, New York, and Philadelphia. FDA's accelerated approval pathway compresses development timelines for surrogate endpoint trials. The Mayo Clinic and Cleveland Clinic anchor refractory patient referral networks and real-world evidence generation.
Germany
Statutory health insurance funds favor immunosuppressant-first protocols, creating volume concentration in outpatient rheumatology networks. EMA's MDR convergence extends review timelines for device-enabled drug delivery systems. Berlin and Munich host the largest infusion center expansions for biologic administration.
Japan
PMDA's Sakigake designation accelerates access for biomarker-enriched autoimmune therapies. Tokyo and Osaka rheumatology departments concentrate lupus specialist training and clinical trial enrollment. The national health insurance reimbursement framework supports rapid adoption of mechanism-differentiated biologics.
United Kingdom
NICE technology appraisals create step-therapy requirements that delay biologic access in cost-constrained settings. London's tertiary rheumatology centers manage complex multi-organ involvement cases. The NHS England specialized commissioning framework concentrates high-cost prescribing in designated treatment centers.
France
ANSM pharmacovigilance requirements shape post-approval commitment studies for biologic agents. Paris and Lyon dermatology-rheumatology referral networks prioritize topical-first protocols before systemic escalation. The HAS reimbursement assessment framework evaluates real-world effectiveness data for maintenance therapy positioning.
Global Systemic Lupus Erythematosus Treatment Market Competitive Landscape
The competitive structure tilts toward large-cap biopharma with immunology franchise depth. Market concentration reflects high R&D barriers and specialized manufacturing requirements for monoclonal antibodies. Two strategic archetypes dominate: established autoimmune incumbents with rheumatology sales infrastructure and emerging biotechs with mechanism-differentiated pipeline assets. Competitive moves center on portfolio diversification into complement pathway modulation and strategic partnerships for pediatric indication expansion.
Within the established biopharma tier, GSK plc and AstraZeneca exemplify archetypes of mechanism-specific franchise builders. F. Hoffmann-La Roche Ltd occupies a position representing deep immunology R&D pipeline investment. These three companies anchor the biologic agents segment through differentiated B-cell and interferon pathway approaches.
| Leading Market Players |
|---|
| GSK plc |
| AstraZeneca |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Sanofi |
| Pfizer Inc. |
| Eli Lilly and Company |
| Aurinia Pharmaceuticals Inc. |
| Others |
Supply & Pricing Matrix
United States rheumatology centers and German statutory insurance funds anchor demand concentration, locking in a buy-and-bill reimbursement model that bundles infusion administration with drug acquisition. This buyer archetype alignment preserves premium pricing for biologic agents while compressing margins on oral generics through formulary step-therapy protocols.
Pricing Analysis
Biologic pricing splits between bundled infusion services and unbundled specialty pharmacy distribution, with subcutaneous formulations capturing patient-convenience premiums. Price differentiation rests on interferon signature assay availability and site-of-care economics, with academic medical centers commanding higher reimbursement than community practices. Pricing pressure stems from corticosteroid substitution persistence in cost-constrained markets, where generic prednisone delays biologic initiation by six to eighteen months. Payer step-therapy protocols render emerging economies most price-sensitive, while United States rheumatology centers exhibit lowest sensitivity due to prior authorization insulation.
Supply Chain Analysis
Fill-finish capacity certification under FDA's sterile drug product guidelines and EMA's GMP Annex 1 revisions gates supplier qualification, concentrating monoclonal antibody production among three global CDMO networks in the United States, Switzerland, and Ireland. Active pharmaceutical ingredient sourcing draws from Chinese and Indian fermentation capacity for small-molecule immunosuppressants, while biologic cell lines remain captive to developer-owned facilities. Single-source dependencies in aseptic manufacturing create vulnerability to regulatory inspection delays. Distribution runs through specialty pharmacy channels for subcutaneous products and hospital outpatient infusion centers for intravenous formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in systemic lupus erythematosus treatment hinges on corticosteroid-sparing protocol adoption, where biologic premium pricing offsets manufacturing complexity costs through reduced hospitalization burden.
For Market Incumbents: Cement dominance in lupus nephritis protocols by deepening rheumatology center partnerships and securing site-of-care exclusivity contracts. Threats from bispecific antibody pipelines require accelerated investment in interferon pathway biomarker standardization. Backward integration into fill-finish capacity insulates against CDMO concentration risk. For New Entrants and Emerging Players: FDA's accelerated approval pathway in the United States opens a window for surrogate endpoint trial designs that compress development timelines. White-space targets include pediatric lupus indications and Japan's PMDA Sakigake-eligible biomarker-enriched subsets. A telemedicine-enabled monitoring go-to-market angle differentiates against incumbent infusion center dependency. For Investors and Strategic Acquirers: Large-cap biopharma with immunology franchise depth is the most active acquirer in this space, seeking mechanism-differentiated pipeline assets. Long-term viability centers on complement pathway modulation science and pediatric indication expansion. The signal to watch is real-world evidence infrastructure maturity, indicating post-approval commercialization readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA's accelerated approval compresses lupus nephritis trial duration through surrogate endpoints. |
| Manufacturing Scale-Up | Aseptic fill-finish capacity expansion reduces single-source CDMO dependency for monoclonal antibodies. |
| Pipeline Diversification | Complement inhibition programs target refractory cutaneous and renal manifestations beyond B-cell depletion. |
| Reimbursement Strategy | Site-of-care economics alignment secures formulary placement in United States buy-and-bill networks. |
| Strategic Partnership | Telemedicine platform alliances enable rural patient retention and real-world data capture infrastructure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Segment-weighting approaches distributed value across biologic agents, immunosuppressants, corticosteroids, and antimalarials by therapy area, delivery mode, and end-user channel. CAGRs were derived from epidemiological trend extrapolation and pricing trajectory analysis across the projection horizon. Forecast inputs incorporated rheumatology center expansion rates and regulatory approval velocity assumptions.
Revisions become necessary when interferon signature assay standardization delays, CDMO capacity constraints, or payer step-therapy protocol extensions materialize beyond baseline assumptions. Forecasts reflect documented judgments on biomarker validation timelines and real-world evidence infrastructure maturity. A model refresh is warranted upon material change in FDA accelerated approval evidentiary requirements or EMA MDR framework implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Radiation Proctitis Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Mercury Poisoning Treatment Market