
 Inguinal Hernia Market | 2026-2036
Inguinal Hernia Market Size, Share, and Industry Trends Forecast 2026-2036
Inguinal Hernia Market Outlook
Multi-source mesh procurement is consolidating around manufacturers with captive polymer spinning and weaving operations. Ethicon Inc. leverages its Johnson & Johnson parent infrastructure for vertical control over polypropylene supply. B. Braun Melsungen AG anchors European production with specialized extrusion lines for lightweight macroporous mesh. W. L. Gore & Associates differentiates through expanded polytetrafluoroethylene biomaterials that command premium positioning in complex bilateral repairs.
An inguinal hernia denotes a protrusion of abdominal cavity contents through a weakened area in the groin canal, typically repaired via implantation of a reinforcing mesh prosthetic measuring 10-15 cm in width to restore fascial integrity. Synthetic polypropylene mesh dominates procedural economics due to tensile strength exceeding 40 N/cm and cost profiles accessible to public health systems. Laparoscopic surgery applications now represent the fastest-expanding application segment as port-site placement techniques reduce chronic pain incidence. Biologic mesh technology occupies a narrow but high-margin niche in contaminated fields where synthetic implantation risks enteric erosion.
The FDA's 510(k) premarket notification pathway governs mesh device commercialization in the United States, while the EU Medical Device Regulation mandates clinical evaluation reports for Class III implantable prosthetics. Health Canada and the Therapeutic Goods Administration impose parallel biocompatibility testing standards that prolong registration timelines for new market entrants. Stakeholders must monitor evolving regulatory divergence between North American and European requirements for permanent implant materials.
Market Dynamics
Mesh procurement is consolidating around manufacturers with captive polymer spinning operations, compressing margins for distributors and forcing mid-tier suppliers to specialize in regional niches or exit the market entirely.
Growth Catalysts
- Ambulatory surgical center expansion:CMS reimbursement codes in the United States now favor same-day discharge protocols, accelerating procedural volume migration from inpatient settings.
- Laparoscopic technique maturation:Port-site placement refinements reduce chronic pain incidence below open repair baselines, driving surgeon retraining investments across hospital systems.
- EU Medical Device Regulation harmonization:MDR Class III implantable prosthetic pathways streamline cross-border commercialization for manufacturers with established quality management systems.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer prices fluctuate with crude oil benchmarks, squeezing gross margins for mesh producers without long-term supply contracts.
- Single-source extrusion concentration:European lightweight macroporous mesh production clusters in southern Germany, creating geographic vulnerability to regional logistics disruptions.
- Biologic mesh cost ceiling:Porcine and bovine-derived substrates command 8-12x synthetic pricing, limiting addressable market penetration to contaminated field cases.
Strategic Opportunities
- India outpatient infrastructure buildout:Ayushman Bharat health assurance expansion funds hernia repair camps in tier-2 cities, creating volume pipelines for value-tier mesh suppliers.
- Robotic-assisted laparoscopic convergence:Da Vinci platform integration with 3D visualization reduces operative time variability, opening premium positioning for compatible mesh fixation systems.
- Japan PMDA fast-track designation:Sakigake approval pathway accelerates market entry for novel anti-adhesive barrier coatings on polypropylene substrates.
Industry Challenges
- Polymer characterization skill scarcity:ISO 10993 biocompatibility testing expertise concentrates in contract research organizations, extending internal R&D timelines for new entrants.
- Legacy open repair technique entrenchment:Rural general surgeons in lower-volume markets resist laparoscopic certification investments, fragmenting training standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inguinal Hernia Market |
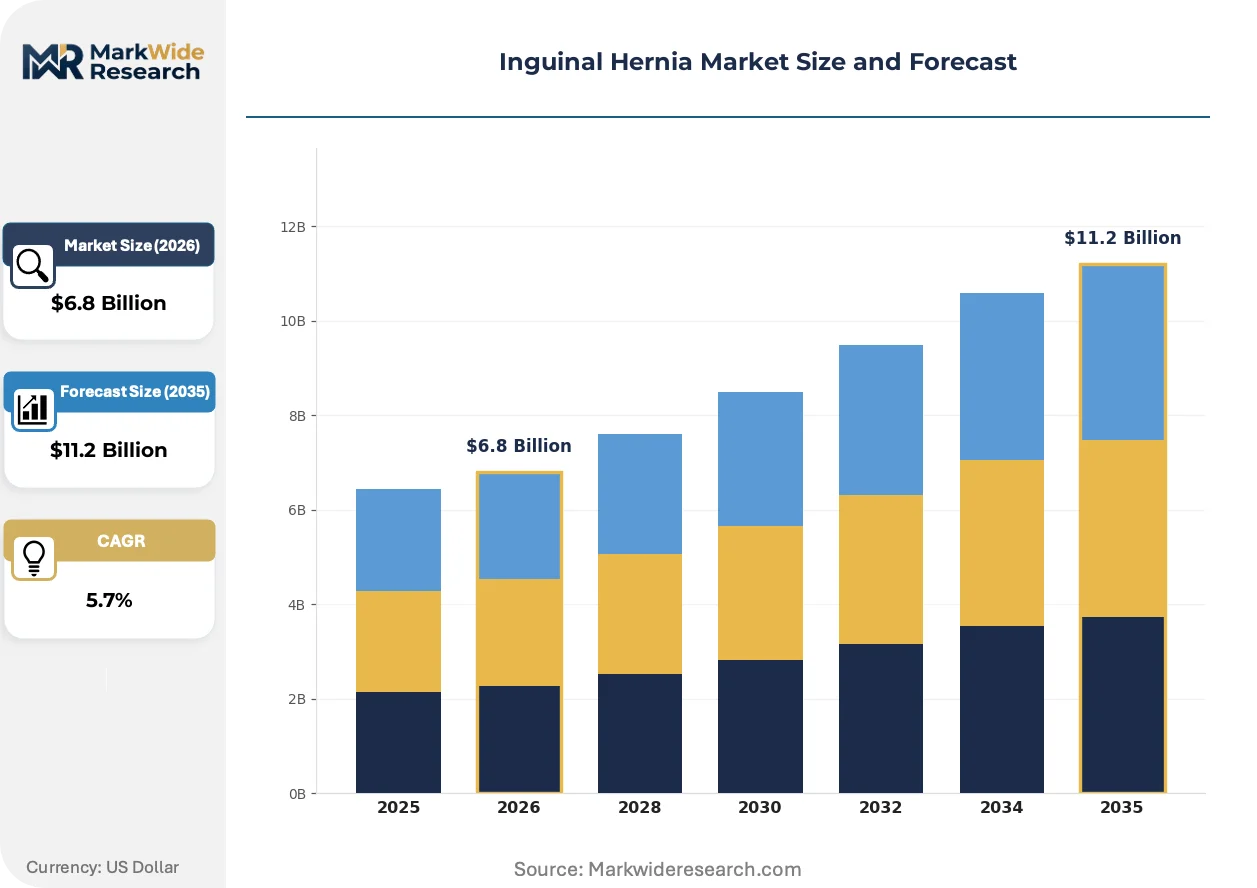
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh, Sutures, Fixation Devices, Staples End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Home Care Application: Open Surgery, Laparoscopic Surgery, Robotic Surgery, Revision Surgery Technology: Biologic Mesh, Synthetic Mesh, Expandable Mesh, Composite Mesh |
| Companies Covered | B. Braun Melsungen AG, Cook Medical, Ethicon Inc. (Johnson & Johnson), Atrium Medical, AbbVie Inc., Medtronic, W. L. Gore & Associates, Integra LifeSciences, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inguinal Hernia Market Strategic Shifts
Device-level innovation is compressing toward materials science differentiation, with manufacturers racing to optimize pore architecture and surface chemistry rather than pursuing radical procedural disruption.
Lightweight macroporous polypropylene mesh is consolidating procedural preference in elective bilateral repairs. Ambulatory surgical centers in Germany and the United States now specify sub-40 g/m² areal density constructs for tension-free Lichtenstein repairs. This specification shift is consolidating procurement decisions around suppliers with in-house extrusion and textile finishing capabilities.
The EU Medical Device Regulation's clinical evaluation report mandate for Class III implantables is reshaping documentation burdens. Manufacturers must now submit post-market surveillance data for predicate devices, extending registration timelines by 12-18 months. Small-cap mesh specialists without legacy clinical databases are responding through strategic partnerships with academic medical centers for retrospective cohort assembly.
Surgeon preference for pre-shaped three-dimensional mesh constructs is altering distributor inventory requirements. Hospital purchasing committees in France and Italy now demand sterilized, ready-to-implant configurations that eliminate intraoperative cutting. This specification compression is forcing distributors to carry broader SKU portfolios or cede accounts to manufacturer-direct service models.
Inguinal Hernia Market Segmentation
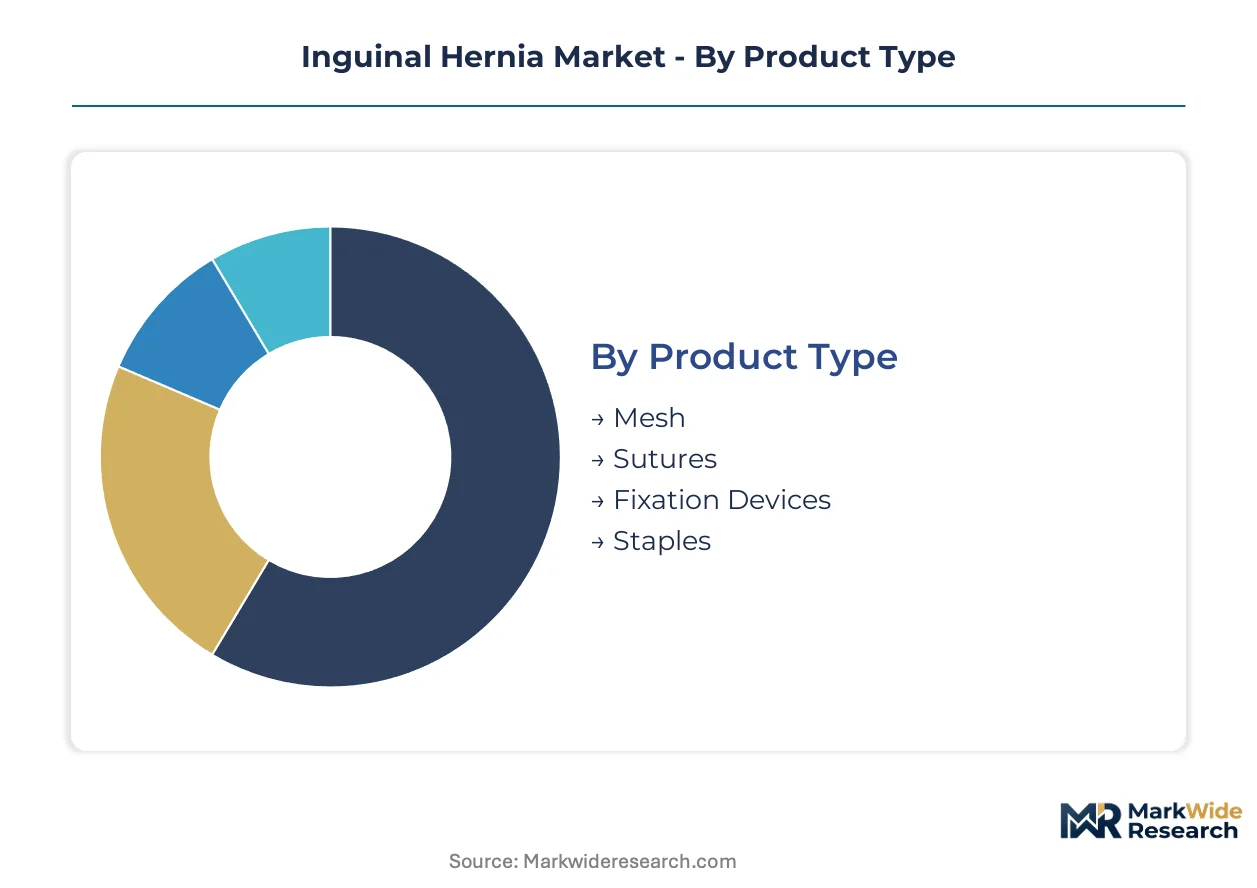
Mesh selection dictates procedural economics and reimbursement pathways across repair settings. Product architecture, surgical venue, operative technique, and material composition each create distinct procurement and margin profiles.
Product Type:
Mesh functions as the standalone revenue anchor, while fixation systems and sutures embed within broader procedural bundles.
- Mesh:Polypropylene constructs measuring 10-15 cm width dominate volume, with lightweight macroporous specifications below 40 g/m² density displacing heavyweight legacy products in ambulatory settings. Procurement in Germany and the United States now specifies pre-shaped three-dimensional configurations that eliminate intraoperative customization.
- Fixation Devices:Tackers and absorbable anchors secure mesh placement in laparoscopic repairs, with compatibility requirements tightening around robotic platform integration. Demand clusters in hospital systems with Da Vinci platform investments.
- Sutures:Polypropylene monofilament remains standard for open Lichtenstein repairs, though volume share compresses as mechanical fixation gains preference in minimally invasive techniques.
- Staples:Titanium and absorbable polymer variants serve niche applications in bilateral repairs requiring rapid deployment.
Volume placements concentrate in Mesh; the faster expansion belongs to Fixation Devices.
End User:
Venue selection determines reimbursement rates, inventory turnover velocity, and supplier relationship structures.
- Ambulatory Surgical Centers:CMS reimbursement codes in the United States now favor same-day discharge protocols, accelerating procedural migration from inpatient settings. These centers specify lightweight mesh with sterilized ready-to-implant configurations to minimize processing overhead.
- Hospitals:Academic medical centers and community hospitals retain complex bilateral and revision cases, maintaining demand for biologic mesh in contaminated fields. Inventory requirements span broader SKU portfolios to cover robotic, laparoscopic, and open techniques.
- Specialty Clinics:Hernia-focused centers concentrate high-volume elective repairs, negotiating direct manufacturer relationships that bypass distributor markups.
- Home Care:Post-operative monitoring and wound management services capture limited device revenue, primarily drainage and dressing supplies.
Revenue concentration sits with Ambulatory Surgical Centers; hospital systems retain the premium-case margin.
Application:
Technique selection reflects surgeon training investment, patient comorbidity profiles, and institutional equipment availability.
- Laparoscopic Surgery:Port-site placement refinements reduce chronic pain incidence below open repair baselines, driving surgeon retraining investments across hospital systems in Germany and the United States. This technique now commands preference in bilateral repairs.
- Open Surgery:Lichtenstein tension-free repair remains dominant in rural markets and resource-constrained settings where laparoscopic infrastructure is absent. General surgeons without minimally invasive certification sustain volume here.
- Robotic Surgery:Da Vinci platform integration with 3D visualization reduces operative time variability, opening premium positioning for compatible mesh fixation systems in high-volume centers.
- Revision Surgery:Recurrence and chronic pain cases require biologic mesh or specialized composite constructs, commanding 8-12x synthetic pricing in contaminated or previously operated fields.
Case volume tilts toward Open Surgery; Laparoscopic Surgery climbs the fastest as training standardization advances.
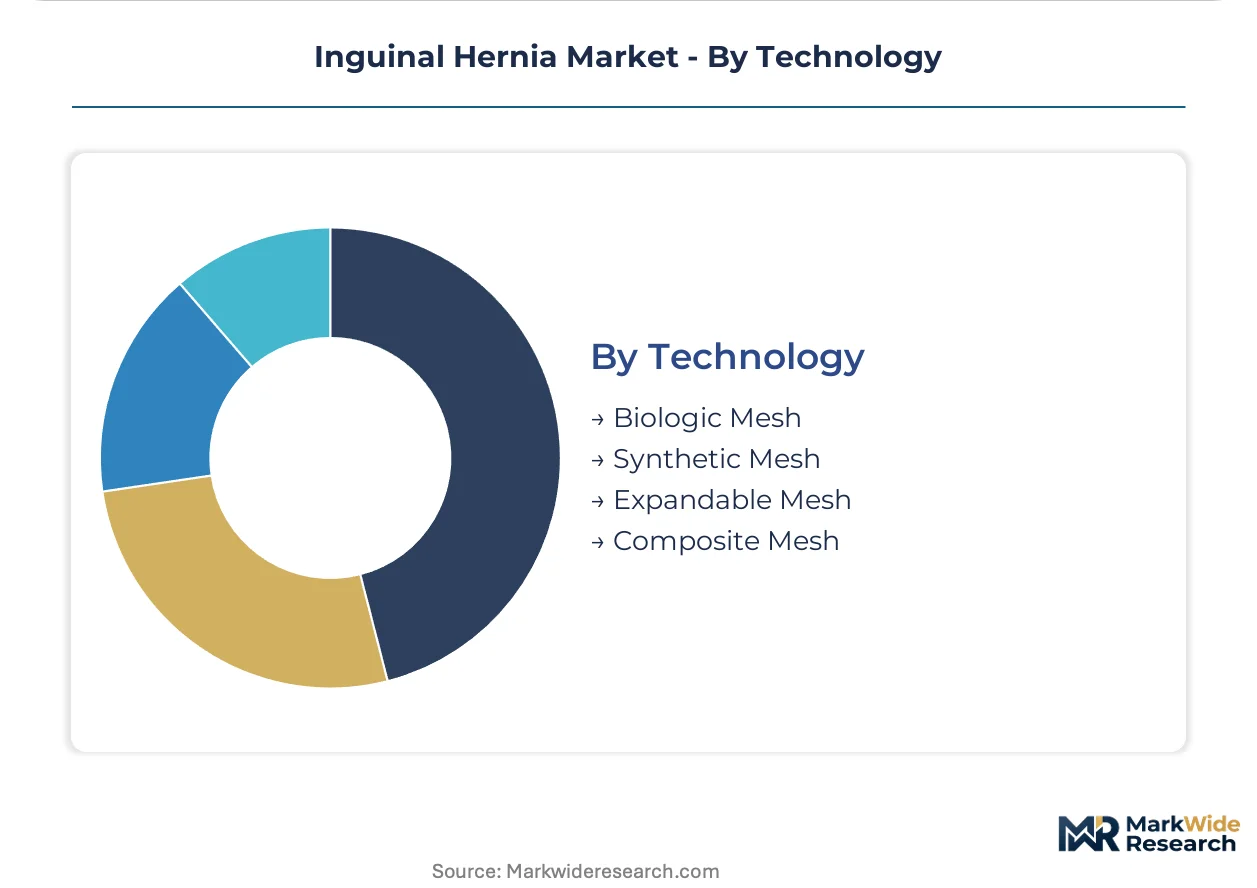
Technology:
Material science differentiation separates mass-market synthetic supply from high-margin biologic and composite niches.
- Synthetic Mesh:Polypropylene dominates procedural economics due to tensile strength exceeding 40 N/cm and cost profiles accessible to public health systems. Manufacturers with captive polymer spinning operations control supply security.
- Biologic Mesh:Porcine and bovine-derived substrates occupy contaminated field applications where synthetic implantation risks enteric erosion. FDA 510(k) clearance pathways govern commercialization in the United States.
- Composite Mesh:Anti-adhesive barrier coatings on polypropylene substrates target intraperitoneal placement, with Japan's PMDA Sakigake pathway accelerating novel coating approvals.
- Expandable Mesh:Self-expanding nitinol or shape-memory configurations serve specialized applications requiring conformal fit to irregular tissue planes.
Unit volume centers on Synthetic Mesh; Composite Mesh gains share fastest as barrier technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene monomer supply chains anchored in the US Gulf Coast and Rotterdam-Antwerp corridor shape regional manufacturing economics for mesh producers. Hospital procurement patterns and ambulatory center expansion trajectories diverge markedly across national healthcare systems.
United States
Ambulatory surgical center volume migration accelerates as CMS reimbursement codes favor same-day discharge protocols. The FDA's 510(k) premarket notification pathway governs mesh device commercialization, with clearance timelines compressing for predicate-backed submissions. The Texas Medical Center in Houston anchors high-volume robotic repair training programs that diffuse technique standardization nationwide.
Germany
Laparoscopic repair rates exceed European regional averages as reimbursement frameworks favor minimally invasive techniques. The EU Medical Device Regulation mandates clinical evaluation reports for Class III implantable prosthetics, extending registration timelines for new market entrants. Southern Germany's specialized extrusion lines for lightweight macroporous mesh concentrate European production capacity.
Japan
Surgeon preference for anti-adhesive barrier coatings drives demand for composite mesh constructs. The PMDA Sakigake fast-track designation accelerates market entry for novel coating technologies on polypropylene substrates. Tokyo's academic medical centers assemble retrospective cohort databases to satisfy MDR-equivalent clinical evaluation requirements.
India
Ayushman Bharat health assurance expansion funds hernia repair camps in tier-2 cities, creating volume pipelines for value-tier mesh suppliers. The Central Drugs Standard Control Organization governs import licensing and manufacturing site inspections for implantable devices. Maharashtra's Mumbai-Pune corridor concentrates distributor networks serving western India's hospital procurement committees.
Brazil
Private health insurance penetration drives elective repair volume in metropolitan centers while public sector capacity constrains access. ANVISA imposes biocompatibility testing standards parallel to ISO 10993 protocols, prolonging registration timelines for imported mesh devices. São Paulo's hospital networks anchor training programs for laparoscopic technique diffusion across Latin America.
Inguinal Hernia Market Competitive Environment
Backward integration into polymer spinning operations dominates the current landscape as manufacturers seek supply security amid feedstock volatility. The vendor base stratifies across three tiers: diversified medical device conglomerates with captive materials operations, mid-tier specialists with regional extrusion partnerships, and distribution-dependent entrants facing margin compression. Strategic archetypes include upstream-integrated polymer producers, biologic substrate specialists, and robotic-platform compatibility developers. Capacity expansion and M&A consolidation represent the dominant competitive vectors as scale advantages harden.
Among diversified medical device conglomerates, Ethicon Inc., B. Braun Melsungen AG, and W. L. Gore & Associates occupy positions defined by materials science differentiation. Ethicon exemplifies the vertically integrated archetype through parent-company infrastructure control over polypropylene supply. B. Braun Melsungen AG anchors European production positioning with specialized manufacturing capabilities. W. L. Gore & Associates represents the premium-tier biomaterials specialist archetype, commanding positioning in complex bilateral repair applications through differentiated substrate technologies.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Cook Medical |
| Ethicon Inc. (Johnson & Johnson) |
| Atrium Medical |
| AbbVie Inc. |
| Medtronic |
| W. L. Gore & Associates |
| Integra LifeSciences |
| Becton Dickinson and Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap mesh manufacturers in southern Germany anchor European supply discipline through generational capital structures that resist short-term margin erosion, enabling pricing stability across lightweight polypropylene tiers even as propylene feedstock volatility squeezes distributors without long-term polymer contracts.
Pricing Analysis
Warranty and sterilization service bundling separates manufacturer-direct pricing from distributor-mediated transactions, with pre-shaped three-dimensional constructs commanding premium positioning over intraoperative-cuttable sheets. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and ISO 10993 biocompatibility certification grade. Pricing pressure stems from CMS reimbursement compression on ambulatory procedures, forcing mid-tier suppliers toward unbundled service models. Hospital purchasing committees exhibit lowest price sensitivity for biologic mesh in contaminated fields, while tier-2 Indian clinics drive volume at economy synthetic tiers.
Supply Chain Analysis
Ocean freight cost spikes from Rotterdam-Antwerp corridor to Mumbai-Pune distribution hubs compress margins for European exporters serving India's Ayushman Bharat expansion. Supply concentrates in Germany, the United States, and China, with propylene monomer feedstock drawing from US Gulf Coast petrochemical complexes. Specialized extrusion equipment for macroporous lightweight mesh rests on single-source German engineering houses, creating geographic vulnerability to regional logistics disruptions. Distribution runs through hospital purchasing committees in developed markets and government tender systems in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
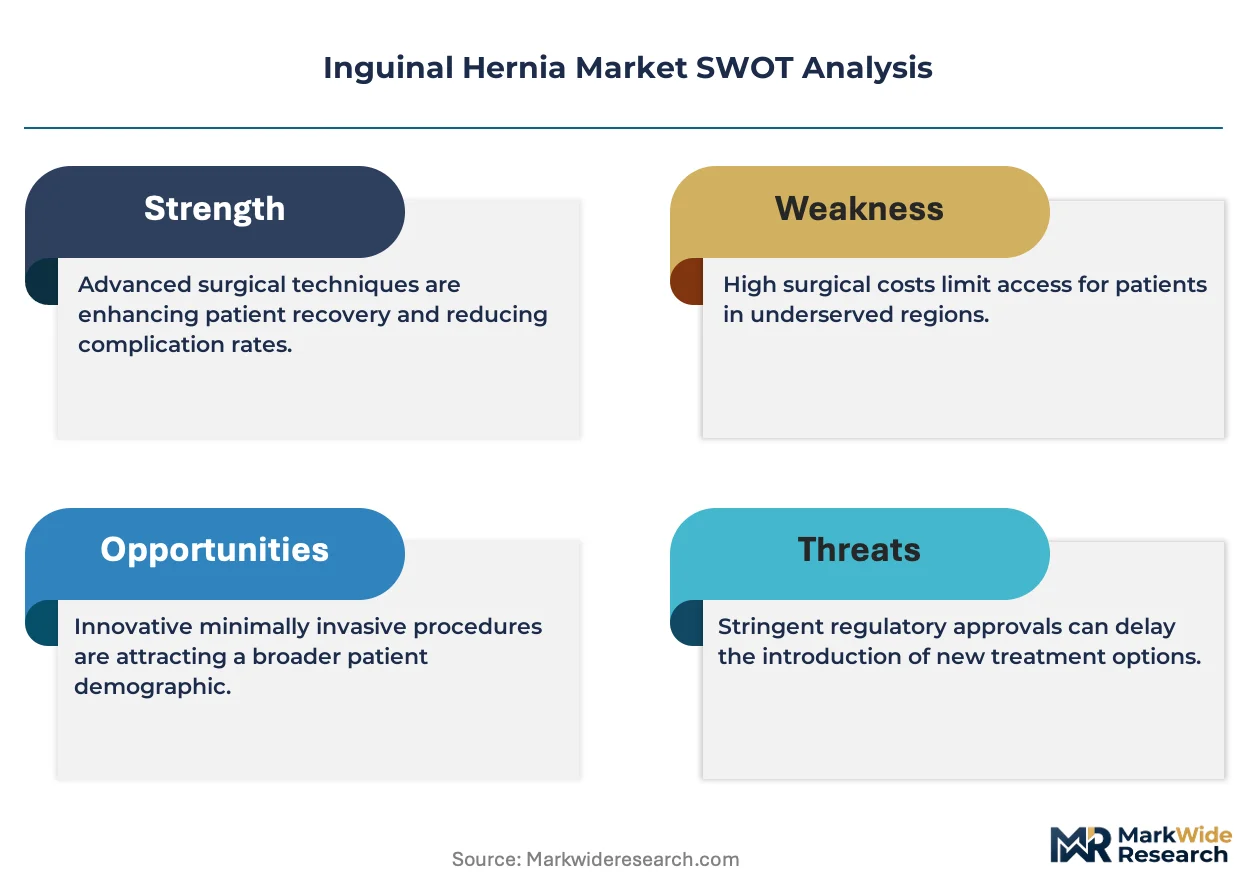
The EU Medical Device Regulation's clinical evaluation report mandate for Class III implantables erects a compliance moat that rewards manufacturers with legacy clinical databases while extending registration timelines for undercapitalized entrants by 12-18 months.
For Market Incumbents: Anticipate biologic mesh substitution threats in contaminated field applications by deepening anti-adhesive barrier R&D partnerships with Japanese academic medical centers. Secure propylene supply through captive polymer spinning operations or long-term offtake agreements with US Gulf Coast producers. Consolidate distributor relationships in Germany through direct service models for pre-shaped sterilized constructs. For New Entrants and Emerging Players: The 8-12x pricing gap between biologic and synthetic mesh creates white-space opportunity in value-tier composite constructs for India's tier-2 outpatient infrastructure. Target Maharashtra's Mumbai-Pune corridor distributor networks with lightweight macroporous specifications below 40 g/m² density. Pursue CDSCO import licensing pathways ahead of domestic manufacturing site investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier mesh specialists with established EU MDR technical documentation but constrained clinical evaluation resources in southern Germany. Long-term viability hinges on robotic-platform compatibility positioning as Da Vinci system penetration deepens. Monitor Japan PMDA Sakigake approval velocity as inflection signal for novel coating technology commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evaluation Report Assembly | Accelerates market entry for predicate-backed mesh submissions through retrospective cohort partnerships with German academic centers. |
| Backward Integration into Polypropylene Extrusion | Secures margin control against propylene monomer volatility for manufacturers serving CMS-reimbursed ambulatory procedures. |
| Robotic Platform Fixation Compatibility Development | Captures premium positioning in Da Vinci-equipped hospital systems through tacker and anchor system integration. |
| India CDSCO Manufacturing Site Certification | Unlocks government tender access for Ayushman Bharat-funded hernia repair camps in western India's tier-2 cities. |
| Japan PMDA Sakigake Pathway Navigation | Compresses approval timelines for anti-adhesive barrier coatings through fast-track designation for novel polypropylene substrates. |
Study Parameters
Document review covered FDA 510(k) premarket notification databases, EU MDR clinical evaluation report submissions, and CMS reimbursement code filings, complemented by interviews with hospital purchasing committee directors, GPO contracts managers, biomedical engineers specializing in hernia repair, and regulatory affairs leads at mesh manufacturers. Secondary sources included hospital procurement databases, ANVISA import licensing records, and PMDA approval tracking systems. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue disclosures.
Historical repair volume trajectories cross-referenced against surgeon panel input on technique migration timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product architecture, surgical venue, operative technique, material composition, and regional regulatory cluster. CAGRs derived from weighted average of epidemiological incidence projections and reimbursement policy scenario analysis, with propylene feedstock cost curves and laparoscopic training penetration rates as industry-specific forecast inputs.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in private-pay procedural volume reporting from Brazilian and Indian outpatient clinics introduce uncertainty bands around emerging market estimates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Beta Thalassemia Treatment Market