
 Necrotizing Skin Infections Treatment Market | 2026-2036
Necrotizing Skin Infections Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Necrotizing Skin Infections Treatment Market Analytics
Next-generation bacteriophage adjunct therapy is reconfiguring how clinicians approach polymicrobial necrotizing infections, moving beyond traditional broad-spectrum coverage toward targeted pathogen elimination. Pfizer leverages its established anti-infectives infrastructure to sustain commercial reach across hospital formularies. CSL Behring anchors the immunoglobulin segment with plasma-derived therapies for toxin-mediated cases. Grifols competes through vertical control of plasma collection networks spanning multiple continents.
Necrotizing skin infections treatment encompasses pharmaceutical and surgical interventions targeting rapidly progressive soft-tissue destruction caused by bacterial, fungal, or polymicrobial pathogens, typically requiring intravenous broad-spectrum antibiotics with minimum inhibitory concentration-guided dosing plus emergent surgical debridement to remove devitalized tissue and restore perfusion. The primary purpose centers on reducing mortality through rapid source control and hemodynamic stabilization in critical care settings. Antibiotics dominate product type revenue due to mandatory empiric initiation within one hour of sepsis recognition, while immunoglobulins capture concentrated margin pools in severe streptococcal toxic shock syndrome. Combination therapy leads treatment protocol selection as clinicians layer bactericidal agents with toxin-neutralizing modalities, whereas targeted therapy grows fastest as rapid molecular diagnostics shorten pathogen identification timelines.
The FDA's Qualified Infectious Disease Product program shapes antibiotic development incentives through extended market exclusivity provisions, while the EMA's priority medicines scheme accelerates European access review timelines for novel anti-infectives. Both frameworks directly influence corporate R&D allocation toward pathogens designated as urgent antimicrobial resistance threats by the WHO. Stakeholders must monitor how hospital reimbursement policies evolve around novel adjunctive therapies versus standard-of-care surgical and pharmaceutical protocols.
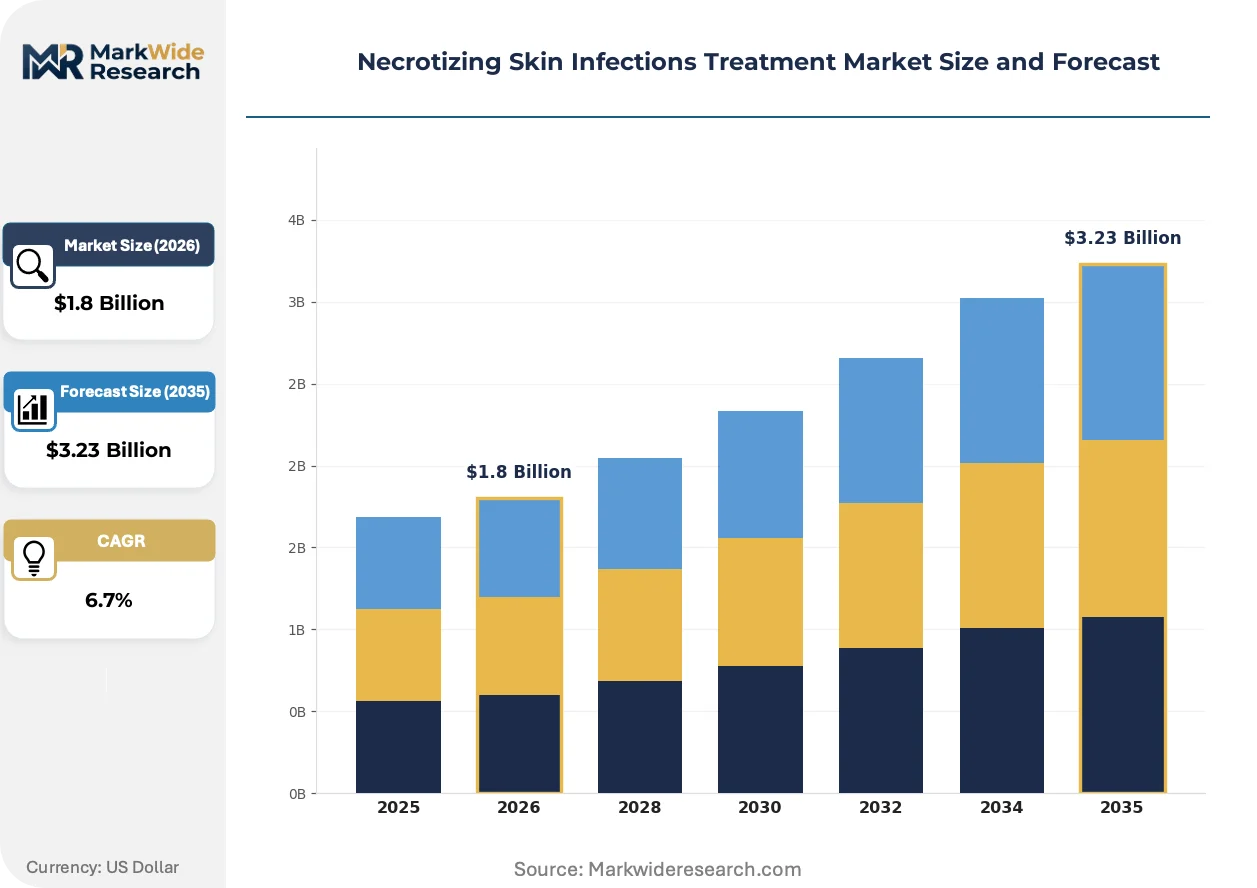
Market Dynamics
The FDA's Qualified Infectious Disease Product designation is restructuring antibiotic development economics by extending market exclusivity windows, redirecting R&D investment toward pathogens the WHO classifies as urgent antimicrobial resistance threats.
Growth Catalysts
- Regulatory Acceleration Frameworks:The FDA's QIDP program grants novel antibiotics additional exclusivity periods, incentivizing sponsors to target multidrug-resistant organisms in necrotizing infections.
- Hospital Emergency Department Protocol Standardization:Trauma centers and burn units are implementing one-hour sepsis recognition mandates that drive mandatory empiric antibiotic initiation.
- Plasma Collection Network Expansion:Specialized immunoglobulin production capacity is scaling across North American and European collection infrastructure to address toxin-mediated streptococcal cases.
Market Restraints
- Plasma Supply Concentration:Immunoglobulin manufacturing depends on geographically concentrated donor collection networks, creating vulnerability to regional supply disruptions.
- Antimicrobial Stewardship Restrictions:Hospital formulary committees limit broad-spectrum antibiotic utilization through mandatory infectious disease consultation requirements.
- Surgical Resource Bottlenecks:Emergent debridement capacity concentrates in Level I trauma centers, restricting rural and community hospital access to definitive source control.
Strategic Opportunities
- Bacteriophage Adjunct Therapy:Polymicrobial infection management is opening to targeted pathogen elimination approaches that complement traditional broad-spectrum coverage.
- Rapid Molecular Diagnostic Integration:Pathogen identification timeline compression is enabling faster targeted therapy selection versus empiric protocols.
- Critical Care Telemedicine Networks:Hub-and-spoke consultation models are extending specialized necrotizing infection expertise to underserved hospital systems.
Industry Challenges
- Surgical-Pharmaceutical Coordination Complexity:Optimal outcomes require precise timing between antibiotic initiation, hemodynamic stabilization, and operative intervention across emergency medicine, critical care, and surgical teams.
- Reimbursement Policy Lag:Novel adjunctive therapies face coverage uncertainty as payers evaluate evidence frameworks for toxin-neutralizing modalities alongside standard surgical and pharmaceutical protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Necrotizing Skin Infections Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Immunoglobulins, Surgical Treatments Delivery Mode: Intravenous, Oral, Topical, Intra-arterial End User: Hospitals, Clinics, Home Care, Long-term Facilities Treatment Protocol: Empirical Therapy, Targeted Therapy, Combination Therapy, Supportive Care |
| Companies Covered | Pfizer, Merck & Co, GSK, Sanofi, AstraZeneca, Bayer, Takeda, CSL Behring, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Necrotizing Skin Infections Treatment Market Evolving Landscape
Treatment protocols are converging around combination approaches that layer bactericidal agents with toxin-neutralizing interventions, while diagnostic speed becomes the critical variable in shifting from empiric to targeted therapy selection.
Next-generation bacteriophage adjunct therapy is migrating from experimental protocols toward clinical integration in polymicrobial necrotizing infections. Academic medical centers with specialized infectious disease units are piloting phage banks matched to regional resistance patterns. This technology is compressing the timeline between pathogen identification and targeted elimination, reducing reliance on prolonged broad-spectrum exposure.
The EMA's priority medicines scheme is accelerating European access review timelines for novel anti-infectives targeting urgent antimicrobial resistance threats. Sponsors gain earlier scientific advice and accelerated assessment pathways, compressing development-to-access intervals. Hospital pharmacy and therapeutics committees across Germany, France, and Italy are pre-positioning formulary slots for designated priority medicines.
Combination therapy protocols are displacing monotherapy as the default clinical standard in hospital emergency departments and burn units. Clinicians are layering intravenous antibiotics with immunoglobulin preparations in severe streptococcal toxic shock syndrome, unbundling the pharmaceutical intervention from surgical source control. This pattern is most visible in United States trauma centers where sepsis bundle compliance mandates drive protocol standardization.
Necrotizing Skin Infections Treatment Market Segmentation
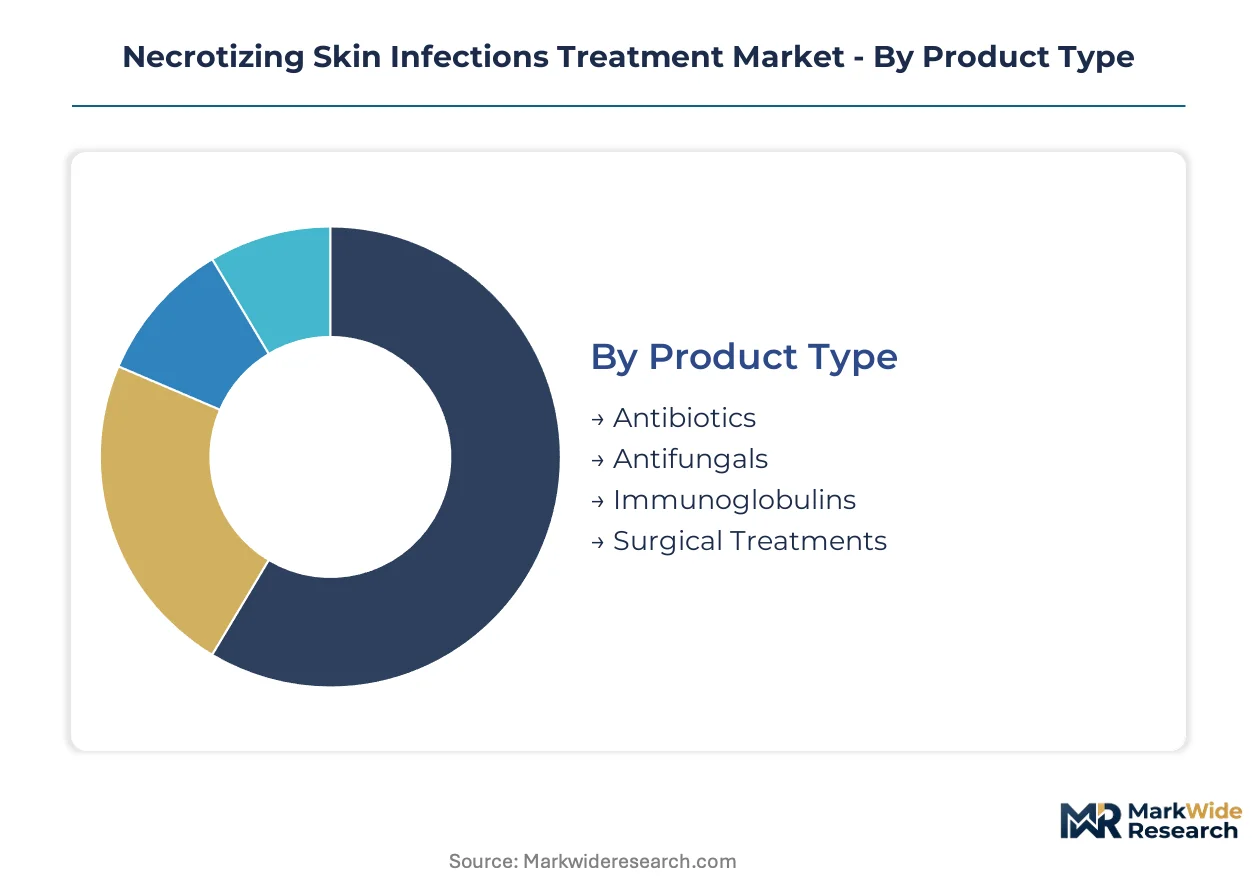
Treatment pathway complexity in necrotizing infections demands precise segmentation to match clinical urgency with appropriate intervention intensity. Each dimension—product chemistry, delivery route, care setting, and protocol logic—shapes how stakeholders allocate resources across the critical care continuum.
Product Type:
After-sales service intensity varies sharply across pharmaceutical versus surgical modalities, with biologics requiring cold-chain logistics and infusion support that antibiotics rarely need.
- Antibiotics:Intravenous broad-spectrum agents with minimum inhibitory concentration-guided dosing form the mandatory first-line intervention in hospital emergency departments. Demand concentrates in United States trauma centers where sepsis bundle compliance mandates drive empiric initiation within one hour of recognition, though antimicrobial stewardship programs constrain duration and spectrum selection.
- Immunoglobulins:Plasma-derived polyclonal antibodies neutralize streptococcal superantigens in toxic shock syndrome cases. Production depends on geographically concentrated donor collection networks across North America and Europe, creating supply vulnerability that shapes hospital inventory management and pre-positioning strategies.
- Antifungals:Lipid formulations of amphotericin B and echinocandins address Candida and Mucorales in immunocompromised hosts.
- Surgical Treatments:Emergent debridement instruments, negative pressure wound therapy systems, and reconstructive graft materials enable source control.
Antibiotics hold the largest share; momentum sits with immunoglobulins as toxin-mediated case recognition improves.
Delivery Mode:
Route selection tracks disease severity and pharmacokinetic requirements, with cost tier differentiation between hospital-based infusion and outpatient transition.
- Intravenous:Continuous or intermittent infusion of beta-lactams, glycopeptides, and lipopeptides achieves reliable tissue penetration in critically ill patients with capillary leak. United States burn units and Level I trauma centers anchor demand as these facilities manage the highest-acuity necrotizing fasciitis presentations requiring prolonged parenteral therapy.
- Oral:Bioavailability-limited agents serve step-down therapy after hemodynamic stabilization and source control. Adoption concentrates in long-term acute care hospitals where IV-to-oral transition reduces central line complications and accelerates discharge readiness.
- Topical:Antimicrobial dressings and negative pressure wound therapy deliver localized pharmacologic effect to open wounds.
- Intra-arterial:Regional perfusion techniques target limb-salvage scenarios in peripheral vascular compromise.
Intravenous dominates current volume; oral delivery is expanding most quickly as early discharge protocols mature.
End User:
Customer type determines reimbursement pathway and protocol standardization, with margin structure varying across facility-based versus distributed care.
- Hospitals:Emergency departments, intensive care units, and surgical services coordinate multidisciplinary response to necrotizing infections. United States academic medical centers with specialized infectious disease units pilot bacteriophage adjunct protocols and rapid molecular diagnostic integration that community hospitals cannot replicate.
- Clinics:Outpatient parenteral antimicrobial therapy programs manage stabilized patients requiring prolonged IV courses. Demand clusters in metropolitan areas with established infusion center networks and infectious disease specialist availability.
- Home Care:Skilled nursing services administer prolonged antibiotic regimens post-discharge.
- Long-term Facilities:Nursing homes and rehabilitation centers manage wound care transitions.
Hospitals capture the greatest value; home care is gaining share fastest as payers push site-of-service optimization.
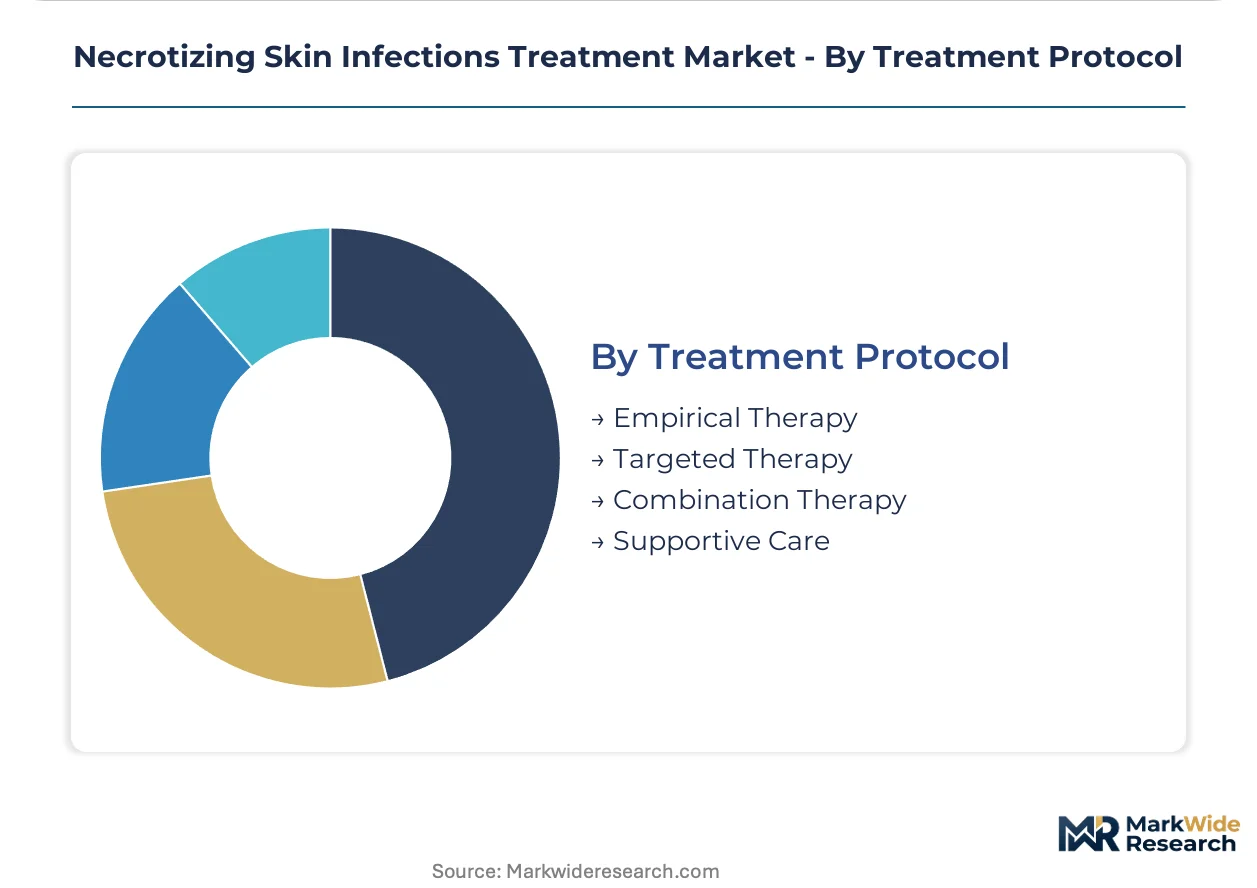
Treatment Protocol:
Protocol maturity reflects diagnostic speed and pathogen identification capability, with application logic shifting from empiric coverage toward precision targeting.
- Combination Therapy:Layering bactericidal antibiotics with immunoglobulins and surgical debridement addresses polymicrobial polymorbidity in severe presentations. United States trauma centers and burn units have standardized this approach through sepsis bundle mandates that require simultaneous antimicrobial, hemodynamic, and operative intervention.
- Targeted Therapy:Pathogen-specific selection follows rapid molecular diagnostic identification, reducing broad-spectrum exposure. Academic medical centers in Germany and France are integrating PCR-based resistance profiling into emergency department workflows, compressing the timeline from culture collection to tailored therapy.
- Empirical Therapy:Broad-spectrum coverage initiated before microbiologic confirmation remains standard in undifferentiated shock.
- Supportive Care:Vasopressor management, fluid resuscitation, and organ support parallel antimicrobial intervention.
Combination therapy commands current protocol share; targeted therapy shows the steepest expansion trajectory as diagnostic turnaround times collapse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized plasma-derived immunoglobulin therapies to trauma centers across the United States and Western Europe. This trade corridor reflects concentrated European biologics manufacturing capacity serving high-acuity hospital demand in North American critical care markets.
United States
Level I trauma centers in Houston, Baltimore, and Los Angeles anchor specialized necrotizing fasciitis treatment capacity with dedicated burn units and infectious disease units. The FDA's Qualified Infectious Disease Product designation accelerates novel antibiotic development through extended market exclusivity provisions. Academic medical centers in Boston and San Francisco pilot bacteriophage adjunct protocols matched to regional resistance patterns.
Germany
Plasma collection networks concentrated in Bavaria and North Rhine-Westphalia supply raw material for immunoglobulin manufacturing serving streptococcal toxic shock syndrome cases. The EMA's priority medicines scheme compresses development-to-access timelines for novel anti-infectives targeting urgent antimicrobial resistance threats. Frankfurt and Munich host specialized infectious disease units integrating rapid molecular diagnostics into emergency department workflows.
France
Hospital pharmacy and therapeutics committees in Paris and Lyon pre-position formulary slots for EMA-designated priority medicines in necrotizing infection management. ANSM regulates plasma-derived product quality standards for immunoglobulin therapies distributed through centralized hospital purchasing. The Île-de-France region concentrates academic research on polymicrobial infection pathophysiology and toxin-neutralizing modalities.
United Kingdom
London teaching hospitals coordinate national referral pathways for severe necrotizing fasciitis requiring emergent surgical debridement and critical care support. NHS England reimbursement policies shape adoption of combination therapy protocols layering antibiotics with immunoglobulins in toxic shock presentations. The Oxford-Cambridge-London biotech corridor hosts rapid diagnostic developers targeting pathogen identification timeline compression.
Japan
PMDA accelerated review pathways enable earlier market access for novel antibiotics addressing multidrug-resistant organisms in severe soft-tissue infections. Tokyo and Osaka academic medical centers specialize in limb-salvage surgical techniques for peripheral vascular compromise cases. METI industrial policy supports domestic plasma fractionation capacity to reduce import dependence for immunoglobulin therapies.
Necrotizing Skin Infections Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital formulary access and trauma center procurement networks. Antibiotic developers leverage FDA exclusivity incentives while plasma fractionators defend geographic collection advantages. Three archetypes dominate: diversified pharmaceutical conglomerates with anti-infectives infrastructure, specialized plasma-derived biologics manufacturers with vertical collection control, and rapid diagnostic developers enabling targeted therapy selection. Competitive moves concentrate on M&A to secure plasma collection assets and strategic partnerships to integrate molecular diagnostics with therapeutic protocols.
Among diversified pharmaceutical developers, Pfizer and Merck & Co occupy positions anchoring broad-spectrum antibiotic supply to hospital emergency departments. CSL Behring exemplifies the plasma-specialist archetype with concentrated immunoglobulin production capacity. Grifols represents vertical collection network control spanning multiple continents. These three entities collectively illustrate how market structure separates product-scale pharmaceutical distribution from biologics manufacturing dependent on donor plasma access.
| Leading Market Players |
|---|
| Pfizer |
| Merck & Co |
| GSK |
| Sanofi |
| AstraZeneca |
| Bayer |
| Takeda |
| CSL Behring |
| Grifols |
| Others |
Value Network & Pricing Analysis
Plasma collection networks concentrated in the United States and Germany anchor immunoglobulin manufacturing economics, directing margin pools toward fractionators with vertical control over donor infrastructure and cold-chain distribution to hospital burn units.
Pricing Analysis
Next-generation bacteriophage adjunct therapy commands premium positioning against established broad-spectrum antibiotics and generic IV formulations. Three-tier pricing structure across novel biologics, branded anti-infectives, and commoditized generics reflects FDA exclusivity status and manufacturing complexity. Pricing pressure stems from antimicrobial stewardship committees restricting empiric broad-spectrum utilization. Community hospitals exhibit highest price sensitivity due to formulary budget constraints, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Export-control regimes governing dual-use biotechnology constrain bacteriophage strain transfers between national phage banks. Plasma fractionation draws from concentrated US and European donor collection infrastructure, with Candida-active antifungals sourcing fermentation capacity from Ireland and Singapore. Single-source vulnerability concentrates in immunoglobulin feedstock supply. Distribution runs through specialized hospital pharmacy and therapeutics committees with formulary pre-positioning authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where rapid molecular diagnostic interoperability determines therapy selection speed, creating winner-take-most dynamics for integrated diagnostic-therapeutic protocols.
For Market Incumbents: Pre-empt bacteriophage therapy integration by securing regional phage bank partnerships before academic medical centers establish captive supply. Plasma fractionators must defend donor collection density against emerging precision-fermentation alternatives. Backward integration into rapid diagnostic development anchors formulary positioning against antibiotic commoditization. For New Entrants and Emerging Players: Mid-market community hospitals in underserved metropolitan regions represent the most penetrable entry point for telemedicine-enabled critical care consultation. Targeted rapid diagnostic deployment with 24-hour pathogen identification turnaround addresses surgical resource bottlenecks. Partnership with existing GPO contracts accelerates hospital system access without direct formulary committee navigation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across plasma-derived biologics manufacturing as donor collection infrastructure requires geographic expansion. Long-term viability favors fractionators with multi-continent collection networks and captive immunoglobulin production. Acquisition targets include rapid molecular diagnostic developers with FDA breakthrough device designation. Monitor EMA priority medicines scheme designations as early inflection signals for novel anti-infective commercial traction.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Vertical control over Bavaria and North Rhine-Westphalia donor infrastructure secures immunoglobulin feedstock against regional supply disruptions. |
| Rapid Molecular Diagnostic Integration | PCR-based resistance profiling in Frankfurt emergency departments compresses pathogen identification timelines enabling targeted therapy selection. |
| Bacteriophage Bank Development | Regional phage libraries matched to Houston and Baltimore resistance patterns accelerate adjunct therapy clinical adoption. |
| FDA QIDP Pathway Navigation | Extended exclusivity provisions for novel antibiotics targeting WHO urgent threat pathogens redirect R&D investment toward multidrug-resistant organisms. |
| Critical Care Telemedicine Deployment | Hub-and-spoke consultation models extend Level I trauma center expertise to rural emergency departments lacking surgical debridement capacity. |
Research Methodology
Desk research of FDA QIDP designations, EMA priority medicines submissions, and hospital formulary databases preceded structured interviews with infectious disease specialists, burn unit directors, plasma fractionation executives, and hospital procurement managers. Secondary validation drew from ClinicalTrials.gov entries, WHO antimicrobial resistance threat assessments, and GPO contract disclosure filings. Bottom-up demand modeling across treatment protocols triangulated against top-down pharmaceutical revenue estimates.
Assumptions held fixed include regulatory exclusivity period durations and sepsis bundle compliance mandates, while variables encompassed diagnostic adoption curves and phage therapy integration timelines. Segmentation dimensions modeled comprised product chemistry, delivery route, care setting acuity, and protocol logic across the analysis window. CAGR derivation incorporated minimum inhibitory concentration-guided dosing penetration and immunoglobulin inventory pre-positioning patterns.
Practitioners should monitor FDA breakthrough therapy designation grants and plasma donor collection volume reports for early signals of supply constraint or therapeutic innovation. Forecasts reflect assumptions about antimicrobial stewardship enforcement intensity and surgical capacity expansion rates. Cross-checking against CDC antimicrobial resistance surveillance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Anemia Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market