
 Global Von Willebrand Disease Treatment Market | 2026-2036
Global Von Willebrand Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Von Willebrand Disease Treatment Market Intelligence
The U.S. Food and Drug Administration's (FDA) Orphan Drug Act is repositioning the economic incentives for developing therapies for rare bleeding disorders. Takeda Pharmaceutical Company Limited leverages its extensive portfolio of plasma-derived and recombinant therapies. CSL Behring sustains its market presence through a focus on developing novel factor concentrates. Grifols, S.A. competes with a broad geographic footprint in plasma collection and manufacturing.
Von Willebrand Disease treatment involves therapies designed to replace or stimulate the release of deficient Von Willebrand Factor (VWF), a crucial blood-clotting protein. The primary purpose is to manage and prevent bleeding episodes in patients with this inherited coagulation disorder. Factor concentrates represent the core product segment due to their established efficacy in managing severe cases. The development of subcutaneous delivery modes challenges the dominance of traditional intravenous administration, offering improved patient convenience.
The European Medicines Agency (EMA) and Japan's Pharmaceuticals and Medical Devices Agency (PMDA) mandate stringent clinical trial data for marketing authorization, influencing development timelines. These regulations ensure product safety and efficacy, setting high barriers for new market entrants. Stakeholder success depends on navigating complex reimbursement landscapes and demonstrating clear clinical differentiation for new therapies.
Market Dynamics
The market's central dynamic is the shift towards patient-managed care, driven by innovations in subcutaneous delivery systems. This empowers patients with greater autonomy, moving routine treatment administration from clinical settings into the home and fundamentally altering service delivery models.
Growth Catalysts
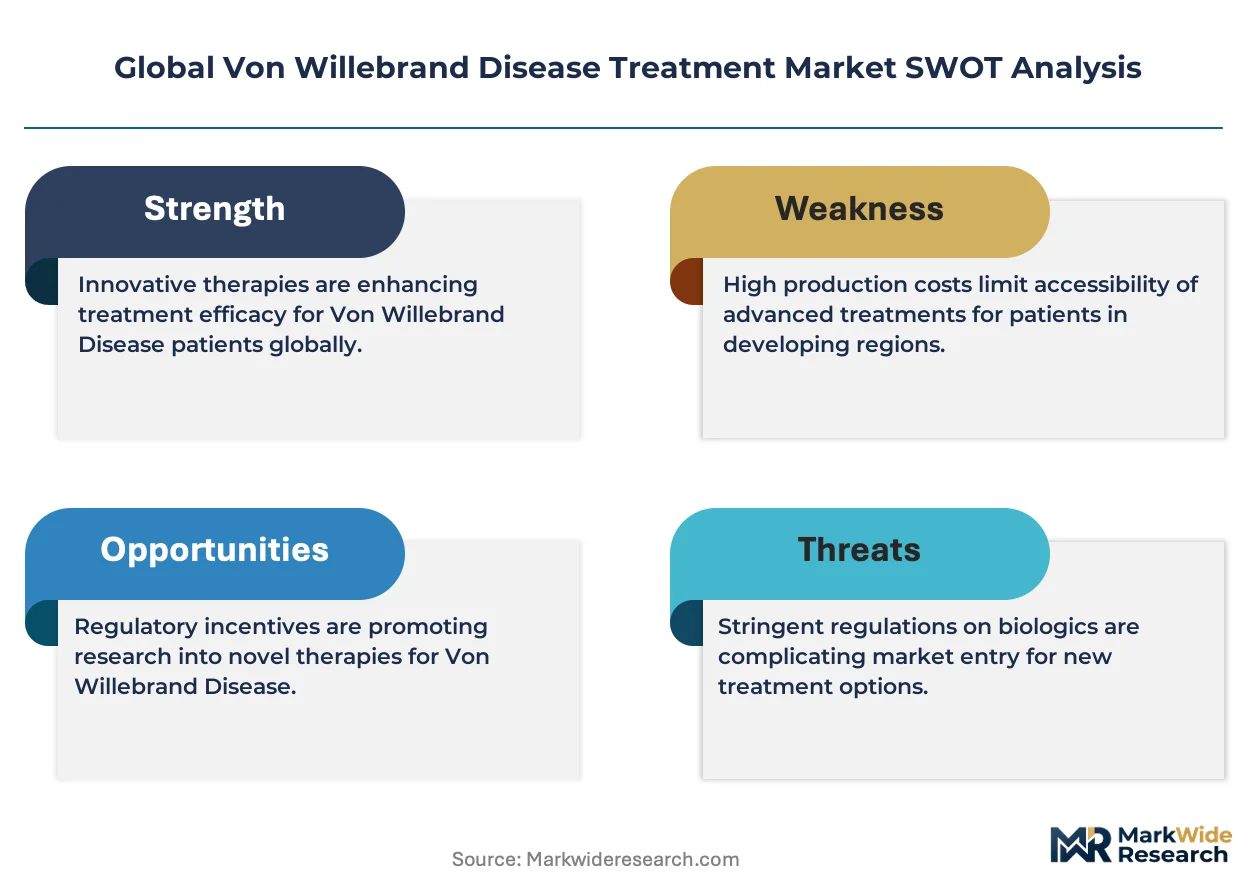
- Favorable Regulatory Frameworks:The U.S. Food and Drug Administration's Orphan Drug Act provides significant economic incentives, including tax credits and market exclusivity, which stimulate investment in developing therapies for rare conditions like Von Willebrand Disease.
- Novel Delivery Technologies:The development of subcutaneous administration methods offers a less invasive alternative to traditional intravenous infusions, improving patient convenience and adherence to prophylactic treatment regimens, especially within homecare.
- Expanding Diagnostic Infrastructure:Increased access to advanced molecular and functional assays in developed countries like the United States and Germany enhances accurate diagnosis, expanding the identifiable patient population requiring treatment.
Market Restraints
- High Treatment Costs:The manufacturing of plasma-derived factor concentrates is a complex and costly process, involving extensive screening and purification, which translates to high therapy costs that can limit access in markets with less comprehensive reimbursement.
- Stringent Regulatory Hurdles:Regulatory bodies such as the European Medicines Agency and Japan's PMDA impose rigorous clinical trial requirements for marketing authorization, leading to long and expensive development timelines that act as a barrier for new entrants.
- Dominance of Intravenous Therapy:For managing severe, acute bleeding episodes, intravenous administration of factor concentrates remains the standard of care due to its rapid action, slowing the full displacement by newer subcutaneous options in critical care.
Strategic Opportunities
- Gene Therapy Development:Long-term research into gene therapies presents a significant opportunity to develop a curative treatment for Von Willebrand Disease, moving beyond the current paradigm of managing symptoms and bleeding episodes.
- Emerging Market Penetration:There is an opportunity to expand into geographies with improving healthcare infrastructure, such as Brazil and Mexico, by introducing established therapies and supporting the development of local diagnostic capabilities.
- Digital Health Integration:Developing mobile applications and telehealth platforms to support homecare patients with treatment tracking, adherence reminders, and virtual consultations represents a key area for service differentiation and value creation.
Industry Challenges
- Plasma Supply Chain Volatility:Therapies dependent on human plasma face the challenge of maintaining a consistent and safe supply, which is subject to fluctuations in donations and requires a sophisticated, highly regulated collection and processing network.
- Complex Reimbursement Navigation:Manufacturers face the operational challenge of securing favorable reimbursement status across diverse national and private payer systems, each with unique evidence requirements for clinical and economic value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Von Willebrand Disease Treatment Market |
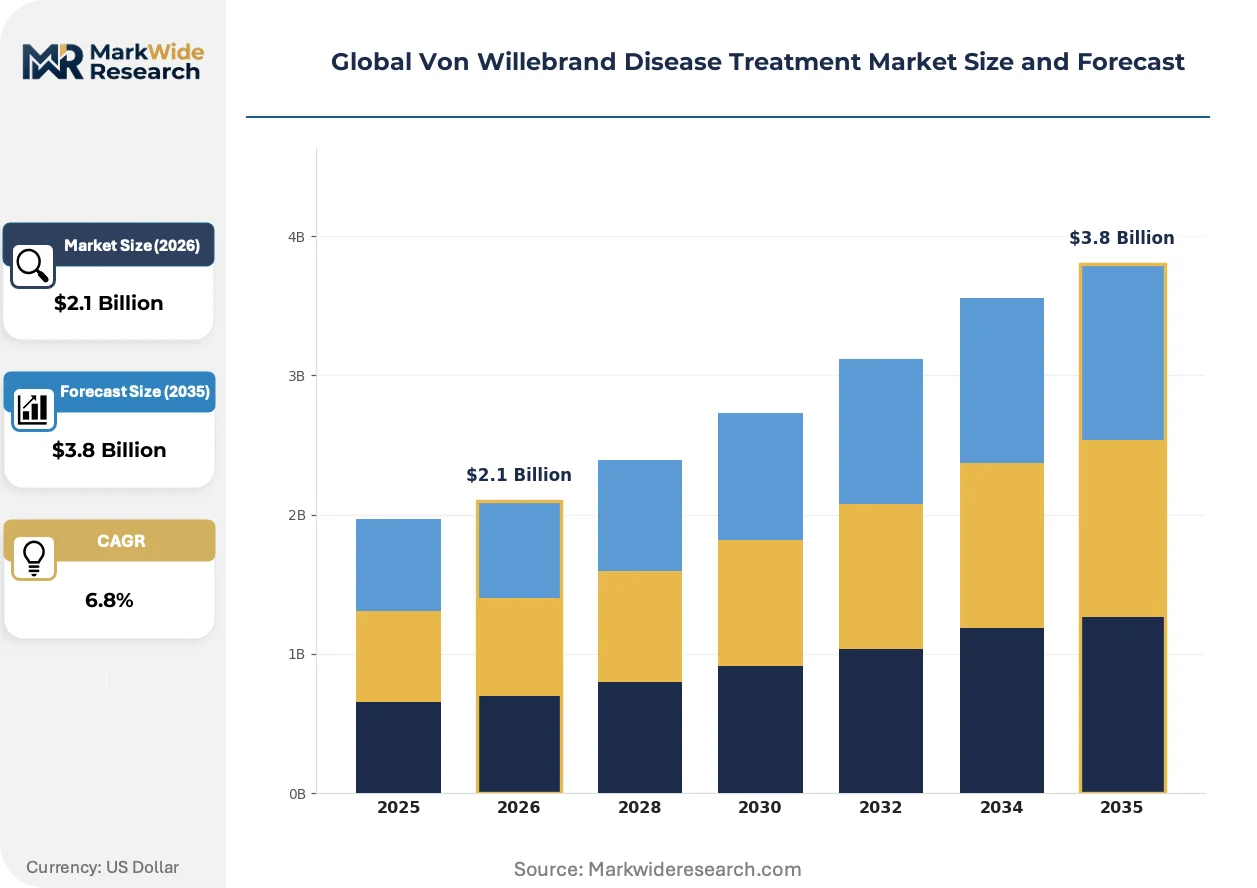
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desmopressin, Factor Concentrates, Antifibrinolytics, Others Delivery Mode: Intravenous, Subcutaneous, Oral, Others End User: Hospitals, Clinics, Homecare, Ambulatory Surgery Centers Therapy Area: Hemophilia, Bleeding Disorders, Preventive Care, Others |
| Companies Covered | CSL Behring, Octapharma AG, Grifols, S.A., Takeda Pharmaceutical Company Limited, Novo Nordisk A/S, Bayer AG, Pfizer, Inc., Bio Products Laboratory Limited, Kedrion S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Von Willebrand Disease Treatment Market Strategic Shifts & Innovations
The therapeutic landscape for Von Willebrand Disease is being redefined by a focus on patient convenience and treatment personalization. This evolution prioritizes reducing the burden of care through innovations in drug delivery and more targeted biological therapies that address specific VWF deficiencies.
Subcutaneous delivery systems for factor concentrates represent a major product evolution. Patients in homecare settings are increasingly adopting these less invasive methods for routine prophylactic care. This migration away from clinician-administered intravenous infusions is electrifying the patient experience by enhancing personal autonomy and improving long-term adherence to treatment schedules.
In the European Union, the European Medicines Agency's (EMA) mandate for robust clinical data for rare disease therapies influences development strategy. This regulation forces developers to conduct extensive trials demonstrating not just safety but a clear clinical advantage over existing treatments. The recombinant product segment is particularly affected, as companies must justify premium pricing with superior efficacy or patient-reported outcomes to gain market access.
A clear behavioral change is the decentralization of disease management from specialized treatment centers to patient homes. This disrupts the established hospital-based distribution chain, spurring demand for integrated homecare services, including patient training, telehealth support, and direct-to-patient delivery of therapies. This shift is most advanced in the United States, where it is supported by established home healthcare providers and favorable insurance coverage for self-administration.
Global Von Willebrand Disease Treatment Market Segmentation
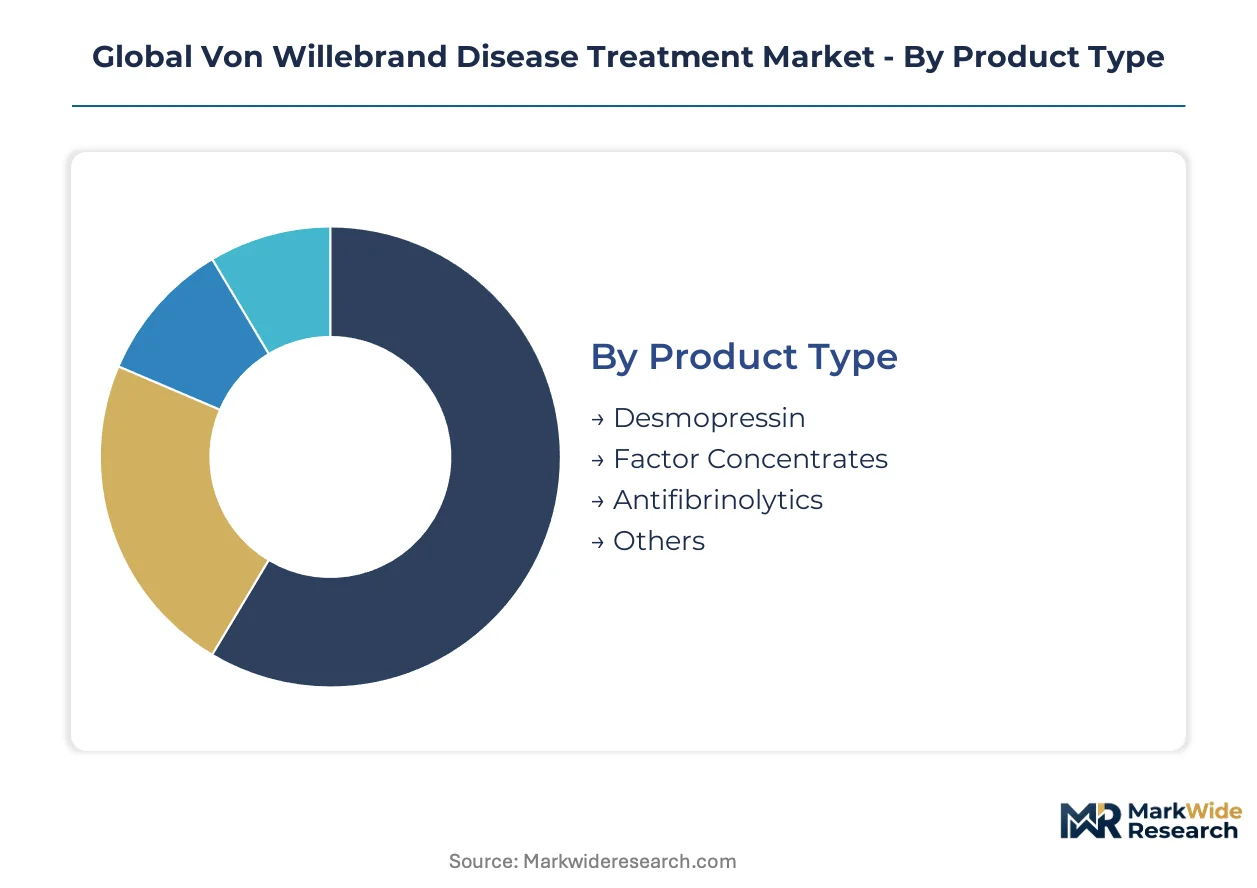
The Global Von Willebrand Disease Treatment Market segmentation clarifies the diverse approaches to managing this inherited bleeding disorder. Different product types and delivery methods address varying patient needs and disease severities. Understanding these distinctions is critical for optimizing treatment strategies and market penetration across healthcare settings.
Product Type:
The market's product offerings range from standardized pharmaceutical agents to highly customized factor replacement therapies.
- Factor Concentrates:These products contain purified Von Willebrand Factor and Factor VIII, derived from human plasma or produced recombinantly. They are primarily utilized for severe Von Willebrand Disease types or acute bleeding episodes, with demand concentrating in the United States due to established reimbursement pathways.
- Desmopressin:This synthetic analog of vasopressin stimulates the release of endogenous VWF from endothelial cells, suitable for patients with Type 1 VWD. Its widespread use in Europe reflects its efficacy for milder forms of the disorder and lower cost compared to factor concentrates.
- Antifibrinolytics:These medications, such as tranexamic acid, prevent the breakdown of blood clots, often used as adjunctive therapy for mucosal bleeding.
- Others:This category encompasses emerging therapies and supportive care products, including topical hemostatic agents.
Most installed capacity flows through Factor Concentrates. Expansion is steepest in Desmopressin.
Delivery Mode:
Treatment administration methods are evolving, driven by patient convenience and the severity of clinical application.
- Subcutaneous:This delivery route involves injecting medication under the skin, offering improved patient convenience and supporting home-based prophylactic treatment regimens. Demand for subcutaneous options is increasing in Germany, driven by patient preference for self-administration.
- Intravenous:This traditional method involves direct infusion into a vein, providing rapid systemic delivery of therapeutic agents. Intravenous administration remains the standard for managing acute bleeding episodes in hospital settings across Japan.
- Oral:Oral medications are typically reserved for adjunctive therapies or milder symptoms, offering ease of use for long-term management.
- Others:This segment includes intranasal sprays and other non-standard delivery methods, often for specific patient populations.
The largest volume of treatments utilizes Intravenous delivery. New patient adoption is highest for Subcutaneous options.
End User:
The settings where Von Willebrand Disease treatments are administered reflect the disease's varied presentation and management requirements.
- Homecare:This segment involves patients self-administering treatments in their homes, supported by telehealth and specialized nursing services. The shift towards homecare is pronounced in the United States, driven by convenience and patient autonomy.
- Hospitals:Hospitals serve as primary sites for initial diagnosis, severe bleeding management, and complex surgical interventions requiring intensive factor replacement. Hospitals in France maintain high patient volumes for acute care.
- Clinics:Specialized hematology clinics provide ongoing patient monitoring, routine prophylactic care, and patient education.
- Ambulatory Surgery Centers:These facilities handle minor surgical procedures for patients with VWD, requiring pre-operative factor administration.
The predominant treatment delivery occurs in Hospitals. Growth in patient access is most pronounced within Homecare.
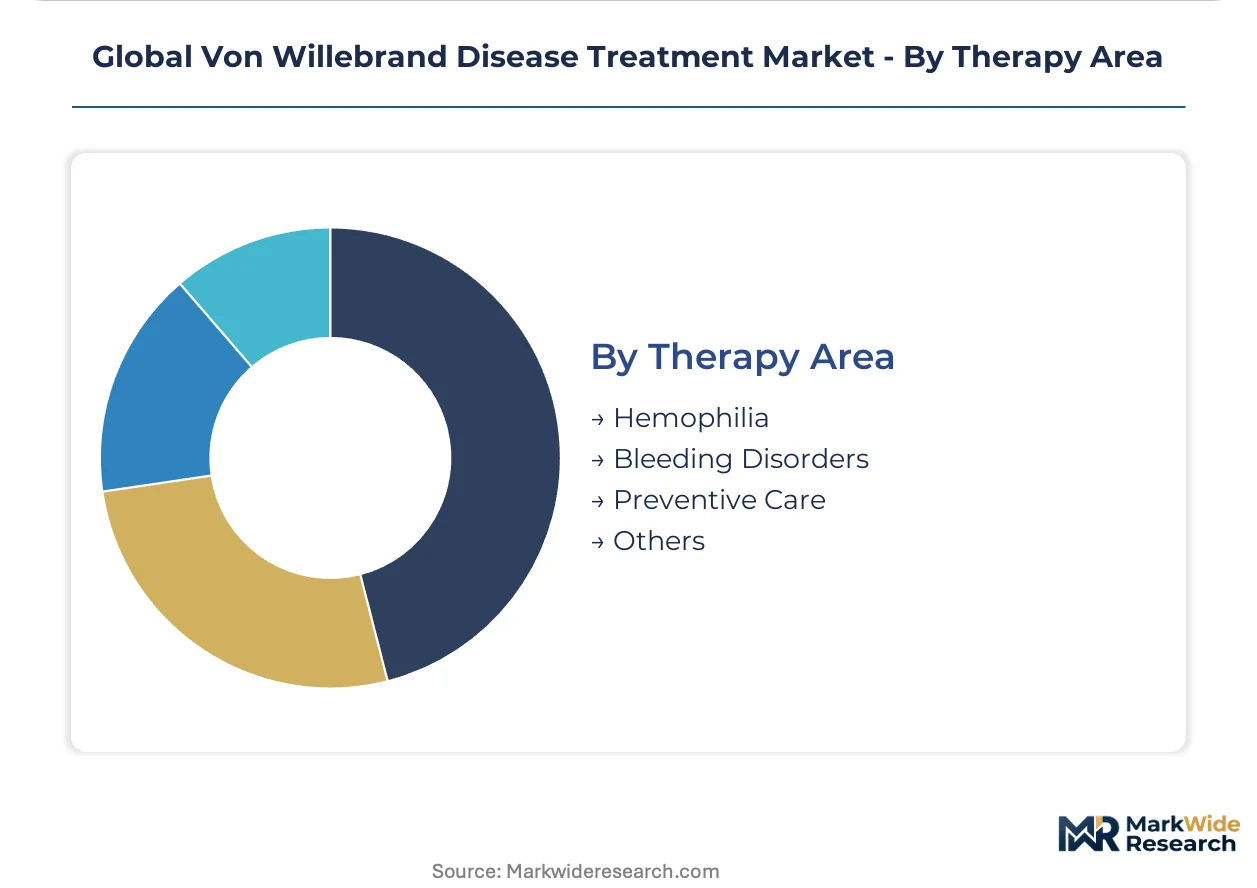
Therapy Area:
Von Willebrand Disease treatments span various therapeutic applications, from managing immediate bleeding to long-term preventive strategies.
- Bleeding Disorders:This core area focuses on treating active bleeding episodes, including surgical bleeding, trauma-induced hemorrhages, and spontaneous bleeding. This remains the largest application area across all geographies.
- Preventive Care:Prophylactic treatment aims to prevent bleeding episodes, particularly in patients with severe VWD, significantly improving quality of life. The adoption of preventive care is expanding in Canada, emphasizing long-term health outcomes.
- Hemophilia:While distinct, some treatments for VWD, particularly Factor VIII-containing concentrates, overlap with hemophilia management.
- Others:This category includes treatments for related coagulopathies or specific patient populations with unique needs.
The largest segment addresses Bleeding Disorders. Prophylactic applications are expanding most quickly in Preventive Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Von Willebrand Disease treatment market initially scaled in regions with advanced healthcare infrastructure and diagnostic capabilities. Early adoption of factor replacement therapies and robust research into bleeding disorders first established strong market foundations in North America and Western Europe. These regions continue to drive innovation and demand for advanced treatment modalities.
United States
Demand in the United States is driven by advanced diagnostic infrastructure and favorable reimbursement policies. The FDA's Orphan Drug Act provides significant economic incentives, stimulating investment in rare disease therapies. Established home healthcare providers and insurance coverage for self-administration support the shift towards patient-managed care in major metropolitan areas.
Germany
Germany exhibits strong demand for subcutaneous delivery options, reflecting patient preference for self-administration and expanding diagnostic capabilities. European Medicines Agency (EMA) regulations ensure product safety and efficacy, influencing development strategies across the region. Demand for innovative delivery methods concentrates in urban centers with robust homecare support networks.
Japan
The Japanese market maintains intravenous administration as the standard for managing acute bleeding episodes due to its rapid action. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) mandates stringent clinical trial data for marketing authorization, setting high barriers for new market entrants. Hospitals across major cities, such as Tokyo and Osaka, remain central for acute care delivery.
Canada
Preventive care applications are expanding quickly in Canada, driven by an emphasis on improving long-term health outcomes for patients. Health Canada oversees the approval and market access for new therapies, ensuring their safety and efficacy for the Canadian population. Prophylactic treatment adoption is growing in provinces like Ontario and Quebec, supported by public healthcare systems.
France
Hospitals in France maintain high patient volumes for acute care and initial diagnosis of Von Willebrand Disease. The European Medicines Agency (EMA) regulations directly impact market access and product development timelines within the country. Major medical centers in cities like Paris and Lyon serve as key hubs for intensive factor replacement and complex surgical interventions.
Global Von Willebrand Disease Treatment Market Key Industry Players
The competitive structure tilts toward moderately consolidated, with established pharmaceutical companies holding significant market share through diverse portfolios. This market features a mix of established plasma fractionators, biopharmaceutical innovators, and niche therapy developers. Dominant competitive moves include portfolio diversification, encompassing both plasma-derived and recombinant therapies, and strategic investments in novel delivery technologies.
Among the established biopharmaceutical companies, Takeda Pharmaceutical Company Limited exemplifies a broad portfolio approach, leveraging its extensive range of plasma-derived and recombinant therapies. CSL Behring represents a focused strategy on developing novel factor concentrates, sustaining its market presence through continuous innovation. Grifols, S.A. anchors the vertically integrated plasma collection and manufacturing segment, utilizing its broad geographic footprint to compete effectively.
| Leading Market Players |
|---|
| CSL Behring |
| Octapharma AG |
| Grifols, S.A. |
| Takeda Pharmaceutical Company Limited |
| Novo Nordisk A/S |
| Bayer AG |
| Pfizer, Inc. |
| Bio Products Laboratory Limited |
| Kedrion S.p.A. |
| Others |
Cost & Logistics Intelligence
Ethical plasma sourcing guidelines, ensuring donor safety and product integrity, gate access to qualified raw material supply. These mandates directly influence premium-tier pricing for plasma-derived therapies.
Pricing Analysis
Contract-based pricing agreements define the market for Von Willebrand Disease treatments. Price differentiation arises from product origin, distinguishing between plasma-derived and recombinant therapies, alongside the level of patient support services. Pricing pressure stems from payer negotiations seeking cost-effectiveness for long-term prophylactic care. Patients in markets with less comprehensive reimbursement exhibit higher price sensitivity compared to those in well-insured regions.
Supply Chain Analysis
Skilled workforce availability in key manufacturing geographies like the United States and Germany impacts the production of advanced VWF therapies. The supply chain draws from human plasma and specialized recombinant protein production facilities. Plasma supply chain volatility represents a structural risk, influenced by donor recruitment and processing capacity. Distribution runs through a hybrid model, combining direct-to-patient homecare services with established hospital and clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Von Willebrand Disease treatment market operates as a regulatory compounder, with the U.S. FDA's Orphan Drug Act significantly driving investment and demand. This framework provides economic incentives that stimulate therapy development.
For Market Incumbents: Anchor existing market share by diversifying portfolios across plasma-derived and recombinant VWF therapies. Invest strategically in gene therapy research to counter the long-term threat of curative treatments. Reinforce channel control by forging partnerships with homecare providers to support decentralized patient management. Maintain high certification standards to navigate stringent regulatory hurdles in Europe and Japan.
For New Entrants and Emerging Players: Telehealth platforms offer a strategic entry point for new players, supporting homecare patients with adherence tracking and virtual consultations. Target emerging markets like Brazil and Mexico by focusing on establishing local diagnostic capabilities and introducing established therapies. Prioritize development of cost-effective subcutaneous delivery options for Type 1 VWD patients seeking greater convenience. Leverage digital health integration to differentiate service offerings and build patient loyalty.
For Investors and Strategic Acquirers: Roll-up economics work for specialized rare disease biopharmaceutical firms because high regulatory barriers and established reimbursement pathways ensure long-term value. Target innovators developing gene therapies or advanced subcutaneous delivery systems. Focus on companies with strong intellectual property portfolios and demonstrated clinical differentiation. The signal to watch is successful Phase 3 trial readouts for curative or significantly improved treatment modalities.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Advancing clinical trials for gene therapies will redefine long-term disease management. |
| Regulatory Approval Pathway | Navigating EMA and PMDA approval pathways secures market access in key European and Asian regions. |
| Manufacturing Scale-Up | Scaling up recombinant factor concentrate production ensures supply stability against plasma volatility. |
| Licensing Agreement | Securing licensing agreements for novel subcutaneous delivery systems enhances patient convenience. |
| Pipeline Diversification | Diversifying the product pipeline with adjunctive therapies addresses unmet patient needs. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This involved interviews with hematologists, R&D executives, regulatory affairs specialists, and homecare providers. Secondary validation utilized FDA filings, EMA submissions, ClinicalTrials.gov, and national health agency reports. Bottom-up market sizing was triangulated with top-down validation to ensure data integrity.
Market modeling analyzed granularity across product type, delivery mode, end user, therapy area, and patient severity over the projection horizon. Compound annual growth rates were derived from historical market data and projected new product introductions. Key forecast inputs included patient population demographics, novel therapy approvals by the FDA, and evolving national reimbursement policies.
The model assumes a particular technology adoption path for subcutaneous therapies; alternative pathways for gene therapy development would alter the outlook. Forecasts reflect current regulatory landscapes and anticipated market entry timelines. Material deviation in key triggers like major clinical trial failures or plasma supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Nontuberculous Mycobacterium Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market