
 Radiation-Induced Myelosuppression Treatment Market | 2026-2036
Radiation-Induced Myelosuppression Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation-Induced Myelosuppression Treatment Market Analytics
Next-generation recombinant cytokine formulations is reorganizing competitive dynamics across the radiation-induced myelosuppression landscape. Amgen Inc. leverages decades of granulocyte colony-stimulating factor expertise to anchor premium positioning in hospital infusion centers. Pfizer Inc. competes through integrated oncology portfolios that bundle myelosuppression prophylaxis with cytotoxic regimens. Novartis AG differentiates via sustained investment in biosimilar pathways that broaden access across European and Asian markets.
Radiation-induced myelosuppression describes the pathological suppression of bone marrow hematopoietic activity following ionizing radiation exposure, clinically manifesting as neutropenia, thrombocytopenia, and anemia with nadir counts typically occurring 7–14 days post-exposure. Recombinant human granulocyte colony-stimulating factors such as filgrastim and pegfilgrastim remain the pharmacological cornerstone, administered subcutaneously to accelerate neutrophil recovery and reduce infection risk during curative or palliative radiotherapy. Growth factors command the dominant revenue share within product type segmentation, driven by established ASCO and ESMO guideline incorporation and predictable reimbursement in tertiary care settings. Subcutaneous administration routes are gaining fastest volume expansion, reflecting the shift toward outpatient oncology models and patient preference for reduced clinic time.
FDA oncology center of excellence reviews and EMA's committee for medicinal products for human use shape development priorities through iterative scientific advice on hematopoietic support endpoints. The IRA's Medicare price negotiation provisions and EU joint clinical assessment processes under HTA coordination will increasingly determine commercial viability for new myelosuppression agents. Stakeholders must monitor evolving radiotherapy fractionation protocols and corresponding cytokine prophylaxis duration requirements to align pipeline investments with clinical practice trajectories.
Market Dynamics
Prophylactic growth factor protocols are displacing reactive treatment models across curative radiotherapy settings, compressing hospitalization windows and redistributing economic value toward outpatient cytokine administration.
Growth Catalysts
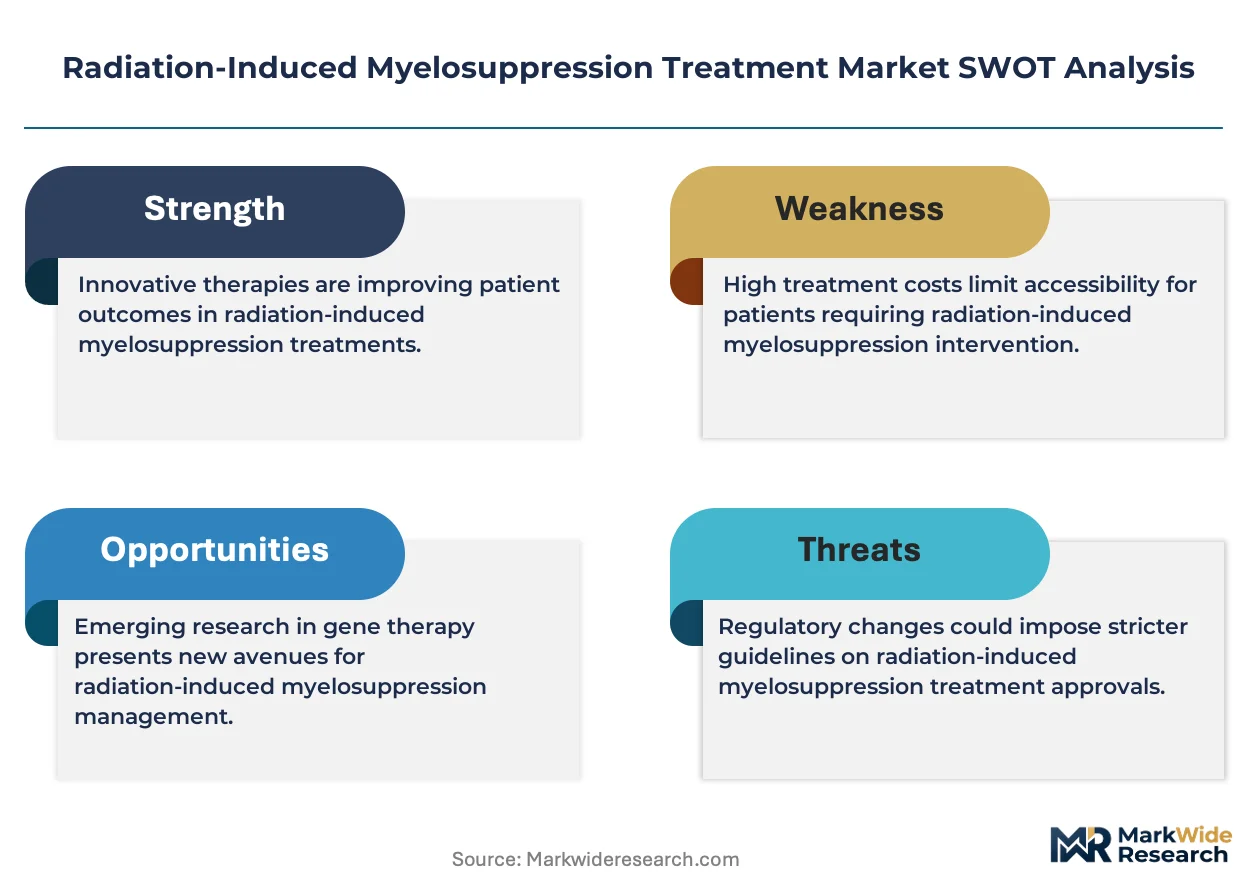
- IRA Medicare Price Negotiation:The Inflation Reduction Act's provisions for supportive care biologics create reimbursement clarity that accelerates hospital formulary adoption of myelosuppression prophylaxis in United States oncology centers.
- ASCO Guideline Incorporation:American Society of Clinical Oncology recommendations for granulocyte colony-stimulating factor use in radiation oncology standardize prescribing behavior across academic medical centers.
- Aging Cancer Populations:Demographic shifts in Germany and Japan expand the addressable patient pool for hematopoietic support agents ahead of fractionated radiotherapy regimens.
Market Restraints
- Biosimilar Price Compression:European Medicines Agency accelerated pathways for filgrastim biosimilars erode originator pricing power and compress revenue per treated patient across EU5 markets.
- Subcutaneous Administration Training:Home-based cytokine delivery requires specialized nursing infrastructure that remains unevenly distributed across rural United States health systems.
- Neutropenia Duration Variability:Heterogeneous radiotherapy fractionation schedules complicate standardized prophylaxis duration protocols and create dosing uncertainty.
Strategic Opportunities
- EMA Joint Clinical Assessment:EU HTA coordination processes under the European Health Data Space framework create harmonized market access pathways for novel hematopoietic support agents.
- Extended-Release Formulations:Pegylated cytokine variants reduce injection frequency and align with patient preference for reduced clinic burden in outpatient oncology models.
- India CDSCO Accelerated Review:India's pharmaceutical regulator offers priority review pathways for supportive care biologics that address unmet need in radiation oncology.
Industry Challenges
- Cold Chain Integrity:Temperature-sensitive biologic distribution requires specialized logistics infrastructure that strains regional pharmacy capabilities during peak demand periods.
- Interoperable EHR Integration:Neutrophil count tracking across radiation oncology and pharmacy information systems demands health IT capital investment that delays protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation-Induced Myelosuppression Treatment Market |
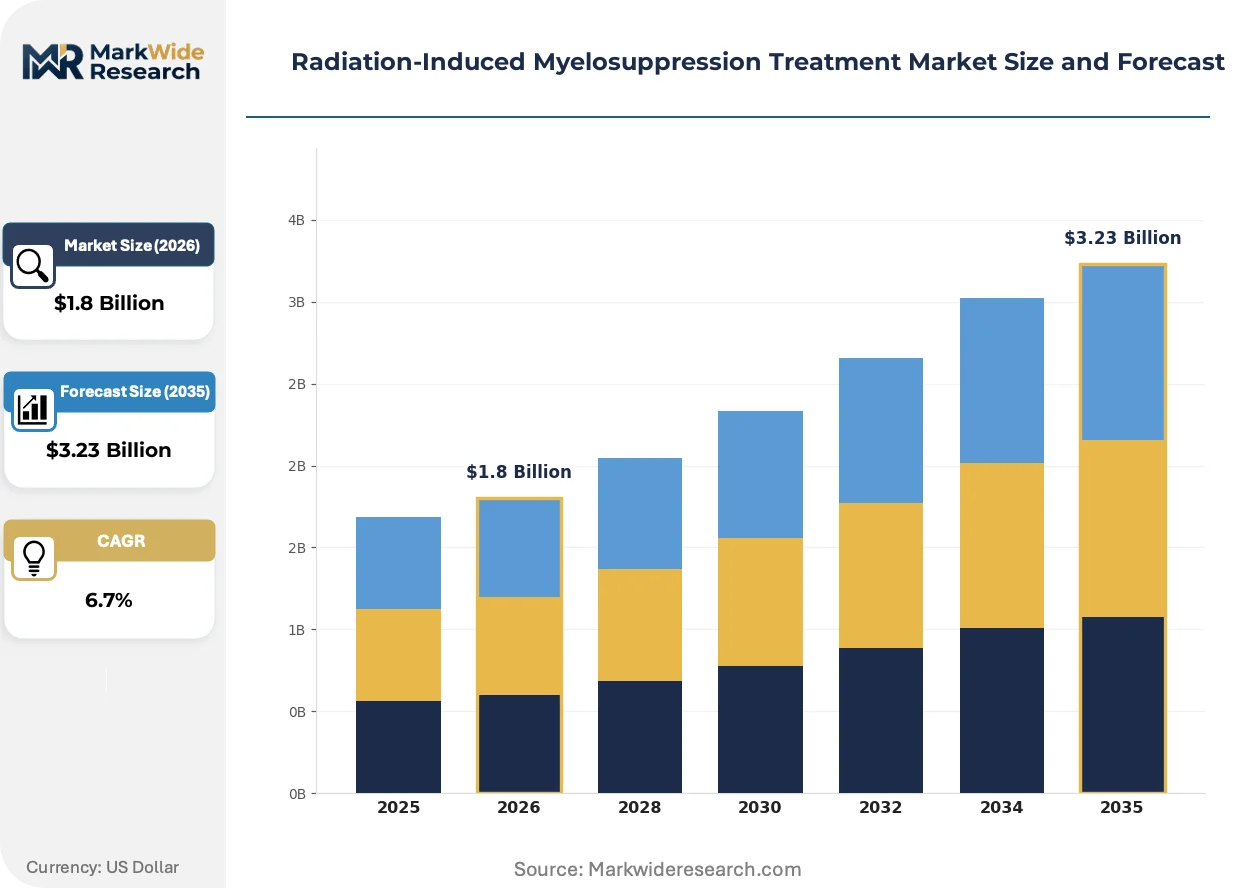
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Factors, Cytokines, Antineoplastic Agents, Immunosuppressants Administration Route: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Formulation: Injectable, Oral Tablets, Oral Capsules, Lyophilized Products |
| Companies Covered | Amgen Inc., Janssen Global Services, LLC (Johnson & Johnson), Teva Pharmaceutical Industries Ltd., Pfizer Inc., Novartis AG, Mylan N.V., Partner Therapeutics, Inc., Myelo Therapeutics GmbH, Pluristem Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation-Induced Myelosuppression Treatment Market Evolving Landscape
Next-generation cytokine engineering and regulatory science convergence are compressing development timelines while fragmenting historical competitive moats around established growth factor franchises.
Biosimilar development programs are fragmenting the historical concentration of granulocyte colony-stimulating factor supply across European and Asian manufacturing networks. Contract development organizations in South Korea and India are scaling mammalian cell culture capacity to serve abbreviated licensure pathways. This manufacturing diffusion is eroding the pricing premiums that originator molecules commanded in tertiary care infusion centers.
EMA's committee for medicinal products for human use has issued iterative scientific advice on hematopoietic recovery endpoints that reshape Phase III trial designs for radiation-induced myelosuppression candidates. The guidance prioritizes time-to-neutrophil recovery over traditional survival endpoints, shortening regulatory review cycles. Oncology sponsors are responding by embedding biomarker stratification into adaptive trial protocols across Germany, France, and Italy.
Hospital procurement committees are consolidating vendor relationships for supportive care biologics into bundled oncology contracts that span cytotoxic agents and hematopoietic growth factors. This purchasing consolidation displaces standalone cytokine negotiations and compresses supplier margins. The shift is most pronounced in United States integrated delivery networks and German hospital federations seeking formulary simplification.
Radiation-Induced Myelosuppression Treatment Market Segmentation
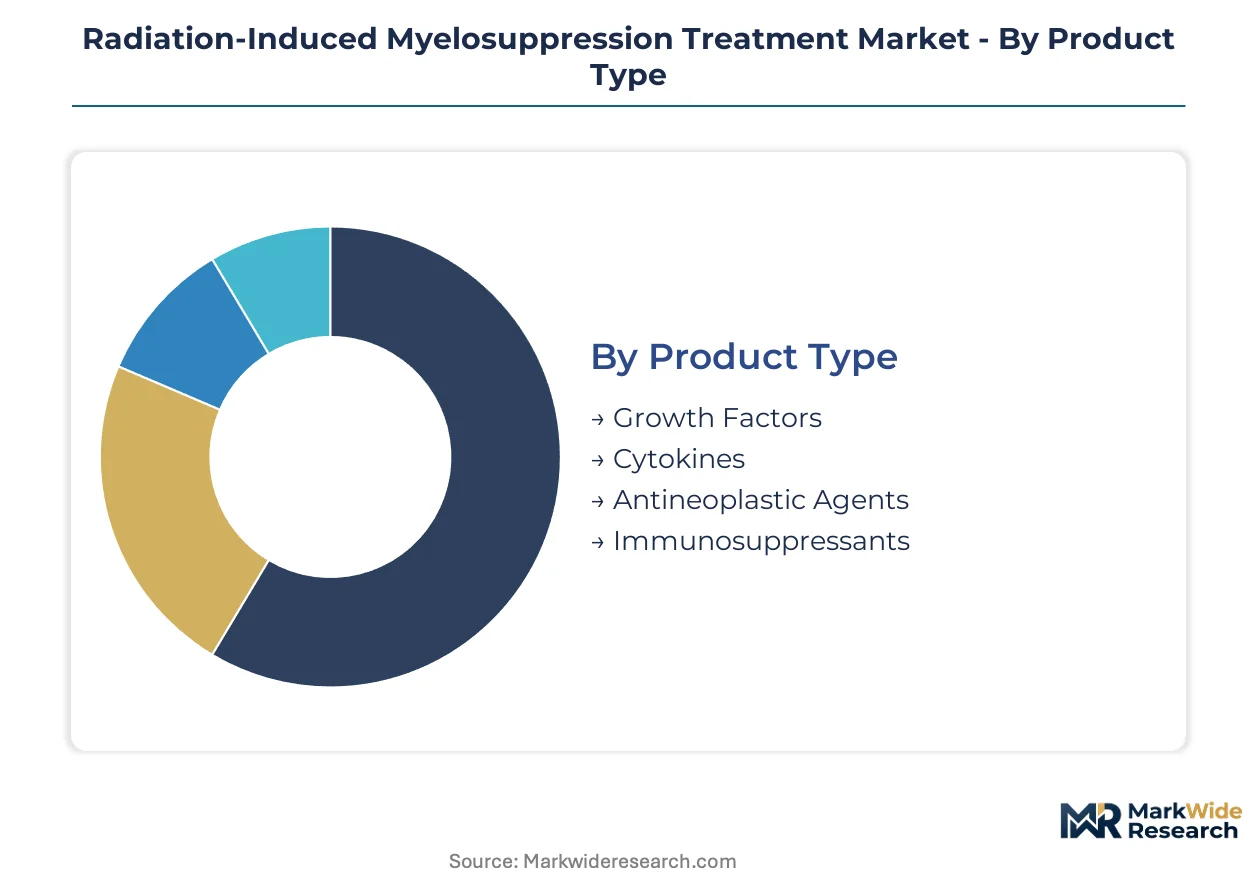
Segmentation in radiation-induced myelosuppression treatment reveals how therapeutic modalities, delivery mechanisms, and care settings allocate value across the patient journey. Distinct formulation and administration preferences shape procurement patterns in tertiary centers versus outpatient environments.
Product Type:
Demand concentrates in markets with established reimbursement for biologic supportive care, while emerging economies gravitate toward synthetic alternatives with simpler cold-chain requirements.
- Growth Factors:Recombinant human granulocyte colony-stimulating factors such as filgrastim and pegfilgrastim accelerate neutrophil recovery following radiotherapy. United States oncology centers drive volume through ASCO-guided prophylaxis protocols in curative radiotherapy settings.
- Cytokines:Interleukin-based therapies and thrombopoietin mimetics address platelet recovery in combined modality treatment. German hospital federations prioritize these agents for fractionated regimens in aging cancer populations.
- Antineoplastic Agents:Cytoprotective compounds including amifostine derivatives scavenge free radicals in radiation-exposed bone marrow.
- Immunosuppressants:Corticosteroid and calcineurin inhibitor combinations manage inflammatory complications of severe myelosuppression.
Growth factors command the established base. The steepest expansion runs through cytokines.
Administration Route:
Route selection reflects the tension between clinical efficacy requirements and patient preference for reduced facility dependence, with cost tier differentiation across inpatient and outpatient reimbursement bands.
- Subcutaneous:Self-administered cytokine injections reduce clinic burden and align with outpatient oncology models. Japanese health systems favor this route for elderly patients receiving palliative radiotherapy.
- Intravenous:Hospital-based infusion ensures bioavailability for high-dose growth factor protocols. United States academic medical centers maintain this route for curative regimens requiring dose-intense support.
- Oral:Small-molecule immunomodulators offer convenience in resource-limited settings with inconsistent nursing infrastructure.
- Topical:Localized delivery systems address mucositis-associated neutropenia risk in head and neck radiotherapy.
Intravenous delivery retains the revenue concentration. Subcutaneous administration gains share fastest.
End User:
Customer type segmentation tracks the decentralization of cancer care from inpatient wards toward ambulatory and home-based models, with reimbursement parity determining site-of-service economics.
- Hospitals:Tertiary oncology centers manage complex myelosuppression in combined chemoradiotherapy. Germany's university hospitals anchor demand through integrated supportive care pathways.
- Homecare Settings:Subcutaneous growth factor administration shifts economic value toward specialty pharmacy and nursing services. United States integrated delivery networks expand these programs for Medicare Advantage populations.
- Specialty Clinics:Freestanding radiation oncology centers focus on prophylactic protocols for curative intent treatment.
- Research Institutions:Phase I-II trial sites evaluate next-generation cytokine engineering in radiation sensitization studies.
Hospitals anchor current utilization. Homecare settings climb the fastest.
Formulation:
Formulation maturity correlates with manufacturing complexity, where lyophilized and extended-release variants command premium positioning against immediate-release standards.
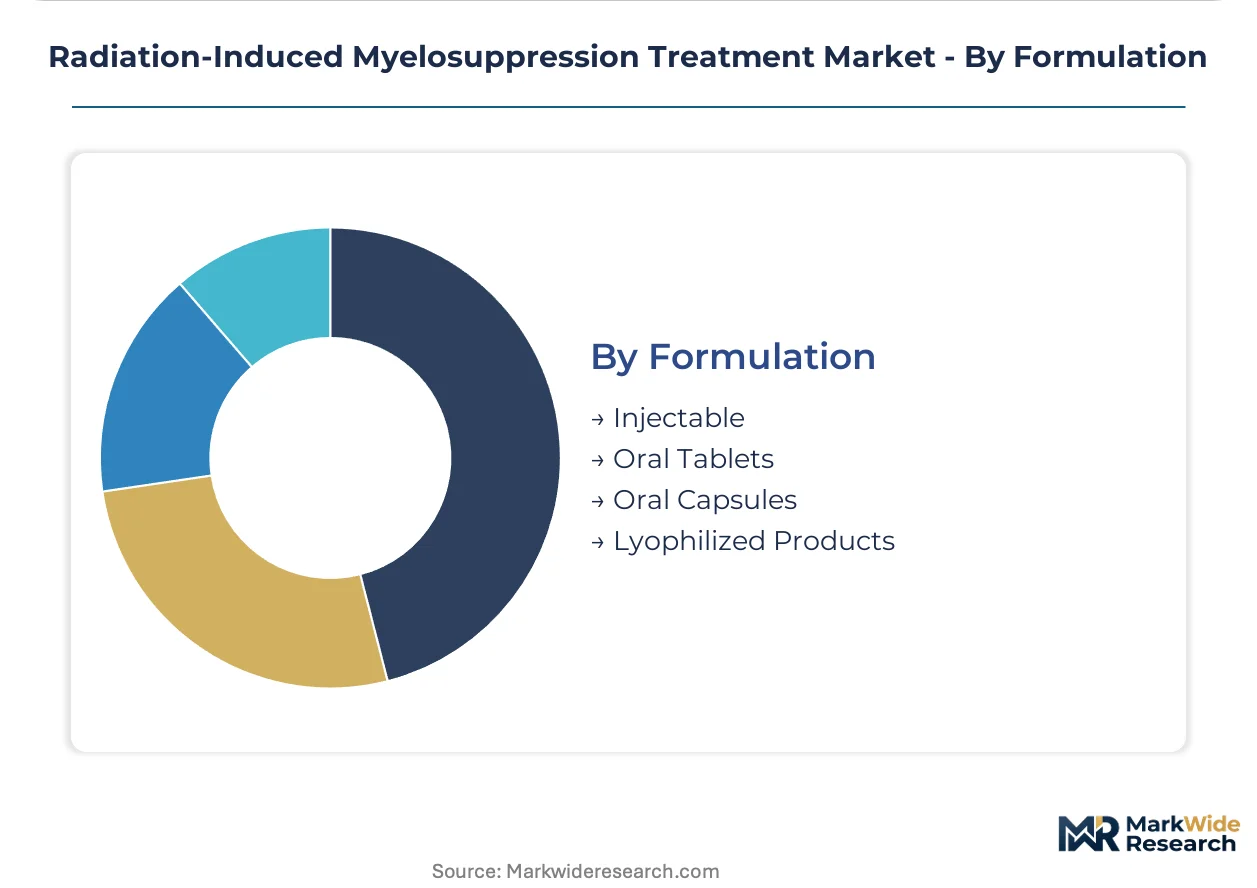
- Injectable:Liquid and lyophilized parenteral formulations dominate biologic growth factor supply. Japanese PMDA-approved pegfilgrastim prefilled syringes streamline outpatient administration.
- Lyophilized Products:Freeze-dried cytokine preparations extend shelf life for strategic stockpiling and military medical countermeasures. United States national stockpile requirements sustain this segment.
- Oral Tablets:Small-molecule immunosuppressants offer patient convenience in maintenance phases of radiation recovery.
- Oral Capsules:Enteric-coated formulations protect acid-labile compounds during gastrointestinal transit.
Injectable formulations hold the dominant position. Lyophilized products expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exporters supply cytokine formulations to United States oncology centers under EMA-certified manufacturing protocols. This transatlantic trade corridor anchors premium pricing for hematopoietic support agents while Asian biosimilar manufacturers penetrate European tender markets.
United States
Medicare Advantage expansion and ASCO guideline adoption drive prophylactic growth factor utilization across curative radiotherapy settings. FDA oncology center of excellence reviews accelerate hematopoietic support agent approvals through streamlined scientific advice. Boston and Houston academic medical centers anchor demand through integrated supportive care pathways in combined chemoradiotherapy protocols.
Germany
Aging cancer populations and hospital federation purchasing consolidation expand the addressable patient pool for myelosuppression prophylaxis. EMA joint clinical assessment processes under HTA coordination harmonize market access for novel cytokine formulations. Bavarian university hospitals lead protocol standardization through the German Cancer Society's radiation oncology working groups.
Japan
PMDA-approved pegfilgrastim prefilled syringes streamline outpatient administration for elderly patients receiving palliative radiotherapy. METI's pharmaceutical industry revitalization strategy prioritizes domestic manufacturing of temperature-sensitive biologics. Tokyo and Osaka metropolitan oncology networks concentrate subcutaneous cytokine delivery infrastructure.
India
CDSCO accelerated review pathways attract contract manufacturing investment for supportive care biologics addressing radiation oncology unmet need. Government hospital procurement programs expand access to granulocyte colony-stimulating factors in tier-two cities. Hyderabad and Bengaluru biotech clusters scale mammalian cell culture capacity for abbreviated biosimilar licensure.
South Korea
MFDS regulatory science initiatives align hematopoietic recovery endpoints with international trial standards for radiation-induced myelosuppression candidates. National health insurance reimbursement clarity supports hospital formulary adoption of extended-release cytokine variants. Seoul Capital Area oncology centers pioneer outpatient growth factor administration models for fractionated radiotherapy regimens.
Radiation-Induced Myelosuppression Treatment Market Competitive Landscape
Listed leaders compete with private specialists across intellectual property and manufacturing scale dimensions. The vendor base clusters around three strategic archetypes: originator biologics manufacturers defending premium positioning, biosimilar developers exploiting abbreviated approval pathways, and emerging cell therapy platforms pursuing novel mechanisms. Consolidation pressures intensify as hospital procurement committees bundle supportive care contracts across cytotoxic and hematopoietic agent portfolios. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure mammalian cell culture infrastructure.
Among originator-tier anchors, Amgen Inc. and Pfizer Inc. occupy positions reflecting decades of granulocyte colony-stimulating factor expertise and integrated oncology portfolio breadth respectively. Novartis AG exemplifies the biosimilar pathway strategy through sustained investment in European and Asian market access expansion. These three entities represent the competitive spectrum from premium biologic defense to volume-driven access broadening.
| Leading Market Players |
|---|
| Amgen Inc. |
| Janssen Global Services, LLC (Johnson & Johnson) |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Novartis AG |
| Mylan N.V. |
| Partner Therapeutics, Inc. |
| Myelo Therapeutics GmbH |
| Pluristem Therapeutics Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between United States integrated delivery networks and German cytokine manufacturers lock in multi-year supply access while anchoring price visibility for hematopoietic growth factor portfolios. These contract structures insulate hospital formulary committees from spot-market volatility in temperature-sensitive biologics while compressing supplier margins through volume-commitment clauses.
Pricing Analysis
Next-generation pegylated cytokine formulations command substantial premiums over immediate-release filgrastim standards, while biosimilar entrants erode originator pricing across European tender markets. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, EMA certification tier, and bundled oncology contract scale. Price differentiation stems from cold-chain reliability guarantees and after-sales nursing support infrastructure. Pricing pressure intensifies as hospital procurement committees consolidate vendor relationships into cytotoxic-plus-supportive-care bundles. Community oncology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical outcome data over acquisition cost.
Supply Chain Analysis
Inventory buffers for lyophilized cytokine preparations extend to ninety-day strategic reserves, while liquid formulations demand continuous cold-chain rotation with forty-eight-hour replenishment cycles. Manufacturing concentrates in Germany, South Korea, and India, with Bavarian facilities serving EMA-certified export demand and Hyderabad clusters scaling mammalian cell culture for abbreviated biosimilar pathways. Raw material dependencies center on recombinant DNA starter cultures, pharmaceutical-grade polyethylene glycol, and borosilicate glass syringes. Single-source vulnerability in temperature-controlled logistics strains regional pharmacy capabilities during peak radiotherapy seasons. Distribution runs through specialty pharmaceutical wholesalers with dedicated biologics handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as prophylactic growth factor protocols displace reactive treatment models across curative radiotherapy settings, with ASCO guideline incorporation accelerating hospital formulary adoption ahead of demographic tailwinds in aging cancer populations.
For Market Incumbents: Fortify mammalian cell culture capacity in EMA-certified manufacturing corridors to defend against biosimilar price compression from South Korean and Indian contract development organizations. Deepen backward integration into recombinant DNA starter culture production to secure input cost stability. Lock hospital procurement committees into bundled cytotoxic-plus-cytokine contracts that displace standalone negotiations and protect margin structure. For New Entrants and Emerging Players: CDSCO accelerated review pathways offer the fastest regulatory onramp for supportive care biologics addressing radiation oncology unmet need in tier-two Indian cities. Target homecare administration segments where subcutaneous delivery infrastructure remains unevenly distributed across rural United States health systems. Pursue white-label manufacturing partnerships with established German exporters to bypass originator patent thickets. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap biosimilar developers with abbreviated licensure expertise and existing EMA scientific advice relationships. Long-term viability hinges on manufacturing scale rather than molecule novelty, favoring players with captive mammalian cell culture infrastructure. Watch for inflection signals in Medicare Advantage penetration rates that shift site-of-service economics toward outpatient cytokine administration.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Scientific Advice Engagement | Iterative guidance on hematopoietic recovery endpoints shortens Phase III trial durations for radiation-induced myelosuppression candidates. |
| Mammalian Cell Culture Scale-Up | Captive bioreactor capacity in Germany and South Korea insulates supply against cold-chain logistics bottlenecks during peak demand. |
| Bundled Oncology Contracting | Integrated cytotoxic-plus-cytokine purchasing consolidations displace standalone growth factor negotiations across United States hospital systems. |
| Extended-Release Formulation Development | Pegylated cytokine variants align with patient preference for reduced clinic burden in Japanese palliative radiotherapy settings. |
| Homecare Nursing Infrastructure Investment | Specialty pharmacy partnerships enable subcutaneous administration shifts toward Medicare Advantage populations in decentralized care models. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with formulary directors and GPO contracts managers across United States, German, and Japanese oncology centers. Secondary validation drew from FDA filings, EMA committee minutes, ClinicalTrials.gov protocols, and hospital procurement databases. Bottom-up patient-flow modeling and top-down epidemiological triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across alternative radiotherapy fractionation scenarios and biosimilar penetration trajectories. The projection framework modeled treatment line, administration route, formulation type, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from iterative reconciliation of epidemiological incidence projections, protocol adoption curves, and pricing elasticity assumptions. Forecast inputs incorporated ASCO guideline revision schedules and IRA Medicare price negotiation implementation timelines.
Underlying assumptions cover stable reimbursement parity between inpatient and outpatient cytokine administration, with deviation risk concentrated in HTA coordination delays under EU joint clinical assessment processes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Febrile Neutropenia Market
Hematology
Sickle Cell Treatment Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Blood Plasma Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Anemia Drugs Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Hemocytometer Market
Hematology
Blood Screening Market
Hematology
Bone Marrow Transplant Market
Hematology
Global Hematology Market
Hematology
Thalassemia Treatment Market
Hematology
Idiopathic Thrombocytopenic Purpura Market