
 Filariasis Treatment Market | 2026-2036
Filariasis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Filariasis Treatment Market Foresight
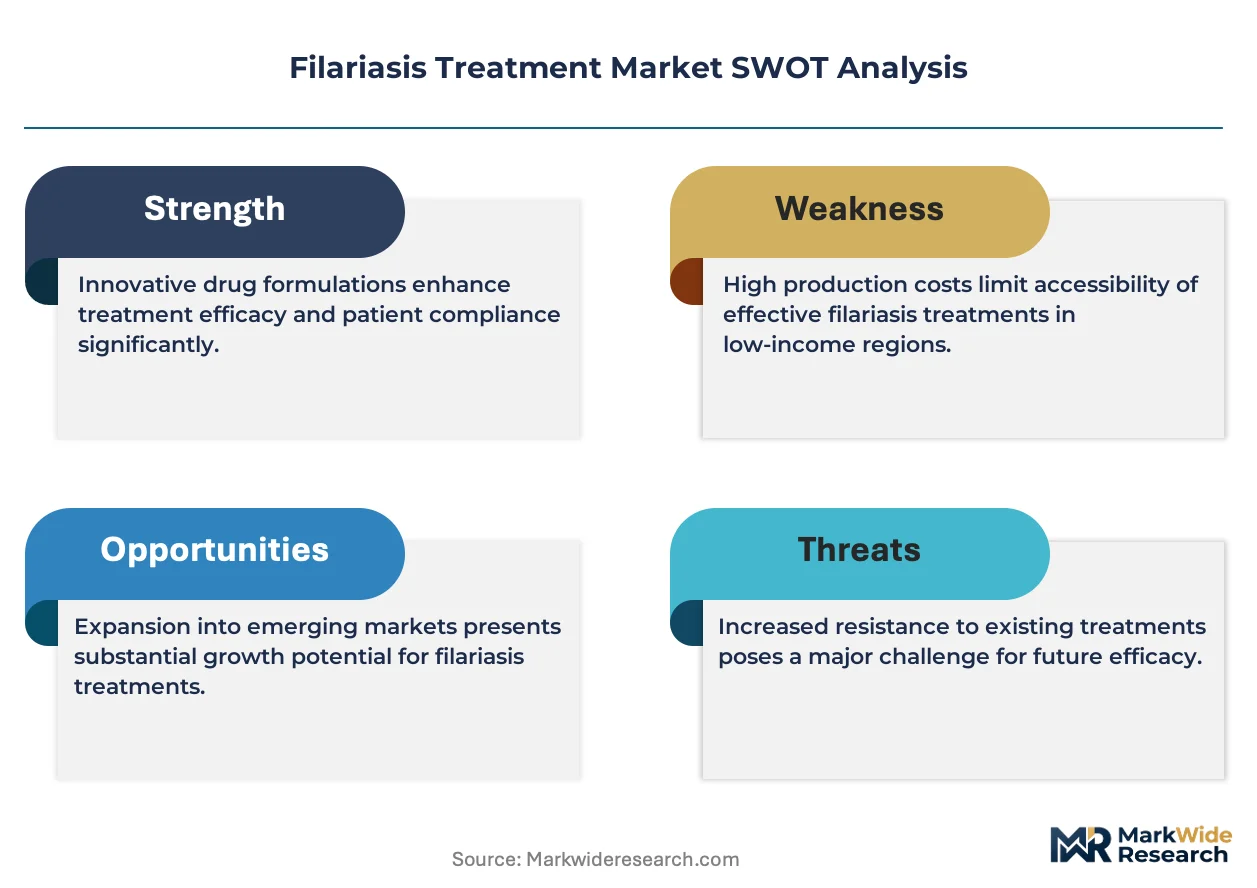
The manufacturing scale gap between large pharmaceutical conglomerates and regional generics producers is unwinding competitive dynamics in filariasis therapeutics. Merck & Co. leverages its established ivermectin supply infrastructure to sustain donation program commitments across endemic zones. GlaxoSmithKline anchors its position through albendazole manufacturing partnerships that support mass drug administration campaigns. Eisai Co., Ltd. differentiates via diethylcarbamazine citrate production expertise tied to Pacific Island elimination programs.
Filariasis treatment encompasses pharmaceutical interventions targeting nematode parasites of the Filarioidea family, principally employing benzimidazole derivatives, macrocyclic lactones, and piperazine-based compounds that disrupt microfilarial metabolism or adult worm symbiosis with Wolbachia endobacteria. These agents serve the primary commercial purpose of interrupting disease transmission in endemic populations while managing lymphedema progression in established infections. Anthelmintics occupy the dominant value position given their centrality to preventive chemotherapy protocols, while combination therapies represent the fastest-expanding segment as WHO guidelines increasingly endorse co-administration regimens for accelerated elimination timelines. Injectable solutions command premium positioning in community health programs where patient compliance barriers favor supervised parenteral delivery over oral tablet courses.
FDA bioequivalence standards and WHO prequalification pathways shape product registration requirements for filariasis therapeutics entering endemic markets, while EMA orphan drug incentives stimulate European-headquartered firms to pursue tropical disease indications. National regulatory authorities in endemic countries increasingly mandate stability testing under tropical climate conditions as a condition of import authorization. Stakeholders must monitor evolving WHO target product profiles for next-generation macrofilaricidal compounds and assess manufacturing readiness for candidate therapies currently in clinical development.
Market Dynamics
Mass drug administration scale-up through WHO's neglected tropical disease roadmap is compressing procurement cycles and forcing manufacturers to align production with coordinated national elimination timelines rather than fragmented commercial orders.
Growth Catalysts
- Preventive chemotherapy protocols:WHO's triple-drug administration guidelines for lymphatic filariasis accelerate regimen standardization across endemic countries, creating predictable demand anchors for albendazole-ivermectin-diethylcarbamazine combinations.
- Sub-Saharan Africa:Nigeria's Federal Ministry of Health and Tanzania's National Institute for Medical Research anchor the world's largest active treatment cohorts, driving volume commitments that justify dedicated manufacturing lines.
- Wolbachia endosymbiont targeting:Doxycycline-based macrofilaricidal regimens expand the therapeutic arsenal beyond microfilaricides, opening new prescriber segments in lymphedema management programs.
Market Restraints
- API supply concentration:Ivermectin active pharmaceutical ingredient production clusters in Chinese and Indian chemical synthesis hubs, exposing procurement to export license volatility and freight cost spikes.
- Tropical stability requirements:WHO prequalification mandates for 30°C/75%RH accelerated stability testing extend development timelines and raise formulation costs for heat-sensitive macrocyclic lactones.
- Diagnostic substitution:Antigen detection assays for Wuchereria bancrofti reduce presumptive treatment volumes in surveillance-intensive settings, compressing addressable patient pools in mature elimination programs.
Strategic Opportunities
- Pacific Island territories:Vanuatu, Samoa, and Tonga operate under WHO-certified elimination status maintenance protocols, creating recurring procurement for post-elimination surveillance dosing and test-and-treat reserves.
- EMA orphan drug incentives:European manufacturers can access protocol assistance and fee waivers for macrofilaricidal candidates targeting onchocerciasis-filariasis overlap, accelerating development of next-generation Wolbachia inhibitors.
- Community-directed distributors:Village health worker networks in Ghana and Uganda bypass clinic infrastructure constraints, enabling last-mile penetration that conventional pharmaceutical distribution cannot replicate.
Industry Challenges
- Pharmacovigilance capacity gaps:National regulatory authorities in endemic zones lack adverse event reporting infrastructure to support post-marketing surveillance for mass administration safety signals.
- Co-administration formulation complexity:Fixed-dose combination development for ivermectin-albendazole requires bioequivalence bridging studies that strain clinical trial resources in resource-limited settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filariasis Treatment Market |
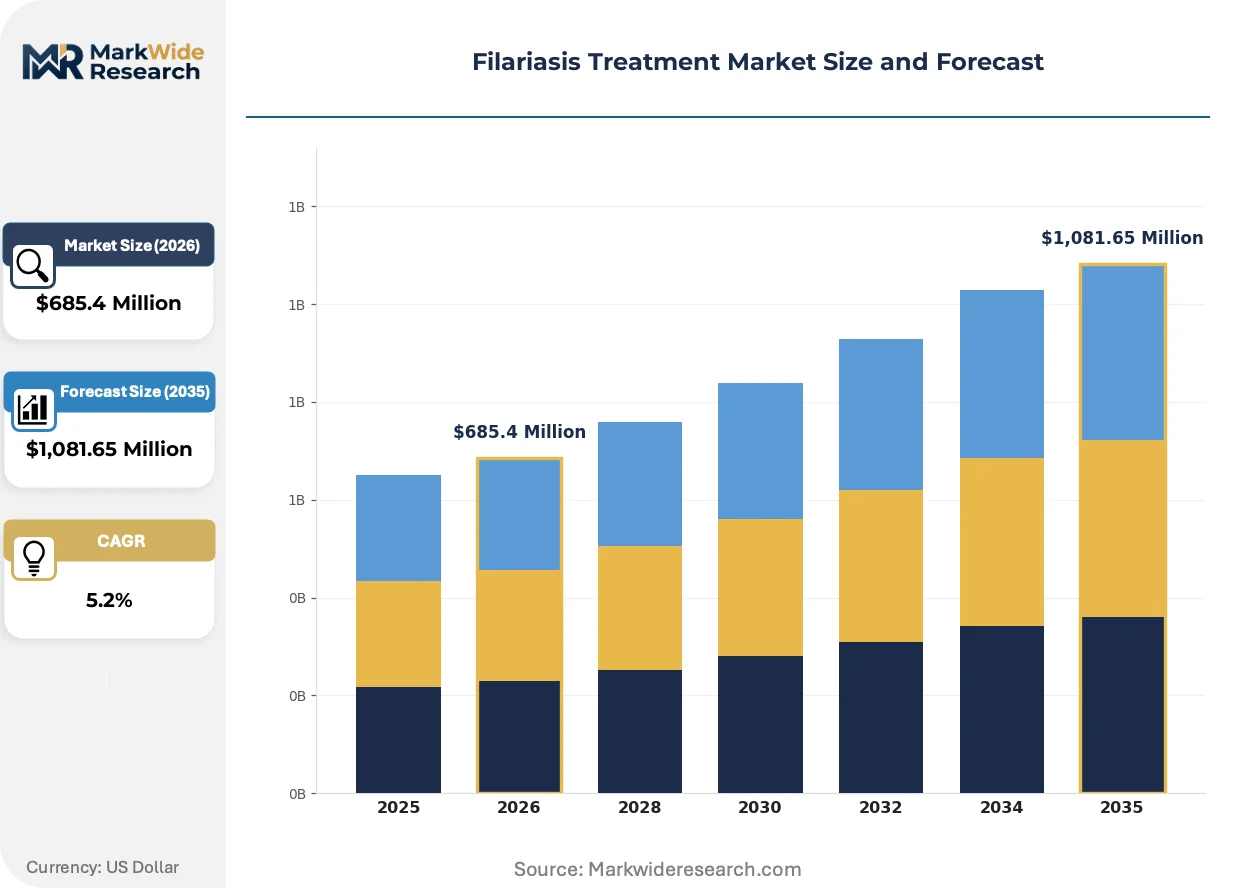
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anthelmintics, Microfilaricides, Antibiotics, Immunomodulators, Combination Therapies Therapy Area: Lymphatic Filariasis, Subcutaneous Filariasis, Tropical Pulmonary Eosinophilia, Occult Filariasis End User: Primary Care Centers, Community Health Programs, Research Institutions, Public Health Agencies Delivery Mode: Oral Tablets, Injectable Solutions, Topical Applications, Sustained Release Formulations |
| Companies Covered | Merck & Co., GlaxoSmithKline, Pfizer Inc., Eisai Co., Ltd., Novartis AG, Johnson & Johnson, Cipla Inc., AbbVie Inc., Bausch Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filariasis Treatment Market Shifts & Advancements
Product evolution and procurement restructuring are converging to reshape competitive positioning in filariasis therapeutics, with formulation innovation and distribution model experimentation now outpacing traditional molecule development.
Macrofilaricidal candidates targeting adult worm viability through Wolbachia symbiosis disruption are supplanting microfilaricide-only regimens in late-stage development pipelines. Novartis and the Drugs for Neglected Diseases Initiative prioritize clinical trials for emodepside and oxfendazole analogues that shorten treatment duration from annual to single-dose protocols. This technology is compressing the competitive window for legacy benzimidazole manufacturers while elevating value capture toward curative rather than suppressive endpoints.
WHO's 2021-2030 neglected tropical disease roadmap revision tightens elimination certification criteria and mandates transmission assessment surveys at pre-defined prevalence thresholds. National programs in Indonesia and the Philippines must now integrate xenomonitoring and antibody testing into surveillance frameworks, redirecting procurement budgets toward diagnostic-therapeutic bundles. Pharmaceutical suppliers respond by packaging drug donations with entomological training and vector control commodities.
Donor-funded procurement through the WHO Praziquantel Donation Program and Merck's Mectizan Expert Committee is displacing commercial tender processes in endemic country purchasing. Ministries of health in Ethiopia and Malawi now receive pre-positioned drug stocks through consolidated supply chains managed by international NGOs, compressing transaction volumes available to private distributors. This channel consolidation concentrates supplier relationships with manufacturers holding established donation program credentials.
Filariasis Treatment Market Segmentation
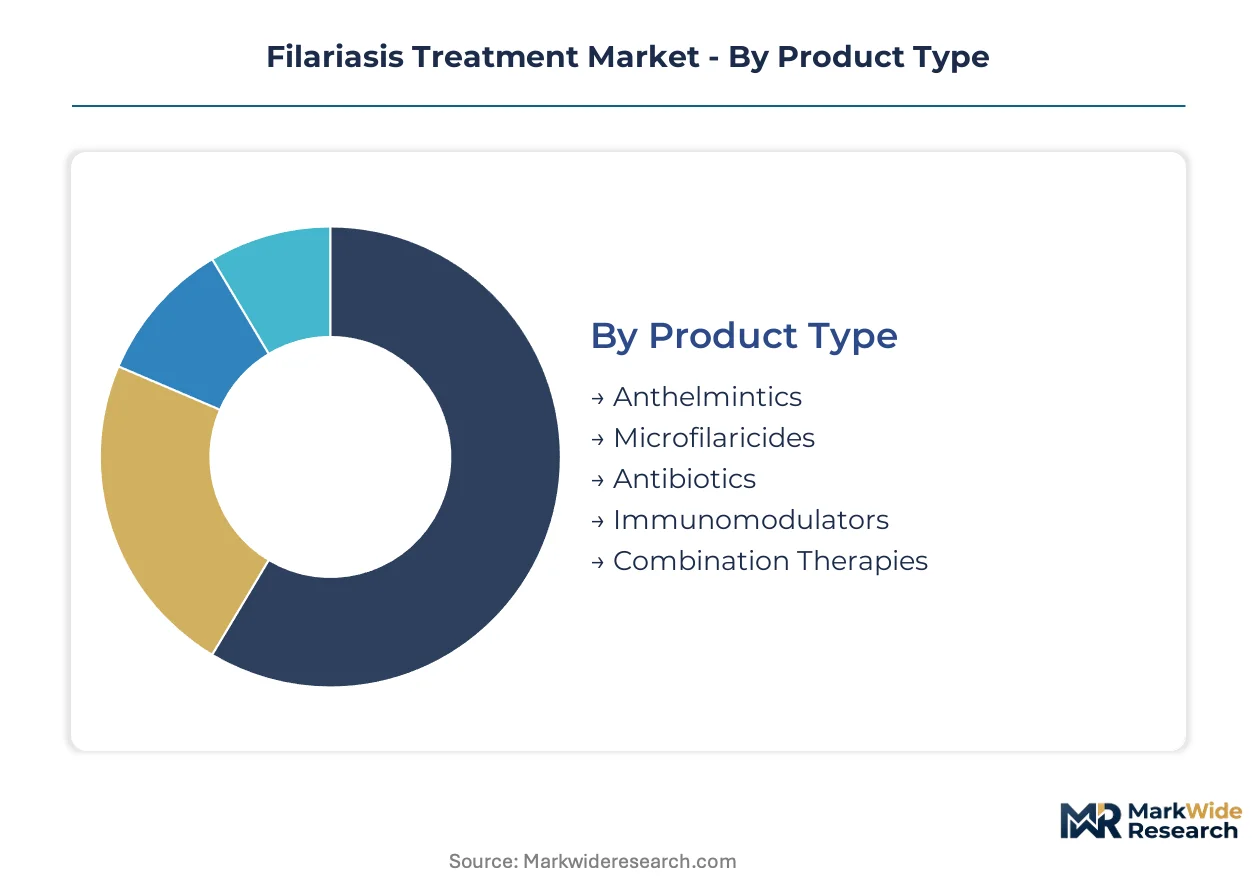
Treatment modality selection in filariasis therapeutics hinges on WHO prequalification status and national program procurement specifications. Manufacturers align formulation development with the specific stability, bioequivalence, and distribution requirements that each segment category imposes on supply chains serving endemic regions.
Product Type:
FDA bioequivalence standards and WHO prequalification pathways create tiered registration barriers that concentrate commercial activity among prequalified molecular categories.
- Anthelmintics:Benzimidazole derivatives—principally albendazole and mebendazole—disrupt microtubule formation in nematode intestinal cells. Nigeria's Federal Ministry of Health and Tanzania's National Institute for Medical Research anchor the world's largest procurement volumes for mass drug administration campaigns.
- Microfilaricides:Macrocyclic lactones including ivermectin and diethylcarbamazine citrate paralyze microfilariae through glutamate-gated chloride channel activation. Merck's Mectizan donation program and Eisai's Pacific Island supply commitments dominate distribution channels where supervised community dosing is mandatory.
- Antibiotics:Doxycycline regimens target Wolbachia endosymbionts essential for adult worm fertility.
- Immunomodulators:Adjunctive agents manage lymphedema inflammation in chronic infection management protocols.
- Combination Therapies:Fixed-dose albendazole-ivermectin-diethylcarbamazine formulations compress elimination timelines per WHO triple-drug guidelines.
Anthelmintics handle the majority of throughput; combination therapies are climbing the fastest on procurement share.
Therapy Area:
Diagnostic test availability and disease prevalence patterns concentrate manufacturing investment toward clinically distinct parasitic manifestations.
- Lymphatic Filariasis:Wuchereria bancrofti and Brugia malayi infections drive lymphedema progression and hydrocele formation. Sub-Saharan Africa and Southeast Asia concentrate active treatment cohorts where antigen detection assays enable precision targeting of endemic communities.
- Subcutaneous Filariasis:Onchocerca volvulus and Loa loa infections present distinct therapeutic challenges including severe adverse event risks with microfilaricides. River blindness control programs in Ethiopia and Malawi require specialized ivermectin dosing protocols.
- Tropical Pulmonary Eosinophilia:Hypersensitivity reactions to filarial antigens demand corticosteroid co-administration.
- Occult Filariasis:Asymptomatic infections detected through serological surveillance expand addressable patient pools in elimination-phase programs.
Lymphatic filariasis commands the dominant procurement volume; subcutaneous filariasis presents the steepest unmet need for macrofilaricidal alternatives.
End User:
Channel economics and patient access constraints favor distribution models that bypass conventional healthcare infrastructure.
- Primary Care Centers:Clinic-based diagnosis and treatment delivery serves urban populations and symptomatic lymphedema cases. Ghana's district health systems and Uganda's regional referral hospitals anchor procurement for established infection management.
- Community Health Programs:Village health worker networks enable last-mile penetration in rural endemic zones. Community-directed distributors in Nigeria and Indonesia bypass clinic infrastructure constraints that conventional pharmaceutical distribution cannot replicate.
- Research Institutions:Clinical trial sites and transmission assessment survey teams drive demand for diagnostic-therapeutic bundles.
- Public Health Agencies:National elimination programs consolidate procurement through WHO-coordinated supply chains.
Community health programs absorb the largest drug volumes; research institutions are expanding most quickly as elimination trials proliferate.
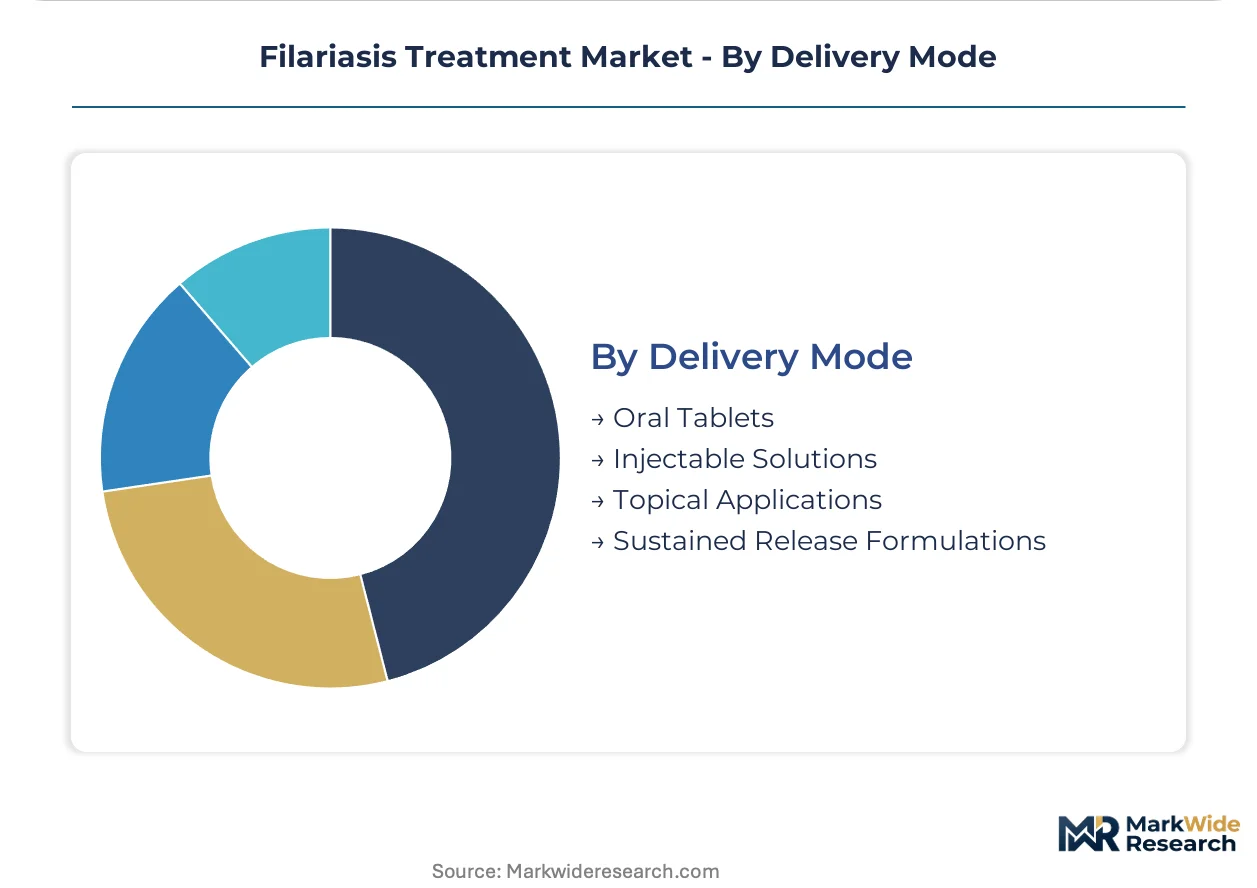
Delivery Mode:
Patient compliance barriers and tropical climate stability requirements shape formulation technology investment priorities.
- Oral Tablets:Standard albendazole and ivermectin formulations dominate mass drug administration for their storage stability and ease of community distribution. WHO prequalification mandates for 30°C/75%RH accelerated stability testing extend development timelines for heat-sensitive macrocyclic lactones.
- Injectable Solutions:Parenteral diethylcarbamazine and ivermectin preparations command premium positioning where supervised dosing is required. Pacific Island territories including Vanuatu and Samoa rely on injectable regimens for elimination status maintenance protocols.
- Topical Applications:Localized delivery systems address cutaneous manifestations and vector control integration.
- Sustained Release Formulations:Long-acting injectable and implant technologies reduce dosing frequency in resource-limited settings.
Oral tablets carry the bulk of distribution volume; sustained release formulations are gaining share fastest as macrofilaricidal development advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across endemic zones. Pacific Island territories absorb premium-priced injectable regimens for elimination maintenance, while sub-Saharan ministries of health drive hard volume discounts on oral albendazole and ivermectin combinations.
Nigeria
The Federal Ministry of Health operates the world's largest lymphatic filariasis treatment cohort through mass drug administration campaigns. WHO prequalification requirements govern all import authorizations for anthelmintic formulations. Lagos and Abuja anchor procurement consolidation as the national program shifts toward triple-drug combination protocols.
Tanzania
The National Institute for Medical Research coordinates transmission assessment surveys that trigger precision-targeted treatment rounds. The country's national pharmaceutical regulator mandates stability testing under tropical climate conditions for all macrocyclic lactone imports. Dar es Salaam concentrates distribution logistics for community-directed treatment networks spanning Lake Victoria endemic zones.
Indonesia
The Ministry of Health integrates xenomonitoring and antibody testing into surveillance frameworks per WHO 2021-2030 roadmap revisions. National regulatory authorities require bioequivalence documentation for fixed-dose combination approvals. Java and Sumatra host the primary manufacturing partnerships supporting domestic albendazole production for regional elimination programs.
Ethiopia
The Federal Ministry of Health receives pre-positioned drug stocks through consolidated supply chains managed by international NGOs. River blindness control programs in the Omo and Blue Nile valleys require specialized ivermectin dosing protocols. Addis Ababa anchors the procurement coordination for co-administration regimens targeting onchocerciasis-filariasis overlap zones.
Philippines
The Department of Health maintains elimination certification criteria through transmission assessment surveys at pre-defined prevalence thresholds. WHO prequalification pathways shape product registration for all filariasis therapeutics entering the archipelago. Manila and Cebu concentrate diagnostic-therapeutic bundle procurement as national programs redirect budgets toward surveillance-intensive settings.
Filariasis Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in filariasis therapeutics. Merck & Co. and GlaxoSmithKline anchor the upper tier through established donation program infrastructures and WHO partnership credentials. The specialist tier encompasses regional generics producers and macrofilaricidal developers pursuing EMA orphan drug incentives. Competitive moves concentrate on manufacturing scale alignment with national elimination timelines and formulation innovation for tropical stability compliance.
Among research-intensive pharmaceutical conglomerates, Merck & Co., GlaxoSmithKline, and Novartis occupy positions defined by distinct therapeutic anchors. Merck exemplifies the macrocyclic lactone specialist through ivermectin supply infrastructure sustaining endemic zone commitments. GlaxoSmithKline represents the benzimidazole manufacturing archetype via albendazole partnerships supporting mass drug administration scale. Novartis sits within the macrofilaricidal development tier, prioritizing clinical advancement of compounds that target Wolbachia symbiosis disruption for curative endpoints.
| Leading Market Players |
|---|
| Merck & Co. |
| GlaxoSmithKline |
| Pfizer Inc. |
| Eisai Co., Ltd. |
| Novartis AG |
| Johnson & Johnson |
| Cipla Inc. |
| AbbVie Inc. |
| Bausch Health |
| Others |
Supply & Pricing Matrix
API sourcing substitution from Western chemical synthesis to Indian and Chinese manufacturing hubs simultaneously compresses formulation costs and concentrates pricing power among bulk producers holding WHO prequalification credentials. Donor-funded procurement through consolidated NGO supply chains displaces commercial tender processes, forcing manufacturers to absorb tropical stability testing costs within compressed margin structures.
Pricing Analysis
After-sales service bundling—including pharmacovigilance training and community distributor certification—drives lifetime value capture in filariasis therapeutics. Three-tier pricing structure across WHO-prequalified premium, national program standard, and unregistered economy levels stratifies procurement channels. Cost compression in standard-tier oral albendazole intensifies because Nigerian and Tanzanian ministries of health consolidate volume tenders. Community health programs exhibit highest price sensitivity due to donor budget constraints; Pacific Island maintenance protocols show lowest sensitivity given elimination certification urgency.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for ivermectin and albendazole, with secondary formulation finishing in Indonesia and Nigeria. Macrocyclic lactone fermentation and benzimidazole chemical synthesis draw from concentrated agricultural substrate and petrochemical feedstock networks. Single-source vulnerability in Chinese export license administration threatens procurement continuity for heat-sensitive formulations. Distribution runs through WHO-coordinated international NGO channels that pre-position drug stocks in Addis Ababa, Dar es Salaam, and Lagos distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing scale alignment with national elimination timelines represents the critical capability gap separating donation program incumbents from regional generics competitors unable to synchronize production with coordinated procurement cycles.
For Market Incumbents: Fortify supply chain resilience through backward integration into Indian API sourcing partnerships that bypass export license volatility. Anchor manufacturing capacity in Dar es Salaam and Lagos to compress logistics costs for community-directed treatment networks. Certification investment in WHO tropical stability testing accelerates prequalification timelines against emerging macrofilaricidal developers. For New Entrants and Emerging Players: EMA orphan drug protocol assistance offers the fastest regulatory pathway to commercial relevance for Wolbachia-targeting candidates. Pacific Island elimination maintenance protocols represent the most penetrable geography given premium pricing tolerance and limited incumbent service infrastructure. Target hospital-based lymphedema management programs as the initial prescriber channel before mass drug administration scale. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional generics manufacturers holding Indian API offtake agreements but lacking WHO prequalification credentials. Five-to-ten-year viability hinges on elimination timeline extensions and macrofilaricidal pipeline failures. Watch for transmission assessment survey results in Indonesia and the Philippines as volume inflection signals redirecting procurement toward surveillance-intensive diagnostic-therapeutic bundles.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Fast-Track | EMA orphan drug incentives compress regulatory timelines for macrofilaricidal candidates targeting Wolbachia symbiosis disruption. |
| Fixed-Dose Combination Development | Bioequivalence bridging studies for albendazole-ivermectin-diethylcarbamazine formulations strain clinical trial resources in Nigerian and Tanzanian sites. |
| Community-Distributor Network Expansion | Village health worker programs in Ghana and Uganda bypass clinic infrastructure constraints that conventional pharmaceutical distribution cannot replicate. |
| Tropical Stability Formulation Investment | 30°C/75%RH accelerated testing mandates from WHO extend development timelines for heat-sensitive macrocyclic lactone derivatives. |
| Diagnostic-Therapeutic Bundle Packaging | Indonesian xenomonitoring requirements redirect procurement budgets toward entomological training and vector control commodity integration. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads at WHO prequalification units, national program procurement managers in Nigeria and Tanzania, and community health distribution coordinators, then refined through secondary validation against FDA bioequivalence filings, EMA orphan drug submission databases, ClinicalTrials.gov macrofilaricidal trial records, and WHO neglected tropical disease roadmap documentation. Bottom-up treatment volume estimates from endemic country mass drug administration campaigns were triangulated with top-down pharmaceutical procurement value aggregation.
Variance decomposition across product type, therapy area, end user channel, and delivery mode segments structured the analytical framework over the projection horizon. CAGRs were derived from patient cohort expansion rates, elimination timeline compressions, and regimen substitution patterns. Forecast inputs incorporated WHO transmission assessment survey trigger thresholds, national regulatory stability testing mandates, and donor fund allocation shifts between preventive chemotherapy and surveillance diagnostics.
Underlying assumptions cover sustained WHO elimination commitment funding, API export license continuity from Indian and Chinese hubs, and tropical climate storage infrastructure expansion, with deviation risk concentrated in macrofilaricidal clinical trial outcomes and diagnostic substitution effects in mature elimination programs. Recalibration cycles align with material shifts in WHO roadmap revisions, national program procurement consolidation events, and macrofilaricidal regulatory approval milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
Ascites Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market