
 Microwave Ablation Market | 2026-2036
Microwave Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Ablation Market Intelligence
Aftermarket service revenue is reshaping margin capture in the microwave ablation sector as hospitals extend generator lifecycles and demand calibration contracts. Medtronic leverages its installed base of capital equipment to sustain recurring revenue streams across North American hospital networks. Boston Scientific Corporation competes through specialized applicator portfolios that anchor its position in liver and lung cancer interventions. AngioDynamics differentiates via integrated navigation platforms that combine microwave energy delivery with computed tomography guidance.
Microwave ablation employs electromagnetic energy at frequencies between 915 MHz and 2.45 GHz to generate frictional heat within tissue, achieving target temperatures of 60°C to 100°C for controlled coagulative necrosis. The technology serves primary industrial purpose in percutaneous, laparoscopic, and open surgical settings where precise thermal destruction of malignant tissue is required without extensive resection. Generator systems command the dominant share of product-type value pools given their capital intensity and software-dependent energy modulation capabilities. Liver cancer applications lead procedural volumes due to established clinical evidence and repeat-treatment feasibility for hepatocellular carcinoma patients. Hospitals represent the most concentrated end-user channel, though ambulatory surgical centers are gaining capacity for same-day ablation discharge protocols.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation mandates clinical evidence thresholds for microwave ablation systems marketed in Europe. China's National Medical Products Administration enforces GB standards for electromagnetic compatibility and tissue-contact safety in imported ablation equipment. Stakeholders must monitor evolving reimbursement coding for image-guided tumor ablation across Medicare, national health services, and provincial insurance schemes to anticipate capital allocation cycles and technology adoption curves.
Market Dynamics
Real-time thermometry integration is compressing treatment cycles and forcing generator manufacturers to embed sensor fusion algorithms directly into capital equipment. This hardware-software convergence is redrawing competitive boundaries between pure-play ablation device firms and imaging system vendors.
Growth Catalysts
- FDA 510(k) pathway expansion:Clearances for expanded oncologic indications accelerate clinical protocol adoption across interventional radiology departments in tertiary hospitals.
- Hepatocellular carcinoma recurrence patterns:Repeat-treatment feasibility for liver cancer patients sustains procedural volume growth and device utilization rates.
- Ambulatory surgical center capacity buildouts:Same-day discharge protocols for percutaneous ablation shift site-of-care economics toward outpatient settings.
Market Restraints
- Generator capital intensity:Electromagnetic compatibility testing and GB standard compliance for 915 MHz systems inflate upfront equipment costs for hospital procurement committees.
- Supply concentration in precision coaxial cable:Limited qualified suppliers for 2.45 GHz applicator assemblies create single-source vulnerability in component sourcing.
- Radiofrequency ablation substitution:Established RF thermal ablation protocols in cardiology and pain management compete for capital budget allocation against microwave systems.
Strategic Opportunities
- China's provincial insurance scheme maturation:Reimbursement codification for image-guided tumor ablation in Jiangsu and Guangdong provinces opens volume expansion for imported equipment.
- Navigation platform convergence:Integration of microwave energy delivery with computed tomography guidance creates premium positioning for integrated system vendors.
- Calibration contract unbundling:Aftermarket service revenue streams from generator lifecycle extension reshape margin capture beyond initial capital sales.
Industry Challenges
- Interventional radiologist training pipelines:Specialized credentialing requirements for percutaneous thermal ablation create bottlenecks in procedural capacity expansion.
- Legacy imaging system interoperability:Retrofitting navigation platforms to existing CT and MRI suites demands costly PACS integration and software validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Ablation Market |
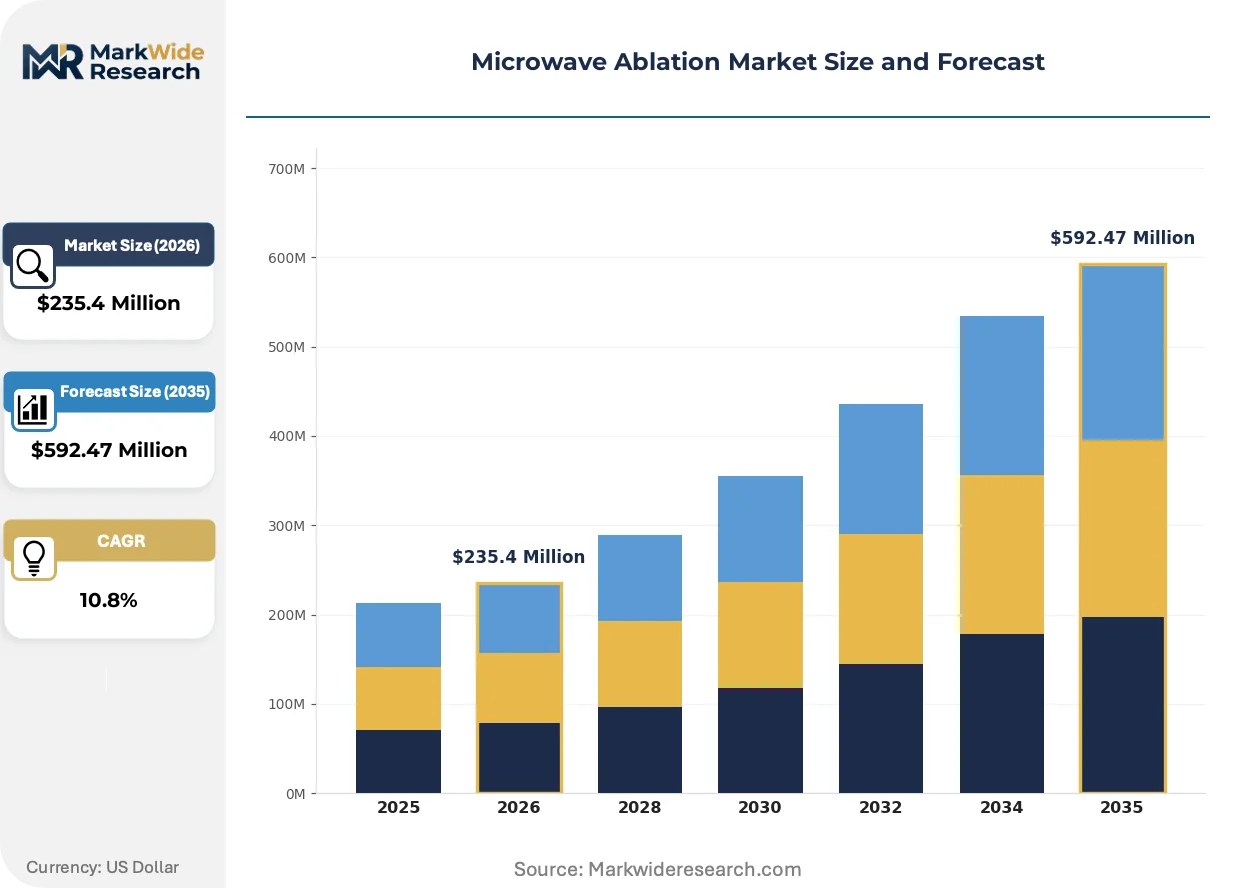
| Market Size in 2026 | $235.4 Million |
| Market Size in 2035 | $592.47 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrode, Generator, Applicator, Accessories Application: Liver Cancer, Lung Cancer, Kidney Tumors, Cardiac Arrhythmias End User: Hospitals, Ambulatory Surgical Centers, Cancer Treatment Centers, Academic Research Institutions Technology: Thermal Ablation, Radiofrequency Ablation, Cryoablation, Others |
| Companies Covered | AngioDynamics, Medtronic, Emblation Ltd., HUBER+SUHNER, Johnson & Johnson Services, Inc., MedWaves, Inc., Boston Scientific Corporation, NeuWave Medical, Varian Medical Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Ablation Market Strategic Shifts & Innovations
Energy modulation algorithms and closed-loop temperature feedback are transforming microwave ablation from empirical technique to precision intervention. These advances compress operator learning curves while tightening therapeutic margins.
Real-time thermometry systems embed fiber-optic sensors within applicator shafts to monitor tissue temperatures during energy delivery. Interventional radiology suites at academic medical centers deploy these platforms to reduce procedure times and improve ablation zone predictability. The technology is digitizing treatment planning by enabling automated energy titration based on live thermal mapping rather than fixed power protocols.
The EU Medical Device Regulation mandates clinical evidence thresholds for microwave ablation systems marketed in Europe, elevating post-market surveillance requirements. Manufacturers must maintain technical documentation and periodic safety reporting that exceeds previous Medical Device Directive obligations. Class III device reclassifications for certain applicator types are forcing portfolio rationalization among smaller vendors.
Hospital procurement committees increasingly unbundle generator purchases from multi-year service agreements, treating calibration and software maintenance as separate line items. Original equipment manufacturers respond by offering subscription-based thermometry upgrades rather than full capital replacements. This shift is most visible in United States hospital networks where GPO-negotiated contracts emphasize total cost of ownership over upfront equipment pricing.
Microwave Ablation Market Segmentation
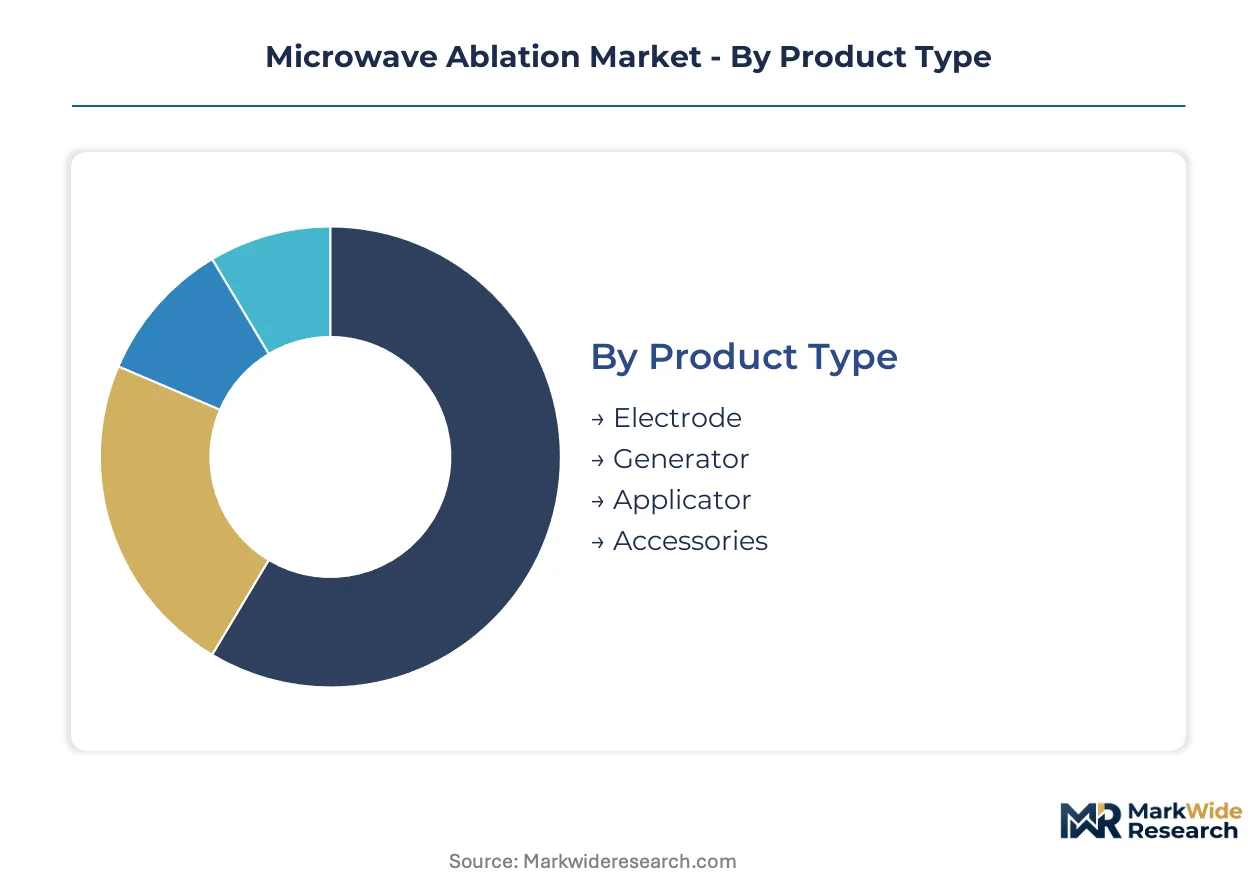
Microwave ablation market segmentation reveals distinct value capture mechanisms across hardware tiers, clinical applications, and care delivery sites. Procurement patterns diverge sharply between capital-intensive generator systems and disposable applicator consumables.
Product Type:
Cost tier stratification in microwave ablation hardware separates capital equipment from recurring consumable revenue streams.
- Generator:Electromagnetic energy systems operating at 915 MHz and 2.45 GHz frequencies command premium pricing through software-dependent modulation capabilities. Tertiary hospitals in the United States concentrate procurement for these capital units, though electromagnetic compatibility testing and GB standard compliance inflate upfront acquisition costs for procurement committees.
- Applicator:Coaxial cable assemblies deliver energy to target tissue with precision thermal control. Demand clusters in liver and lung cancer interventions at academic medical centers, where repeat-treatment feasibility for hepatocellular carcinoma patients sustains utilization rates and replacement cycles.
- Electrode:Tissue-contact components engineered for specific anatomical access routes. These single-use elements generate recurring revenue through procedure-volume correlation.
- Accessories:Supplementary hardware including grounding pads, cooling systems, and connector interfaces. These components complete system configurations without independent therapeutic function.
Generator holds installed capacity. Applicator is rotating up the share rankings.
Application:
Clinical application segmentation tracks oncologic procedure volumes and repeat-treatment eligibility across malignancy types.
- Liver Cancer:Hepatocellular carcinoma interventions dominate procedural volumes due to established clinical evidence and thermal ablation suitability for cirrhotic patients. Tertiary hospital interventional radiology suites in Germany and China concentrate demand, where reimbursement pathways for minimally invasive oncology interventions have matured.
- Lung Cancer:Percutaneous ablation of pulmonary lesions expands as surgical alternatives for high-risk patients. Academic medical centers deploy navigation-integrated platforms to improve targeting precision in respiratory-moving tissue.
- Kidney Tumors:Renal cell carcinoma applications leverage microwave energy for nephron-sparing destruction. These procedures concentrate at centers with established urologic oncology programs.
- Cardiac Arrhythmias:Cardiac tissue ablation competes for capital budget allocation against established radiofrequency protocols in electrophysiology departments.
Liver Cancer anchors procedure volumes. Lung Cancer is climbing the fastest as navigation platforms improve targeting feasibility.
End User:
Customer type segmentation reflects site-of-care economics shifting between inpatient and outpatient settings.
- Hospitals:Tertiary academic centers with interventional radiology suites represent the most concentrated channel, hosting complex multi-lesion procedures and training pipelines for specialized credentialing.
- Ambulatory Surgical Centers:Same-day discharge protocols for percutaneous ablation shift volume toward outpatient settings where capital equipment sharing models reduce individual facility investment burdens.
- Cancer Treatment Centers:Dedicated oncology facilities integrate ablation into multimodal treatment pathways for hepatocellular carcinoma and metastatic disease management.
- Academic Research Institutions:Research hospitals drive protocol innovation and thermometry algorithm validation through clinical trial infrastructure.
Hospitals retain procedural complexity concentration. Ambulatory Surgical Centers are gaining share fastest as reimbursement codification enables site-of-care migration.
Technology:
Technology modality segmentation captures competitive displacement dynamics between thermal energy platforms.
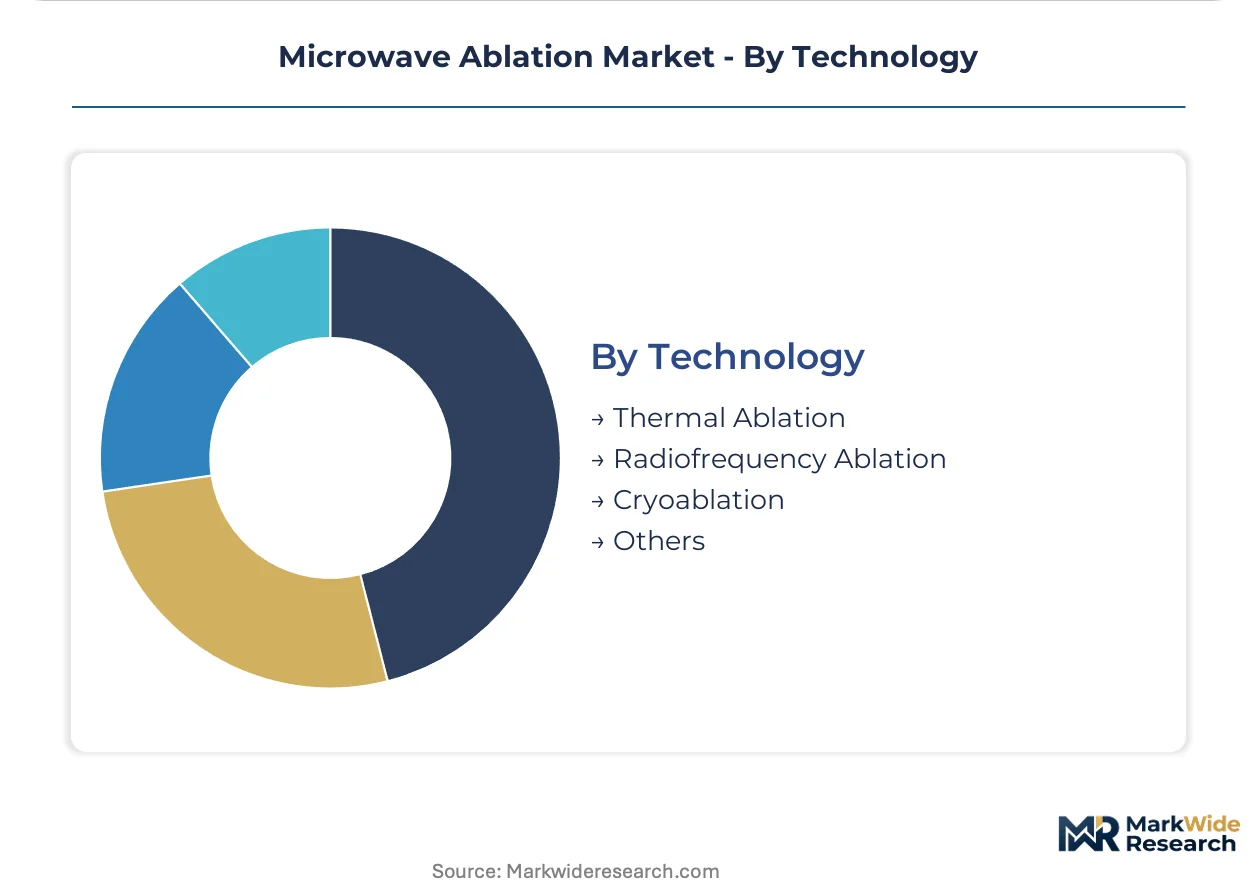
- Thermal Ablation:Microwave-specific thermal destruction achieves target temperatures of 60°C to 100°C for controlled coagulative necrosis, differentiating through larger ablation zones and reduced heat-sink effects compared to alternative modalities.
- Radiofrequency Ablation:Established RF protocols in cardiology and pain management compete for capital budget allocation, constraining microwave system penetration in electrophysiology departments.
- Cryoablation:Freeze-thaw tissue destruction offers visual ice-ball monitoring but requires longer procedure times and argon gas infrastructure.
- Others:Emerging energy modalities including irreversible electroporation and laser ablation occupy niche indications without microwave's procedural volume scale.
Thermal Ablation commands technology-specific installed base. Radiofrequency Ablation retains parallel presence across cardiac applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement committees exhibit the lowest price elasticity for microwave ablation generators, while Chinese provincial tenders force aggressive localization requirements. Germany and Japan occupy intermediate positions where reimbursement codification moderates budget sensitivity.
United States
Tertiary hospital interventional radiology suites in Houston and Boston drive generator demand through repeat hepatocellular carcinoma protocols. FDA 510(k) clearances for expanded oncologic indications accelerate clinical adoption timelines. The Texas Medical Center cluster anchors procedural volume concentration in the Southwest.
Germany
University hospitals in Munich and Heidelberg concentrate liver cancer ablation capacity with established reimbursement pathways. The EU Medical Device Regulation mandates clinical evidence thresholds that elevate post-market surveillance obligations. Baden-Württemberg hosts the densest concentration of navigation-integrated platform deployments.
China
Jiangsu and Guangdong provincial insurance schemes codify image-guided tumor ablation reimbursement, opening volume expansion for imported equipment. The National Medical Products Administration enforces GB standards for electromagnetic compatibility in 915 MHz systems. Shanghai's Ruijin Hospital anchors training pipelines for percutaneous thermal ablation credentialing.
Japan
Academic medical centers in Tokyo and Osaka deploy real-time thermometry systems to compress procedure times. The Pharmaceuticals and Medical Devices Agency maintains stringent clinical evidence requirements for microwave ablation system approvals. The Kanto region concentrates navigation platform integration with existing CT suites.
Microwave Ablation Market Key Industry Players
Capability concentration sits with integrated navigation platform vendors; scale advantage sits with diversified medical technology conglomerates. The market structure stratifies between capital equipment specialists and multipoint energy modality portfolios. Three archetypes dominate: pure-play ablation device firms, imaging system integrators, and diversified surgical technology suppliers. Competitive moves center on strategic partnerships for sensor fusion algorithms and geographic expansion through distributor networks in provincial Chinese markets.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson Services, Inc. exemplify scale-driven positioning through installed base leverage and recurring service revenue capture. Boston Scientific Corporation and AngioDynamics occupy the specialized applicator and navigation integration tier, representing capability-focused competitive positioning. These four entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| AngioDynamics |
| Medtronic |
| Emblation Ltd. |
| HUBER+SUHNER |
| Johnson & Johnson Services, Inc. |
| MedWaves, Inc. |
| Boston Scientific Corporation |
| NeuWave Medical |
| Varian Medical Systems, Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in precision coaxial cable manufacturing for 2.45 GHz applicator assemblies tightens supplier pricing power while forcing microwave ablation OEMs into long-term offtake commitments. This utilization squeeze propagates through generator procurement committees as electromagnetic compatibility testing costs inflate capital equipment quotes.
Pricing Analysis
Aftermarket calibration contracts and thermometry software subscriptions drive lifetime value capture beyond initial generator sales. Three-tier pricing structure across premium navigation-integrated systems, standard generator-applicator bundles, and economy-tier disposable electrodes stratifies hospital procurement tiers. Cost compression in entry-level generator segments intensifies as Chinese provincial tenders force localization compliance. Academic medical centers in Germany and the United States exhibit lowest price sensitivity due to bundled service agreements, while ambulatory surgical centers in China face acute budget constraints.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities enable precision component suppliers to buffer working capital strain. Manufacturing concentrates in the United States for generator systems, Germany for navigation platform integration, and China for coaxial cable assemblies. Production draws from rare earth magnet suppliers, high-purity copper for electrodes, and medical-grade polymers for applicator sheathing. Single-source vulnerability in 2.45 GHz precision cable sourcing creates structural risk. Distribution runs through hospital GPO contracts in North America, direct tender participation in China, and specialized interventional radiology distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microwave ablation markets sustain defensive moats through regulatory entrenchment, where FDA 510(k) clearances and EU MDR clinical evidence thresholds create multi-year barriers to competitive entry.
For Market Incumbents: Harden installed base retention by embedding subscription-based thermometry upgrades that extend generator lifecycles beyond traditional replacement cycles. Fortify calibration contract unbundling to capture recurring revenue as hospital procurement committees shift toward total cost-of-ownership metrics. Vertical integration into precision coaxial cable sourcing mitigates single-supplier vulnerability threatening production continuity.
For New Entrants and Emerging Players: China's Jiangsu and Guangdong provincial insurance schemes represent underpenetrated volume expansion corridors where reimbursement codification for image-guided tumor ablation remains nascent. Target ambulatory surgical center capacity buildouts with capital equipment sharing models that reduce individual facility investment burdens. Pursue navigation platform partnerships with established CT imaging vendors to bypass legacy PACS integration barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated navigation platform vendors with embedded thermometry software subscriptions. Five-to-ten year viability favors firms with diversified applicator portfolios spanning liver, lung, and kidney cancer indications rather than single-modality pure-plays. Monitor FDA 510(k) clearance velocity for expanded oncologic indications as inflection signal for clinical protocol adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Expansion | Clearances for hepatocellular carcinoma and lung lesion indications accelerate tertiary hospital adoption curves. |
| Navigation Platform Integration | CT-guided microwave delivery systems command premium positioning in academic medical center procurement. |
| Calibration Contract Unbundling | Aftermarket service revenue streams reshape margin capture beyond initial capital equipment sales. |
| Provincial Reimbursement Strategy | Codification in Jiangsu and Guangdong insurance schemes unlocks volume expansion for imported equipment. |
| Real-Time Thermometry Development | Closed-loop temperature feedback algorithms compress operator learning curves and procedure times. |
Research Approach
Desk research of FDA 510(k) filings, EU MDR technical documentation, and Chinese NMPA registration databases preceded structured interviews with interventional radiologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement schedules, and provincial insurance scheme announcements. Bottom-up procedure volume estimates triangulated against top-down generator shipment data.
Assumptions held reimbursement codification timelines and regulatory clearance velocities constant across the projection horizon while varying ambulatory surgical center capacity buildout rates and interventional radiologist training pipeline throughput. Segmentation modeling incorporated product type tiers, oncologic application categories, end-user site-of-care distinctions, and technology modality competitive dynamics. CAGRs derived from fitted growth curves anchored to disclosed procedural volume trends and equipment replacement cycles.
Practitioners should monitor FDA 510(k) clearance delays, EU MDR reclassification rulings, and Chinese provincial insurance scheme expansions for early signals requiring forecast adjustment. Macroeconomic contraction affecting hospital capital budgets, regulatory deviation from established electromagnetic compatibility standards, or technological displacement by irreversible electroporation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Otoplasty Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Spinal Cord Compression Market