
 Elderly Walker Market | 2026-2036
Elderly Walker Market Size, Share, and Industry Trends Forecast 2026-2036
Elderly Walker Market Analytics
ISO 11199-2 certification for walking aids is bifurcating the competitive landscape into qualified suppliers and marginal entrants. Invacare Corporation leverages its vertically integrated manufacturing footprint across North American distribution channels. Drive DeVilbiss Healthcare anchors its position through specialized rehabilitation partnerships with institutional buyers. Medline Industries competes on scale, sustaining one of the broadest SKU ranges across the standard and rolling walker categories.
An elderly walker constitutes a mobility assistance frame with handgrips, adjustable height settings, and either fixed or wheeled bases engineered from aluminum tubing or steel alloys to support partial body-weight transfer during ambulation. Four-wheel walkers with integrated seating and braking systems command the widest margin pools due to component complexity and replacement-part aftermarket value. Aluminum construction dominates unit economics across product types, while rehabilitation centers represent the most price-sensitive end-user channel relative to home care providers and assisted living facilities.
The FDA's 510(k) notification requirements and the EU Medical Device Regulation (MDR) Class I rules jointly determine which manufacturers can access reimbursed distribution channels in the United States and European Union member states. The Centers for Medicare & Medicaid Services (CMS) durable medical equipment fee schedule directly constrains pricing flexibility for suppliers targeting the senior citizen segment. Stakeholders must monitor pending CMS competitive bidding program expansions and evolving MDR technical documentation requirements to anticipate which product configurations will retain market access.
Market Dynamics
The aging-in-place movement is restructuring walker procurement toward home care channels, while Medicare Part B reimbursement constraints compress pricing flexibility across all supplier tiers.
Growth Catalysts
- CMS Durable Medical Equipment Fee Schedule:Medicare Part B coverage for walkers with prescribed medical necessity sustains baseline demand volumes among seniors with mobility limitations.
- Aluminum Tubing Advances:Lightweight alloy formulations reduce unit shipping costs and expand same-day retail availability through pharmacy chains.
- Home Care Provider Networks:Post-acute care agencies are scaling walker provision as hospital discharge planners prioritize home-based recovery protocols.
Market Restraints
- Raw Material Concentration:Primary aluminum smelting capacity clusters in China and Russia, exposing manufacturers to tariff volatility and energy-cost spikes.
- EU MDR Technical Documentation:Expanded clinical evidence requirements for Class I devices extend clearance timelines and raise compliance expenditures for European market entry.
- Rollator Substitution:Powered mobility scooters capture higher-acuity patients who might otherwise progress through walker-assisted rehabilitation.
Strategic Opportunities
- Telehealth Integration:Remote physical therapy platforms create direct-to-patient distribution channels bypassing traditional durable medical equipment suppliers.
- ISO 11199-2 Premium Tier:Certified walking aids command reimbursement premiums in Germany and Scandinavia where clinical outcome metrics influence procurement decisions.
- Aging-in-Place Retrofit Services:Home modification contractors in Japan bundle walker provision with bathroom grab-bar installation and ramp construction.
Industry Challenges
- Biomechanical Engineering Talent:Shortage of specialists combining anthropometric data analysis with tubular frame stress modeling delays product iteration cycles.
- 510(k) Predicate Device Strategy:FDA clearance pathways require demonstrating substantial equivalence to existing devices, constraining radical design innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elderly Walker Market |
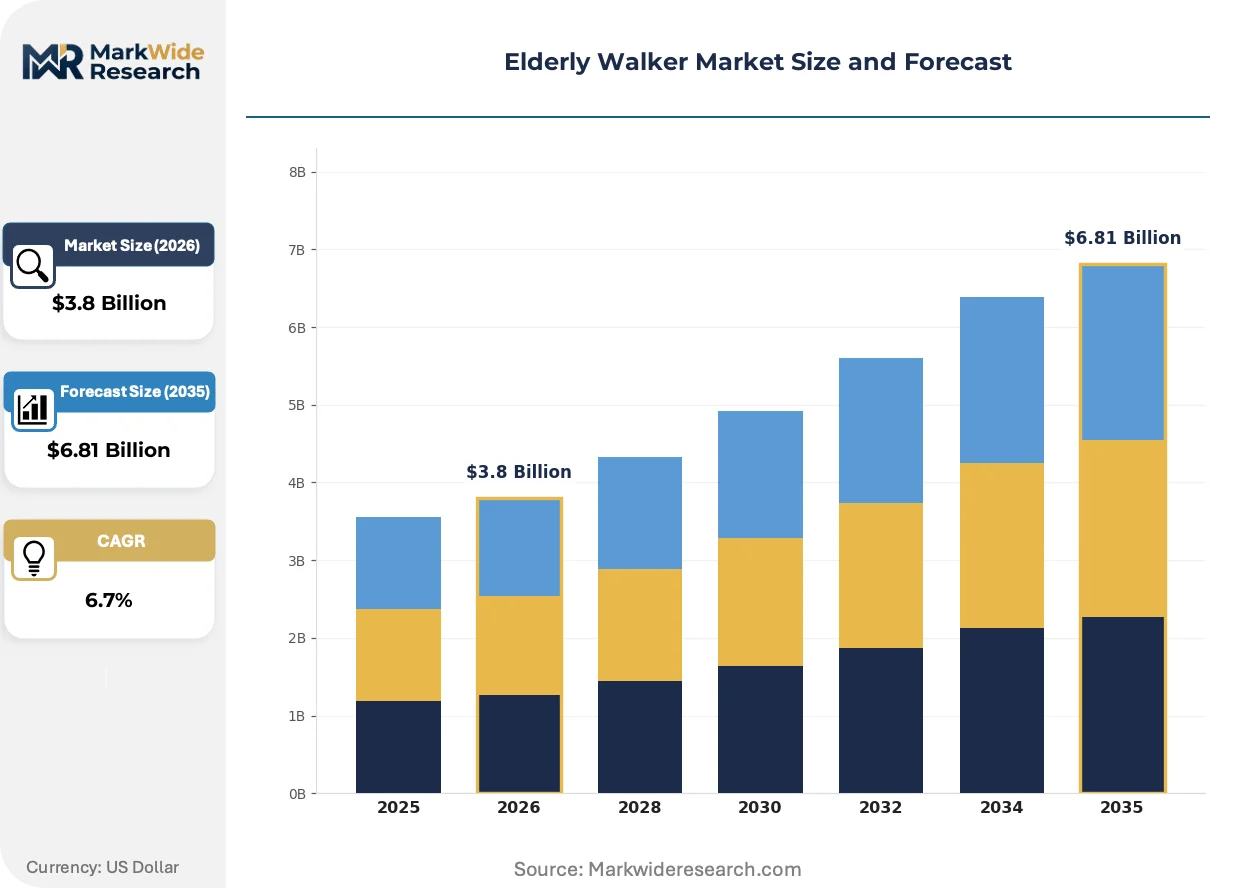
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheel Walkers, Four-Wheel Walkers, Rolling Walkers, Standard Walkers Material: Aluminum, Steel, Wood, Plastic End User: Senior Citizens, Rehabilitation Centers, Home Care Providers, Assisted Living Facilities Distribution Channel: Online Retail, Medical Supply Stores, Pharmacies, Direct Sales |
| Companies Covered | Invacare Corporation, Drive DeVilbiss Healthcare, Medline Industries, Carex Health Brands, Nova Medical Products, GF Health Products, Topro USA, Sunrise Medical, Hugo Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elderly Walker Market Evolving Landscape
Walker design is converging with digital health infrastructure and modular component systems, shifting competitive advantage from scale manufacturing toward software-integrated service delivery.
Carbon fiber-reinforced polymer tubing is fragmenting the traditional aluminum-dominated material hierarchy. Rehabilitation centers in Switzerland and the Netherlands are piloting these frames for bariatric patients requiring higher load-bearing capacity. The technology is fragmenting procurement patterns as insurers debate coverage parity with standard metal constructions.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing serialization investments across the supply chain. Manufacturers must now embed machine-readable codes on every walker frame to enable post-market surveillance traceability. German and French suppliers are absorbing these compliance costs fastest, while Italian and Spanish entrants face working-capital constraints.
Subscription-based equipment provision is replacing outright purchase in institutional channels. Assisted living facilities in Denmark and the Netherlands now lease walker fleets with bundled maintenance and upgrade rights. This model concentrates buying power with procurement consortia and compresses supplier margins through volume-commitment negotiations.
Elderly Walker Market Segmentation
Walker procurement patterns diverge sharply across patient acuity levels and care settings. Product configuration, material specification, and channel access determine which suppliers capture reimbursed versus retail transactions.
Product Type:
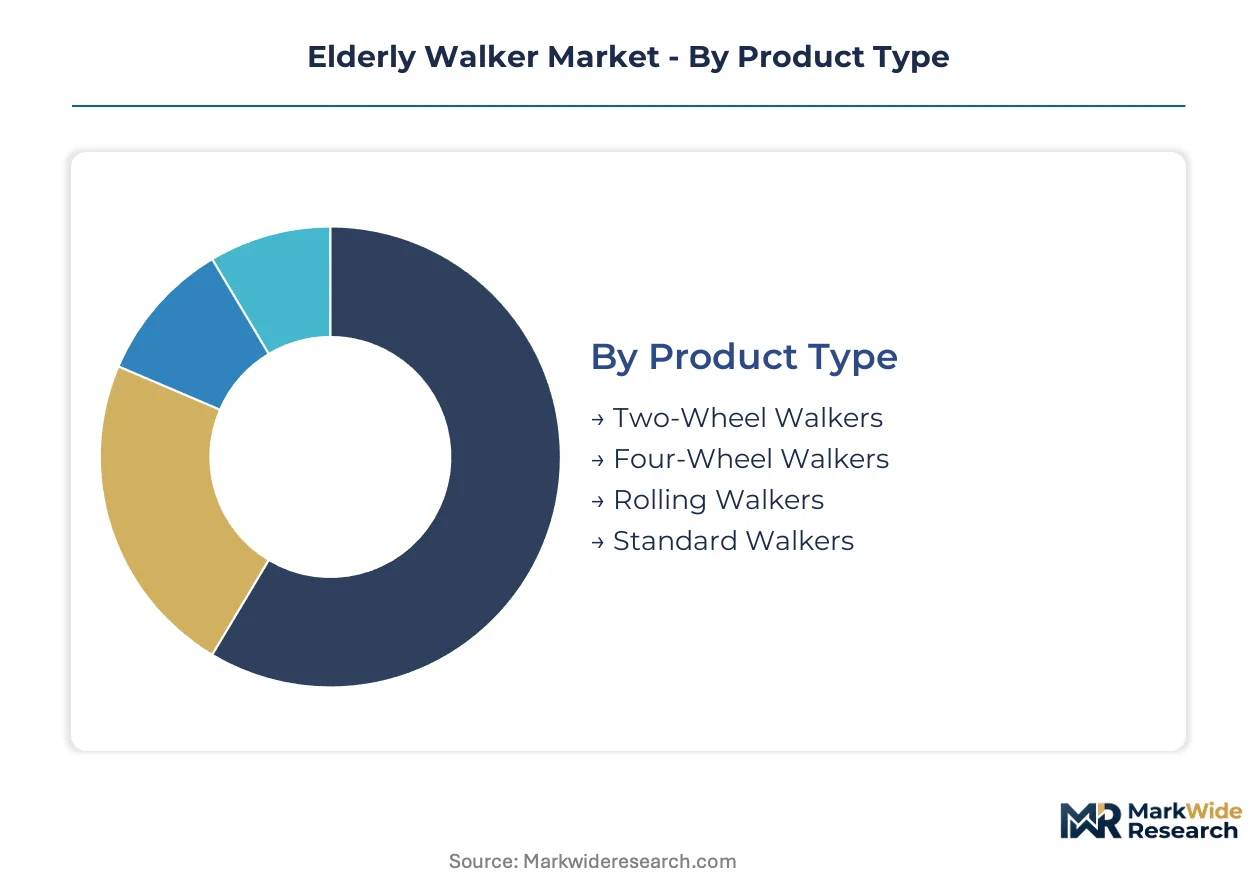
Margin pools concentrate in wheeled configurations with integrated braking and seating systems, where component complexity sustains aftermarket revenue streams.
- Four-Wheel Walkers:These rollators incorporate hand-operated brakes, padded seats, and storage compartments within a collapsible aluminum frame. Demand clusters among assisted living facilities in Florida and Arizona where outdoor mobility requirements are highest. Medicare Part B reimbursement for these devices requires documented medical necessity, filtering volume toward prescribed channels.
- Rolling Walkers:Three-wheel configurations prioritize maneuverability in confined residential spaces over load-bearing capacity. Home care providers in Germany and the Netherlands are scaling procurement of these lighter units for apartment-dwelling seniors. The ISO 11199-2 certification pathway in Scandinavia creates pricing premiums for clinically validated frame geometries.
- Two-Wheel Walkers:Front-wheel designs with rear glide tips balance stability against lift requirements during ambulation.
- Standard Walkers:Fixed-base frames without wheels serve post-surgical rehabilitation protocols requiring maximum weight-bearing restriction.
The dominant share belongs to Four-Wheel Walkers, while Rolling Walkers is closing the gap fastest.
Material:
Raw material selection governs shipping economics and durability warranties across institutional procurement contracts.
- Aluminum:Alloy tubing dominates unit economics through weight reduction that enables pharmacy chain same-day stocking. Demand concentrates in United States retail channels where CMS reimbursement constraints pressure landed cost optimization. Chinese primary smelting capacity exposes manufacturers to tariff volatility.
- Steel:Chromoly and carbon steel constructions serve bariatric patient segments exceeding standard load ratings. Rehabilitation centers in Switzerland specify these frames for institutional durability requirements. Higher unit weights restrict direct-to-patient shipping economics.
- Wood:Traditional constructions persist in Japanese long-term care facilities prioritizing aesthetic integration with residential interiors.
- Plastic:Injection-molded components appear primarily in grip surfaces, caster housings, and accessory attachments rather than primary load-bearing structures.
Aluminum commands institutional procurement volume, though Steel is expanding most quickly in specialized clinical applications.
End User:
Price sensitivity gradients separate reimbursed clinical channels from direct-pay retail transactions.
- Home Care Providers:Post-acute agencies coordinate walker provision with hospital discharge planning protocols. Demand is accelerating fastest in United States markets where aging-in-place preferences reshape post-operative care pathways. These buyers prioritize collapsible configurations for vehicle transport.
- Rehabilitation Centers:Clinical facilities demand ISO-certified frames with documented biomechanical testing for liability protection. German and Austrian procurement consortia negotiate volume commitments with maintenance-inclusive leasing terms. Budget constraints limit specification flexibility.
- Senior Citizens:Individual purchasers through retail channels prioritize aesthetic customization and accessory compatibility.
- Assisted Living Facilities:Campus-wide fleet management drives standardization around interchangeable component systems.
Home Care Providers hold the largest addressable demand base, with Rehabilitation Centers exhibiting the steepest expansion trajectory.
Distribution Channel:
Channel selection determines regulatory compliance burden and margin retention for manufacturers.
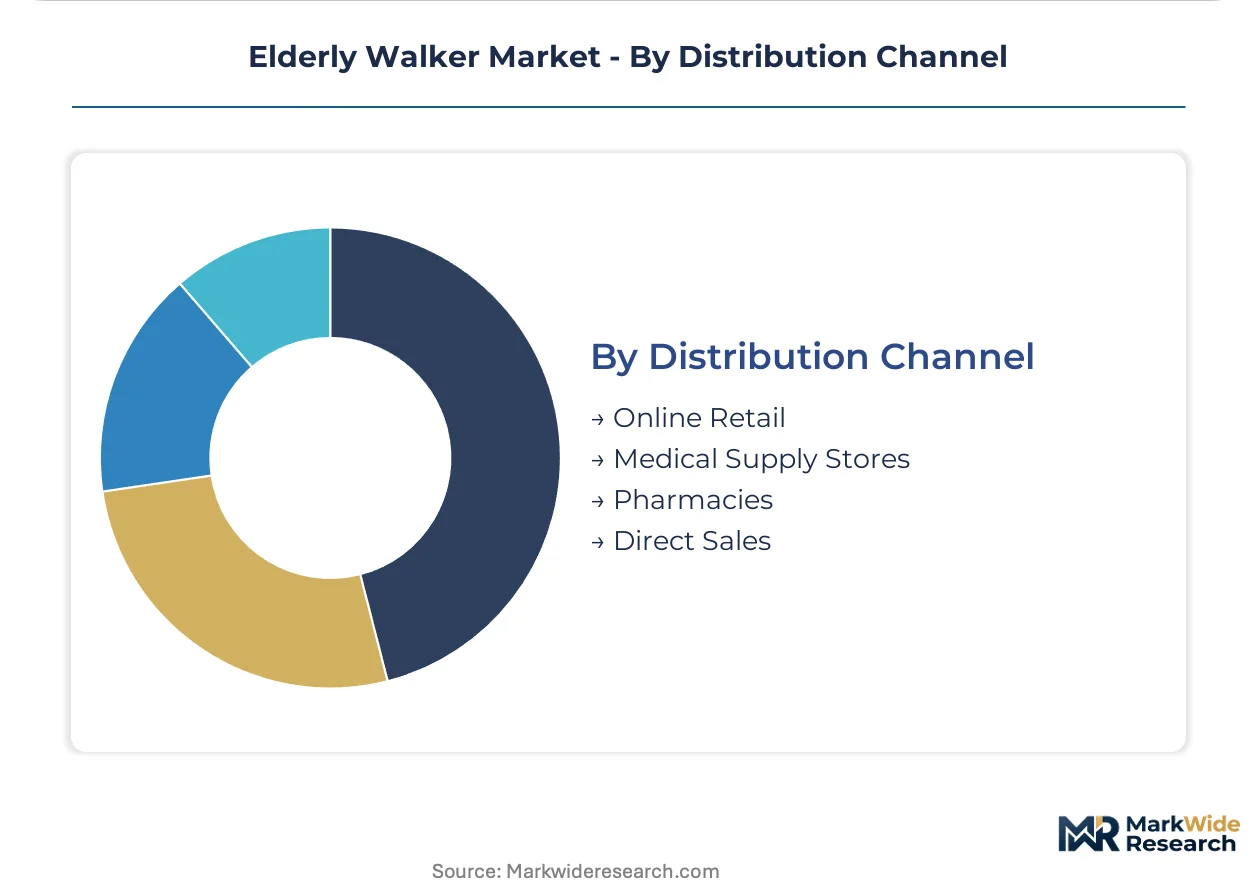
- Medical Supply Stores:Brick-and-mortar durable medical equipment dealers maintain FDA 510(k) documentation for reimbursed transactions. These outlets cluster in Medicare Advantage penetration corridors including Texas and Pennsylvania. Staff fitting services justify price premiums over retail alternatives.
- Pharmacies:Chain drugstore networks leverage existing senior foot traffic for accessory and replacement-part sales. CVS and Walgreens distribution infrastructure enables rapid inventory turns on lightweight aluminum configurations. Reimbursement processing capabilities vary by location.
- Online Retail:Direct-to-patient platforms bypass traditional supplier networks for cash-pay transactions.
- Direct Sales:Manufacturer field representatives serve institutional accounts with customized fleet management contracts.
Medical Supply Stores retain the highest reimbursement-accessible volume, while Pharmacies is gaining share fastest through convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home care providers concentrate procurement volume in the United States, Germany, and Japan where aging-in-place infrastructure and reimbursement frameworks align. Institutional buyers in the Netherlands and Australia are scaling fleet-management contracts that reshape supplier access patterns.
United States
Medicare Part B reimbursement sustains baseline demand among seniors with prescribed mobility limitations. The FDA's 510(k) clearance pathway filters market participants through substantial equivalence requirements. Florida and Arizona assisted living facilities drive four-wheel rollator procurement for outdoor mobility needs.
Germany
ISO 11199-2 certification creates pricing premiums for clinically validated frame geometries in reimbursed channels. The EU Medical Device Regulation's Unique Device Identification mandate forces serialization investments across Bavarian and North Rhine-Westphalian manufacturing clusters. German procurement consortia negotiate volume commitments with maintenance-inclusive leasing terms.
Japan
Home modification contractors bundle walker provision with bathroom retrofit services for apartment-dwelling seniors. The Ministry of Economy, Trade and Industry (METI) standards govern domestic medical device quality frameworks. Tokyo and Osaka metropolitan areas concentrate long-term care facility demand for aesthetic-integrated wooden frame constructions.
Netherlands
Subscription-based equipment provision is replacing outright purchase in assisted living channels. The EU MDR Class I rules determine reimbursement access for Dutch institutional buyers. Eindhoven Region suppliers absorb compliance costs fastest through integrated traceability systems.
Australia
Rehabilitation centers in Sydney and Melbourne pilot carbon fiber-reinforced polymer frames for bariatric patient segments. The Therapeutic Goods Administration (TGA) regulates medical device market entry. Victorian and New South Wales procurement networks debate coverage parity between composite and standard metal constructions.
Elderly Walker Market Competitive Landscape
Player mix skews toward diversified durable medical equipment conglomerates with vertically integrated manufacturing footprints. The competitive structure concentrates around three to five dominant suppliers controlling reimbursed distribution channels, while regional fabricators capture retail and direct-pay segments. Strategic archetypes include scale-driven SKU breadth competitors, rehabilitation partnership specialists, and premium-certified frame engineers. M&A activity targets ISO-certified European assets, and capacity expansion concentrates on lightweight aluminum alloy tubing production.
Among North American diversified suppliers, Invacare Corporation and Drive DeVilbiss Healthcare exemplify the conglomerate archetype with broad institutional channel access. Medline Industries occupies a position representing scale-driven SKU breadth across standard and rolling walker categories. Carex Health Brands and Nova Medical Products sit within the retail-focused tier targeting pharmacy chain distribution and direct-to-patient channels.
| Leading Market Players |
|---|
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Medline Industries |
| Carex Health Brands |
| Nova Medical Products |
| GF Health Products |
| Topro USA |
| Sunrise Medical |
| Hugo Mobility |
| Others |
Value Network & Pricing Analysis
Chinese primary aluminum smelting capacity at 60 million annual tons shapes global walker manufacturing economics, compressing price floors for standard aluminum frames while creating margin pools for certified European producers with ISO 11199-2 documentation. Scale concentration in Yangtze River Delta fabrication clusters feeds downstream cost-plus contracting indexed to London Metal Exchange aluminum pricing, leaving smaller regional fabricators exposed to energy-cost volatility and tariff discontinuities.
Pricing Analysis
Cost-plus contracts with LME aluminum indexation dominate institutional procurement, particularly for Medicare Part B reimbursed transactions where CMS fee schedules cap pass-through flexibility. Price differentiation separates ISO 11199-2 certified frames from uncertified alternatives in German and Scandinavian markets, while volume-scale discounts concentrate buying power with Dutch and Danish procurement consortia. Pricing pressure stems from raw material tariff exposure on Chinese aluminum imports, with rehabilitation centers exhibiting highest price sensitivity due to fixed clinical budgets and assisted living facilities showing lowest sensitivity through subscription-based leasing models.
Supply Chain Analysis
Just-in-time inventory strategies prevail among United States pharmacy chains stocking lightweight aluminum configurations, while European institutional buyers maintain strategic stockpiles of ISO-certified frames to buffer EU MDR compliance timeline uncertainty. Primary aluminum supply concentrates in China, Russia, and Canada, with secondary fabrication clustering in Vietnam and Mexico for tariff-advantaged access to North American markets. Component dependencies include precision caster assemblies from Taiwan, polymer grip compounds from South Korea, and braking systems from German automotive tier suppliers. Single-source vulnerability concentrates in Chinese primary smelting capacity exposed to energy-cost spikes and export restriction risk. Distribution runs through three-tier structures: manufacturer-direct for institutional fleet contracts, medical supply dealers for reimbursed retail, and pharmacy chains for cash-pay transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elderly walker market functions as a regulatory-moat business where FDA 510(k) clearance and ISO 11199-2 certification create entrenched switching costs for institutional buyers, with Medicare Part B reimbursement access acting as a network-effect barrier that compounds over successive procurement cycles.
For Market Incumbents: Shield market position by deepening backward integration into aluminum alloy tubing production across North American manufacturing footprints, capturing margin compression from tariff-exposed Chinese supply. Prioritize ISO 11199-2 certification maintenance and EU MDR technical documentation investment to defend against emerging carbon fiber substitute technologies in bariatric segments. Channel control through exclusive rehabilitation center partnerships remains the priority lever against retail-focused new entrants. For New Entrants and Emerging Players: FDA 510(k) predicate device fast-tracks offer the most penetrable pathway for rollator variants with integrated digital health sensors, targeting home care provider networks in United States markets where aging-in-place procurement is accelerating fastest. Telehealth-integrated distribution models bypass traditional durable medical equipment supplier gatekeepers. White-space exists in subscription-based fleet provision for assisted living facilities in Japan and the Netherlands, where maintenance-inclusive leasing contracts concentrate buying power with procurement consortia seeking vendor consolidation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified durable medical equipment conglomerates with vertically integrated manufacturing and established reimbursement channel access over pure-play walker specialists facing raw material concentration risk. Long-term viability hinges on regulatory entrenchment durability across multiple jurisdiction clearances. Acquisition target archetype: ISO 11199-2 certified European fabricators with German or Scandinavian procurement consortia relationships. The signal to watch is CMS competitive bidding program expansion into walker categories, which would compress margins and accelerate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | 510(k) clearance unlocks Medicare Part B reimbursed distribution channels for institutional buyers. |
| CE Marking Pathway | EU MDR Class I technical documentation enables access to German and Scandinavian procurement consortia. |
| Hospital System Partnership | Post-acute care agreements with discharge planners secure home care provider volume commitments. |
| Software Companion Development | Telehealth platform integration creates direct-to-patient channels bypassing traditional suppliers. |
| Reimbursement Strategy | Medicare Part B medical necessity documentation maximizes prescription-based transaction capture. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, home care agency procurement directors, biomedical engineers at rehabilitation centers, GPO contracts managers, and durable medical equipment dealer principals. Secondary validation drew from FDA 510(k) device listings, CMS Medicare fee schedule databases, EU MDR notified body certificates, hospital procurement contract disclosures, and aluminum trade flow customs records. Bottom-up unit shipment estimates triangulated against top-down reimbursement claim volume analytics.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, material specification, end-user channel, and geographic regulatory cluster dimensions. CAGRs derived from historical Medicare Part B claim trajectory analysis, aluminum price elasticity modeling, and aging-in-place infrastructure investment correlation. Industry-specific forecast inputs included CMS competitive bidding program expansion probability and EU MDR Unique Device Identification compliance cost absorption rates.
The analysis sits within stated boundaries; outcomes outside sustained Medicare Part B reimbursement stability, aluminum tariff regime continuity, or EU MDR enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding institutional procurement pattern persistence and raw material supply concentration. Revision becomes warranted when CMS policy crosses threshold uncertainty or when Chinese aluminum export restrictions disrupt fabrication economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Cooling Mattress Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Medical Products Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Pressure Ulcer Prevention Market