
 Global Adalimumab Drugs Market | 2026-2036
Global Adalimumab Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adalimumab Drugs Market Foresight
Biosimilar-grade formulation quality is bifurcating the competitive landscape as manufacturers compete on analytical similarity and immunogenicity profiles. AbbVie Inc sustains its originator position through extensive patent estate management and formulation refinements. Samsung Bioepis differentiates via accelerated biosimilar development timelines and strategic European partnerships. Fresenius Kabi anchors its presence through integrated manufacturing from active pharmaceutical ingredient to finished dosage form.
Adalimumab is a recombinant human monoclonal antibody targeting tumor necrosis factor-alpha (TNF-α), produced through mammalian cell culture expression systems with glycosylation patterns critical for effector function. The molecule binds soluble and transmembrane TNF-α to inhibit inflammatory cytokine signaling in autoimmune pathologies. Biosimilars now command structural attention as pricing pressure and interchangeability designations reshape rheumatoid arthritis and psoriasis prescribing patterns. Auto-injectors and pre-filled syringes concentrate margin pools through patient adherence programs and reduced healthcare administration costs. Hospital procurement of original biologics persists in ulcerative colitis where physician confidence in immunogenicity profiles remains decisive.
The FDA's biosimilar approval framework and the EMA's biosimilar comparability guidelines shape product development costs and market access timelines across developed markets. WHO prequalification standards influence procurement eligibility in emerging health systems expanding biologic access. Japan's PMDA maintains distinct immunogenicity assessment requirements that filter entrants capable of sustained commercial presence. Stakeholders must monitor interchangeability study outcomes and real-world evidence generation as determinants of formulary positioning and physician switching behavior.
Market Dynamics
The FDA's biosimilar interchangeability pathway and EMA's comparability guidelines are compressing originator exclusivity windows while fragmenting prescribing authority across rheumatology, dermatology, and gastroenterology departments.
Growth Catalysts
- Autoimmune prevalence expansion:Rising diagnosed cases of rheumatoid arthritis and psoriasis in aging populations are expanding addressable patient pools across hospital systems.
- EMA biosimilar framework:Accelerated European market entry timelines for approved biosimilars are compressing competitive lag behind US launches.
- Pre-filled delivery devices:Auto-injector and syringe formats are improving adherence rates and reducing infusion center dependency for chronic therapy management.
Market Restraints
- Mammalian cell culture capacity:Limited contract manufacturing organization availability for glycosylation-critical biologics is constraining biosimilar supply scaling.
- PMDA immunogenicity requirements:Japan's distinct antibody response assessment protocols are extending development timelines for entrants lacking local clinical data.
- Originator patent estate:AbbVie's formulation and device patent clusters are creating litigation friction zones for biosimilar launch timing.
Strategic Opportunities
- Indian biologics procurement:WHO prequalification pathways are opening institutional tender access for cost-optimized biosimilars in emerging health systems.
- Ulcerative colitis subsegment:Physician confidence gaps in biosimilar immunogenicity profiles preserve premium positioning for originator biologics in severe IBD cases.
- Real-world evidence mandates:FDA's emphasis on post-market interchangeability data is creating competitive differentiation through patient registry investments.
Industry Challenges
- Analytical similarity expertise:Biosimilar developers face acute shortages of mass spectrometry and glycan mapping specialists for comparability protocol execution.
- Cold chain integrity:Temperature excursion risks during multi-node distribution to rheumatology clinics are elevating logistics insurance and monitoring costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adalimumab Drugs Market |
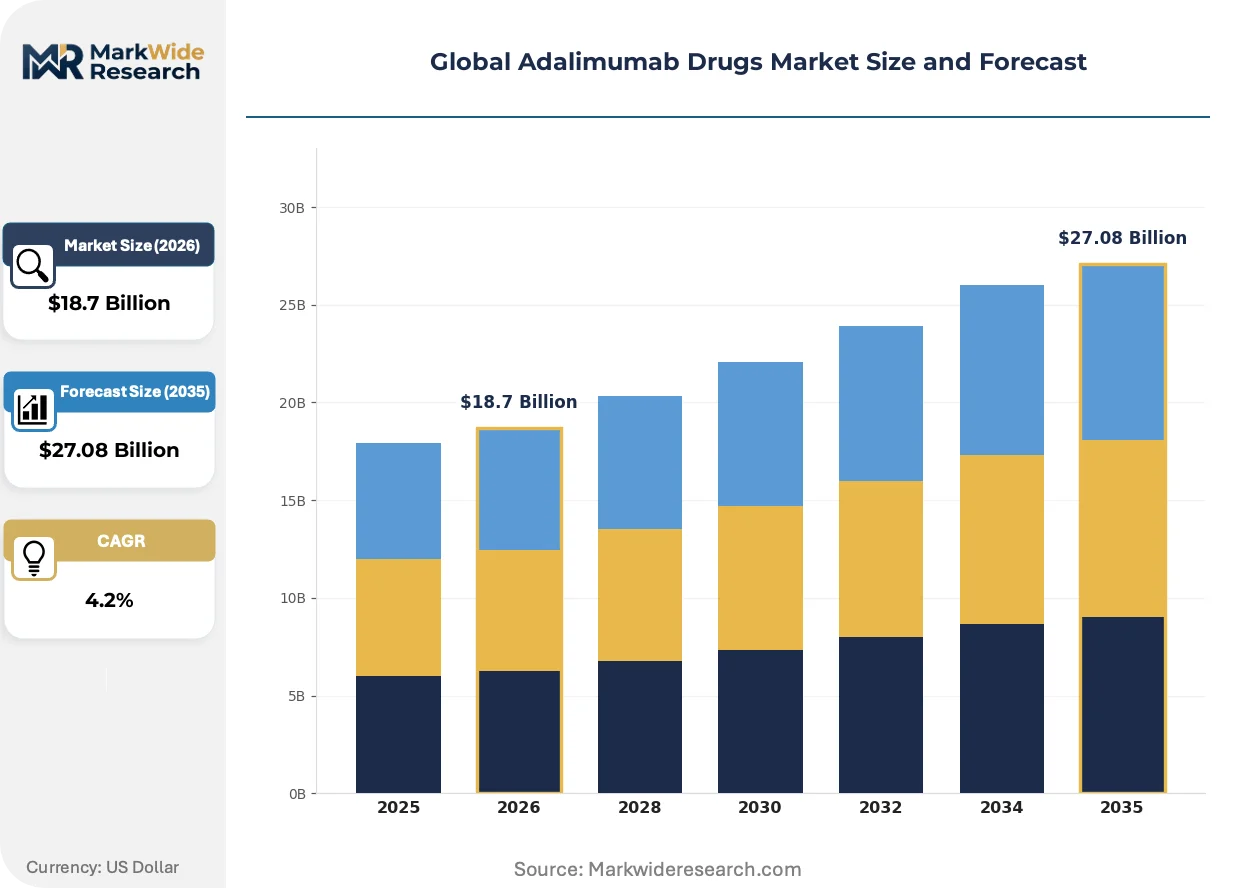
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Original Biologics, Biosimilars, Generic Versions, Recombinant Forms Therapy Area: Rheumatoid Arthritis, Psoriasis, Crohn's Disease, Ankylosing Spondylitis, Ulcerative Colitis Delivery Mode: Pre-filled Syringes, Vials, Auto-injectors, Pen Injectors End User: Hospitals, Specialty Clinics, Ambulatory Care Centers, Home Healthcare Providers |
| Companies Covered | AbbVie Inc, Amgen Inc, Pfizer Inc, Boehringer Ingelheim, Sandoz, Fresenius Kabi, Samsung Bioepis, Zydus Lifesciences Ltd, Hetero Healthcare Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adalimumab Drugs Market Shifts & Advancements
Biologic manufacturing and prescribing patterns are converging around analytical precision, regulatory data generation, and patient-administered delivery formats that reduce healthcare system touchpoints.
High-resolution mass spectrometry and peptide mapping protocols are supplanting lower-sensitivity analytical methods for biosimilar comparability demonstrations. Samsung Bioepis and Fresenius Kabi are deploying these platforms to accelerate FDA and EMA filing timelines. The shift is compressing the traditional 12-18 month analytical development phase while raising capital barriers for entrants lacking in-house protein characterization infrastructure.
REACH registration requirements for novel excipients and device materials are forcing reformulation investments across European supply chains. The regulation's industrial consequence is a bifurcation between legacy formulations grandfathered under prior frameworks and next-generation presentations requiring full chemical safety dossiers. Germany and France are seeing accelerated transitions to citrate-free buffer systems as manufacturers preempt regulatory scrutiny on histidine-based formulations.
Hospital formulary committees are consolidating biologic purchasing through centralized procurement contracts that bundle originator and biosimilar access. This concentration is displacing individual physician prescribing autonomy in favor of pharmacy-driven therapeutic substitution protocols. The pattern is most visible in United States integrated delivery networks where pharmacy benefit managers negotiate exclusive biosimilar tiers based on rebate structures rather than clinical differentiation.
Global Adalimumab Drugs Market Segmentation
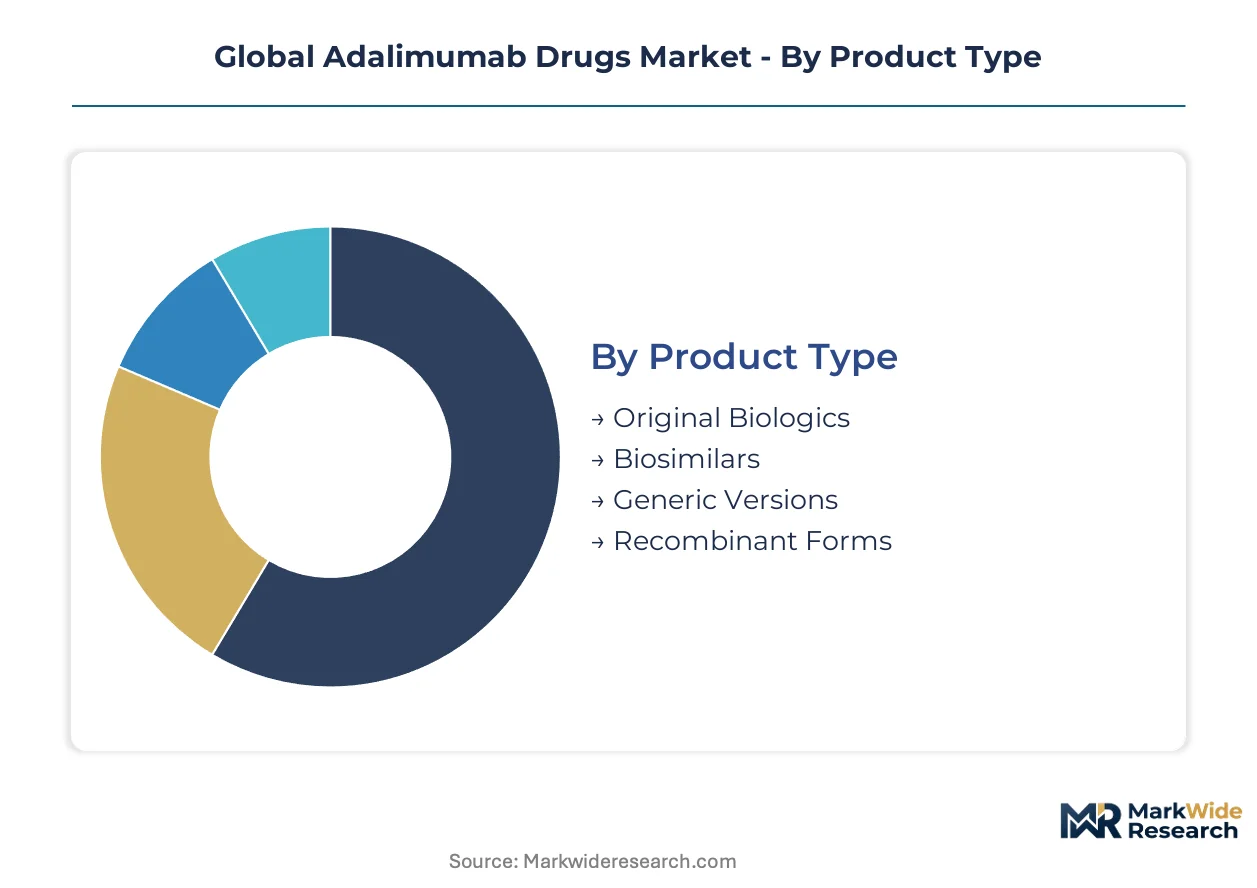
Adalimumab market segmentation reveals distinct channel economics and prescribing authority patterns. Each dimension—molecule origin, clinical indication, delivery format, and care setting—carries unique margin structures and regulatory access requirements that shape commercial strategy.
Product Type:
Channel mix varies sharply by originator status, with original biologics flowing through hospital pharmacy committees and biosimilars penetrating retail specialty pharmacy networks.
- Original Biologics:AbbVie's Humira and equivalent originator molecules command premium pricing through patent-protected formulations and established immunogenicity profiles. Rheumatology departments in United States academic medical centers maintain strong formulary preference for originator biologics in high-risk autoimmune cases.
- Biosimilars:Samsung Bioepis, Fresenius Kabi, and Amgen biosimilar entries compete on analytical similarity and interchangeability designations. German sickness funds and United States pharmacy benefit managers are consolidating biosimilar purchasing through exclusive tier placement.
- Generic Versions:Post-patent small-molecule formulations face limited clinical acceptance for TNF-α inhibition due to immunogenicity concerns.
- Recombinant Forms:Alternative expression system variants target supply security and glycosylation consistency for emerging market tenders.
By volume, biosimilars lead in European tenders. By growth pace, original biologics in ulcerative colitis applications are expanding most quickly.
Therapy Area:
Cost tier stratification separates premium-priced severe inflammatory indications from higher-volume maintenance therapy segments.
- Rheumatoid Arthritis:The largest addressable population with established TNF-α inhibition protocols. Japanese rheumatology societies maintain conservative switching guidelines that preserve originator share.
- Psoriasis:Dermatology prescribing concentrates in United States and Germany where biologic penetration in moderate-to-severe cases exceeds 60 percent. Biosimilar uptake is accelerating through integrated delivery network formularies.
- Crohn's Disease:Gastroenterology departments prioritize immunogenicity track records in fistulizing disease. Pediatric Crohn's populations in France and Italy remain originator-dominant.
- Ankylosing Spondylitis:Axial spondyloarthritis expansion is widening diagnostic capture in South Korea and United Kingdom rheumatology practices.
- Ulcerative Colitis:Severe IBD cases preserve the steepest originator premium due to physician confidence gaps in biosimilar switching. Hospital procurement in United States and Japan maintains originator preference for acute severe colitis.
Rheumatoid arthritis generates highest absolute revenue. Ulcerative colitis shows the steepest expansion trajectory among severe autoimmune indications.
Delivery Mode:
Patient-administered formats are displacing infusion center dependency and capturing margin through adherence program bundling.
- Pre-filled Syringes:Citrate-free buffer formulations dominate European markets where REACH registration is forcing excipient transitions. German and French tenders specify pre-filled syringes for 80 percent of ambulatory biologic volumes.
- Auto-injectors:Device-locked combinations extend patent protection and improve adherence metrics. United States specialty pharmacy networks favor auto-injector formats for prior authorization efficiency.
- Vials:Hospital infusion centers retain vial preference for dose flexibility in acute settings. Japanese hospital procurement maintains vile-based purchasing for in-clinic administration.
- Pen Injectors:Next-generation connected devices with adherence tracking are penetrating United States and Netherlands markets through value-based contract structures.
Auto-injectors lead by volume in United States retail channels. Pen injectors are gaining share fastest through digital health integration.
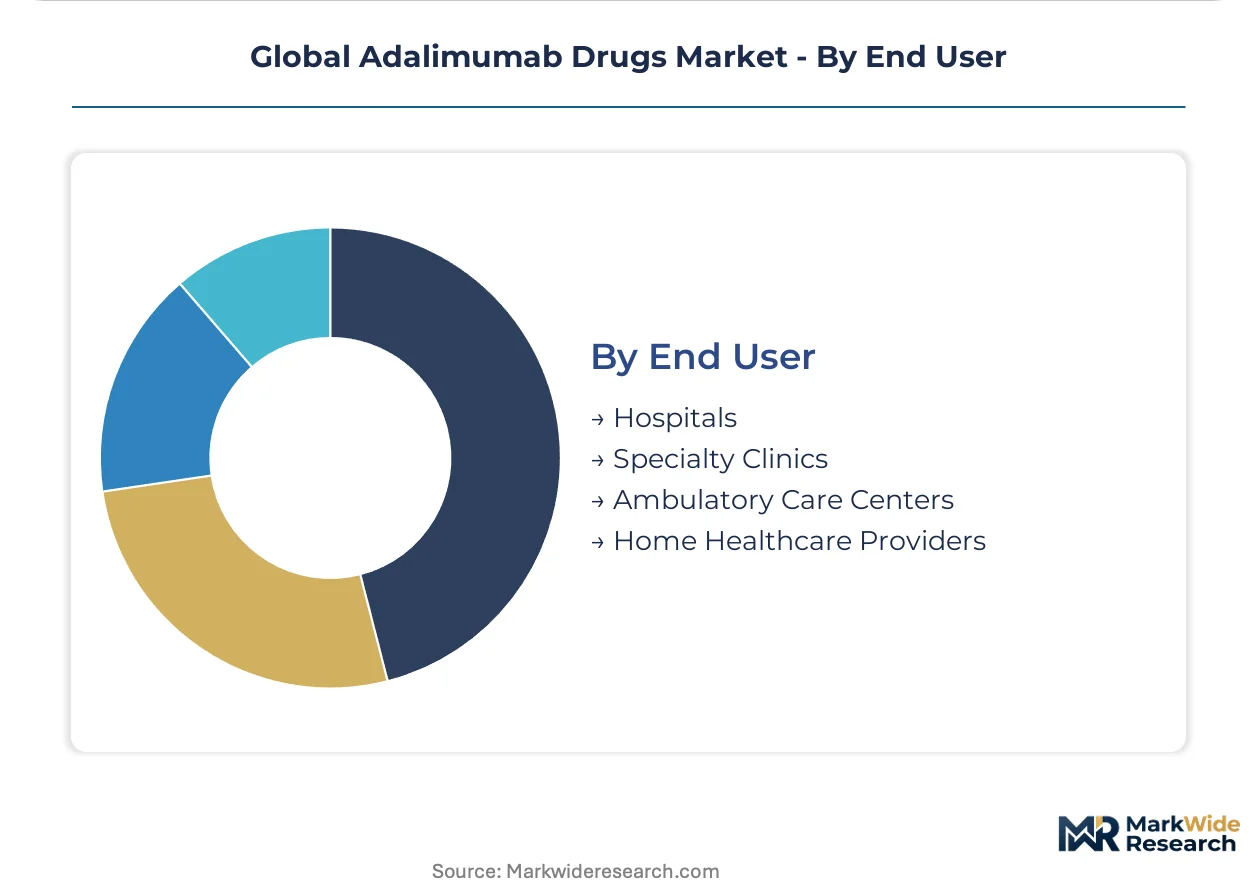
End User:
Customer type determines procurement authority concentration and switching protocol rigidity.
- Hospitals:Centralized pharmacy committees in United States integrated delivery networks and German university hospitals control biologic purchasing through therapeutic substitution protocols. Formulary lock-in periods extend 12-24 months.
- Specialty Clinics:Rheumatology and dermatology group practices in United States and United Kingdom retain prescribing autonomy for originator biologics in complex cases.
- Ambulatory Care Centers:Outpatient infusion facilities in France and Italy are consolidating biosimilar purchasing through regional tender structures.
- Home Healthcare Providers:United States home infusion networks and Dutch domiciliary care services are expanding self-administration support for pre-filled syringe and auto-injector formats.
Hospitals dominate by volume through committee purchasing. Home healthcare providers are climbing the fastest as self-administration protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for glycosylation-critical biologics clusters in the United States, Germany, and Japan where mammalian cell culture infrastructure and regulatory expertise have concentrated. AbbVie's production network and biosimilar contract manufacturers anchor supply in these jurisdictions.
United States
FDA's biosimilar interchangeability pathway and pharmacy benefit manager consolidation are accelerating therapeutic substitution in rheumatoid arthritis and psoriasis. Integrated delivery networks in Texas and California negotiate exclusive biosimilar tiers through centralized procurement. Boston's biologics manufacturing corridor houses mammalian cell culture facilities serving both originator and biosimilar supply chains.
Germany
Sickness funds and university hospital pharmacy committees drive biosimilar penetration through tender-based purchasing in North Rhine-Westphalia and Bavaria. REACH registration requirements for citrate-free buffer formulations are forcing excipient transitions across European supply chains. Frankfurt's pharmaceutical logistics hub manages cold chain distribution to rheumatology clinics throughout the Rhine-Ruhr metropolitan region.
Japan
PMDA's distinct immunogenicity assessment protocols filter biosimilar entrants capable of sustained commercial presence in severe IBD applications. Tokyo and Osaka rheumatology societies maintain conservative switching guidelines that preserve originator share in pediatric Crohn's populations. Kanto region hospitals concentrate biologic procurement through centralized pharmacy committees with 12-24 month formulary lock-in periods.
United Kingdom
NICE cost-effectiveness thresholds and NHS England biosimilar switching programs compress originator prescribing in rheumatoid arthritis maintenance therapy. London and Manchester integrated care systems bundle originator and biosimilar access through pharmacy-driven substitution protocols. The Midlands region sees expanding ambulatory care center consolidation of biosimilar purchasing through regional tender structures.
South Korea
MFDS accelerated approval pathways and domestic biologics manufacturing investments are expanding biosimilar export capacity to Southeast Asian tenders. Seoul Capital Area rheumatology practices lead axial spondyloarthritis diagnostic capture and biologic penetration. Busan-Ulsan's biopharmaceutical cluster houses contract manufacturing organizations serving global biosimilar developers.
Global Adalimumab Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the adalimumab landscape. Originators with patent-protected formulations and established immunogenicity profiles command premium positioning in severe IBD cases. Biosimilar specialists compete on analytical similarity demonstration and interchangeability designation speed. Three archetypes dominate: originator incumbents with device-locked combinations, biosimilar developers with accelerated regulatory timelines, and integrated manufacturers controlling API-to-finished-dosage production. Competitive moves concentrate on patent estate litigation and real-world evidence generation for formulary positioning.
Within the originator tier, AbbVie Inc anchors premium positioning through extensive patent clusters and formulation refinements. Among biosimilar specialists, Samsung Bioepis and Fresenius Kabi exemplify archetypes differentiated by European partnership networks and integrated manufacturing control respectively. These three companies represent the structural poles around which prescribing authority and procurement concentration organize.
| Leading Market Players |
|---|
| AbbVie Inc |
| Amgen Inc |
| Pfizer Inc |
| Boehringer Ingelheim |
| Sandoz |
| Fresenius Kabi |
| Samsung Bioepis |
| Zydus Lifesciences Ltd |
| Hetero Healthcare Limited |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between United States integrated delivery networks and biosimilar manufacturers lock in supply access while anchoring price visibility for mammalian cell culture capacity. These arrangements concentrate procurement authority in pharmacy benefit managers who negotiate rebate-driven tier placement across rheumatology and dermatology formularies.
Pricing Analysis
FDA's biosimilar interchangeability pathway dictates the pricing tier structure across United States retail and hospital channels. Three-tier pricing separates originator biologics with device-locked formulations from interchangeable biosimilars and non-interchangeable alternatives. Price differentiation stems from immunogenicity profile certification and volume scale commitments in German sickness fund tenders. Cost compression in European biosimilar tiers is intensifying because of REACH-mandated excipient reformulations. Hospital procurement committees show lowest price sensitivity in ulcerative colitis applications where physician confidence in originator immunogenicity data remains decisive.
Supply Chain Analysis
Mammalian cell culture capacity constraints in South Korean contract manufacturing organizations create supply chokepoints for glycosylation-critical biologics. Production gravity centers on United States, Germany, and Japan where AbbVie's originator network and Samsung Bioepis biosimilar facilities anchor supply. Raw material dependencies include cell culture media, single-use bioreactor systems, and citrate-free buffer excipients. Single-source vulnerability runs through specialized peptide mapping and mass spectrometry equipment suppliers. Distribution runs through cold chain logistics networks serving rheumatology clinics with temperature-controlled auto-injector and pre-filled syringe formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient adherence program bundling with auto-injector devices represents a service-attach opportunity expanding faster than molecule sales alone. Digital health integration layers for injection tracking and prior authorization automation are capturing margin pools beyond the biologic itself.
For Market Incumbents: Compound defensive moats through formulation patent clusters and device-locked combinations that extend exclusivity windows beyond composition-of-matter expiry. AbbVie's citrate-free buffer transitions exemplify how incremental formulation refinements preserve premium positioning. Invest in real-world evidence generation for interchangeability designation defense against biosimilar rebate pressure. Capacity addition in Japanese mammalian cell culture facilities strengthens PMDA immunogenicity assessment credibility. For New Entrants and Emerging Players: Differentiate on analytical similarity demonstration speed and European partnership networks that accelerate EMA filing timelines. White-space targets include Indian institutional tenders qualifying through WHO prequalification pathways and United States home healthcare provider channels for self-administration support. The most penetrable segment is German sickness fund biosimilar purchasing where tender-based consolidation favors cost-optimized entrants. Go-to-market angle: citrate-free buffer formulations that preempt REACH registration scrutiny. For Investors and Strategic Acquirers: Biosimilar developers with captive mammalian cell culture infrastructure and established FDA/EMA filing track records offer the strongest acquisition profile for long-term viability through the patent cliff window. Contract manufacturing organizations with glycosylation-critical biologics expertise in South Korea and United States anchor upstream value capture. The signal to watch is interchangeability study outcome announcements that trigger formulary tier renegotiations and physician switching behavior inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Interchangeability Study Completion | FDA designation unlocks pharmacy-level substitution in United States integrated delivery networks. |
| REACH-Compliant Excipient Transition | Citrate-free buffer reformulations preempt ECHA regulatory scrutiny in German and French tenders. |
| Real-World Evidence Registry Investment | Post-market immunogenicity data generation secures formulary positioning against biosimilar challengers. |
| Integrated Manufacturing Scale-Up | API-to-finished-dosage control reduces reliance on contract manufacturing organization capacity constraints. |
| WHO Prequalification Pathway Advancement | Institutional tender eligibility opens emerging health system procurement in Indian and Southeast Asian markets. |
Research Methodology
A standing panel of formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration against market developments. Primary interviews with drug development executives at originator and biosimilar manufacturers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down revenue triangulation anchored segmentation outputs across therapy area, delivery mode, and end user dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from patient population growth, biosimilar penetration curves, and pricing trajectory assumptions. Forecast inputs included autoimmune prevalence expansion rates and mammalian cell culture capacity utilization indicators.
Material uncertainties — regulatory approval delays, interchangeability designation reversals, and cold chain disruption events — sit outside the modeled envelope. Forecasts reflect assumptions about physician switching behavior and pharmacy benefit manager tier consolidation that could shift with post-market immunogenicity signal detection. Practitioners should keep alternative scenarios live as biosimilar real-world evidence generation and patent litigation outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
GCC Generic Drug Market
Generics and Biosimilars
West Africa Generic Drug Market
Generics and Biosimilars
Super Generics Market
Generics and Biosimilars
Latin America Generic Drug Market
Generics and Biosimilars
Europe Branded Generics Market
Generics and Biosimilars
US Specialty Injectable Generics Market
Generics and Biosimilars
Europe Specialty Generics Market
Generics and Biosimilars
Adalimumab Market