
 North America Breast Reconstruction Market | 2026-2036
North America Breast Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
North America Breast Reconstruction Market Intelligence
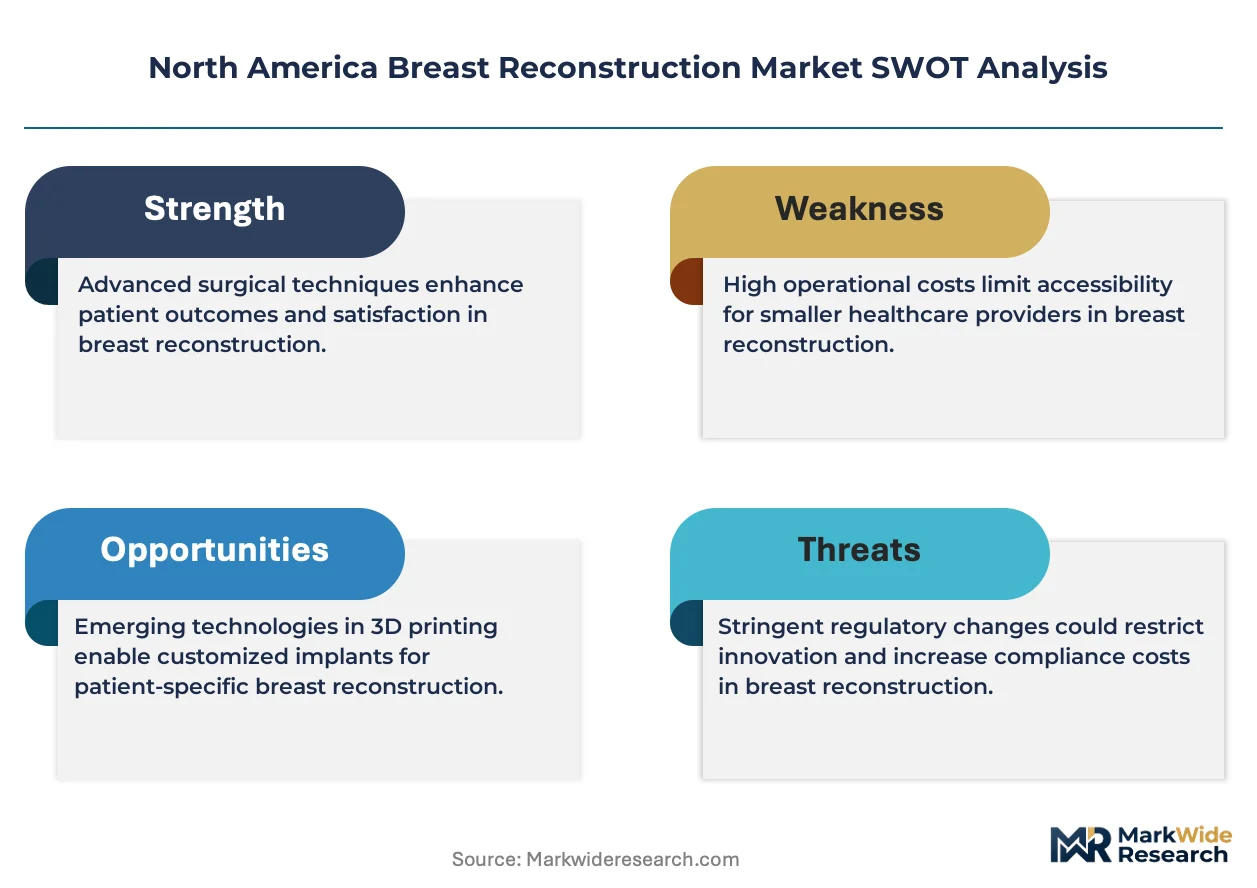
FDA premarket notification requirements for silicone gel-filled breast implants is hardening the cost-of-entry calculus for new manufacturers. AbbVie Inc. leverages its Allergan Aesthetics division's vertical integration across implant manufacturing and physician training networks. Johnson & Johnson sustains competitive positioning through its Ethicon surgical portfolio and broad hospital GPO contracts. Sientra, Inc. specializes in differentiated silicone implant textures and direct-to-physician distribution control.
Breast reconstruction encompasses surgical restoration of breast mound symmetry following mastectomy or lumpectomy, utilizing silicone or saline implants, tissue expanders, or autologous tissue transfer with microvascular anastomosis requiring sub-1mm vessel precision. The primary purpose is oncologic rehabilitation with aesthetic and psychosocial functional restoration. Implant-based reconstruction occupies the dominant volume position due to shorter operative times and established reimbursement, while regenerative medicine and 3D printing represent emerging margin pools where bioresorbable scaffolds command premium positioning. Autologous tissue reconstruction, particularly deep inferior epigastric perforator flap procedures, anchors the highest reimbursement tier but faces capacity constraints from specialized microsurgical training requirements.
FDA Center for Devices and Radiological Health oversight, combined with state-level facility accreditation through the American College of Surgeons Commission on Cancer, shapes product standards and site-of-service access across the United States and Canada. Health Canada's Medical Devices Directorate maintains parallel but distinct licensing pathways that fragment cross-border product launch sequencing. Stakeholders must monitor evolving FDA post-approval study requirements and provincial reimbursement harmonization pressures as determinants of portfolio prioritization and capital deployment timing.
Market Dynamics
FDA post-approval study mandates for silicone implants are compressing product development timelines while forcing manufacturers to maintain longitudinal safety databases across extended patient cohorts.
Growth Catalysts
- Same-day surgical protocols:Ambulatory surgical centers across Texas and California are expanding capacity for implant-based reconstruction with discharge within 23 hours.
- ACS Commission on Cancer accreditation:Mandatory facility certification requirements are standardizing quality benchmarks across hospital networks.
- Prepectoral implant placement:Muscle-sparing techniques are reducing postoperative pain and accelerating return-to-function timelines for patients.
Market Restraints
- Microsurgical workforce scarcity:Deep inferior epigastric perforator flap procedures require fellowship-trained surgeons with sub-1mm vessel anastomosis skills concentrated in academic medical centers.
- Silicone raw material concentration:Medical-grade silicone supply chains cluster among a limited set of specialty chemical producers.
- Health Canada licensing fragmentation:Parallel but distinct premarket pathways delay synchronized product launches across the United States-Canada border.
Strategic Opportunities
- 3D-printed bioresorbable scaffolds:Patient-specific lattice structures for prepectoral tissue support command premium positioning in metropolitan hospital clusters.
- Provincial reimbursement harmonization:Canadian provincial health plans are converging toward standardized coverage for autologous reconstruction.
- Direct-to-physician distribution:Implant manufacturers are bypassing traditional distributor networks to capture margin and control surgical training.
Industry Challenges
- Post-approval surveillance infrastructure:Manufacturers must maintain registries tracking implant performance across 10-year horizons with patient-reported outcome capture.
- Microsurgical training pipeline:Fellowship programs produce fewer than 50 new DIEP flap specialists annually across the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Breast Reconstruction Market |
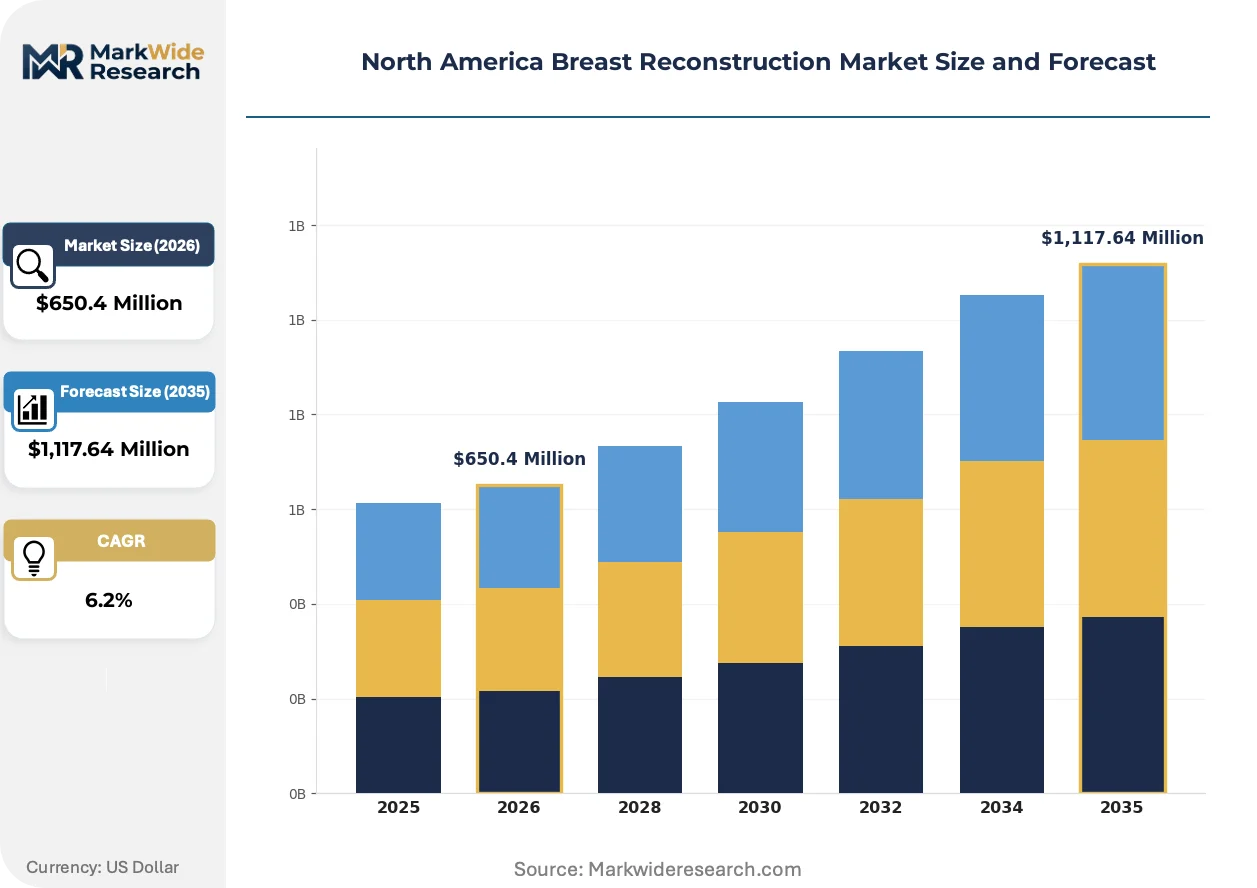
| Market Size in 2026 | $650.4 Million |
| Market Size in 2035 | $1,117.64 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Tissue Expanders, Autologous Tissue, Flap Reconstruction Technology: 3D Printing, Regenerative Medicine, Laser-assisted Techniques, Microsurgery End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Specialty Hospitals Delivery Mode: Inpatient, Outpatient, Telehealth, Homecare |
| Companies Covered | AbbVie Inc., Johnson & Johnson, Sientra, Inc., Integra LifeSciences, Stryker Corporation, Establishment Labs, GC Aesthetics, RTI Surgical, TELA Bio, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Breast Reconstruction Market Strategic Shifts & Innovations
Prepectoral implant placement is displacing traditional submuscular techniques, while bioresorbable scaffolding and point-of-care 3D printing reshape operative planning workflows across major metropolitan surgical centers.
Prepectoral implant reconstruction is overtaking submuscular placement as the dominant operative approach for immediate post-mastectomy restoration. Academic medical centers in New York and California are adopting this technique for over sixty percent of eligible cases. The shift is compressing operative times and reducing postoperative opioid requirements while enabling faster return to adjuvant therapy.
FDA Center for Devices and Radiological Health post-approval study requirements are hardening data collection burdens for silicone gel-filled implant manufacturers. Extended longitudinal tracking mandates are extending product liability exposure windows and inflating regulatory affairs staffing. Manufacturers are responding by embedding patient registry enrollment into surgical consent workflows.
Patient steering toward accredited breast centers is consolidating surgical volume within ACS Commission on Cancer-certified facilities. Independent community hospitals without on-site plastic surgery coverage are referring reconstruction cases to regional academic networks. This concentration is most pronounced across the Texas Medical Center corridor and the California Pacific coast metropolitan clusters.
North America Breast Reconstruction Market Segmentation
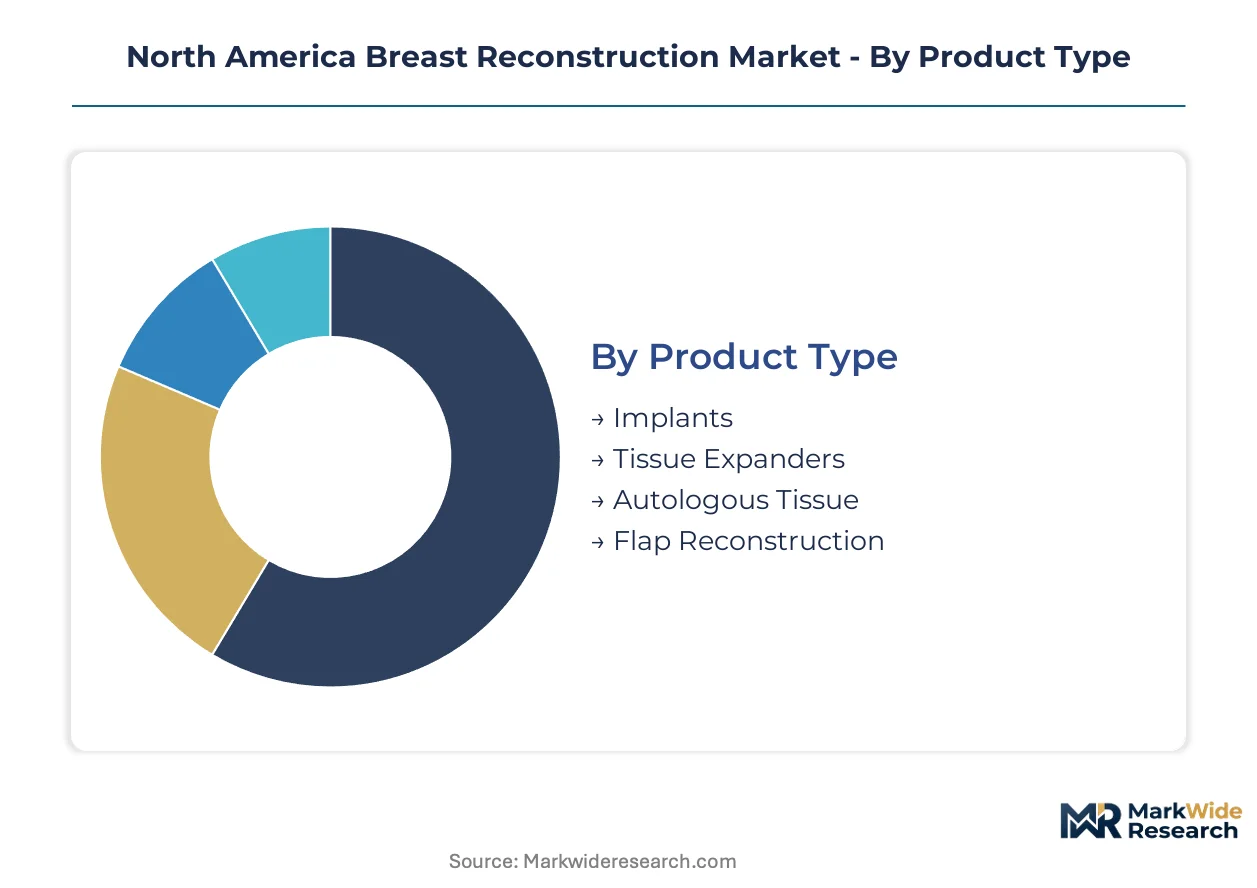
Segmentation in breast reconstruction reveals how technology maturity, site-of-service economics, and reimbursement architecture partition commercial opportunity. Product and technology categories stratify by capital intensity and regulatory burden, while end-user and delivery mode segments track the migration toward ambulatory settings.
Product Type:
Silicone polymer specifications and tissue-engineering capabilities define the product architecture across reconstruction modalities.
- Implants:Silicone gel-filled devices with textured or smooth shells dominate procedural volume due to shorter operative times and established CPT reimbursement codes. Demand concentrates in metropolitan hospital clusters across Texas and California where same-day discharge protocols are expanding.
- Tissue Expanders:Temporary saline-filled devices enable staged reconstruction through serial inflation protocols. Academic medical centers in New York deploy these for delayed reconstruction pathways requiring neoadjuvant chemotherapy completion.
- Autologous Tissue:Patient-derived abdominal or gluteal tissue transfers eliminate foreign-body complications but require extended operative duration. Deep inferior epigastric perforator procedures anchor premium reimbursement tiers within ACS Commission on Cancer-certified facilities.
- Flap Reconstruction:Microvascular free tissue transfer with sub-1mm vessel anastomosis demands specialized fellowship training. Volume concentrates in academic centers with dedicated microsurgical teams.
Mature deployment sits with Implants. Newer deployment is concentrated in Autologous Tissue as patients prioritize device-free outcomes.
Technology:
Capital equipment requirements and regulatory pathway complexity segment innovation investment across the technology stack.
- 3D Printing:Point-of-care manufacturing of bioresorbable scaffolds enables patient-specific prepectoral support structures. Metropolitan surgical centers in California are piloting these for complex chest wall reconstructions.
- Regenerative Medicine:Bioresorbable matrices derived from decellularized dermis or synthetic polymers command premium positioning. Demand from academic medical centers is climbing fastest as adjunctive coverage expands.
- Laser-assisted Techniques:Preoperative vessel mapping and intraoperative perfusion assessment reduce flap failure rates. Texas Medical Center corridors are adopting these for DIEP flap planning.
- Microsurgery:Sub-1mm vessel anastomosis with operating microscope magnification enables autologous reconstruction. Workforce scarcity limits geographic penetration to fellowship-trained specialists.
Established penetration sits with Microsurgery. Emerging adoption is concentrated in 3D Printing as device manufacturers build point-of-care partnerships.
End User:
Facility accreditation status and anesthesia infrastructure determine site-of-service eligibility for reconstruction procedures.
- Hospitals:ACS Commission on Cancer-certified facilities capture complex autologous cases requiring extended monitoring. Volume is consolidating within integrated delivery networks across the Northeast corridor.
- Outpatient Clinics:Office-based settings handle expander adjustments and postoperative surveillance. California and Florida are expanding these for stable implant monitoring.
- Ambulatory Surgical Centers:Medicare-certified ASCs are scaling implant-based reconstruction with 23-hour discharge protocols. Texas and Arizona lead capacity expansion.
- Specialty Hospitals:Dedicated cancer centers with on-site plastic surgery coverage capture high-acuity reconstructions. These anchor regional referral networks.
Traditional concentration sits with Hospitals. Volume migration is accelerating toward Ambulatory Surgical Centers as payers steer toward lower-cost settings.
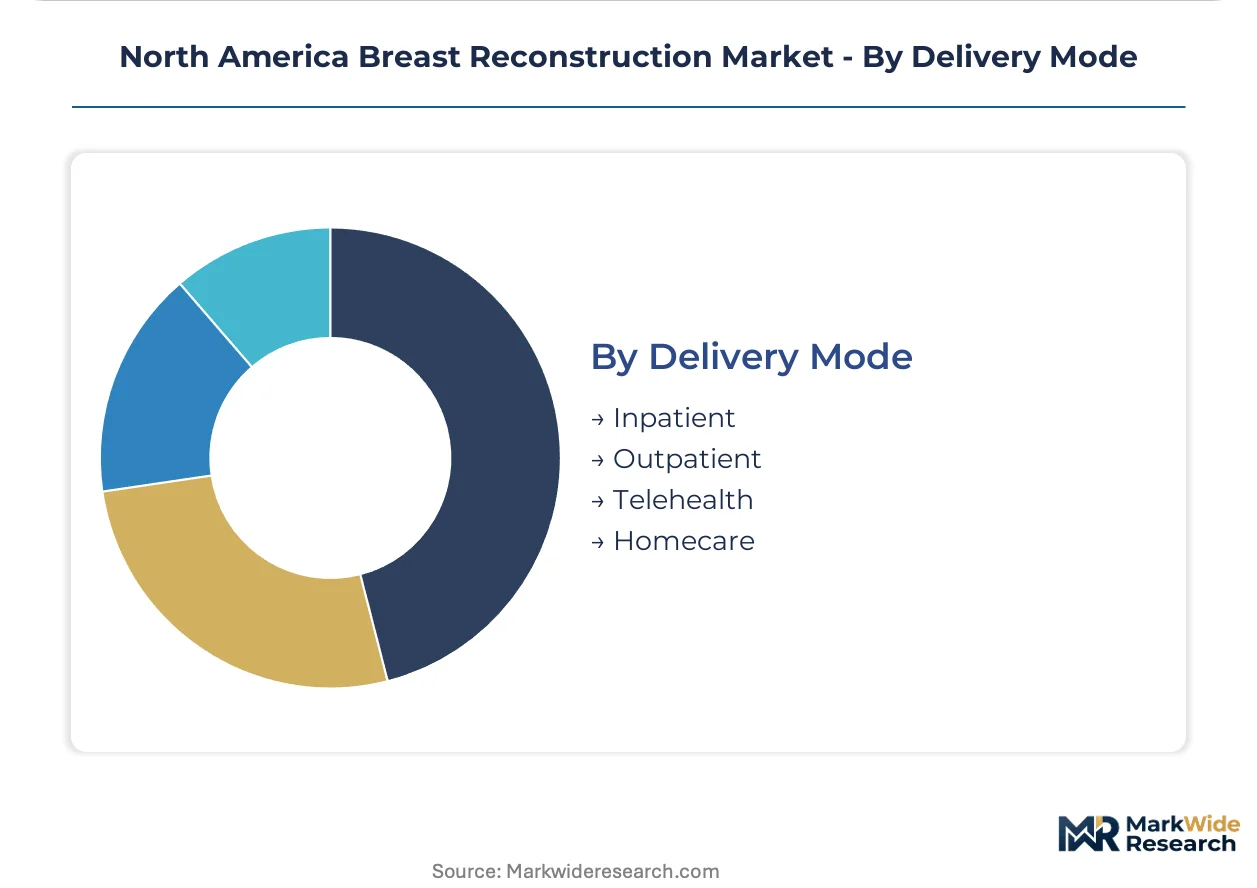
Delivery Mode:
Reimbursement classification and medical necessity documentation shape how care episodes are structured across settings.
- Inpatient:Overnight stays anchor autologous flap procedures requiring hemodynamic monitoring. Academic centers maintain this for DIEP and TRAM flap protocols.
- Outpatient:Same-day discharge dominates implant-based reconstruction with multimodal anesthesia. California and New York are standardizing these pathways.
- Telehealth:Remote postoperative monitoring and expander adjustment counseling are expanding. Rural patient access is improving through synchronous video consultation.
- Homecare:Drain management and wound care services support early discharge. Home health agencies are contracting with ASC networks for bundled episode support.
Established volume sits with Inpatient. Steepest expansion trajectory is occurring in Outpatient as surgical techniques and anesthesia protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones across Texas and California metropolitan corridors concentrate surgical capacity through state-level tax incentives for healthcare infrastructure investment. Hospital networks in these zones capture disproportionate reconstruction volume through integrated delivery models.
United States
Texas Medical Center in Houston anchors the highest procedural density for autologous flap reconstruction. FDA post-approval study mandates for silicone implants compress product development timelines. California's Pacific coast metropolitan clusters standardize prepectoral implant placement protocols.
Canada
Provincial health plans in Ontario and Quebec drive demand through converging reimbursement standards for autologous reconstruction. Health Canada's Medical Devices Directorate maintains distinct licensing pathways that fragment cross-border product launches. Toronto and Vancouver academic medical centers concentrate microsurgical fellowship training.
Mexico
Medical tourism corridors in Tijuana and Monterrey attract cross-border patients seeking cost-advantaged implant procedures. COFEPRIS regulatory alignment with FDA standards enables faster product registration for multinational manufacturers. Guadalajara's private hospital networks expand ambulatory surgical capacity.
North America Breast Reconstruction Market Key Industry Players
United States producers anchor one tier; Irish and Costa Rican specialists hold manufacturing positions through contract arrangements. The vendor base stratifies across three tiers: diversified medical device conglomerates with aesthetic divisions, pure-play breast implant specialists, and regenerative matrix developers. Competitive dynamics center on direct-to-physician distribution control and longitudinal patient registry maintenance.
Within the diversified conglomerate tier, AbbVie Inc. and Johnson & Johnson occupy positions defined by vertical integration across implant manufacturing and surgical training networks. Sientra, Inc. exemplifies the specialist archetype through focused silicone implant texture differentiation and controlled distribution channels.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson |
| Sientra, Inc. |
| Integra LifeSciences |
| Stryker Corporation |
| Establishment Labs |
| GC Aesthetics |
| RTI Surgical |
| TELA Bio, Inc. |
| Others |
Cost & Logistics Intelligence
Ambulatory surgical center procurement consolidation across Texas and California is forcing implant manufacturers to compress delivery windows while absorbing inventory carrying costs, tightening margin structures across the silicone implant tier.
Pricing Analysis
Expedited fulfillment premiums dominate contract negotiations as hospital GPOs demand 48-hour implant availability for urgent reconstruction cases. Three-tier pricing structure across premium textured implants, standard smooth-shell devices, and economy saline alternatives reflects FDA certification tier and surgeon training bundling. Cost compression in the standard tier intensifies because raw material pass-through clauses are weakening. Ambulatory surgical centers exhibit highest price sensitivity due to fixed-case reimbursement rates, while academic medical centers prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, California, and New York operate hub-and-spoke patterns to serve metropolitan surgical clusters within four-hour ground transit. Manufacturing concentrates in Costa Rica, Ireland, and the United States for FDA-inspected facilities. Medical-grade silicone polymer, textured shell substrates, and bioresorbable scaffold matrices anchor component dependencies. Single-source vulnerability from specialty chemical producers for implant-grade silicone creates concentration risk. Distribution runs through manufacturer-direct sales representatives controlling surgical training and case support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive control over physician training networks to lock in implant selection and capture service-margin pools.
For Market Incumbents: Deploy direct-to-physician distribution infrastructure to bypass traditional medical device distributors and capture training-margin economics. Consolidate microsurgical fellowship relationships to anchor DIEP flap referral volume against emerging regenerative matrix substitutes. Invest in point-of-care 3D printing partnerships to preempt bioresorbable scaffold disruption in prepectoral reconstruction. For New Entrants and Emerging Players: Health Canada's Medical Devices Directorate licensing convergence with FDA standards opens a window for synchronized US-Canada product launches that incumbents with legacy parallel submissions cannot match. Target provincial reimbursement harmonization in Ontario and Quebec for autologous reconstruction coverage expansion. Pursue ambulatory surgical center direct contracts with 23-hour discharge protocol bundling as the go-to-market wedge. For Investors and Strategic Acquirers: The window for entry favors regenerative matrix developers with bioresorbable scaffold platforms and point-of-care manufacturing capabilities. Long-term viability hinges on FDA post-approval study infrastructure maintenance and longitudinal patient registry ownership. Watch Health Canada licensing pathway simplification as the signal for cross-border portfolio consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | Streamlined 510(k) clearance for silicone implants accelerates competitive entry timelines against PMA-heavy portfolios. |
| Hospital System Partnership | ACS Commission on Cancer-certified facility alliances concentrate surgical volume and anchor GPO contract exclusivity. |
| Physician Training Network | Captive fellowship program relationships lock in implant selection preference across academic medical center referral corridors. |
| Bioresorbable Scaffold Development | Patient-specific 3D-printed matrices command premium positioning in prepectoral reconstruction protocols. |
| Provincial Reimbursement Strategy | Harmonized autologous coverage across Canadian provincial health plans expands addressable market for DIEP flap procedures. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plastic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) and PMA submission databases, Health Canada medical device licenses, and ACS Commission on Cancer facility accreditation records provided structured validation. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data.
Segment-level modeling operated at product type, technology platform, end-user facility category, and delivery mode dimensions across the projection horizon. CAGRs derived from weighted average of historical trend extrapolation and driver-based scenario analysis. Forecast inputs incorporated FDA post-approval study completion rates, provincial reimbursement policy trajectories, and microsurgical fellowship graduation pipeline constraints.
The model assumes a particular technology adoption path; alternative pathways for bioresorbable scaffold integration would alter the outlook for implant-based reconstruction volume shares. Forecasts reflect documented assumptions regarding regulatory timeline stability and reimbursement rate persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
Radiation Therapy Market