
 Gaucher Disease Treatment Market | 2026-2036
Gaucher Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Gaucher Disease Treatment Market Intelligence
Gene therapy vector engineering is tilting toward lentiviral and AAV platforms that enable durable glucocerebrosidase expression. Sanofi sustains manufacturing scale across recombinant enzyme facilities in Europe and North America. Protalix BioTherapeutics specializes in plant-cell-derived protein production, a distinctive approach that lowers upstream costs. Amicus Therapeutics positions its pharmacological chaperone portfolio toward neuronopathic Gaucher variants where blood-brain barrier penetration matters.
Gaucher disease treatment encompasses therapeutic interventions that restore or compensate for deficient glucocerebrosidase enzyme activity, including intravenous infusions of recombinant enzymes, oral small molecules that reduce substrate accumulation, and emerging gene therapies that insert functional GBA1 copies. Enzyme Replacement Therapy dominates current revenue as the established standard for Type 1 patients with intact neurological function. Substrate Reduction Therapy captures growth in adult patients with milder phenotypes who prefer oral administration. Gene Therapy represents the fastest-expanding segment structurally, though commercialization timelines depend on durable expression data and manufacturing scalability.
FDA orphan drug exclusivity and EMA's PRIME designation shape investment allocation by shortening regulatory review periods for Gaucher therapies. The EU's F-Gas Regulation and corresponding EPA mandates on perfluorinated compounds increasingly influence cold-chain logistics decisions for biologics distribution. Stakeholders must weigh manufacturing platform choices against evolving payer requirements for outcome-based contracts in rare disease categories.
Market Dynamics
Gene therapy manufacturing scale-up is compressing development timelines for Gaucher treatments while reshaping competitive investment priorities across enzyme replacement and substrate reduction platforms.
Growth Catalysts
- Orphan Drug Exclusivity:FDA's seven-year market exclusivity provisions and EMA's PRIME designation accelerate regulatory pathways for novel Gaucher therapies, reducing time-to-market risk for developers targeting neuronopathic variants.
- Plant-Cell Production Platforms:Proprietary bioreactor systems using carrot-cell cultures lower upstream manufacturing costs for recombinant glucocerebrosidase, expanding supply elasticity for high-dose chronic regimens.
- Specialty Clinic Networks:Dedicated lysosomal storage disorder centers in the United States, Germany, and Japan concentrate diagnostic expertise and streamline patient identification for therapy initiation.
Market Restraints
- Biologics Cold-Chain Costs:Perfluorinated compound restrictions under EPA mandates and the EU's F-Gas Regulation elevate refrigeration logistics expenses for enzyme replacement products requiring 2-8°C distribution.
- Vector Manufacturing Bottlenecks:Lentiviral and AAV production capacity constraints in contract manufacturing organizations limit gene therapy batch yields and extend clinical supply lead times.
- Diagnostic Access Gaps:Sphingolipid assay availability concentrates in tertiary academic medical centers, leaving community hospitals without enzymatic testing capability to identify Type 1 patients with splenomegaly presentations.
Strategic Opportunities
- Neuronopathic Indication Expansion:Blood-brain barrier-penetrant pharmacological chaperones address the unmet need in Type 2 and Type 3 Gaucher patients where current intravenous enzymes fail to reach central nervous system pathology.
- Outcome-Based Reimbursement Pilots:Payer contracts tying physician-administered therapy payment to hepatosplenomegaly reduction metrics create financial alignment between manufacturers and public health systems in France and the Netherlands.
- Gene Therapy Durability Data:Long-term expression studies from early-phase lentiviral trials, if sustained beyond five years, would displace chronic infusion requirements and capture lifetime patient value.
Industry Challenges
- Vector Immunogenicity Management:Pre-existing neutralizing antibodies against AAV serotypes in patient populations complicate eligibility screening and necessitate plasmapheresis protocols that delay treatment initiation.
- GBA1 Variant Heterogeneity:Over four hundred documented mutations in the glucocerebrosidase gene create pharmacogenomic complexity, requiring biomarker stratification that fragments addressable patient cohorts across clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaucher Disease Treatment Market |
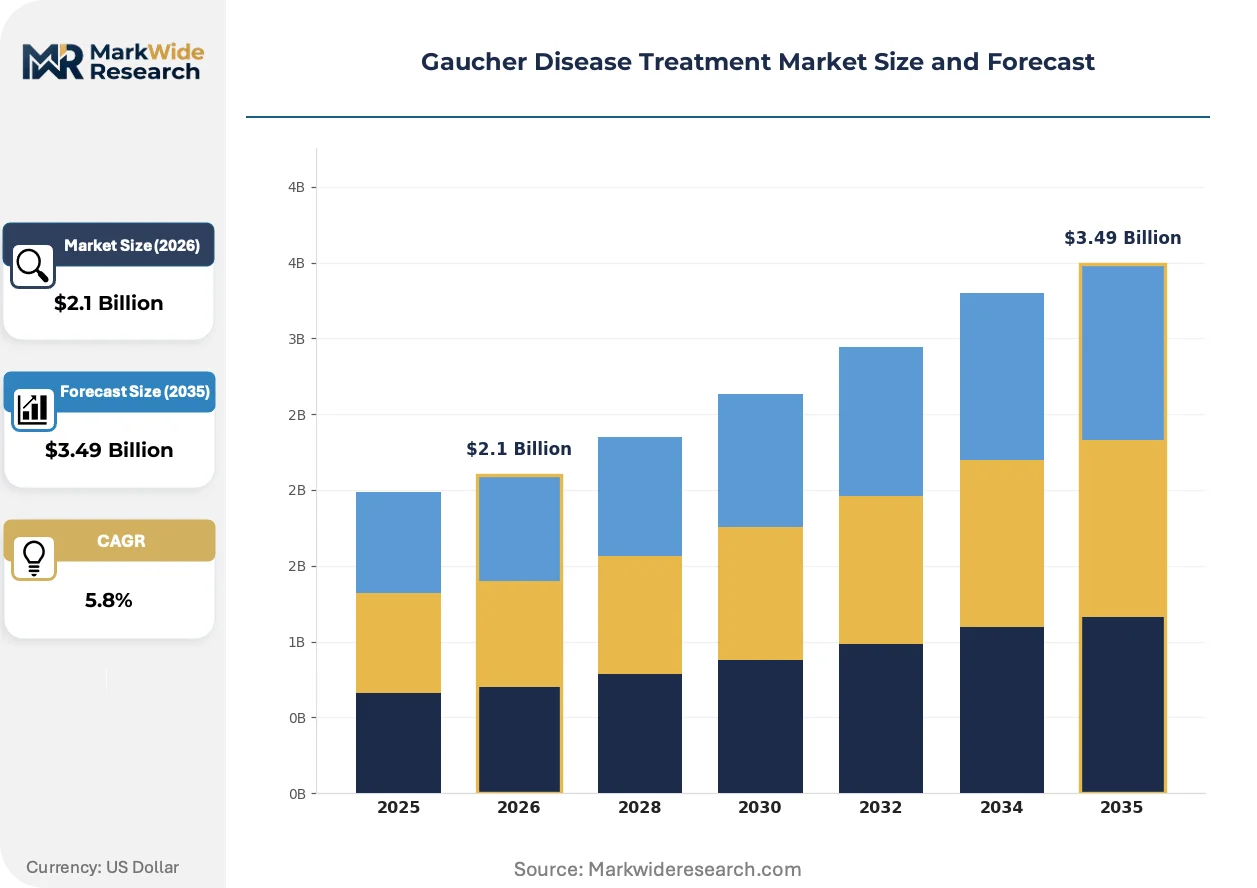
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Substrate Reduction Therapy, Pharmacological Chaperones, Gene Therapy Therapy Area: Type 1 Gaucher, Type 2 Gaucher, Type 3 Gaucher, Chronic Visceral End User: Specialty Clinics, Research Institutes, Diagnostic Laboratories, Rare Disease Centers Route of Administration: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | Johnson & Johnson, Protalix BioTherapeutics Inc., Sanofi, Shire Plc, Sobi (Swedish Orphan Biovitrum AB), Takeda Pharmaceutical Company Limited, Amicus Therapeutics, Inc., Orchard Therapeutics plc, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaucher Disease Treatment Market Strategic Shifts & Innovations
Platform engineering decisions in vector design and protein production are redrawing manufacturing economics while regulatory frameworks for advanced therapy medicinal products create new approval pathways.
Next-generation lentiviral vectors incorporating chromatin insulator elements and self-inactivating long terminal repeats are digitizing patient monitoring requirements through integrated digital biomarker capture. Gene therapy developers deploy these enhanced constructs in neuronopathic Gaucher trials to enable remote safety surveillance. The technology is digitizing clinical trial operations by embedding electronic patient-reported outcome tools directly into treatment protocols.
EMA's Advanced Therapy Medicinal Products Regulation and FDA's regenerative medicine advanced therapy designation create parallel accelerated review tracks for gene-based Gaucher interventions. These frameworks compress the traditional phase transition timeline for products demonstrating substantial improvement over enzyme replacement. European reference pricing systems, particularly Germany's AMNOG process, are adapting assessment methodologies to accommodate single-administration curative therapies.
Patient advocacy organizations increasingly coordinate directly with manufacturers on natural history study design, displacing traditional academic principal investigator control over registry data. This behavioral shift concentrates real-world evidence generation under sponsor direction, streamlining health technology assessment submissions in England and Scotland. The phenomenon is most visible in the United States, where the National Gaucher Foundation maintains structured data-sharing agreements with multiple developers.
Gaucher Disease Treatment Market Segmentation
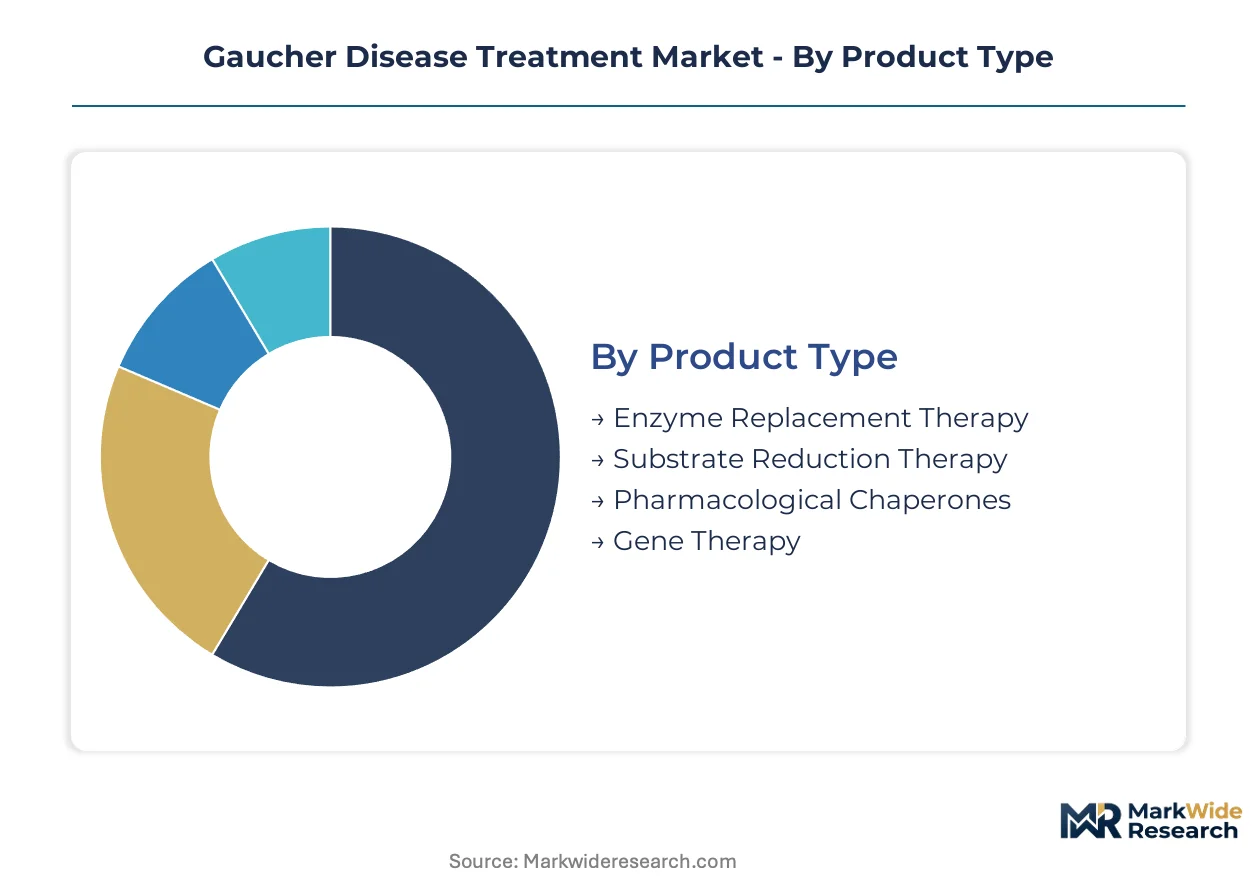
Treatment modality selection in Gaucher disease hinges on phenotypic severity, neurological involvement, and patient preference for administration frequency. Segmentation reveals how chronic infusion requirements, oral convenience, and one-time curative potential partition addressable populations across the clinical spectrum.
Product Type:
After-sales service intensity varies dramatically across production platforms, with recombinant biologics demanding cold-chain monitoring, gene therapies requiring long-term follow-up protocols, and small molecules needing minimal post-dispensing support.
- Enzyme Replacement Therapy:Intravenous infusions of recombinant glucocerebrosidase restore enzymatic activity in Type 1 patients. Demand concentrates in the United States and Germany where specialty infusion center networks and established reimbursement pathways support chronic administration schedules.
- Substrate Reduction Therapy:Oral small molecules inhibit glucosylceramide synthase to reduce substrate accumulation. Adult patients with milder phenotypes in France and the Netherlands prefer this convenience, driving preference among employed populations seeking to avoid monthly hospital visits.
- Pharmacological Chaperones:Small molecules stabilize misfolded glucocerebrosidase for residual activity enhancement.
- Gene Therapy:Lentiviral and AAV vectors insert functional GBA1 copies for durable expression.
By volume, Enzyme Replacement Therapy leads. By growth pace, Gene Therapy is ahead.
Therapy Area:
Cost tier stratification separates acute neuronopathic intervention from chronic visceral management, with intensive care requirements and blood-brain barrier penetration commanding premium pricing.
- Type 1 Gaucher:Non-neuronopathic variant presenting with splenomegaly, hepatomegaly, and cytopenias. Patients in the United States and Western Europe receive diagnosis through newborn screening expansion programs, concentrating addressable volume where enzymatic testing infrastructure exists.
- Type 3 Gaucher:Chronic neuronopathic form with progressive neurological deterioration. Substrate Reduction Therapy with blood-brain barrier penetration addresses unmet need in Japan and Germany where specialized lysosomal storage disorder centers coordinate multidisciplinary care.
- Type 2 Gaucher:Acute neuronopathic variant with infantile onset and rapid progression.
- Chronic Visceral:Sustained organ-focused disease without neurological progression.
By patient volume, Type 1 Gaucher dominates. By unmet need severity, Type 2 and Type 3 variants represent the steepest expansion trajectory for novel modalities.
End User:
Customer type fragmentation reflects referral pathway complexity, with academic medical centers anchoring diagnosis and community specialty clinics managing chronic therapy.
- Specialty Clinics:Dedicated lysosomal storage disorder centers in Boston, Munich, and Tokyo concentrate infusion capacity and genetic counseling expertise.
- Rare Disease Centers:National referral hubs coordinate multidisciplinary care across hepatology, hematology, and neurology disciplines.
- Research Institutes:Academic medical centers conduct natural history studies and gene therapy trials.
- Diagnostic Laboratories:Reference labs perform enzymatic assay confirmation and GBA1 sequencing.
By treatment volume, Specialty Clinics lead. By trial enrollment growth, Research Institutes are expanding most quickly.
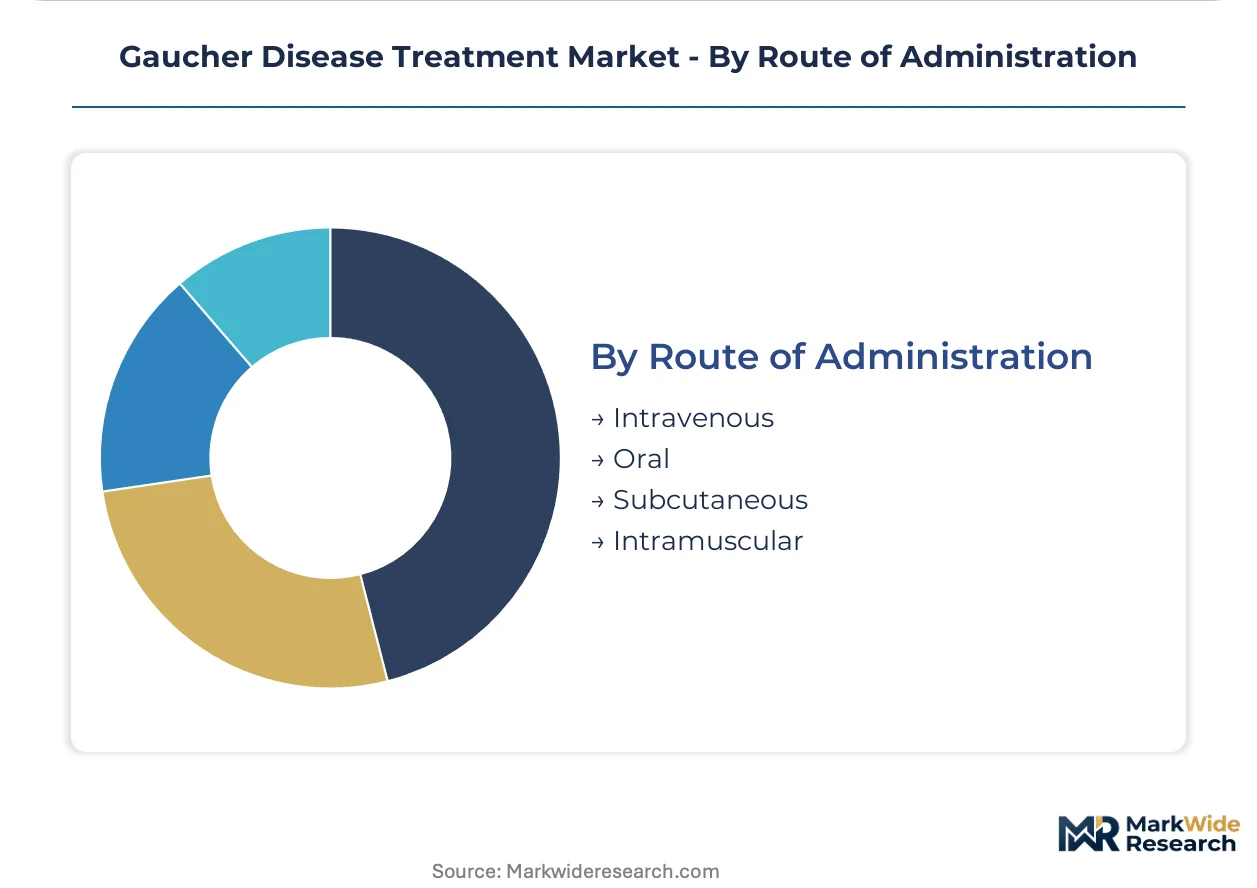
Route of Administration:
Supply concentration in parenteral manufacturing shapes competitive positioning, with oral formulation expertise residing in distinct pharmaceutical portfolios.
- Intravenous:Hospital-based enzyme infusion requires infusion center capacity and nursing support.
- Oral:Small molecule substrates and chaperones enable home administration with pharmacy dispensing.
- Subcutaneous:Emerging delivery for next-generation enzyme formulations seeks to reduce infusion burden.
- Intramuscular:Investigational gene therapy administration routes explore depot-based expression.
By current utilization, Intravenous administration leads. By development pipeline activity, Subcutaneous delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net trade in enzyme replacement therapies tilts toward surplus in Western manufacturing hubs while emerging diagnostic programs in Asia-Pacific narrow the import dependency for reference testing materials.
United States
Newborn screening expansion in New York and California drives patient identification for Type 1 Gaucher. FDA orphan drug exclusivity provisions accelerate review timelines for neuronopathic variants. Boston's Longwood Medical Area anchors gene therapy trial coordination through specialized lysosomal storage disorder centers.
Germany
AMNOG reference pricing processes shape reimbursement negotiations for chronic enzyme infusions. EMA's PRIME designation channels early dialogue toward accelerated assessments. Munich's university hospital network concentrates multidisciplinary care for Type 2 and Type 3 patients.
Japan
PMDA's Sakigake designation system fast-tracks innovative therapies for unmet neurological needs. METI funding supports domestic vector manufacturing capacity expansion. Tokyo's National Center of Neurology and Psychiatry coordinates pharmacological chaperone trials for blood-brain barrier penetration.
United Kingdom
NICE technology appraisals enforce cost-effectiveness thresholds for orphan biologics. MHRA post-Brexit recognition pathways maintain parallel EMA alignment for gene therapy submissions. London's Great Ormond Street Hospital anchors pediatric neuronopathic patient registries.
France
ANSM early access programs enable compassionate use for acute neuronopathic presentations. Outcome-based reimbursement pilots in the Haute Autorité de Santé system tie payment to hepatosplenomegaly reduction metrics. Paris's Necker-Enfants Malades Hospital maintains Europe's largest Gaucher natural history database.
Gaucher Disease Treatment Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: multinational biologics manufacturers with recombinant enzyme scale, gene therapy developers building lentiviral vector platforms, and plant-cell production specialists pursuing cost-disruptive manufacturing models. Dominant competitive moves include capacity expansion in contract manufacturing organizations and strategic partnerships for blood-brain barrier-penetrant formulation development.
Within the gene therapy archetype, Orchard Therapeutics plc and Amicus Therapeutics, Inc. occupy positions at the vector engineering frontier. Sanofi exemplifies the established biologics tier with sustained manufacturing footprint across European and North American facilities. Protalix BioTherapeutics Inc. anchors the alternative production platform segment through its distinctive plant-cell-derived approach.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Protalix BioTherapeutics Inc. |
| Sanofi |
| Shire Plc |
| Sobi (Swedish Orphan Biovitrum AB) |
| Takeda Pharmaceutical Company Limited |
| Amicus Therapeutics, Inc. |
| Orchard Therapeutics plc |
| Pfizer Inc. |
| Others |
Cost & Logistics Intelligence
Recombinant enzyme manufacturing concentration in Belgium and Ireland positions contract manufacturing organizations as gatekeepers for margin capture across chronic infusion therapies. Cold-chain logistics costs from perfluorinated compound restrictions feed directly into pricing negotiations between specialty infusion centers and payer formularies.
Pricing Analysis
Specialty clinic buyers anchor value-based pricing structures for enzyme replacement therapies. Pricing stratifies across premium branded biologics, standard biosimilar tiers, and economy-access programs based on orphan drug exclusivity status and manufacturing platform differentiation. Pricing pressure stems from outcome-based reimbursement pilots in France and the Netherlands tying payment to hepatosplenomegaly reduction metrics. Employed adult patients seeking oral convenience exhibit highest price sensitivity, while pediatric neuronopathic cases show lowest sensitivity due to unmet clinical need severity.
Supply Chain Analysis
Tariff exposure between the United States and European Union member states dominates supply chain risk calculations for cold-chain biologics distribution. Manufacturing draws from Belgium, Ireland, and Switzerland for recombinant enzyme production, with plant-cell platforms in Israel providing cost-disruptive alternatives. Lentiviral vector production capacity constraints in contract manufacturing organizations create single-source vulnerability for gene therapy clinical supply. Distribution runs through specialty pharmacy networks and hospital-based infusion centers with direct-to-patient home infusion emerging as an alternative channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gaucher disease treatment market operates as a regulatory entrenchment story where FDA orphan drug exclusivity and EMA PRIME designation create seven-year moats against competitive entry. Switching costs between enzyme replacement platforms lock patients into established chronic infusion regimens.
For Market Incumbents: Pre-empt gene therapy displacement by securing long-term expression data partnerships with academic medical centers before lentiviral durability claims mature. Expand manufacturing scale in Belgium and Ireland to capture biosimilar defense economics. Vector immunogenicity management protocols represent the critical capability gap to close against emerging platform competitors. For New Entrants and Emerging Players: Establish a beachhead in pharmacological chaperones for Type 2 and Type 3 neuronopathic variants where blood-brain barrier penetration creates unmet need white space. Target employed adult Type 1 populations in France and the Netherlands seeking oral administration convenience. Pursue natural history study partnerships with the National Gaucher Foundation to accelerate health technology assessment submissions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with plant-cell production specialists possessing cost-disruptive manufacturing platforms and established carrot-cell bioreactor infrastructure. Five-to-ten year viability hinges on gene therapy durability data displacing chronic infusion economics. Watch for sustained lentiviral expression beyond five years as the inflection signal for lifetime patient value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Lentiviral vector capacity expansion in Belgium addresses clinical supply bottlenecks for neuronopathic trials. |
| Outcome-Based Reimbursement Strategy | Hepatosplenomegaly reduction metrics in French Haute Autorité de Santé pilots align manufacturer-payer financial interests. |
| Plant-Cell Production Platform Investment | Carrot-cell bioreactor systems in Israel lower upstream costs for high-dose chronic enzyme regimens. |
| Specialty Clinic Network Partnership | Boston and Munich lysosomal storage disorder centers concentrate diagnostic expertise and streamline patient identification. |
| Regulatory Fast-Track Designation Pursuit | FDA regenerative medicine advanced therapy and EMA ATMP frameworks compress phase transition timelines for gene-based interventions. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient volume modeling across Type 1, Type 2, and Type 3 Gaucher populations triangulated with top-down market value reconstruction.
Forecast inputs incorporated treatment modality adoption curves, regional regulatory cluster differentiation, and manufacturing platform economics across the projection horizon. Segmentation dimensions modeled included therapy type, route of administration, phenotypic severity, and geographic reimbursement framework. CAGRs derived from patient prevalence projections, pricing trajectory assumptions, and competitive entry timing analysis.
Stress conditions across gene therapy durability data, vector manufacturing capacity expansion, and payer outcome-based contract adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions subject to revision from regulatory pathway acceleration, biosimilar entry dynamics, and diagnostic infrastructure expansion in emerging markets. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Adenomyosis Treatment Market