
 Morquio Syndrome Treatment Market | 2026-2036
Morquio Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Morquio Syndrome Treatment Market Analysis
Orphan drug designation under FDA and EMA frameworks is rotating competitive access, with only qualified sponsors securing priority review vouchers and tax credits. Ultragenyx Pharmaceutical leverages its rare disease commercial infrastructure to sustain pediatric prescriber relationships across North America and Europe. BioMarin Pharmaceutical anchors the enzyme replacement segment with manufacturing scale for biologic supply security. Takeda Pharmaceutical competes through its Japan-centric regulatory expertise and Asia-Pacific distribution reach.
Morquio syndrome treatment encompasses therapeutic interventions for mucopolysaccharidosis type IV, a lysosomal storage disorder caused by deficient N-acetylgalactosamine-6-sulfatase or beta-galactosidase enzyme activity resulting in glycosaminoglycan accumulation in bone, cartilage, and connective tissue. The primary clinical purpose is to modify disease progression, preserve skeletal function, and extend mobility and lifespan through intravenous enzyme infusions, investigational gene transfer vectors, or multidisciplinary supportive protocols. Enzyme replacement therapy dominates current revenue as the only approved disease-modifying modality, while gene therapy represents the fastest-growing development category with multiple candidates in pivotal trials. Supportive care maintains stable demand as a margin pool for orthopedic and respiratory management, though it lacks disease-modifying economics.
FDA orphan drug incentives, EMA conditional marketing authorization pathways, and Japan's PMDA sakigake designation system collectively shape trial design, approval timelines, and pricing latitude for developers. Reimbursement negotiations with national health technology assessment bodies determine commercial viability more than clinical efficacy alone in single-payer markets. Stakeholders must monitor regulatory precedents for gene therapy durability claims and corresponding value-based payment structures.
Market Dynamics
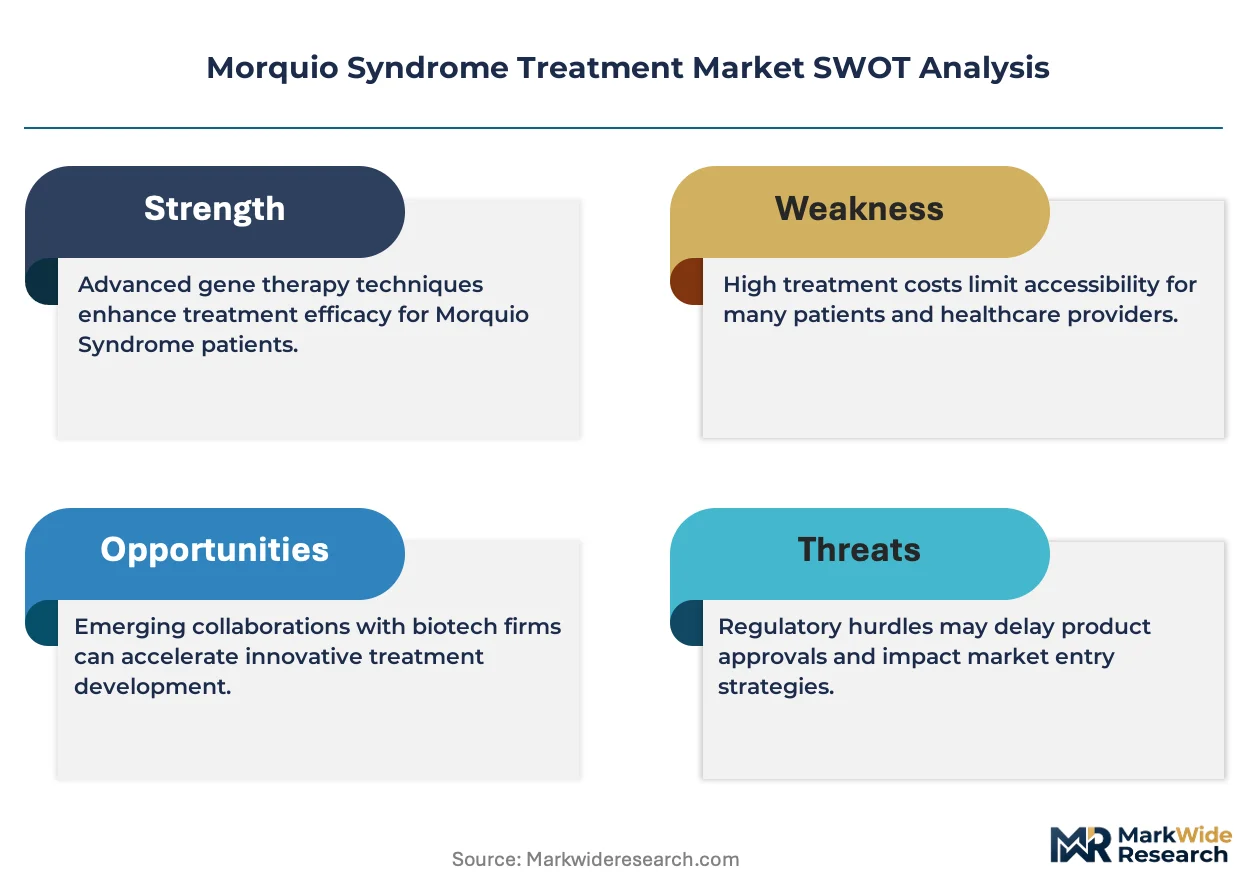
Gene therapy vector engineering is compressing clinical development timelines for Morquio syndrome, forcing enzyme replacement incumbents to accelerate next-generation platform investments.
Growth Catalysts
- FDA Priority Review Vouchers:Orphan drug designation under this framework accelerates regulatory timelines, attracting venture capital into ultra-rare disease pipelines.
- Pediatric Specialty Centers:Concentrated diagnostic expertise at these institutions in the United States, Germany, and Japan shortens time-to-treatment initiation.
- EMA Conditional Marketing Authorization:This pathway permits earlier patient access based on surrogate endpoints, reducing pivotal trial duration for gene therapy candidates.
Market Restraints
- Biologics Manufacturing Concentration:Single-source contract manufacturing organizations in Switzerland and Massachusetts control viral vector production capacity.
- Reimbursement Negotiation Friction:National health technology assessment bodies in England, France, and Germany demand extended durability evidence before formulary inclusion.
- Gene Therapy Durability Uncertainty:Long-term expression data for AAV-based vectors remains immature, constraining payer willingness to accept premium pricing.
Strategic Opportunities
- Japan's PMDA Sakigake Designation:This priority review system offers expedited consultations and early approval for innovative therapies addressing unmet needs.
- Subcutaneous Delivery Formulations:Transition from intravenous infusion to home-administered regimens could expand addressable patient populations.
- Neonatal Screening Expansion:State-level newborn screening panels in Texas, California, and New York are adding lysosomal storage disorders.
Industry Challenges
- Gene Therapy Manufacturing Scale-Up:Suspension cell culture and downstream purification bottlenecks limit batch yields for clinical-grade material.
- Cross-Border Patient Access Coordination:Treatment center concentration in major metropolitan hubs creates logistical complexity for rural and international families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morquio Syndrome Treatment Market |
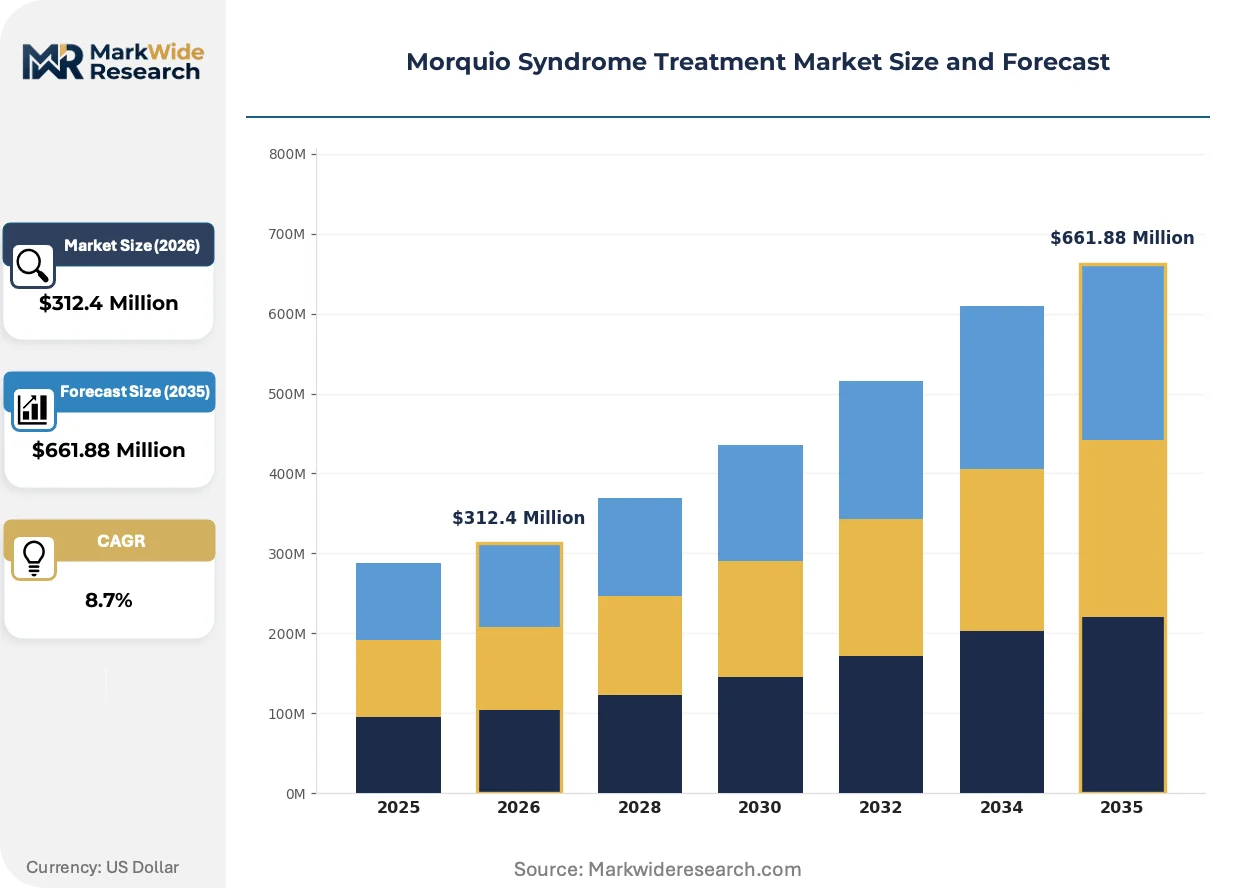
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Supportive Care, Surgical Intervention End User: Pediatrics, Adults, Clinics, Research Institutions Treatment Approach: Symptomatic Management, Disease-Modifying Treatments, Experimental Therapies, Multidisciplinary Care Administration Route: Intravenous, Subcutaneous, Oral, Intraosseous |
| Companies Covered | JCR Pharmaceuticals Co., Ltd., Ultragenyx Pharmaceutical Inc., BioMarin Pharmaceutical Inc., Alexion Pharmaceuticals Inc., Shire, Sanofi, Sangamo Therapeutics, Concert Pharmaceuticals, Inc., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morquio Syndrome Treatment Market Emerging Trajectories
Next-generation delivery platforms and adaptive regulatory frameworks are restructuring competitive positioning across the Morquio syndrome therapeutic landscape.
AAV serotype engineering is miniaturizing immunogenicity profiles while enhancing tissue tropism for skeletal and cardiac tissues. Pediatric gene therapy programs at academic medical centers in Boston, Philadelphia, and London are adopting these vectors for first-in-human protocols. The technology is miniaturizing exclusion criteria related to pre-existing neutralizing antibodies, expanding eligible patient pools by an estimated one-third in screening cohorts.
EMA's adaptive pathway pilot for regenerative medicines is compressing confirmatory evidence timelines for gene therapies. Developers now pursue conditional approval based on biomarker endpoints with post-authorization efficacy studies. Ultrarare disease sponsors in the Netherlands, Sweden, and Italy are leveraging this framework to secure national reimbursement ahead of traditional marketing authorization.
Patient advocacy organizations are consolidating procurement influence through centralized treatment access programs. The National MPS Society and similar entities in Canada and Australia now coordinate travel logistics, insurance navigation, and clinical trial matching. This channel consolidation is shifting prescribing influence from individual physicians to organized patient networks with dedicated case management resources.
Morquio Syndrome Treatment Market Segmentation
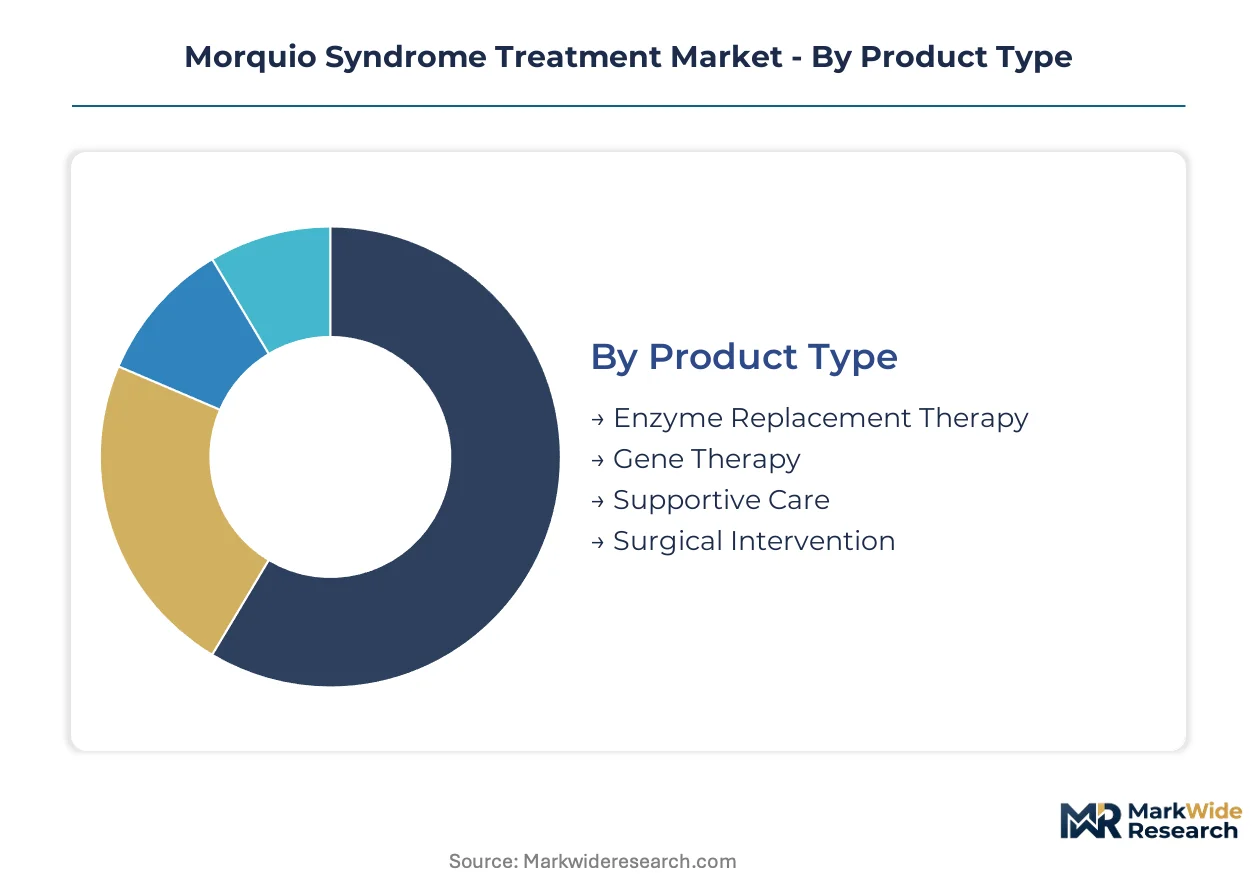
Morquio syndrome treatment flows through distinct commercial channels shaped by regulatory approval status, reimbursement complexity, and patient acuity. Segmentation reveals where manufacturing investment concentrates and where clinical trial recruitment faces friction.
Product Type:
Channel mix varies sharply across modalities: enzyme replacement ships through specialty pharmacy distributors with cold-chain logistics, while gene therapy requires treatment center administration with embedded genetic counseling.
- Enzyme Replacement Therapy:Intravenous infusions of recombinant N-acetylgalactosamine-6-sulfatase constitute the only FDA-approved disease-modifying option. Pediatric specialty centers in the United States and Germany anchor demand, constrained by biologics manufacturing concentration in Massachusetts and Switzerland contract organizations.
- Gene Therapy:AAV-based vectors delivering functional GALNS or GLB1 genes target single-dose durability. Academic medical centers in Boston, Philadelphia, and London drive clinical access, with EMA conditional marketing authorization pathways accelerating European site activation.
- Supportive Care:Orthopedic, respiratory, and pain management protocols lacking disease-modifying economics.
- Surgical Intervention:Spinal decompression and hip reconstruction procedures for skeletal complications.
By volume, enzyme replacement leads. By growth pace, gene therapy is ahead.
End User:
Cost tier separation dominates: pediatric patients command premium pricing through orphan drug frameworks, while adult populations face reimbursement gaps where treatment initiation occurred after skeletal damage.
- Pediatrics:Early-diagnosed patients under 18 years with preserved ambulatory function represent the addressable population for disease-modifying therapy. Texas, California, and New York newborn screening expansion is compressing diagnostic delay.
- Adults:Patients with established skeletal deformities require supportive and surgical management with limited enzyme replacement eligibility.
- Clinics:Multidisciplinary centers coordinating genetics, orthopedics, and pulmonology.
- Research Institutions:Academic sites running gene therapy trials with NIH and EU funding.
By patient count, pediatrics dominates enrollment. By revenue per patient, research institutions command premium protocol fees.
Treatment Approach:
Application urgency determines margin structure: disease-modifying treatments carry biologic manufacturing costs, while symptomatic management fragments across lower-margin service billing.
- Symptomatic Management:Pain control, mobility assistance, and respiratory support without altering disease trajectory. Physical therapy and assistive device provisioning concentrates in Germany and Japan rehabilitation networks.
- Disease-Modifying Treatments:Interventions altering natural history through substrate reduction or enzyme restoration.
- Experimental Therapies:Early-phase gene editing and stem cell protocols.
- Multidisciplinary Care:Coordinated cardiology, ophthalmology, and neurosurgery consultations.
By current revenue contribution, disease-modifying treatments anchor the market. By pipeline velocity, experimental therapies are climbing fastest.
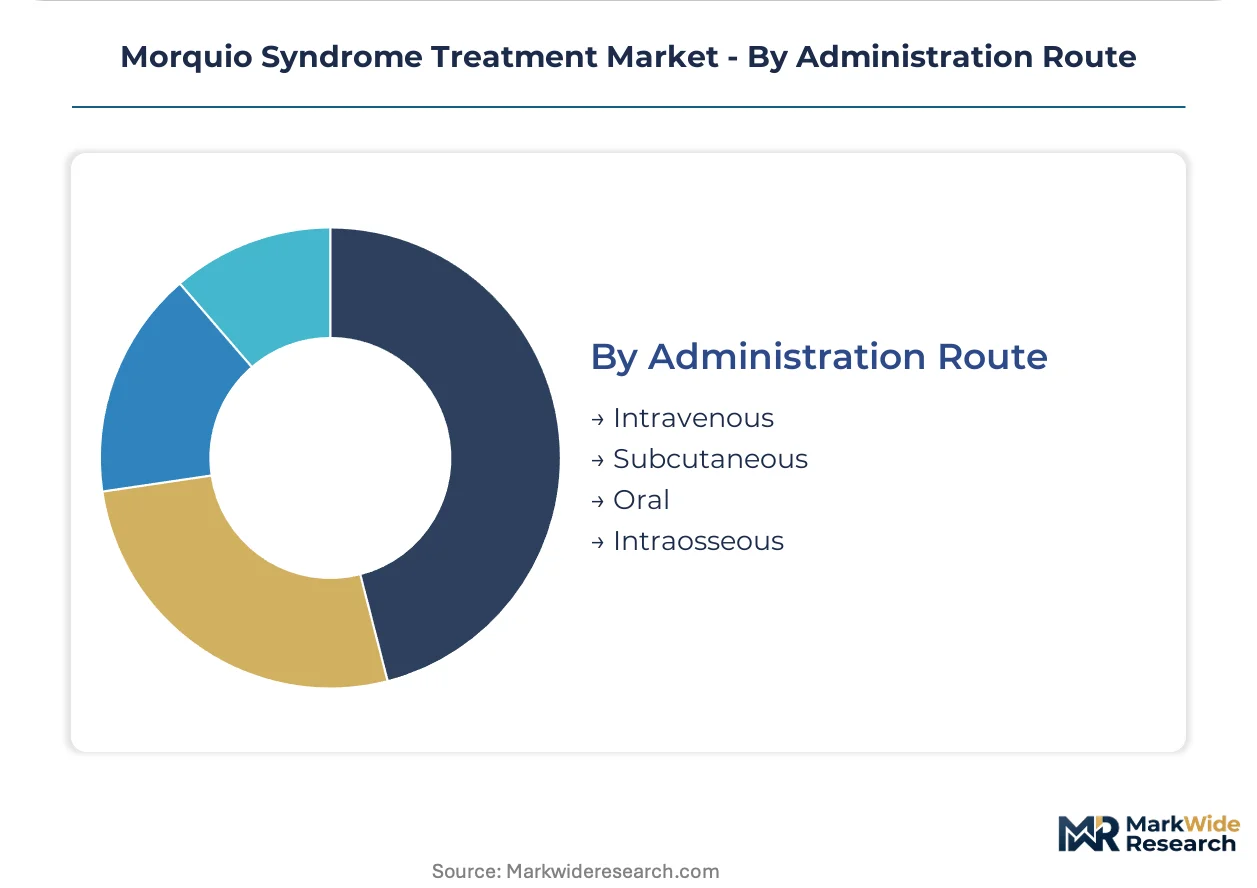
Administration Route:
Supply concentration shapes access: intravenous capacity clusters at academic medical centers, while subcutaneous development aims to decentralize into home settings.
- Intravenous:Weekly to biweekly infusions requiring infusion center infrastructure. Hospital-based administration in the United States, Germany, and Japan limits rural patient access and drives travel coordination through National MPS Society programs.
- Subcutaneous:Investigational formulations targeting home administration with auto-injector delivery.
- Oral:Substrate reduction therapy candidates in preclinical development.
- Intraosseous:Direct skeletal delivery experimental approaches for bone-targeted gene transfer.
By installed treatment capacity, intravenous leads. By development priority, subcutaneous commands the steepest resource allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug incentives in the United States, Germany, and Japan concentrate clinical trial infrastructure and reimbursement frameworks for Morquio syndrome therapeutics. Pediatric specialty centers in these markets anchor diagnostic and treatment access. Regulatory designations from FDA, EMA, and PMDA compress development timelines and shape commercial viability.
United States
Pediatric specialty centers in Boston, Philadelphia, and New York drive enzyme replacement adoption through established lysosomal storage disorder programs. FDA orphan drug designation and priority review vouchers attract venture capital into ultra-rare disease pipelines. Texas, California, and New York newborn screening expansion compresses diagnostic delay and expands addressable patient pools.
Germany
Academic medical centers in Munich, Hamburg, and Berlin coordinate multidisciplinary care protocols for skeletal and respiratory complications. EMA conditional marketing authorization pathways permit earlier patient access based on surrogate endpoints. The country's national health technology assessment body demands extended durability evidence before formulary inclusion for gene therapy candidates.
Japan
PMDA sakigake designation offers expedited consultations and early approval for innovative therapies addressing unmet needs in this ultra-rare indication. Takeda Pharmaceutical leverages domestic regulatory expertise and Asia-Pacific distribution reach. Pediatric specialty centers in Tokyo and Osaka anchor regional patient access and clinical trial recruitment.
United Kingdom
Academic medical centers in London and Manchester adopt AAV serotype engineering for first-in-human gene therapy protocols. NHS England's specialized commissioning framework determines reimbursement for enzyme replacement through national centers of excellence. The country's national health technology assessment body evaluates cost-effectiveness against quality-adjusted life year thresholds.
Switzerland
Contract manufacturing organizations in Basel and Zurich control viral vector production capacity for gene therapy clinical-grade material. Swissmedic regulates advanced therapy medicinal products through expedited pathways for regenerative medicines. The country's biologics manufacturing concentration creates supply security dependencies for developers across European markets.
Morquio Syndrome Treatment Market Vendor Landscape
Listed leaders compete with private specialists across regulatory strategy and manufacturing scale in the Morquio syndrome treatment space. The market structure concentrates around enzyme replacement incumbents with established biologics infrastructure and emerging gene therapy developers with vector engineering capabilities. Three archetypes dominate: large-cap diversified pharmaceuticls with rare disease divisions, mid-cap rare disease specialists with pediatric commercial infrastructure, and clinical-stage gene therapy developers with academic partnerships. Competitive moves center on manufacturing capacity reservations for viral vector production and strategic partnerships for neonatal screening program access.
Within the rare disease specialist tier, Ultragenyx Pharmaceutical Inc. and BioMarin Pharmaceutical Inc. exemplify archetypes with established pediatric prescriber relationships and biologics manufacturing scale. Takeda Pharmaceutical Company Limited occupies a position bridging Japanese regulatory expertise with Asia-Pacific distribution reach. JCR Pharmaceuticals Co., Ltd. represents the regional specialist model with concentrated domestic infrastructure. These named entities anchor industry-level commentary on competitive positioning without asserting specific strategic actions or market shares.
| Leading Market Players |
|---|
| JCR Pharmaceuticals Co., Ltd. |
| Ultragenyx Pharmaceutical Inc. |
| BioMarin Pharmaceutical Inc. |
| Alexion Pharmaceuticals Inc. |
| Shire |
| Sanofi |
| Sangamo Therapeutics |
| Concert Pharmaceuticals, Inc. |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply Flow & Price Mechanics
Capacity reservation agreements with Swiss and Massachusetts contract manufacturing organizations lock in viral vector production slots and provide multi-year price visibility for gene therapy developers navigating biologics manufacturing bottlenecks. These structures transfer supply risk to sponsors while securing batch allocation for clinical-grade material.
Pricing Analysis
Certification level (FDA-grade, EMA-grade, PMDA-grade) creates the primary spread across enzyme replacement and gene therapy tiers, with orphan drug designation commanding premium positioning through priority review vouchers and tax incentives. Value-based pricing models predominate in single-payer markets where national health technology assessment bodies evaluate cost-effectiveness against quality-adjusted life year thresholds. Pricing pressure stems from gene therapy durability uncertainty constraining payer willingness to accept premium pricing for single-dose interventions. Pediatric specialty centers demonstrate lowest price sensitivity due to orphan drug reimbursement frameworks, while adult supportive care segments face intensifying cost compression.
Supply Chain Analysis
Inventory lead times for clinical-grade viral vectors extend eighteen to twenty-four months due to suspension cell culture bottlenecks and downstream purification capacity constraints. Manufacturing concentrates in Switzerland, Massachusetts, and Japan, where contract organizations control AAV production for gene therapy candidates. Raw material dependencies include plasmid DNA, transfection reagents, and specialized media formulations sourced from limited qualified suppliers. Single-source vulnerability pervades viral vector production, with batch failures cascading into clinical trial delays. Distribution runs through cold-chain specialty pharmacy networks for enzyme replacement and direct-to-treatment-center delivery for gene therapy protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morquio syndrome treatment sits at an early-cycle expansion story where neonatal screening expansion in Texas, California, and New York compresses diagnostic delay and enlarges the addressable pediatric population for disease-modifying therapy.
For Market Incumbents: Consolidate manufacturing capacity reservations with Basel and Zurich contract organizations to defend against gene therapy vector supply competition. Deepen backward integration into plasmid DNA production to reduce single-source dependency for clinical-grade material. Lock in long-term offtake agreements with pediatric specialty centers before subcutaneous delivery formulations decentralize treatment access.
For New Entrants and Emerging Players: Anchor in Japan's PMDA sakigake designation pathway to secure expedited approval and national reimbursement ahead of European market access. Target adult supportive care segments where reimbursement gaps and limited enzyme replacement eligibility create white-space opportunity for orthopedic and respiratory management protocols. Pursue strategic partnerships with National MPS Society chapters for patient identification and clinical trial recruitment.
For Investors and Strategic Acquirers: The market sits at a pre-inflection phase that favors clinical-stage gene therapy developers with academic medical center partnerships and validated AAV serotype platforms. Long-term viability hinges on durability data maturation and corresponding value-based payment structure acceptance. Watch for gene therapy manufacturing scale-up milestones as the inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Pivotal gene therapy trials at Boston and Philadelphia academic centers validate AAV serotype engineering for skeletal tropism. |
| Regulatory Approval Pathway | EMA conditional marketing authorization permits earlier patient access based on surrogate biomarker endpoints. |
| Manufacturing Scale-Up | Suspension cell culture capacity expansion in Swiss contract organizations addresses viral vector batch yield constraints. |
| Neonatal Screening Expansion | State-level newborn screening panel additions in Texas and California compress diagnostic delay for early intervention. |
| Subcutaneous Formulation Development | Auto-injector delivery platforms target home administration to expand addressable patient populations beyond infusion centers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, EMA conditional marketing authorization pathways, ClinicalTrials.gov entries, and national health technology assessment body evaluations. Drug development executives, regulatory affairs leads at rare disease specialists, formulary directors at pediatric specialty centers, and payer access specialists provided qualitative input. Bottom-up patient population estimates triangulate against top-down revenue aggregation across enzyme replacement, gene therapy, and supportive care segments.
Segmentation dimensions modeled include treatment modality, patient age cohort, administration route, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves for disease-modifying therapies and scenario-weighted gene therapy approval timelines. Forecast inputs incorporate newborn screening expansion rates, manufacturing capacity buildout schedules, and national reimbursement negotiation outcomes.
Material uncertainties — gene therapy durability data maturation, manufacturing batch failure rates, and payer value assessment revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway efficiency and pricing latitude retention. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Radiation Proctitis Treatment Market
Medical Treatment
Global Sciatica Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market