
 Non-Steroidal Anti-Inflammatory API Market | 2026-2036
Non-Steroidal Anti-Inflammatory API Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Steroidal Anti-Inflammatory API Market Insights
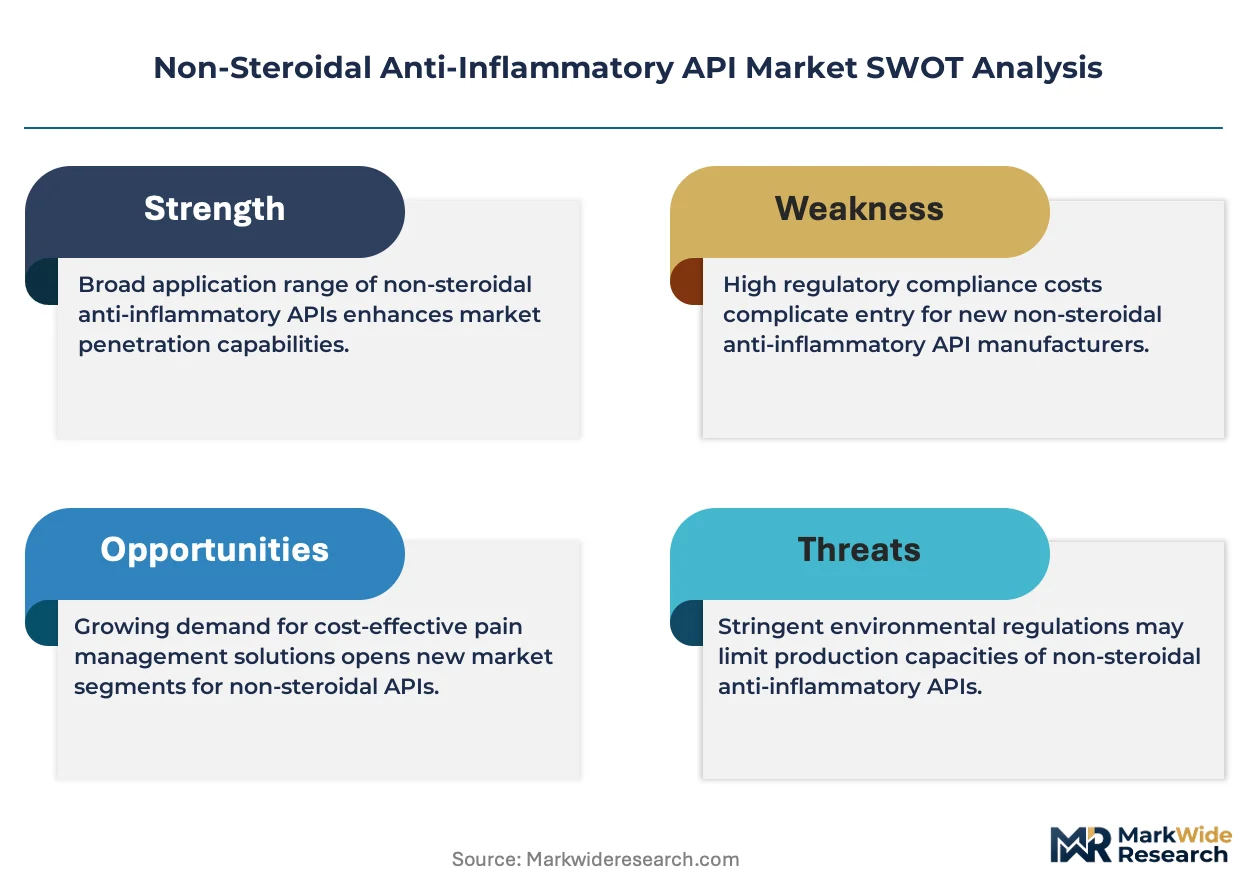
Project finance and leasing arrangements for multi-purpose API reactor trains is reconfiguring competitive entry barriers, allowing mid-scale producers to access capacity without full capital ownership. Dr. Reddy's Laboratories leverages its vertically integrated Kakinada facility to sustain cost leadership in ibuprofen sodium. Lonza Group competes through specialized continuous-flow manufacturing capabilities that reduce solvent waste. Aurobindo Pharma anchors its position with backward integration into key starting materials for diclofenac synthesis.
Non-steroidal anti-inflammatory active pharmaceutical ingredients comprise synthetic organic compounds that inhibit cyclooxygenase enzymes, typically manufactured through multi-step catalytic hydrogenation and acylation reactions with stringent control of polymorph purity and residual solvent limits. Their primary commercial purpose is to serve as the pharmacologically active core of finished dosage forms targeting pain, inflammation, and fever across prescription and over-the-counter channels. Ibuprofen dominates volume throughput due to its established safety profile and broad OTC accessibility, while ketoprofen occupies a narrower premium position in topical and transdermal delivery systems where dermatological compatibility commands higher unit economics. Oral delivery mode retains the largest share of API consumption, though injectable formulations for post-operative pain management represent the fastest-growing demand pool as hospitals seek alternatives to opioid analgesics.
The FDA enforces ICH Q3D elemental impurity guidelines and nitrosamine risk assessment protocols that determine batch release eligibility for US-bound API shipments. EMA's REACH and MDR frameworks impose parallel substance registration and clinical evidence requirements that shape European sourcing decisions. India's CDSCO aligns with ICH standards through its Schedule M manufacturing compliance audits, creating a convergent regulatory baseline that simplifies multi-territory supply qualification. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence study design changes that could abruptly alter acceptable API specification windows.
Market Dynamics
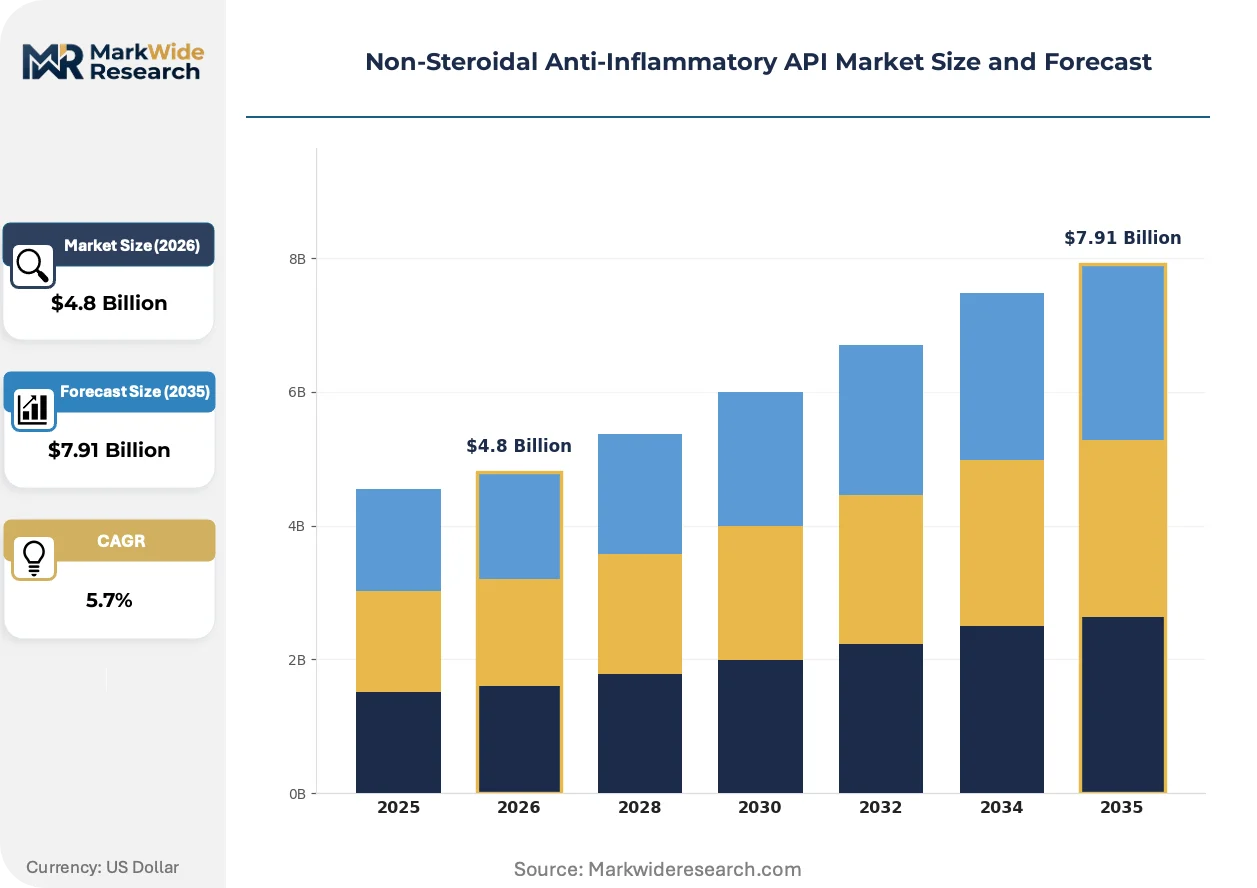
API manufacturers face intensifying pressure from FDA nitrosamine impurity mandates that require costly purification upgrades, while chronic pain prevalence in aging demographics pulls volume through generic channels. This regulatory-demand tension defines current competitive positioning.
Growth Catalysts
- ICH Q3D Compliance Convergence:India's CDSCO alignment with international elemental impurity standards streamlines multi-territory qualification for contract manufacturers serving North American and European formulation clients.
- Post-Operative Pain Protocols:Hospital systems seeking opioid alternatives are expanding injectable NSAID formularies, creating dedicated demand pools for parenteral-grade ketoprofen and diclofenac APIs.
- Continuous-Flow Manufacturing:Adoption of specialized reactor technologies by mid-scale producers reduces solvent waste volumes and accelerates batch cycle times without full capital ownership of fixed assets.
Market Restraints
- Purification Capex Burden:FDA-mandated nitrosamine risk assessment protocols force suppliers to deploy advanced chromatographic separation systems, elevating fixed cost structures for batch release eligibility.
- Starting Material Concentration:Backward integration into acylation precursors for diclofenac synthesis concentrates among Indian integrated players, limiting sourcing flexibility for European and North American formulators.
- Topical Formulation Substitution:Transdermal NSAID delivery systems face displacement pressure from lidocaine patches and capsaicin formulations in dermatology and sports medicine channels.
Strategic Opportunities
- Latin American Generic Expansion:Underpenetrated markets in Brazil and Mexico present white space for ibuprofen API suppliers as ANVISA accelerates abbreviated new drug application reviews for chronic pain indications.
- Continuous Processing Convergence:Integration of flow chemistry with real-time analytical release testing enables manufacturers to compress specification verification timelines and capture premium pricing for just-in-time supply contracts.
- Green Chemistry Incentives:EMA's REACH framework and EU Green Deal solvent reduction mandates create competitive advantage for producers with catalytic hydrogenation routes that minimize organic solvent throughput.
Industry Challenges
- Polymorph Control Expertise:Batch-to-batch consistency in ibuprofen crystal form specification requires specialized process analytical technology talent that remains scarce outside established manufacturing clusters.
- Legacy Equipment Retrofit Complexity:Multi-purpose reactor trains designed for batch operations face integration friction with continuous-flow modules, extending validation timelines for hybrid manufacturing configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Steroidal Anti-Inflammatory API Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ibuprofen, Naproxen, Diclofenac, Ketoprofen End User: Pharmaceutical Manufacturers, Contract Manufacturers, Research Institutions, Distributors Delivery Mode: Oral, Injectable, Topical, Transdermal Application: Pain Management, Fever Reduction, Inflammation Control, Arthritis Treatment |
| Companies Covered | Pfizer Inc., Dr. Reddy's Laboratories Ltd., Bayer AG, Aurobindo Pharma, Teva Pharmaceutical Industries Ltd., AstraZeneca, Boehringer Ingelheim Group, Lonza Group, Cambrex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Steroidal Anti-Inflammatory API Market Trends and Innovations
Process intensification technologies are compressing traditional manufacturing economics while regulatory transparency requirements reshape supplier qualification protocols. These forces are reconfiguring how API value is captured across the supply chain.
Continuous-flow catalytic hydrogenation is collapsing the cost structure for high-volume NSAID synthesis. Generic pharmaceutical manufacturers in India and Europe are retrofitting existing facilities with modular skid-mounted reactors that eliminate solvent recovery bottlenecks. This technology compression enables mid-scale entrants to achieve parity with vertically integrated leaders on unit production costs.
EMA's nitrosamine risk assessment guidance and FDA parallel impurity profiling requirements are forcing real-time analytical release testing adoption. Suppliers must deploy high-resolution mass spectrometry at-line to demonstrate batch safety before shipment. European formulation companies are responding by consolidating qualified supplier lists to those with verified continuous monitoring capabilities.
Hospital procurement consortia are consolidating NSAID API purchasing through long-term offtake agreements with nominated manufacturers. This channel concentration displaces spot-market transactions and rewards suppliers with demonstrated regulatory track records across multiple pharmacopeias. The shift is most visible in North American health system buying groups seeking supply security for injectable post-operative pain formulations.
Non-Steroidal Anti-Inflammatory API Market Segmentation
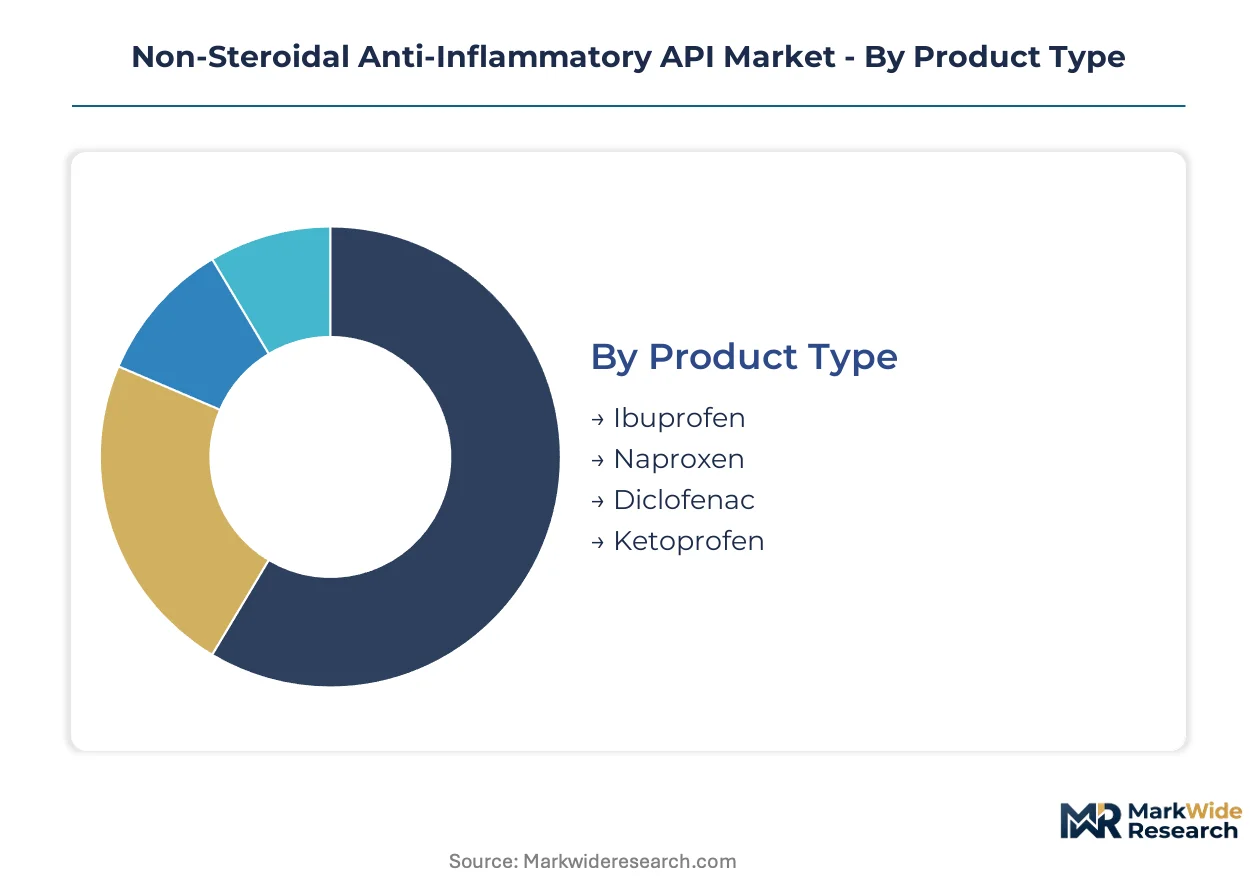
NSAID API procurement patterns diverge sharply across product chemistries and delivery specifications, with purification-grade requirements and regulatory filing histories determining supplier-customer matching. Pharmaceutical formulators select API categories based on bioequivalence study portfolios, polymorph control capabilities, and territory-specific pharmacopeial compliance.
Product Type:
After-sales technical support intensity varies dramatically across NSAID chemistries, with complex synthesis routes demanding sustained process analytical technology assistance from API suppliers.
- Ibuprofen:Manufactured through acylation and catalytic hydrogenation of isobutylbenzene derivatives, this high-volume API commands specification discipline around residual solvent limits and crystal polymorphism. Demand concentrates in Indian and Chinese contract manufacturing facilities serving North American OTC formulation clients, pulled by chronic pain prevalence in aging US and European populations.
- Diclofenac:Synthesis requires controlled Friedel-Crafts acylation and nitration steps with stringent nitrosamine impurity profiling under FDA protocols. Procurement clusters among vertically integrated Indian producers with backward integration into key starting materials, limiting sourcing flexibility for European formulators seeking multi-supplier qualification.
- Naproxen:Chiral resolution during manufacturing demands specialized enzymatic separation or crystallization expertise.
- Ketoprofen:Narrower volume position serving topical and parenteral formulation specialists.
Ibuprofen holds the largest share; momentum sits with ketoprofen as hospital systems expand injectable post-operative pain protocols.
End User:
Customer type determines contract structure, with volume commitments and regulatory filing support obligations scaling across the procurement hierarchy.
- Pharmaceutical Manufacturers:Vertically integrated formulators with captive API needs or long-term supply agreements. These buyers prioritize pharmacopeial multi-compendial compliance and documented nitrosamine risk assessment protocols for US and European submissions.
- Contract Manufacturers:CDMOs serving branded and generic clients require flexible batch sizing and rapid specification verification. Demand concentrates in India's Hyderabad and Ahmedabad clusters, where CDSCO-aligned facilities qualify simultaneously for FDA and EMA inspections.
- Research Institutions:Small-batch procurement for clinical trial material synthesis and formulation development.
- Distributors:Inventory-holding intermediaries bridging API producers with smaller formulation accounts.
Pharmaceutical manufacturers dominate procurement volume; contract manufacturers are expanding most quickly as outsourcing consolidates across the industry.
Delivery Mode:
Formulation technology dictates API specification tiers, with parenteral grades commanding premium pricing for endotoxin and particulate control.
- Oral:Standard-grade APIs for tablet and capsule manufacturing represent the baseline consumption pool, with specification windows defined by USP and EP monographs for dissolution profile consistency.
- Injectable:Parenteral-grade ketoprofen and diclofenac require sterile manufacturing environments and endotoxin testing protocols. Hospital procurement consortia in the US are consolidating purchasing through nominated supplier agreements as opioid-alternative protocols expand.
- Topical:Semi-solid formulation bases with dermatological compatibility requirements.
- Transdermal:Patch-compatible APIs with enhanced permeation characteristics for sustained release.
Oral delivery retains the largest share; injectable formulations gain share fastest on post-surgical pain management demand.
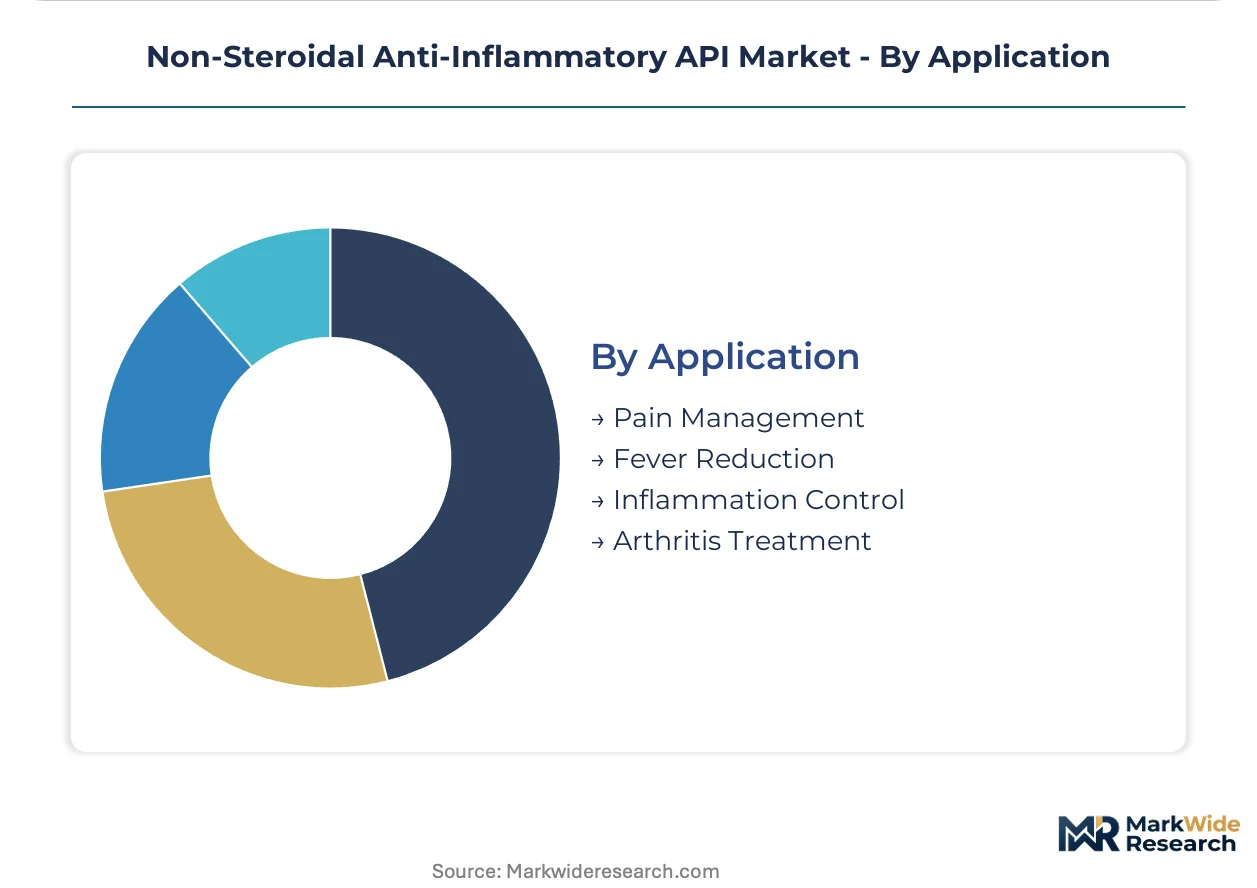
Application:
Therapeutic indication shapes API selection criteria, with chronic versus acute use patterns influencing stability and bioequivalence study design.
- Pain Management:The core demand driver spanning acute post-operative, chronic musculoskeletal, and neuropathic indications. Ibuprofen and diclofenac APIs dominate procurement for this indication, with formulators prioritizing batch-to-batch dissolution consistency for bioequivalence maintenance.
- Arthritis Treatment:Long-term dosing protocols for osteoarthritis and rheumatoid arthritis require API suppliers with demonstrated stability data and impurity profiling across extended shelf-life claims. European formulators emphasize EMA REACH compliance for chronic exposure risk assessment.
- Fever Reduction:OTC pediatric and adult antipyretic applications with compressed specification margins.
- Inflammation Control:Post-traumatic and autoimmune-mediated inflammatory indications.
Pain management commands the largest share; arthritis treatment shows the steepest expansion trajectory on aging demographics and extended dosing protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics define regional positioning, with India and China supplying raw material conversion while the United States and Germany absorb finished API volumes for formulation. Trade flows concentrate on nitrosamine-compliant shipments qualifying for FDA and EMA release protocols.
United States
Hospital procurement consortia drive injectable NSAID API demand as opioid-alternative protocols expand across health systems. FDA nitrosamine risk assessment mandates filter qualified supplier lists to those with verified continuous monitoring capabilities. New Jersey and North Carolina clusters host formulation operations sourcing parenteral-grade ketoprofen from nominated Indian contract manufacturers.
India
Hyderabad and Ahmedabad manufacturing hubs supply ibuprofen and diclofenac APIs to North American and European generic formulators under CDSCO-aligned ICH Q3D compliance. The country's PLI scheme incentivizes domestic API production to reduce import dependence on Chinese starting materials. Kakinada facilities anchor vertically integrated ibuprofen sodium production for cost-competitive export positioning.
Germany
EMA REACH framework and EU Green Deal solvent reduction mandates shape sourcing decisions for chronic pain indication APIs. Bavarian and North Rhine-Westphalia chemical parks specialize in continuous-flow catalytic hydrogenation technologies that minimize organic solvent throughput. German formulators prioritize suppliers with demonstrated polymorph control expertise for bioequivalence maintenance.
China
Zhejiang and Jiangsu provinces concentrate acylation precursor manufacturing for diclofenac synthesis, though nitrosamine profiling upgrades lag Indian competitors. NMPA alignment with ICH standards accelerates for domestic market release, yet export qualification to FDA jurisdictions requires additional purification investments. Environmental inspections under dual carbon goals constrain batch chemical expansion.
Brazil
ANVISA abbreviated new drug application reviews for chronic pain indications open procurement opportunities for ibuprofen API suppliers. São Paulo and Rio de Janeiro formulation clusters rely on imported APIs from Indian contract manufacturers due to limited domestic synthesis capacity. Local distributors bridge supply gaps for smaller generic pharmaceutical accounts.
Non-Steroidal Anti-Inflammatory API Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the synthesis chain. The vendor base stratifies between vertically integrated pharmaceutical conglomerates with captive API needs and independent contract manufacturers serving outsourced demand. Two archetypes dominate: scale-driven commodity producers optimizing reactor throughput for high-volume ibuprofen, and precision specialists capturing premium positioning in parenteral-grade ketoprofen. Competitive moves center on backward integration into key starting materials and continuous-flow technology licensing to compress batch cycle economics.
Among Indian integrated pharmaceutical manufacturers, Dr. Reddy's Laboratories and Aurobindo Pharma exemplify the scale-specialist archetype through Kakinada and Hyderabad facility positioning. Lonza Group represents the precision-tier model with Swiss-based continuous manufacturing capabilities. These three anchors demonstrate how geographic clustering and process technology differentiation create defensible supply positions under tightening FDA and EMA impurity protocols.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Bayer AG |
| Aurobindo Pharma |
| Teva Pharmaceutical Industries Ltd. |
| AstraZeneca |
| Boehringer Ingelheim Group |
| Lonza Group |
| Cambrex Corporation |
| Others |
Pricing and Supply Chain Analysis
Hyderabad's API manufacturing cluster anchors global ibuprofen sodium supply, with reactor utilization rates at Kakinada and Ahmedabad facilities directly translating into downstream pricing leverage for North American generic formulators. CDSCO-aligned compliance investments concentrate procurement power among Indian contract manufacturers serving FDA-bound shipments.
Pricing Analysis
Pharmaceutical manufacturers anchor contract-based long-term offtake agreements that compress spot-market volatility for parenteral-grade ketoprofen. Pricing stratifies across USP-grade premium, EP-compliant standard, and multi-compendial economy tiers, with FDA nitrosamine certification commanding measurable premiums. Cost compression in standard-grade ibuprofen is intensifying because Chinese acylation precursor suppliers face environmental inspection constraints. Hospital procurement consortia exhibit lowest price sensitivity due to opioid-alternative protocol mandates, while smaller generic distributors face acute margin pressure.
Supply Chain Analysis
Export control regimes on catalytic hydrogenation technologies limit flow chemistry equipment transfers to emerging API producers, constraining capacity expansion outside established clusters. Supply concentrates in India, China, and Germany, with Zhejiang province feeding acylation precursors into Indian conversion facilities. The chain draws from isobutylbenzene derivatives, nitration intermediates, and chiral resolution enzymes. Single-source vulnerability concentrates in backward-integrated diclofenac starting material production. Distribution runs through nominated supplier agreements with hospital procurement consortia displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as chronic pain prevalence in aging demographics pulls volume through generic channels, repeating demand patterns last visible during prior patent cliff cycles.
For Market Incumbents: Harden nitrosamine risk assessment protocols through at-line high-resolution mass spectrometry deployment, defending against FDA batch rejection threats. Consolidate supplier qualification lists by acquiring CDSCO-aligned Indian contract manufacturers with verified continuous monitoring capabilities. Capacity addition in Bavarian chemical parks anchors European REACH compliance positioning.
For New Entrants and Emerging Players: Pursue Latin American white space as ANVISA accelerates abbreviated new drug application reviews for chronic pain indications, with Brazil and Mexico showing underpenetrated generic penetration. Target parenteral-grade ketoprofen production for hospital procurement consortia seeking opioid alternatives. License modular continuous-flow reactor skids to bypass legacy equipment capital barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-commodity play because FDA and EMA impurity protocol convergence creates durable competitive moats for verified suppliers. Acquisition targets cluster around mid-scale Indian producers with backward integration into diclofenac starting materials. The signal to watch is CDSCO audit frequency acceleration as proxy for multi-territory qualification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Manufacturing Scale-Up | Modular reactor deployment at Hyderabad facilities compresses solvent waste volumes and accelerates FDA batch release timelines. |
| Backward Integration into Acylation Precursors | Kakinada captive production of isobutylbenzene derivatives insulates Dr. Reddy's Laboratories from Chinese environmental inspection disruptions. |
| Nitrosamine Risk Assessment Infrastructure | At-line mass spectrometry investments separate qualified suppliers from batch rejection exposure under tightened FDA protocols. |
| Latin American Distribution Partnerships | São Paulo distributor alliances bridge supply gaps for ANVISA-registered generic formulators lacking direct Indian procurement relationships. |
| Green Chemistry Certification Pathway | EMA REACH solvent reduction compliance opens premium positioning for Bavarian producers with catalytic hydrogenation expertise. |
Research Methodology
A spread of perspectives from API plant managers, regulatory affairs leads at Indian contract manufacturers, hospital procurement managers, and generic pharmaceutical formulation executives converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA 483 inspection observations, EMA nitrosamine guidance documents, CDSCO Schedule M audit reports, and US customs import data. Bottom-up capacity utilization modeling and top-down therapeutic demand estimation triangulated volume assumptions.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation across product chemistry, delivery mode specification, and regional regulatory cluster. CAGR derivation rested on reactor throughput expansion rates, chronic pain epidemiology trends, and hospital formulary adoption curves for injectable NSAID alternatives. Modeled inputs included polymorph control capability scarcity and continuous-flow technology licensing velocity.
Macroeconomic conditions sit as an overlay; deviation in Indian rupee-denominated production costs or EU carbon border adjustment mechanisms would shift the trajectory. Forecasts reflect documented assumptions on CDSCO-FDA inspection parity maintenance and nitrosamine protocol stability. Material shifts in US hospital procurement consortium consolidation or Chinese environmental enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Traveler's Diarrhea Treatment Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Alirocumab Market