
 Radiation Oncology Market | 2026-2036
Radiation Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Oncology Market Intelligence
Demand from specialized Cancer Treatment Centers is bifurcating the traditional, large-scale hospital procurement model. This shift favors vendors with flexible and highly precise technology platforms. Varian Medical Systems leverages its extensive installed base to maintain a leading market position. Elekta AB differentiates with advanced software and systems for stereotactic radiosurgery, while Accuray Incorporated competes through its unique robotic delivery technologies.
Radiation oncology is a medical discipline that uses ionizing radiation to deliver a prescribed dose to a tumor volume, aiming to destroy cancerous cells. This process relies on complex equipment like Linear Accelerators, which generate high-energy X-rays or electrons for treatment. Linear Accelerators constitute the core product category due to their versatility in treating a wide range of cancers. In terms of application, treatments for Breast Cancer and Prostate Cancer represent significant and established volume segments.
Device manufacturers must navigate stringent approval pathways set by bodies like the US Food and Drug Administration (FDA) and secure CE marking under Europe's Medical Device Regulation (MDR). In China, the National Medical Products Administration (NMPA) governs market access and product registration, creating a distinct compliance landscape. Future competitiveness will depend on aligning technological innovation with evolving reimbursement policies and the push for value-based healthcare outcomes.
Market Dynamics
The bifurcation of procurement, driven by specialized cancer centers demanding flexible and high-precision platforms, is the central force shaping the market. This trend marks a departure from the traditional, large-scale consolidated purchasing model common in general hospitals.
Growth Catalysts
- Image-Guided Radiation Therapy:The integration of advanced imaging into treatment delivery improves targeting accuracy, reduces side effects, and boosts patient outcomes, driving adoption by leading cancer centers.
- Aging Global Population:A demographic shift towards older populations is increasing the incidence rates of cancers, particularly prostate and breast cancer, expanding the core patient volume for radiotherapy.
- Government Investment:National cancer control plans in countries like Germany and the United States are channeling funds into advanced radiotherapy infrastructure, accelerating equipment replacement cycles.
Market Restraints
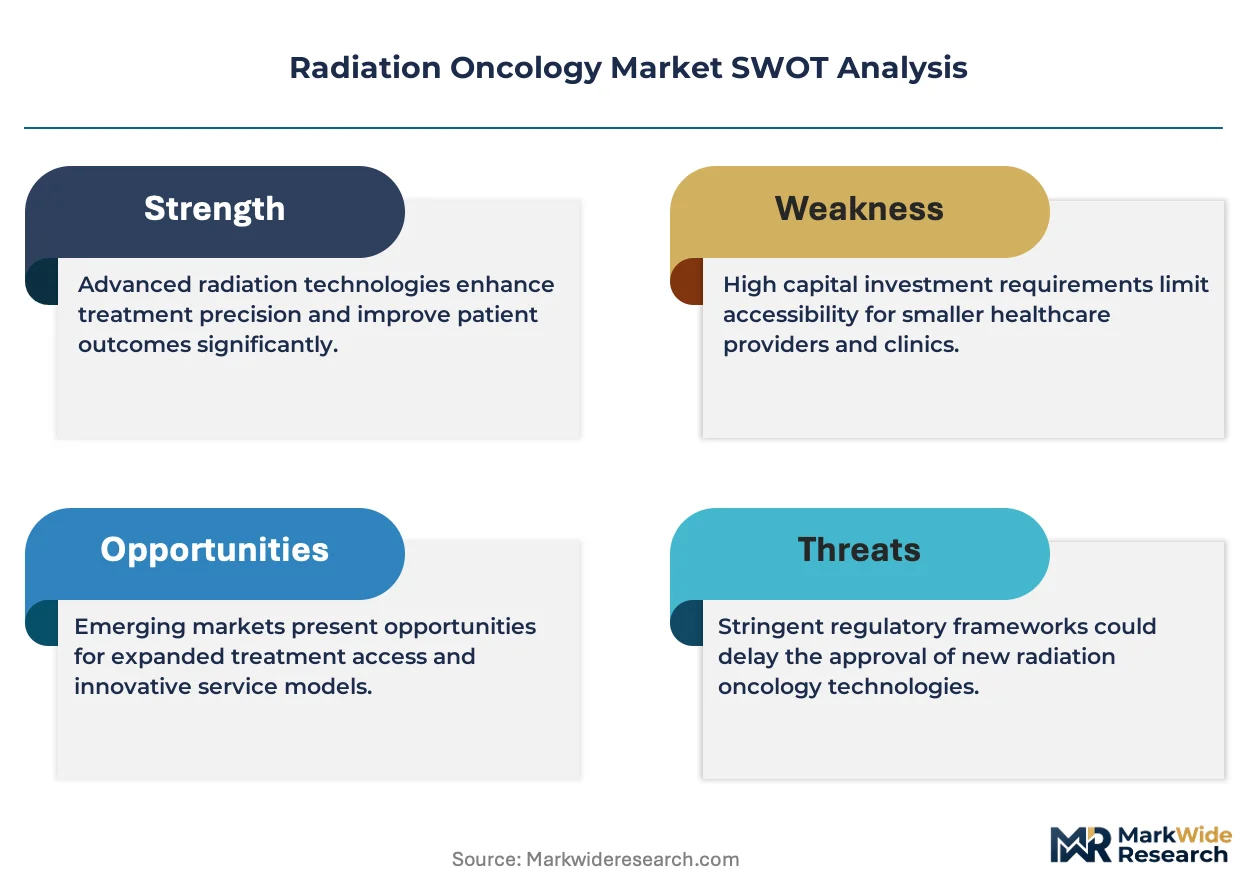
- High Capital Expenditure:The substantial cost of acquiring, installing, and maintaining linear accelerators and associated facilities limits adoption, particularly in resource-constrained healthcare systems and smaller clinics.
- Stringent Regulatory Hurdles:Protracted approval timelines under frameworks like the FDA's 510(k) or PMA pathways and Europe's MDR delay market entry for new technologies.
- Technical Complexity:Operating advanced radiotherapy systems requires highly specialized personnel, and a shortage of trained medical physicists and dosimetrists can constrain treatment capacity.
Strategic Opportunities
- AI in Treatment Planning:Integrating artificial intelligence algorithms can automate and optimize the creation of treatment plans, reducing planning time while improving plan quality and consistency across institutions.
- Emerging Market Expansion:Significant underpenetration of radiotherapy services in large parts of Asia and Latin America presents a major growth vector for vendors offering scalable and cost-effective solutions.
- Hypofractionation Protocols:The clinical validation of treatment regimens with fewer, higher-dose radiation fractions creates an opportunity for technologies optimized for stereotactic body radiation therapy (SBRT).
Industry Challenges
- Data Interoperability:Integrating new radiation therapy systems with disparate hospital information systems (HIS) and electronic health records (EHR) remains a significant operational hurdle for healthcare providers.
- Reimbursement Policy Uncertainty:Evolving payment models and reimbursement cuts for certain radiotherapy procedures in markets like the US create financial pressure on treatment centers.
- Public Perception of Radiation:Overcoming patient and public concerns regarding radiation exposure requires continuous education and communication efforts by healthcare providers and industry stakeholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Oncology Market |
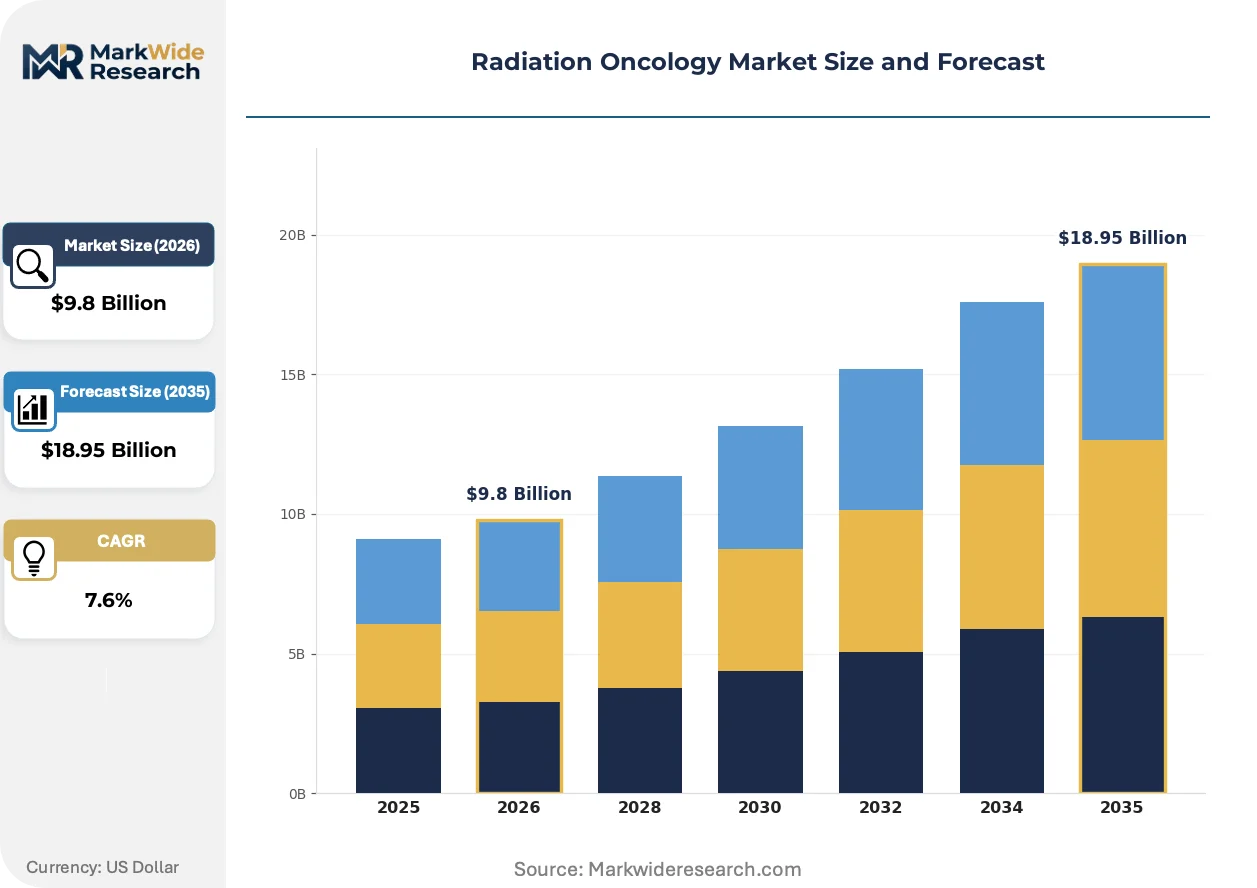
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Brachytherapy Equipment, Proton Therapy Systems, Radiation Dosimeters, Imaging Systems Application: Breast Cancer, Lung Cancer, Prostate Cancer, Brain Tumors, Cervical Cancer End User: Hospitals, Cancer Treatment Centers, Research Institutes, Ambulatory Surgical Centers Delivery Mode: External Beam Radiation Therapy, Internal Radiation Therapy, Systemic Radiation Therapy, Image-Guided Radiation Therapy |
| Companies Covered | Varian Medical Systems, Elekta AB, Accuray Incorporated, IBA, Mevion Medical Systems, Canon Medical Systems Corporation, Curium, BD, Brainlab AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Oncology Market Strategic Shifts & Innovations
A fundamental transition toward personalized and adaptive radiotherapy is underway. This shift prioritizes real-time adjustments to treatment plans based on patient-specific anatomical changes, moving away from static, one-size-fits-all protocols.
Compact proton therapy systems are a key evolution, using smaller synchrocyclotrons to reduce facility footprints. Specialized cancer centers are the primary adopters, seeking to add proton capabilities without major construction. This technology is miniaturizing the infrastructure for advanced particle therapy, making it accessible to more institutions.
Europe's Medical Device Regulation (MDR) introduces rigorous requirements for clinical evaluation and post-market surveillance. This impacts equipment manufacturers, who must generate more extensive data to obtain and maintain CE marking. The regulation forces companies with broad portfolios to strategically reassess which products to support in the EU market.
A shift from single-vendor ecosystems to a multi-vendor, best-of-breed approach is changing purchasing behavior. This pattern disrupts the model where a linear accelerator purchase dictated software choices. This change is most visible in academic medical centers demanding open APIs to select specialized tools from different vendors.
Radiation Oncology Market Segmentation
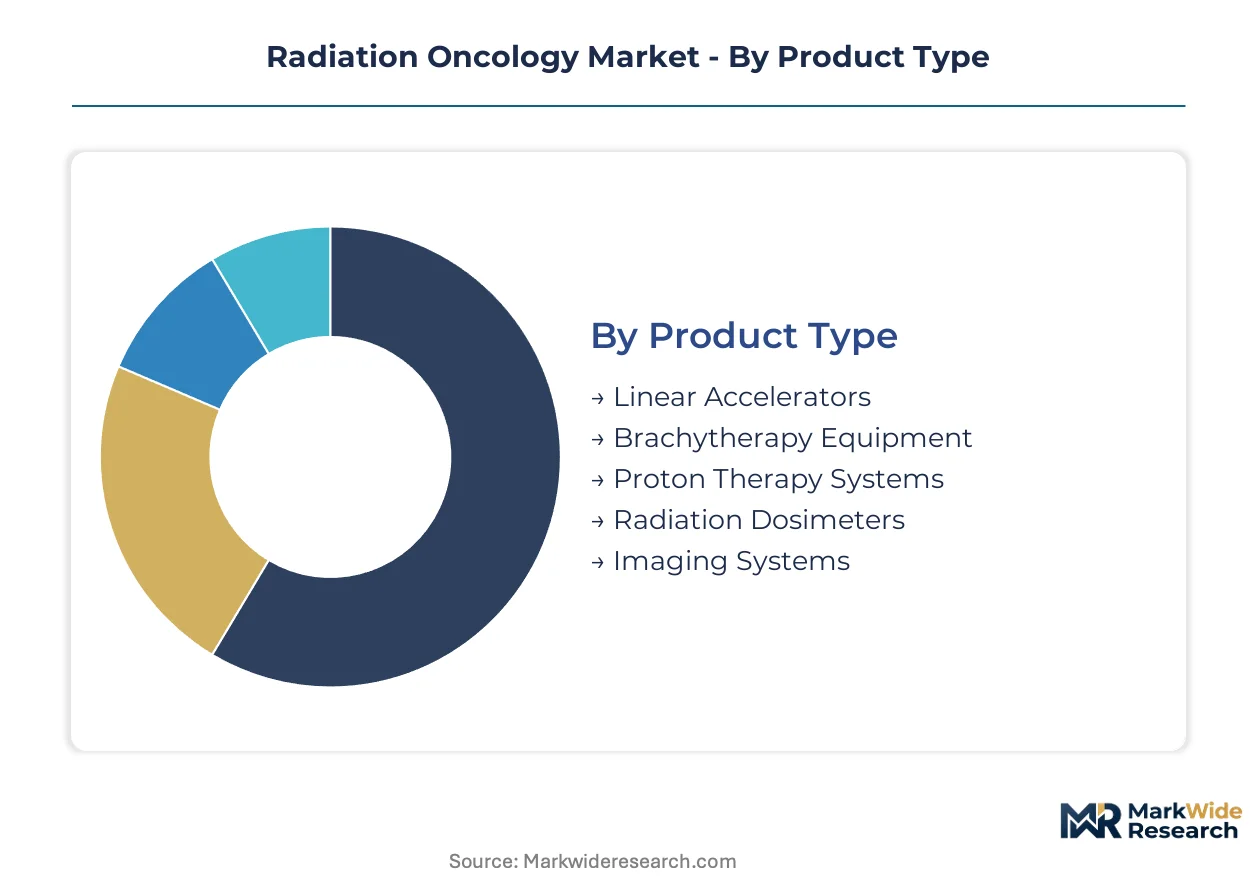
Understanding the distinct segments within the Radiation Oncology Market is crucial for identifying areas of concentrated value creation and evolving demand patterns. Each category reveals specific technological preferences, clinical applications, and end-user requirements influencing market dynamics.
Product Type:
Profitability within product type segmentation often concentrates in highly specialized and technologically advanced systems.
- Linear Accelerators:These devices generate high-energy X-rays or electrons for external beam treatments. Demand concentrates in established cancer centers in the United States, driven by their versatility across numerous cancer types.
- Proton Therapy Systems:These systems utilize protons to deliver a precise radiation dose with minimal exit dose. Adoption is increasing among specialized cancer treatment centers in Germany, seeking to enhance treatment precision for pediatric and complex cases.
- Brachytherapy Equipment:This equipment delivers radiation internally via implanted radioactive sources for localized treatment.
- Radiation Dosimeters:These instruments measure radiation exposure to ensure patient and staff safety during procedures.
- Imaging Systems:These technologies provide real-time visualization for accurate tumor targeting and patient positioning during therapy.
Linear Accelerators hold significant installed capacity. Proton Therapy Systems are rotating up the share rankings.
Application:
Volume drivers within application segmentation reflect the prevalence and treatability of specific cancer types.
- Breast Cancer:Radiation therapy often follows surgery or chemotherapy to reduce recurrence risk in breast cancer patients. Global demand for treatment is substantial, driven by high incidence rates across older populations.
- Prostate Cancer:This cancer type is frequently treated with external beam radiation or brachytherapy, often as a primary therapy. Demand is significant in countries like the United States due to an aging demographic and established screening protocols.
- Lung Cancer:Radiation is crucial for both curative intent and palliative care in lung cancer management.
- Brain Tumors:Stereotactic radiosurgery offers precise, high-dose treatment for intracranial lesions.
- Cervical Cancer:Radiotherapy is a standard treatment protocol for cervical cancer, often combined with chemotherapy.
Treatments for Breast Cancer and Prostate Cancer represent established volume segments. Therapies for Brain Tumors are expanding most quickly.
End User:
Procurement patterns among end users vary, reflecting differing capital expenditure budgets and specialization requirements.
- Cancer Treatment Centers:These specialized facilities prioritize flexible, high-precision platforms for advanced therapies. Investment in countries like Germany supports their demand for cutting-edge equipment.
- Hospitals:Traditional large-scale procurement models still operate within general hospitals, often seeking versatile systems for broad patient populations. Their purchasing decisions are influenced by existing infrastructure.
- Research Institutes:These organizations focus on developing novel radiation therapy techniques and protocols.
- Ambulatory Surgical Centers:These centers are increasingly adopting radiation therapy for specific, less complex cases.
Hospitals historically held the largest share of equipment. Cancer Treatment Centers are driving a diversification of the purchasing landscape.
Delivery Mode:
Technological innovation within delivery modes focuses on enhancing precision and minimizing collateral damage to healthy tissues.
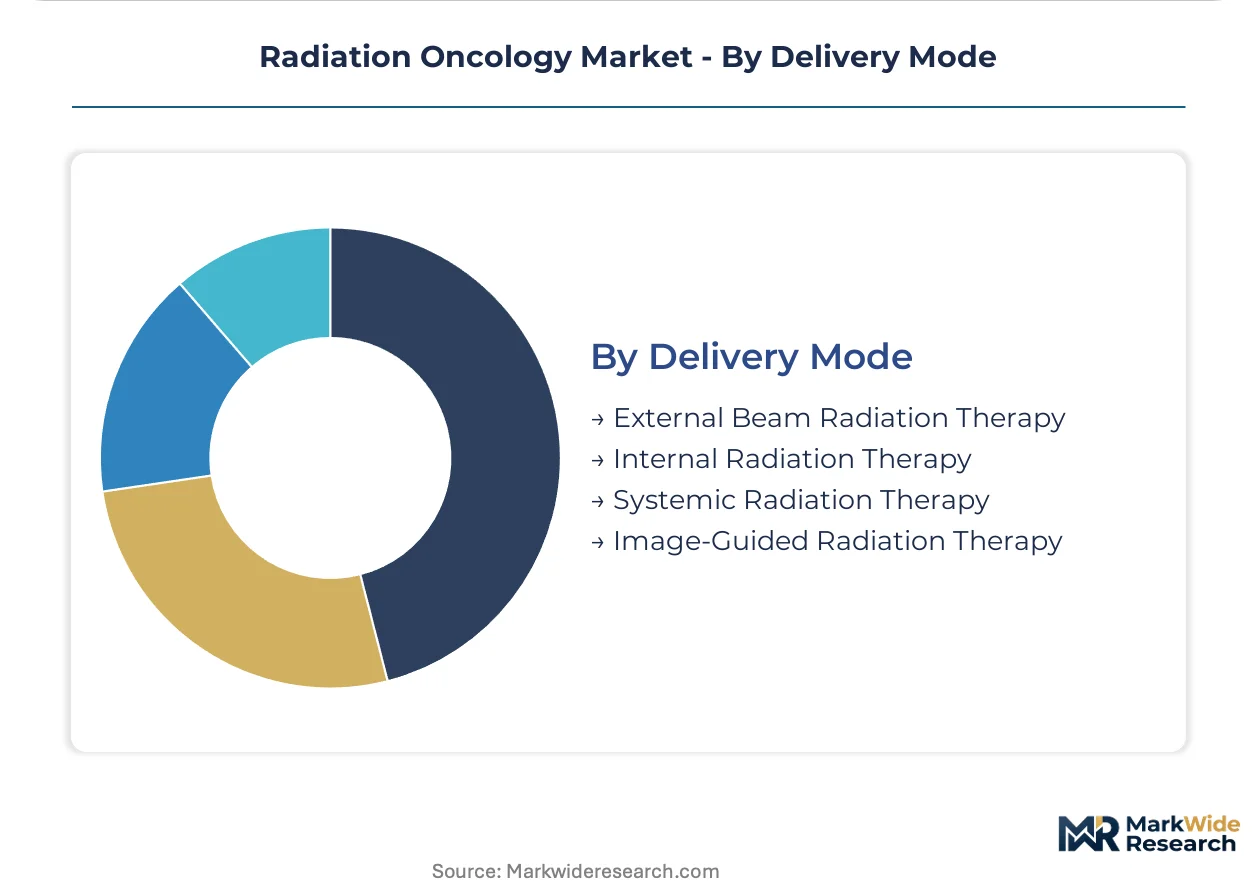
- External Beam Radiation Therapy:This mode delivers radiation from outside the body using machines like linear accelerators. This remains the most widely used globally due to its broad applicability across various cancer sites.
- Image-Guided Radiation Therapy:This method integrates imaging during treatment to confirm tumor position and adjust radiation delivery in real-time. Leading cancer centers in the United States are increasingly adopting this technology to improve targeting accuracy.
- Internal Radiation Therapy:This technique involves placing radioactive sources directly into or near the tumor.
- Systemic Radiation Therapy:This approach administers radioactive substances that travel through the bloodstream to target cancer cells throughout the body.
External Beam Radiation Therapy forms the foundational approach. Image-Guided Radiation Therapy is improving treatment efficiency and outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration sits with technologically advanced healthcare systems in North America and Europe, driving demand for sophisticated radiation oncology equipment. These regions lead in infrastructure investment and specialized cancer treatment centers. Emerging economies in Asia and Latin America are expanding their radiotherapy capabilities, aiming to address significant underpenetration.
United States
Demand for advanced radiation therapy is driven by high cancer incidence rates and a focus on precision medicine. The US Food and Drug Administration (FDA) regulatory pathways influence technology adoption and market entry for new devices. Major cancer research centers in cities like Houston and Boston actively integrate Image-Guided Radiation Therapy into clinical practice.
Germany
Specialized cancer treatment centers in Germany are increasing adoption of proton therapy systems, seeking enhanced treatment precision. The national cancer control plans support significant investment in advanced radiotherapy infrastructure. Medical technology clusters in regions like Bavaria and Baden-Württemberg foster innovation in radiation oncology equipment manufacturing.
China
Expanding healthcare access and a rising cancer burden fuel demand for both linear accelerators and emerging technologies. The National Medical Products Administration (NMPA) governs market access and product registration, creating a distinct compliance landscape. Large metropolitan areas such as Beijing and Shanghai are establishing advanced radiotherapy facilities to meet patient needs.
India
Underpenetration of radiotherapy services presents a substantial growth vector, particularly for scalable and cost-effective solutions. Government initiatives to improve cancer care infrastructure influence procurement decisions across public and private hospitals. Major medical hubs like Mumbai and Delhi are witnessing increased investment in modern radiation oncology departments.
Brazil
Aging demographics contribute to a growing patient volume requiring radiation therapy for common cancers. Regulatory bodies like ANVISA oversee medical device approvals, impacting market entry for international manufacturers. Metropolitan regions such as São Paulo and Rio de Janeiro are central to the development of advanced cancer treatment facilities.
Radiation Oncology Market Key Industry Players
Concentration sits with established multinational corporations offering comprehensive radiation oncology portfolios, while specialized innovators target niche segments. The market structure exhibits a tiered consolidation, with a few dominant players alongside numerous smaller, specialized technology providers. Competitive moves frequently involve strategic partnerships to integrate AI-driven planning software and focused geographic expansion into emerging markets.
Within the high-precision technology tier, Varian Medical Systems and Elekta AB represent leading positions, leveraging extensive installed bases and advanced software platforms. Accuray Incorporated exemplifies differentiation through unique robotic delivery systems, addressing specific clinical needs for stereotactic treatments. These companies anchor innovation in treatment delivery and patient outcomes.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Accuray Incorporated |
| IBA |
| Mevion Medical Systems |
| Canon Medical Systems Corporation |
| Curium |
| BD |
| Brainlab AG |
| Others |
Cost & Logistics Intelligence
Project-based procurement for advanced radiation oncology systems locks in both supply access and price visibility for specialized cancer centers. This model mitigates volatility in high-value equipment acquisitions.
Pricing Analysis
Volume-discount tiering structures influence pricing for linear accelerators and associated software platforms. Price differentiation stems from certification levels, such as FDA approval, and the breadth of after-sales service bundles. Pricing pressure stems from the push for value-based healthcare outcomes, particularly in public health systems. General hospitals are most price-sensitive, while specialized cancer centers prioritize technology features and precision.
Supply Chain Analysis
Strategic stockpiles of critical components are preferred by manufacturers of radiation oncology equipment, mitigating single-source vulnerabilities. Geographic supply concentration for advanced components sits with Germany, the United States, and Japan. Raw material dependencies include specialized alloys for shielding and high-purity rare earths for imaging detectors. Regulatory restrictions, such as export controls on advanced technologies, represent a structural risk. Distribution runs through direct sales forces and specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radiation oncology market is undergoing a platform-economics inflection, driven by the shift towards multi-vendor, best-of-breed software ecosystems. Open APIs are enabling greater interoperability and choice for treatment centers.
For Market Incumbents:Shield existing installed bases by investing in software upgrades and integration services that support multi-vendor environments. Deepen vertical integration into AI-driven treatment planning to counter emerging software-only entrants. Capacity additions in emerging markets, like India, can expand reach. Prioritizing CE marking under Europe's MDR ensures market access against regulatory threats.
For New Entrants and Emerging Players:NMPA fast-track pathways in China for innovative medical devices present a penetrable segment for new entrants. Target underpenetrated radiotherapy services in Latin America with scalable and cost-effective solutions. Go-to-market angles should emphasize AI integration for workflow optimization and improved plan quality. Focus on specialized software tools with open APIs to integrate into existing hardware platforms.
For Investors and Strategic Acquirers:Mid-cap software developers specializing in AI for treatment planning represent attractive acquisition targets for long-term viability. The market favors companies enhancing precision and efficiency over the next decade. Strategic acquirers should seek firms with strong intellectual property in adaptive radiotherapy. A signal to watch is clinical validation of new hypofractionation protocols driving demand for SBRT-optimized technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Software Integration | Enhances existing hardware platforms with AI-driven treatment planning capabilities for better patient outcomes. |
| Emerging Market Expansion | Addresses significant underpenetration of radiotherapy services in regions like Asia and Latin America. |
| Regulatory Compliance Investment | Secures market access and product longevity under stringent frameworks like Europe's MDR and China's NMPA. |
| Proton Therapy System Miniaturization | Reduces facility footprint and capital expenditure, making advanced particle therapy accessible to more institutions. |
| Open API Development | Fosters multi-vendor ecosystems, allowing specialized cancer centers to select best-of-breed software solutions. |
Research Approach
Initial hypotheses were tested against primary input from medical physicists, radiation oncologists, and hospital procurement managers and refined through iterative analysis. Secondary validation drew from FDA filings, NMPA product registrations, and industry association reports. This approach ensured a balanced perspective through bottom-up and top-down triangulation of market data.
Variance decomposition identified key drivers impacting market growth across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and delivery mode, alongside regional regulatory differences. Compound annual growth rates were derived from historical data trends and projected adoption rates. Industry-specific forecast inputs included cancer incidence rates and government healthcare spending on oncology infrastructure.
The analysis sits within stated boundaries; outcomes outside major shifts in reimbursement policies or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding regulatory stability and healthcare investment trends. Revision becomes warranted when significant changes in global cancer incidence or treatment paradigms cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Oncology Devices Market
Oncology
Angiosarcomas Treatment Market
Oncology
Europe Proton Therapy Market
Oncology
Radiotherapy Market
Oncology
Thymus Cancer Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Hadron Therapy Market
Oncology
Metastatic Cancer Drug Market
Oncology
Bone Cancer Treatment Market
Oncology
Sterile Oncology Injectable Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
Testicular Cancer Treatment Market
Oncology
Pituitary Cancer Market
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
America Cancer Immunotherapy Market
Oncology
Lung Cancer Treatment Market