
 Rabies Treatment Market | 2026-2036
Rabies Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rabies Treatment Market Outlook
Indian vaccine manufacturers is restructuring capacity allocation toward purified Vero cell rabies vaccines to serve domestic immunization programs and export commitments. Serum Institute of India Pvt. Ltd. leverages its large-volume fermentation infrastructure to supply cost-competitive doses across Africa and Southeast Asia. Bharat Biotech International Limited anchors its portfolio on novel vaccine platforms, while Sanofi sustains brand recognition through decades of post-exposure prophylaxis deployment in endemic regions.
Rabies treatment encompasses biological interventions administered after viral exposure to neutralize rabies virus before central nervous system invasion, typically involving tissue-culture or purified duck embryo vaccines combined with rabies immunoglobulin infiltration at wound sites. Vaccines dominate commercial value due to multi-dose regimen requirements for both pre-exposure prophylaxis and post-exposure treatment protocols. Immunoglobulins command premium positioning in emergency care settings where immediate passive immunity proves critical, while intramuscular delivery mode retains clinical preference over subcutaneous alternatives for reliable seroconversion rates.
FDA and EMA standards for lot release testing and potency assays constrain market entry for new biological manufacturers, while WHO prequalification shapes procurement eligibility for developing country immunization programs. India's CDSCO enforces progressively stringent cold chain documentation and pharmacovigilance reporting that elevates compliance costs for domestic producers. Stakeholders must monitor evolving regulatory divergence between stringent market requirements and emerging economy affordability pressures when prioritizing portfolio investments.
Market Dynamics
Post-exposure prophylaxis protocols are tightening manufacturing benchmarks as WHO prequalification standards force emerging producers toward purified Vero cell platforms and enhanced cold chain documentation.
Growth Catalysts
- CDSCO cold chain mandates:India's progressively stringent pharmacovigilance reporting elevates compliance costs but simultaneously filters substandard suppliers, concentrating procurement toward qualified domestic manufacturers.
- Street dog population management:Mass vaccination campaigns across endemic regions sustain recurring demand for human rabies immunoglobulin and tissue-culture vaccine regimens.
- Purified Vero cell technology:Capacity reallocation toward this platform enables manufacturers to meet both domestic immunization programs and export commitments to Africa and Southeast Asia.
Market Restraints
- Fermentation capacity scarcity:Large-volume biological production requires dedicated infrastructure that concentrates supply among a limited set of Indian and multinational manufacturers.
- FDA and EMA lot release testing:Stringent potency assay requirements constrain market entry for new biological producers seeking access to stringent markets.
- Equine rabies immunoglobulin substitution:Cost pressures in public health systems drive partial displacement of human-derived products with lower-cost animal-origin alternatives.
Strategic Opportunities
- Sub-Saharan Africa procurement gaps:WHO prequalification eligibility opens tender participation for Indian manufacturers supplying cost-competitive doses to underpenetrated national immunization programs.
- Novel vaccine platform convergence:mRNA and viral vector technologies intersect with rabies applications, enabling faster immune response induction and dose-sparing regimens.
- Emergency department protocol expansion:Hospital-based post-exposure prophylaxis infiltration protocols create channel innovation opportunities for immunoglobulin suppliers.
Industry Challenges
- Wound-site infiltration technique standardization:Variable clinical training across emergency departments creates inconsistent passive immunity delivery and protocol adherence gaps.
- Seroconversion verification complexity:Rapid fluorescent focus inhibition test requirements for potency confirmation extend batch release timelines and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rabies Treatment Market |
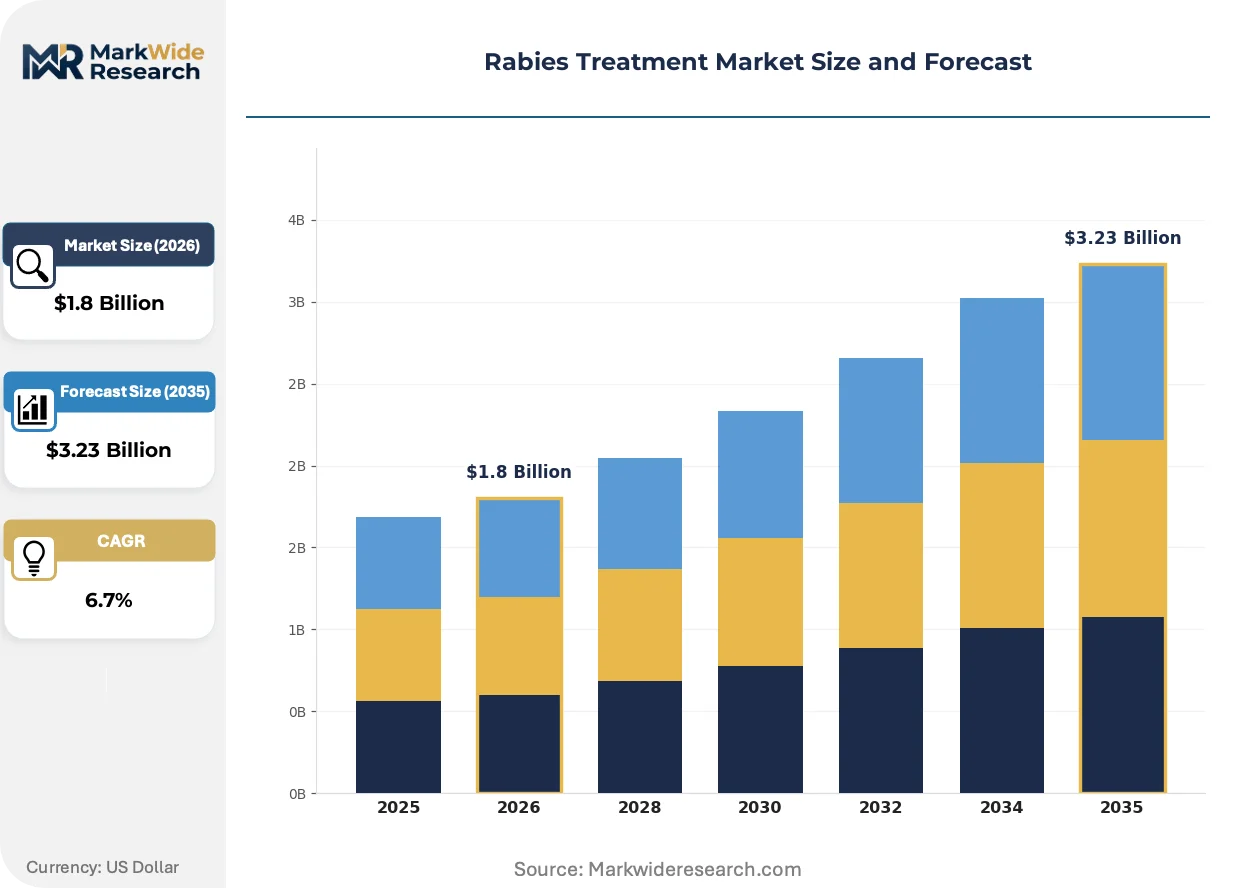
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Immunoglobulins, Antivirals, Therapeutics Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Oral End User: Hospitals, Clinics, Research Laboratories, Home Care Care Setting: Emergency Care, Outpatient Care, Inpatient Care, Veterinary Care |
| Companies Covered | Sanofi, Boehringer Ingelheim, Merck & Co., Inc., Serum Institute of India Pvt. Ltd., Novartis AG, Cadila Pharmaceuticals, Bharat Biotech International Limited, Pfizer, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rabies Treatment Market Strategic Shifts
Manufacturing technology and regulatory harmonization are compressing the gap between emerging economy affordability and stringent market quality benchmarks.
Single-dose device platforms are modularizing rabies vaccine administration by integrating pre-filled syringes with temperature-stable formulations. Rural health clinics in endemic districts are adopting these units to reduce cold chain dependency. The technology is modularizing distribution networks toward point-of-care delivery, bypassing centralized hospital procurement.
EMA's tightening of F-Gas Regulation compliance for cold chain refrigerants is forcing manufacturers toward climate-neutral cooling technologies. Biological producers must retrofit storage and transport infrastructure to meet fluorinated gas phase-down schedules. European distribution networks are responding by consolidating shipments and investing in phase-change material packaging.
Hospital procurement committees are unbundling rabies immunoglobulin from bundled infectious disease contracts. Emergency departments now source passive immunity products through separate tenders emphasizing immediate availability and wound-site infiltration training support. This pattern is most visible in Indian tier-1 cities where private hospital chains centralize pharmacy purchasing decisions.
Rabies Treatment Market Segmentation
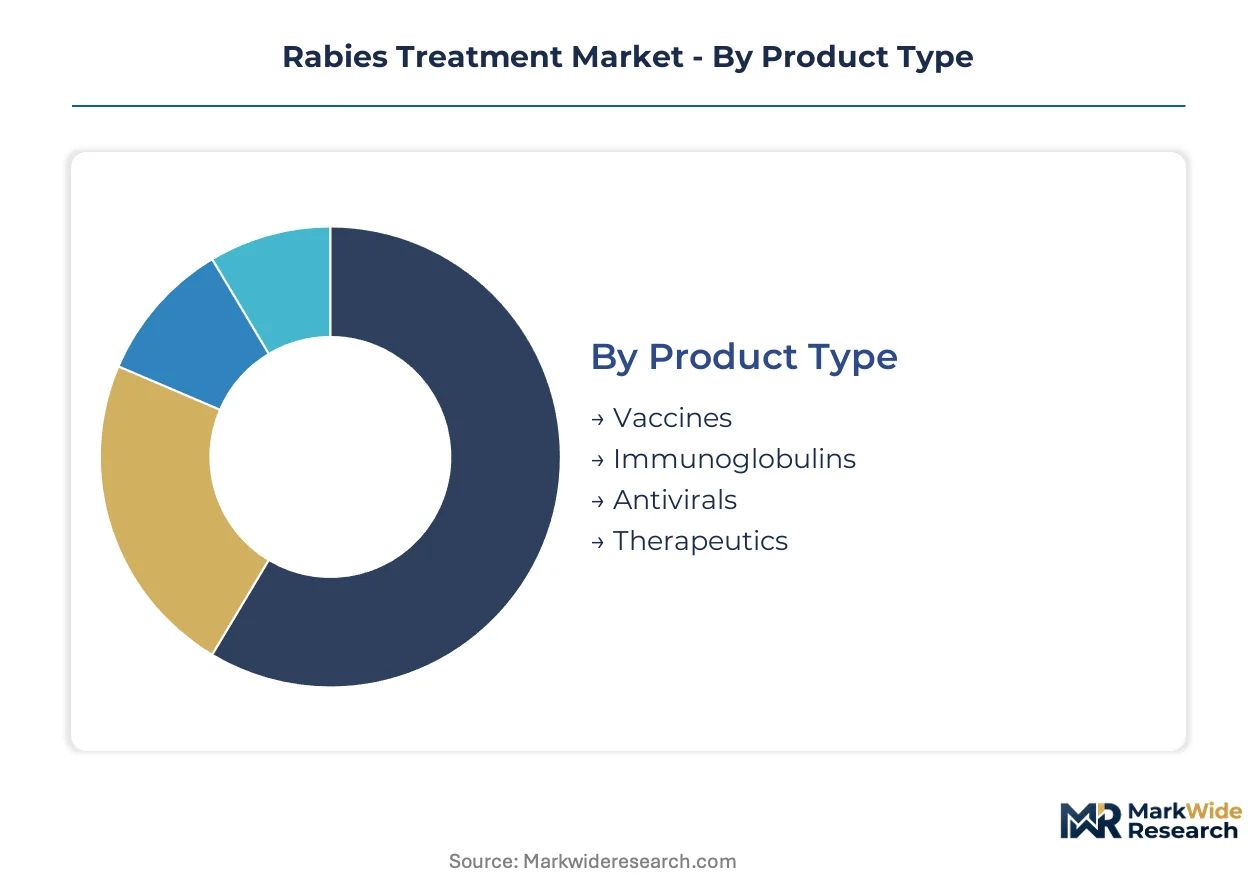
Rabies treatment markets fragment across biological product categories, administration routes, and care settings that each carry distinct regulatory pathways and procurement dynamics. Understanding segment-level demand drivers enables manufacturers to align capacity investments with the highest-velocity channels.
Product Type:
Vaccines and immunoglobulins operate on fundamentally different replacement cycles—vaccines require multi-dose completion regimens while immunoglobulins deliver immediate passive immunity with single administration.
- Vaccines:Purified Vero cell and tissue-culture formulations dominate procurement volumes through WHO prequalified supply channels. Demand concentrates in Indian national immunization programs and Sub-Saharan African tender markets where multi-dose post-exposure prophylaxis protocols sustain recurring orders.
- Immunoglobulins:Human-derived products command premium positioning in emergency department settings where immediate viral neutralization at wound sites proves critical. CDSCO pharmacovigilance mandates are elevating compliance costs but filtering substandard suppliers toward qualified domestic manufacturers.
- Antivirals:Adjunctive agents with limited standalone efficacy in established rabies infection.
- Therapeutics:Experimental modalities including monoclonal antibodies still in clinical development pipelines.
Vaccines sit at the top of the volume ranking, with immunoglobulins climbing the fastest as hospital emergency protocols expand wound-site infiltration requirements.
Delivery Mode:
Route selection directly impacts seroconversion reliability, cold chain requirements, and the feasibility of rural point-of-care deployment.
- Intravenous:Reserved for critical care settings with established vascular access and monitoring capabilities.
- Intramuscular:Retains clinical preference across post-exposure prophylaxis protocols due to proven seroconversion rates and manageable adverse event profiles. WHO guidelines reinforce this route for both vaccine and immunoglobulin administration in endemic regions.
- Subcutaneous:Offers logistical advantages for mass vaccination campaigns but demonstrates variable immune response induction compared to intramuscular alternatives.
- Oral:Limited to veterinary applications and experimental human formulations not yet incorporated into standard protocols.
Intramuscular delivery anchors current procurement volumes, though subcutaneous alternatives are gaining share fastest in resource-constrained outreach settings.
End User:
Procurement authority and reimbursement pathways diverge sharply between institutional purchasers and emerging decentralized channels.
- Hospitals:Emergency departments in Indian tier-1 cities and African referral centers drive immunoglobulin demand through unbundled tender processes. Separate pharmacy committees now source passive immunity products outside bundled infectious disease contracts.
- Clinics:Primary care facilities in endemic districts are adopting single-dose device platforms to reduce cold chain dependency and enable point-of-care administration.
- Research Laboratories:Academic and commercial entities advancing novel vaccine platforms including mRNA and viral vector technologies.
- Home Care:Negligible current penetration given the acute nature of post-exposure intervention requirements.
Hospitals dominate absolute spending, with clinics expanding most quickly through modular distribution networks bypassing centralized procurement.
Care Setting:
Protocol standardization and reimbursement availability vary dramatically across acute intervention versus preventive channels.
- Emergency Care:Hospital-based post-exposure prophylaxis infiltration protocols concentrate immunoglobulin utilization where immediate passive immunity delivery proves time-critical. Wound-site technique standardization remains inconsistent across departments.
- Outpatient Care:Pre-exposure prophylaxis for veterinary workers and travelers sustains vaccine demand through scheduled multi-dose regimens.
- Inpatient Care:Limited to suspected rabies cases requiring supportive management after symptomatic presentation.
- Veterinary Care:Animal vaccination programs reduce human exposure incidence but operate on separate procurement and regulatory tracks.
Emergency care generates the highest per-intervention value, while outpatient channels deliver the steepest volume expansion through preventive programming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India procures rabies biologicals at volumes exceeding any single country, while Brazil manages comparable exposure burdens through distinct public health procurement channels. National immunization programs and street dog population dynamics create divergent demand patterns across endemic regions.
India
Mass vaccination campaigns and the world's largest street dog population sustain procurement volumes for human rabies immunoglobulin and tissue-culture vaccines. CDSCO enforces progressively stringent cold chain documentation and pharmacovigilance reporting that elevates compliance costs for domestic manufacturers. The Pune-Hyderabad corridor concentrates Serum Institute of India and Bharat Biotech facilities supplying cost-competitive doses across Africa and Southeast Asia.
Brazil
Amazon basin exposure incidents and urban canine rabies reservoirs sustain emergency department demand for post-exposure prophylaxis protocols. ANVISA harmonizes manufacturing standards with WHO prequalification benchmarks to enable domestic producer participation in Pan American Health Organization tenders. São Paulo and Rio de Janeiro hospital networks anchor immunoglobulin utilization where private pharmacy committees unbundle procurement from infectious disease contracts.
United States
Wildlife reservoir management in raccoon and bat populations sustains pre-exposure prophylaxis demand among veterinary and conservation workers. FDA lot release testing and potency assay requirements constrain market entry for new biological manufacturers seeking commercial distribution. The Research Triangle Park cluster in North Carolina anchors contract manufacturing organizations supporting domestic vaccine production.
China
Rural bite incidence and expanding tier-2 hospital emergency department capabilities drive post-exposure prophylaxis protocol adoption. NMPA enforces progressively stringent lot release timelines and seroconversion verification standards that extend working capital cycles for domestic producers. The Chengdu-Chongqing corridor concentrates Vero cell vaccine manufacturing capacity serving western provincial immunization programs.
Germany
Travel medicine clinics and occupational health programs for veterinary professionals sustain pre-exposure prophylaxis demand through scheduled multi-dose regimens. EMA tightening of F-Gas Regulation compliance forces manufacturers toward climate-neutral cooling technologies for biological storage and transport. The Rhine-Main metropolitan region anchors hospital procurement committees unbundling rabies immunoglobulin from bundled infectious disease contracts.
Rabies Treatment Market Competitive Environment
Indian producers anchor one tier through large-volume fermentation infrastructure and cost-competitive positioning across developing country tenders; European and North American multinationals hold premium-tier positioning through decades of post-exposure prophylaxis deployment in endemic regions. The market structure concentrates supply among a limited set of manufacturers possessing dedicated biological production capabilities. Three strategic archetypes dominate: scale-driven Indian suppliers, innovation-focused platform specialists, and legacy multinational incumbents. Capacity expansion and WHO prequalification pursuit constitute the dominant competitive moves reshaping procurement eligibility.
Among Indian-based biological manufacturers, Serum Institute of India Pvt. Ltd., Bharat Biotech International Limited, and Cadila Pharmaceuticals exemplify the scale-driven archetype supplying cost-competitive doses to underpenetrated national immunization programs. Sanofi and Novartis AG occupy positions within the legacy multinational tier, leveraging decades of brand recognition and established post-exposure prophylaxis deployment relationships across endemic regions. These named entities serve as anchors for understanding how geographic origin and organizational scale stratify competitive positioning rather than as subjects of specific strategic action claims.
| Leading Market Players |
|---|
| Sanofi |
| Boehringer Ingelheim |
| Merck & Co., Inc. |
| Serum Institute of India Pvt. Ltd. |
| Novartis AG |
| Cadila Pharmaceuticals |
| Bharat Biotech International Limited |
| Pfizer |
| GlaxoSmithKline |
| Others |
Value Chain & Pricing Dynamics
Biological fermentation specialists concentrated in the Pune-Hyderabad corridor anchor labor-cost differentials that widen pricing-tier spreads between Indian scale producers and European cold chain-dependent suppliers. CDSCO compliance investments and WHO prequalification pursuit concentrate margin recovery in qualified domestic manufacturers while filtering substandard entrants.
Pricing Analysis
Capacity additions in India are reshaping price floors for purified Vero cell rabies vaccines across African and Southeast Asian tender markets. Three-tier pricing structure separates WHO-prequalified premium doses from standard domestic immunization supplies and economy equine immunoglobulin alternatives. Price differentiation hinges on cold chain documentation rigor and seroconversion verification standards. Cost compression in public health procurement intensifies as national immunization programs unbundle immunoglobulin from bundled infectious disease contracts. Government tenders demonstrate highest price sensitivity; private hospital emergency departments in Indian tier-1 cities show lowest sensitivity due to immediate availability requirements.
Supply Chain Analysis
Regional distribution centers in Mumbai, Chennai, and Lagos operate hub-and-spoke patterns consolidating temperature-controlled shipments to endemic districts. Manufacturing concentrates in India, China, and Germany, with Vero cell vaccine production anchored in the Pune-Hyderabad and Chengdu-Chongqing corridors. Production draws from fetal bovine serum, specialized cell culture media, and phase-change packaging materials. Single-source vulnerability in large-volume fermentation infrastructure concentrates supply risk among limited qualified manufacturers. Distribution runs through cold chain logistics providers with WHO GDP certification serving hospital procurement committees and national immunization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Purified Vero cell platform standardization enables margin expansion as CDSCO pharmacovigilance mandates filter substandard competitors toward qualified domestic producers. Premium-tier positioning in emergency department unbundled procurement offsets compliance cost elevation.
For Market Incumbents: Deepen backward integration into fetal bovine serum supply and captive cold chain logistics to defend against equine immunoglobulin substitution pressure. Expand fermentation capacity in the Pune-Hyderabad corridor to capture WHO prequalification eligibility for Sub-Saharan African tenders. Prioritize CDSCO pharmacovigilance system investments that filter substandard domestic competitors. For New Entrants and Emerging Players: WHO prequalification standards in Sub-Saharan Africa open a window for cost-competitive purified Vero cell vaccine supply to underpenetrated national immunization programs. Target decentralized clinic channels adopting single-dose device platforms that bypass centralized hospital procurement. Pursue partnership-based distribution through regional hub-and-spoke cold chain networks rather than direct tender participation. For Investors and Strategic Acquirers: Indian biological manufacturers with WHO prequalified status and large-volume fermentation infrastructure are the most active acquirer targets in this space. Long-term viability rests on regulatory compliance moats rather than commodity volume scale. Watch for CDSCO enforcement actions against substandard domestic producers as inflection indicator for qualified manufacturer market share consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Enables tender participation for Indian manufacturers supplying African immunization programs. |
| Cold Chain Infrastructure Expansion | Phase-change material packaging investments respond to EMA F-Gas Regulation compliance requirements. |
| Single-Dose Device Platform Launch | Modular distribution networks bypass centralized hospital procurement for rural clinic point-of-care delivery. |
| Immunoglobulin Wound-Site Training Programs | Hospital emergency department protocol standardization creates channel loyalty for passive immunity suppliers. |
| Novel Vaccine Platform R&D Investment | mRNA and viral vector technologies intersect with rabies applications for dose-sparing regimen development. |
Study Parameters
Multiple input streams — biological manufacturing executives, CDSCO regulatory affairs leads, hospital emergency department procurement managers, and national immunization program officers — were reconciled with secondary validation from FDA lot release documentation, WHO prequalification listings, ClinicalTrials.gov rabies vaccine pipelines, and Indian customs export records. Bottom-up capacity and demand modeling triangulated against top-down epidemiological exposure incidence estimates across endemic regions.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of product type, delivery mode, end user, and care setting dimensions. CAGRs were derived from epidemiological trend extrapolation, procurement pipeline visibility, and manufacturing capacity expansion announcements. Forecast inputs incorporated street dog population management campaign schedules, CDSCO pharmacovigilance mandate implementation timelines, and WHO prequalification eligibility status changes.
Revisions become necessary when regulatory enforcement intensity shifts, novel vaccine platform clinical trial outcomes materialize, or cold chain infrastructure investment patterns diverge from baseline assumptions. Forecasts reflect documented assumptions about epidemiological stability and procurement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Ascites Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Skin Grafts Market
Medical Treatment
Anti-Rickettsial Treatment Market