
 Global Medication Management Market | 2026-2036
Global Medication Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medication Management Market Intelligence
Pharmacy informatics specialist labor is bifurcating the competitive landscape between vendors that can embed clinical decision support and those limited to inventory logistics. Omnicell, Inc. leverages automated dispensing hardware to anchor hospital pharmacy workflows. McKesson Corporation sustains distribution-scale advantages through its control over pharmaceutical supply chain data feeds. Oracle Cerner Corporation competes by extending enterprise EHR integration into medication reconciliation workflows.
Medication management encompasses software, hardware, and clinical protocols that coordinate prescribing, dispensing, administration, and monitoring of pharmaceutical therapies, typically integrating barcode verification, allergy cross-checking, and dose-range validation to prevent adverse drug events. Its primary commercial purpose is reducing preventable medication errors while optimizing inventory turns and regulatory compliance in healthcare delivery organizations. Software Solutions currently lead revenue contribution due to recurring subscription economics and lower capital barriers, while Cloud-Based deployment is displacing on-premises installations as health systems prioritize interoperability and remote access. Automated Dispensing Systems occupy the highest capital-intensity tier, with margin pools concentrating in service contracts and replenishment logistics rather than hardware margins alone.
FDA 21 CFR Part 11 electronic records requirements, the EU MDR's traceability mandates for medical device software, and HIPAA security rule provisions collectively shape product architecture decisions and market access thresholds for vendors serving regulated healthcare environments. Japan's PMDA software-as-medical-device guidance adds a third compliance layer for Asia-Pacific expansion. Stakeholders must monitor how emerging AI-enabled dosing algorithms trigger premarket review pathways across FDA, EMA, and PMDA jurisdictions.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for medication management platforms, forcing incumbent vendors to restructure service delivery models around API-first interoperability rather than monolithic enterprise licensing.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in the United States are accelerating hospital pharmacy digitization timelines and expanding addressable market for compliant software vendors.
- Barcode verification:Integration of point-of-care scanning with allergy cross-checking protocols is reducing adverse drug events and driving replacement demand for legacy dispensing infrastructure.
- Japan's aging demographics:Elderly population concentration is tightening medication adherence requirements and expanding home-based care monitoring deployments.
Market Restraints
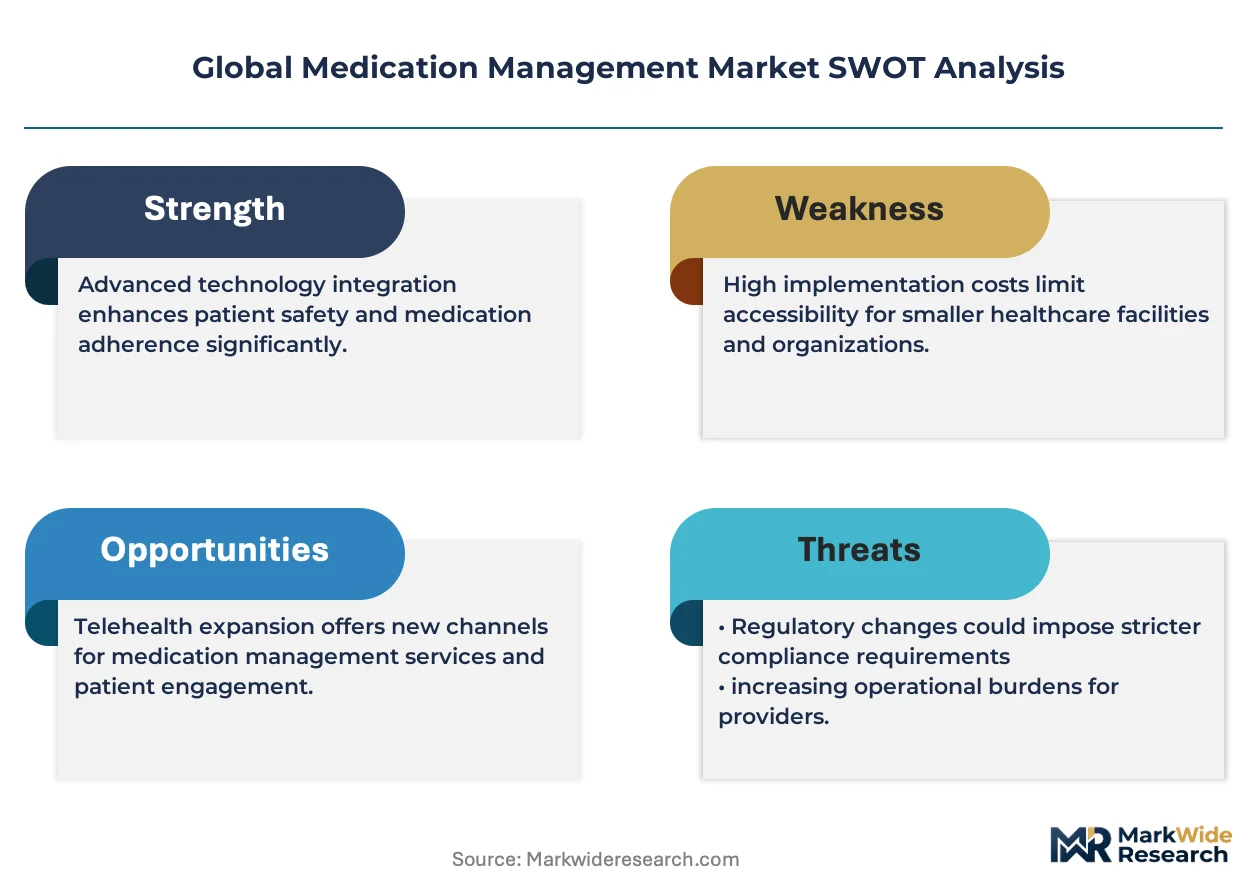
- Capital intensity:Automated dispensing hardware requires substantial upfront investment, compressing margins for mid-size hospital systems and extending replacement cycles beyond seven years.
- Supply concentration:Critical dispensing hardware components concentrate among German and Japanese precision manufacturers, creating vulnerability to regional production disruptions.
- Technical debt:Legacy on-premises installations in United States health systems impede cloud migration velocity and fragment data architectures across departmental silos.
Strategic Opportunities
- Germany's EUDAMED integration:EU MDR traceability mandates for medical device software are creating first-mover advantages for vendors with pre-validated compliance architectures.
- AI-enabled dosing:Convergence of machine learning algorithms with clinical decision support is opening premarket review pathways across FDA, EMA, and PMDA jurisdictions simultaneously.
- Remote access architectures:Cloud-based deployment models are penetrating previously inaccessible rural hospital networks in the United States through subscription economics.
Industry Challenges
- Pharmacy informatics talent:Scarcity of specialists capable of embedding clinical decision support into automated workflows is bifurcating vendor competitive capabilities.
- Interoperability certification:Multi-jurisdictional validation requirements across FDA, EMA, and PMDA are extending product launch timelines and inflating regulatory compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medication Management Market |
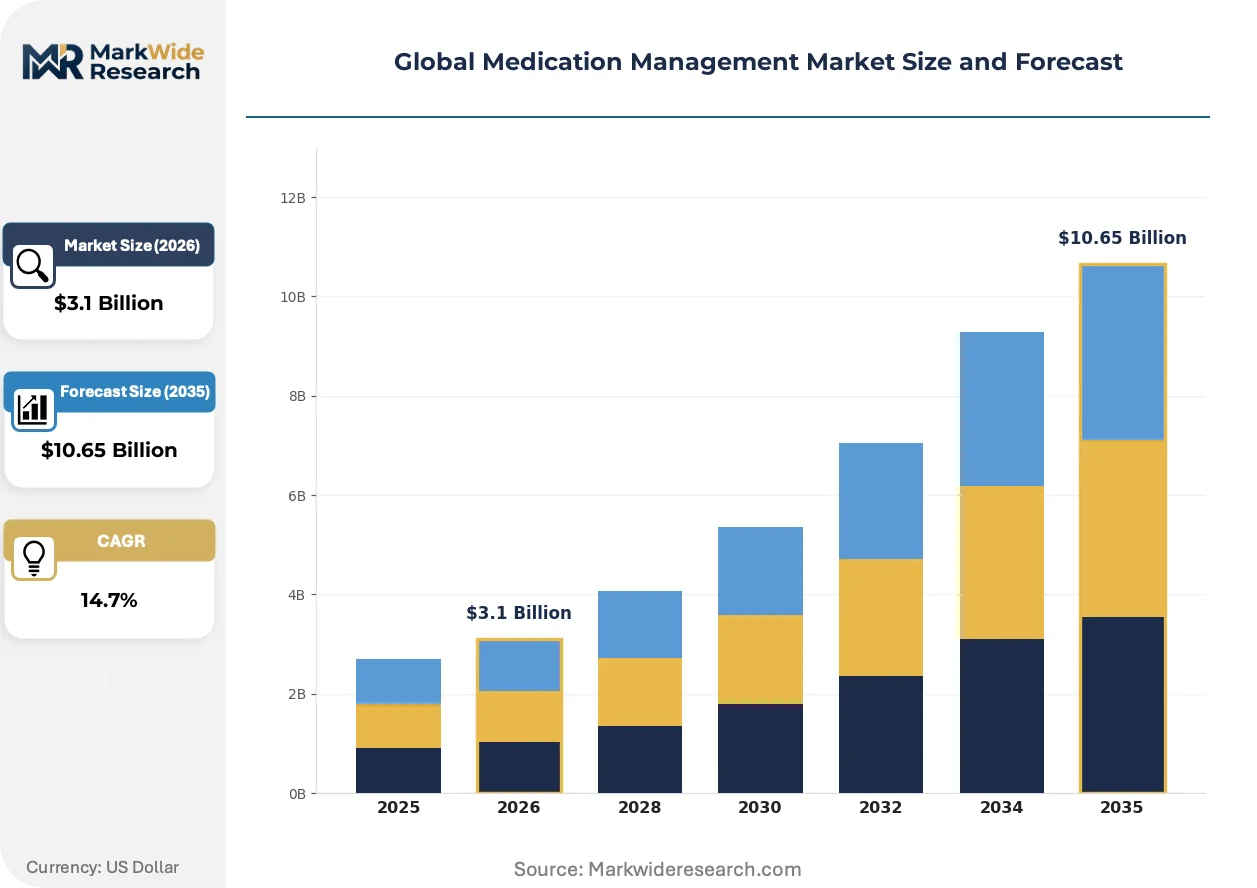
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $10.65 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Automated Dispensing Systems, Mobile Applications, Barcoding Systems, Electronic Health Records Application: Chronic Disease Management, Postoperative Care, Medication Adherence Monitoring, Prescription Management, Remote Patient Monitoring End User: Pharmacies, Long-Term Care Facilities, Home Healthcare Providers, Specialized Clinics, Community Health Centers Deployment: On-Premises, Cloud-Based, Hybrid, Web-Based, Mobile-Based |
| Companies Covered | Omnicell, Inc., McKesson Corporation, Becton, Dickinson and Company, Oracle Cerner Corporation, Epic Systems Corporation, Cardinal Health, Inc., Swisslog Healthcare, BD, Wolters Kluwer N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medication Management Market Strategic Shifts & Innovations
Artificial intelligence integration is restructuring competitive differentiation around predictive analytics rather than transactional workflow automation, compressing traditional hardware-centric business models.
Machine learning algorithms for dose-range validation are fragmenting the clinical decision support landscape. Hospital pharmacy departments in the United States are piloting these tools at accelerating pace. The technology is fragmenting vendor market positions between AI-native entrants and legacy automation suppliers struggling to retrofit predictive capabilities.
EU MDR traceability mandates for medical device software are forcing architectural redesigns across European vendor portfolios. Industrial consequence includes mandatory unique device identification integration and post-market surveillance data feeds. German hospital systems are responding fastest, leveraging existing EUDAMED infrastructure investments to compress compliance timelines.
Subscription pricing for cloud-based medication management is displacing perpetual license models among United States health systems. Large integrated delivery networks are consolidating vendor relationships around platforms offering remote access and interoperability. This shift is most visible in multi-hospital systems spanning urban and rural catchment areas.
Global Medication Management Market Segmentation
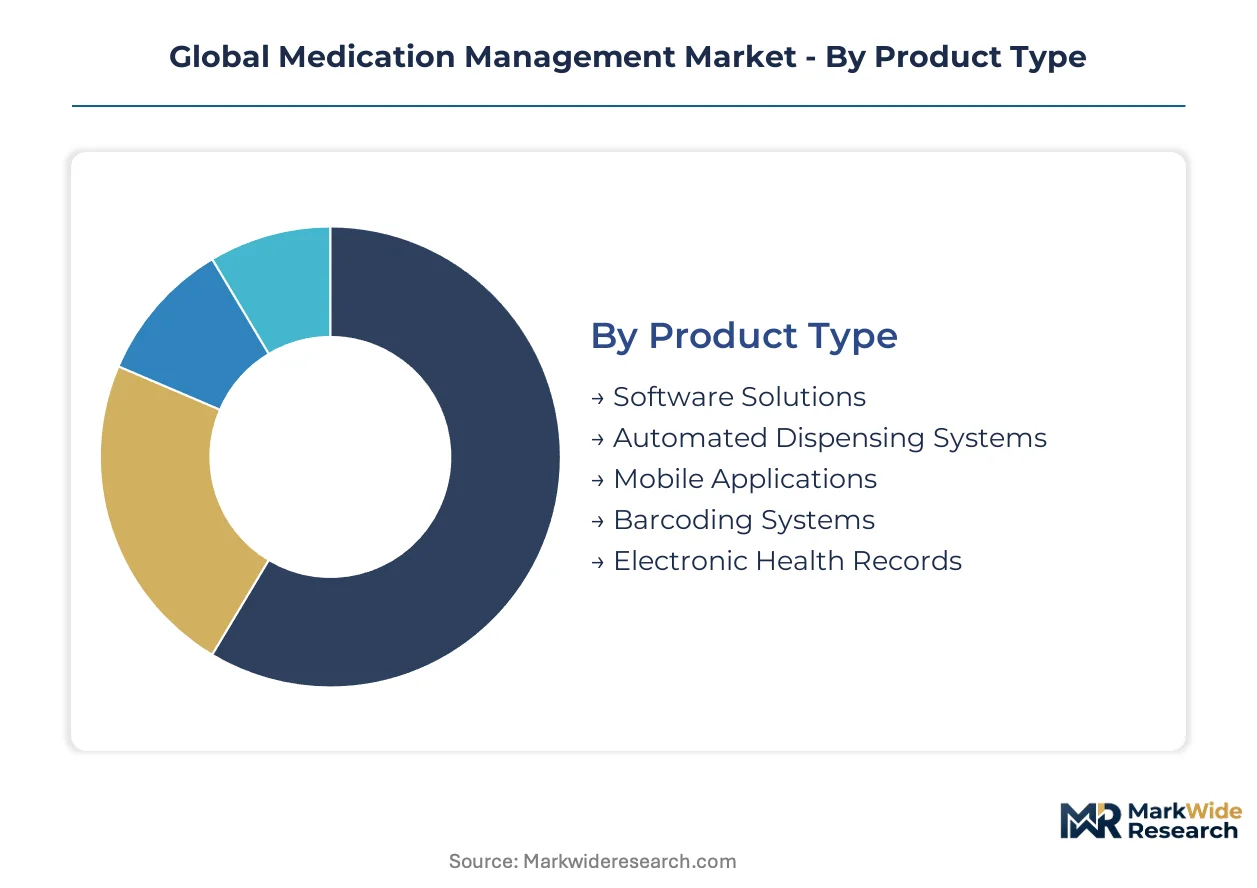
Medication management vendors configure product portfolios around distinct procurement channels. Hospital systems favor capital-intensive hardware with service contracts, while ambulatory networks prioritize subscription software with rapid deployment cycles.
Product Type:
Channel-mix dynamics split sharply between recurring software subscriptions and capital hardware sales with attached service revenue.
- Software Solutions:Modular platforms integrating clinical decision support, allergy cross-checking, and dose-range validation into existing EHR workflows. United States health systems drive demand through FDA 21 CFR Part 11 compliance mandates for electronic records.
- Automated Dispensing Systems:Cabinet and cart-based hardware with barcode verification, biometric access control, and inventory tracking. German hospital networks anchor procurement volumes as EUDAMED traceability requirements tighten.
- Mobile Applications:Patient-facing adherence tools with dose reminders and refill alerts.
- Barcoding Systems:Point-of-care scanning infrastructure for medication verification at administration.
- Electronic Health Records:Medication reconciliation modules embedded within enterprise clinical documentation platforms.
Automated Dispensing Systems dominate installed base. Software Solutions is where expansion concentrates.
Application:
Cost-tier stratification separates premium predictive analytics from standard workflow automation and economy-grade basic compliance tools.
- Chronic Disease Management:Longitudinal therapy optimization for diabetes, hypertension, and heart failure with remote monitoring integration. Japan's aging demographics expand home-based deployments under PMDA software-as-medical-device guidance.
- Medication Adherence Monitoring:Digital pillboxes, smart packaging, and behavioral analytics targeting polypharmacy patients. United States payers drive adoption through outcome-based contracting models.
- Postoperative Care:Pain management protocols with opioid diversion detection.
- Prescription Management:Electronic prescribing with formulary checking and prior authorization automation.
- Remote Patient Monitoring:Telehealth-integrated medication therapy management for rural access.
Chronic Disease Management captures the highest per-patient revenue. Medication Adherence Monitoring is climbing the fastest.
End User:
Customer-type concentration varies by procurement sophistication and regulatory exposure.
- Pharmacies:Hospital inpatient, outpatient, and retail dispensaries with inventory optimization and clinical screening requirements. German pharmacy chains invest fastest under EU MDR software traceability mandates.
- Long-Term Care Facilities:Skilled nursing and assisted living with high medication pass volumes and staff turnover challenges. United States facilities face CMS compliance pressure for electronic medication administration records.
- Home Healthcare Providers:Visiting nurse services and infusion therapy with mobile documentation needs.
- Specialized Clinics:Oncology, dialysis, and pain management with high-risk medication protocols.
- Community Health Centers:Federally qualified health centers with 340B drug pricing program compliance requirements.
Pharmacies dominate installed base. Long-Term Care Facilities is where expansion concentrates.
Deployment:
Maturity-stage differentiation separates legacy on-premises installations from cloud-native architectures and transitional hybrid models.
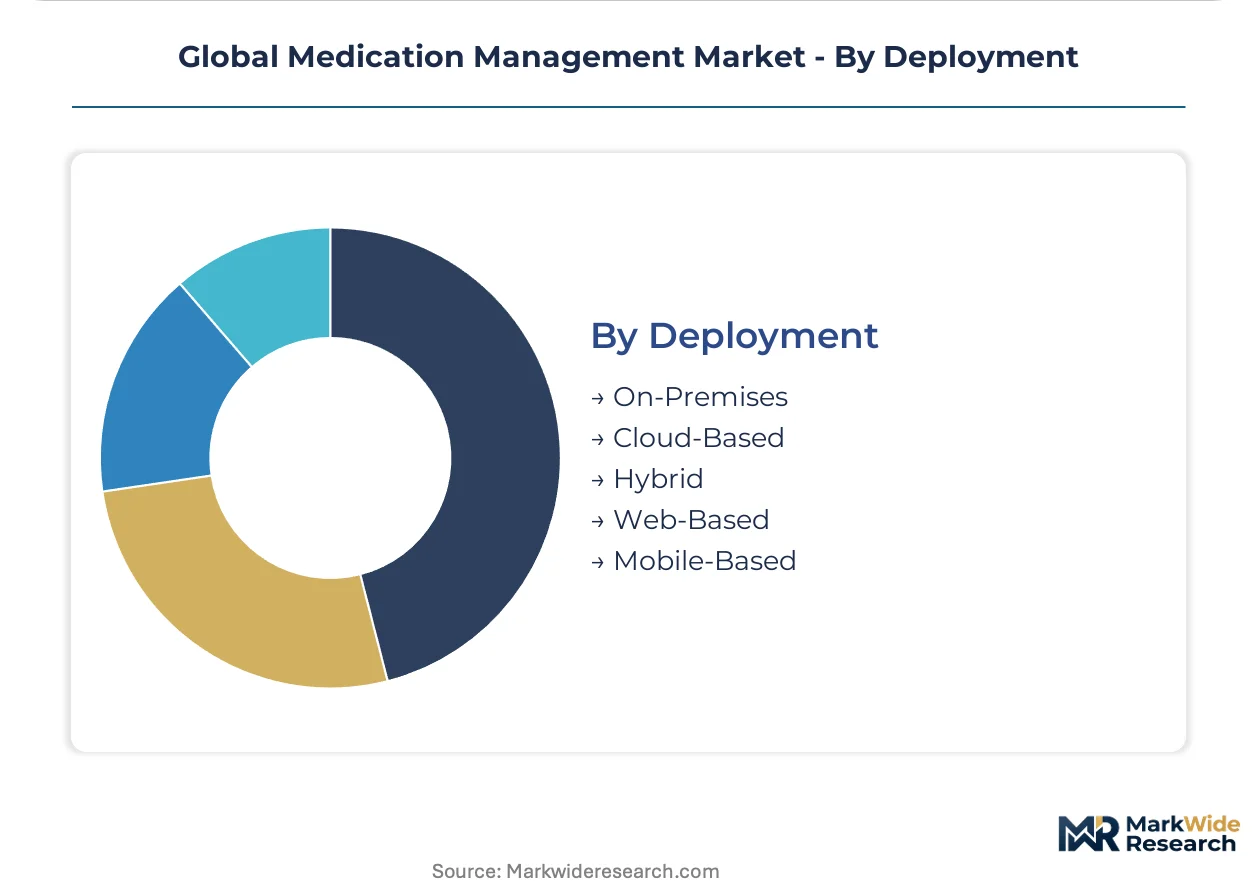
- Cloud-Based:Multi-tenant SaaS platforms with API-first interoperability, remote access, and automatic regulatory updates. United States integrated delivery networks consolidate procurement around these models for rural hospital network extension.
- On-Premises:Single-tenant installations behind institutional firewalls with full data sovereignty control. Japanese health systems retain preference due to PMDA data localization expectations.
- Hybrid:Sensitive patient data on local servers with analytics and reporting in cloud tiers.
- Web-Based:Browser-accessible applications without dedicated mobile infrastructure.
- Mobile-Based:Native iOS and Android applications for point-of-care workflows.
On-Premises retains legacy footprint. Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes medication management systems through hospital-anchored enterprise deployments, while Germany and Japan favor modular pharmacy infrastructure with stricter localization requirements.
United States
FDA 21 CFR Part 11 electronic records mandates accelerate hospital pharmacy digitization timelines. Integrated delivery networks consolidate procurement around cloud-native platforms for rural network extension. The Boston-Cambridge corridor anchors health informatics R&D concentration with academic medical center pilot programs.
Germany
EU MDR traceability requirements for medical device software tighten compliance timelines for hospital networks. EUDAMED infrastructure investments enable faster validation cycles for compliant vendors. The Baden-Württemberg industrial cluster concentrates precision dispensing hardware manufacturing with embedded software integration.
Japan
Aging demographics expand home-based medication adherence monitoring deployments under PMDA software-as-medical-device guidance. Data localization expectations sustain preference for on-premises architectures in metropolitan hospital systems. The Kanto region around Tokyo anchors pharmaceutical supply chain automation with robotics integration.
United Kingdom
NHS electronic prescribing mandates drive replacement demand for legacy pharmacy infrastructure across acute trusts. MHRA software medical device registration requirements extend product launch timelines for international vendors. The Greater Manchester health innovation cluster pilots AI-enabled dosing algorithms with academic validation partnerships.
India
CDSCO medical device software regulations tighten quality management system requirements for domestic and imported platforms. Hospital chain consolidation in tier-1 cities accelerates standardization around interoperable medication reconciliation modules. The Hyderabad- Bengaluru corridor concentrates health informatics development with export-oriented service capabilities.
Global Medication Management Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hospital system procurement favoring vendors offering combined hardware-software-service bundles. The upper tier controls automated dispensing infrastructure and enterprise EHR integration channels. Mid-tier specialists compete on clinical decision support depth and regional compliance expertise. Dominant competitive moves include cloud-native platform development and API-first interoperability certification.
Within the integrated systems tier, Omnicell, Inc. and McKesson Corporation exemplify divergent strategic positions. Omnicell anchors hardware-centric workflows through automated dispensing cabinet deployments. McKesson leverages pharmaceutical distribution data feeds to sustain supply chain-scale advantages. Oracle Cerner Corporation occupies the enterprise EHR integration vector, extending medication reconciliation into clinical documentation platforms.
| Leading Market Players |
|---|
| Omnicell, Inc. |
| McKesson Corporation |
| Becton, Dickinson and Company |
| Oracle Cerner Corporation |
| Epic Systems Corporation |
| Cardinal Health, Inc. |
| Swisslog Healthcare |
| BD |
| Wolters Kluwer N.V. |
| Others |
Cost & Logistics Intelligence
Ninety-day hardware replenishment cycles for automated dispensing cabinets concentrate margin pressure on German and Japanese precision manufacturers while amplifying pricing power for vendors with captive service contract revenue. Cloud-native software subscriptions compress upfront capital requirements for United States hospital systems, yet extend total cost-of-ownership calculations across elongated depreciation horizons.
Pricing Analysis
Long-term service contracts with attached hardware leases dominate hospital pharmacy procurement, displacing spot-market equipment purchases. Three-tier pricing structure across enterprise, mid-market, and rural hospital tiers reflects FDA 21 CFR Part 11 validation depth and EHR integration complexity. Pricing pressure stems from cloud-native entrants undercutting perpetual license maintenance fees. Rural integrated delivery networks exhibit highest price sensitivity; academic medical centers prioritize clinical decision support depth over unit economics.
Supply Chain Analysis
Strategic stockpiling of biometric sensors and precision dispensing motors characterizes vendor inventory strategy given single-source dependencies on Baden-Württemberg and Kanto region manufacturers. Automated dispensing hardware draws from Germany, Japan, and United States component suppliers. Critical dependencies include precision stepper motors, barcode scanning modules, and stainless-steel fabrication. Tariff exposure on Japanese precision electronics fragments procurement timelines. Distribution runs through hospital group purchasing organizations and direct enterprise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as hospital capital expenditure cycles rebound from pandemic-deferred infrastructure replacement. Replacement demand for legacy on-premises installations drives procurement velocity across United States integrated delivery networks.
For Market Incumbents: Shield installed base through API-first interoperability certification and embedded AI dosing algorithm development. Cloud-native entrants threaten hardware-centric margins; backward integration into precision component supply secures availability commitments. Prioritize FDA premarket review pathway preparation for machine learning-enabled clinical decision support.
For New Entrants and Emerging Players: Differentiate on chronic disease management analytics for Japan's home-based care expansion. White-space concentrates in rural United States hospital networks lacking cloud infrastructure and in EU MDR pre-validated compliance architectures for German pharmacy chains. Go-to-market through GPO channel partnerships accelerates procurement committee access.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA, EMA, and PMDA premarket review pathways create durable moats for compliant vendors. Acquisition targets include clinical decision support specialists with pharmacy informatics talent scarcity. Watch AI-enabled dosing algorithm pilot outcomes at academic medical centers as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | API-first architectures enable rural hospital network extension for United States IDNs. |
| FDA Premarket Submission | AI dosing algorithms trigger regulatory review pathways that fragment competitive positioning. |
| EU MDR Compliance Investment | EUDAMED traceability mandates create first-mover advantages in German hospital procurement. |
| Pharmacy Informatics Acquisition | Clinical decision support talent scarcity bifurcates vendor competitive capabilities. |
| Hospital System Partnership | Enterprise EHR integration contracts anchor recurring revenue through medication reconciliation workflows. |
Research Approach
The analysis maps software solutions, automated dispensing systems, and clinical decision support modules, each validated through hospital pharmacy directors, biomedical engineers, GPO contracts managers, and health system CIOs. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EUDAMED device registrations, CMS hospital cost report data, and pharmaceutical supply chain disclosures. Bottom-up segmentation sizing triangulates against top-down health IT expenditure benchmarks.
Consistency checks against external health IT expenditure surveys and hospital capital budget disclosures validated volume and value outputs across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user facility type, product category, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, cloud migration velocity, and compliance mandate effective dates. Forecast inputs incorporate hospital bed count projections and electronic prescribing adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable FDA enforcement posture and uninterrupted German-Japanese precision manufacturing supply; material deviation would warrant model refresh. Revision becomes warranted when cloud-native platform penetration or AI dosing algorithm regulatory classification crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Ascites Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Urea Cycle Disorders Treatment Market