
 Protective Cultures Market | 2026-2036
Protective Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Cultures Market Intelligence
The global push to reduce food waste, a core tenet of initiatives like the EU Green Deal, is realigning demand towards natural shelf-life extension solutions. Chr. Hansen leverages its extensive microbial strain library to offer specialized solutions for dairy and meat applications. Lallemand specializes in yeast and bacteria production for diverse food segments, including plant-based alternatives. DSM-Firmenich competes with a broad portfolio integrating enzymes and cultures for comprehensive food preservation strategies.
Protective cultures are live microorganisms intentionally added to food to inhibit the growth of spoilage and pathogenic microbes. These cultures, primarily lactic acid bacteria, function by producing antimicrobial compounds like organic acids, bacteriocins, and hydrogen peroxide. Dairy products constitute the largest application, with Lactobacillus and Bifidobacterium strains dominating product formulations. Freeze-dried formats represent the most common packaging type due to superior stability and ease of use for food manufacturers.
Regulatory bodies such as the US FDA and the European Food Safety Authority (EFSA) establish safety and efficacy standards for microbial food ingredients. These frameworks, including Generally Recognized as Safe (GRAS) notifications in the United States, govern market access and influence consumer trust in bio-preservation. The key decision for producers is balancing investment in novel strain discovery against the cost of navigating complex, country-specific approval processes.
Market Dynamics
The central structural force shaping the protective cultures market is the convergence of consumer demand for 'clean label' foods and regulatory pressure to reduce food waste. This dual pressure accelerates the replacement of chemical preservatives with microbial solutions in mainstream food production.
Growth Catalysts
- Clean Label Movement:The consumer-driven rejection of synthetic additives, particularly in the dairy and processed meat sectors, creates a direct demand pull for natural preservation alternatives like protective cultures to maintain product quality and safety without compromising ingredient lists.
- Food Waste Reduction Policies:Governmental initiatives, such as the EU Green Deal's farm-to-fork strategy, incentivize the use of technologies that extend shelf life. Protective cultures offer a biologically-based method to meet these spoilage reduction targets.
- Expansion into Plant-Based Foods:The plant-based meat and dairy alternative segments require novel preservation systems. Protective cultures are being adapted to control spoilage microbes in these new, often nutrient-rich, food matrices, opening a significant new application area.
Market Restraints
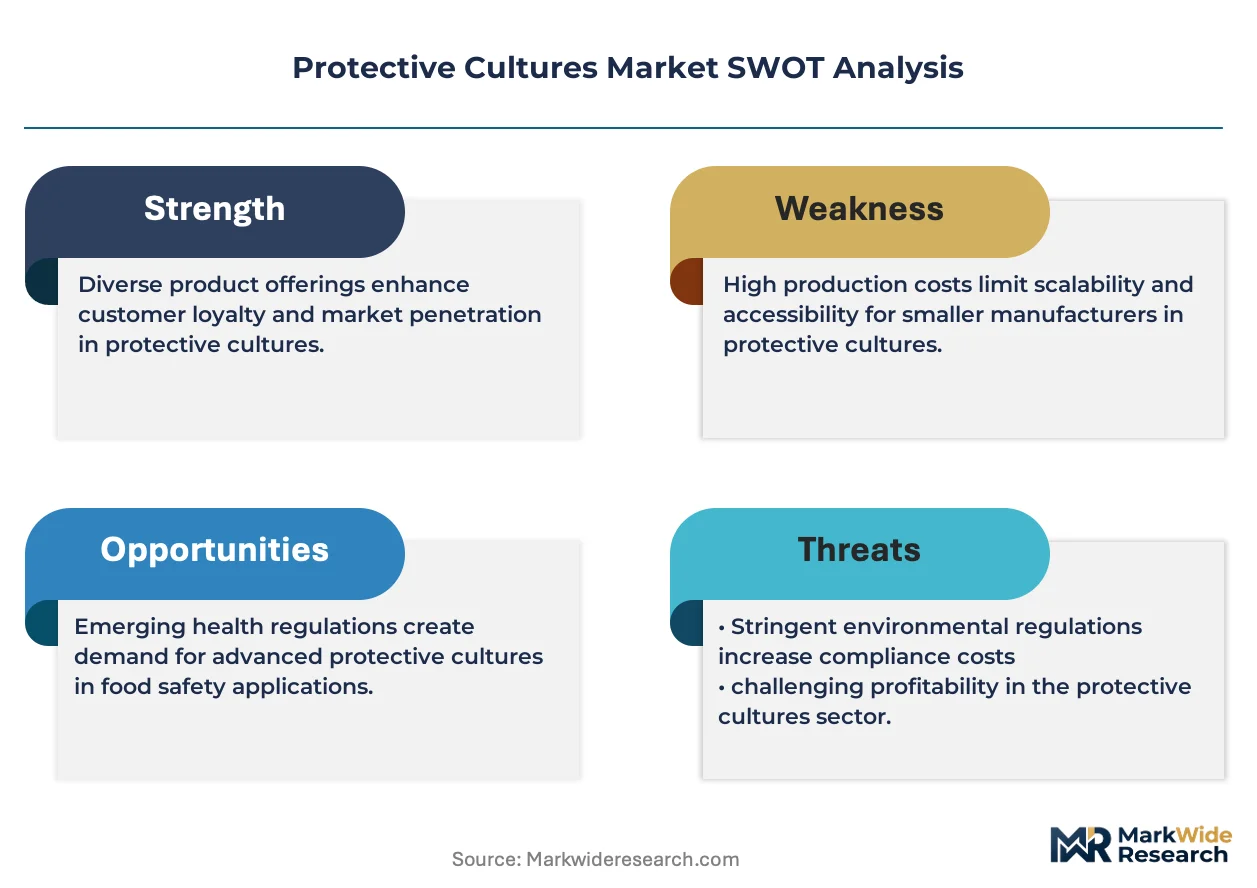
- High R&D Investment:The process of discovering, screening, and validating new microbial strains for safety and efficacy is resource-intensive and lengthy. This high barrier to entry limits the number of suppliers capable of developing novel culture solutions.
- Complex Regulatory Pathways:Navigating disparate regulatory frameworks, such as the US FDA's Generally Recognized as Safe (GRAS) notification system and the European Food Safety Authority's (EFSA) Qualified Presumption of Safety (QPS) list, creates significant compliance costs and delays market access.
- Matrix-Specific Efficacy:The performance of a protective culture is highly dependent on the specific food's properties, including pH, water activity, and native microflora. This lack of universal applicability requires extensive validation for each new product, constraining rapid adoption.
Strategic Opportunities
- Underpenetrated Geographies:Markets in Latin America and Southeast Asia, where the processed food industry is expanding rapidly, present significant growth opportunities as consumer awareness of clean label products increases and local food manufacturers seek to upgrade their preservation methods.
- Application in Bakery and Beverages:The use of protective cultures to inhibit mold in baked goods and spoilage yeasts in beverages is an emerging opportunity. This would displace chemical preservatives like sorbates and benzoates in high-volume categories.
- Synergistic Preservation Technologies:Combining protective cultures with non-thermal processing methods like high-pressure processing (HPP) offers a multi-hurdle approach to food safety. This creates an opportunity to develop integrated solutions that provide superior protection against microbial spoilage.
Industry Challenges
- Cold Chain Integrity:Maintaining the viability of live, freeze-dried cultures throughout the supply chain is an operational challenge. Any break in the cold chain from the manufacturer to the food processor can compromise culture efficacy and final product quality.
- Consumer and Manufacturer Education:A significant challenge lies in educating both food producers and end-consumers on the science and benefits of using live bacteria for preservation. This requires clear communication to differentiate protective cultures from probiotics and overcome potential skepticism.
- Specialized Application Expertise:Effective implementation requires food technologists with a strong background in microbiology to properly select, handle, and apply cultures. A scarcity of this specialized talent at food manufacturing plants can hinder successful adoption and troubleshooting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Cultures Market |
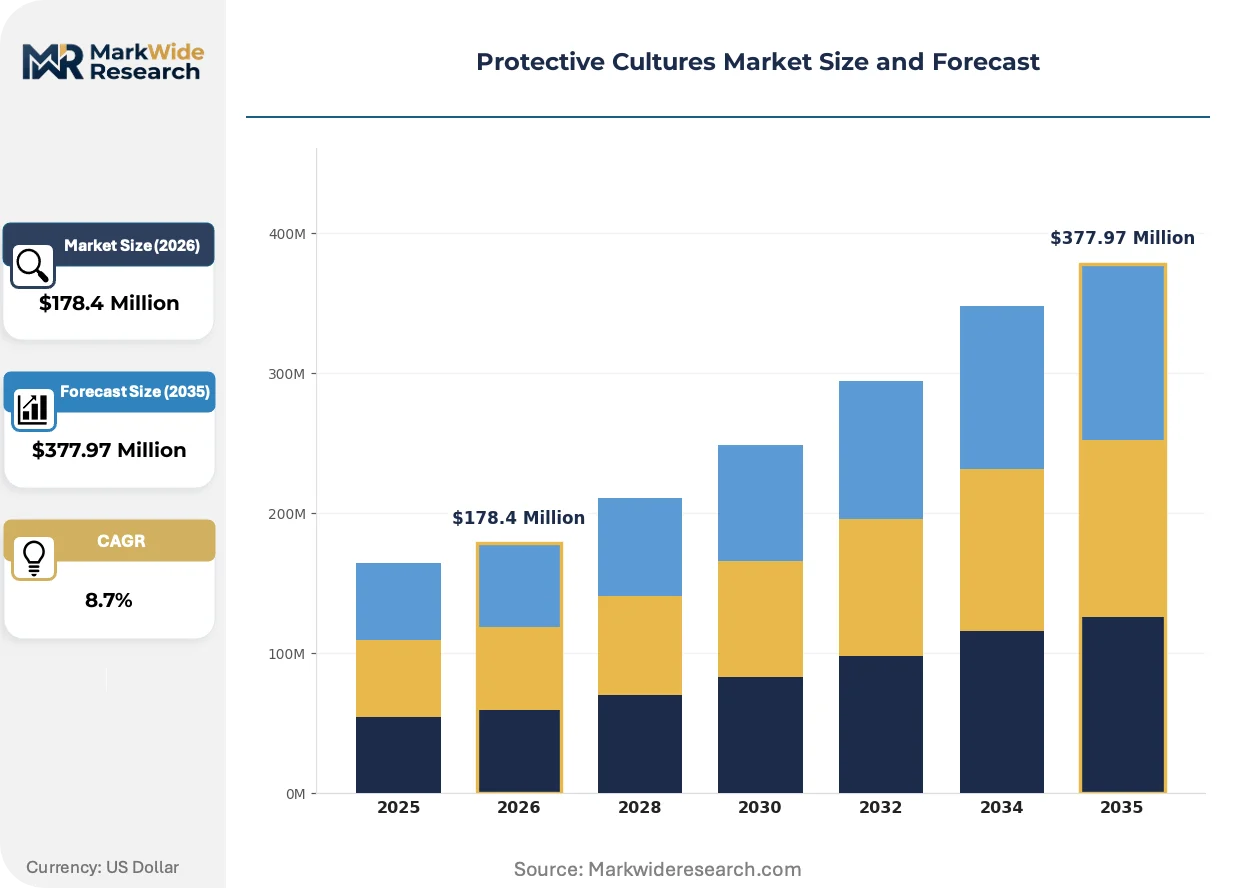
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $377.97 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactobacillus, Bifidobacterium, Pediococcus, Leuconostoc, Propionibacterium Application: Dairy Products, Meat Processing, Seafood Preservation, Plant-Based Foods, Beverage Production End User: Food Manufacturers, Biotechnological Firms, Nutraceutical Companies, Agricultural Producers, Research Laboratories Packaging Type: Freeze-Dried, Frozen, Liquid Concentrate, Spray-Dried, Encapsulated |
| Companies Covered | Chr. Hansen, DSM-Firmenich, Sacco System, Bioprox, Lallemand, International Flavors & Fragrances, DuPont Nutrition & Biosciences, Kerry Group, CSK Food Enrichment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Cultures Market Strategic Shifts & Innovations
Precision biology and data-driven strain selection are transforming the development of protective cultures. This shift enables the creation of targeted solutions for specific spoilage organisms and food applications, moving the industry beyond generic, broad-spectrum products toward customized biopreservation strategies.
Genomic sequencing and high-throughput screening technologies allow for the rapid identification of microbial strains with potent antimicrobial properties. Major culture producers and sophisticated food companies are adopting these tools to build proprietary strain libraries tailored to their product portfolios. This capability is decentralizing innovation, enabling the design of bespoke culture blends that address unique spoilage challenges in specific food matrices, from artisanal cheese to plant-based yogurt.
Stricter regulations on food additives in key markets are a major innovation driver. For example, China's updated National Food Safety Standards, enforced by the State Administration for Market Regulation (SAMR), are limiting the use of certain chemical preservatives. This regulatory tightening is compelling food manufacturers operating in China to accelerate their transition to natural alternatives. The dairy and processed meat sectors are most affected, increasing their reliance on protective cultures with well-documented safety and efficacy profiles.
A notable behavioral shift is the demand for full supply chain transparency from food brands. This change is altering ingredient procurement, moving beyond simple functional specifications to a model where the origin and purpose of every ingredient, including protective cultures, are part of the brand's story. This trend is most visible in the premium and organic food segments in Germany and the United States, forcing culture suppliers to provide traceability data and marketing support to their food manufacturing clients.
Protective Cultures Market Segmentation
Understanding the segmentation of the protective cultures market reveals how diverse needs across food production drive product development and adoption. This analysis highlights the distinct characteristics of microbial strains, applications, end-users, and packaging formats that shape market dynamics.
Product Type:
What differentiates buyers in this category is the specific antimicrobial mechanism and target spoilage organisms required for their food matrices.
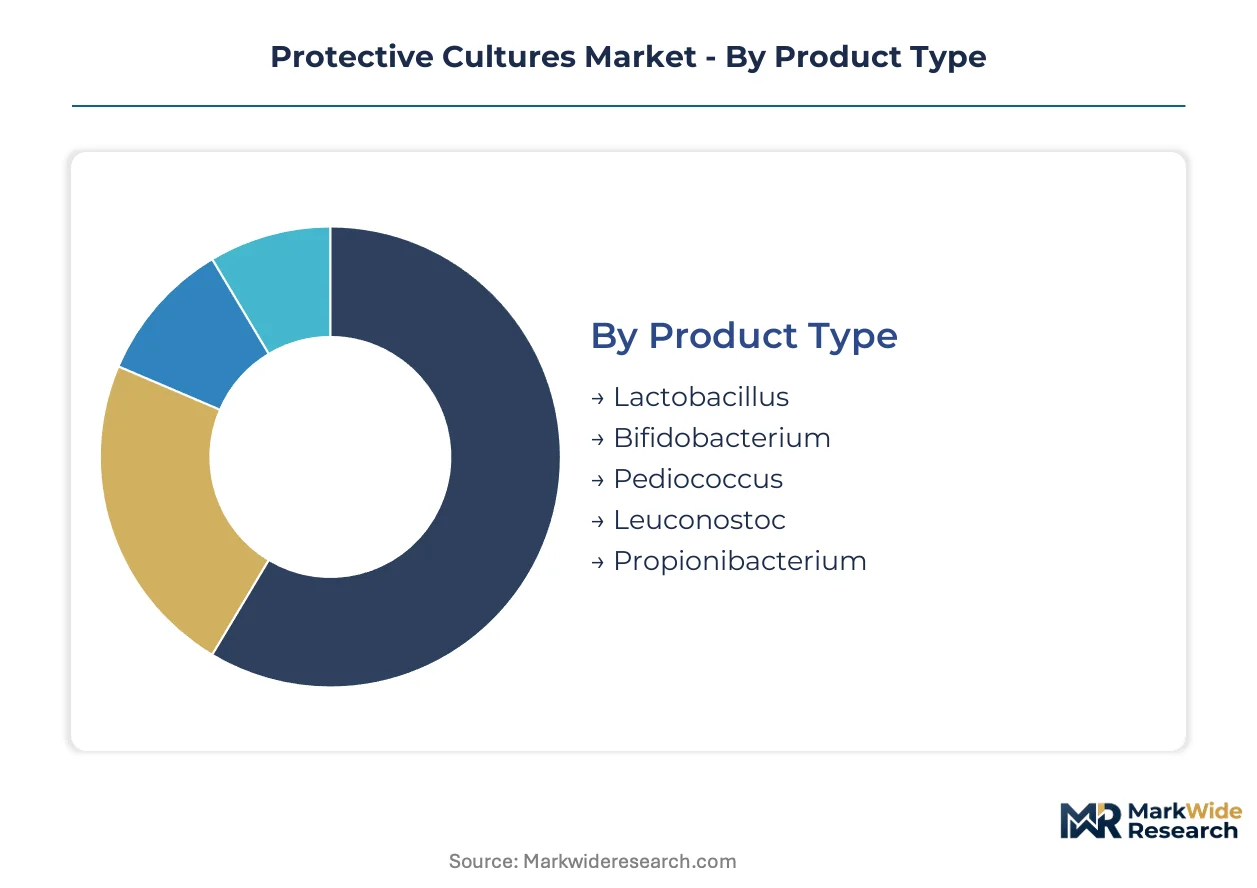
- Lactobacillus:These rod-shaped lactic acid bacteria are widely used for producing organic acids like lactic and acetic acid, inhibiting spoilage microbes and pathogens. Demand concentrates in the dairy sector, particularly in Europe, for extending the shelf life of yogurts and cheeses without chemical additives.
- Bifidobacterium:These anaerobic, gram-positive bacteria are known for producing acetic and lactic acids, contributing to biopreservation and gut health benefits. Their application is expanding rapidly in fermented dairy and plant-based alternatives in the United States, driven by consumer interest in functional foods.
- Pediococcus:These spherical lactic acid bacteria are effective in fermented meats and vegetables, producing bacteriocins that suppress undesirable bacteria.
- Leuconostoc:These heterofermentative bacteria contribute to flavor development and inhibit spoilage in dairy products and fermented vegetables, often used in artisanal cheese production.
- Propionibacterium:Known for producing propionic acid, these bacteria are crucial for inhibiting mold growth in cheese and baked goods, particularly in markets like Germany.
Lactobacillus leads volumes today; Bifidobacterium is gaining share fastest.
Application:
The market's application landscape is shaped by the specific food matrices requiring targeted biopreservation solutions to meet shelf-life and safety standards.
- Dairy Products:This segment represents the largest application area, utilizing cultures to prevent spoilage, extend freshness, and enhance safety in milk, yogurt, and cheese. Manufacturers in Germany and France heavily rely on protective cultures to meet clean label demands.
- Plant-Based Foods:This emerging segment requires specialized cultures to control spoilage and improve the sensory properties of plant-based yogurts, cheeses, and meat alternatives. Innovation is particularly strong in the United States and the UK for novel preservation systems.
- Meat Processing:Cultures are applied to cured meats and fresh meat products to inhibit pathogens like Listeria monocytogenes and extend color stability.
- Seafood Preservation:Protective cultures help prevent spoilage in fresh and processed fish products, reducing histamine formation and extending market reach.
- Beverage Production:The use of cultures in non-alcoholic beverages helps to control spoilage yeasts and molds, offering a natural alternative to chemical preservatives.
Dairy Products commands the largest share; Plant-Based Foods shows the steepest expansion trajectory.
End User:
The type of end-user dictates the scale of procurement, technical support requirements, and regulatory adherence for protective cultures.
- Food Manufacturers:These entities represent the primary consumers of protective cultures, integrating them into large-scale production lines for various food and beverage products. Major food producers across Europe and North America drive significant demand for established culture solutions.
- Biotechnological Firms:These companies develop and produce novel microbial strains, often supplying food manufacturers or integrating cultures into their own specialized ingredients. Investment in R&D for new strains is particularly high in countries like Denmark and the Netherlands.
- Nutraceutical Companies:These firms incorporate protective cultures into health-focused food supplements and functional foods, leveraging the dual benefits of preservation and probiotic activity.
- Agricultural Producers:Some agricultural operations use cultures for silage fermentation or animal feed preservation, improving feed quality and reducing spoilage.
- Research Laboratories:Academic and industrial research facilities utilize protective cultures for studying microbial interactions, developing new applications, and validating efficacy.
Food Manufacturers represent the largest consumer base; Biotechnological Firms exhibit substantial R&D expenditure.
Packaging Type:
The packaging type for protective cultures reflects considerations for stability, ease of handling, and cost-effectiveness for industrial applications.
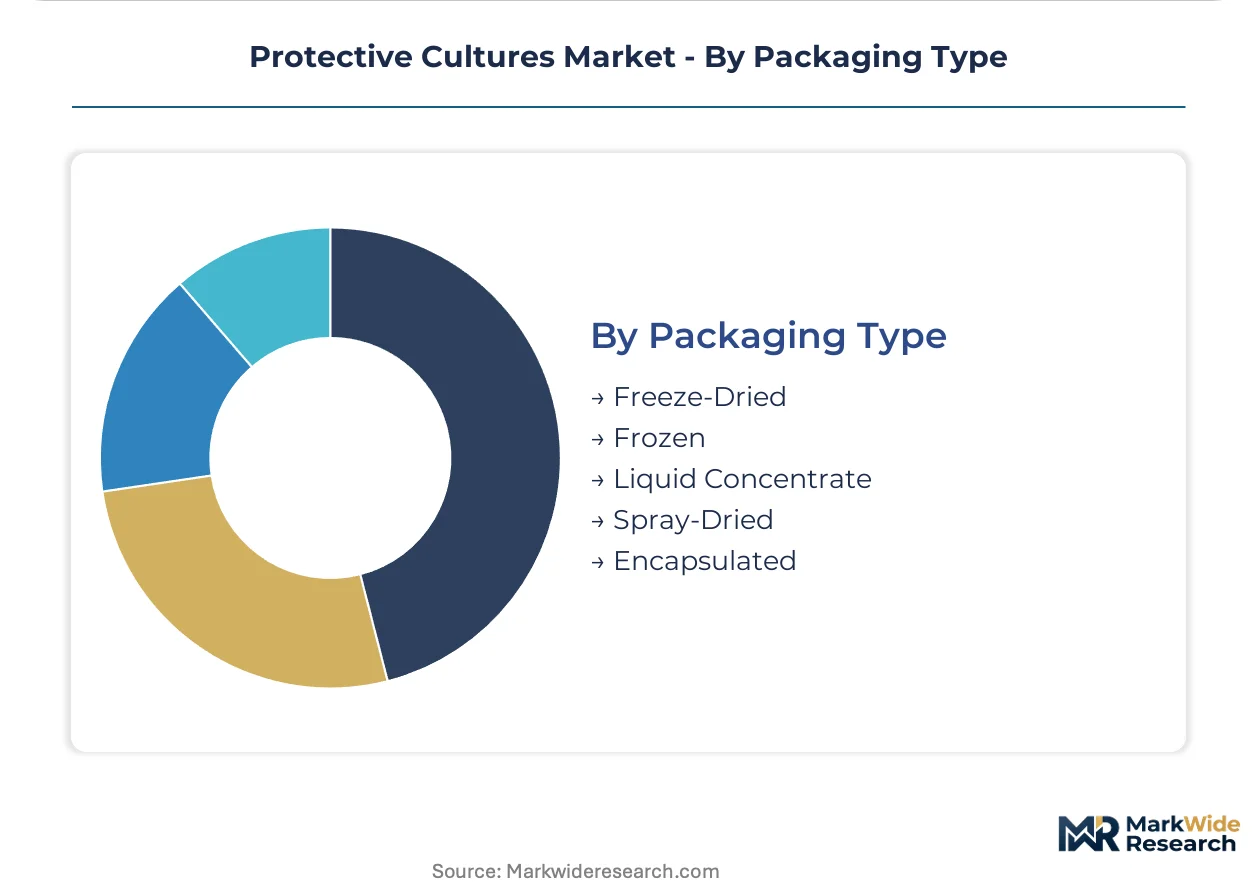
- Freeze-Dried:This format involves lyophilization to remove water, resulting in highly stable, dormant cultures with extended shelf life at ambient temperatures. Its superior stability and ease of transport make it the most common choice for global distribution to food manufacturers.
- Liquid Concentrate:These cultures are provided in a concentrated liquid form, offering convenience and rapid dispersion in food matrices, though requiring refrigeration. Liquid formats are gaining traction in applications where immediate activity is desired, particularly in the United States.
- Frozen:Cultures are preserved at very low temperatures, maintaining high cell viability but requiring a robust cold chain for storage and transport.
- Spray-Dried:A less common drying method, spray-drying offers a cost-effective solution for some culture types, producing powders with moderate stability.
- Encapsulated:Cultures are encased in a protective matrix, improving survival during processing and targeted release in the food product, suitable for specific applications.
Freeze-Dried cultures dominate the market; Liquid Concentrate is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The protective cultures market historically scaled in European dairy-producing nations, driven by traditional fermentation practices. This foundational heritage continues to influence innovation in natural preservation methods. Germany currently exhibits a significant demand concentration for these advanced solutions.
Germany
Germany's extensive food manufacturing base drives significant demand for protective cultures, especially within its dairy sector. The EU Green Deal's farm-to-fork strategy incentivizes German producers to adopt natural shelf-life extension technologies. Bavaria, a prominent dairy processing hub, sees concentrated investment in bio-preservation solutions to meet clean label consumer preferences.
United States
The United States market experiences strong demand for protective cultures, particularly from the expanding plant-based food and functional dairy segments. US FDA's GRAS notification system governs market access for microbial food ingredients, influencing product development and consumer trust. California, a center for plant-based food innovation, sees significant adoption of specialized cultures for novel preservation systems.
China
China's market for protective cultures is accelerating due to stricter regulations on chemical food additives across its vast food industry. The State Administration for Market Regulation (SAMR) enforces updated National Food Safety Standards, compelling a shift to natural alternatives. Major food manufacturers in the Yangtze River Delta region are increasing their reliance on protective cultures for dairy and processed meat.
France
France's robust dairy sector, known for its artisanal cheese production, consistently drives demand for high-quality protective cultures. The European Food Safety Authority (EFSA) sets rigorous safety and efficacy standards for microbial food ingredients, impacting French market access. Dairy producers in Normandy utilize protective cultures to enhance product safety and extend the shelf life of traditional fermented products.
Brazil
Brazil’s rapidly expanding processed food industry creates significant growth opportunities for protective cultures in Latin America. The country's national health surveillance agency, ANVISA, establishes approval processes for new food ingredients, including bio-preservation solutions. Food manufacturers in the São Paulo region are upgrading preservation methods to meet increasing consumer awareness of clean label products.
Protective Cultures Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in protective cultures. The market structure involves large, integrated ingredient suppliers alongside specialized biotechnological firms focused on novel strain discovery. Strategic archetypes include global solution providers, niche strain developers, and regional distributors. Companies prioritize M&A activities to expand microbial libraries and form strategic partnerships for market access and tailored application development.
Within the global solution provider archetype, Chr. Hansen exemplifies extensive microbial strain libraries for dairy and meat applications. DSM-Firmenich occupies a position as a broad portfolio integrator, combining enzymes and cultures for comprehensive food preservation strategies. Lallemand represents a specialist in yeast and bacteria production across diverse food segments, including plant-based alternatives. These entities anchor distinct segments of the market by offering specialized solutions and leveraging their R&D capabilities.
| Leading Market Players |
|---|
| Chr. Hansen |
| DSM-Firmenich |
| Sacco System |
| Bioprox |
| Lallemand |
| International Flavors & Fragrances |
| DuPont Nutrition & Biosciences |
| Kerry Group |
| CSK Food Enrichment |
| Others |
Cost & Logistics Intelligence
Integrated ingredient suppliers and specialized biotechnological firms shape both supply behavior and pricing discipline in the protective cultures market. This structure allows for differentiated offerings, from commodity strains to highly specialized biopreservation solutions for novel applications.
Pricing Analysis
Value-based pricing dominates the protective cultures market for specialized solutions. Price differentiation stems from proven strain efficacy and regulatory certification such as GRAS or EFSA approval. Pricing pressure intensifies for generic, established cultures due to increasing commoditization. Large food manufacturers are typically price-sensitive for standard strains, while biotechnological firms and nutraceutical companies pay premiums for novel, patented microbial solutions with unique functional benefits.
Supply Chain Analysis
Domestic content mandates, particularly in Europe, are subtly reshaping sourcing strategies for food ingredients. Supply of protective cultures concentrates in Denmark, the Netherlands, and France, leveraging strong R&D ecosystems. The industry depends on specialized fermentation media and cryoprotectants as key raw materials. Cold chain integrity represents a significant structural risk, as any disruption compromises culture viability and product quality. Distribution primarily runs directly from culture producers to large-scale food manufacturers, often bundled with application support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, driven by the persistent consumer demand for clean label foods. Steady growth is assured as manufacturers transition from chemical to natural preservation methods.
For Market Incumbents: Deepen microbial strain libraries through sustained investment in genomic sequencing and precision biology. This strategy mitigates the threat from niche strain developers offering highly targeted solutions. Expand regulatory certification efforts, especially for novel strains, to secure market access in diverse geographies. Focus R&D on developing multi-functional cultures that offer both preservation and sensory benefits to prevent commoditization of existing portfolios.
For New Entrants and Emerging Players: Enter via specialized application niches like plant-based foods or non-alcoholic beverages, where chemical preservatives face increasing scrutiny. Target underpenetrated geographies in Southeast Asia where food processing is expanding rapidly. A compelling go-to-market angle involves offering integrated preservation solutions that combine cultures with process optimization expertise for specific food matrices. Focus on developing unique strains with documented efficacy against emerging spoilage organisms.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized biotechnological firms with proprietary strain collections and proven R&D capabilities. The long-term viability of this market is strong, anchored by irreversible clean label and food waste reduction trends. Acquisition targets should possess strong intellectual property in novel strain discovery or specialized application expertise. The signal to watch is accelerating regulatory tightening on chemical preservatives in key emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Expansion | Enhances competitive advantage by offering a broader range of targeted biopreservation solutions. |
| Regulatory Approval Pathway | Secures market access and builds consumer trust for novel microbial food ingredients. |
| Application-Specific R&D | Develops tailored cultures that effectively address unique spoilage challenges in diverse food matrices. |
| Geographic Manufacturing Footprint | Reduces logistics costs and improves responsiveness to regional food manufacturing demand. |
| Strategic Partnership | Accelerates market penetration and leverages complementary expertise in food processing or distribution. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive market view. Primary research involved discussions with food technologists, R&D directors, procurement managers, and regulatory affairs specialists across the value chain. Secondary validation drew from EFSA reports, FDA GRAS notices, company annual reports, and food industry trade publications, with bottom-up and top-down triangulation ensuring data robustness.
The segment-weighting approach informed the analytical framework for the protective cultures market. Segmentation dimensions included product type, application, end-user, packaging type, and regional regulatory compliance across the modeling period. Compound annual growth rates were derived from historical trend analysis and future demand projections. Key forecast inputs included consumer preference shifts for clean labels and governmental food waste reduction targets.
Inputs from industry reports and regulatory filings were available through the study window; gaps in novel strain efficacy data for specific food matrices introduce uncertainty bands. Forecasts reflect assumptions regarding evolving country-specific regulatory approvals and technological advancements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Spain Food Emulsifiers Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Global Cereal Ingredients Market