
 Spain Food Emulsifiers Market | 2026-2036
Spain Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Emulsifiers Market Analytics
Artisan and industrial bakeries are reorganizing Spain's food emulsifier demand, pulling volume away from mass-market dairy processors. Cargill, Incorporated leverages its European ingredient network to supply clean-label lecithin variants across Iberian production sites. Kerry Group anchors its position through specialized bakery application labs in Barcelona. Palsgaard A/S competes with tailored emulsifier systems for plant-based reformulations gaining traction in Spanish retail channels.
Food emulsifiers are surface-active agents that reduce interfacial tension between immiscible phases such as oil and water, typically possessing hydrophilic-lipophilic balance values between 3 and 16 depending on molecular structure; manufacturers deploy them to stabilize textures, extend shelf life, and control viscosity in processed foods. Lecithin dominates volume flows due to its natural positioning and non-GMO supply chains, while polyglycerol esters capture faster growth from confectionery fat-reduction trends. Mono- and diglycerides retain mature, price-sensitive demand in mass-market baked goods where cost efficiency outweighs label claims.
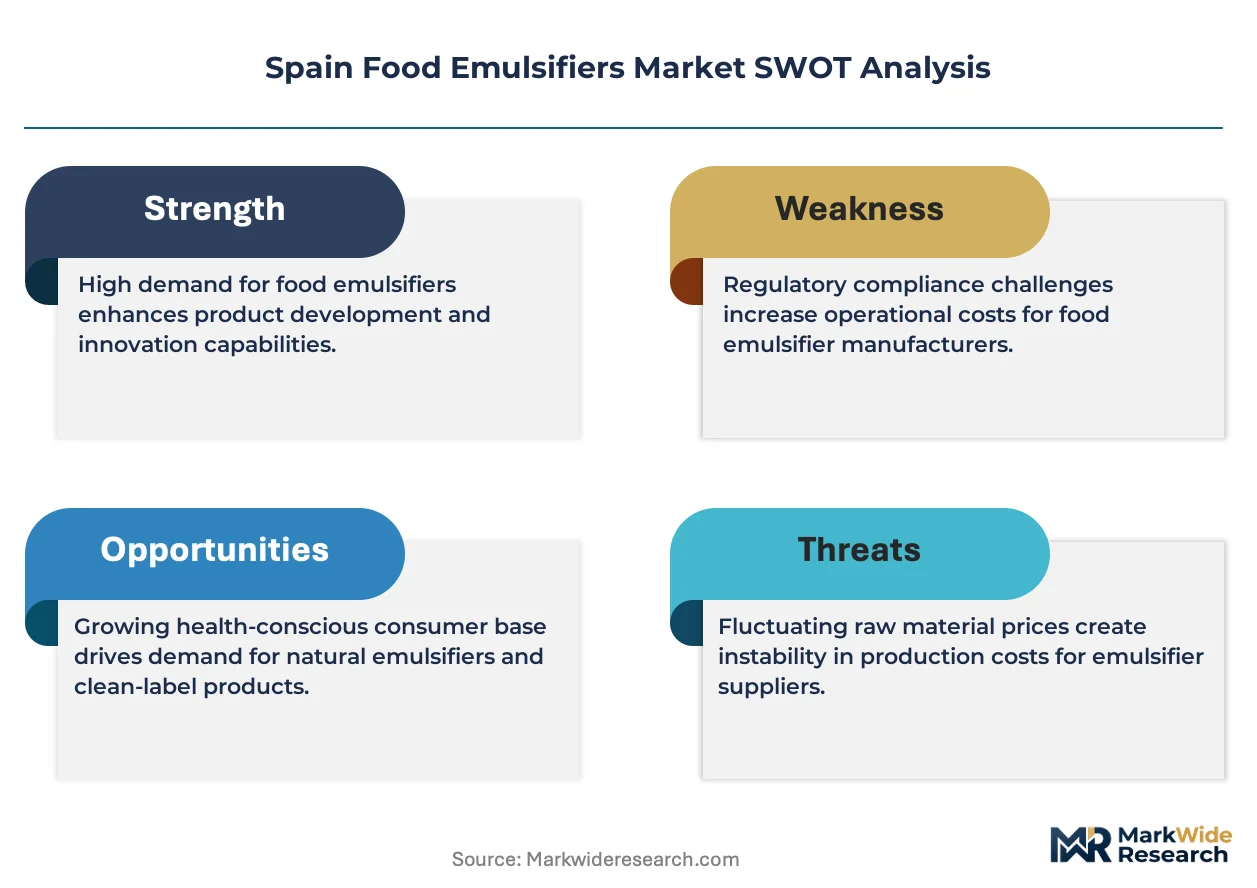
EFSA evaluates emulsifier safety dossiers under EU food additive regulations, while the EU Green Deal's Farm to Fork strategy pressures Spanish formulators toward reduced additive intensity and transparent supply chains. BIS-equivalent Spanish food safety authorities enforce compositional standards that determine which emulsifier grades qualify for organic or clean-label product positioning. Stakeholders must monitor evolving EFSA re-evaluations of specific emulsifier categories and align R&D portfolios with tightening EU-wide additive approval thresholds.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing additive intensity across Spanish food manufacturing, forcing emulsifier suppliers to reformulate around cleaner label credentials while maintaining functional performance in cost-sensitive bakery and dairy applications.
Growth Catalysts
- Clean-label bakery expansion:Artisan and industrial bakeries across Catalonia and Andalusia are pulling volume toward non-GMO lecithin and plant-derived emulsifier systems. EFSA's ongoing re-evaluations of food additive safety are accelerating transparency investments among Spanish formulators.
- Plant-based dairy analogues:Spanish retail channels are absorbing specialized emulsifier systems for oat, almond, and soy milk formulations. Reformulation labs in Barcelona are scaling application-specific technical support for these emerging product categories.
- EU Green Deal compliance:The Farm to Fork strategy's additive reduction targets are creating procurement pull for reduced-emulsifier and label-friendly alternatives. Spanish processed food corridors are consolidating purchasing power around suppliers with verified sustainable supply chains.
Market Restraints
- Sunflower lecithin supply concentration:Ukraine and Black Sea sourcing disruptions have introduced input cost volatility for Spain's dominant natural emulsifier feedstock. Spanish manufacturers face margin compression from unpredictable raw material availability.
- EFSA re-evaluation timeline uncertainty:Pending safety dossier reviews for specific emulsifier categories are freezing R&D investment decisions. Formulators hesitate to commit to long-term product development without regulatory clarity.
- Enzyme-based emulsification substitution:Lipase and phospholipase technologies are capturing clean-label positioning in premium bakery segments. These biological alternatives threaten conventional chemical emulsifier volumes in label-sensitive applications.
Strategic Opportunities
- Basque Country specialty food cluster:Underpenetrated artisan cheese and confectionery producers in northern Spain represent white space for tailored emulsifier technical service. Local formulation expertise remains thin relative to Catalonia's density.
- Direct-to-processor digital procurement:E-procurement platforms are disintermediating traditional ingredient distributors. Spanish mid-size bakery cooperatives are piloting volume aggregation through digital channels.
- CSRD-aligned supply chain transparency:The EU Corporate Sustainability Reporting Directive creates competitive differentiation for emulsifier suppliers with granular carbon footprint data. Spanish organic certification bodies are expanding emulsifier-grade approval pathways.
Industry Challenges
- Reformulation technical talent scarcity:Spain's food science programs produce insufficient specialists in clean-label emulsifier application. Barcelona and Valencia labs compete aggressively for experienced bakery technologists.
- Organic certification timeline compression:BIS-equivalent Spanish authorities enforce extended approval periods for organic-qualified emulsifier grades. Product launch cycles stretch 18-24 months for certification-dependent segments.
- Legacy equipment incompatibility:Plant-based emulsifier systems often require processing parameter adjustments incompatible with existing Spanish bakery infrastructure. Capital retrofit demands strain mid-tier producer budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Emulsifiers Market |
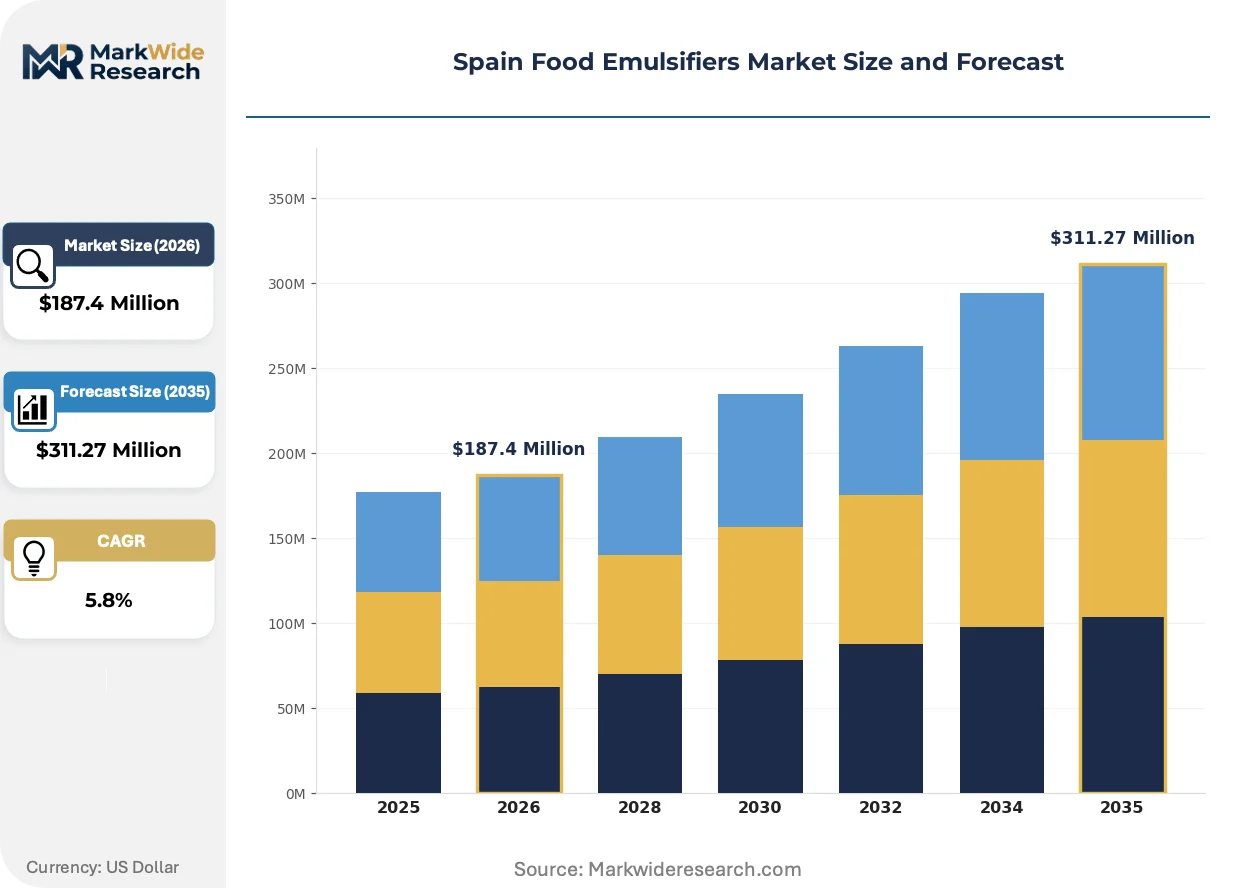
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Mono- and Diglycerides, Sorbitan Esters, Polyglycerol Esters Application: Baked Goods, Dairy Products, Sauces, Confectionery Form: Powder, Liquid, Granular, Paste End User: Food Processors, Bakeries, Restaurants, Retail |
| Companies Covered | Cargill, Incorporated, DuPont de Nemours, Inc., Ingredion Inc, Kerry Group, Archer Daniels Midland Company, International Flavors & Fragrances Inc., Corbion, Palsgaard A/S, Lasenor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Emulsifiers Market Evolving Landscape
Spanish food emulsifier innovation is pivoting around regulatory pressure and procurement model transformation. Technology substitution, compliance architecture, and buyer behavior are converging to reshape competitive requirements.
Enzymatically modified lecithin is supplanting standard fluid lecithin in premium Spanish chocolate and confectionery applications. Industrial manufacturers in Barcelona and Valencia are adopting these variants at accelerating pace to achieve cleaner labels without sacrificing viscosity control. The technology is compressing market space for chemically modified alternatives while commanding 15-25% price premiums.
EFSA's systematic re-evaluation of food additive safety dossiers is tightening approval thresholds across the EU. Spanish formulators must now submit expanded toxicological data packages for emulsifier renewals, extending regulatory timelines and increasing compliance costs. The bakery segment is responding by accelerating internal clean-label roadmaps to preempt potential restriction scenarios.
Spanish food cooperatives are consolidating procurement through digital volume aggregation platforms. Mid-size bakery and dairy processors in Andalusia and Castile-La Mancha are bypassing traditional distributors to negotiate directly with multinational ingredient suppliers. This channel shift is most visible among organic-certified producers seeking supply chain transparency documentation for EU Green Deal compliance.
Spain Food Emulsifiers Market Segmentation
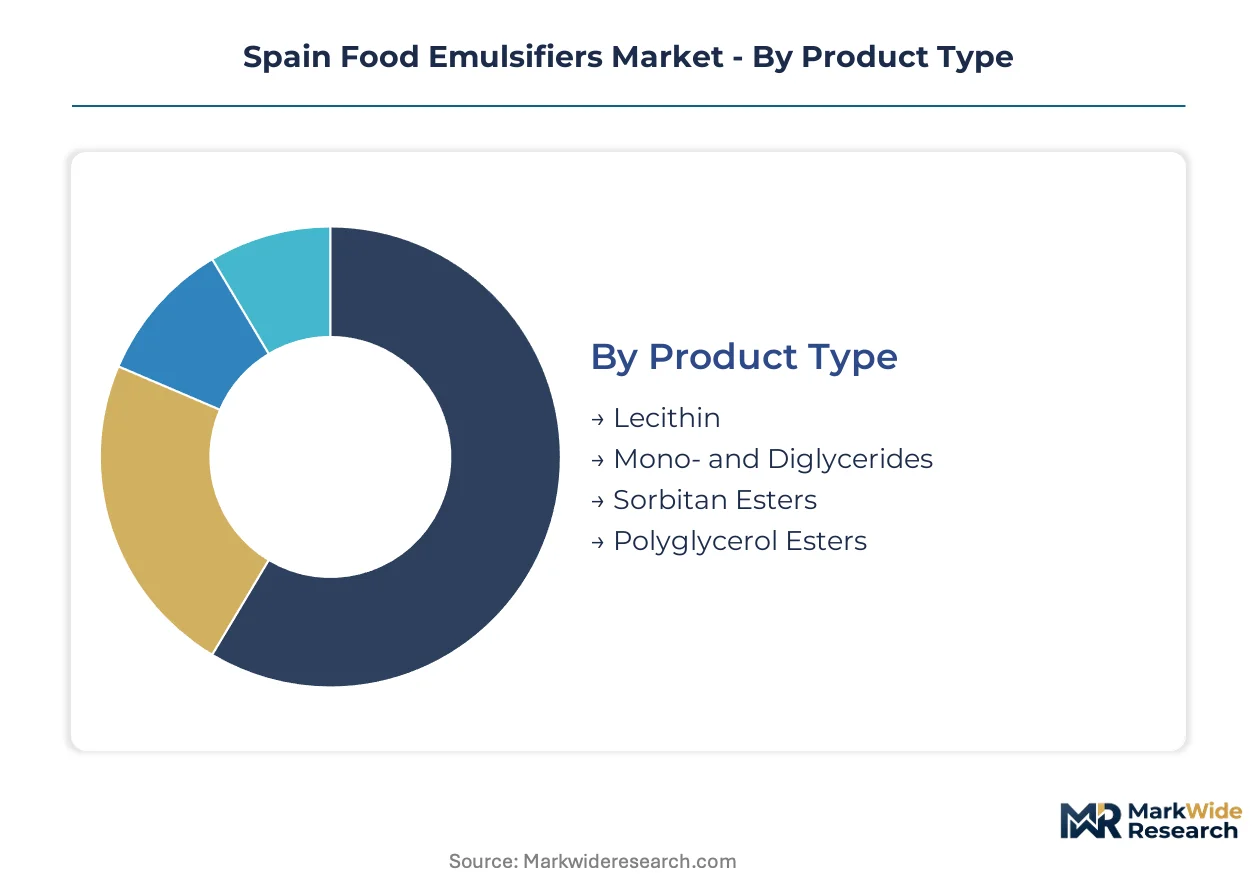
Spain's food emulsifier segmentation reveals how regulatory pressure and procurement consolidation are reshaping supplier priorities. Each dimension carries distinct margin profiles and compliance burdens that determine competitive positioning.
Product Type:
Domestic production dominates lecithin and mono-diglyceride supply, while polyglycerol esters rely heavily on import channels from Northern European specialty chemical producers.
- Lecithin:Derived from sunflower and rapeseed oils through mechanical extraction and degumming processes, this phospholipid mixture delivers natural emulsification with HLB values between 3 and 8. Andalusian oilseed crushing facilities supply the majority of Spanish food-grade lecithin, though Black Sea sourcing disruptions have compressed margins for fluid and de-oiled variants alike. EFSA's clean-label preferences reinforce sunflower lecithin's dominance over soy alternatives.
- Mono- and Diglycerides:Produced through glycerolysis of triglycerides, these partial esters offer cost-efficient stabilization in mass-market applications with HLB ranges of 3 to 6. Industrial bakeries across Catalonia and Castile-La Mancha absorb the largest procurement volumes, prioritizing price stability over label claims as EFSA re-evaluations create formulation uncertainty.
- Sorbitan Esters:Span-derived lipophilic emulsifiers with HLB values from 4 to 8, manufactured primarily through esterification of sorbitol with fatty acids.
- Polyglycerol Esters:Synthetic multi-hydroxyl emulsifiers enabling advanced fat reduction in confectionery and dairy analogues.
Lecithin holds the largest share; momentum sits with polyglycerol esters.
Application:
Cost tier stratification separates premium artisan positioning from commodity-scale procurement, with clean-label investments concentrated in mid-tier bakery and plant-based dairy segments.
- Baked Goods:Emulsifiers control dough rheology, crumb structure, and shelf-life extension through starch complexation and protein interaction. Barcelona's industrial bakery corridor drives specialized technical service demands, with enzymatically modified lecithin capturing premium positioning against standard fluid grades.
- Dairy Products:Ice cream, cream liqueurs, and processed cheese rely on emulsifier-fat-protein interactions for texture stability and freeze-thaw resistance. Plant-based analogues in Valencia and Madrid retail channels are pulling specialized emulsifier system development.
- Sauces:Mayonnaise, dressings, and emulsified condiments require oil-in-water stabilization with varying droplet size specifications.
- Confectionery:Chocolate and coatings demand precise viscosity control and fat bloom prevention through emulsifier-cocoa butter interactions.
Baked goods command the greatest volume; dairy applications are expanding most quickly.
Form:
Supply concentration in powder processing facilities around Valencia and Zaragoza shapes regional availability, while liquid form dominates import-dependent coastal processors.
- Powder:Spray-dried or plated variants enable precise dosing, extended shelf stability, and clean handling in automated bakery systems. Catalonia's industrial bakeries prefer powder for scaled production, though capital investment in pneumatic conveying systems limits adoption among smaller Andalusian cooperatives.
- Liquid:Fluid lecithin and ester concentrates offer lower unit costs and easier incorporation into high-shear processes. Seville and Málaga processors favor liquid delivery for mayonnaise and sauce manufacturing, with bulk tank installations reducing per-kilogram handling expenses.
- Granular:Free-flowing agglomerated forms bridge powder convenience with liquid dispersibility for mid-scale operations.
- Paste:High-viscosity semisolids target artisan producers with batch-scale mixing equipment and limited automation.
Powder form leads value capture; paste formats are climbing the fastest among specialty segments.
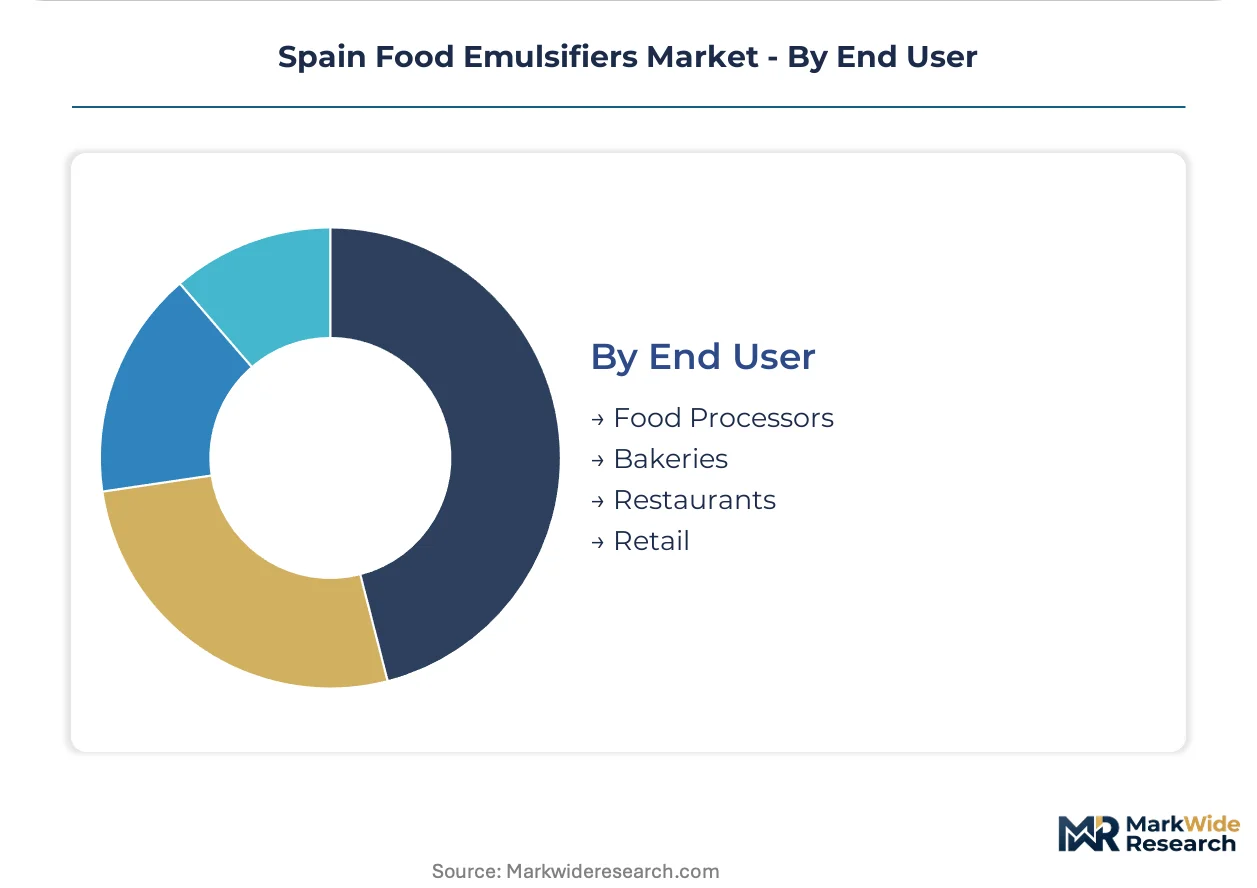
End User:
Customer type determines technical service intensity, with food processors demanding formulation support and retail channels prioritizing supply chain documentation for EU Green Deal compliance.
- Food Processors:Industrial manufacturers of packaged foods, ready meals, and ingredient systems require emulsifier suppliers with application laboratories and regulatory dossier support. Basque Country dairy processors and Murcia-based sauce manufacturers are consolidating procurement through cooperative purchasing platforms.
- Bakeries:Artisan and industrial bread, pastry, and biscuit producers span from Barcelona's automated facilities to Castile-León's traditional operations. Clean-label roadmaps differentiate premium positioning, though cost pressures in commodity pan bread constrain emulsifier grade selection.
- Restaurants:Foodservice operations and central kitchens for chain operators source emulsifiers through distributor channels with limited technical engagement.
- Retail:Private-label product developers and organic-certified brands demand granular supply chain transparency documentation.
Food processors represent the dominant revenue pool; retail channels are gaining share fastest on compliance-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish emulsifier exports flow primarily toward neighboring EU markets, with Portugal and France absorbing significant volumes of lecithin and mono-diglyceride shipments through cross-border processing corridors.
Catalonia
Barcelona's industrial bakery cluster drives specialized emulsifier demand for artisan and automated bread production. EFSA's additive transparency requirements accelerate clean-label reformulation investments across Catalan food processors. The province's confectionery manufacturers in Vilafranca del Penedès anchor regional polyglycerol ester consumption.
Andalusia
Seville and Málaga processors concentrate Spain's sauce and mayonnaise emulsifier procurement, favoring liquid delivery formats for high-shear manufacturing. The EU Green Deal's Farm to Fork strategy pressures Andalusian cooperatives toward reduced-additive formulations. Córdoba's oilseed crushing facilities supply domestic sunflower lecithin feedstock to regional emulsifier producers.
Valencia
Plant-based dairy analogue startups in Valencia and Alicante pull specialized emulsifier systems for oat and almond milk formulations. Spanish organic certification bodies enforce extended approval timelines for clean-label emulsifier grades. The province's powder processing infrastructure serves automated bakery systems across the eastern seaboard.
Basque Country
Artisan cheese and confectionery producers in San Sebastián and Bilbao represent underpenetrated demand for tailored emulsifier technical service. BIS-equivalent regional authorities apply stringent compositional standards for specialty food positioning. The cluster's procurement consolidation through cooperative platforms disintermediates traditional ingredient distributors.
Madrid
Central Spain's retail channel headquarters and private-label developers demand granular supply chain transparency documentation for EU Green Deal compliance. The capital's food science talent scarcity constrains clean-label reformulation capacity. Madrid-based procurement teams pilot direct-to-supplier digital volume aggregation for mid-size bakery networks.
Spain Food Emulsifiers Market Competitive Landscape
Player mix skews toward multinational ingredient conglomerates with European application laboratories and regional distribution networks. Market structure consolidates around suppliers with verified sustainable supply chains and EFSA-aligned regulatory dossier capabilities. Three archetypes dominate: integrated agribusinesses with captive oilseed processing, specialized emulsifier system houses, and diversified food ingredient platforms. Competitive intensity centers on portfolio diversification toward plant-based analogue formulations and strategic partnerships with Spanish food cooperatives.
Among North American agribusiness conglomerates, Cargill, Incorporated and Archer Daniels Midland Company occupy positions anchored by European oilseed processing infrastructure and non-GMO supply chain certification. Kerry Group and International Flavors & Fragrances Inc. represent the diversified ingredient platform archetype, with Barcelona application labs providing technical service density for bakery and dairy reformulation. Palsgaard A/S and Corbion exemplify specialized emulsifier system houses competing on tailored solutions for clean-label and plant-based segments. Lasenor anchors the regional specialist tier with Spain-based production proximity to Andalusian and Catalan processing corridors.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| DuPont de Nemours, Inc. |
| Ingredion Inc |
| Kerry Group |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc. |
| Corbion |
| Palsgaard A/S |
| Lasenor |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Andalusian sunflower lecithin crushers and Barcelona bakery cooperatives lock in supply access while capping price visibility for Spanish food processors navigating EU Green Deal compliance timelines. These agreements compress spot market liquidity and force mid-tier buyers toward volatile short-term procurement.
Pricing Analysis
Enzymatically modified lecithin commands 15-25% premiums over standard fluid grades, while chemically modified variants face price erosion from clean-label substitution. Three-tier pricing structure across premium enzymatic, standard fluid, and economy-grade mono-diglycerides reflects certification intensity and non-GMO verification costs. Pricing pressure stems from Black Sea sunflower supply disruptions compressing margins for natural emulsifier variants. Mass-market industrial bakeries in Castile-La Mancha exhibit highest price sensitivity, while Basque Country artisan producers absorb premiums for label-friendly positioning.
Supply Chain Analysis
Port congestion at Barcelona and Valencia container terminals elevates inbound logistics costs for polyglycerol ester imports from Northern European specialty chemical producers. Spain's emulsifier supply draws from domestic Andalusian oilseed crushing, German and Dutch polyglycerol ester manufacturing, and Black Sea sunflower lecithin feedstock. Single-source vulnerability concentrates in Ukraine-origin sunflower phospholipids, with Spanish formulators holding limited buffer inventory. Distribution runs through regional ingredient distributors serving Catalonia and Andalusia, though digital procurement platforms are disintermediating traditional channels for organic-certified buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions expand faster than commodity emulsifier sales, as Spanish processors outsource clean-label reformulation expertise. Recurring revenue from application laboratories and regulatory dossier preparation now exceeds hardware margins for specialized suppliers.
For Market Incumbents: Compound technical service density through Barcelona and Valencia application labs to preempt enzyme-based emulsification substitution in premium bakery segments. Deepen backward integration into Andalusian sunflower crushing capacity to secure non-GMO lecithin feedstock against Black Sea supply volatility. Certification investment in EU Organic and CSRD-aligned carbon footprinting creates defensive moats as EFSA re-evaluations tighten approval thresholds. For New Entrants and Emerging Players: Lead with Basque Country specialty cheese and confectionery technical service, where local formulation expertise remains thin relative to Catalonia's density. Target Murcia-based sauce manufacturers and Castile-León traditional bakeries through direct digital procurement pilots, bypassing established distributor relationships. White space sits in plant-based dairy analogue systems for Valencia's oat and almond milk startups, where specialized emulsifier development lags demand. For Investors and Strategic Acquirers: Regional emulsifier system houses with captive application laboratories and CSRD-compliant supply chain documentation represent priority acquisition targets for platform consolidation. Long-term viability hinges on portfolio diversification toward plant-based analogue formulations and regulatory dossier capabilities aligned with EFSA's tightening approval framework. Watch EFSA's systematic re-evaluation timeline for specific emulsifier categories as the inflection signal for reformulation investment cycles and potential restriction scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Application Laboratory Expansion | Barcelona technical centers capture premium formulation service revenue from clean-label bakery reformulation. |
| Backward Integration into Oilseed Crushing | Andalusian sunflower lecithin captive supply insulates margins from Black Sea sourcing disruptions. |
| CSRD-Aligned Supply Chain Certification | Granular carbon footprint data differentiates suppliers for EU Green Deal procurement compliance. |
| Digital Procurement Platform Development | Direct-to-processor volume aggregation disintermediates traditional distributors for mid-size cooperatives. |
| Plant-Based Dairy System Specialization | Valencia oat and almond milk analogue formulations capture fastest-expanding application segment demand. |
Research Methodology
Operator-level perspectives from emulsifier procurement managers at Spanish food cooperatives, application technologists at Barcelona bakery labs, and regulatory affairs directors navigating EFSA dossier requirements anchored the qualitative base. Secondary validation drew from EU food additive regulation filings, Spanish organic certification body records, customs trade data on lecithin imports, and SEC disclosures from listed ingredient suppliers. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and regional demand clusters.
Sensitivity analysis tested forecast outputs against alternative scenarios for EFSA re-evaluation timing, Black Sea supply disruption duration, and enzyme-based substitution penetration rates. The analytical framework modeled segmentation dimensions spanning lecithin grade tier, bakery versus dairy end-use, powder versus liquid form factor, and regional processing corridor concentration. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and procurement consolidation trends. Industry-specific inputs included sunflower lecithin crush margins, polyglycerol ester import dependency ratios, and clean-label certification timeline compressions.
Forecasts assume regulatory continuity in EU food additive approval regimes and Spanish organic certification pathways; material policy shifts would require re-modeling. Specific risks include accelerated EFSA restriction scenarios, sustained Ukraine supply disruption, and faster-than-projected enzyme technology cost parity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market