
 Global Wood-Derived Food Additives Market | 2026-2036
Global Wood-Derived Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood-Derived Food Additives Market Foresight
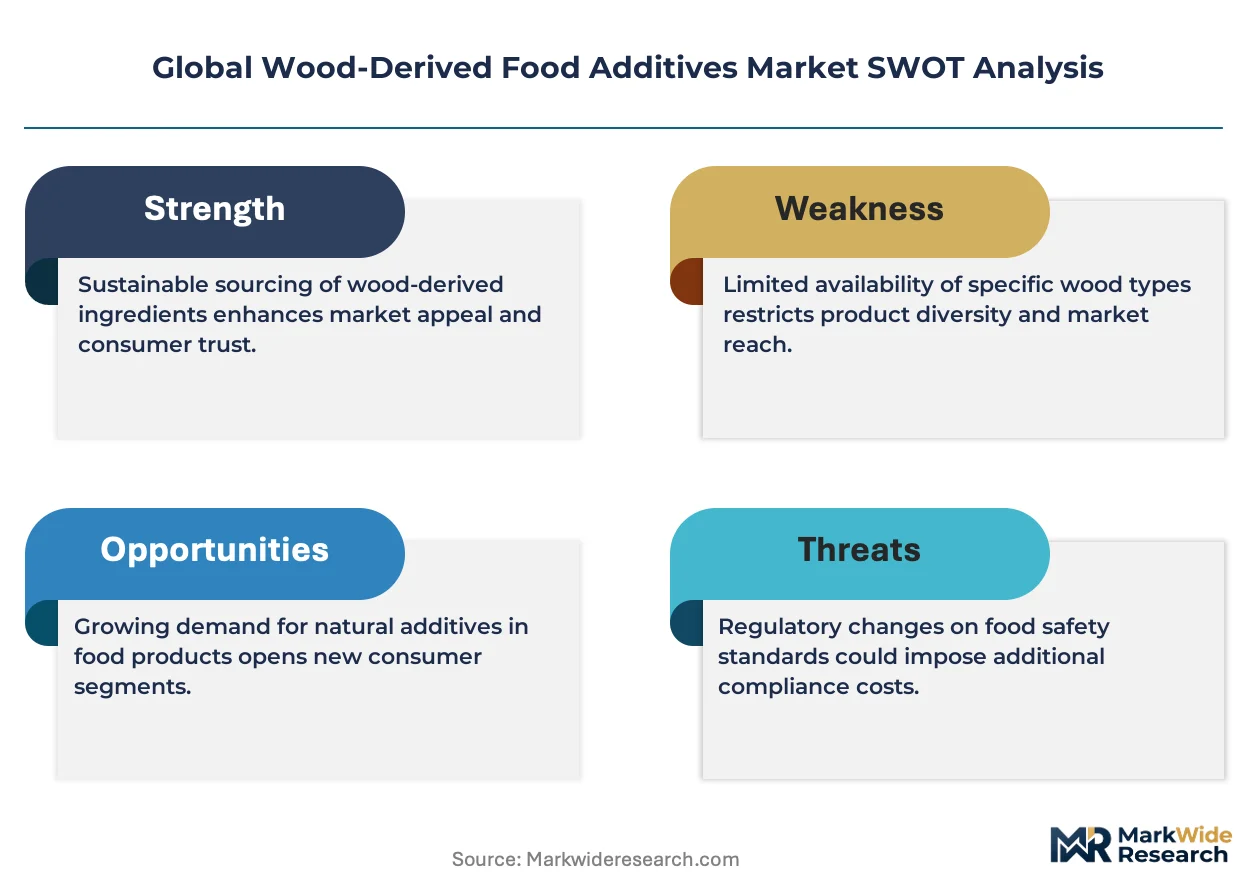
ISO 22000 certification is redrawing competitive boundaries in wood-derived food additives, filtering out smaller extractors that lack hazard-analysis documentation. Cargill Inc. leverages its grain-processing infrastructure to secure consistent hemicellulose feedstock volumes. Kerry Group Plc. anchors European supply relationships through specialized emulsifier formulations for dairy processors.
Wood-derived food additives comprise refined polysaccharides and phenolic polymers extracted from hardwood and softwood biomass through alkaline pulping, enzymatic hydrolysis, or steam explosion, typically achieving 85-95% purity for food-grade cellulose. These compounds function as viscosity modifiers, emulsion stabilizers, and soluble fiber fortifiers across processed food matrices. Cellulose and hemicellulose segments dominate current volume flows, reflecting mature thickening-agent demand in baking and dairy applications. Xylan and lignin fractions are expanding fastest within nutraceutical and clean-label preservative channels, where margin pools sit 15-20% above commodity cellulose grades.
The FDA maintains Generally Recognized As Safe determinations for microcrystalline cellulose, while EFSA reviews novel food dossiers for emerging hemicellulose isolates under EU 2015/2283. China's SAMR enforces GB standards for food additive purity that constrain import eligibility for non-compliant extractors. Stakeholders must monitor evolving GRAS notification pathways and harmonized purity benchmarks to sustain cross-border formulation approvals.
Market Dynamics
Clean-label formulation mandates from beverage and dairy processors are compressing synthetic stabilizer volumes while pulling wood-derived cellulose and xylan into mainstream supply chains, forcing extractors to scale food-grade purification capacity.
Growth Catalysts
- EU Green Deal compliance deadlines:The F-Gas Regulation and tightening extraction standards are filtering out legacy solvent-based processors, creating volume capture opportunities for enzymatic hydrolysis operators in Germany and Scandinavia.
- Beverage manufacturer reformulation:Dairy and plant-milk processors in the Netherlands and France are substituting carrageenan with lignin-based stabilizers to meet clean-label retail specifications.
- Steam explosion technology maturation:This mechanical pretreatment method is reducing alkaline chemical inputs by half, enabling smaller Nordic hardwood processors to achieve food-grade hemicellulose purity thresholds.
Market Restraints
- Softwood feedstock price volatility:Pulp mill capacity constraints in Canada and Sweden are squeezing hemicellulose precursor availability, compressing extractor margins during Q4 procurement cycles.
- Technical limitation in lignin color consistency:Batch-to-batch chromatic variation in Kraft lignin isolates restricts uptake in transparent beverage applications where visual clarity is non-negotiable.
- Substitution threat from bacterial cellulose:Precision-fermented alternatives from glucose feedstock are capturing premium nutraceutical capsule contracts, displacing wood-derived microcrystalline cellulose in high-margin pharmaceutical-adjacent channels.
Strategic Opportunities
- Underpenetrated bakery fortification in India:FSSAI's evolving fiber-labeling rules are creating first-mover openings for xylan isolates in packaged bread and biscuit matrices.
- Regulatory tailwind from China's dual carbon goals:SAMR's GB standard revisions are incentivizing enzymatic extraction methods that demonstrate lower carbon intensity versus acid hydrolysis.
- Technology convergence of supercritical CO2 and membrane filtration:This paired approach is unlocking food-grade lignin fractions previously relegated to industrial binders, opening preservative and antioxidant applications.
Industry Challenges
- ISO 22000 certification timeline compression:Hazard-analysis documentation requirements are extending qualification periods for Southeast Asian extractors seeking EU export eligibility, straining working capital.
- Specialized food technologist scarcity:Formulation chemists capable of integrating hemicellulose into UHT dairy matrices without protein aggregation are concentrated in Germany and Denmark, limiting geographic expansion.
- Legacy ERP integration friction:Batch-level traceability systems required for EFSA novel food dossiers are incompatible with existing pulp mill inventory platforms, demanding parallel IT infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood-Derived Food Additives Market |
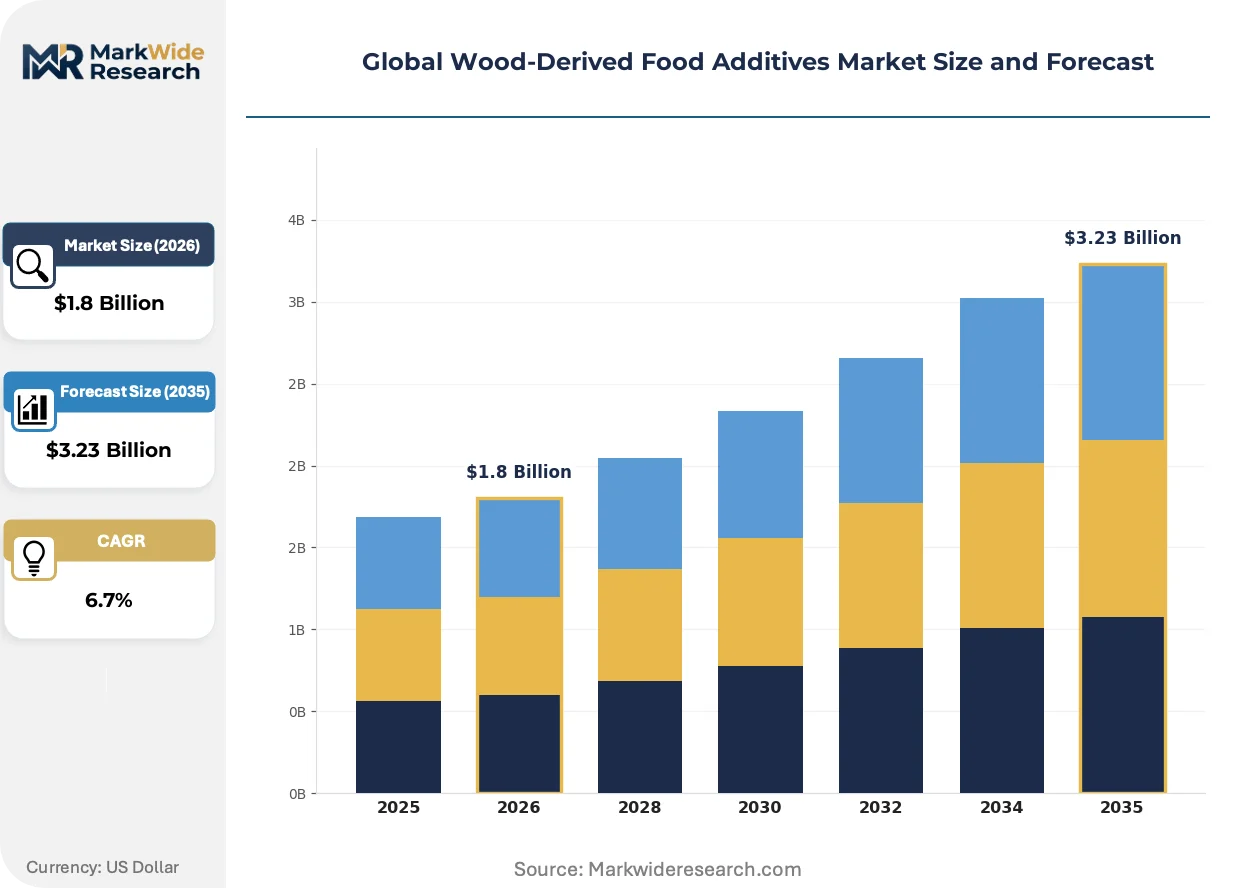
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
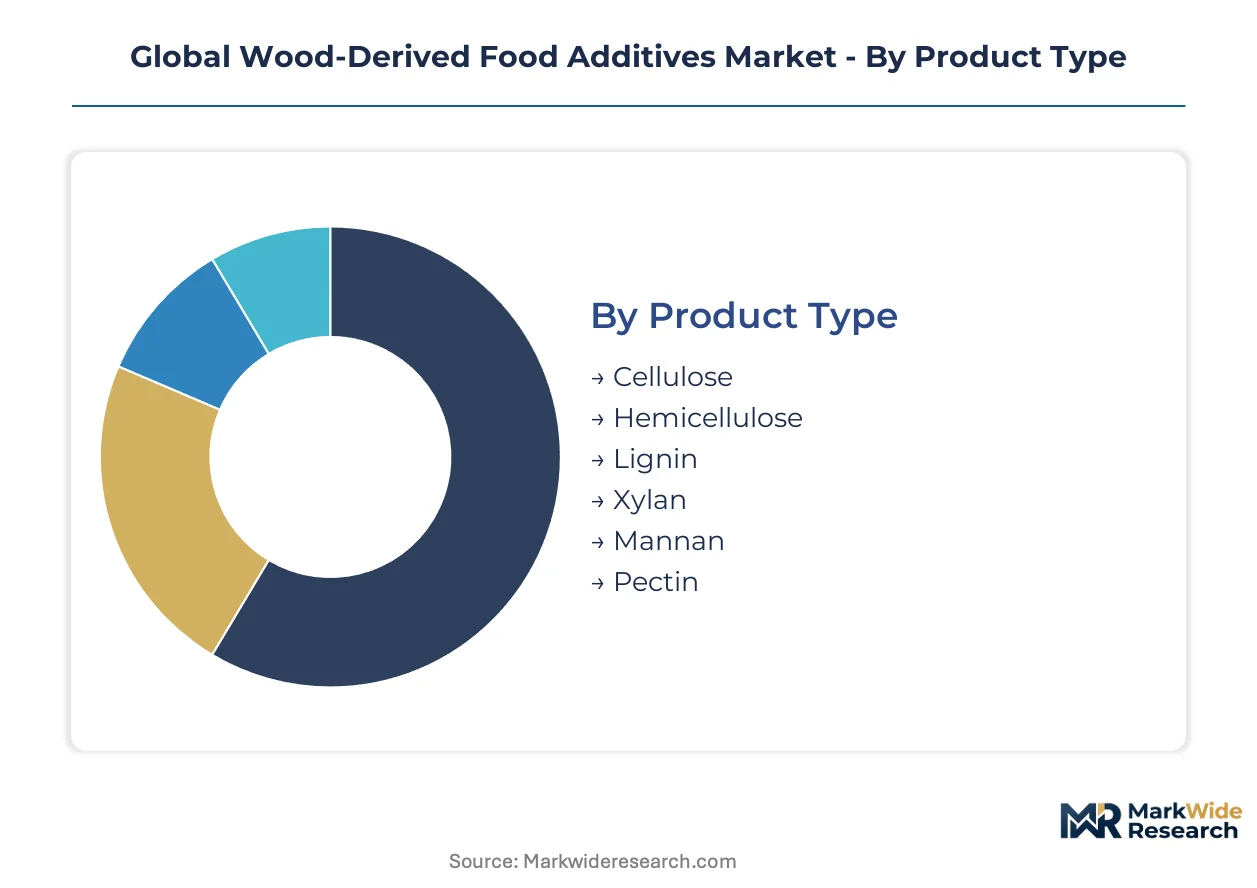
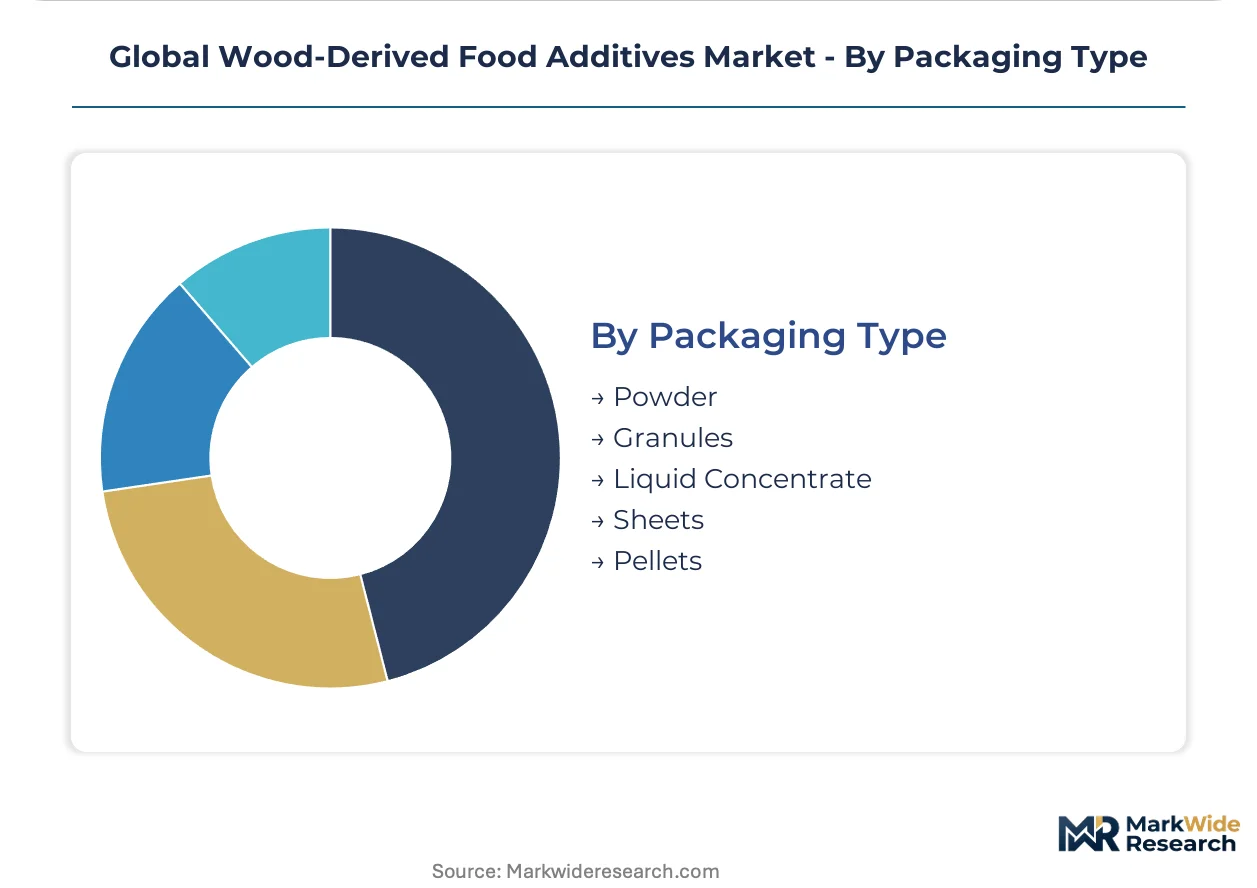
| Segmentation | Product Type: Cellulose, Hemicellulose, Lignin, Xylan, Mannan, Pectin Application: Thickening Agent, Emulsifier, Stabilizer, Dietary Fiber, Flavor Enhancer, Preservative End User: Baking Industry, Beverage Manufacturers, Dairy Processors, Confectionery Producers, Meat Processors, Nutraceutical Firms Packaging Type: Powder, Granules, Liquid Concentrate, Sheets, Pellets |
| Companies Covered | BASF SE, Cargill Inc., Archer-Daniels-Midland Company, Ingredion Incorporated, Tate & Lyle Plc., Kerry Group Plc., CP Kelco U.S., Inc., FMC Corporation, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood-Derived Food Additives Market Shifts & Advancements
Extraction technology convergence and regulatory purity benchmarking are compressing synthetic additive displacement timelines while fragmenting competitive advantage between chemical engineering capability and food-safety certification depth.
Enzymatic hydrolysis platforms utilizing cellulase and xylanase cocktails are decomposing lignocellulosic biomass at lower temperature thresholds than alkaline pulping. Nordic hardwood processors are adopting these systems to reduce energy intensity and secure EFSA novel food approvals for hemicellulose isolates. This technology is decomposing the historical cost advantage of sulfur-based Kraft processes, forcing legacy pulp mills to retrofit or exit food-grade supply.
EFSA's systematic review of hemicellulose isolates under EU 2015/2283 is tightening purity documentation requirements for xylan and arabinoxylan fractions. The regulation is compelling extractors to implement batch-level contaminant testing that exceeds current ISO 22000 hazard-analysis protocols. German dairy processors are responding by consolidating supplier relationships around certified enzymatic hydrolysis operators with established novel food dossier track records.
Direct-procurement contracts between cellulose extractors and bakery conglomerates are displacing traditional ingredient distributor intermediaries. CPG manufacturers in France and Italy are negotiating volume commitments with Swedish hardwood processors to secure supply chain transparency for clean-label marketing claims. This channel restructuring is most visible in premium gluten-free bakery segments where fiber-content verification carries regulatory and consumer scrutiny weight.
Global Wood-Derived Food Additives Market Segmentation
Segmentation in wood-derived food additives reveals how extraction chemistry, functional performance, and end-use specifications intersect to determine commercial viability. Channel dynamics differ sharply across product types versus applications, with enzymatic hydrolysis operators capturing premium positions in beverage and nutraceutical supply chains while alkaline pulping volumes flow predominantly into cost-sensitive bakery applications.
Product Type:
Channel-mix patterns show cellulose and hemicellulose dominating commodity distributor networks, while lignin and xylan fractions increasingly move through direct-procurement contracts with clean-label formulators.
- Cellulose:Microcrystalline and powdered grades achieve 85-95% purity through mechanical and chemical refinement, supplying viscosity control in gluten-free bakery matrices. German and French dairy processors specify food-grade cellulose for UHT milk stabilization, where protein aggregation resistance is mandatory. By volume, cellulose leads. By growth pace, xylan is ahead.
- Hemicellulose:Arabinoxylan and galactomannan fractions extracted via enzymatic hydrolysis deliver soluble fiber fortification with lower carbon intensity than acid-based processes. Dutch plant-milk manufacturers are substituting carrageenan with hemicellulose isolates to meet retailer clean-label specifications, concentrating demand in enzymatic hydrolysis supply channels.
- Lignin:Kraft and organosolv fractions function as natural antioxidants and emulsion stabilizers in preservative applications.
- Xylan:Hardwood-derived fractions are expanding fastest within nutraceutical capsules and functional beverage fortification.
- Mannan:Softwood galactomannan isolates serve as water-binding agents in processed meat matrices.
- Pectin:Wood-derived pectin substitutes complement citrus-sourced volumes in specific texture applications.
Margin structures stratify sharply: commodity cellulose competes on scale, while xylan and lignin fractions command 15-20% premia through novel food dossier positioning.
Application:
Cost-tier differentiation separates premium positioning in dietary fiber and preservative applications from commodity thickening-agent volumes.
- Thickening Agent:Cellulose derivatives dominate cost-sensitive bakery and sauce applications through distributor channels.
- Emulsifier:Hemicellulose and lignin fractions stabilize oil-water interfaces in plant-based dairy alternatives.
- Stabilizer:Xylan isolates prevent syneresis in UHT dairy matrices, commanding specification-driven procurement from Swedish and German processors.
- Dietary Fiber:Soluble fiber claims drive xylan and hemicellulose uptake in Indian packaged bread following FSSAI labeling rule evolution.
- Flavor Enhancer:Lignin-derived vanillin and smoke fractions penetrate natural flavoring channels.
- Preservative:Antioxidant lignin fractions are gaining traction in clean-label meat and bakery preservation, displacing synthetic alternatives.
Thickening agents generate the highest absolute volumes. Preservative applications are climbing the fastest as clean-label mandates harden across European retail.
End User:
Customer-type concentration shows beverage manufacturers and dairy processors driving specification innovation, while baking industry volumes flow through consolidated distributor relationships.
- Baking Industry:Gluten-free and high-fiber bread segments absorb commodity cellulose and xylan volumes through ingredient distributors.
- Beverage Manufacturers:Plant-milk and functional drink formulators in the Netherlands and France specify hemicellulose stabilizers for clean-label positioning.
- Dairy Processors:German UHT and yogurt manufacturers consolidate supplier relationships around ISO 22000-certified enzymatic hydrolysis operators.
- Confectionery Producers:Texture modification requirements in sugar-reduced formulations drive cellulose and pectin demand.
- Meat Processors:Water-binding and preservation functions utilize mannan and lignin antioxidant fractions.
- Nutraceutical Firms:Capsule and supplement manufacturers specify high-purity xylan for prebiotic fiber claims.
Dairy processors anchor volume commitment scale. Nutraceutical firms are expanding most quickly as prebiotic positioning gains regulatory clarity.
Packaging Type:
Supply-chain configuration separates bulk powder and granule flows to industrial processors from specialized liquid and sheet formats for precision formulation.
- Powder:Standardized cellulose and hemicellulose powders dominate high-volume bakery and dairy applications.
- Granules:Controlled particle-size grades improve dispersibility in instant beverage matrices.
- Liquid Concentrate:Enzymatic hydrolysis operators supply pre-hydrated hemicellulose solutions to beverage manufacturers seeking process integration efficiency.
- Sheets:Specialty cellulose formats serve pharmaceutical-adjacent nutraceutical encapsulation.
- Pellets:Compressed lignin fractions facilitate handling in industrial preservative blending operations.
Powder formats command the largest shipment volumes. Liquid concentrates are gaining share fastest as beverage manufacturers prioritize production-line integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in wood-derived food additive distribution, while the Øresund Bridge corridor links Swedish hardwood processors to Copenhagen's food-tech innovation cluster.
Germany
Enzymatic hydrolysis operators in Hamburg and Bremen supply lignin-based stabilizers to dairy reformulators. The EU F-Gas Regulation and Green Deal compliance deadlines are filtering out solvent-based processors. Food technologists in Lower Saxony are consolidating supplier relationships around ISO 22000-certified extractors for UHT milk applications.
Sweden
Nordic hardwood processors leverage steam explosion technology to achieve food-grade hemicellulose purity. The Swedish Environmental Protection Agency enforces extraction standards that exceed baseline EU requirements. Pulp mill clusters in Värmland and Gävleborg are retrofitting alkaline pulping lines to capture beverage manufacturer demand for clean-label stabilizers.
Netherlands
Plant-milk manufacturers in Friesland and Gelderland specify hemicellulose isolates to replace carrageenan in retailer-compliant formulations. The Dutch Food and Consumer Product Safety Authority enforces novel food dossier requirements under EU 2015/2283. Rotterdam's port infrastructure enables direct-procurement contracts between extractors and CPG conglomerates.
France
Bakery conglomerates in Île-de-France negotiate volume commitments with Swedish processors for gluten-free fiber fortification. ANSM and DGCCRF coordinate purity benchmarking that aligns with EFSA hemicellulose reviews. Lyon-based dairy processors are reformulating yogurt lines with xylan isolates to meet clean-label retail specifications.
China
Enzymatic extraction operators in Shandong and Jiangsu provinces target carbon-intensity reductions under SAMR's evolving GB standards. The Ministry of Ecology and Environment's dual carbon goals incentivize process upgrades versus acid hydrolysis. Qingdao's port facilities are expanding food-grade cellulose export capacity to Southeast Asian nutraceutical manufacturers.
Global Wood-Derived Food Additives Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and feedstock security, creating a tiered structure where scale-driven commodity producers coexist with enzymatic hydrolysis innovators. The vendor base stratifies between grain-processing conglomerates leveraging existing biomass infrastructure and dedicated extractors pursuing novel food dossier positioning. Three archetypes dominate: diversified agribusinesses with captive hemicellulose supply, Nordic hardwood specialists with steam explosion capabilities, and Asian enzymatic platform operators. Competitive moves center on backward integration into pulp mill partnerships and parallel IT infrastructure investment for batch-level traceability compliance.
Among diversified agribusinesses, Cargill Inc. and Archer-Daniels-Midland Company exemplify the feedstock-security archetype, leveraging grain-processing infrastructure to secure consistent hemicellulose precursor volumes. Kerry Group Plc. occupies a position within the European formulation-specialist tier, anchoring supply relationships through dairy processor technical service capabilities. BASF SE represents the chemical-engineering pathway, sitting within the industrial-to-food-grade conversion segment where supercritical CO2 technology unlocks preservative applications.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Inc. |
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| Tate & Lyle Plc. |
| Kerry Group Plc. |
| CP Kelco U.S., Inc. |
| FMC Corporation |
| DuPont |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Swedish hardwood processors and German dairy conglomerates lock in both hemicellulose feedstock access and eighteen-month price visibility, insulating enzymatic hydrolysis operators from pulp mill spot-market volatility while compressing margins for non-contracted extractors.
Pricing Analysis
Volume-discount tiering separates ISO 22000-certified enzymatic hydrolysis operators commanding 15-20% premia from commodity cellulose grades competing on scale. Three-tier pricing structure across premium certified, standard food-grade, and industrial-tier economy levels reflects certification depth and batch-traceability investment. Pricing pressure stems from bacterial cellulose substitution in nutraceutical capsules, eroding wood-derived microcrystalline cellulose positioning. Beverage manufacturers exhibit highest price sensitivity due to reformulation volume requirements, while nutraceutical firms accept premium positioning for novel food dossier security.
Supply Chain Analysis
Inventory lead times stretch to twelve weeks for food-grade hemicellulose isolates as Nordic hardwood processors balance steam explosion capacity against EFSA novel food dossier backlogs. Supply concentrates in Sweden, Germany, and Canada, with pulp mill retrofit decisions in Värmland and Gävleborg determining regional hemicellulose precursor availability. Feedstock draws from spruce, birch, and pine biomass streams tethered to forestry harvest cycles and FSC certification verification. Single-source vulnerability runs through Canadian softwood export constraints. Distribution runs through Rotterdam and Hamburg port infrastructure linking extractors to direct-procurement CPG relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Dutch and French dairy processors consolidating supplier relationships around three certified enzymatic hydrolysis operators, fragmenting pricing leverage for uncontracted extractors.
For Market Incumbents: Compound certification depth advantage by accelerating ISO 22000 batch-traceability system deployment ahead of EFSA novel food dossier deadline compression. Lock in backward integration into Swedish pulp mill partnerships to secure spruce and birch feedstock streams against Canadian export volatility. Defend against bacterial cellulose substitution by anchoring technical service capabilities with German UHT dairy formulators. For New Entrants and Emerging Players: Differentiate on carbon-intensity positioning by deploying supercritical CO2 extraction platforms targeting China's SAMR GB standard revisions under dual carbon goals. White-space availability concentrates in Indian bakery fortification as FSSAI fiber-labeling rules evolve, with xylan isolates penetrating packaged bread matrices. Go-to-market through direct-procurement relationships with Mumbai and Bangalore bakery conglomerates bypassing distributor intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enzymatic hydrolysis operators with established EFSA novel food dossier track records and locked-in dairy processor technical service contracts. Long-term viability over the next decade hinges on backward integration into forestry assets and parallel IT infrastructure for batch-level traceability compliance. Target acquisition archetype: Nordic hardwood specialists with steam explosion capabilities and incomplete certification depth. Signal to watch: FSSAI rule finalization triggering Indian bakery procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Assets | Captive spruce and birch supply secures feedstock against Canadian pulp mill export constraints. |
| ISO 22000 Certification Acceleration | Batch-traceability compliance unlocks EFSA novel food dossier eligibility for hemicellulose isolates. |
| Supercritical CO2 Technology Deployment | Lower carbon intensity extraction aligns with SAMR GB standard revisions in Shandong province. |
| Direct-Procurement Channel Establishment | Bypassing distributors captures margin from French and Italian gluten-free bakery conglomerates. |
| Technical Service Capability Buildout | On-site formulation support anchors German dairy processor relationships against bacterial cellulose substitution. |
Research Methodology
A standing panel of enzymatic hydrolysis plant managers, dairy processor procurement leads, EFSA regulatory affairs specialists, and Swedish forestry supply coordinators provided ongoing calibration across the analysis window. Primary interview data triangulated against customs trade records for hemicellulose and cellulose flows, SEC filings from diversified agribusinesses, EFSA novel food register entries, and SAMR GB standard revision notices. Bottom-up volume modeling from extraction capacity utilization converged with top-down demand aggregation across beverage, dairy, and bakery end-use segments.
Consistency checks validated volume and value outputs against pulp mill production statistics from Värmland and Gävleborg clusters, EFSA novel food approval timelines, and FSSAI fiber-labeling implementation tracking. Segmentation dimensions spanned product type chemistry, application functional performance, end-user procurement behavior, and packaging format logistics configuration. CAGRs derived from year-over-year growth rate reconciliation across enzymatic hydrolysis capacity expansion plans and dairy reformulation volume commitments. Forecast inputs incorporated EU F-Gas Regulation compliance cost trajectories and steam explosion technology adoption curves.
Material uncertainties — regulatory approval delays for hemicellulose isolates, Canadian softwood export disruption, bacterial cellulose scale-up acceleration — sit outside the modeled envelope and could compress or extend projected growth trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Oxygen Absorbers Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Germany Food Acidulants Market