
 Gelatin Films Market | 2026-2036
Gelatin Films Market Size, Share, and Industry Trends Forecast 2026-2036
Gelatin Films Market Foresight
Asset-light leasing models for extrusion and casting equipment is narrowing the capital barrier for mid-scale entrants in gelatin film production. Gelita AG leverages its captive collagen supply chain to sustain cost advantages across pharmaceutical-grade sheet output. Rousselot dominates European cold water-soluble formulations through specialized hydrolysis technology. PB Leiner competes on technical-grade laminates for agricultural mulch applications in Southeast Asian markets.
Gelatin films comprise protein matrices derived from partial hydrolysis of collagen, typically exhibiting tensile strength of 25-45 MPa and moisture barriers below 10 g/m²/day at 25°C, serving as biodegradable substrates for oxygen-sensitive packaging and controlled-release drug layers. Pharmaceutical-grade sheets command premium positioning due to USP-NF compliance burdens and batch certification costs that limit supplier pools. Food-grade rolls face margin compression from competing polysaccharide films, though cold water-soluble variants retain growth traction in instant beverage encapsulation. Biomedical membranes represent the fastest-expanding application as tissue-engineering scaffolds drive demand for composite laminates with synthetic polymer blends.
FDA excipient guidance and USP-NF monographs govern pharmaceutical-grade film purity thresholds, while EMA's MDR framework imposes biocompatibility testing burdens on biomedical membrane suppliers seeking European market access. ISO 10993 standards further structure entry barriers for collagen-derived implantable materials. Stakeholders must monitor regulatory divergence between FDA and EMA pathways for novel gelatin-crosslinking chemistries, as asynchronous approval timelines will fragment competitive positioning across Atlantic supply chains.
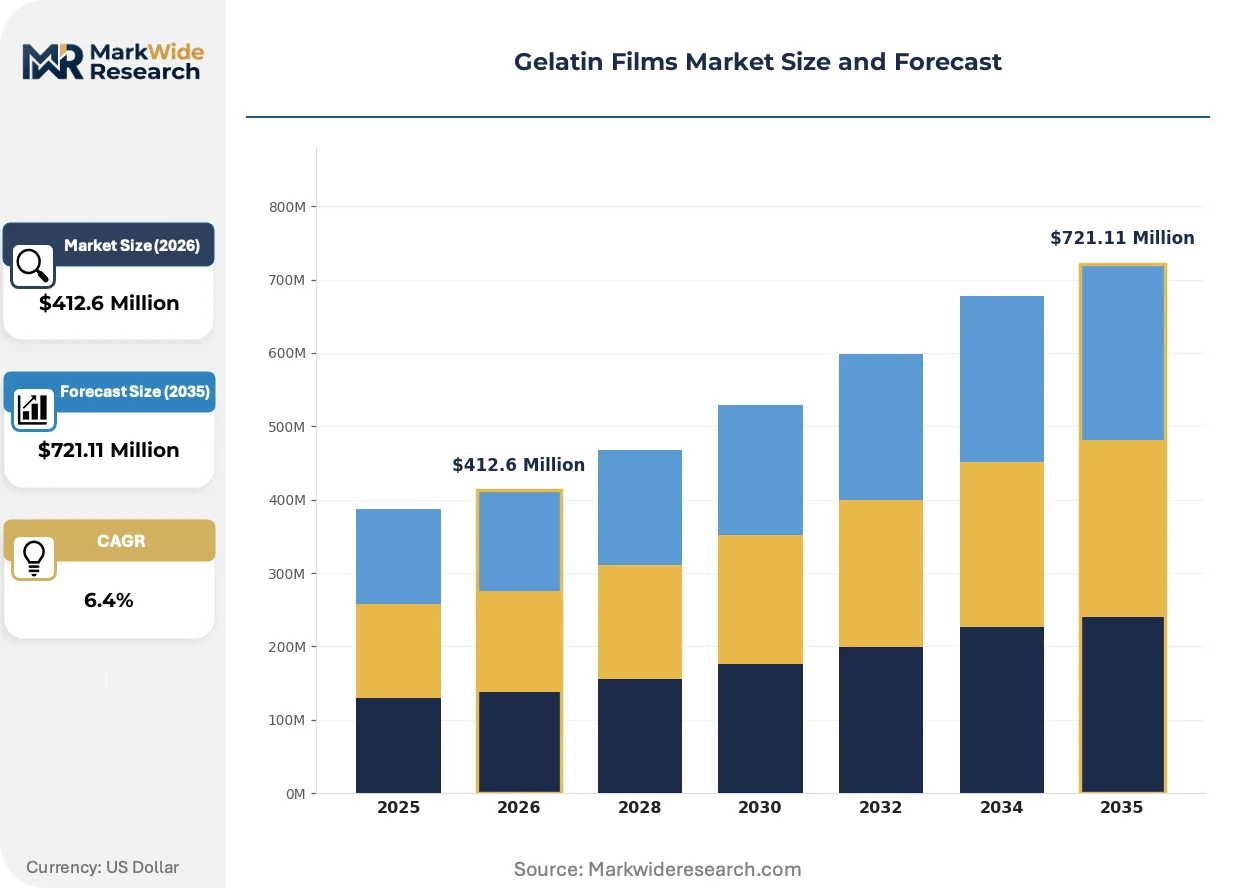
Market Dynamics
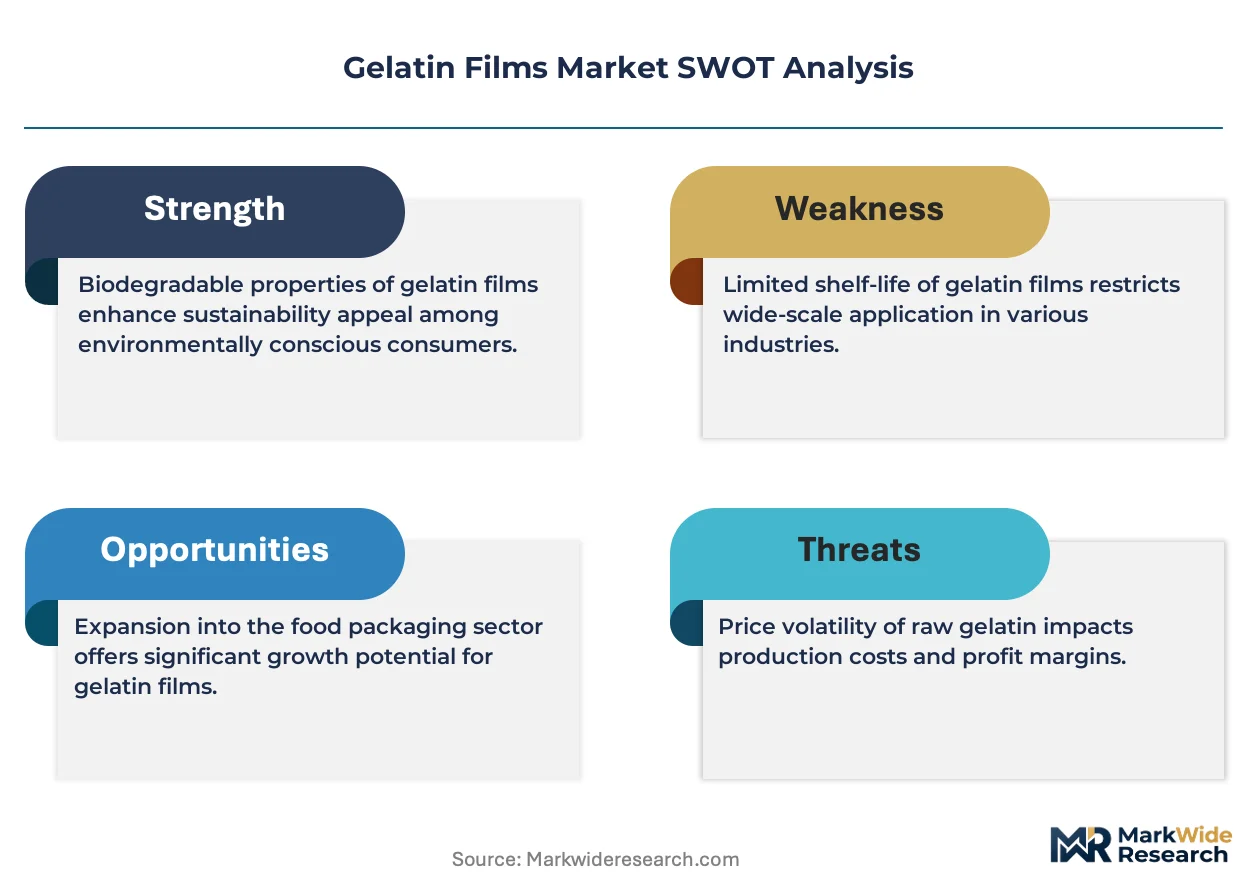
Pharmaceutical-grade certification requirements are compressing supplier pools while cold water-soluble formulations open adjacent food and beverage applications, creating divergent margin structures across gelatin film grades.
Growth Catalysts
- EMA MDR biocompatibility testing:Implantable membrane suppliers face heightened entry barriers that validate incumbent capabilities and sustain premium pricing for certified biomedical laminates.
- Instant beverage encapsulation:Cold water-soluble gelatin films capture share from polysaccharide alternatives in single-serve powder formats across Asian and European markets.
- Halal certification protocols:Pharmaceutical capsule manufacturers in Indonesia and Malaysia require bovine-derived alternatives, expanding addressable demand for porcine-free supply chains.
Market Restraints
- Collagen feedstock volatility:Bovine hide and porcine skin prices fluctuate with livestock cycle conditions and rendering industry capacity constraints.
- German production concentration:Gelita AG and specialized clusters near Eberbach control disproportionate pharmaceutical-grade output, amplifying geographic supply risk.
- Polysaccharide substitution:Pullulan and starch-based films erode food-grade gelatin margins in oxygen-barrier packaging applications.
Strategic Opportunities
- Tissue-engineering scaffold demand:Composite laminates blending gelatin with synthetic polymers address unmet needs in regenerative medicine applications.
- India PLI scheme for medical devices:Domestic manufacturing incentives attract gelatin film converters seeking to serve subcontinent pharmaceutical packaging growth.
- Asset-light extrusion leasing:Equipment rental models reduce capital barriers for mid-scale entrants targeting technical-grade agricultural mulch segments.
Industry Challenges
- USP-NF batch certification timelines:Pharmaceutical-grade film validation requires extended quality documentation that delays new product commercialization.
- Crosslinking chemistry IP fragmentation:Patent thickets around transglutaminase and carbodiimide modification methods complicate freedom-to-operate assessments for novel formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gelatin Films Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $721.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Gelatin, Cold Water-Soluble Gelatin, Pharmaceutical Grade, Food Grade, Technical Grade Application: Food Packaging, Pharmaceutical Capsules, Cosmetic Packaging, Biomedical Membranes, Agricultural Films End User: Pharmaceutical Manufacturers, Food Processing Units, Cosmetic Producers, Biomedical Research Centers, Agricultural Suppliers Form: Sheets, Rolls, Sheets with Coatings, Laminates, Composite Films |
| Companies Covered | Gelita AG, Rousselot, PB Leiner, Darling Ingredients, Nitta Gelatin, Weishardt, Sterling Biotech, Tessenderlo Group, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gelatin Films Market Shifts & Advancements
Material science advances are dissolving traditional boundaries between edible packaging and controlled-release pharmaceutical substrates, with regulatory frameworks struggling to keep pace with hybrid application categories.
Enzymatic hydrolysis protocols are hybridizing cold water-soluble gelatin with modified starch matrices to create dual-function films that dissolve at variable temperature thresholds. Instant coffee and probiotic powder manufacturers in Japan and South Korea adopt these laminates to replace multi-layer plastic sachets. The convergence is compressing demand for single-material polysaccharide alternatives while opening premium positioning for performance-differentiated gelatin grades.
REACH authorization requirements for chromium VI in leather processing are redirecting collagen feedstock flows toward pharmaceutical-grade gelatin production. Tannery byproduct availability shifts as chemical restrictions tighten across ECHA-regulated supply chains. European film converters respond by qualifying Brazilian and Argentinian bovine hide sources to diversify geographic input exposure.
Pharmaceutical procurement departments now mandate excipient supplier qualification audits that extend to collagen source traceability and rendering facility certification. Large capsule manufacturers in the United States and Germany consolidate vendor lists to reduce compliance overhead. This behavioral shift favors integrated producers with captive rendering operations while disqualifying smaller converters lacking documentation infrastructure.
Gelatin Films Market Segmentation
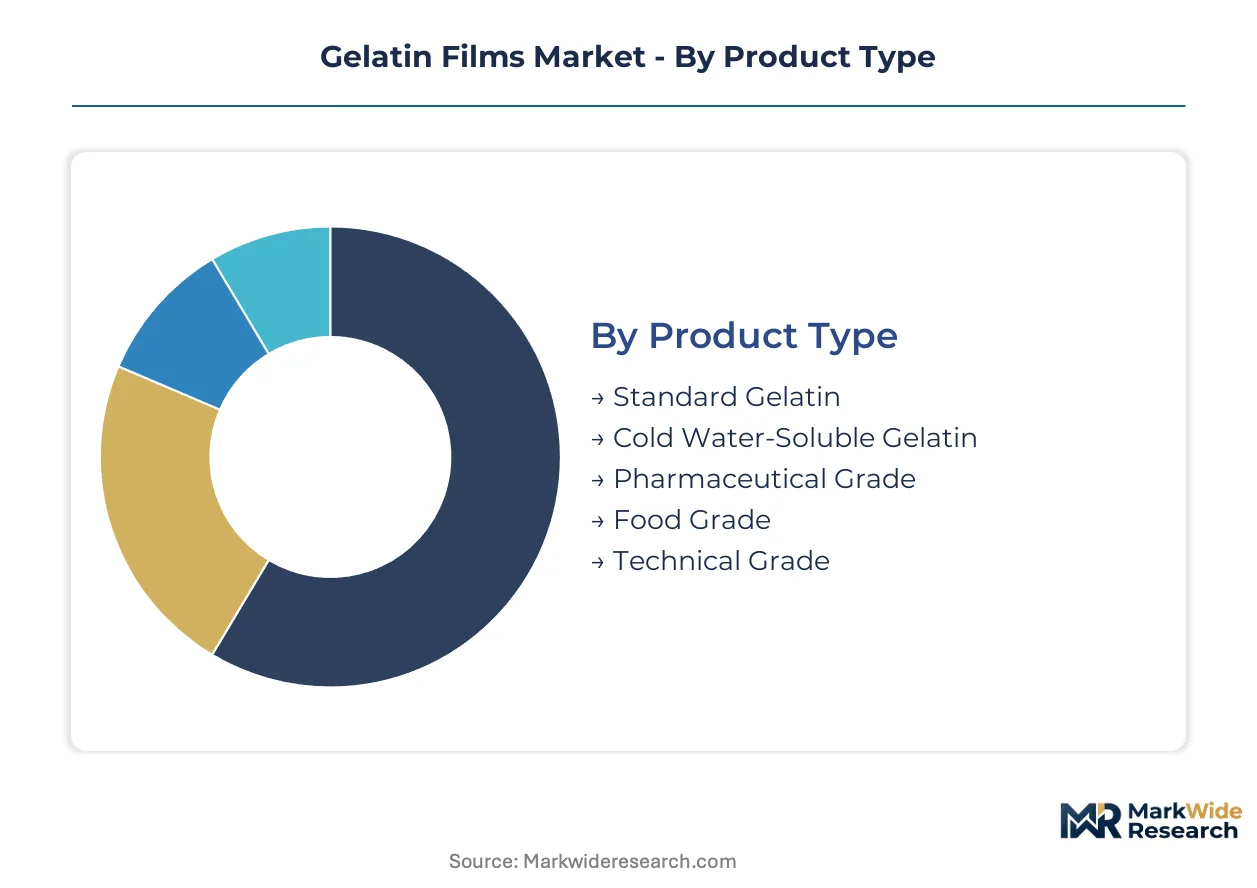
Segmentation in gelatin films determines compliance pathways, pricing tiers, and supplier qualification requirements. Pharmaceutical-grade specifications impose fundamentally different production economics than food or technical grades, fragmenting competitive dynamics across each tier.
Product Type:
After-sales service intensity varies sharply across product tiers, with pharmaceutical-grade films demanding batch certification support and regulatory documentation that technical grades never require.
- Standard Gelatin:Conventional bovine or porcine-derived films with 25-35 MPa tensile strength serve general food wrapping and non-critical packaging. Demand concentrates in European meat packaging operations seeking oxygen barriers below 10 g/m²/day.
- Cold Water-Soluble Gelatin:Specialized hydrolysis protocols yield rapid-dissolution matrices for instant beverage encapsulation. Japanese and South Korean probiotic powder manufacturers adopt these laminates to replace multi-layer plastic sachets, driving fastest share expansion in food-grade categories.
- Pharmaceutical Grade:USP-NF compliance and extended validation documentation anchor premium positioning for capsule shell and controlled-release layer applications.
- Food Grade:Edible film specifications compete directly with pullulan and starch alternatives in oxygen-sensitive confectionery wrapping.
- Technical Grade:Lower-purity formulations serve agricultural mulch and industrial laminate substrates where biodegradability outweighs barrier performance.
Pharmaceutical Grade holds the largest share; momentum sits with Cold Water-Soluble Gelatin.
Application:
Cost tier stratification separates commodity food wrapping from certified biomedical applications, with price multiples exceeding 10x between lowest and highest specification grades.
- Food Packaging:Oxygen barrier films for meat, cheese, and confectionery applications compete against polysaccharide alternatives on unit economics. German and Italian processed meat producers remain anchor demand sources despite margin compression.
- Pharmaceutical Capsules:Two-piece hard shell and soft gel applications demand traceable bovine or porcine collagen sourcing with halal certification protocols expanding addressable demand in Indonesia and Malaysia. USP-NF batch certification sustains supplier pool constraints.
- Cosmetic Packaging:Dissolvable film masks and single-use serum sachets leverage gelatin's skin affinity in South Korean and Chinese beauty markets.
- Biomedical Membranes:Tissue-engineering scaffolds and wound dressing substrates require ISO 10993 biocompatibility validation.
- Agricultural Films:Biodegradable mulch applications in Southeast Asian vegetable production favor technical-grade cost structures.
Pharmaceutical Capsules command the highest value concentration; Biomedical Membranes are climbing the fastest.
End User:
Customer type determines procurement sophistication, with pharmaceutical manufacturers imposing supplier audits that extend to rendering facility certification while agricultural buyers prioritize landed cost.
- Pharmaceutical Manufacturers:Large capsule producers in the United States and Germany consolidate vendor lists to reduce compliance overhead, favoring integrated producers with captive rendering operations.
- Food Processing Units:Instant coffee and probiotic powder manufacturers in Japan drive cold water-soluble formulation demand.
- Cosmetic Producers:South Korean beauty brands specify dissolvable film substrates for premium positioning.
- Biomedical Research Centers:Academic and clinical tissue-engineering programs source composite laminates with synthetic polymer blends.
- Agricultural Suppliers:Southeast Asian vegetable growers adopt technical-grade mulch films for biodegradability compliance.
Pharmaceutical Manufacturers dominate procurement value; Biomedical Research Centers show steepest expansion trajectory.
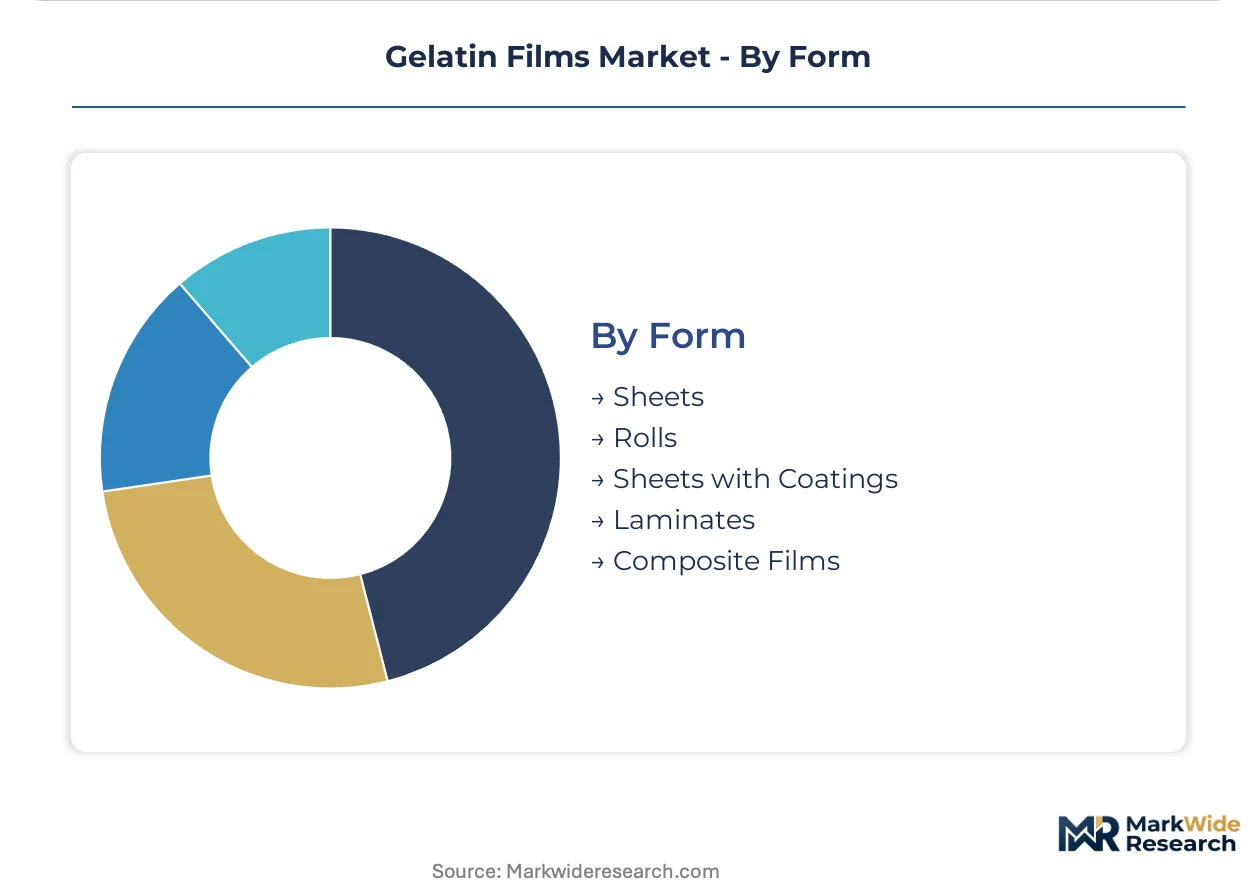
Form:
Volume economics favor roll formats for high-speed converting operations while sheet specifications serve precision pharmaceutical and biomedical applications.
- Sheets:Precision-cut pharmaceutical and biomedical formats require dimensional tolerance controls that rollstock cannot match.
- Rolls:Continuous web formats optimize food packaging line throughput in European meat processing operations.
- Sheets with Coatings:Barrier-enhanced laminates address oxygen-sensitive pharmaceutical and cosmetic applications.
- Laminates:Multi-layer constructions blend gelatin with synthetic polymers for tissue-engineering scaffolds.
- Composite Films:Hybrid matrices with modified starch enable variable temperature dissolution thresholds for instant beverage applications.
Rolls capture highest volume throughput; Composite Films are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is drawing gelatin film converters toward domestic pharmaceutical packaging capacity. REACH authorization pressures in Europe and FDA excipient guidance in North America are tightening compliance requirements that favor established producers with captive supply chains.
Germany
EMA MDR biocompatibility testing requirements sustain premium positioning for certified biomedical membrane suppliers. REACH chromium VI restrictions redirect tannery byproduct flows toward pharmaceutical-grade gelatin production. The Eberbach cluster anchors specialized output serving medical-grade film consumers across European pharmaceutical supply chains.
United States
FDA excipient guidance and USP-NF monographs govern pharmaceutical-grade film purity thresholds for capsule manufacturers. Large capsule producers consolidate vendor lists to reduce compliance overhead. New Jersey and Pennsylvania pharmaceutical corridors favor integrated producers with captive rendering operations and documentation infrastructure.
India
CDSCO pharmaceutical regulations and the PLI scheme for medical devices attract gelatin film converters seeking to serve subcontinent pharmaceutical packaging growth. Halal certification protocols expand addressable demand for bovine-derived alternatives. Gujarat and Maharashtra pharmaceutical manufacturing zones concentrate domestic converting capacity expansion.
Japan
PMDA pharmaceutical standards and METI industrial policy support cold water-soluble formulation development for instant beverage encapsulation. Probiotic powder manufacturers adopt rapid-dissolution matrices to replace multi-layer plastic sachets. The Kanto region around Tokyo anchors demand from functional food and cosmetic packaging sectors.
Indonesia
National halal certification mandates from the country's religious affairs ministry require porcine-free supply chains for pharmaceutical capsule manufacturers. Bovine-derived gelatin alternatives capture share from traditional sources. Java-based pharmaceutical production clusters drive specification requirements for imported pharmaceutical-grade films.
Gelatin Films Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification grades. The supplier base concentrates around integrated collagen producers with captive rendering operations and batch certification capabilities. Three archetypes dominate: pharmaceutical-grade specialists with USP-NF validation infrastructure, food-grade volume producers competing on unit economics, and technical-grade converters serving agricultural mulch segments. Competitive moves center on backward integration into collagen feedstock sourcing and geographic expansion toward Asian pharmaceutical manufacturing growth corridors.
Among European integrated producers, Gelita AG exemplifies the pharmaceutical-grade specialist archetype through its German production concentration. Rousselot occupies a position within cold water-soluble formulation development. PB Leiner sits within the technical-grade segment serving agricultural applications.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| PB Leiner |
| Darling Ingredients |
| Nitta Gelatin |
| Weishardt |
| Sterling Biotech |
| Tessenderlo Group |
| Roquette Frères |
| Others |
Supply & Pricing Matrix
German production clusters near Eberbach anchor pharmaceutical-grade output, concentrating margin capture among integrated collagen producers with captive rendering operations while mid-scale converters face cost disadvantages in certification-heavy tiers.
Pricing Analysis
Certification level creates the primary spread across gelatin film tiers. USP-NF pharmaceutical-grade validation commands premium positioning against food-grade alternatives, with cold water-soluble formulations occupying a mid-tier based on hydrolysis protocol complexity. Cost compression runs through food-grade segments as pullulan and starch films erode oxygen-barrier applications. Agricultural buyers exhibit highest price sensitivity, while biomedical membrane purchasers prioritize biocompatibility documentation over unit economics.
Supply Chain Analysis
REACH authorization requirements for chromium VI in leather processing redirect collagen feedstock flows toward pharmaceutical-grade production, limiting tannery byproduct availability across ECHA-regulated supply chains. Raw material sourcing draws from Brazilian and Argentinian bovine hide operations as European converters diversify geographic input exposure. Single-source vulnerability concentrates around Gelita AG's German cluster for medical-grade sheet output. Distribution feeds through pharmaceutical capsule manufacturers and food packaging converters with qualified supplier status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA and EMA pathways fragments competitive positioning, creating white-space opportunities for specialists capable of navigating asynchronous approval timelines in hybrid application categories.
For Market Incumbents: Pre-empt polysaccharide substitution threats in food-grade segments by accelerating cold water-soluble formulation development for instant beverage encapsulation. Secure backward integration into South American bovine hide sourcing to reduce REACH-driven feedstock volatility. Invest in ISO 10993 biocompatibility infrastructure to capture tissue-engineering scaffold demand. For New Entrants and Emerging Players: Pursue technical-grade agricultural mulch applications in Southeast Asian markets where certification burdens remain lowest. Target India's PLI scheme for medical devices as a manufacturing foothold serving subcontinent pharmaceutical packaging growth. Lead with asset-light extrusion leasing models to bypass capital barriers. For Investors and Strategic Acquirers: Capital is best deployed toward integrated collagen producers with captive rendering operations and USP-NF validation infrastructure, as vendor consolidation among large capsule manufacturers favors documented supply chains. Long-term viability hinges on biocompatibility certification capabilities in regenerative medicine applications. Watch for divergence between FDA and EMA crosslinking chemistry approvals as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collagen Feedstock | Captive bovine hide sourcing insulates margin from REACH-driven tannery byproduct shortages. |
| Halal Certification Infrastructure | Porcine-free supply chains unlock Indonesian and Malaysian pharmaceutical capsule demand. |
| Cold Water-Soluble Formulation Development | Specialized hydrolysis protocols capture share from polysaccharide alternatives in Asian instant beverage markets. |
| ISO 10993 Biocompatibility Investment | EMA MDR compliance validates positioning in fastest-expanding tissue-engineering scaffold applications. |
| Asset-Light Extrusion Leasing | Equipment rental models reduce capital barriers for mid-scale entrants in technical-grade agricultural segments. |
Research Methodology
Operator-level perspectives from pharmaceutical procurement directors, food packaging converters, biomedical research program managers, and collagen rendering facility operators anchored the qualitative base. Secondary validation drew from FDA excipient guidance documents, EMA MDR submission databases, USP-NF monograph revisions, and customs trade flows for gelatin derivatives. Bottom-up demand modeling triangulated against top-down industry value estimates across certification tiers.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product grade, application category, end-user type, and geographic production cluster. CAGRs derived from fitted growth curves applied to validated baseline volumes, incorporating collagen feedstock cycle conditions and regulatory approval timeline assumptions specific to pharmaceutical-grade film commercialization.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Brazilian or Argentinian integrated producers would shift outcomes. Material shifts in EMA-FDA regulatory divergence or REACH chromium VI enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
Potassium Lactate Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Resistant Dextrin Market