
 Organic Food Additives Market | 2026-2036
Organic Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Food Additives Market Outlook
Buyer concentration among European bakery chains and North American beverage co-packers is hardening, forcing additive suppliers to lock multi-year supply agreements. Cargill leverages its integrated grain origination network to secure organic starch feedstock across Midwestern US growing regions. Chr. Hansen Holding A/S specializes in fermentation-derived natural colorants, anchoring its position in dairy applications where label transparency commands premium positioning.
Organic food additives comprise certified organic compounds—preservatives, colors, flavors, and starches—synthesized or extracted from USDA- or EU-organic-approved agricultural feedstocks without synthetic chemical intermediates, typically requiring minimum 95% organic content by dry weight and processing under certified organic handling protocols to maintain integrity for clean-label food manufacturing. Natural preservatives and organic colors lead current revenue pools, reflecting established bakery and dairy demand, while organic flavors represent the fastest-expanding segment as beverage formulators replace artificial flavor systems in functional and premium drinks. Organic starches occupy a mature, volume-heavy position where margin compression from commodity grain volatility competes against steady pull from sauce and convenience food manufacturers seeking thickening without modified starch labeling.
USDA National Organic Program standards, EU Organic Regulation 2018/848, and FDA food additive safety evaluations collectively govern market access, with the EU framework particularly restricting synthetic preservative alternatives and accelerating organic-certified ingredient substitution timelines. The EU Green Deal's Farm to Fork strategy tightens residue thresholds and synthetic input phase-out schedules, directly expanding addressable demand for certified organic preservative and color systems. Stakeholders must monitor evolving equivalency agreements between USDA and third-country organic certifiers, as recognition shifts will determine which suppliers retain access to dual-jurisdiction food manufacturing contracts.
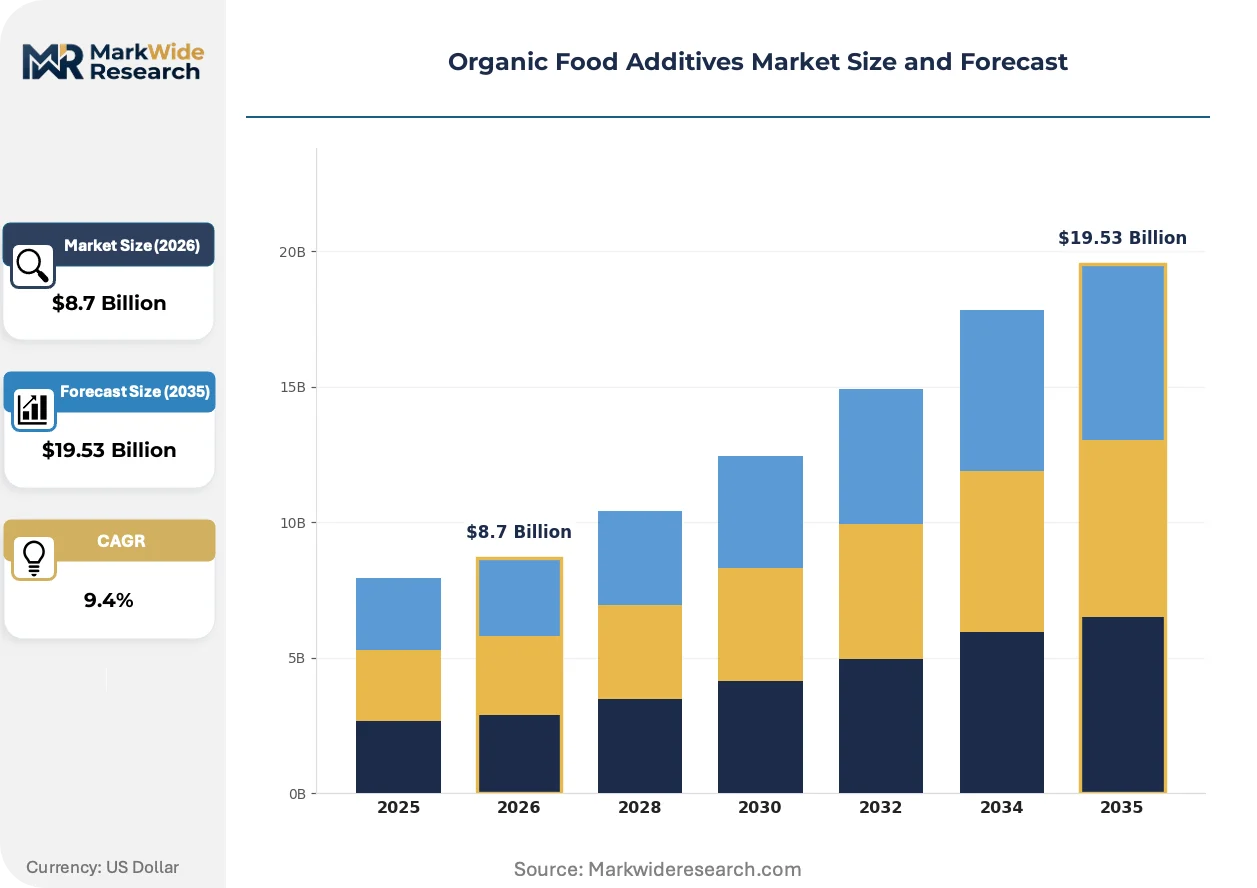
Market Dynamics
EU Green Deal implementation is compressing synthetic additive approval pathways while bakery and beverage manufacturers scramble to reformulate with certified organic alternatives before F-Gas Regulation phase-out deadlines.
Growth Catalysts
- EU Organic Regulation 2018/848:The framework's tightened residue thresholds and synthetic input restrictions are mandating certified organic preservative substitution across dairy and convenience food manufacturing.
- Clean-label bakery demand:European retail chains are specifying organic color and starch certifications as non-negotiable procurement criteria for private-label bread and pastry lines.
- Fermentation-derived colorants:Advances in microbial pigment production are expanding the organic-certified color palette beyond anthocyanin limitations into yellow and orange dairy applications.
Market Restraints
- Organic grain feedstock volatility:Certified organic corn and potato supply fluctuations in Midwestern US growing regions create input cost instability for starch manufacturers.
- Processing capacity concentration:Organic-certified handling facility scarcity in Germany and France limits throughput expansion for preservative and flavor compound producers.
- Shelf-life performance gap:Organic acid and rosemary extract preservatives deliver shorter protection windows than synthetic benzoates in ambient-distribution beverage applications.
Strategic Opportunities
- Functional beverage white space:Organic flavor systems for adaptogenic and protein-fortified drinks remain underdeveloped relative to established bakery and dairy penetration.
- EU Farm to Fork procurement mandates:Public sector foodservice contracts across Italy and Spain are introducing organic additive specifications for school and hospital nutrition programs.
- Direct-to-manufacturer digital platforms:Specialty ingredient marketplaces are disintermediating traditional distributor layers for mid-size organic starch and colorant procurement.
Industry Challenges
- Organic handling certification timelines:New processing facility accreditation under USDA National Organic Program protocols requires 18-24 month validation cycles that delay capacity activation.
- Cross-jurisdictional equivalency complexity:Divergent residue testing methodologies between EU and USDA organic certifiers create documentation friction for dual-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Food Additives Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Preservatives, Organic Colors, Organic Flavors, Organic Starches Application: Bakery, Beverages, Dairy, Sauces End User: Food Manufacturers, Retailers, Restaurants, Home Cooks Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Archer Daniels Midland Company, Cargill, Chr. Hansen Holding A/S, Kerry Group Plc, BASF SE, DuPont, Novozymes, Ingredion, Tate & Lyle Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Food Additives Market Strategic Shifts
Reformulation chemistry and certification protocols are converging to enable synthetic-free preservation across temperature-sensitive food categories previously dependent on artificial additives.
Encapsulation technology for organic essential oil preservatives is integrating controlled-release functionality that extends antimicrobial efficacy in high-moisture bakery applications. Mid-size European contract manufacturers are piloting these systems for clean-label sandwich bread lines. The technology is integrating organic acid protection into supply chains that previously required synthetic calcium propionate.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-dependent cold chain conversions that favor organic acid preservatives over heat-labile synthetic alternatives. Food logistics operators in France and Germany are retrofitting transport fleets with climate-friendly cooling systems. Dairy processors in these markets are responding by locking multi-year organic preservative supply agreements.
Concentrated buyer power among North American beverage co-packers is compressing supplier qualification cycles and unbundling technical service from base ingredient contracts. Smaller organic flavor houses are losing share to integrated starch-color-preservative portfolios that simplify procurement. This pattern is most visible in California and Texas functional drink manufacturing clusters where co-packer consolidation has accelerated since 2023.
Organic Food Additives Market Segmentation
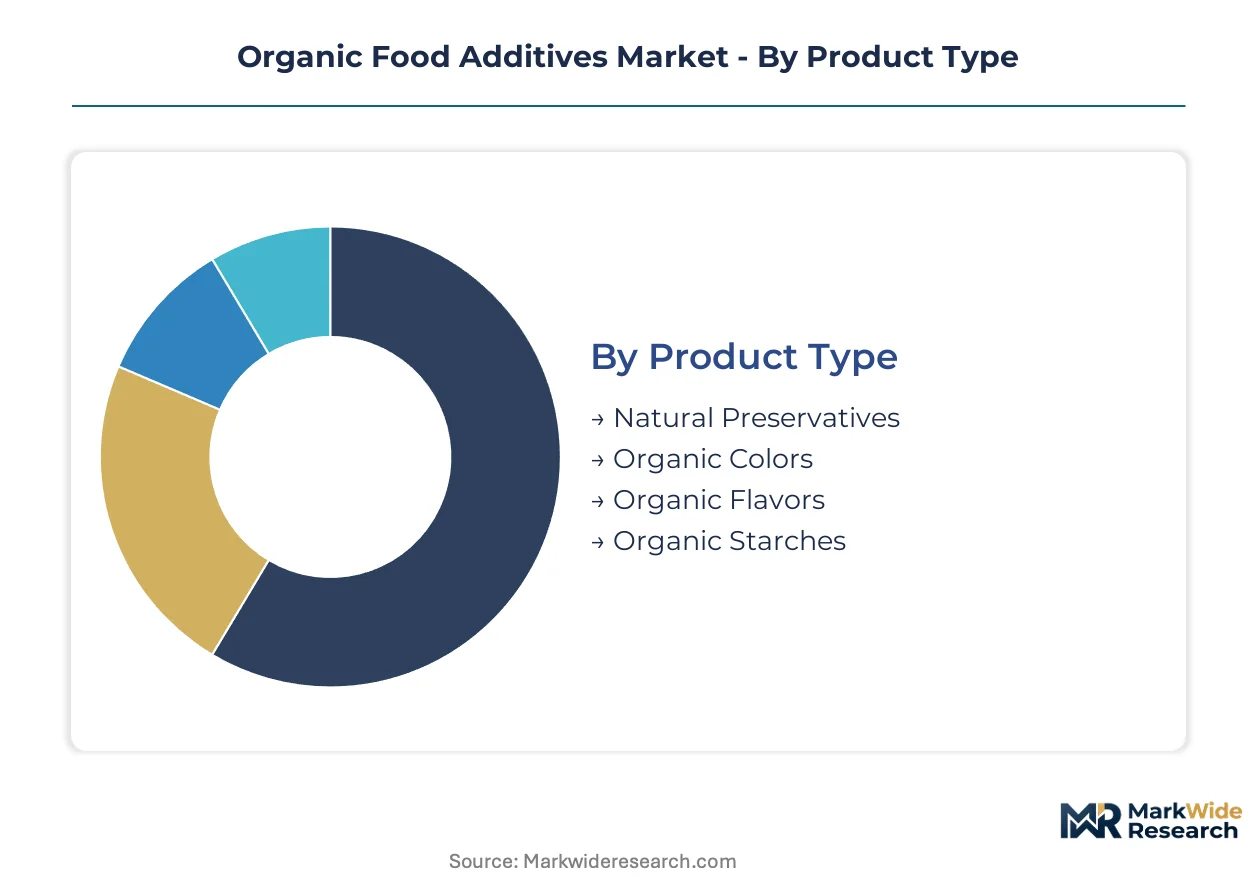
Segmentation in organic food additives reveals where certification premiums command pricing power versus where commodity substitution dominates procurement. Understanding these divisions exposes which product lines justify integrated manufacturing investments and which remain vulnerable to feedstock volatility.
Product Type:
Standalone preservation and color systems anchor bakery and dairy reformulation, while embedded flavor and starch complexes penetrate deeper into processed food matrices.
- Natural Preservatives:Comprising organic acids, rosemary extracts, and cultured dextrose fermented from certified organic substrates. European bakery chains specify these for private-label bread lines where EU Organic Regulation 2018/848 mandates synthetic benzoate replacement.
- Organic Colors:Anthocyanin, carotenoid, and chlorophyll derivatives extracted from USDA- or EU-organic-approved agricultural sources. Beverage co-packers in California and Texas are locking multi-year supply agreements as clean-label positioning hardens.
- Organic Flavors:Fermentation-derived and botanical extracts meeting minimum 95% organic content thresholds.
- Organic Starches:Native corn, potato, and tapioca starches processed under certified organic handling protocols without chemical modification.
Volume placements concentrate in organic starches; the faster expansion belongs to organic flavors.
Application:
Reformulation urgency varies sharply across temperature-controlled versus ambient-stable distribution channels, with regulatory phase-outs dicting substitution timelines.
- Bakery:Clean-label bread and pastry manufacturing drives concentrated demand for organic acid preservatives and natural colorants. German and French retail chains now require organic certification as non-negotiable procurement criteria.
- Beverages:Functional and premium drink categories are displacing artificial flavor systems fastest. Adaptogenic and protein-fortified formulations in North American co-packer networks remain underdeveloped relative to established segments.
- Dairy:Fermentation-derived colorants anchor positioning where label transparency commands premium shelf placement.
- Sauces:Thickening applications favor native organic starches over modified alternatives for clean-label compliance.
Procurement scale tilts toward bakery; beverage applications are climbing the fastest.
End User:
Contract manufacturing concentration versus fragmented foodservice procurement creates divergent margin structures across the value chain.
- Food Manufacturers:Integrated starch-color-preservative portfolios simplify procurement for consolidated co-packer networks.
- Retailers:Private-label specification power is hardening around organic certification requirements.
- Restaurants:Foodservice procurement remains fragmented with slower organic additive adoption.
- Home Cooks:Consumer-packaged goods represent the smallest volume tier with limited commercial significance.
Contract volumes dominate through food manufacturers; retailer specifications are gaining influence fastest.
Form:
Processing compatibility and distribution economics separate high-activity concentrates from bulk-handling formats.
- Liquid:Preferred for beverage integration and automated dosing systems.
- Powder:Dominates bakery dry mixes and extended shelf-life applications.
- Granular:Handles like conventional ingredients with reduced dusting versus powders.
- Paste:Concentrated color and flavor delivery for high-viscosity food matrices.
Operational throughput favors powders; liquid formats are expanding most quickly in beverage manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern US organic corn and potato belts anchor feedstock supply for starch manufacturers, while European bakery chains and North American beverage co-packers concentrate downstream procurement power across distinct regulatory jurisdictions.
United States
Iowa and Illinois organic corn growers supply certified starch processors facing volatile input costs. USDA National Organic Program standards govern handling protocols, with 18-24 month facility accreditation cycles delaying capacity expansion. California and Texas functional beverage manufacturing clusters are locking multi-year organic flavor and colorant supply agreements as co-packer consolidation accelerates clean-label procurement.
Germany
Private-label bakery chains in Bavaria and North Rhine-Westphalia mandate organic certification as non-negotiable procurement criteria for bread and pastry lines. EU Organic Regulation 2018/848 and the F-Gas Regulation are compressing synthetic additive approval pathways. Frankfurt and Hamburg logistics operators are retrofitting climate-friendly cooling fleets, prompting dairy processors to secure multi-year organic preservative contracts.
France
Retail concentration in Île-de-France and Auvergne-Rhône-Alpes drives demand for organic acid preservatives in ambient-distribution bakery applications. The EU Green Deal's Farm to Fork strategy tightens residue thresholds and synthetic input phase-out schedules. Lyon and Marseille dairy processors are anchoring fermentation-derived colorant procurement where label transparency commands premium shelf placement.
Italy
Emilia-Romagna and Lombardy sauce manufacturers favor native organic starches over modified alternatives for clean-label compliance. Public sector foodservice contracts under Farm to Fork procurement mandates are introducing organic additive specifications for school and hospital nutrition programs. Bologna and Milan convenience food producers are piloting encapsulation technology for organic essential oil preservatives in high-moisture applications.
India
Maharashtra and Gujarat food manufacturers are expanding organic-certified handling capacity to serve export markets requiring dual USDA-EU equivalency documentation. FSSAI alignment with international organic standards is accelerating domestic certification infrastructure investment. Mumbai and Ahmedabad ingredient suppliers are navigating 18-24 month validation cycles to activate organic processing facilities for starch and flavor compound production.
Organic Food Additives Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived specialty positions. The vendor base clusters around integrated grain processors, fermentation technology specialists, and diversified ingredient portfolios. Three archetypes dominate: captive feedstock controllers, microbial platform developers, and full-spectrum solution providers. Competitive intensity manifests through multi-year supply agreement lock-ins and organic handling facility accreditation races.
Within the integrated processing tier, Cargill and Archer Daniels Midland Company exemplify captive feedstock strategies anchored in Midwestern US organic grain origination networks. Chr. Hansen Holding A/S occupies a fermentation-specialist position, representing microbial pigment and cultured ingredient platforms. BASF SE and Kerry Group Plc sit within diversified chemical and nutrition portfolios, anchoring positions where cross-selling organic color, flavor, and preservative systems simplifies procurement for consolidated manufacturing customers.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Chr. Hansen Holding A/S |
| Kerry Group Plc |
| BASF SE |
| DuPont |
| Novozymes |
| Ingredion |
| Tate & Lyle Plc |
| Others |
Value Chain & Pricing Dynamics
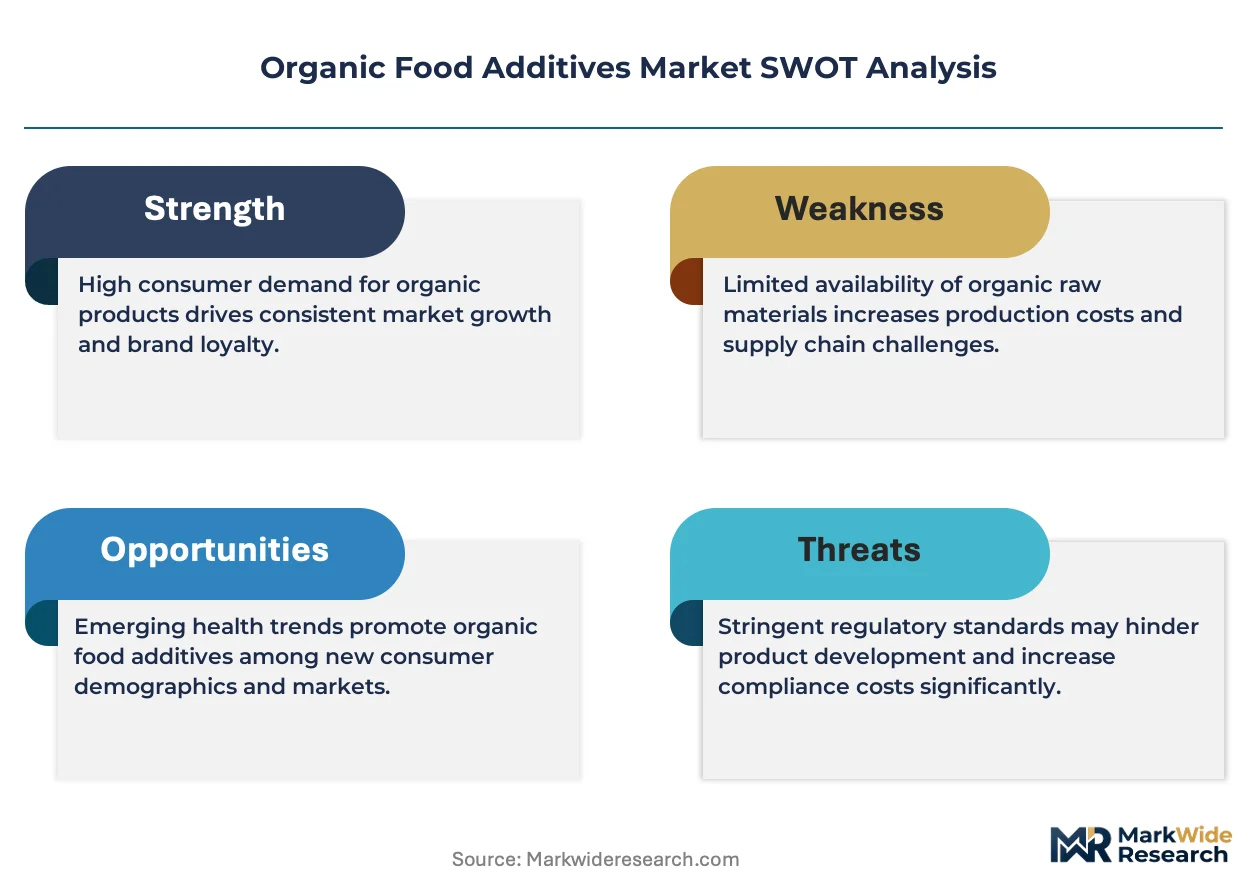
Certification-grade divergence between EU Organic Regulation 2018/848-compliant systems and conventional natural alternatives manifests in both pricing premiums and supply chain fragmentation, with multi-year contract lock-ins at the premium tier and spot-market volatility at the commodity end.
Pricing Analysis
Technical service bundling separates integrated portfolio suppliers from unbundled commodity traders. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EU Organic Regulation 2018/848 full-compliance commanding the highest tier. Cost compression in the economy tier is intensifying because organic grain feedstock volatility transfers directly to starch manufacturers. Beverage co-packers in California and Texas show the least price sensitivity due to clean-label positioning requirements, while fragmented foodservice procurement remains most exposed to spot-price swings.
Supply Chain Analysis
Organic corn and potato supply rests on Iowa and Illinois growers, with German and French handling facilities providing downstream processing concentration. Certified organic substrates, fermentation-derived colorants, and native starches constitute the core input stack. Single-source vulnerability runs through Midwestern organic grain origination where weather-driven yield fluctuations create input instability. Distribution runs through multi-year supply agreements with consolidated bakery chains and beverage co-packers, bypassing traditional distributor layers for mid-size procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated feedstock-to-ingredient platforms, with organic handling certification timelines and buyer concentration squeezing specialty suppliers without captive grain networks.
For Market Incumbents: Anchor multi-year supply agreements with EU bakery chains and North American beverage co-packers before F-Gas Regulation phase-out deadlines accelerate reformulation demand. Deepen backward integration into Midwestern organic corn origination to insulate starch margins from feedstock volatility. Lock fermentation-derived colorant capacity in Germany and France where processing facility scarcity limits competitor expansion. For New Entrants and Emerging Players: The price-point gap between premium EU Organic Regulation 2018/848-certified systems and economy-tier conventional natural additives opens white space in functional beverage flavor systems. Target adaptogenic and protein-fortified drink categories in California and Texas manufacturing clusters where established penetration lags bakery and dairy. Pursue direct-to-manufacturer digital platform distribution to disintermediate traditional layers and secure qualification cycles with mid-size processors. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-technology specialists given EU Green Deal synthetic substitution mandates expanding addressable demand. Long-term viability favors microbial pigment and cultured ingredient platforms over commodity starch processors facing margin compression. Watch organic handling facility accreditation activation rates in Germany and France as the inflection signal for throughput-constrained supply tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Grain Origination | Cargill's Midwestern network demonstrates how captive feedstock insulates starch margins from commodity volatility. |
| Fermentation-Derived Colorant Capacity Expansion | Chr. Hansen's microbial pigment platforms capture EU dairy reformulation demand where synthetic alternatives face phase-out. |
| Multi-Year Supply Agreement Lock-Ins | Beverage co-packers in California and Texas are consolidating procurement around integrated portfolios simplifying technical qualification. |
| Organic Handling Facility Accreditation | EU processing scarcity in Germany and France creates throughput bottlenecks that accredited competitors can monetize. |
| Direct-to-Manufacturer Digital Platform Launch | Specialty ingredient marketplaces disintermediate distributor layers for mid-size organic starch and colorant procurement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at organic-certified handling facilities, procurement leads at European bakery chains and North American beverage co-packers, technical R&D directors at fermentation specialists, and distribution channel partners in Germany and France. FDA food additive safety evaluations, USDA National Organic Program standards documentation, EU Organic Regulation 2018/848 implementation guidance, and FSSAI alignment reports provided regulatory validation. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Product-type granularity modeled natural preservatives, organic colors, organic flavors, and organic starches separately, with application-level splits across bakery, beverages, dairy, and sauces, and end-user distinctions between food manufacturers, retailers, restaurants, and home cooks. CAGRs were derived from trend extrapolation adjusted for regulatory phase-out schedules and reformulation urgency indicators across the projection horizon. Organic grain feedstock yield assumptions and fermentation technology cost curves informed cost-side modeling.
Underlying measurement precision varies by segment; organic starches and natural preservatives carry tighter precision given established volume data, while organic flavors and encapsulation technology pilots carry wider uncertainty bands. Forecasts reflect documented assumptions about EU Green Deal implementation pace and USDA-EU equivalency agreement stability. Regulatory recognition shifts, organic certification validation delays, and commodity grain price spikes warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Allulose for Food Market