
 Emulsified Shortenings Market | 2026-2036
Emulsified Shortenings Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsified Shortenings Market Foresight
Foodservice distribution networks are reshaping how emulsified shortenings reach mid-sized bakeries and regional restaurant chains. Cargill leverages its oilseed crush and refining footprint to sustain supply security across North American baking corridors. Wilmar International anchors Asia-Pacific availability through integrated palm oil operations spanning plantation to specialty fats. AAK AB differentiates through tailored lipid formulations for industrial confectionery clients requiring precise melting profiles.
Emulsified shortening consists of plasticized fat systems containing mono- and diglycerides, lecithin, or polysorbate emulsifiers distributed within a hydrogenated or interesterified vegetable oil base, typically exhibiting solid fat indices between 15 and 35 percent at 25 degrees Celsius to ensure aeration stability and moisture retention. Bakery shortening dominates volume as established formulations serve high-throughput commercial bread and cake operations, while whipping shortening captures expanding margin pools from premium dessert and frozen confectionery applications where overrun control commands technical premiums. Deep-frying shortening faces structural pressure from alternate frying media in quick-service restaurant chains, though its stability at elevated temperatures preserves niche demand in snack manufacturing.
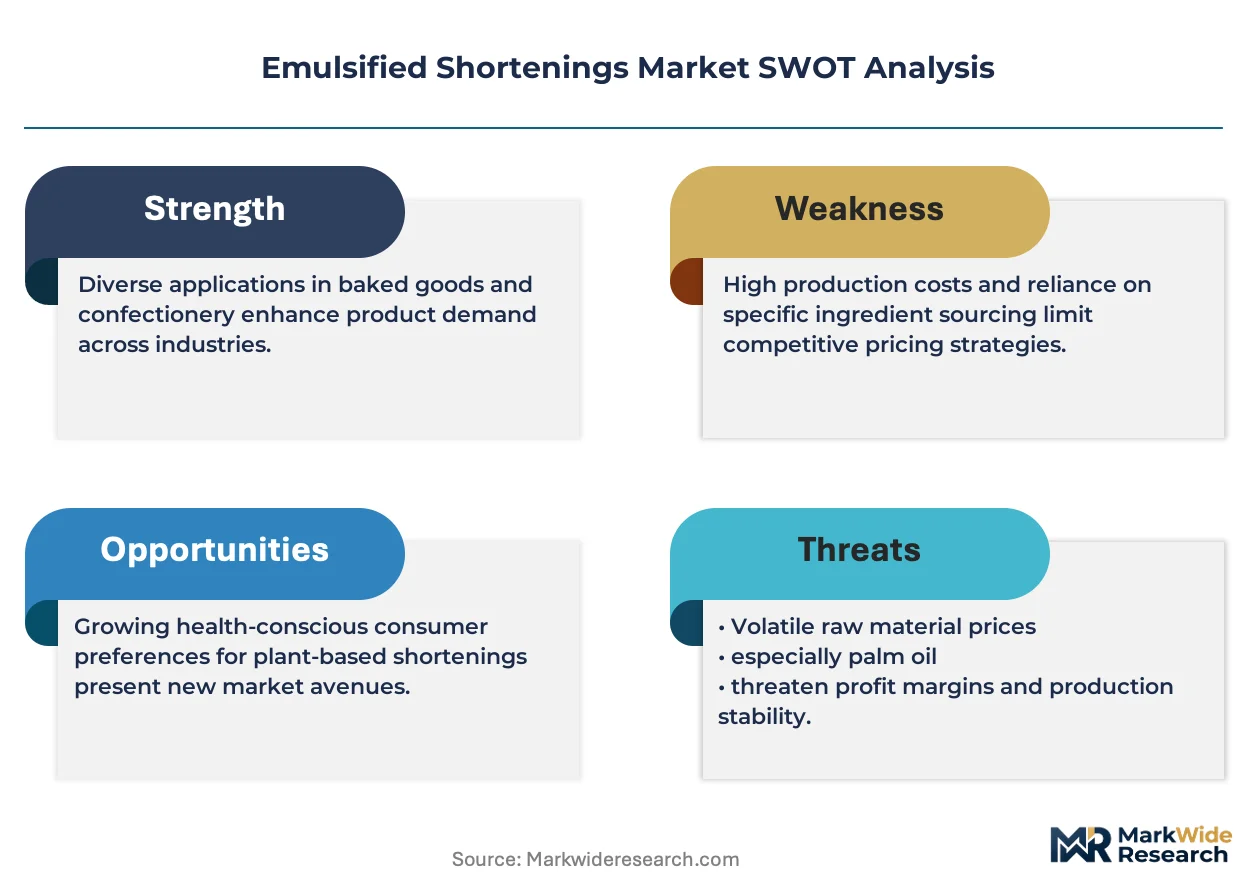
The FDA's trans-fat elimination framework and the EU's F-Gas Regulation on industrial processing emissions shape formulation chemistry and equipment investment requirements for manufacturers serving regulated jurisdictions. BIS standards in India and China's GB food additive specifications further fragment compliance obligations for exporters targeting multiple national markets. Stakeholders must monitor enzymatic interesterification scale-up economics and regional oilseed supply shifts to align capacity with evolving emulsifier cost structures.
Market Dynamics
Enzymatic interesterification is collapsing the technical barrier between functional performance and clean-label positioning, forcing reformulation investments across hydrogenated shortening portfolios.
Growth Catalysts
- Trans-fat labeling mandates:FDA's trans-fat elimination framework and the EU's updated nutrition claims regulation compel industrial bakeries to source interesterified alternatives.
- Southeast Asian palm oil clusters:Integrated refiners in Malaysia and Indonesia control upstream emulsifier supply, concentrating cost-competitive feedstock access.
- High-ratio bakery formulations:Commercial bread and cake operations demand consistent creaming performance that only emulsified shortenings deliver at scale.
Market Restraints
- Palm oil price volatility:Crude palm oil futures in Kuala Lumpur and Rotterdam create margin compression for specialty fat processors.
- Upstream concentration risk:Malaysian and Indonesian plantation groups control 85% of global palm oil trade, exposing buyers to supply disruptions.
- Enzymatic process capex:Commercial-scale interesterification reactors require stainless steel vessels and immobilized lipase systems that smaller refiners cannot finance.
Strategic Opportunities
- Indian foodservice expansion:Mid-sized bakeries in Mumbai and Bangalore lack reliable emulsified shortening supply, creating white space for distribution partnerships.
- Frozen confectionery premiumization:Dessert manufacturers seek whipping shortenings with precise overrun control for premium layered cakes and mousses.
- EU F-Gas Regulation compliance:Industrial processors investing in low-emission chilling systems for fat crystallization lines qualify for green financing incentives.
Industry Challenges
- Refrigeration engineer scarcity:Crystallization line optimization requires specialists who understand solid fat index modulation, a skill set concentrated in European and Malaysian technical institutes.
- Multi-jurisdiction additive approvals:Mono- and diglyceride emulsifiers face divergent GB standards in China, BIS specifications in India, and FDA GRAS determinations, extending product launch timelines.
- Legacy hydrogenation asset stranding:Partial hydrogenation equipment cannot pivot to interesterification without complete reactor replacement, trapping capital in obsolete configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsified Shortenings Market |
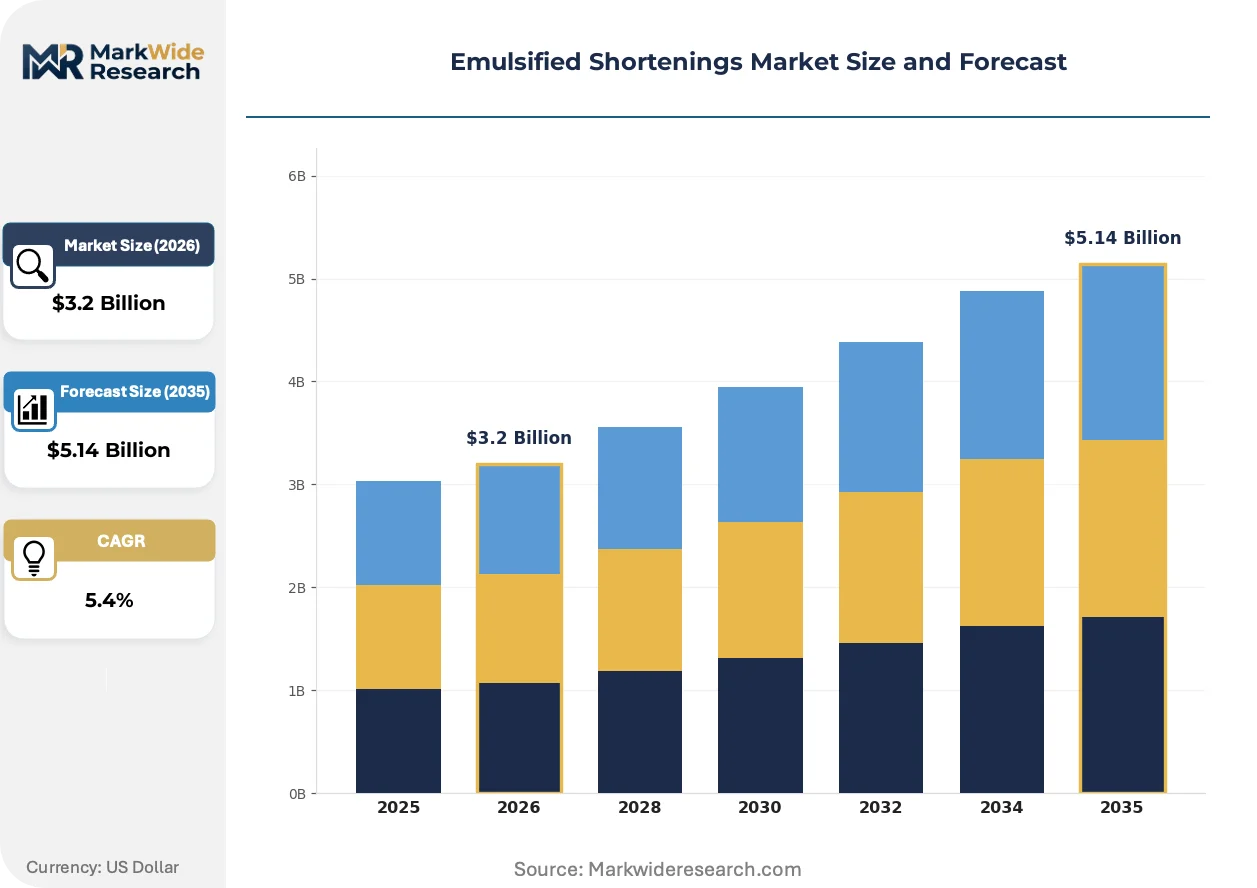
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bakery Shortening, Creaming Shortening, Deep-Frying Shortening, Whipping Shortening Application: Baking, Frying, Spreading, Confectionery End User: Bakeries, Restaurants, Food Manufacturers, Catering Services Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Wilmar International, Mallet & Co, Cargill, Fuji Oil Holdings, Lonza, Archer Daniels Midland Company, AAK AB, IOI Group, Bunge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsified Shortenings Market Shifts & Advancements
Process chemistry and procurement architecture are reshaping competitive positioning in emulsified shortenings, with enzymatic methods and direct distribution models compressing legacy value chains.
Enzymatic interesterification is collapsing the cost premium between hydrogenated and non-hydrogenated shortening bases. Immobilized lipase reactors from Novozymes and DSM modify triglyceride structure without trans-fat generation. Industrial bakeries in Germany and the Netherlands are retrofitting crystallization lines to accept enzymatically processed feedstocks, compressing the price differential that previously favored chemical interesterification.
REACH authorization requirements for nickel catalyst residues are tightening specification windows for European shortening imports. The European Chemicals Agency's 2023 updated dossier review demands sub-ppm nickel detection in food-grade fats. Exporters to Rotterdam and Hamburg ports must install atomic absorption spectroscopy at refinery gates, adding analytical overhead that smaller Malaysian processors struggle to absorb.
Direct sourcing contracts between plantation-integrated refiners and multinational bakery groups are displacing spot market purchasing. Cargill and Wilmar International now negotiate three-year offtake agreements with industrial bread manufacturers, locking in volume commitments against palm oil price bands. This concentration is most visible in North American baking corridors, where procurement teams consolidate supplier panels to secure emulsifier supply security.
Emulsified Shortenings Market Segmentation
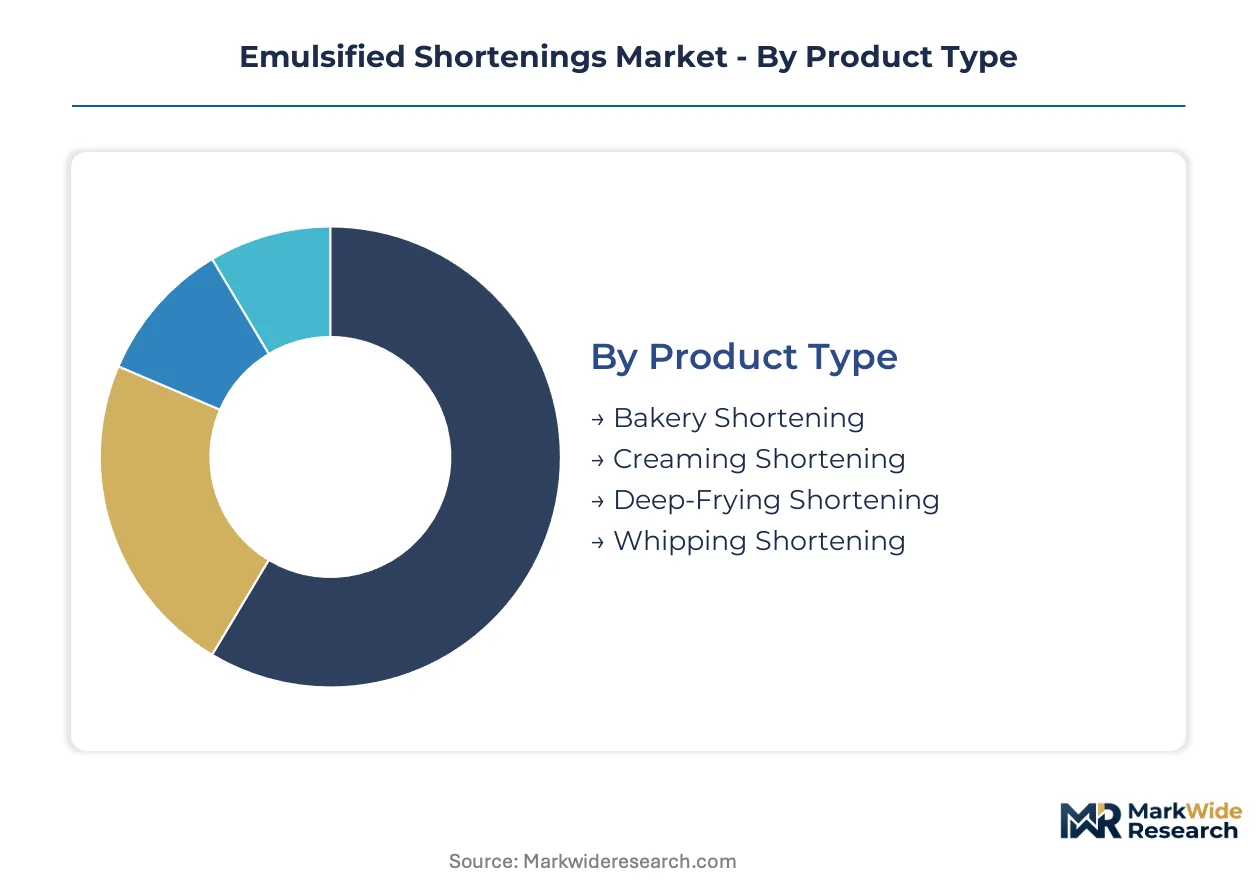
Segmentation in emulsified shortenings reveals how technical specifications align with distinct operational requirements across baking, frying, and confectionery environments. Product viscosity, solid fat index ranges, and emulsifier loadings determine suitability for specific equipment and throughput demands. Understanding these divisions helps procurement teams match shortening functionality to production line constraints.
Product Type:
After-sales technical support intensity varies sharply across product categories, with industrial bakeries demanding formulation troubleshooting that commodity shortening suppliers rarely provide.
- Bakery Shortening:Plasticized fat systems with 15-35% solid fat content at 25°C deliver consistent creaming performance for high-throughput bread and cake operations. Demand concentrates in Southeast Asian palm oil processing clusters where integrated refiners control upstream emulsifier supply, though enzymatic interesterification investments are reshaping formulation chemistry.
- Whipping Shortening:Specialized emulsifier blends enable precise overrun control for premium dessert applications requiring stable foam structures. Frozen confectionery manufacturers in Germany and the Netherlands are retrofitting crystallization lines to accept enzymatically processed feedstocks, compressing price differentials that previously favored chemical interesterification.
- Creaming Shortening:Optimized mono- and diglyceride distributions support rapid air incorporation in cake batters.
- Deep-Frying Shortening:Oxidative stability at elevated temperatures preserves niche demand in snack manufacturing despite pressure from alternate frying media.
Bakery shortening holds the largest share; momentum sits with whipping shortening.
Application:
Cost tier stratification separates commodity frying applications from premium confectionery formulations requiring precise melting profiles.
- Baking:Commercial bread and cake operations represent the foundational demand base, with industrial bakeries expanding procurement of high-ratio emulsified shortenings for consistent creaming performance at scale.
- Confectionery:Layered cakes and mousses require whipping shortenings with controlled solid fat indices that deliver technical premiums through overrun precision.
- Frying:Quick-service restaurant chains are displacing traditional deep-frying shortenings with alternate frying media, constraining volume growth.
- Spreading:Retail and foodservice table spreads demand specific plasticity ranges for knifeability and mouthfeel.
Baking commands volume leadership; confectionery offers the steepest expansion trajectory.
End User:
Customer type determines order frequency, technical service requirements, and contract structure across the value chain.
- Food Manufacturers:Industrial scale operations negotiate multi-year offtake agreements with plantation-integrated refiners, locking in volume commitments against palm oil price bands.
- Bakeries:Mid-sized operations in Mumbai and Bangalore lack reliable emulsified shortening supply, creating white space for distribution partnerships.
- Restaurants:Regional chains source through foodservice distribution networks reshaping procurement access.
- Catering Services:Event-based demand requires flexible packaging formats and rapid replenishment cycles.
Food manufacturers dominate procurement volume; bakeries represent the most underpenetrated segment.
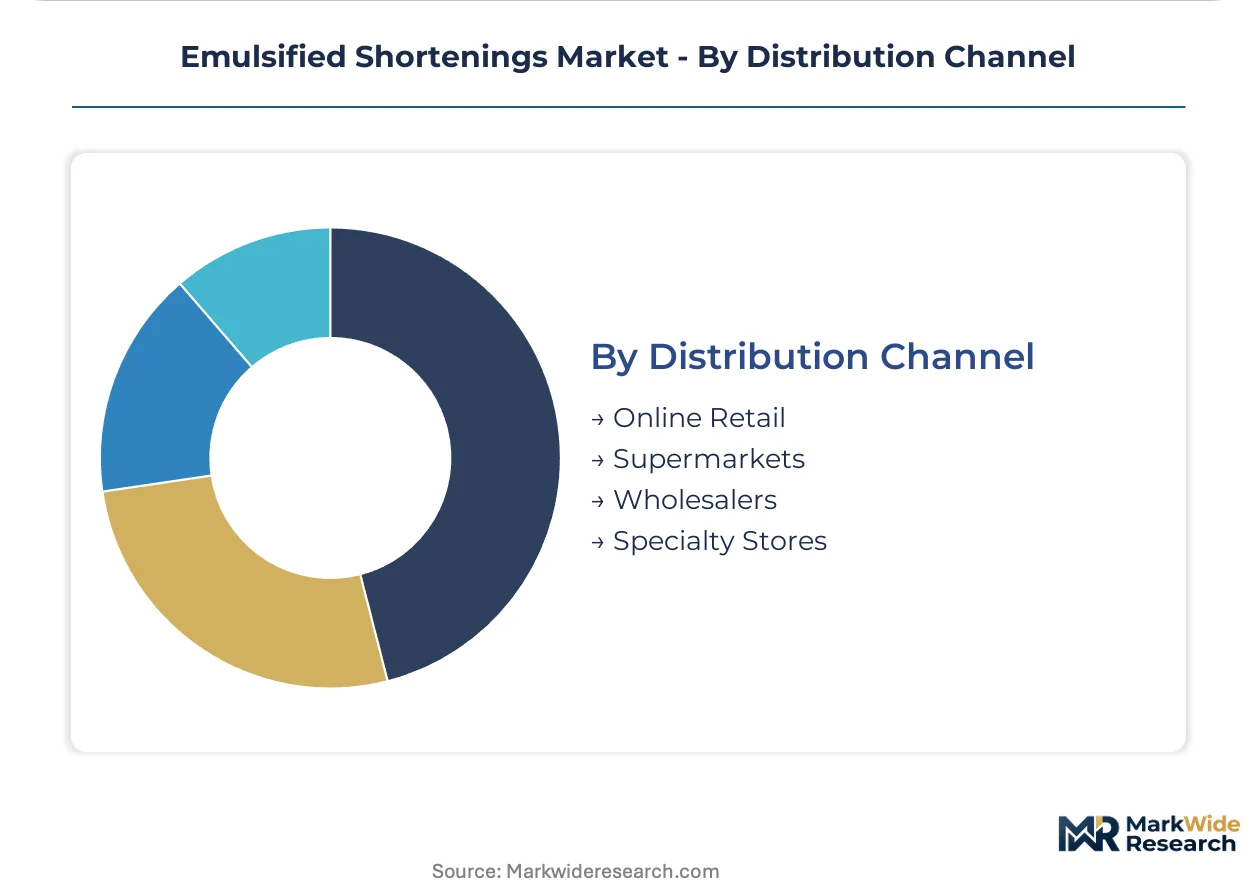
Distribution Channel:
Supply concentration in Malaysian and Indonesian plantation groups shapes channel economics and buyer risk exposure.
- Wholesalers:Traditional bulk distribution to industrial bakeries and food manufacturers maintains volume leadership through established logistics networks.
- Online Retail:E-commerce platforms are gaining traction among mid-sized bakeries seeking transparent pricing and reduced procurement friction.
- Supermarkets:Retail packaging for small commercial and institutional buyers requires adapted product formats.
- Specialty Stores:Niche channels serve artisanal bakers requiring customized lipid formulations with precise melting profiles.
Wholesalers retain the largest share; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palm oil refiners in Malaysia and Indonesia extract pricing premiums from integrated plantation control, while European processors absorb compliance costs from REACH nickel catalyst rules that Asian exporters bypass. This asymmetry reshapes trade flows and investment location decisions.
United States
Industrial bakeries along the Midwest baking corridor source high-ratio emulsified shortenings through multi-year offtake agreements. FDA trans-fat elimination rules finalized in 2015 continue forcing hydrogenated portfolio reformulations. Kansas City and Chicago distribution hubs concentrate procurement teams consolidating supplier panels for emulsifier supply security.
Germany
Confectionery manufacturers in Hamburg and Cologne retrofit crystallization lines for enzymatically processed feedstocks. ECHA's 2023 REACH nickel residue authorization demands sub-ppm detection thresholds at Rotterdam port entry. Bavarian technical institutes train the refrigeration engineers scarce across European fat processing operations.
China
GB food additive specifications for mono- and diglyceride emulsifiers fragment compliance timelines for multinational exporters. Yangtze River Delta baking clusters in Shanghai and Suzhou expand procurement of interesterified alternatives. Domestic refiners scale enzymatic reactor capacity to serve mid-sized bakeries in Beijing-Tianjin-Hebei.
India
BIS standards for food-grade fats diverge from FDA and EFSA specifications, extending product registration cycles. Mumbai and Bangalore mid-sized bakeries lack reliable emulsified shortening supply, creating distribution partnership opportunities. Gujarat and Maharashtra industrial zones attract Malaysian plantation-integrated refiners seeking direct sourcing contracts.
Indonesia
Integrated plantation-to-refinery operations in Sumatra and Kalimantan control upstream emulsifier supply for Asia-Pacific bakery chains. Domestic processors face margin compression from Kuala Lumpur crude palm oil futures volatility. Surabaya and Medan clusters export specialty fats to Indian and Chinese food manufacturers under long-term volume commitments.
Emulsified Shortenings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in emulsifier and base oil supply. The market structures around plantation-integrated refiners with captive palm oil supply, independent specialty fat processors with formulation expertise, and diversified agribusiness trading houses with oilseed crush networks. Three archetypes dominate: integrated plantation-refinery operators, enzymatic process technology licensors, and regional distribution consolidators. Competitive moves concentrate on direct sourcing contract negotiations and crystallization line retrofit partnerships.
Among Asia-Pacific plantation-integrated operators, Wilmar International and IOI Group exemplify the upstream-control archetype through Sumatra and Kalimantan refining footprints. Cargill represents the North American agribusiness trading house model with oilseed crush and distribution density across Midwest baking corridors. AAK AB occupies the European specialty fat processor tier, differentiated by tailored lipid formulation capabilities for industrial confectionery clients requiring precise melting profile control.
| Leading Market Players |
|---|
| Wilmar International |
| Mallet & Co |
| Cargill |
| Fuji Oil Holdings |
| Lonza |
| Archer Daniels Midland Company |
| AAK AB |
| IOI Group |
| Bunge |
| Others |
Supply & Pricing Matrix
Malaysian and Indonesian plantation groups controlling 85 percent of global palm oil trade concentrate upstream pricing power in the hands of integrated refiners, pushing margin pools downstream toward enzymatic process technology licensors and specialty formulation houses in Europe and North America.
Pricing Analysis
Configured-to-order pricing for tailored lipid formulations with precise melting profiles commands 15-25 percent premiums over standard bakery shortening grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by emulsifier loading and solid fat index precision. Cost compression in standard grades is intensifying because spot market palm oil volatility erodes processor margins. Mid-sized bakeries in emerging markets exhibit the highest price sensitivity, while industrial confectionery clients prioritize technical performance over unit economics.
Supply Chain Analysis
Contract-manufacturing concentration sits with plantation-integrated refiners in Sumatra and Kalimantan, where Wilmar International and IOI Group hold crystallization line capacity for Asia-Pacific bakery chains. Geographic supply concentrates in Malaysia, Indonesia, and the Netherlands, with Rotterdam serving as the primary European entry point. Raw material dependencies center on crude palm oil, mono- and diglyceride emulsifiers, and immobilized lipase enzyme systems. Single-source vulnerability from Malaysian-Indonesian upstream control exposes buyers to supply disruptions. Distribution runs through direct sourcing contracts between plantation-integrated refiners and multinational bakery groups, displacing spot market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in emulsified shortenings rests on enzymatic interesterification adoption accelerating as FDA and EU trans-fat regulations mature, with industrial bakeries retrofitting crystallization lines at rates that outpace legacy hydrogenation asset depreciation.
For Market Incumbents: Entrench enzymatic process capabilities through partnerships with Novozymes or DSM for immobilized lipase reactor access, and lock in three-year offtake agreements with Midwest baking corridor procurement teams before specialty fat processors capture formulation relationships. Hydrogenation asset stranding threatens capital trapped in obsolete partial hydrogenation equipment. For New Entrants and Emerging Players: Build out distribution partnerships targeting Mumbai and Bangalore mid-sized bakeries lacking reliable emulsified shortening supply, and develop white-label whipping shortening formulations for frozen confectionery manufacturers in Germany seeking overrun control precision. Foodservice distribution networks offer the most penetrable channel for regional market entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty fat processors in Europe holding REACH-compliant nickel-residue detection infrastructure and Bavarian-trained refrigeration engineering talent. Five-to-ten year viability hinges on enzymatic interesterification scale-up economics achieving parity with chemical processing. Watch enzymatic reactor capacity utilization rates as the inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil Plantations | Captive supply of crude palm oil insulates integrated refiners from Kuala Lumpur futures volatility. |
| Enzymatic Interesterification Licensing | Technology partnerships with DSM and Novozymes accelerate clean-label reformulation timelines for industrial bakeries. |
| REACH Nickel Residue Compliance Investment | Atomic absorption spectroscopy at refinery gates secures Rotterdam and Hamburg port access for European exports. |
| Direct Sourcing Contract Negotiation | Three-year offtake agreements with multinational bakery groups displace spot market purchasing concentration risk. |
| Crystallization Line Retrofit Partnership | Equipment upgrades for enzymatically processed feedstocks compress price differentials favoring chemical interesterification. |
Research Methodology
A spread of perspectives from procurement directors at industrial bakeries, technical R&D leads at specialty fat processors, distribution channel partners in foodservice networks, and regulatory affairs specialists at plantation-integrated refiners converged on the working assumptions. Primary interviews combined with secondary validation from FDA GRAS determinations, ECHA REACH authorization dossiers, BIS food additive specifications, and customs trade data for palm oil derivatives. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Demand-supply-balance framing across the analysis window modeled consumption by industrial bakeries, confectionery manufacturers, and foodservice operators against enzymatic reactor capacity expansion and hydrogenation asset retirement. Segmentation dimensions included product type, application environment, end-user scale, and regional regulatory cluster. CAGRs derived from slope analysis of historical volume trends adjusted for trans-fat regulation implementation timelines and enzymatic process adoption curves. Forecast inputs incorporated solid fat index specification shifts and emulsifier cost structure evolution.
Stress conditions across crude palm oil price volatility bands, enzymatic lipase cost inflation scenarios, and REACH nickel residue enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and technology substitution rates. Palm oil futures volatility, enzymatic reactor scale-up delays, and multi-jurisdiction additive approval fragmentation present revision risks. Quarterly review of enzymatic reactor capacity utilization and trans-fat regulation enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Glandular Ingredients Market