
 Cultures Market | 2026-2036
Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Cultures Market Analysis
Direct-to-brewery distribution is reshaping how culture suppliers engage craft and industrial beverage producers. Chr. Hansen Holding A/S leverages its strain banking capabilities to anchor long-term supply contracts with dairy cooperatives across Northern Europe. Lallemand Inc. competes through specialized yeast portfolios tailored for wine and brewing applications. Angel Yeast Co. Ltd. dominates Asian fermentation markets through integrated production from molasses sourcing to finished dry yeast.
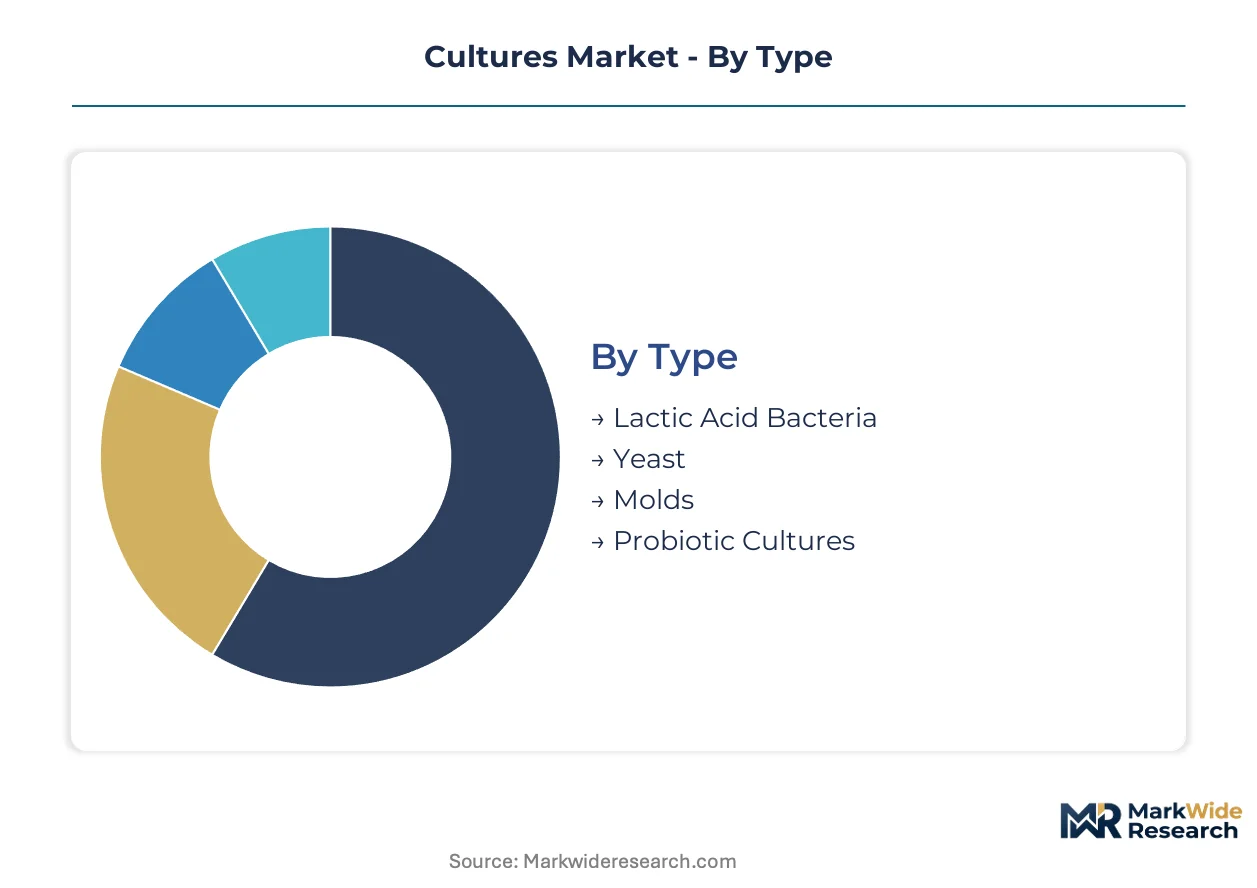
Cultures comprise live or attenuated microorganisms—bacteria, yeast, or molds—cultivated under controlled conditions of temperature, pH, and nutrient availability, typically achieving cell densities of 10^8 to 10^12 CFU per gram in commercial preparations. These organisms serve as biological catalysts in food fermentation, probiotic formulations, and industrial enzyme production, converting substrates into metabolites with defined flavor, texture, or bioactive profiles. Lactic acid bacteria cultures command the largest share within dairy applications, where mesophilic and thermophilic strains determine product identity for cheese and yogurt categories. Probiotic cultures represent the fastest-expanding type segment, as nutraceutical end users demand validated strain-specific health claims supported by clinical documentation. Yeast cultures in fermented beverages maintain mature, high-volume demand, though margin pools increasingly concentrate in specialty strains for low-alcohol and flavored beer variants.
FDA oversight of Generally Recognized As Safe notifications shapes strain approval timelines for US-targeted probiotic launches, while EFSA's qualified health claim assessments determine market access for European nutraceutical applications. The EU F-Gas Regulation constrains refrigeration-dependent culture manufacturing, pushing producers toward energy-efficient fermentation technologies. Stakeholders must monitor evolving strain patent landscapes and regulatory divergence between jurisdictions to secure competitive positioning in culture supply.
Market Dynamics
Precision fermentation scale-up is compressing batch timelines and forcing biopharmaceutical manufacturers to renegotiate strain supply contracts with culture houses. This technology shift is redistributing margin pools from traditional dairy applications toward industrial biotechnology corridors.
Growth Catalysts
- EU Green Deal compliance mandates:The EU F-Gas Regulation is accelerating energy-efficient fermentation technology adoption across European biological production facilities. Refrigeration-dependent manufacturers face equipment replacement deadlines.
- Biopharmaceutical precision fermentation:Microbial culture demand from pharmaceutical manufacturers is expanding as cell therapy and recombinant protein production scales. Heidelberg and Mannheim host concentrated facility investments.
- Probiotic health claim validation:Clinical documentation requirements for strain-specific benefits are pulling nutraceutical end-users toward documented culture suppliers. EFSA qualified health claim assessments determine European market access.
Market Restraints
- Molasses supply volatility:Yeast culture production depends on sugar industry byproduct availability. Weather-driven harvest fluctuations in Brazil and India create input cost instability for dry yeast manufacturers.
- Strain banking concentration:Long-term supply contracts anchor dairy cooperatives to limited culture repositories. Northern European strain banks control access to heritage mesophilic and thermophilic varieties.
- FDA GRAS notification timelines:US-targeted probiotic launches face extended approval cycles. Strain-specific safety documentation requirements delay product commercialization by 18-24 months.
Strategic Opportunities
- Direct-to-brewery distribution channels:Craft and industrial beverage producers are bypassing traditional ingredient distributors. Culture suppliers capture margin through specialized yeast portfolio segmentation.
- Low-alcohol beer strain development:Specialty yeast variants for reduced-alcohol fermentation represent untapped application space. Flavored beer variants demand tailored metabolic profiles.
- Asian fermentation market penetration:Integrated molasses-to-yeast production models dominate regional supply. Western suppliers face barriers to entry without backward integration into raw material sourcing.
Industry Challenges
- Patent landscape navigation:Strain intellectual property disputes complicate licensing agreements. Proprietary genome editing techniques create enforcement complexity across jurisdictions.
- Clinical documentation capacity:Probiotic health claim validation requires sustained investment in human trials. Mid-size culture houses lack internal research infrastructure to support EFSA submission requirements.
- Legacy dairy contract renegotiation:Long-term supply agreements with cooperatives embed volume commitments that constrain flexibility. Industrial biotechnology demand competes for fermentation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultures Market |
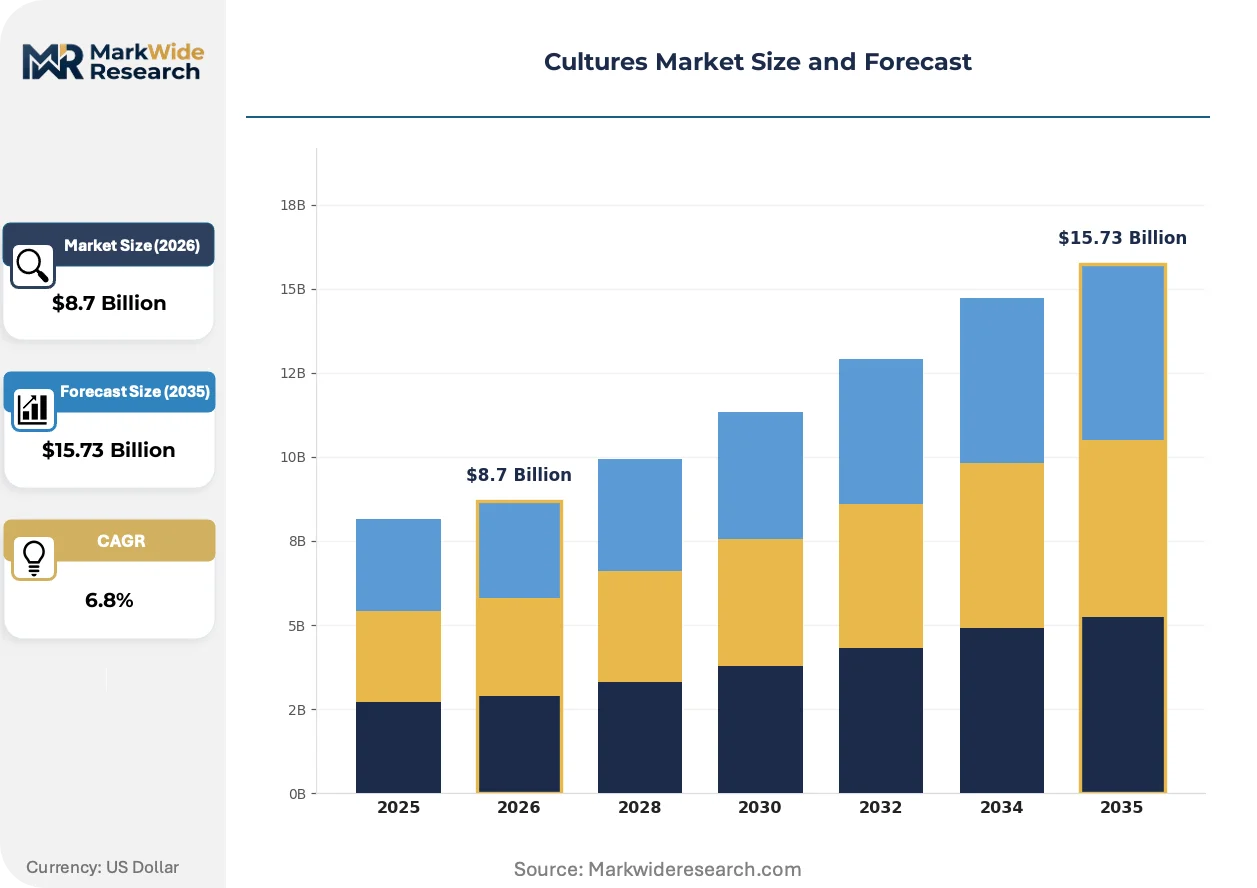
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Lactic Acid Bacteria, Yeast, Molds, Probiotic Cultures Application: Dairy Products, Fermented Beverages, Meat Products, Sauces Form: Liquid, Powder, Granular, Capsules End User: Food Industry, Beverage Production, Nutraceuticals, Personal Care |
| Companies Covered | Chr. Hansen Holding A/S, Dohler Group, DSM-Firmenich AG, Lallemand Inc., Angel Yeast Co. Ltd., Sacco S.R.L, Novonesis A/S, International Flavors & Fragrances Inc., CSK Food Enrichment B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultures Market Emerging Trajectories
Continuous fermentation systems are displacing batch processing in high-volume applications, while genome editing tools accelerate strain development cycles. Regulatory divergence between FDA and EFSA pathways is fragmenting product launch strategies.
Single-use bioreactor technology is migrating from stainless steel vessel dominance in pharmaceutical-grade culture production. Biopharmaceutical manufacturers adopt disposable contact surfaces to reduce cross-contamination risk between therapeutic protein campaigns. This shift compresses facility turnaround times from weeks to days, enabling multi-product manufacturing at previously dedicated sites.
EFSA qualified health claim assessments are tightening evidentiary standards for probiotic strain benefits. European nutraceutical applications now require human intervention studies with defined endpoints for digestive or immune function. Strain suppliers without clinical documentation capabilities face exclusion from premium positioning in German and French pharmacy channels.
Buyer concentration among industrial biotechnology clusters is consolidating procurement leverage. Heidelberg and Mannheim corridor manufacturers negotiate multi-year strain supply agreements with volume guarantees and exclusive metabolic pathway access. Direct technical collaboration between culture houses and precision fermentation operators is displacing traditional ingredient distributor intermediation in this segment.
Cultures Market Segmentation
Culture suppliers configure product portfolios across multiple technical and commercial dimensions. Strain characteristics, physical form factors, and end-use specifications determine manufacturing investment priorities and margin capture potential.
Type:
Microorganism taxonomy defines fermentation performance parameters and regulatory classification pathways.
- Lactic Acid Bacteria:Mesophilic and thermophilic strains achieve 10^8 to 10^12 CFU per gram in commercial preparations. Dairy cooperatives across Northern Europe anchor long-term supply contracts to heritage strain repositories for cheese and yogurt identity.
- Yeast:Saccharomyces and non-Saccharomyces variants catalyze alcoholic fermentation with defined metabolic profiles. Craft breweries in Germany and industrial beverage producers in Brazil concentrate procurement around specialty strains for low-alcohol and flavored beer applications.
- Molds:Filamentous fungi including Penicillium and Aspergillus species generate proteolytic and lipolytic enzymes. Surface-ripened cheese production and traditional fermented soy applications in Japan and Korea drive strain selection criteria.
- Probiotic Cultures:Clinically documented strains with validated health claims command premium positioning. EFSA qualified health claim assessments and FDA GRAS notification pathways determine European and US market access timelines.
Lactic acid bacteria holds installed capacity. Probiotic cultures is rotating up the share rankings.
Application:
End-use categories align strain development investment with specific substrate conversion requirements and finished product specifications.
- Dairy Products:Cheese, yogurt, and fermented milk applications require precise acidification kinetics and texture development. Thermophilic streptococci and lactobacilli determine product identity in Italian PDO varieties and Greek strained yogurt formats.
- Fermented Beverages:Wine, beer, and kombucha production demands alcohol tolerance, flocculation behavior, and flavor compound generation. Precision fermentation scale-up in Heidelberg and Mannheim corridors is compressing traditional batch timelines.
- Meat Products:Starter cultures for fermented sausages deliver pH reduction, color stabilization, and biopreservation. Southern European charcuterie traditions and emerging clean-label applications in US specialty meat channels concentrate demand.
- Sauces:Soy sauce, fish sauce, and fermented condiment production relies on mold-dominated koji fermentation. Asian integrated production models from molasses sourcing through finished culture dominate regional supply architecture.
Dairy products holds installed capacity. Fermented beverages is rotating up the share rankings.
Form:
Physical presentation formats determine supply chain logistics, shelf stability, and end-user handling protocols.
- Liquid:Frozen or refrigerated concentrates deliver high viability for immediate industrial inoculation. Cold chain dependency constrains distribution radius and elevates logistics costs for remote brewery and dairy plant deliveries.
- Powder:Freeze-dried or spray-dried preparations achieve extended ambient stability. Direct-to-brewery distribution channels favor powder formats for craft producer flexibility and inventory management.
- Granular:Agglomerated particles improve dispersibility in high-solids food matrices. Meat processing and large-scale dairy applications prioritize handling efficiency over unit viability metrics.
- Capsules:Unit-dose presentation aligns with nutraceutical and personal care finished product requirements. EFSA health claim validation and FDA GRAS status underpin premium positioning in German pharmacy and US supplement channels.
Powder holds installed capacity. Capsules is rotating up the share rankings.
End User:
Customer category concentration shapes technical service intensity and contract structuring approaches.
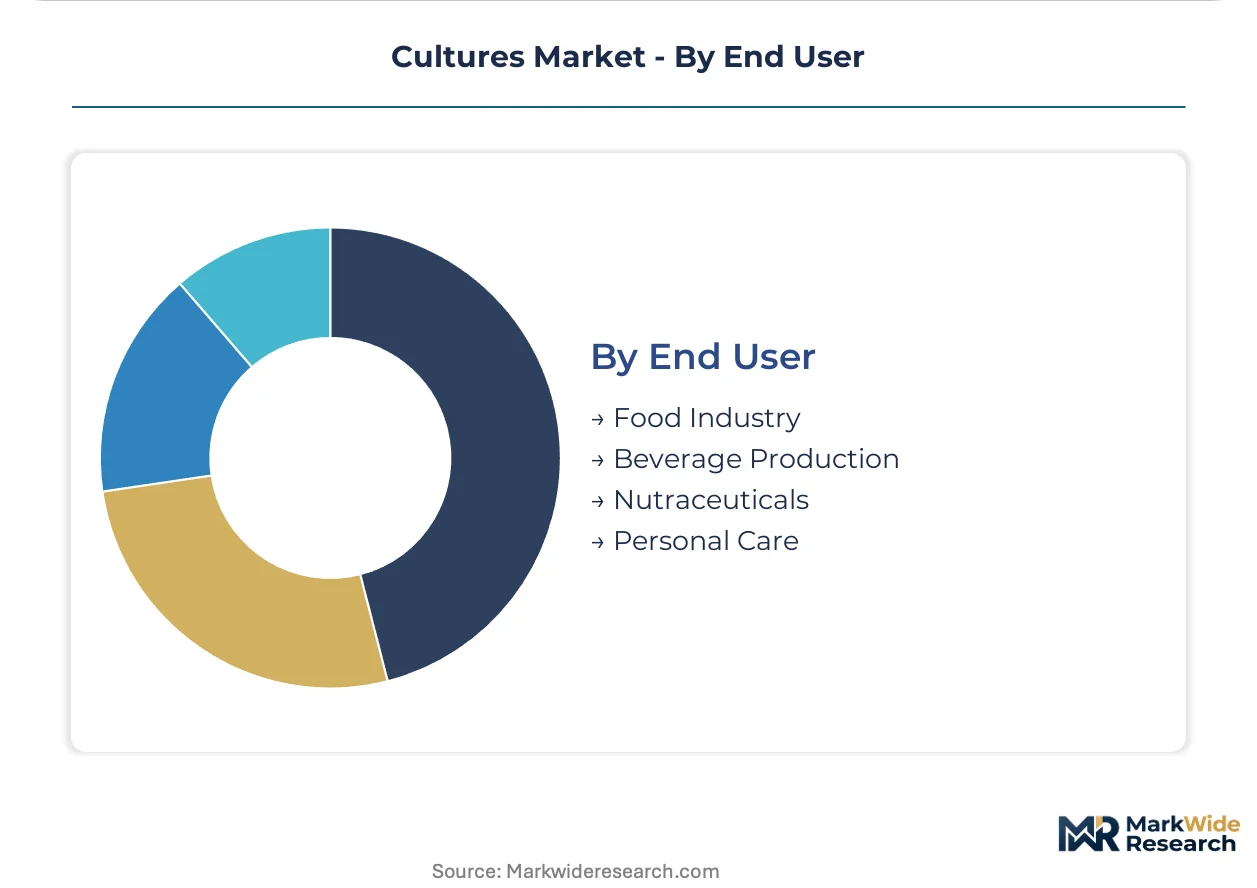
- Food Industry:Industrial dairy, bakery, and prepared food manufacturers procure high-volume, standardized culture specifications. Long-term supply agreements with cooperatives embed volume commitments that constrain fermentation capacity flexibility.
- Beverage Production:Wine, brewing, and distilling operations demand strain-specific metabolic performance. Direct technical collaboration between culture houses and precision fermentation operators is displacing traditional distributor intermediation.
- Nutraceuticals:Probiotic supplement and functional food manufacturers require clinical documentation for health claim substantiation. Human intervention studies with defined digestive or immune endpoints determine EFSA qualified claim eligibility.
- Personal Care:Topical probiotic and fermented ingredient applications in skincare represent emerging demand. Strain selection prioritizes safety for dermal contact over traditional oral consumption pathways.
Food industry holds installed capacity. Nutraceuticals is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European culture suppliers command premium positioning through EFSA-validated health claims, while Asian producers leverage integrated molasses sourcing to undercut on cost. This pricing-power asymmetry redistributes procurement leverage across dairy, beverage, and nutraceutical end users.
Germany
Precision fermentation scale-up in the Heidelberg-Mannheim corridor concentrates biopharmaceutical culture demand. The EU F-Gas Regulation mandates equipment replacement for refrigeration-dependent manufacturers by 2030. Strain banking heritage in Lower Saxony anchors dairy cooperative supply contracts for mesophilic and thermophilic varieties.
United States
FDA GRAS notification timelines extend probiotic commercialization cycles for nutraceutical entrants. The Inflation Reduction Act incentivizes domestic biomanufacturing capacity expansion. Boston-Cambridge cell therapy clusters negotiate multi-year strain supply agreements with volume guarantees.
China
Angel Yeast's integrated molasses-to-dry-yeast production dominates regional fermentation supply. SAMR's strengthened food safety oversight tightens culture import documentation requirements. Yangtze River Delta biopharmaceutical parks attract precision fermentation facility investments from Western technology licensors.
Brazil
Sugarcane harvest volatility in São Paulo state creates molasses input cost instability for yeast manufacturers. ANVISA's probiotic registration pathway requires strain-specific safety dossiers for supplement market access. Southern charcuterie traditions concentrate starter culture demand in Rio Grande do Sul meat processing corridors.
India
FSSAI's standardized culture specifications for traditional dairy products open formal market channels for organized suppliers. The PLI scheme for food processing incentivizes automated fermentation infrastructure. Gujarat dairy cooperatives scale thermophilic culture adoption for Greek yogurt format production.
Cultures Market Vendor Landscape
Heritage strain repositories and integrated fermentation specialists split the market into distinct capability tiers. Consolidation pressure concentrates around biopharmaceutical precision fermentation contracts and EFSA-validated probiotic positioning. Two strategic archetypes dominate: diversified culture houses with clinical documentation infrastructure, and regionally integrated yeast producers with captive raw material access. Capacity expansion and exclusive metabolic pathway licensing represent the dominant competitive moves.
Within the heritage repository tier, Chr. Hansen Holding A/S and Novonesis A/S occupy positions anchored to Northern European dairy cooperative relationships. DSM-Firmenich AG exemplifies the diversified nutrition-science archetype spanning pharmaceutical and food applications. Among Asia-integrated producers, Angel Yeast Co. Ltd. represents backward-controlled supply chain configuration from agricultural substrate through finished culture.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Dohler Group |
| DSM-Firmenich AG |
| Lallemand Inc. |
| Angel Yeast Co. Ltd. |
| Sacco S.R.L |
| Novonesis A/S |
| International Flavors & Fragrances Inc. |
| CSK Food Enrichment B.V. |
| Others |
Supply Flow & Price Mechanics
Fermentation capacity utilization in the Heidelberg-Mannheim corridor sits above 85%, compressing batch availability for new entrants and forcing incumbent culture houses to exercise pricing power through configured-to-order strain development. This tightness propagates through dairy cooperative contracts and biopharmaceutical precision fermentation agreements alike, embedding volume guarantees that insulate established suppliers from spot-price competition.
Pricing Analysis
The customization-premium spread between standard catalog strains and configured-to-order metabolic pathways reaches 3-4x for biopharmaceutical applications. Pricing stratifies across premium, standard, and economy tiers, with EFSA-validated probiotic strains commanding the highest positioning and commodity dry yeast anchoring the base. Cost compression in standard dairy cultures is intensifying because Angel Yeast's integrated molasses sourcing undercuts European producers on input costs. Industrial biotechnology buyers exhibit the least price sensitivity due to strain-specific pathway requirements, while craft breweries demonstrate acute elasticity to yeast pricing.
Supply Chain Analysis
Upstream feedstock dependence on Brazilian and Indian sugarcane harvests creates molasses supply volatility that ripples through yeast culture production economics. Manufacturing concentrates in Germany, China, and Denmark, with strain banking heritage anchoring Northern European dairy supply and integrated molasses-to-yeast models dominating Asian output. Single-source vulnerability around heritage mesophilic repositories in Lower Saxony threatens long-term contract security for cheese identity strains. Distribution runs through direct technical collaboration for precision fermentation clients and traditional ingredient distributors for food industry volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up is fragmenting procurement patterns across biopharmaceutical, nutraceutical, and beverage end users, creating specialist niches for culture houses with documented strain capabilities. This demand-side shift rewards targeted capability investments over undifferentiated volume expansion.
For Market Incumbents: Pre-empt precision fermentation contract consolidation by locking multi-year volume guarantees with Heidelberg-Mannheim corridor manufacturers before capacity constraints harden. Anchor defensive positioning through exclusive metabolic pathway licensing that blocks competitor access to high-margin biopharmaceutical applications. Prioritize strain patent enforcement to protect genome-edited variants from generic replication. For New Entrants and Emerging Players: Build out clinical documentation infrastructure to access EFSA-qualified health claim positioning in German and French pharmacy channels, the most penetrable premium segment for documented probiotic suppliers. Target direct-to-brewery distribution bypassing traditional ingredient intermediaries, capturing margin through specialty yeast portfolios for low-alcohol beer variants. Lead with technical service intensity rather than price competition. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because strain banking concentration and regulatory documentation barriers protect incumbent returns while precision fermentation demand compounds. Target acquisition candidates with EFSA-validated strain libraries or exclusive biopharmaceutical supply relationships. Watch FDA GRAS notification backlog clearance as an inflection signal for US nutraceutical market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Validation Investment | Clinical documentation infrastructure unlocks German pharmacy channel premium positioning for probiotic strains. |
| Precision Fermentation Capacity Expansion | Heidelberg-Mannheim corridor facility investments capture biopharmaceutical contract manufacturing demand. |
| Direct-to-Brewery Distribution Buildout | Specialized yeast portfolio segmentation captures margin from craft and industrial beverage producers. |
| Strain Patent Portfolio Enforcement | Genome-edited variant protection blocks competitor replication in high-value metabolic pathway applications. |
| Molasses Supply Backward Integration | Upstream control over Brazilian sugarcane sourcing insulates yeast production from harvest-driven cost volatility. |
Methodological Framework
A spread of perspectives from culture house technical directors, dairy cooperative procurement managers, biopharmaceutical fermentation scientists, and regulatory affairs specialists converged on the working assumptions underlying strain demand projections. Primary fieldwork combined structured interviews with secondary validation through EFSA qualified health claim databases, FDA GRAS notification filings, and EU F-Gas Regulation compliance disclosures. Trade data from German, Chinese, and Brazilian customs authorities anchored supply-side calibration. Bottom-up strain volume estimates triangulated against top-down fermentation capacity assessments.
Demand-supply-balance dynamics across microorganism type, application category, physical form, and end-user concentration shaped the analytical framework over the projection horizon. Segmentation modeling captured lactic acid bacteria, yeast, mold, and probiotic culture splits intersecting with dairy, beverage, meat, and nutraceutical applications. CAGRs derived from facility investment pipelines, cooperative contract renewal patterns, and precision fermentation scale-up announcements. Molasses harvest forecasts and EFSA health claim approval velocity served as industry-specific sensitivity inputs.
Stress conditions across Brazilian sugarcane yield variance, FDA GRAS notification timeline extension, and EU F-Gas equipment replacement compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions about strain patent enforceability and clinical documentation capacity expansion that regulatory or technological shifts could revise. Cross-checking against biopharmaceutical CDMO capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Sofrito Market
Specialty Foods
Hot Pot Market
Specialty Foods
Moringa Products Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Global Hispanic Foods Market