
 Dairy Starter Culture Market | 2026-2036
Dairy Starter Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Starter Culture Market Analysis
The EU Green Deal Farm to Fork Strategy is pivoting dairy culture selection toward low-carbon fermentation protocols. Chr. Hansen leverages decades of strain-banking expertise to supply freeze-dried cultures that tolerate reduced-energy processing. DSM sustains competitive pressure through its integrated enzyme-culture portfolios for accelerated cheese ripening. Sacco anchors southern European supply chains with region-specific mesophilic blends tailored to Parmigiano-Reggiano and Pecorino traditions.
Dairy starter cultures comprise defined, propagated microbial strains—primarily lactic acid bacteria such as Lactococcus, Streptococcus, Lactobacillus, and Bifidobacterium—delivered in frozen, freeze-dried, or liquid-concentrate formats with titers exceeding 10^11 CFU per gram. These formulations acidify milk, develop texture, generate flavor compounds, and suppress spoilage organisms during controlled fermentation. Mesophilic cultures dominate European cheese-making volumes where temperatures below 40°C prevail, while thermophilic cultures capture accelerating share in industrial yogurt lines requiring 42-45°C incubation cycles. Probiotic cultures command premium positioning as dairy manufacturers reformulate for gut-health positioning in functional fermented milk.
EFSA novel food approvals and EMA-adjacent strain safety assessments govern which bacterial isolates enter EU dairy supply chains, while REACH compliance constrains cryoprotectant chemistries in culture stabilization. FDA GRAS notifications shape transatlantic export viability for European culture houses, and China's NMPA biotech ingredient registry creates separate qualification pathways for thermophilic concentrates. Stakeholders must monitor evolving strain-level traceability mandates as genome-edited starter variants approach regulatory thresholds across multiple jurisdictions.
Market Dynamics
The EU Green Deal Farm to Fork Strategy is forcing dairy processors to requalify starter cultures for reduced-methane fermentation protocols, redirecting procurement toward low-carbon strain portfolios and cryoprotectant chemistries that satisfy tightening REACH compliance thresholds.
Growth Catalysts
- EU Green Deal methane protocols:Dairy cooperatives across France and Italy are expanding defined-strain procurement to meet Farm to Fork sustainability benchmarks for fermented milk production.
- Thermophilic strain innovation:Industrial yogurt lines in Germany and the Netherlands are accelerating adoption of 42-45°C incubation cycles, concentrating demand for heat-tolerant Lactobacillus and Streptococcus concentrates.
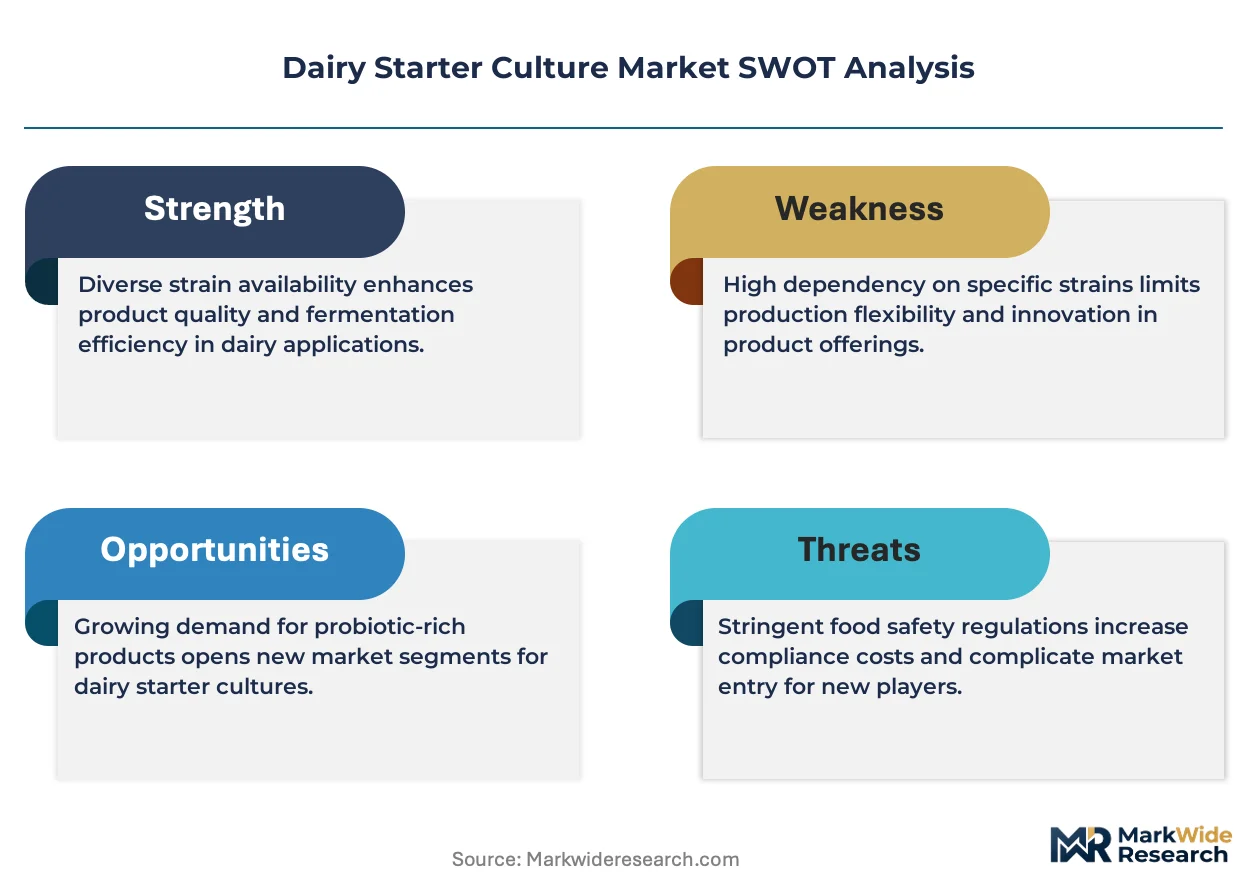
- Probiotic functional positioning:Gut-health reformulation in fermented milk categories is pulling Bifidobacterium and Lactobacillus strains into premium-tier dairy applications with elevated CFU titers.
Market Restraints
- Strain banking concentration:Defined culture collections remain concentrated among legacy European suppliers, creating single-source vulnerability for artisan cheese producers seeking region-specific mesophilic blends.
- EMA-adjacent safety assessment timelines:Strain-level novel food approvals through EFSA extend qualification cycles for genome-edited variants, compressing R&D amortization windows.
- Cryoprotectant chemistry constraints:REACH compliance limits glycerol and trehalose formulations in freeze-dried concentrates, elevating stabilization costs for culture houses serving export markets.
Strategic Opportunities
- China NMPA biotech registry pathway:Thermophilic concentrate suppliers can establish separate qualification tracks for industrial yogurt strains under China's national medical products administration framework.
- Enzyme-culture integration:Accelerated cheese ripening formulations combining proteolytic enzymes with defined starter blends offer white space in Italian hard-cheese segments.
- Direct-to-artisan distribution:Southern European Parmigiano-Reggiano and Pecorino producers are bypassing traditional dairy intermediaries through specialized culture procurement platforms.
Industry Challenges
- Genome-edited strain traceability:Regulatory thresholds for edited starter variants are approaching across multiple jurisdictions, forcing culture houses to rebuild documentation systems for strain lineage verification.
- Legacy equipment integration:Small-batch cheese producers in France and Italy face capex barriers when retrofitting vat systems for precision temperature control required by next-generation thermophilic protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Starter Culture Market |
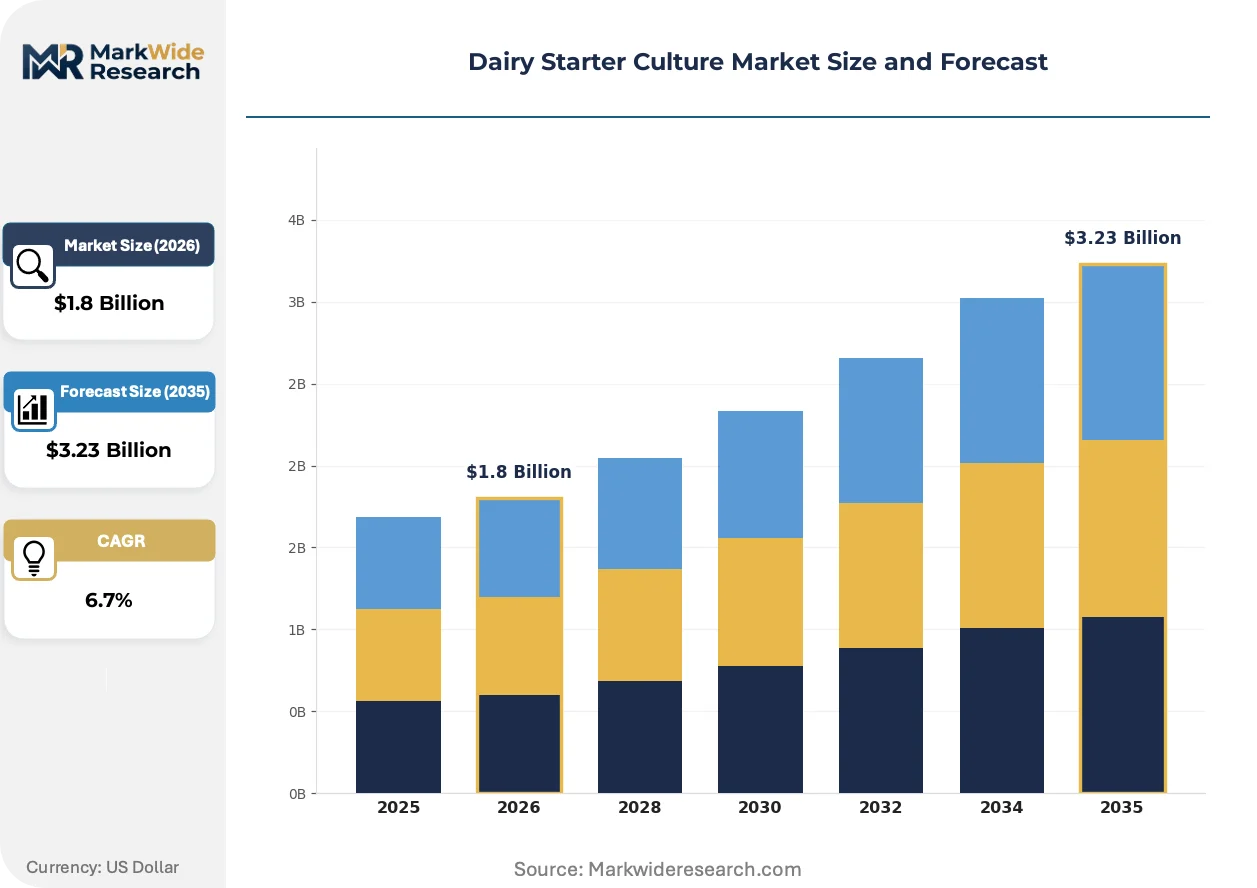
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesophilic Cultures, Thermophilic Cultures, Probiotic Cultures, Specialty Cultures Application: Yougurt Production, Cheese Making, Fermented Milk, Ice Cream Production End User: Dairy Manufacturers, Artisan Producers, Food Service Providers, Home Makers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Sacco, LB Bulgaricum, Chr. Hansen, THT, DuPont, DSM, CSK Food Enrichment, Lesaffre, Novonesis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Starter Culture Market Emerging Trajectories
Automation of culture propagation and quality verification is compressing batch-to-batch variability while regulatory frameworks on both sides of the Atlantic rewrite qualification protocols for novel strains.
High-throughput phenotyping platforms are automating strain selection for acidification kinetics and flavor compound generation. Industrial dairy processors in the Netherlands and Germany are deploying these systems at pilot scale. The technology is automating what previously required months of manual screening, collapsing development cycles for customized thermophilic blends.
REACH amendments targeting cryoprotectant chemistries are constraining formulation flexibility for freeze-dried concentrates. Culture stabilization houses must now requalify glycerol alternatives under tightened ECHA hazard classifications. European cheese-making segments dependent on long-shelf-life mesophilic blends face reformulation timelines that compress competitive windows.
Artisan producers are consolidating procurement through specialized culture platforms that bypass traditional dairy supply intermediaries. French and Italian traditional-cheese consortia now contract directly with strain banks for region-specific blends. This channel disintermediation concentrates volume with defined-culture specialists while fragmenting legacy distributor relationships across southern European supply chains.
Dairy Starter Culture Market Segmentation
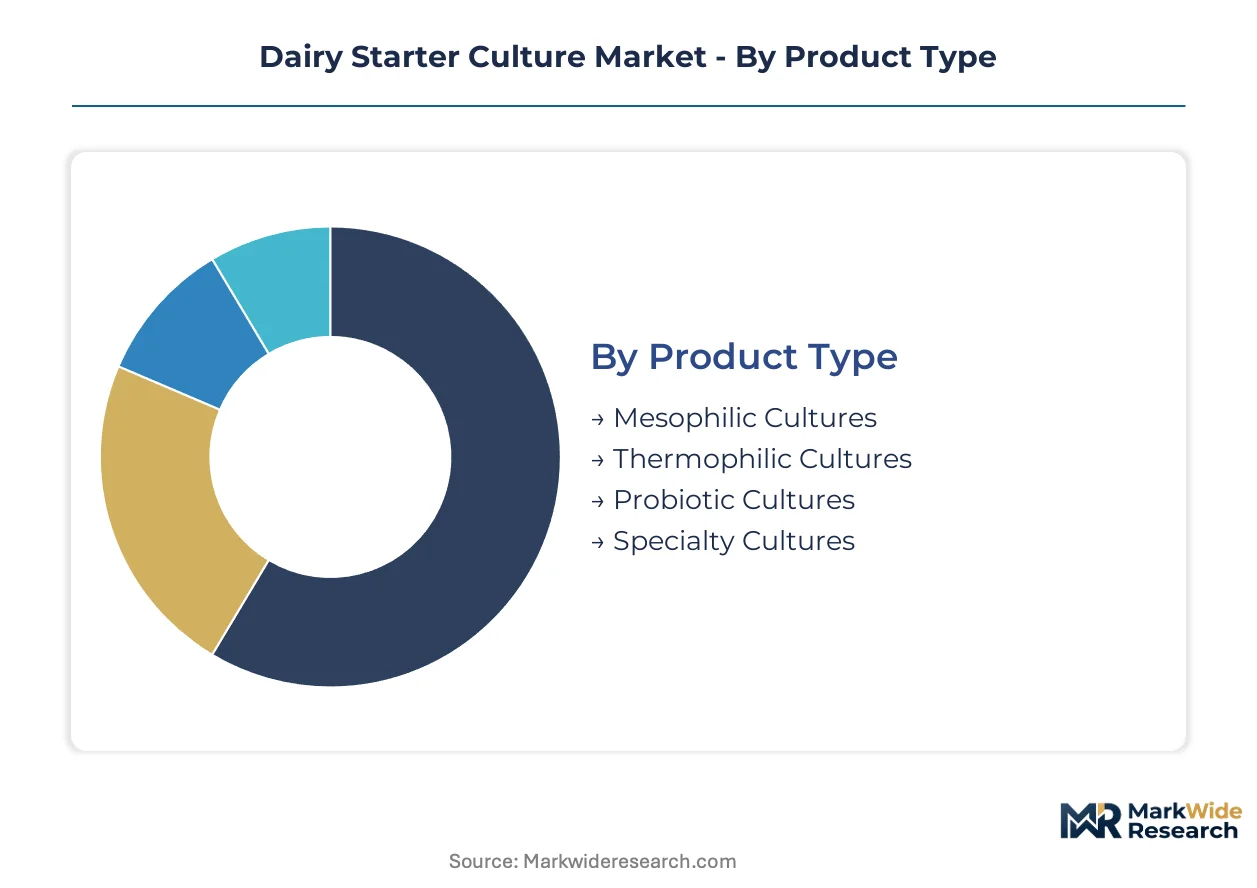
Segmentation in dairy starter cultures reveals how technical specifications, application requirements, and procurement channels create distinct competitive arenas. Manufacturers configure strain portfolios, stabilization formats, and service models differently across each dimension.
Product Type:
Integration depth varies sharply: mesophilic and thermophilic strains dominate embedded industrial systems, while probiotic and specialty cultures often ship as standalone ingredients requiring precise handling protocols.
- Mesophilic Cultures:Defined-strain blends of Lactococcus and Leuconostoc optimized for 20-35°C fermentation. French and Italian artisan cheese producers drive procurement volumes as EU Green Deal protocols favor low-temperature processing for energy efficiency.
- Thermophilic Cultures:Heat-tolerant Streptococcus thermophilus and Lactobacillus delbrueckii concentrates engineered for 42-45°C yogurt incubation. German and Dutch industrial dairy lines concentrate demand as high-throughput automation favors rapid acidification kinetics.
- Probiotic Cultures:Bifidobacterium and Lactobacillus strains with documented gut-health benefits, typically delivered at elevated CFU titers for functional fermented milk positioning.
- Specialty Cultures:Region-specific blends including adjunct cultures for flavor acceleration and surface-ripening bacteria for washed-rind cheese traditions.
Mesophilic cultures lead volumes today; probiotic cultures are gaining share fastest.
Application:
Cost tier differentiation separates commodity-scale industrial fermentation from premium artisan processes where strain specificity commands substantial price premiums.
- Yogurt Production:Thermophilic concentrates in frozen or freeze-dried formats for stirred and set yogurt lines. Industrial processors in the Netherlands prioritize rapid acidification strains that compress incubation cycles.
- Cheese Making:Mesophilic and thermophilic blends tailored to curd acidification, texture development, and proteolysis timelines. Italian hard-cheese consortia specify region-authorized strains for Parmigiano-Reggiano and Pecorino denominations.
- Fermented Milk:Functional positioning drives Bifidobacterium inclusion for gut-health claims in kefir and drinking yogurt segments.
- Ice Cream Production:Limited but growing use of fermentation-derived flavor compounds and texture modifiers in premium frozen dessert formulations.
Cheese making anchors revenue today; yogurt production shows steepest expansion trajectory.
End User:
Customer type determines service intensity: dairy manufacturers demand technical integration support, while artisan producers prioritize strain authenticity and direct strain-bank relationships.
- Dairy Manufacturers:Industrial-scale processors requiring standardized concentrates with batch-to-batch consistency guarantees and regulatory documentation packages for export markets.
- Artisan Producers:Small-batch cheese makers in France and Italy sourcing region-specific mesophilic blends through direct strain-bank contracts, bypassing traditional dairy intermediaries.
- Food Service Providers:Restaurants and catering operations using concentrated cultures for in-house fermented dairy preparation, typically through distributor channels.
- Home Makers:Hobbyist segment purchasing small-format freeze-dried cultures through online retail for domestic cheese and yogurt production.
Dairy manufacturers dominate procurement volumes; artisan producers are expanding most quickly through platform-based direct sourcing.
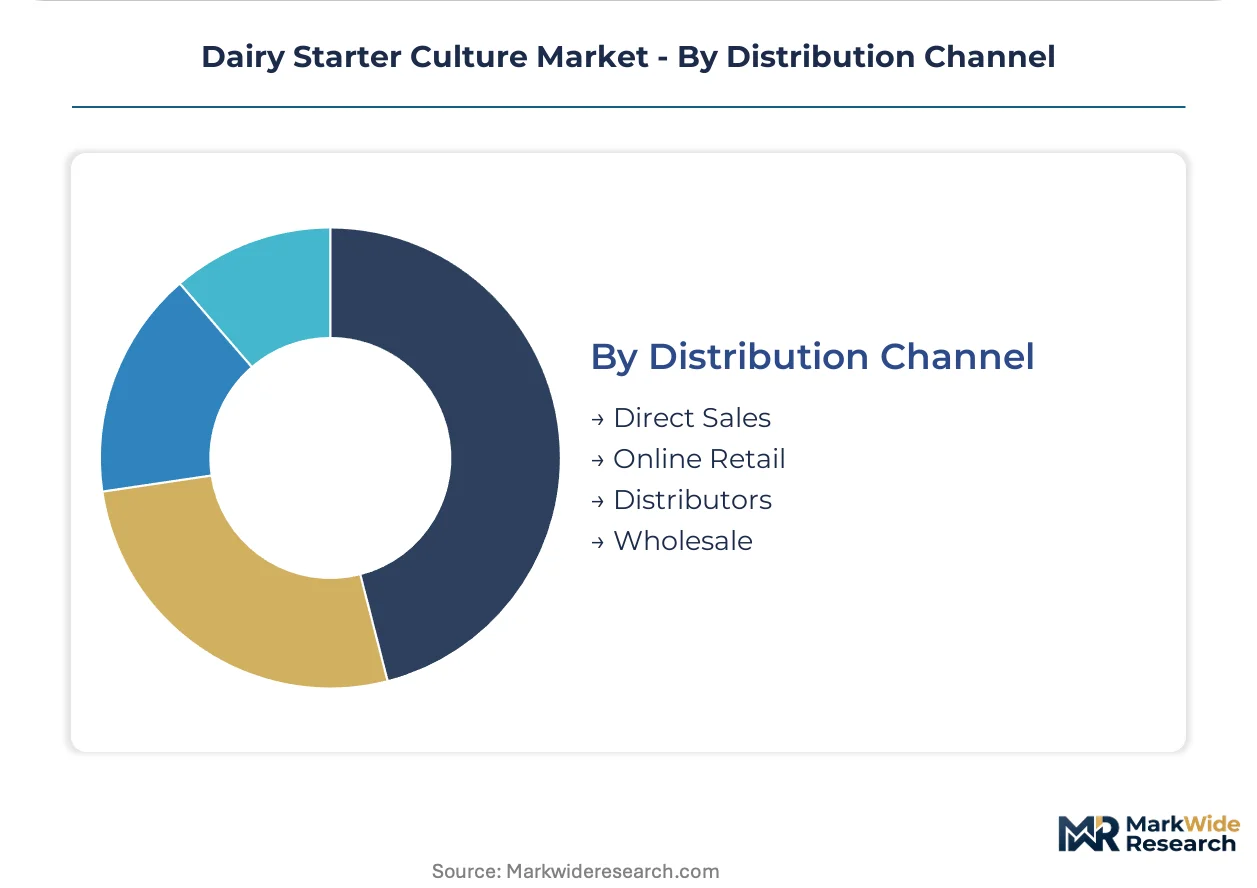
Distribution Channel:
Supply concentration shapes channel strategy: legacy strain banks maintain distributor networks for industrial accounts while building direct platforms for artisan relationships.
- Direct Sales:Strain-to-processor relationships for large dairy cooperatives with dedicated technical service agreements and customized blend development.
- Online Retail:E-commerce platforms serving artisan producers and home makers with small-batch freeze-dried cultures and rapid replenishment logistics.
- Distributors:Regional dairy supply intermediaries carrying frozen and freeze-dried concentrates for mid-scale processors with established procurement relationships.
- Wholesale:Volume-based supply arrangements for industrial yogurt and cheese operations with integrated cold-chain infrastructure.
Direct sales capture largest revenue share; online retail is climbing the fastest as artisan platforms consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dairy starter culture industry traces its modern origins to early twentieth-century Danish and French strain-banking institutions that systematized lactic acid bacteria preservation for industrial cheese-making. These foundational collections established the technical protocols and quality standards that continue to govern global culture supply chains.
France
Artisan cheese consortia in Auvergne-Rhône-Alpes and Normandy are expanding defined-strain procurement to meet EU Green Deal methane-reduction benchmarks for traditional raw-milk fermentation. ANSM oversees strain safety documentation for export-qualified cultures. Roquefort-sur-Soulzon maintains concentrated demand for Penicillium roqueforti adjunct cultures in protected-designation blue cheese production.
Germany
Industrial yogurt processors in Bavaria and Baden-Württemberg are accelerating thermophilic strain adoption for high-throughput 42-45°C incubation lines. The KBA-adjacent federal framework enforces REACH compliance for cryoprotectant chemistries in freeze-dried concentrates. Munich-area dairy cooperatives are deploying automated culture propagation systems to compress batch-to-batch variability.
Italy
Emilia-Romagna and Lombardy hard-cheese consortia specify region-authorized mesophilic blends for Parmigiano-Reggiano and Grana Padano denominations under EFSA novel food protocols. The Ministry of Health coordinates strain traceability mandates with EU Farm to Fork implementation. Parma's concentrated producer network is bypassing traditional intermediaries through direct strain-bank procurement platforms.
Netherlands
Friesland and North Brabant dairy manufacturers are concentrating demand for rapid-acidification thermophilic concentrates in automated stirred-yogurt lines. ECHA hazard classifications are constraining glycerol-based cryoprotectant formulations for export-bound freeze-dried products. Wageningen University's research cluster is piloting high-throughput phenotyping platforms for customized culture development.
United States
Wisconsin and California cheese producers are qualifying European-derived mesophilic strains under FDA GRAS notification pathways for artisan and industrial applications. The USDA coordinates with FDA on dual-jurisdiction oversight for fermented dairy ingredients. Madison-area technical service hubs are expanding to support precision temperature-control retrofitting for small-batch producers.
Dairy Starter Culture Market Vendor Landscape
Capital-heavy strain banks with decades of culture collection maintenance compete with asset-light formulation specialists that license propagated strains for regional stabilization and distribution. The supplier base concentrates among five to seven legacy European houses with proprietary defined-strain portfolios, while mid-scale regional blenders fragment the artisan-tier procurement channel. Two dominant archetypes emerge: integrated culture-enzyme houses with accelerated ripening portfolios, and pure-play strain banks emphasizing region-specific mesophilic authenticity. Competitive moves center on direct-to-artisan platform development and enzyme-culture integration for hard-cheese segments.
Within the integrated culture-enzyme tier, Chr. Hansen and DSM exemplify divergent strategic positioning. The Danish entity anchors its competitive stance on century-old strain-banking depth and freeze-dried stabilization expertise for reduced-energy processing protocols. The Dutch multinational occupies a position emphasizing enzyme-culture combination portfolios for compressed cheese ripening timelines. Sacco, the Italian cooperative, represents the geography-anchored archetype with southern European supply chain concentration in Parmigiano-Reggiano and Pecorino traditions. These three entities collectively illustrate how heritage strain collections, regulatory qualification breadth, and regional authentication credentials structure competitive differentiation in a market where EFSA and FDA approval timelines create substantial barriers to new entrant expansion.
| Leading Market Players |
|---|
| Sacco |
| LB Bulgaricum |
| Chr. Hansen |
| THT |
| DuPont |
| DSM |
| CSK Food Enrichment |
| Lesaffre |
| Novonesis |
| Others |
Supply Flow & Price Mechanics
Freeze-dried premium-grade concentrates diverge sharply from liquid bulk formats on both unit economics and fulfillment architecture. Chr. Hansen and DSM command substantial markups for defined-strain portfolios with EFSA novel food dossiers, while commodity mesophilic blends trade through distributor networks on volume-based contracts. REACH compliance costs for glycerol-alternative cryoprotectants compress margins at the standard tier, forcing stabilization houses to segment service levels by documentation intensity.
Pricing Analysis
Contract-based long-term offtake dominates industrial dairy procurement, with pricing stratifying across premium, standard, and economy tiers based on strain pedigree and regulatory documentation depth. Certification grade—specifically EFSA-qualified versus provisional-status strains—commands the widest price spreads. Cost compression in standard-tier freeze-dried concentrates is intensifying because REACH amendments force reformulation of cryoprotectant chemistries. Artisan cheese consortia exhibit lowest price sensitivity, prioritizing region-specific authenticity over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from French and Italian dairy cooperatives mandate qualified secondary suppliers for all defined-strain categories, preventing single-source concentration despite Chr. Hansen's historical dominance. Production gravity centers on Denmark, the Netherlands, and northern Italy, with raw material dependencies spanning lactose substrates, cryoprotectant chemistries, and specialized fermentation vessels. Single-source vulnerability persists in genome-edited strain lineages awaiting EFSA approval. Distribution runs through direct technical-service relationships for industrial accounts, supplemented by specialized platforms for artisan direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dairy starter culture market represents a late-cycle quality story as EU Green Deal protocols force processors toward low-carbon fermentation specifications with documented strain traceability. Premium-tier positioning now hinges on EFSA qualification breadth and direct artisan relationships rather than commodity volume.
For Market Incumbents: Lock in artisan cheese consortia through exclusive strain-bank partnerships before regional competitors replicate Sacco's Parmigiano-Reggiano platform model. Prioritize backward integration into cryoprotectant chemistry production to defend margin position against REACH-driven input cost volatility. Genome-edited strain pipelines face extended EFSA timelines, threatening R&D amortization windows. For New Entrants and Emerging Players: Begin with thermophilic concentrate supply for mid-scale German yogurt processors seeking alternatives to legacy Danish suppliers. The China NMPA biotech registry pathway offers the most penetrable regulatory entry point for heat-tolerant Lactobacillus concentrates. A technical service-heavy go-to-market model compensates for absence of century-old strain collections. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light formulation specialists licensing propagated strains for regional stabilization and distribution. Five-to-ten-year viability favors entities with demonstrated EFSA novel food approval velocity rather than commodity bulk suppliers. Watch for inflection in direct-to-artisan procurement platform consolidation across southern European cheese consortia.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Accelerates strain qualification timelines for genome-edited variants entering EU dairy supply chains. |
| Cryoprotectant Chemistry Backward Integration | Secures supply of REACH-compliant glycerol alternatives for freeze-dried concentrate stabilization. |
| Direct-to-Artisan Platform Development | Bypasses legacy distributor relationships with French and Italian cheese consortia seeking authenticated strains. |
| China NMPA Biotech Registry Qualification | Opens separate approval pathway for thermophilic concentrates in industrial yogurt segments. |
| Enzyme-Culture Combination Portfolio | Captures accelerated ripening demand from Italian hard-cheese producers compressing aging timelines. |
Methodological Framework
Coverage spans Europe, North America, and Asia-Pacific, with primary inputs from each region's dairy processing clusters. The analysis combines structured interviews with strain-bank technical directors, dairy cooperative procurement leads, and EFSA regulatory affairs specialists with secondary validation from EMA-adjacent safety assessment filings, REACH amendment documentation, and customs trade data for cryoprotectant chemical flows. Bottom-up strain-level demand estimates triangulate against top-down dairy fermentation capacity projections.
Rate-of-change decomposition separates volume expansion from value migration across the analysis window. Segmentation dimensions modeled include product type, application, end-user archetype, and distribution channel, with additional granularity on regulatory qualification status. CAGRs derive from fitted growth curves anchored to documented strain adoption patterns and dairy processor capex disclosures. Industry-specific inputs incorporate EU Green Deal implementation timelines and NMPA biotech registry processing velocities.
Several conditions sit outside the modeled scope, including potential genome-editing regulatory reclassifications and unannounced REACH amendments targeting additional cryoprotectant chemistries. Forecasts reflect assumptions about EFSA approval continuity and sustained artisan cheese demand for region-specific mesophilic blends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Food Preservatives Market