
 Food Grade Acetic Acid Market | 2026-2036
Food Grade Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Acetic Acid Market Analysis
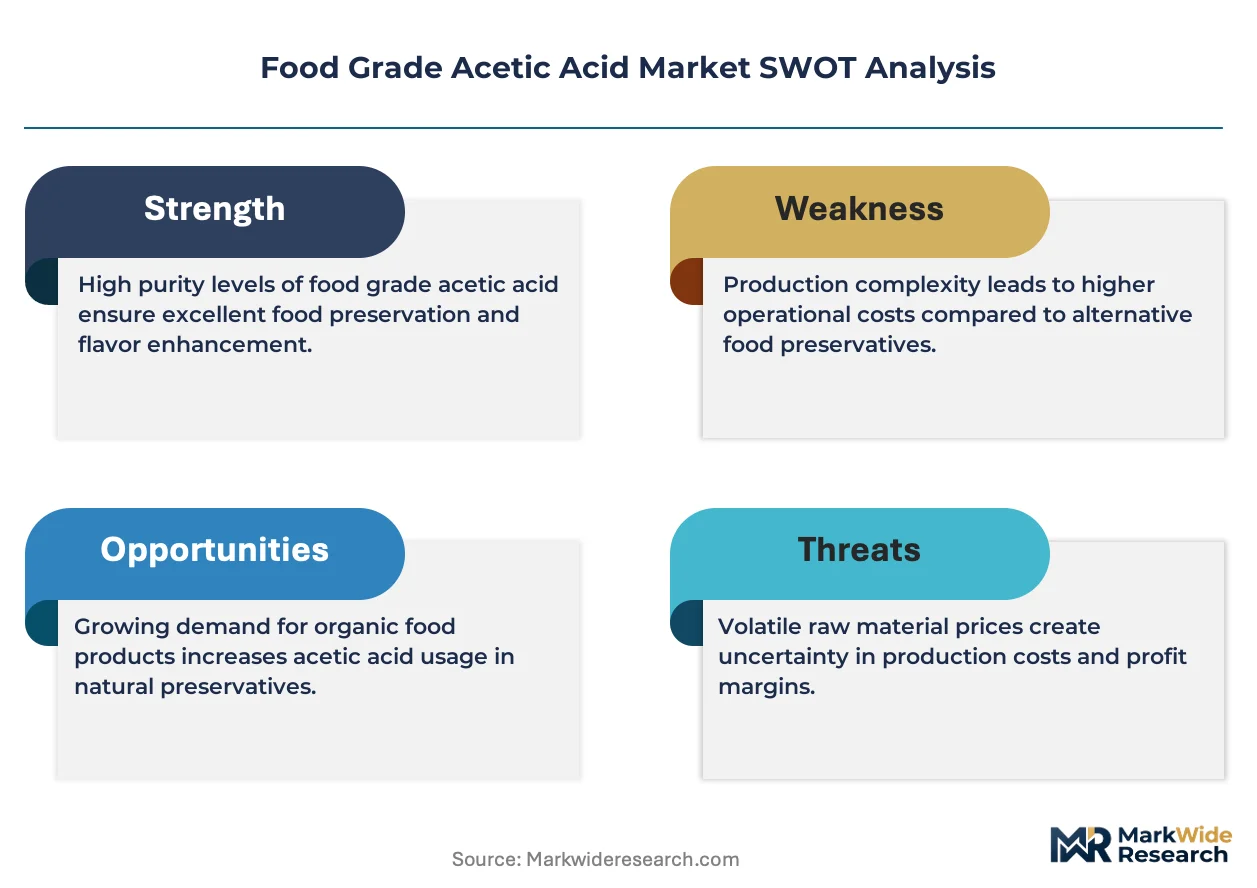
FSSC 22000 certification is reorganizing competitive access in food-grade acetic acid supply, filtering out uncertified bulk producers from branded food manufacturer contracts. Celanese Corporation leverages its integrated methanol-to-acetic acid chain to sustain cost leadership across North American food preservative accounts. Mitsubishi Chemical Corporation anchors Asian supply reliability through dedicated fermentation-derived product lines. BASF SE differentiates via pharmaceutical-grade crossover capabilities that meet dual-use purity thresholds.
Food grade acetic acid denotes a purified form of ethanoic acid meeting food safety purity specifications, typically manufactured through bacterial fermentation of ethanol or carbonylation of methanol, with maximum permissible heavy metal and non-volatile residue limits enforced under codex standards. Its primary commercial purpose centers on pH modulation, microbial inhibition, and flavor development across processed food systems. The application dimension shows food preservation commanding volume leadership due to extended shelf-life demands from packaged goods manufacturers, while vinegar production captures premium margin pools through artisanal and aged-product positioning. Within end users, beverage producers represent the fastest-expanding consumption cluster as functional drinks and kombucha formulations proliferate.
FDA food additive regulations and EPA manufacturing discharge permits govern US production and import eligibility, while REACH registration and EFSA purity evaluations shape European market access conditions. These frameworks elevate compliance costs for smaller fermentation operators and redirect procurement toward certified multi-jurisdictional suppliers. Stakeholders must monitor evolving maximum residue limit harmonization between CODEX Alimentarius and national food safety agencies to anticipate reformulation requirements and qualification timeline shifts.
Market Dynamics
REACH compliance and evolving EU purity standards are tightening supplier qualification requirements, filtering uncertified bulk producers from branded food manufacturer contracts and concentrating procurement toward multi-jurisdictional certified suppliers.
Growth Catalysts
- Clean-label preservation demand:Packaged goods manufacturers across Asia-Pacific are expanding acetic acid procurement to replace synthetic preservatives in sauces, dressings, and ready-to-eat meals.
- FSSC 22000 certification penetration:Food safety management system mandates from major retailers are disqualifying uncertified fermentation operators from tender participation.
- Kombucha and functional beverage proliferation:Beverage producers in North America and Western Europe are scaling vinegar-base formulations, driving fermentation-grade acetic acid offtake.
Market Restraints
- Methanol feedstock volatility:Carbonylation route producers face margin compression from petrochemical input price swings tied to natural gas and crude benchmarks.
- China supply concentration:Domestic vinegar producers scaling fermentation capacity create export market dependency on a single geography for volume availability.
- Non-volatile residue limits:CODEX Alimentarius purity thresholds for heavy metals and sulfates impose capital-intensive purification upgrades on smaller operators.
Strategic Opportunities
- India food processing expansion:FSSAI modernization and PLI scheme incentives for processed food clusters create qualified supply gaps for fermentation-derived acid.
- Pharmaceutical-grade crossover:Dual-use purity capabilities open adjacent revenue streams in parenteral and excipient applications with higher margin profiles.
- Direct-to-brewery distribution:Kombucha craft producers are bypassing traditional chemical distributors, creating channel innovation for drum-to-tanker bulk supply.
Industry Challenges
- Fermentation microbiologist scarcity:Qualified strain management and contamination control expertise commands premium compensation, constraining smaller facility expansions.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and FSSC 22000 qualification cycles extend customer onboarding to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Acetic Acid Market |
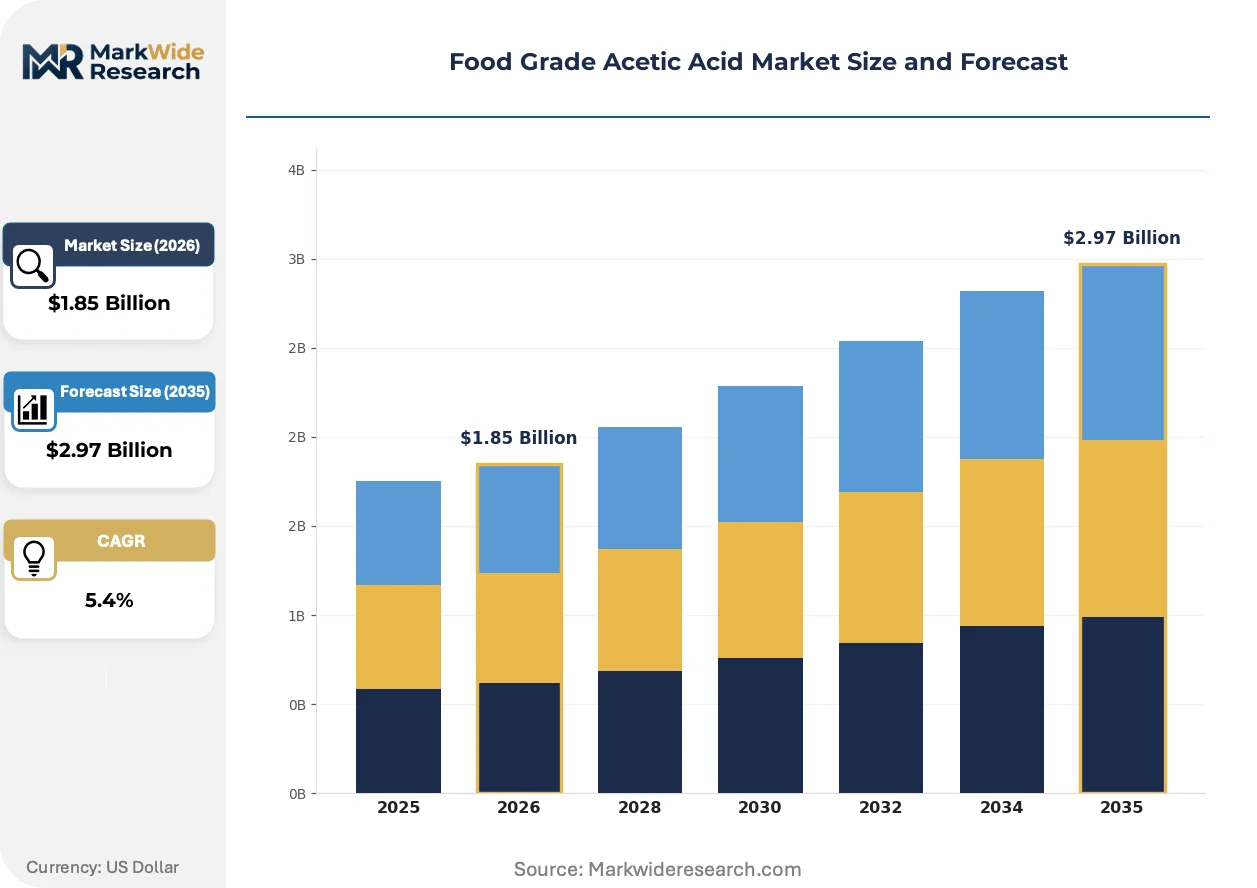
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Industrial Grade, Food Grade, Pharmaceutical Grade Application: Food Preservation, Flavoring Agent, Vinegar Production, Pickling End User: Food Manufacturers, Beverage Producers, Home Cooks, Catering Services Distribution Channel: Online Retailers, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Mitsubishi Chemical Corporation, Perstorp, Celanese Corporation, Saudi International Petrochemicals, Wacker Chemie, Eastman Chemical Company, Daicel Corporation, Sumitomo Chemical, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Acetic Acid Market Emerging Trajectories
Fermentation technology advances and regulatory harmonization pressures are actively reshaping competitive positioning, forcing capital deployment toward integrated purity control and traceability systems.
Membrane filtration and continuous fermentation systems are fragmenting the traditional batch-production economics that dominated acetic acid manufacturing for decades. Mid-scale vinegar producers in Germany and Italy are adopting these systems to achieve pharmaceutical-grade purity without carbonylation infrastructure. The technology is fragmenting volume leadership away from petrochemical-integrated majors toward specialized fermentation operators with captive ethanol supply.
REACH registration renewal deadlines and EFSA purity evaluations are compressing qualification timelines for European market access. Manufacturers must submit updated dossiers demonstrating compliance with evolving heavy metal thresholds and non-volatile residue specifications. Food preservative applications face the steepest compliance burden, redirecting procurement toward suppliers with established multi-jurisdictional certification.
Certification-driven preference shifts are restructuring buyer-supplier relationships across North American and European accounts. Branded food manufacturers are consolidating vendor panels to suppliers holding simultaneous FSSC 22000, BRC, and IFS certifications, disqualifying single-standard operators. Kombucha and functional beverage producers in California and Bavaria represent the most aggressive adopters, embedding certification requirements directly into procurement specifications.
Food Grade Acetic Acid Market Segmentation
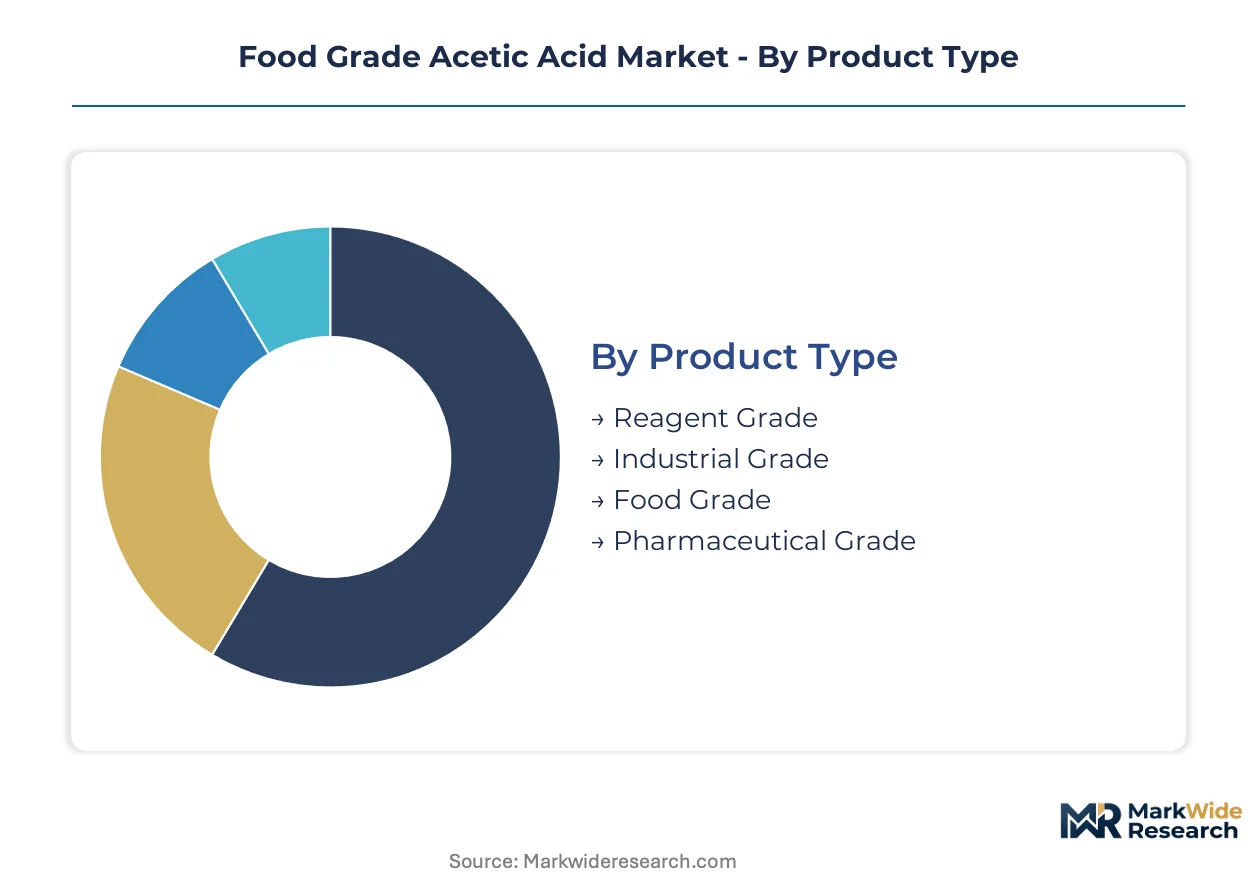
Food grade acetic acid procurement decisions hinge on purity thresholds, application intensity, and certification requirements that vary sharply across downstream use cases. Segmentation reveals how regulatory stringency and end-use specifications fragment supplier qualification pathways.
Product Type:
REACH registration tiers and CODEX Alimentarius specifications create distinct compliance cost structures across purity grades.
- Food Grade:Meets EFSA and FDA additive specifications with maximum heavy metal limits enforced under FSSC 22000 protocols. Demand concentrates among sauce manufacturers in Italy and Germany seeking clean-label preservation credentials without synthetic alternatives.
- Pharmaceutical Grade:Satisfies USP and EP monographs with endotoxin and sterility controls enabling parenteral applications. Japanese pharmaceutical excipient producers represent the steepest expansion trajectory as biologics formulation demand intensifies.
- Reagent Grade:Laboratory analytical specifications with ACS certification requirements.
- Industrial Grade:Technical specifications excluding food contact applications; governed by OSHA exposure limits.
Established volume favors Food Grade; emerging adoption favors Pharmaceutical Grade.
Application:
Processing intensity and microbial load tolerance determine acetic acid concentration requirements across food systems.
- Food Preservation:pH reduction below 4.6 inhibits Clostridium botulinum and Listeria monocytogenes in shelf-stable sauces and dressings. Packaged goods manufacturers in California and Bavaria are expanding procurement for clean-label reformulations displacing benzoate and sorbate systems.
- Vinegar Production:Fermentation-derived acid aged in wood casks commands premium positioning in artisanal balsamic and kombucha categories. Italian and French protected designation of origin producers capture margin pools through terroir-linked supply chains.
- Flavoring Agent:Precise acidity modulation in condiments and marinades.
- Pickling:Vegetable preservation with specific acid-to-salt ratios for texture retention.
Volume leadership sits with Food Preservation; margin expansion concentrates in Vinegar Production.
End User:
Scale economies and formulation expertise separate commercial procurement from household consumption patterns.
- Beverage Producers:Kombucha and functional drink manufacturers require fermentation-grade acid with specific organic acid profiles for SCOBY health. North American craft breweries in Oregon and Colorado are scaling direct tanker deliveries to bypass distributor markups.
- Food Manufacturers:Industrial sauce, dressing, and ready-meal producers with FSSC 22000-mandated supplier panels. German and Dutch co-manufacturers are consolidating vendor bases to triple-certified operators holding simultaneous BRC and IFS credentials.
- Catering Services:Institutional volume procurement with basic food safety compliance.
- Home Cooks:Retail bottle formats governed by consumer labeling regulations.
Procurement sophistication peaks with Beverage Producers; contract stability favors Food Manufacturers.
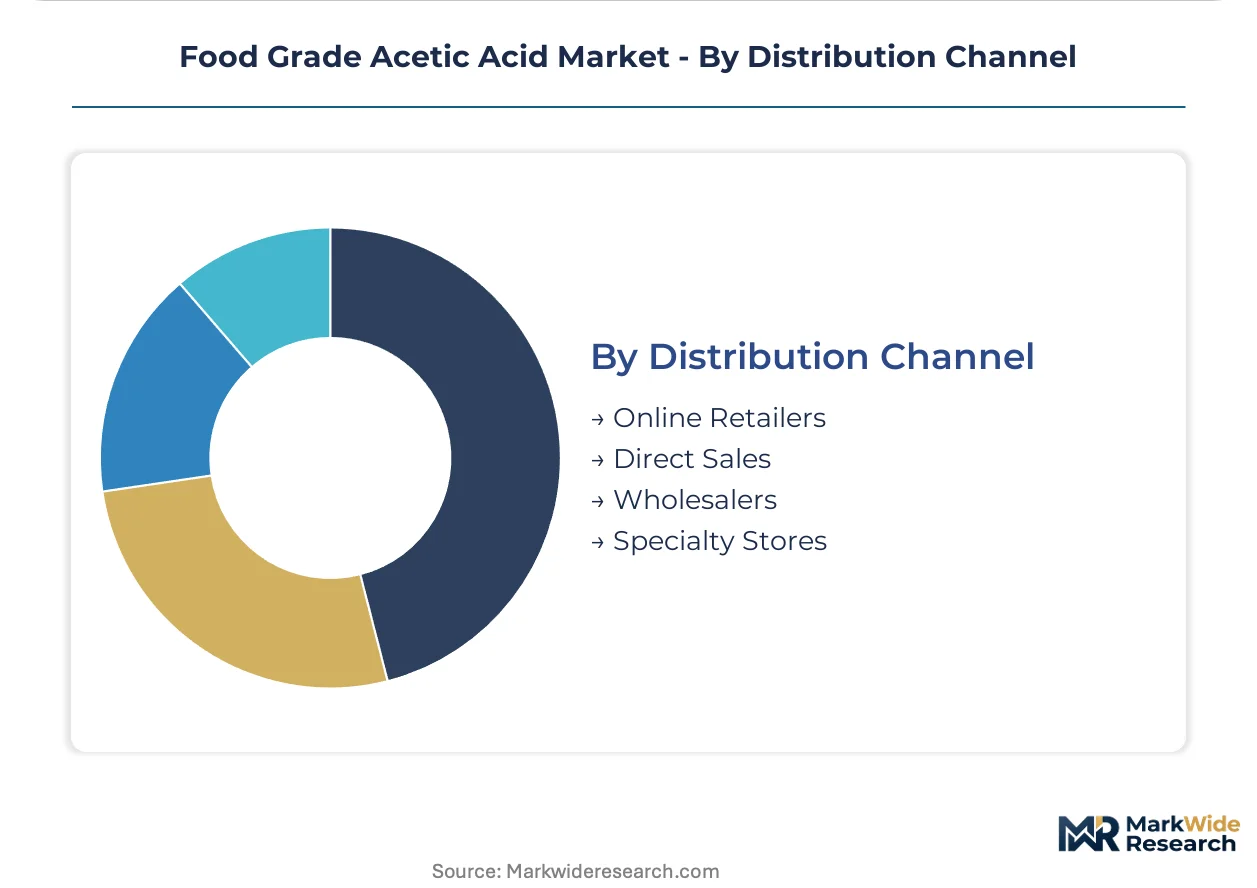
Distribution Channel:
Batch traceability requirements and volume scale determine channel economics for different customer tiers.
- Direct Sales:Bulk tanker and drum deliveries with lot-specific COAs and chain-of-custody documentation. Large-scale vinegar producers in China's Shanxi province leverage direct relationships with Japanese and Korean importers to circumvent trader margins.
- Wholesalers:Intermediate volume consolidation serving regional food processors with mixed chemical procurement needs.
- Online Retailers:Certified organic and non-GMO specialty grades for craft producers and small-batch formulators.
- Specialty Stores:Artisanal vinegar and home fermentation supply channels with premium positioning.
Channel control concentrates in Direct Sales; accessibility expansion favors Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives and FSSAI modernization are redirecting fermentation capacity toward India. REACH renewal deadlines and EFSA purity evaluations compress European supplier qualification timelines. China's domestic vinegar producers now anchor regional export availability.
China
Shanxi province vinegar producers are scaling fermentation capacity to serve Japanese and Korean import demand. SAMR food additive registrations and GB standards enforcement tighten heavy metal thresholds for cross-border shipments. Zhenjiang and Shanxi industrial clusters concentrate wood-cask aging infrastructure for premium balsamic and kombucha acid grades.
United States
FDA food additive regulations and EPA discharge permits govern production eligibility for North American preservative applications. Oregon and Colorado craft kombucha breweries are scaling direct tanker deliveries to bypass traditional distributor markups. California packaged goods manufacturers lead clean-label reformulations displacing benzoate systems with acetic acid preservation.
Germany
EFSA purity evaluations and REACH registration tiers elevate compliance costs for fermentation operators serving sauce and dressing manufacturers. Bavaria and Baden-Württemberg co-manufacturers are consolidating vendor panels to triple-certified suppliers holding simultaneous FSSC 22000, BRC, and IFS credentials. Membrane filtration adoption in Italian and German mid-scale plants achieves pharmaceutical-grade purity without carbonylation infrastructure.
India
FSSAI modernization and PLI scheme incentives for processed food clusters create qualified supply gaps for fermentation-derived acid. Maharashtra and Gujarat food processing hubs are expanding acetic acid procurement for clean-label sauce and ready-meal preservation. Domestic fermentation operators face capital-intensive purification upgrades to meet CODEX Alimentarius non-volatile residue limits.
Japan
PMDA pharmaceutical-grade specifications and METI industrial standards shape dual-use purity requirements for excipient applications. Pharmaceutical excipient producers in the Kanto and Kansai regions represent the steepest expansion trajectory as biologics formulation demand intensifies. Japanese buyers leverage direct relationships with Shanxi vinegar producers to circumvent trader margins on fermentation-grade acid.
Food Grade Acetic Acid Market Vendor Landscape
Listed leaders compete with private specialists across certification and purity tiers, creating a bifurcated supply structure. The vendor base separates between petrochemical-integrated majors with carbonylation infrastructure and specialized fermentation operators with captive ethanol supply. Three archetypes dominate: multi-jurisdictional certified suppliers, pharmaceutical-grade crossover players, and regional fermentation specialists. Competitive moves concentrate on simultaneous FSSC 22000/BRC/IFS qualification attainment and membrane filtration technology licensing.
Within the multi-jurisdictional certified tier, Celanese Corporation and Mitsubishi Chemical Corporation exemplify divergent strategic positioning. Celanese leverages integrated methanol-to-acetic acid chain economics to sustain cost leadership across North American food preservative accounts. Mitsubishi anchors Asian supply reliability through dedicated fermentation-derived product lines serving Japanese and Korean export markets. BASF SE occupies a position in the pharmaceutical-grade crossover archetype, with dual-use purity capabilities meeting USP and EP monograph thresholds for parenteral applications.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Perstorp |
| Celanese Corporation |
| Saudi International Petrochemicals |
| Wacker Chemie |
| Eastman Chemical Company |
| Daicel Corporation |
| Sumitomo Chemical |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
FSSC 22000 certification gates both supplier qualification and price differentiation simultaneously, filtering uncertified fermentation operators from branded food manufacturer contracts while concentrating procurement premiums on triple-certified operators. Food preservative applications face the steepest compliance burden, redirecting volume toward multi-jurisdictional suppliers commanding 15-20% premia over single-standard competitors.
Pricing Analysis
Certification level creates the primary spread between food-grade, pharmaceutical-grade, and industrial-grade tiers. Three-tier pricing structure across premium, standard, and economy levels tracks purity thresholds and CODEX Alimentarius compliance depth. Cost compression in fermentation-derived grades is intensifying because methanol feedstock volatility squeezes carbonylation route margins. Beverage producers exhibit highest price sensitivity due to direct tanker procurement bypassing distributor markups, while pharmaceutical excipient buyers absorb premia for USP and EP monograph compliance.
Supply Chain Analysis
Strategic stockpiling dominates inventory strategy among Japanese and Korean importers buffering against Shanxi province supply concentration. Raw material flows draw from methanol carbonylation in North America and ethanol fermentation in China, Italy, and Germany. Single-source vulnerability concentrates in Shanxi wood-cask aging infrastructure for premium balsamic and kombucha grades. Distribution runs through direct tanker and drum deliveries with lot-specific COAs, supplemented by online retailers serving craft producers seeking certified organic and non-GMO specialty grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service layers expand faster than bulk acid production, creating recurring revenue pools in FSSC 22000 audit preparation, REACH dossier maintenance, and chain-of-custody documentation systems.
For Market Incumbents: Secure triple-certification moats by accelerating simultaneous FSSC 22000, BRC, and IFS attainment ahead of retailer mandate expansion. Membrane filtration technology licensing anchors pharmaceutical-grade crossover capabilities against emerging Italian and German mid-scale fermentation specialists. Backward integration into captive ethanol supply defends margin position from petrochemical input volatility. For New Entrants and Emerging Players: FSSC 22000 fast-track programs unlock procurement participation in German and Dutch co-manufacturer panels disqualifying uncertified operators. White-space concentrates in India's Maharashtra and Gujarat food processing hubs where PLI scheme incentives outpace qualified domestic fermentation capacity. Direct-to-brewery distribution bypasses entrenched chemical distributor relationships in Oregon and Colorado kombucha clusters. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical majors with undermonetized food-grade fermentation assets lacking pharmaceutical-grade crossover infrastructure. Five-to-ten year viability hinges on membrane filtration adoption curves displacing traditional batch economics. Watch for REACH registration renewal deadline clustering as inflection indicator compressing European supplier qualification timelines and triggering consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Licensing | Enables pharmaceutical-grade purity without carbonylation infrastructure investment. |
| Triple Certification Attainment | Unlocks retailer-mandated supplier panels in Germany and North America. |
| Captive Ethanol Supply Integration | Insulates fermentation economics from commodity feedstock volatility. |
| Direct-to-Brewery Distribution | Bypasses distributor markups in Oregon and Colorado kombucha markets. |
| Pharmaceutical-Grade Crossover | Opens USP and EP monograph revenue streams in Japanese excipient markets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SAMR additive registrations, EFSA purity evaluations, and customs trade data. Plant managers at Shanxi fermentation facilities, procurement leads at German sauce manufacturers, and technical R&D directors at membrane filtration equipment suppliers provided operational validation. SEC 10-K filings, Cefic sector reports, and CODEX Alimentarius threshold documentation supplied secondary triangulation. Bottom-up capacity assessments and top-down demand modeling converged on segment-level outputs.
Segmentation dimensions modeled include purity grade tier, end-use application intensity, certification protocol, and regional production hub concentration across the analysis window. CAGRs derive from installed fermentation capacity trajectories, REACH registration renewal schedules, and kombucha formulation proliferation patterns. Methanol price elasticity coefficients and FSSC 22000 penetration curves inform volume projections.
Decision-makers should treat outputs as directional under stable regulatory harmonization between CODEX Alimentarius and national food safety agencies; material deviation would warrant model refresh. Revision becomes warranted when China export permit volatility or EFSA heavy metal threshold tightening crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Global Food Texturants Market
Food Additives and Ingredients
South America Food Additives Market