
 North America Food Anti Caking Agents Market | 2026-2036
North America Food Anti Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Anti Caking Agents Market Analytics
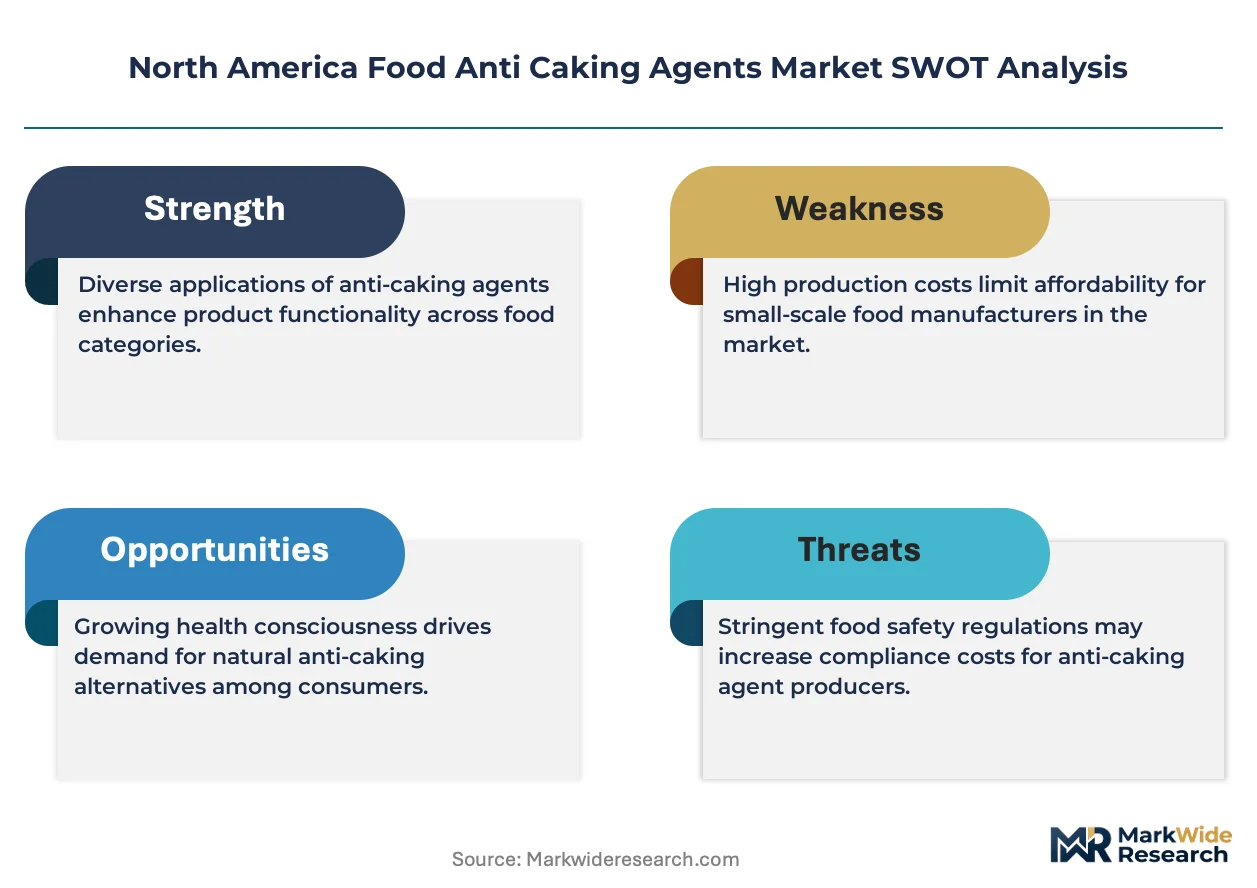
Buyer concentration among large-scale food producers is hardening across the North American supply base. Evonik Industries AG leverages its silicate technology portfolio to serve multinational seasoning houses with customized particle engineering. Solvay anchors phosphate-grade supply relationships with dairy processors seeking calcium phosphate alternatives for cheese powder applications. Huber Engineered Materials specializes in precipitated silica formulations that compete on moisture absorption performance in high-humidity Mexican snack production facilities.
Food anti-caking agents comprise inorganic and organic compounds—primarily silicates, phosphates, and calcium salts—engineered to maintain particulate flowability by absorbing surface moisture and reducing interparticle friction through particle-size distribution control. These additives prevent clumping in hygroscopic food powders during storage, transport, and automated dispensing operations. Silicates command the largest volume share due to their cost efficiency in salt and seasoning applications, while phosphates capture premium positioning in dairy powders where calcium compatibility matters. Calcium compounds are gaining formulation share in baking mixes as producers seek mineral-fortified clean-label positioning. Powder form dominates current shipments, though granule variants are penetrating high-throughput seasoning lines where dust control determines line efficiency.
The FDA's GRAS self-affirmation process and the USDA's organic certification standards shape product development timelines and ingredient disclosure requirements for suppliers targeting North American food manufacturers. Health Canada's Food and Drug Regulations impose additional purity specifications on imports entering Canadian dairy and confectionery channels. Stakeholders must monitor evolving state-level labeling initiatives in California and New York that extend beyond federal disclosure minimums.
Market Dynamics
Clean-label procurement mandates from U.S. retail grocery chains are compressing supplier qualification timelines and forcing reformulation of legacy silicate-based anti-caking systems across seasoning and dairy powder applications.
Growth Catalysts
- GRAS Self-Affirmation Pathway:The FDA's streamlined notification process accelerates new ingredient commercialization, enabling faster market entry for novel calcium-based alternatives in cheese powder formulations.
- Mexican Snack Manufacturing Expansion:Humidity-driven powder flowability requirements in Guadalajara and Monterrey seasoning facilities are pulling silicate and phosphate procurement volumes northward from traditional U.S. supply points.
- Automated Dispensing Infrastructure:High-throughput seasoning lines in California's Central Valley are specifying granule-form anti-caking agents to reduce dust contamination and improve line efficiency metrics.
Market Restraints
- Silicate Raw Material Concentration:Precipitated silica feedstock supply concentrates among a handful of Gulf Coast chemical processors, exposing seasoning manufacturers to hurricane-season disruption risk.
- Phosphate Cost Volatility:Fluctuating sulfuric acid and phosphate rock input costs compress margin stability for dairy powder applications dependent on calcium phosphate systems.
- Clean-Label Substitution Pressure:Consumer-facing brands are reformulating away from synthetic silicates toward rice hull ash and other plant-derived alternatives with inferior moisture absorption performance.
Strategic Opportunities
- Canadian Dairy Export Channel:Health Canada's purity specifications for confectionery and dairy imports create a qualification moat for suppliers meeting dual FDA-Health Canada standards, locking out marginal competitors.
- Mineral-Fortified Baking Mixes:Calcium carbonate anti-caking systems are penetrating clean-label baking applications where mineral content doubles as a nutritional marketing claim.
- State-Level Labeling Preemption:California's Proposition 65 enforcement trends and New York's emerging disclosure requirements are creating first-mover advantage for suppliers with preemptive toxicology documentation.
Industry Challenges
- Particle Engineering Talent Scarcity:Formulation chemists with expertise in controlled particle-size distribution for humidity-stable powders command premium compensation and limited availability across the Great Lakes dairy corridor.
- Dual-Certification Timeline Compression:USDA organic certification叠加 FDA GRAS documentation extends product development cycles by 14-18 months, straining R&D resource allocation for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Anti Caking Agents Market |
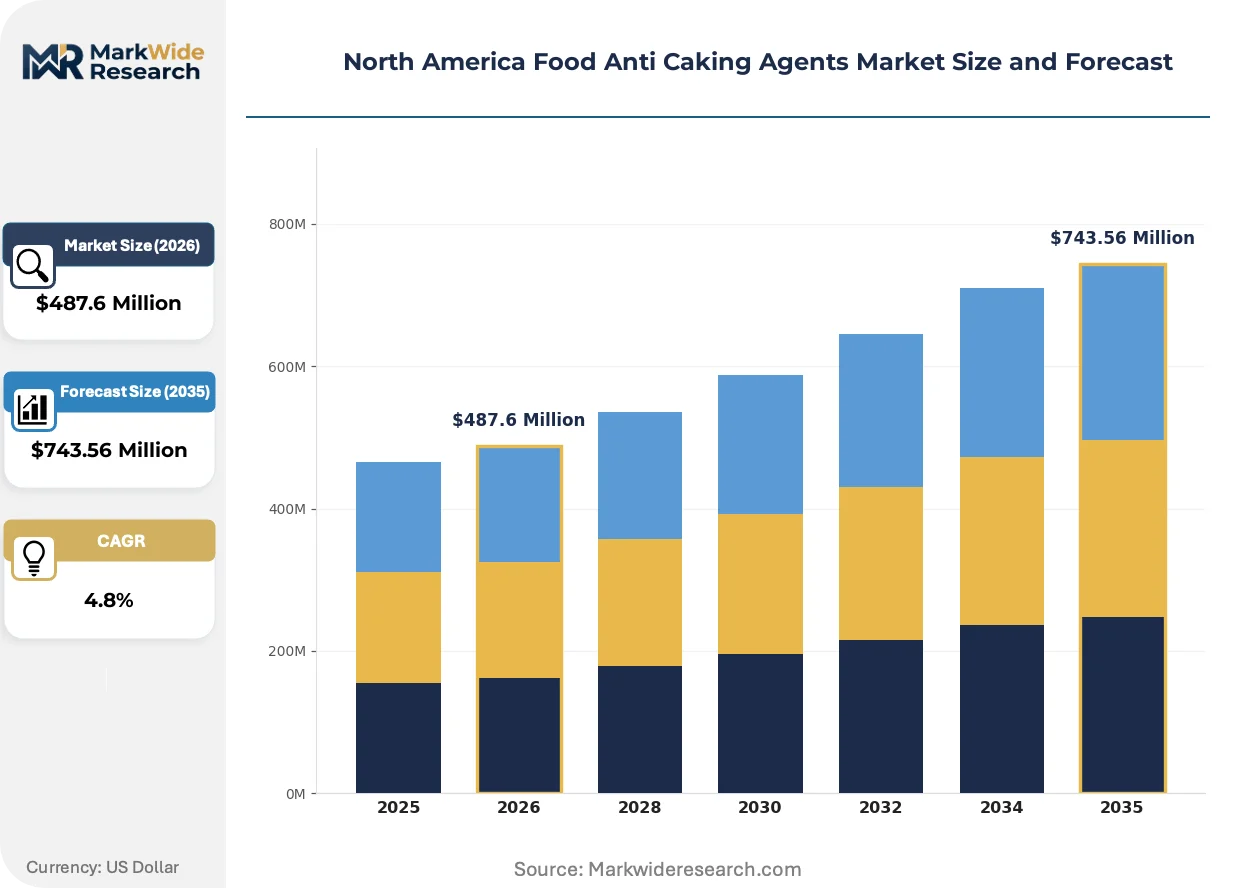
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Silicates, Phosphates, Calcium Compounds, Sugars Application: Snack Foods, Dairy Products, Seasonings, Baking Mixes Form: Powder, Granule, Liquid, Crystal End User: Food Producers, Confectionery Manufacturers, Restaurants, Bakeries |
| Companies Covered | Evonik Industries AG, PPG Industries, Solvay, Huber Engineered Materials, W. R. Grace & Co.-Conn, Cabot Corporation, Brenntag AG, Univar Solutions Inc., Agropur Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Anti Caking Agents Market Evolving Landscape
Moisture-activated encapsulation technologies and precision particle engineering are converging to displace conventional passive absorption systems, while regulatory disclosure requirements and procurement centralization reshape competitive qualification barriers.
Encapsulated salt systems with humidity-triggered release mechanisms are unifying anti-caking and flavor-delivery functions in single-ingredient platforms. Seasoning houses in Illinois and Wisconsin are piloting these systems for soup and sauce applications. This convergence is compressing supplier tiers by eliminating discrete additive procurement for mid-tier processed food manufacturers.
The FDA's evolving GRAS affirmation transparency initiative is forcing public disclosure of safety data previously held as proprietary. Suppliers must now publish toxicology studies that were historically confidential, raising competitive intelligence exposure. Dairy powder processors in Minnesota and Wisconsin are responding by accelerating internal safety documentation to preempt publication timelines.
Category management consolidation among U.S. retail grocery chains is concentrating procurement authority at headquarters level, displacing regional ingredient sourcing autonomy. National account managers now negotiate anti-caking supply contracts covering multiple production facilities simultaneously. This centralization is most visible in the California and Texas retail markets where three chains control over sixty percent of shelf space.
North America Food Anti Caking Agents Market Segmentation
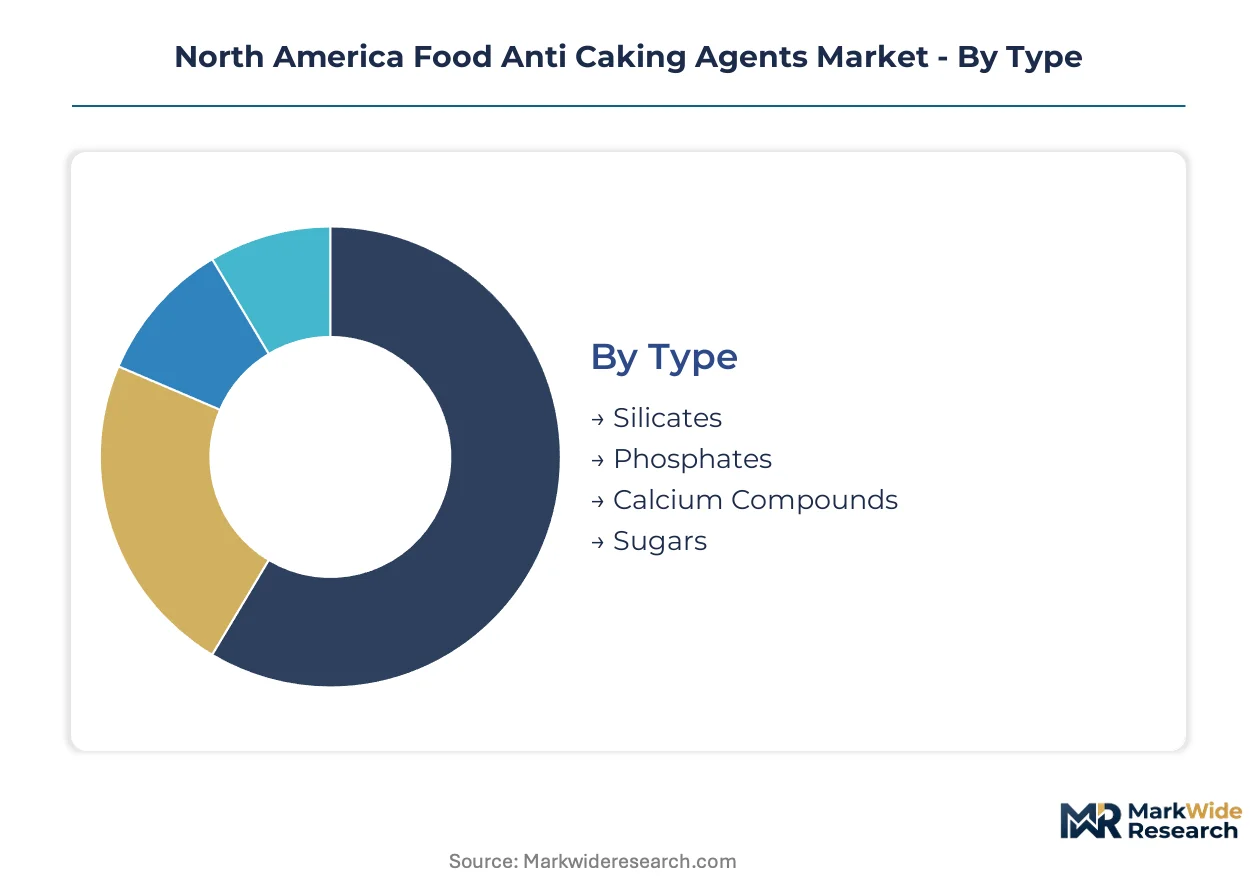
Anti-caking agent procurement patterns diverge sharply between high-volume commodity applications and precision-engineered specialty formulations. Understanding these segment boundaries reveals where margin compression meets premium pricing power across North American food manufacturing.
Type:
Silicates dominate tonnage flows while phosphates capture formulation premiums in moisture-sensitive dairy systems.
- Silicates:Precipitated silica and sodium aluminum silicate absorb surface moisture through high surface-area particle structures. Salt and seasoning processors in California's Central Valley specify silicates for cost-efficient flowability in automated dispensing lines. Hurricane-season feedstock disruptions from Gulf Coast chemical processors expose volume buyers to supply volatility.
- Phosphates:Calcium and sodium phosphate salts reduce interparticle friction while maintaining calcium compatibility critical for cheese powder applications. Dairy processors across Minnesota and Wisconsin favor phosphate systems for protein-stabilized moisture control in whey and lactose formulations. Fluctuating sulfuric acid input costs compress margin stability for integrated suppliers.
- Calcium Compounds:Calcium carbonate and calcium silicate penetrate clean-label baking mixes where mineral fortification doubles as nutritional marketing claims.
- Sugars:Mannitol and sorbitol derivatives serve niche pharmaceutical and premium confectionery applications requiring hygroscopic stability without inorganic residues.
Today's leader: Silicates. Tomorrow's challenger: Calcium Compounds.
Application:
Humidity exposure and processing automation intensity determine specification complexity across end-use categories.
- Snack Foods:Tortilla chip and extruded snack seasoning in Guadalajara and Monterrey facilities demands granule-form anti-caking agents to prevent clumping during high-humidity monsoon seasons. Mexican manufacturing expansion is pulling silicate procurement volumes northward from traditional U.S. supply points.
- Dairy Products:Cheese powder, whey protein, and infant formula applications require calcium-compatible phosphate systems that maintain solubility without protein denaturation. The Great Lakes dairy corridor from Minnesota through Wisconsin concentrates North American demand for pharmaceutical-grade phosphate specifications.
- Seasonings:Soup, sauce, and spice blend manufacturers specify particle-engineered silicates for dust control in high-throughput blending operations.
- Baking Mixes:Clean-label mineral-fortified formulations favor calcium carbonate systems that align with retail grocery chain disclosure requirements.
Snack Foods expand most quickly. Dairy Products defend the highest average selling prices.
Form:
Physical state selection trades dust containment against dissolution kinetics in target processing environments.
- Powder:Fine-ground silicates and phosphates dominate current shipments due to cost efficiency and rapid dispersion in dry blending operations. Seasoning houses in Illinois specify powder forms for homogeneous distribution in low-moisture soup bases.
- Granule:Agglomerated particles reduce airborne dust contamination in high-throughput California seasoning lines where OSHA respiratory exposure limits drive specification changes. Granule variants command 15-25% price premiums over equivalent powder grades.
- Liquid:Suspended anti-caking systems serve wet seasoning applications and slurry-based coating operations for nut and snack products.
- Crystal:Large-particle crystalline salts with integrated anti-caking functionality unify flowability and flavor delivery in single-ingredient platforms.
Granule forms gain share fastest. Powder retains volume dominance.
End User:
Procurement centralization among national food producers is displacing regional ingredient sourcing autonomy across buyer categories.
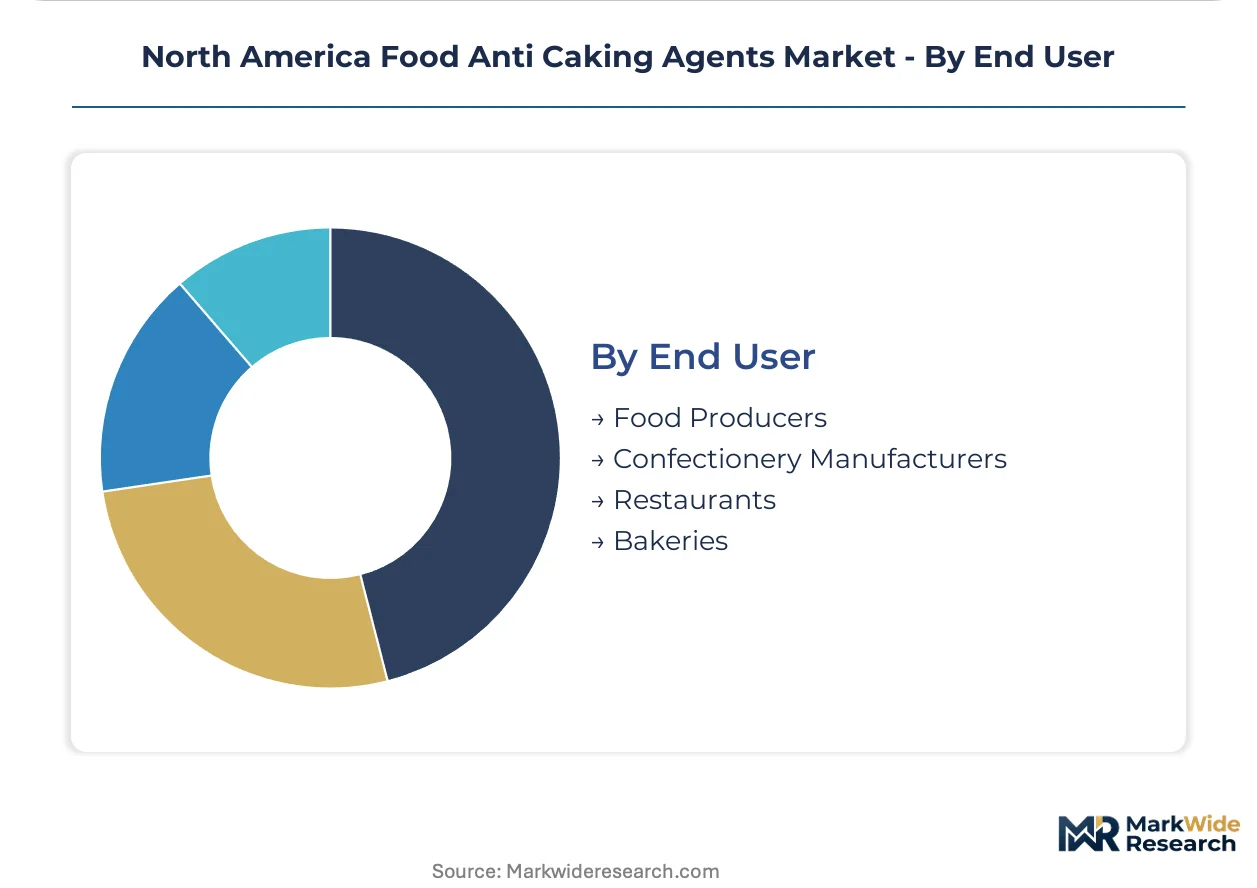
- Food Producers:Multinational processed food manufacturers negotiate enterprise-level contracts covering multiple production facilities simultaneously. Three retail grocery chains controlling sixty percent of California and Texas shelf space now dictate anti-caking specifications through centralized category management.
- Confectionery Manufacturers:Chocolate and candy producers in Ontario and Quebec face Health Canada purity specifications that create qualification moats for dual FDA-Health Canada certified suppliers.
- Restaurants:Chain restaurant commissaries specify pre-blended seasoning systems with integrated anti-caking functionality to reduce kitchen labor and inventory complexity.
- Bakeries:Artisan and industrial bakeries favor calcium-based systems that support clean-label positioning in mineral-fortified bread and pastry applications.
Food Producers concentrate purchasing power. Bakeries show steepest expansion trajectory for clean-label alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands larger procurement volumes than Canada, though Mexican manufacturing expansion is accelerating faster than either neighbor as humidity-driven seasoning demand pulls supply chains southward.
United States
California's Central Valley seasoning clusters and the Great Lakes dairy corridor concentrate demand for silicate and phosphate systems. The FDA's GRAS self-affirmation pathway shapes supplier qualification timelines for cheese powder and whey applications. Minnesota and Wisconsin processors favor calcium-compatible phosphate formulations for protein-stabilized moisture control.
Canada
Health Canada's purity specifications for dairy and confectionery imports create qualification moats for dual-certified suppliers entering Ontario and Quebec. The Food and Drug Regulations impose stricter contaminant thresholds than FDA standards alone. Toronto and Montreal chocolate manufacturers source through channels meeting both regulatory frameworks simultaneously.
Mexico
Guadalajara and Monterrey snack facilities drive granule-form anti-caking procurement for high-humidity monsoon conditions. Mexican federal food safety regulations align with CODEX standards while maintaining regional inspection autonomy. Jalisco's tortilla chip seasoning lines specify dust-controlled formulations for automated dispensing efficiency.
North America Food Anti Caking Agents Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with silicate technology portfolios, phosphate-grade specialists serving dairy compatibility requirements, and precipitated silica formulators targeting moisture absorption performance. Capacity expansion and geographic supply repositioning dominate competitive moves as hurricane-season feedstock risks prompt sourcing diversification.
Within the integrated chemical tier, Evonik Industries AG and Solvay exemplify multinational positioning through technology breadth. PPG Industries occupies a position among diversified materials conglomerates with cross-sector silicate applications. Huber Engineered Materials represents the specialty precipitated silica segment focused on performance-driven formulation partnerships.
| Leading Market Players |
|---|
| Evonik Industries AG |
| PPG Industries |
| Solvay |
| Huber Engineered Materials |
| W. R. Grace & Co.-Conn |
| Cabot Corporation |
| Brenntag AG |
| Univar Solutions Inc. |
| Agropur Ingredients |
| Others |
Value Network & Pricing Analysis
Precipitated silica feedstock costs cascade from Gulf Coast chemical processors through three distinct pricing tiers downstream, with hurricane-season volatility compressing margins for volume buyers while dual-certified suppliers command premiums in Canadian dairy channels.
Pricing Analysis
Capacity additions in Mexico are reshaping price floors for granule-form anti-caking agents serving high-humidity snack production. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade specifications stratifies the market, with calcium phosphate systems capturing premiums for protein compatibility in cheese powder applications. Pricing pressure stems from clean-label substitution toward rice hull ash alternatives with inferior performance metrics. Mid-tier seasoning houses exhibit highest price sensitivity, while infant formula processors prioritize supply security over unit economics.
Supply Chain Analysis
Dual FDA-Health Canada certification requirements gate supplier participation in cross-border dairy and confectionery channels, creating qualification moats for integrated chemical conglomerates. Raw material supply concentrates in the United States, Canada, and Mexico, with precipitated silica feedstock drawing from Gulf Coast chemical processors, phosphate rock sourcing from Florida and North Carolina deposits, and calcium carbonate tapping Midwest limestone quarries. Hurricane-season disruption risk concentrates in Texas and Louisiana production nodes. Distribution runs through national account managers at retail grocery chain headquarters, displacing regional procurement autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Food Anti Caking Agents Market functions as a regulatory compounder where FDA GRAS affirmation transparency and Health Canada purity specifications continuously elevate compliance barriers, locking in advantage for suppliers with preemptive toxicology documentation and dual-certification capabilities.
For Market Incumbents: Cement phosphate-grade supply relationships with Great Lakes dairy processors through dedicated technical service teams and calcium compatibility guarantees. Deepen backward integration into precipitated silica feedstock through long-term offtake agreements with Gulf Coast chemical processors, mitigating hurricane-season disruption exposure that threatens volume commitments to multinational seasoning houses. For New Entrants and Emerging Players: Capture mineral-fortified baking mix applications where calcium carbonate systems align with clean-label procurement mandates from California and New York retail grocery chains. Target artisan bakery channels with smaller batch requirements and lower certification barriers as the most penetrable entry point, leveraging direct technical sales relationships to bypass centralized category management gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where particle engineering talent scarcity intersects with dual-certification timeline compression, favoring acquisition of mid-tier suppliers with existing FDA GRAS documentation and USDA organic certification capabilities. Monitor California Proposition 65 enforcement trends and New York emerging disclosure requirements as the critical inflection signal for preemptive toxicology investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Health Canada purity specifications create qualification moats excluding marginal competitors from Ontario dairy channels. |
| Particle Engineering Partnerships | Controlled particle-size distribution capabilities command premium positioning in humidity-sensitive Mexican snack applications. |
| Granule Form Capacity Expansion | Dust-controlled formulations penetrate high-throughput California seasoning lines where OSHA limits drive specification changes. |
| Encapsulation Technology Licensing | Humidity-triggered release systems unify anti-caking and flavor-delivery functions for Illinois soup manufacturers. |
| Backward Integration into Silica Feedstock | Gulf Coast supply concentration exposes volume buyers to hurricane-season disruption risk requiring sourcing diversification. |
Research Methodology
Bottom-up dairy and snack food modeling reconciled against top-down silicate and phosphate supply tracking forms the analytical core of this study. Primary interviews with formulation chemists, procurement directors at multinational seasoning houses, dairy powder plant managers, and regulatory affairs specialists at FDA GRAS consulting firms combined with secondary validation from FDA GRAS notification databases, USDA organic certification records, Health Canada Food and Drug Regulations, and customs trade data for precipitated silica and phosphate rock imports. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply estimates.
Input-output matrices map anti-caking agent consumption across application segments, form factors, and end-user categories throughout the projection horizon. Segmentation dimensions include type tier, application intensity, physical form, and procurement centralization level. CAGRs derive from regression analysis of historical volume relationships against food manufacturing output indices, humidity-adjusted seasoning demand curves, and dairy powder production trajectories. Forecast inputs incorporate GRAS affirmation timeline data, clean-label reformulation pipeline tracking, and automated dispensing infrastructure deployment rates in California and Mexican manufacturing clusters.
Regulatory disclosure mandate acceleration, feedstock supply disruption events, and clean-label substitution velocity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding FDA GRAS process efficiency, Health Canada import inspection intensity, and retail grocery chain category management consolidation pace. A model refresh is warranted upon material change in California or New York state-level labeling enforcement trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Excipients Market