
 Global Cereal Ingredients Market | 2026-2036
Global Cereal Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cereal Ingredients Market Intelligence
Clean-label and high-fiber ingredient specifications are rotating the market toward higher-value formulations. This shift favors large-scale processors with advanced research and development capabilities. Cargill leverages its extensive global sourcing network to ensure consistent supply of varied raw materials. Archer Daniels Midland specializes in converting base grains into a portfolio of starches and proteins, while Tate & Lyle differentiates with its focus on texturants and fibers for health-focused applications.
Cereal ingredients are processed components derived from grains such as corn, wheat, and oats. These materials undergo processes like milling or extrusion to isolate constituents like starches and fibers for specific functional properties in food manufacturing. While starches continue to dominate by volume, proteins and fibers are the high-growth ingredient types. In end-user industries, demand from the breakfast foods and snack production sectors for texture enhancers and fat replacers is particularly strong.
Product formulation is shaped by food safety and labeling regulations from multiple bodies. For instance, guidance from the US Food and Drug Administration (FDA) on dietary fibers and rulings from the European Food Safety Authority (EFSA) on health claims directly impact ingredient choice. The FSSAI in India also sets stringent standards for fortified foods. Navigating these divergent international rules on novel proteins and fibers is a key strategic challenge.
Market Dynamics
The central dynamic shaping the cereal ingredients market is the tension between the commodity nature of raw grain supply and the accelerating demand for high-value, functional components. This forces a strategic split between bulk processors and specialized innovators focused on clean-label formulations.
Growth Catalysts
- Regulatory Guidance on Fiber:The FDA's updated definition of dietary fiber is compelling food manufacturers to incorporate ingredients like resistant starches and beta-glucans, directly stimulating demand from the breakfast foods and baked goods sectors.
- Convenience Food Consumption:Rising disposable incomes and urbanization in countries like India and Brazil are expanding the market for processed snacks and ready-to-eat meals, which rely on cereal ingredients for texture and stability.
- Plant-Based Protein Demand:The consumer shift toward alternative proteins is creating new applications for protein isolates and concentrates derived from wheat, corn, and oats in meat analogues and dairy-free products.
Market Restraints
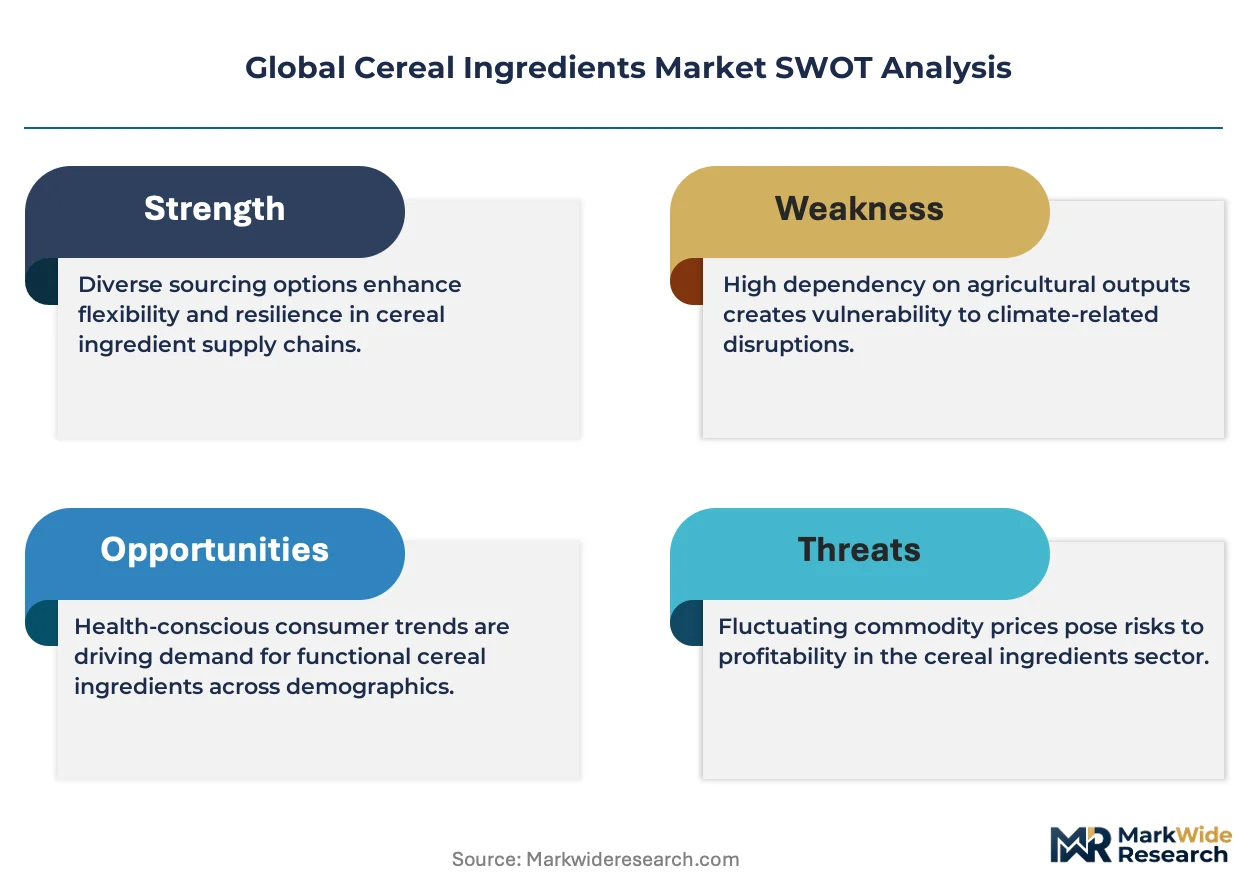
- Input Cost Volatility:Ingredient pricing is directly tied to global grain markets, making processors vulnerable to price swings caused by climate events, geopolitical instability, and fluctuating agricultural subsidies.
- Substitution from Non-Cereal Sources:Cereal-derived starches and fibers face competition from alternatives like tapioca starch, pea protein, and psyllium husk, which offer different functional or labeling advantages.
- Divergent International Standards:Navigating conflicting regulations for novel fibers and proteins between bodies like the FDA in the US and EFSA in Europe creates significant compliance costs and delays market entry.
Strategic Opportunities
- Fortification in Developing Markets:There is significant opportunity in Southeast Asian and African nations to supply fortified cereal ingredients for government-backed nutritional programs aimed at combating micronutrient deficiencies.
- Upcycled Ingredient Streams:Converting processing byproducts, such as bran and germ from milling, into high-value fibers and oils offers a sustainable, circular-economy-aligned revenue stream for manufacturers.
- Extrusion and Enzymatic Modification:Combining advanced extrusion techniques with enzymatic treatments allows for the creation of novel texturants and soluble fibers with unique properties for the snack and beverage industries.
Industry Challenges
- Supply Chain Traceability:Meeting demands for non-GMO, organic, and allergen-free certifications requires complex and costly identity preservation systems to segregate grain supplies from farm to final ingredient.
- High Capital Investment:Building or retrofitting facilities with the specialized fractionation, milling, and extrusion equipment needed for high-purity proteins and fibers requires substantial capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cereal Ingredients Market |
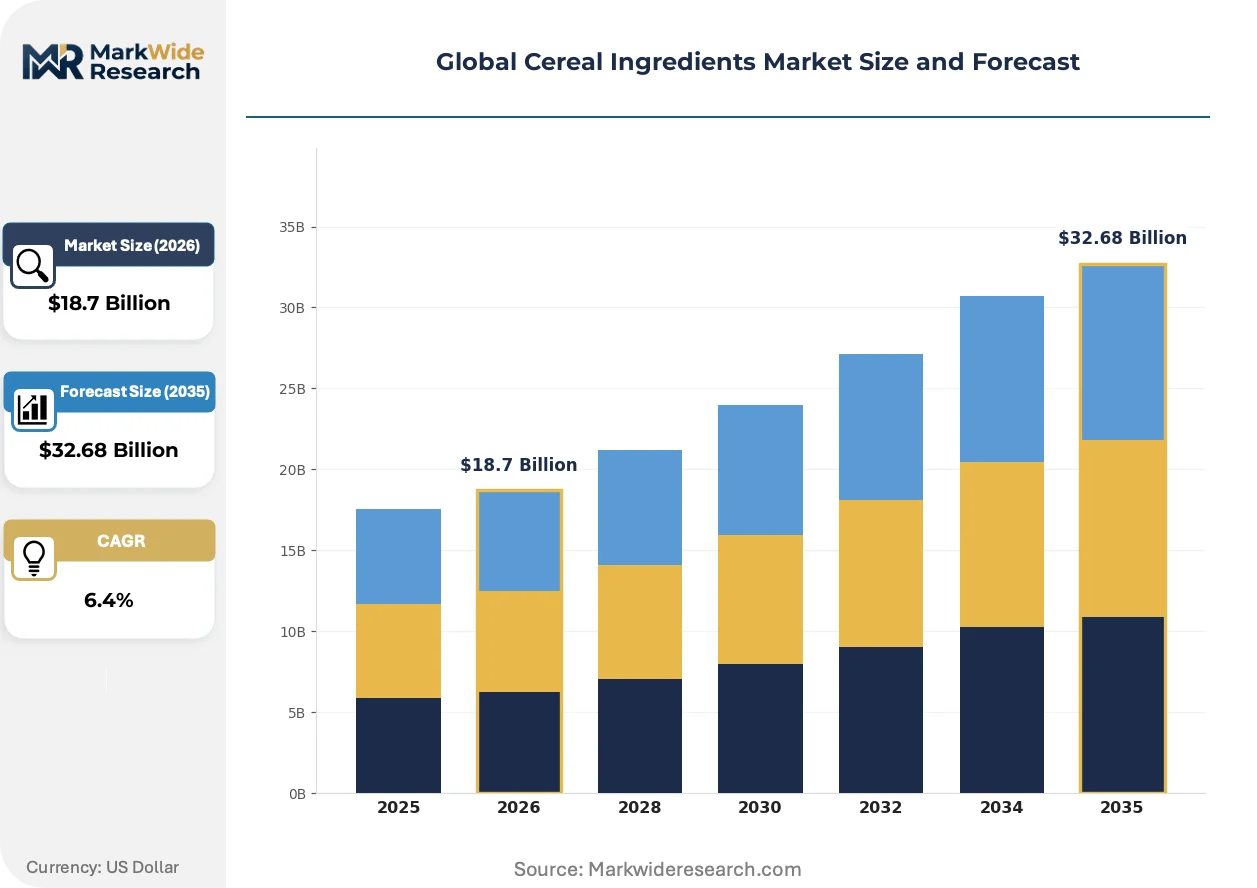
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Starches, Fibers, Proteins, Sweeteners, Enzymes Functional Application: Texture Enhancers, Fat Replacers, Emulsifiers, Bulking Agents, Flavor Enhancers Processing Technology: Extrusion, Milling, Fermentation, Enzymatic Hydrolysis, Spray Drying End User Industry: Bakery, Confectionery, Breakfast Foods, Snack Production, Pet Foods |
| Companies Covered | Kerry Group, Associated British Foods, Archer Daniels Midland, Roquette Frères, Tate & Lyle, Cargill, Ingredion, SunOpta, Bunge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cereal Ingredients Market Strategic Shifts & Innovations
The market's evolution is defined by the industrial-scale application of food science to meet consumer demand for health-centric attributes. This is shifting production focus from bulk commodity starches toward precisely engineered functional ingredients derived from traditional grains.
Microencapsulation technology provides a protective barrier for sensitive vitamins and minerals used in fortification. Breakfast food and infant nutrition manufacturers are rapidly adopting this process to ensure nutrient stability and prevent off-tastes. This technology is miniaturizing the delivery system for functional additives, enabling higher fortification levels without compromising the sensory profile of the final product.
European Food Safety Authority (EFSA) mandates on health claims are forcing a higher standard of scientific substantiation for functional ingredients. This requires suppliers of components like oat beta-glucan to fund clinical trials to prove benefits such as cholesterol reduction. The breakfast cereal and functional beverage segments are most impacted, reformulating products to meet EFSA's rigorous evidence thresholds or removing unproven claims.
A clear behavioral shift is occurring as food formulators move from long-term, fixed-volume contracts to more agile, on-demand purchasing for specialty ingredients. This model disrupts traditional bulk procurement, favoring suppliers that offer digital purchasing platforms and responsive logistics for smaller, more frequent orders. This trend is most pronounced in the North American snack food sector, driven by rapid product development cycles.
Global Cereal Ingredients Market Segmentation
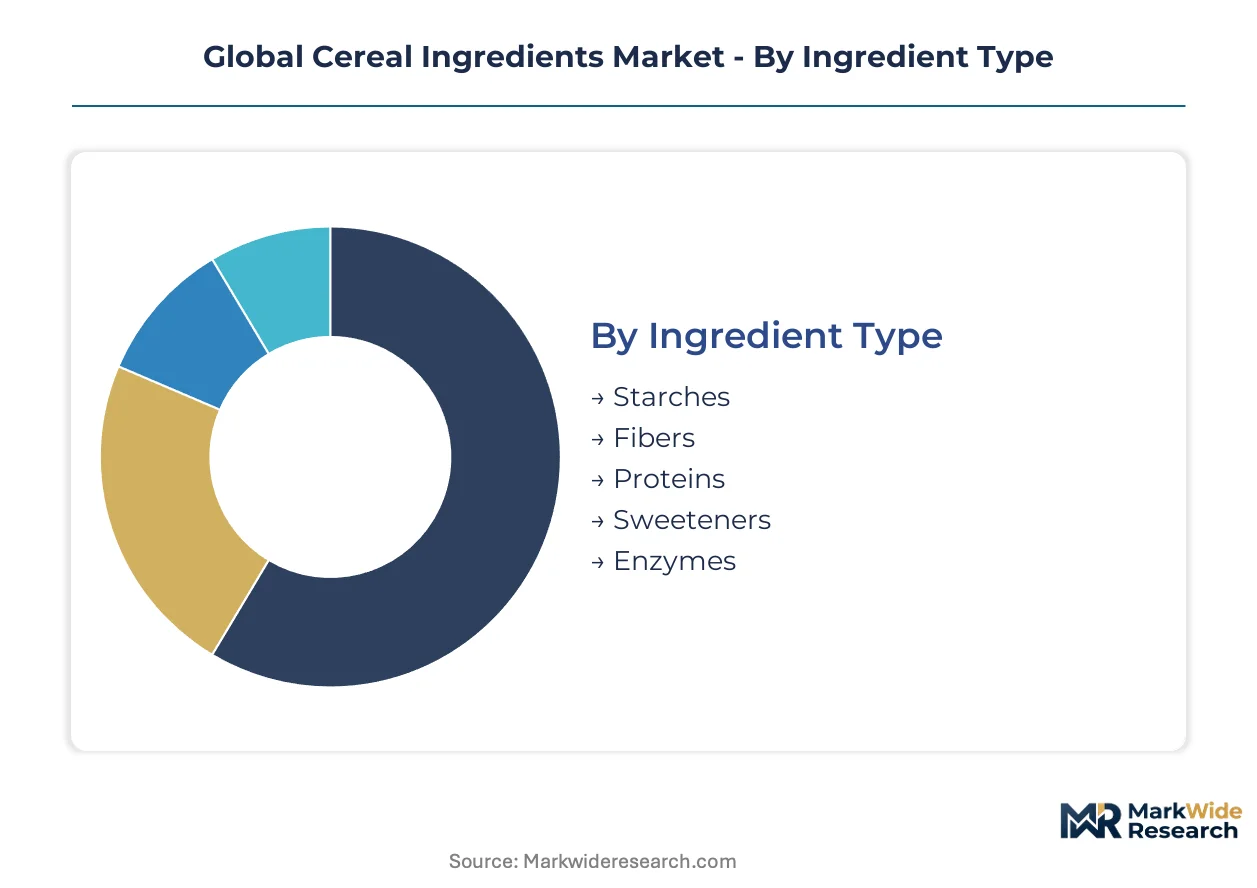
The cereal ingredients market is highly diversified, with distinct segments emerging based on ingredient composition, functional properties, processing methods, and end-user applications. Understanding these segmentations provides clarity on where value is created and how different product types are consumed across the food industry.
Ingredient Type:
The distribution channels for cereal ingredients are differentiated by their core chemical composition and how they are handled by food manufacturers.
- Starches:These complex carbohydrates are primarily used as thickeners, binders, and gelling agents in food systems. Demand concentrates in the bakery and processed food sectors, driven by their cost-effectiveness and functional versatility in product formulation.
- Fibers:Indigestible plant components, such as beta-glucans and resistant starches, are crucial for digestive health and satiety.
- Proteins:Macromolecules composed of amino acid chains, derived from grains like wheat and corn, offer nutritional and functional benefits. Demand is strong in plant-based meat alternatives and dairy-free products, driven by consumer health trends and sustainability concerns.
- Sweeteners:These ingredients provide taste and texture, often derived from corn or wheat through enzymatic processes.
- Enzymes:Biological catalysts are used for specific processing functions, such as improving dough rheology or modifying starch viscosity.
Starches dominate the installed base. Proteins are where expansion concentrates.
Functional Application:
Ingredient utility is categorized by the specific functional properties they impart to food products during manufacturing.
- Texture Enhancers:These ingredients modify the mouthfeel, viscosity, and structural integrity of food products. Demand is strong in snack production and breakfast cereals, driven by consumer preference for specific sensory experiences.
- Fat Replacers:Designed to mimic the properties of fat while significantly reducing caloric content in foods. Demand from health-conscious consumers in baked goods and dairy alternatives drives their integration into new formulations.
- Emulsifiers:These compounds stabilize oil-in-water or water-in-oil mixtures, preventing separation in processed foods.
- Bulking Agents:Ingredients that add volume and body to products without contributing significant calories or altering flavor profiles.
- Flavor Enhancers:Components utilized to intensify or modify existing flavors within food matrices, improving palatability.
Texture enhancers represent the largest volume application. Fat replacers represents the fastest-growing trajectory.
Processing Technology:
The capital intensity of cereal ingredient production varies significantly with the sophistication of the processing technology employed.
- Extrusion:A high-temperature, short-time process used for texturizing proteins and starches into various shapes and forms. Snack production and plant-based meat analogues drive demand, requiring specialized equipment for precise product characteristics.
- Milling:This foundational mechanical process reduces grain size and separates components like flour, bran, and germ. This technology underpins the entire bakery sector, providing essential raw materials for bread and pastry production.
- Fermentation:Utilizes microorganisms to transform raw materials into new compounds, such as organic acids or alcohols.
- Enzymatic Hydrolysis:Breaks down complex molecules into simpler ones using specific enzymes, often for modifying starches or proteins.
- Spray Drying:Converts liquid feedstocks into a dry powder form, preserving sensitive ingredients and enabling easier handling.
Milling remains the most widespread processing method. Extrusion technology shows the steepest expansion trajectory.
End User Industry:
Customer types for cereal ingredients are defined by their specific product portfolios and manufacturing scale.
- Bakery:This sector utilizes a wide range of flours, starches, and fibers for products including bread, cakes, cookies, and pastries.
- Confectionery:Incorporates cereal-derived sweeteners and texturants for candies, chocolates, and other sweet treats.
- Breakfast Foods:Includes cereals, bars, and instant mixes leveraging cereal ingredients for texture, fiber, and protein content. Consumer health consciousness in India and the US drives innovation in fortified and high-fiber options.
- Snack Production:Encompasses chips, crackers, and extruded snacks, utilizing cereal components for crispness and binding. Urbanization and convenience food consumption in Brazil and China fuel the rapid growth of this sector.
- Pet Foods:Employs cereal ingredients as fillers, binders, and nutrient sources, providing caloric content and structural integrity to pet food formulations.
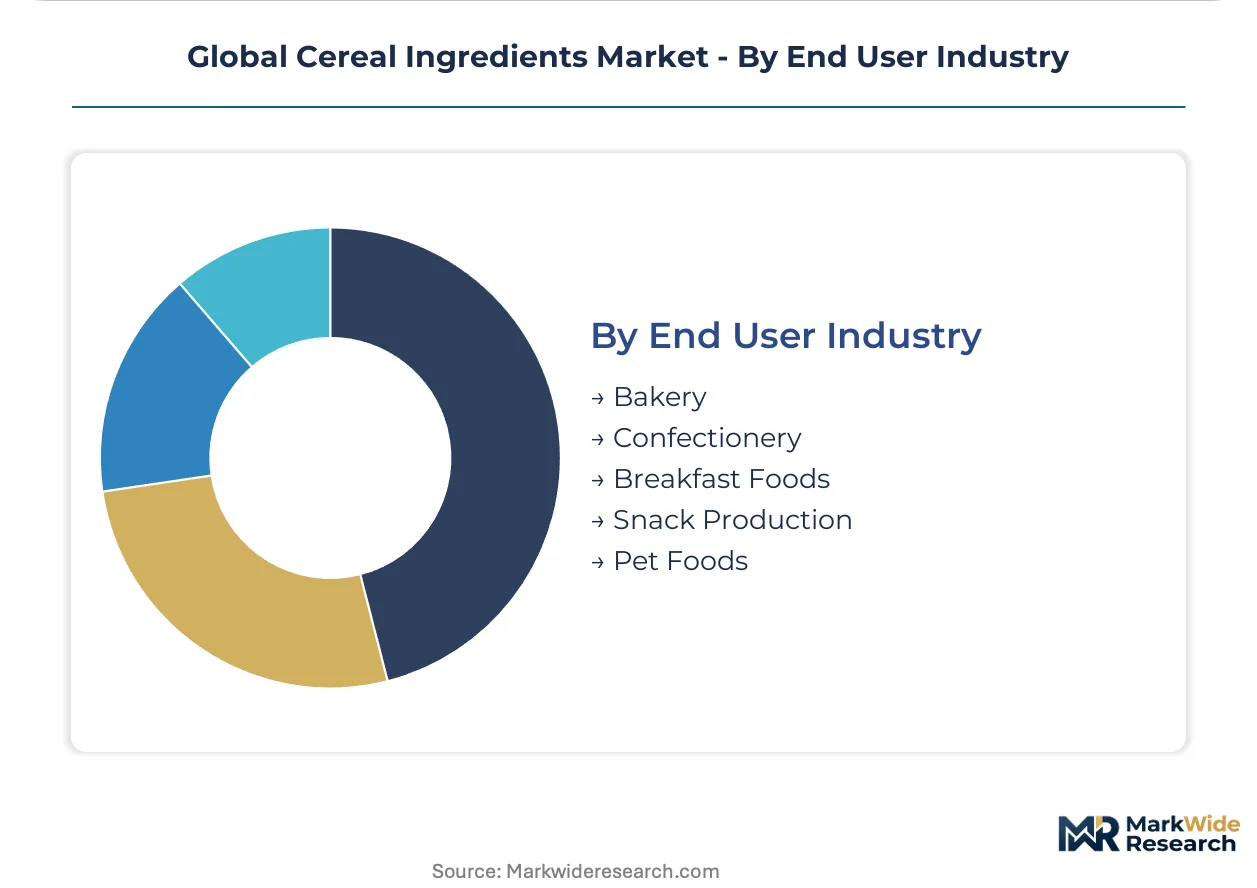
The bakery sector consumes the largest volume of cereal ingredients. Snack production is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for cereal ingredients varies by region, with commodity-grade bulk starches exhibiting higher price sensitivity compared to specialized functional fibers and proteins. Markets with mature food processing infrastructure typically demand higher-value formulations. Conversely, developing economies often prioritize cost-effectiveness for staple food fortification programs.
United States
Consumer health consciousness drives demand for high-fiber and plant-based protein ingredients in the United States. The FDA's updated guidance on dietary fiber composition compels manufacturers to reformulate products. Food innovation hubs in California and the Northeast corridor lead in developing novel snack and breakfast food applications.
India
Rising disposable incomes and rapid urbanization in India expand the market for convenience foods and fortified products. The FSSAI sets stringent standards for food additives, influencing ingredient selection for local manufacturers. Mumbai and Bengaluru serve as key centers for food processing and product development, particularly for snacks.
Germany
The bakery and confectionery sectors in Germany maintain consistent demand for high-quality cereal starches and flours. EFSA regulations on health claims necessitate scientific substantiation for functional ingredients like beta-glucans. Food technology clusters around Munich and Hamburg focus on process optimization and ingredient functionality.
Brazil
Urbanization and a growing middle class in Brazil fuel consumption of processed snacks and ready-to-eat meals. ANVISA regulations govern food safety and labeling, impacting ingredient sourcing for local food companies. São Paulo's extensive food industry infrastructure supports large-scale production of cereal-based products.
China
Demand for cereal ingredients in China is significant, driven by the expanding snack production and convenience food sectors. SAMR oversees food safety standards, influencing the adoption of certified and traceable ingredients. Industrial zones in the Yangtze River Delta concentrate food manufacturing and ingredient innovation.
Global Cereal Ingredients Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global cereal ingredients market. The market exhibits a tiered structure, with large, diversified agricultural processors coexisting with specialized ingredient innovators. Strategic archetypes include integrated commodity suppliers, functional ingredient specialists, and regional processors. Competitive moves frequently involve capacity expansion to meet demand surges and strategic partnerships for technology co-development.
Integrated commodity suppliers like Cargill and Archer Daniels Midland (ADM) anchor the market's bulk ingredient supply, leveraging extensive global sourcing networks. Tate & Lyle occupies a position as a functional ingredient specialist, focusing on high-value texturants and fibers for health-focused applications. These companies exemplify the strategic split between volume-driven processing and innovation-led product differentiation, responding to varying customer needs from cost-sensitive bulk buyers to premium-segment formulators.
| Leading Market Players |
|---|
| Kerry Group |
| Associated British Foods |
| Archer Daniels Midland |
| Roquette Frères |
| Tate & Lyle |
| Cargill |
| Ingredion |
| SunOpta |
| Bunge |
| Others |
Cost & Logistics Intelligence
The FSSAI's stringent standards for fortified foods directly gate both ingredient qualification and price differentiation for cereal ingredients in India. These regulations elevate the cost structure for compliant suppliers while enabling premium pricing for certified products.
Pricing Analysis
Specialized formulation support drives lifetime value in the cereal ingredients market, allowing for premium contracts. The dominant pricing model is a hybrid of commodity spot pricing for bulk starches and long-term, value-based contracts for functional fibers and proteins. Price differentiation stems from certification levels, such as non-GMO or organic, and the degree of customization offered to food manufacturers. Pricing pressure stems from input cost volatility, particularly for commodity grains. Bulk commodity buyers exhibit high price sensitivity, while specialty food formulators are less sensitive to premium ingredient costs.
Supply Chain Analysis
India and Brazil anchor significant raw grain production, serving as crucial supply hubs for cereal ingredients. The supply chain relies heavily on inputs like corn, wheat, and oats, which are processed into starches, proteins, and fibers. A structural risk is commodity price volatility, exacerbated by climate events and geopolitical instability affecting agricultural yields. Distribution runs primarily through direct sales to large food manufacturers and specialized distributors serving smaller, niche food brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a substitution defense, as incumbents must navigate the threat from non-cereal derived alternatives like tapioca starch and pea protein.
For Market Incumbents: Secure long-term supply agreements for key grain inputs to mitigate input cost volatility. Invest in advanced extrusion and enzymatic modification technologies to develop novel functional ingredients, countering substitution from non-cereal sources. Pursue strategic partnerships with R&D-focused food tech startups to accelerate innovation in clean-label formulations. Expand capacity in high-growth regions like Southeast Asia to align with demand for fortified products.
For New Entrants and Emerging Players: Niche clean-label formulation services represent a significant service-layer gap where incumbents under-serve. Target small-to-medium food brands seeking agile, customized ingredient solutions for rapid product development cycles. Focus on developing specialized protein isolates or resistant starches with unique functional properties. A digital purchasing platform offering responsive logistics can serve as a compelling go-to-market angle.
For Investors and Strategic Acquirers: The FDA's updated guidance on dietary fiber reshapes the acquisition landscape, favoring companies with proven functional ingredient portfolios. Focus on specialized innovators with strong intellectual property in fibers, proteins, and texturants derived from cereals. Acquisition targets should possess advanced processing capabilities like extrusion or enzymatic modification. A signal to watch is an increase in M&A activity among firms specializing in sustainable, upcycled ingredient streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Extrusion Technology | This enhances product versatility and creates novel textures for snack and plant-based applications. |
| Secure Long-Term Grain Supply Contracts | This stabilizes input costs and ensures consistent raw material availability for processors. |
| Develop Clean-Label Functional Fibers | This addresses consumer demand for healthier products and regulatory compliance in key markets. |
| Expand Fortified Ingredient Production | This captures opportunities in developing markets with government-backed nutritional programs. |
| Implement Digital Procurement Platforms | This streamlines order processing and improves logistics for agile food manufacturers. |
Research Approach
The analysis maps cereal ingredient types, functional applications, processing technologies, and end-user industries, each validated through primary interviews. These interviews engaged R&D directors, procurement leads, food scientists, and regulatory affairs specialists from across the value chain. Secondary validation drew from FDA filings, EFSA opinions, FSSAI standards, and relevant trade association reports. The study employed both bottom-up and top-down triangulation to ensure data accuracy and consistency.
Consistency checks against external benchmarks validated the volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including ingredient type, functional application, processing technology, end-user industry, and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected market drivers. Key forecast inputs included grain commodity price indices and consumer health trend surveys.
Underlying assumptions cover stable economic growth and predictable regulatory evolution, with deviation risk concentrated in climate events affecting harvests. Geopolitical instability impacting global trade flows also poses a significant risk to forecasts. Recalibration cycles align with material shifts in these named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Phytogenic Feed Additives Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Ph Adjuster Market