
 Hydrogen Water Bottle Market | 2026-2036
Hydrogen Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Water Bottle Market Insights
Medical-grade concentration thresholds is rotating the competitive baseline upward as consumers demand validated dissolved hydrogen outputs. EVOLV leverages proprietary electrolysis engineering to sustain premium positioning in direct-to-consumer channels. IonBottles anchors its portfolio around portable form factors, while OCEMIDA dominates smart-connected variants with app-integrated dosage tracking.
A hydrogen water bottle is a portable or fixed vessel that infuses drinking water with molecular hydrogen gas through electrolytic or membrane-based generation, typically achieving dissolved concentrations between 0.5 and 1.6 parts per million for antioxidant consumption. Electrolysis technology leads the technology dimension due to proven reliability and lower unit economics, though membrane-based systems command higher margins among clinical-adjacent buyers. Portable product types occupy the largest volume share, while smart bottles represent the fastest-growing segment as health-conscious consumers seek real-time hydrogen concentration feedback.
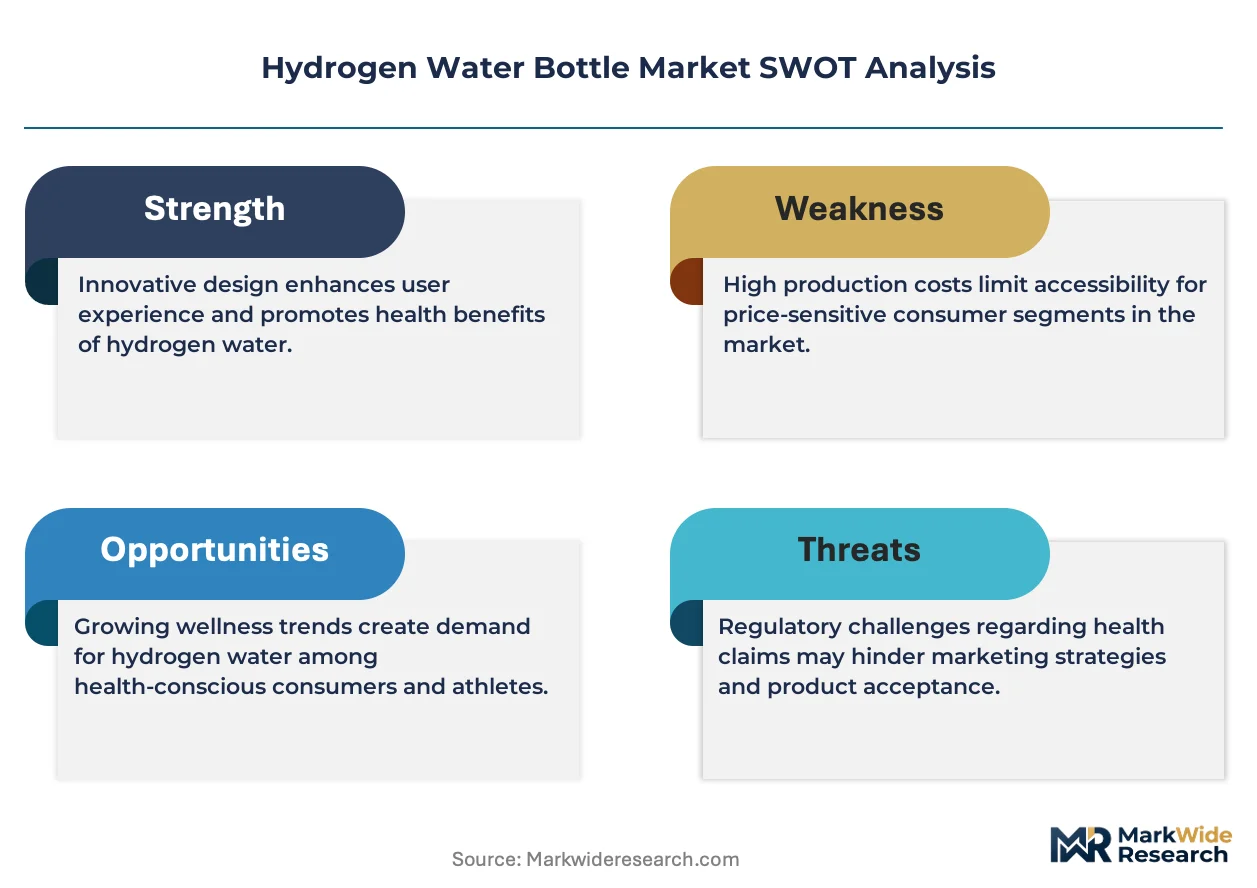
The US FDA scrutinizes hydrogen health claims under existing dietary supplement frameworks, compelling manufacturers to substantiate promotional language or risk enforcement action. Japan's Ministry of Health, Labour and Welfare recognizes hydrogen's safety profile through established food additive classifications, easing market entry for compliant exporters. China's SAMR applies GB standards to electrical hydration devices, creating certification barriers for uncertified imports. Stakeholders must monitor regulatory divergence across these three jurisdictions to align product development with divergent compliance pathways.
Market Dynamics
Medical-grade concentration thresholds are rotating the competitive baseline upward as consumers demand validated dissolved hydrogen outputs from their devices. This technical escalation is forcing manufacturers to substantiate performance claims through measurable electrolysis engineering rather than marketing assertions.
Growth Catalysts
- Fitness Recovery Protocols:Athletic trainers and sports medicine practitioners are integrating hydrogen-enriched hydration into post-workout recovery regimens. This end-use vertical is expanding device adoption beyond wellness consumers into performance-oriented segments.
- Japan's Food Additive Classifications:The Ministry of Health, Labour and Welfare recognizes hydrogen's safety profile through established regulatory frameworks. This classification eases market entry for compliant exporters seeking Asian market penetration.
- Proton Exchange Membrane Advances:Next-generation membrane materials are improving hydrogen dissolution efficiency while reducing power consumption. Portable device manufacturers are incorporating these materials to extend battery life between charges.
Market Restraints
- Platinum Catalyst Cost Volatility:Electrolysis electrodes rely on platinum-group metals subject to commodity price swings. Input cost instability compresses margins for mid-tier manufacturers unable to pass through material increases.
- FDA Claim Scrutiny:The US Food and Drug Administration applies dietary supplement frameworks to hydrogen health assertions. Promotional language must meet substantiation standards or face enforcement action, constraining marketing latitude.
- Alkaline Water Substitutes:pH-elevated bottled water and ionizer pitchers compete for the same antioxidant-conscious consumer wallet. These established alternatives enjoy broader retail distribution and lower price points.
Strategic Opportunities
- SAMR Certification Pathways:China's State Administration for Market Regulation applies GB standards to electrical hydration devices. Early certification compliance creates preferential access to the world's largest consumer electronics market.
- Clinical Adjacent Positioning:Wellness clinics and integrative medicine practices represent an underpenetrated channel for prescription-adjacent hydrogen delivery. Partnership models with healthcare providers could unlock B2B revenue streams.
- App-Integrated Dosage Tracking:Smartphone connectivity enables real-time hydrogen concentration monitoring and consumption logging. This technology convergence appeals to quantified-self enthusiasts seeking biometric integration.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Specialized expertise in proton exchange membrane design and electrolysis optimization is concentrated among a limited pool of researchers. Recruitment competition from fuel cell and battery sectors intensifies compensation pressures.
- Multi-Jurisdiction Certification Timelines:Separate testing protocols for FDA, CE marking, and GB compliance extend product launch cycles. Parallel certification tracks require dedicated regulatory affairs capacity that strains emerging manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Water Bottle Market |
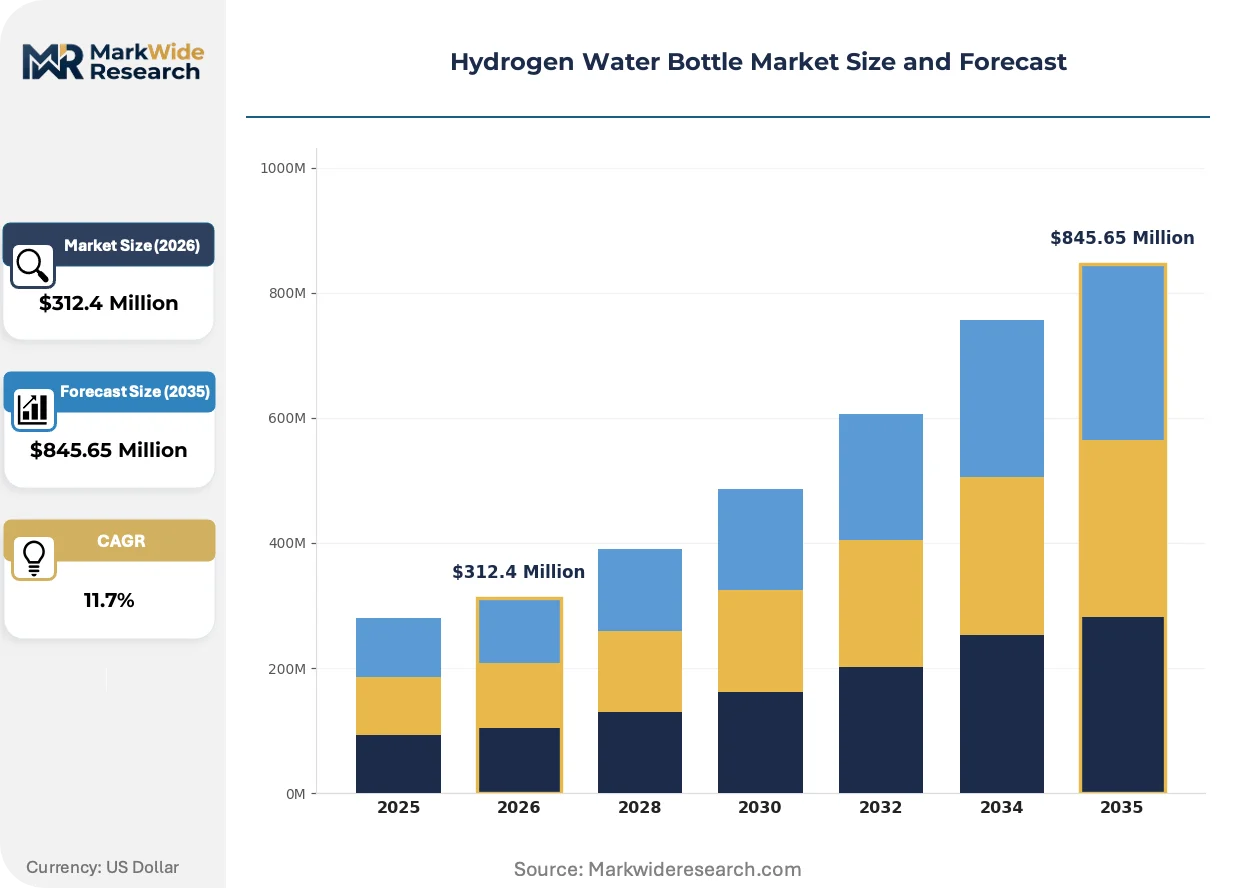
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Smart, Household, Commercial Technology: Electrolysis, Membrane, Magnetic, Ultrasonic End User: Fitness Enthusiasts, Health Conscious, Athletes, General Consumers Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Piurify, OCEMIDA, IonBottles, EVOLV, Dr. Water, PUREPEBRIX, Hydroh Bottle, Aqua Vital, Echo Flask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Water Bottle Market Trends and Innovations
Electrolysis technology variants are fragmenting the product landscape as manufacturers differentiate through proprietary membrane configurations and power management systems. This technical diversification is creating distinct performance tiers that reshape how buyers evaluate purchase decisions.
Membrane-based generation systems are fragmenting the incumbent electrolysis dominance by achieving higher dissolved hydrogen concentrations at lower operating temperatures. Sports medicine facilities and clinical-adjacent wellness centers are adopting these systems despite premium pricing. The technology is fragmenting what was previously a commoditized hardware category into performance-stratified segments with divergent margin structures.
REACH substance restrictions in the European Union are compelling electrode material substitutions away from certain platinum-group metal alloys. Manufacturers serving EU markets must reformulate catalytic surfaces or risk market exclusion. Portable device exporters are responding by developing dual-spectrum product lines with region-specific material certifications.
Direct-to-consumer subscription models are displacing traditional retail distribution for replacement components and consumable filters. Health-conscious buyers in Japan and South Korea are embracing recurring revenue relationships that ensure optimal device performance. This channel evolution is most visible in metropolitan markets with established e-commerce infrastructure and high digital payment penetration.
Hydrogen Water Bottle Market Segmentation
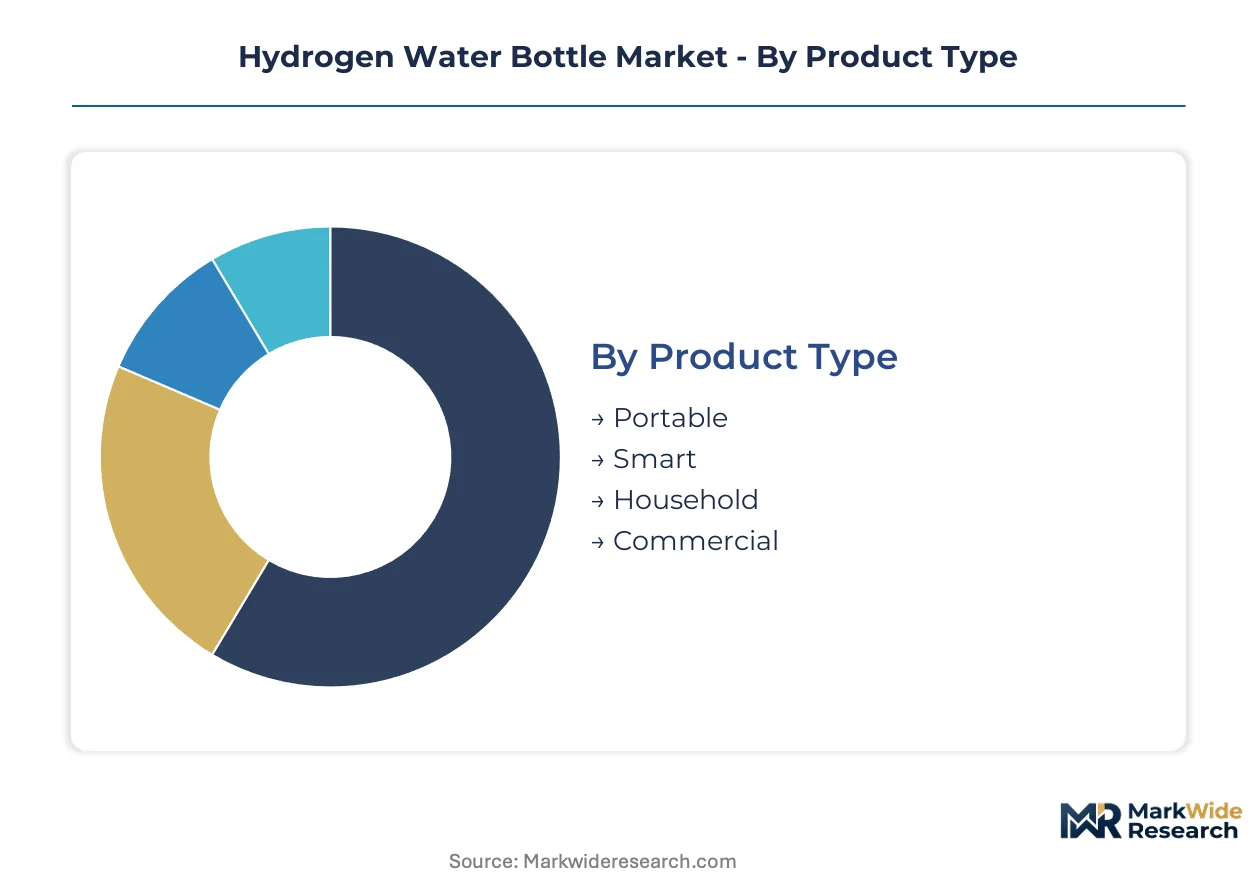
Segmentation in the hydrogen water bottle market determines channel economics and margin capture. Product positioning varies sharply between clinical-adjacent wellness buyers and fitness-oriented consumers, driving divergent distribution strategies and price architecture.
Product Type:
Portable units dominate e-commerce fulfillment and travel retail, while smart variants command premium positioning through direct-to-consumer channels. Household systems flow through appliance retailers and integrative medicine clinics. Commercial installations target sports facilities and corporate wellness programs.
- Portable:Handheld vessels with integrated electrolysis cells achieve dissolved hydrogen concentrations between 0.5 and 1.6 parts per million. Demand concentrates among fitness enthusiasts in Japan and South Korea, where mobile hydration protocols drive replacement cycles. Battery life limitations and platinum catalyst costs constrain margin expansion for mid-tier manufacturers.
- Smart:App-connected bottles with real-time hydrogen concentration sensors and consumption logging appeal to quantified-self enthusiasts. These devices flow primarily through brand-direct websites and specialty wellness platforms, bypassing traditional retail markups. The segment is expanding most quickly as biometric integration becomes a purchase differentiator.
- Household:Countertop systems with larger water reservoirs serve family hydration needs and multi-user environments.
- Commercial:Fixed installations for gyms, wellness clinics, and sports medicine facilities require higher throughput and validated output consistency.
By volume, portable leads. By growth pace, smart is ahead.
Technology:
Cost tier stratification separates proven electrolysis systems from emerging membrane technologies with premium positioning. Magnetic and ultrasonic variants occupy niche applications with limited clinical validation.
- Electrolysis:Proton exchange membrane and alkaline electrolysis systems dominate manufacturing scale due to established supply chains and lower unit economics. Platinum-group metal electrodes face REACH substance restrictions in EU markets, compelling material substitutions. Portable device manufacturers favor this technology for battery efficiency and compact form factors.
- Membrane:Advanced polymer membranes achieve higher dissolved hydrogen concentrations at reduced operating temperatures, justifying premium pricing for clinical-adjacent buyers. Sports medicine facilities in Japan and integrative wellness centers in Germany adopt these systems despite elevated capital costs. The technology is gaining share fastest among performance-oriented segments.
- Magnetic:Field-based hydrogen generation claims reduced power consumption but lacks standardized concentration validation.
- Ultrasonic:Cavitation-driven dissolution methods remain experimental with limited commercial deployment.
Electrolysis commands the volume base. Membrane shows the steepest expansion trajectory.
End User:
Application intensity varies by user commitment to hydrogen protocols, with athletes and fitness enthusiasts driving replacement frequency and accessory attachment rates.
- Fitness Enthusiasts:Recreational athletes integrating hydrogen-enriched hydration into post-workout recovery regimens represent the most active replacement segment. This cohort purchases portable and smart variants through online channels with high subscription attachment for replacement filters. Demand concentrates in metropolitan markets with established fitness infrastructure.
- Athletes:Professional and competitive sports practitioners require validated dissolved hydrogen outputs for training protocols. Sports medicine practitioners in the US and athletic trainers in Japan drive institutional procurement decisions. The segment climbs the fastest as team and league adoption expands beyond individual purchases.
- Health Conscious:General wellness consumers seeking antioxidant benefits with less protocol rigor.
- General Consumers:Casual purchasers responding to marketing exposure with lower retention and replacement rates.
Fitness enthusiasts anchor volume. Athletes show the strongest growth momentum.
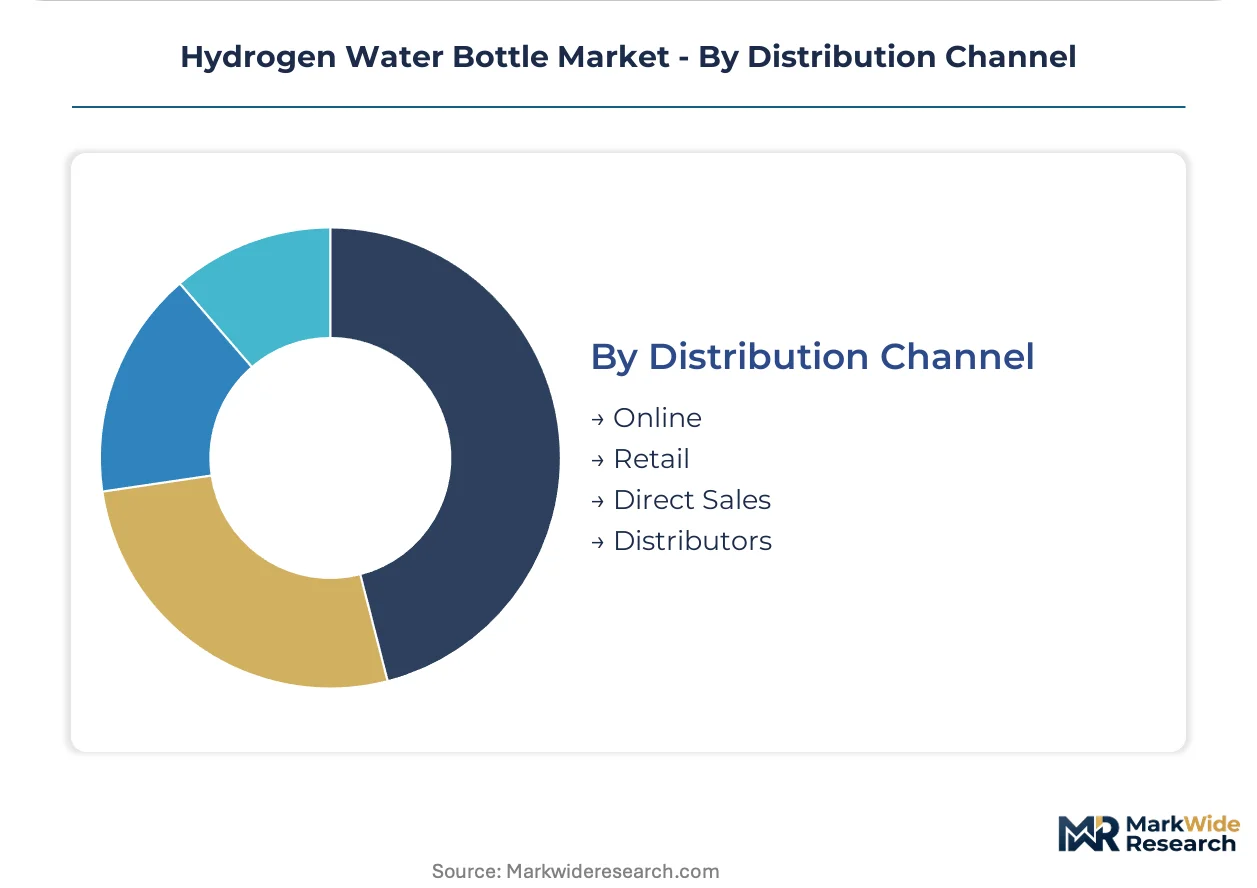
Distribution Channel:
Customer type and purchase sophistication dictate channel selection, with subscription relationships displacing transactional retail for engaged users.
- Online:Brand-direct websites and specialty wellness platforms capture smart and portable sales with subscription filter replenishment. Japan and South Korea lead this channel evolution due to mature e-commerce infrastructure and digital payment penetration. The channel is expanding most quickly as manufacturers bypass retail margin extraction.
- Retail:Electronics stores and pharmacy chains serve general consumers seeking physical product evaluation before purchase.
- Direct Sales:Wellness clinics and integrative medicine practices enable clinical-adjacent positioning with practitioner endorsement.
- Distributors:Regional wholesalers facilitate commercial and household system deployment with installation support.
Online leads by transaction volume. Direct sales shows the fastest expansion as B2B healthcare partnerships mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters for hydrogen water bottles concentrate in East Asian electronics corridors and North American direct-to-consumer hubs. Japanese and South Korean producers leverage mature electrolysis component supply chains. Chinese fabricators dominate membrane material sourcing and GB-certified device assembly.
Japan
Fitness enthusiasts and aging wellness consumers drive portable device demand in Tokyo and Osaka metropolitan corridors. The Ministry of Health, Labour and Welfare's food additive classification for hydrogen streamlines compliance for domestic manufacturers. Shizuoka Prefecture hosts concentrated electrolysis component suppliers serving premium brand assembly lines.
United States
Athletic trainers and integrative medicine practitioners propel smart-connected bottle adoption in California and Florida wellness markets. FDA scrutiny of hydrogen health claims under dietary supplement frameworks constrains promotional language. Denver and Austin emerge as direct-to-consumer brand headquarters leveraging regional fitness culture density.
China
Price-sensitive health-conscious consumers and gym chain procurement fuel volume demand in tier-one cities. SAMR's GB standards for electrical hydration devices create certification barriers for uncertified imports. Shenzhen and Dongguan manufacturing clusters dominate proton exchange membrane assembly and smart sensor integration.
South Korea
Quantified-self enthusiasts and beauty-wellness crossover consumers accelerate smart bottle replacement cycles in Seoul and Busan. MFDS oversight of hydrogen-infused product claims shapes marketing compliance requirements. Gyeonggi Province electronics corridors supply app-integrated dosage tracking hardware to domestic brands.
Germany
Clinical-adjacent wellness centers and sports medicine facilities adopt membrane-based systems in Munich and Berlin metropolitan areas. REACH substance restrictions compel electrode material substitutions away from certain platinum-group alloys. Baden-Württemberg precision engineering clusters develop catalytic surface alternatives for EU-compliant export production.
Hydrogen Water Bottle Market Competitive Landscape
Concentration sits with technology-differentiated specialists rather than diversified hydration conglomerates. The vendor base spans electrolysis engineering houses, smart hardware integrators, and membrane technology laboratories. Three archetypes dominate: proprietary electrolysis engineers, portable form factor optimizers, and connected wellness platform builders. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players secure membrane material supply and app ecosystem partnerships.
Among the named specialists, EVOLV and OCEMIDA occupy positions on the premium-technology vector, while IonBottles anchors the portable accessibility tier. EVOLV exemplifies the electrolysis engineering archetype through its sustained direct-to-consumer channel focus. OCEMIDA represents the connected wellness platform model with its app-integrated positioning. IonBottles sits within the form-factor optimization cluster, emphasizing handheld accessibility. These three companies collectively illustrate how technical differentiation and channel selection stratify competitive positioning in this emerging hardware category.
| Leading Market Players |
|---|
| Piurify |
| OCEMIDA |
| IonBottles |
| EVOLV |
| Dr. Water |
| PUREPEBRIX |
| Hydroh Bottle |
| Aqua Vital |
| Echo Flask |
| Others |
Pricing and Supply Chain Analysis
Platinum-group metal substitution for REACH-compliant electrode alloys in EU-bound production simultaneously shifts procurement toward Japanese and German catalytic suppliers while compressing margin structures for mid-tier manufacturers unable to absorb material cost premiums. This input pivot reconfigures supplier geography and forces pricing recalibration across export-oriented assembly lines.
Pricing Analysis
FDA dietary supplement claim substantiation requirements dictate the pricing tier structure by compelling marketing restraint that flattens brand premium capture. Three-tier pricing structure across premium, standard, and economy levels separates membrane-based clinical systems from electrolysis portables and unvalidated magnetic variants. Cost compression in the standard tier intensifies because platinum catalyst volatility feeds through to bill-of-materials pressure. Fitness enthusiasts exhibit highest price sensitivity due to replacement cycle frequency, while sports medicine facilities show lowest sensitivity given protocol validation requirements.
Supply Chain Analysis
Shizuoka Prefecture electrolysis component concentration underwrites premium device assembly capacity for Japanese brands serving domestic and export markets. Manufacturing draws from South Korean proton exchange membrane foundries and Chinese smart sensor integrators in Shenzhen-Dongguan corridors. Single-source vulnerability sits with platinum-group metal refining concentrated in South Africa and Russia. Distribution runs through direct-to-consumer brand websites and specialty wellness platforms, bypassing traditional retail margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
App-integrated dosage tracking ecosystems are reconfiguring this hardware category toward platform economics where data lock-in and subscription filter replenishment displace transactional device margins. Interoperability with fitness wearables and health record systems accelerates this shift.
For Market Incumbents: Consolidate membrane material supply through captive relationships with Japanese polymer laboratories or backward integration into catalytic surface engineering. Lock in SAMR GB certification pathways ahead of Chinese market expansion to preempt compliance barriers for later entrants. Threat of alkaline water substitute price competition demands channel control through subscription retention programs. For New Entrants and Emerging Players: Lead with clinical-adjacent wellness center partnerships in Germany and California where practitioner endorsement unlocks B2B procurement decisions. White-space concentrates in integrative medicine practices lacking validated hydrogen delivery protocols. Go-to-market angle should emphasize real-time concentration verification to differentiate from unvalidated magnetic alternatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed smart hardware integrators possessing app ecosystem traction but lacking electrolysis engineering depth. Five-to-ten year viability hinges on regulatory moat construction through multi-jurisdiction certification libraries. Signal to watch is FDA enforcement action trajectory against unsubstantiated health claims, which would accelerate consolidation toward substantiation-capable manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Proton exchange membrane IP partnerships with Japanese material labs unlock clinical-tier positioning. |
| Direct-to-Consumer Platform Launch | Brand-direct websites with subscription filter replenishment bypass retail margin extraction in Japan and South Korea. |
| Multi-Jurisdiction Certification Investment | Parallel FDA, CE marking, and SAMR GB compliance creates preferential access to three largest addressable markets. |
| Clinical Partnership Program | Sports medicine facility alliances in California and Germany institutionalize procurement beyond individual consumers. |
| Smart Sensor Integration | App-connected dosage tracking hardware from Gyeonggi Province suppliers enables biometric ecosystem positioning. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrolysis engineering directors, regulatory affairs leads at hydrogen device manufacturers, sports medicine procurement officers, and wellness clinic operators; and secondary validation through FDA warning letter databases, Japan MHLW food additive classification records, SAMR GB standard filings, and trade flow data from East Asian electronics corridors. Bottom-up demand modeling triangulated against top-down market sizing from component supply chain capacity.
Across the analysis window, forecasts applied segmented modeling across product type, technology variant, end-user commitment level, and distribution channel sophistication. CAGRs derived from electrolysis cell shipment volumes, membrane material procurement patterns, and smart sensor integration rates. Industry-specific inputs included platinum-group metal price trajectories and fitness wearable interoperability adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement continuity, stable Japan-South Korea trade flows, and proton exchange membrane yield improvements would require recalibration. Practitioners should keep alternative scenarios live as regulatory divergence across US, EU, and Chinese jurisdictions evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Carbonate Drink Maker Market
Beverages
Water Bottle Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Baby Drinking Water Market
Beverages
Morocco Bottled Water Market
Beverages
Premium Bottled Water Market
Beverages
Japan Kombucha Market
Beverages
Ready to Drink Shakes Market
Beverages
Popping Bobas Market
Beverages
Fermented Foods and Beverages Market
Beverages
South America Mate Market
Beverages
GCC Juice Market
Beverages
Fusion Beverages Market
Beverages
South America Dairy Based Beverages Market
Beverages
Sparkling Soda Market
Beverages
Asia-Pacific Energy Bar Market