
 North America Food Micronized Salt Market | 2026-2036
North America Food Micronized Salt Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Micronized Salt Market Analytics
A capital-intensity divergence between integrated evaporators and toll processors is bifurcating competitive tiers in the North America food micronized salt landscape. Cargill Incorporated leverages captive brine reserves and vertical logistics to sustain cost leadership across bulk food manufacturing accounts. Morton Salt anchors its position through dense retail and foodservice distribution networks, while Compass Minerals dominates highway-deicing cross-subsidies that lower food-grade production overheads.
Food micronized salt refers to sodium chloride processed to particle sizes typically below 100 microns, produced through vacuum evaporation or controlled milling to ensure rapid dissolution, uniform dispersion, and precise sodium delivery in formulated foods. Powdered salt leads the product type dimension due to its adoption in dry seasoning blends and instant soup bases where dispersion speed determines batch consistency. Processed meats represent the fastest-growing application segment as processors replace conventional crystal salt with micronized grades to accelerate cure penetration and reduce sodium per serving without altering sensory profiles.
FDA enforcement of updated sodium reduction targets and USDA FSIS labeling requirements shape product specifications and customer qualification protocols across U.S. food manufacturing. Health Canada and the Canadian Food Inspection Agency maintain parallel purity standards that create dual-compliance burdens for cross-border suppliers. Stakeholders must monitor evolving front-of-package sodium warning regulations at the state and provincial level, as these localized rules increasingly determine formulation choices ahead of federal harmonization.
Market Dynamics
Reformulation mandates from the FDA and Health Canada are compressing batch cycles and forcing micronized salt suppliers to qualify faster dissolution grades for sodium-reduced processed foods.
Growth Catalysts
- USDA FSIS labeling requirements:Processed meat processors must accelerate cure penetration while maintaining sodium targets, driving specification upgrades to sub-50 micron grades.
- Snack food reformulation:Dry seasoning blend manufacturers in the Great Lakes corridor demand rapid-dispersion salts to maintain batch consistency at reduced sodium levels.
- Vacuum evaporation technology:Controlled crystallization methods now achieve particle size distributions previously requiring mechanical milling, lowering energy intensity for food-grade output.
Market Restraints
- Natural gas price volatility:Vacuum evaporation operations in Michigan and New York face feedstock cost swings that compress margins on fixed-price food contracts.
- Great Lakes supply concentration:Over 70 percent of North American food-grade evaporated salt originates within 300 miles of Detroit, creating single-point vulnerability to winter logistics disruptions.
- Potassium chloride substitution:Partial sodium replacement in cured meats and snacks limits volume growth for pure micronized NaCl in certain applications.
Strategic Opportunities
- Quebec and Ontario processing clusters:Cross-border USDA-Health Canada dual-certified production capacity remains underdeveloped relative to demand from Montreal-Toronto food manufacturing corridors.
- Instant soup base applications:Freeze-dried broth manufacturers require sub-20 micron salts for reconstitution speed, a specification tier with limited qualified suppliers.
- Front-of-package sodium warning regulations:New York City and California state-level labeling rules create formulation urgency that outpaces federal harmonization timelines.
Industry Challenges
- Dual-certification timeline compression:Suppliers must parallel-track USDA FSIS and Canadian Food Inspection Agency approvals, stretching technical documentation resources.
- Particle size validation capex:Laser diffraction equipment and in-line monitoring systems require capital deployment that toll processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Micronized Salt Market |
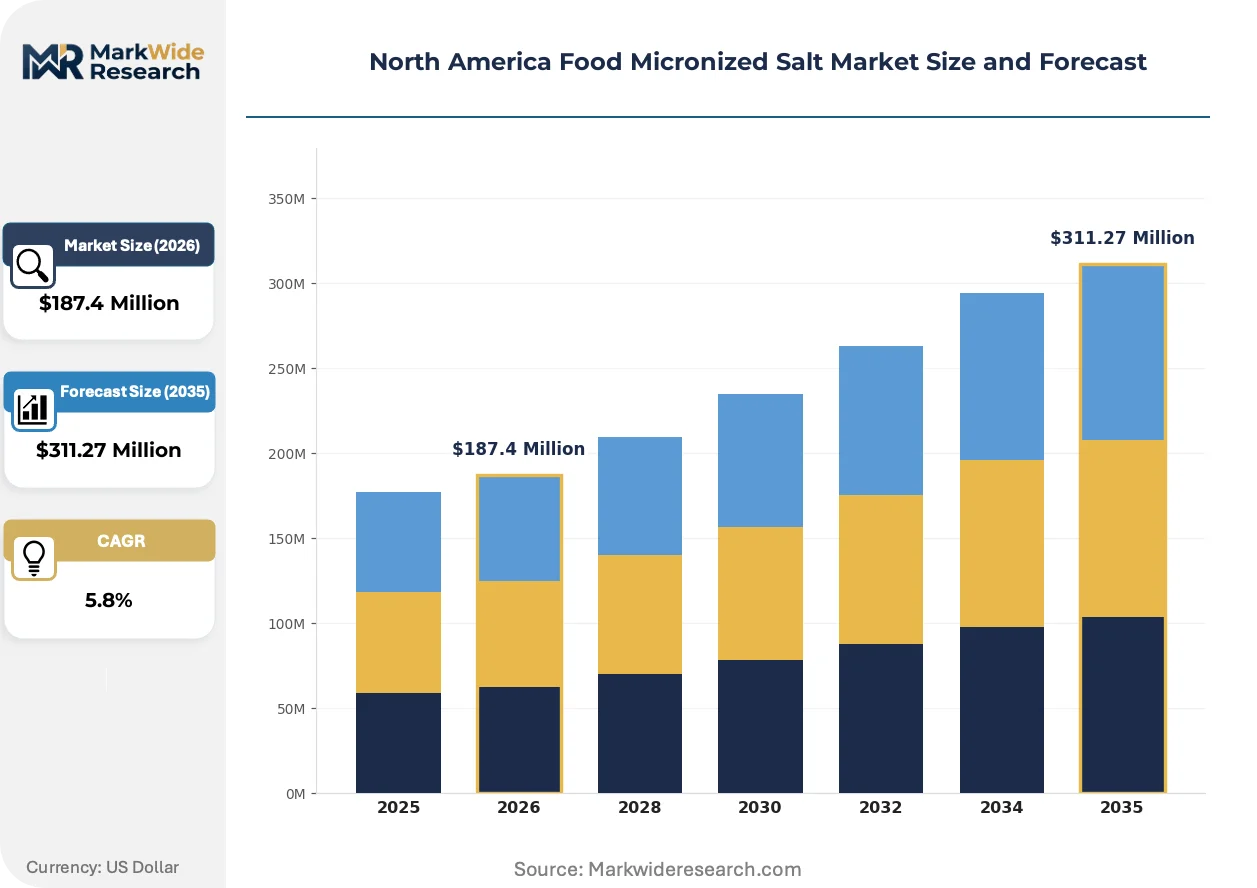
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake Salt, Granulated Salt, Powdered Salt, Coarse Salt Application: Snack Foods, Bakery Products, Sauces, Processed Meats Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Food Manufacturers, Restaurants, Households, Catering Services |
| Companies Covered | Cargill Incorporated, Morton Salt, Compass Minerals, K+S Aktiengesellschaft, ICL Group, DuPont, ADM, Tate & Lyle, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Micronized Salt Market Evolving Landscape
Equipment miniaturization and real-time process control are collapsing the scale advantages that historically separated integrated evaporators from regional toll processors.
Membrane filtration pretreatment is fragmenting the traditional brine preparation sequence. Mid-scale processors in Ohio and Pennsylvania now bypass bulk chemical softening through nanofiltration modules, cutting pretreatment energy by half. This capability shift enables smaller entrants to quote food-grade micronized salt without captive brine reserves, compressing minimum efficient scale in regional markets.
FDA updated sodium reduction targets issued in 2021 are tightening specification windows for cured meat and cheese categories. Processors must document sodium per serving reductions while maintaining water activity and shelf stability, forcing closer collaboration between salt suppliers and R&D labs. The USDA FSIS has responded with accelerated review protocols for reformulated products, though backlog persists in district offices.
Direct supplier relationships are displacing distributor intermediaries among top-20 food manufacturers. Procurement teams at major snack and meat processors now specify particle size distributions and dissolution curves in master service agreements, bypassing traditional ingredient distributors. This pattern concentrates most visibly in the Chicago and Minneapolis-St. Paul metropolitan areas, where procurement consolidation has eliminated two-step distribution for bulk micronized salt.
North America Food Micronized Salt Market Segmentation
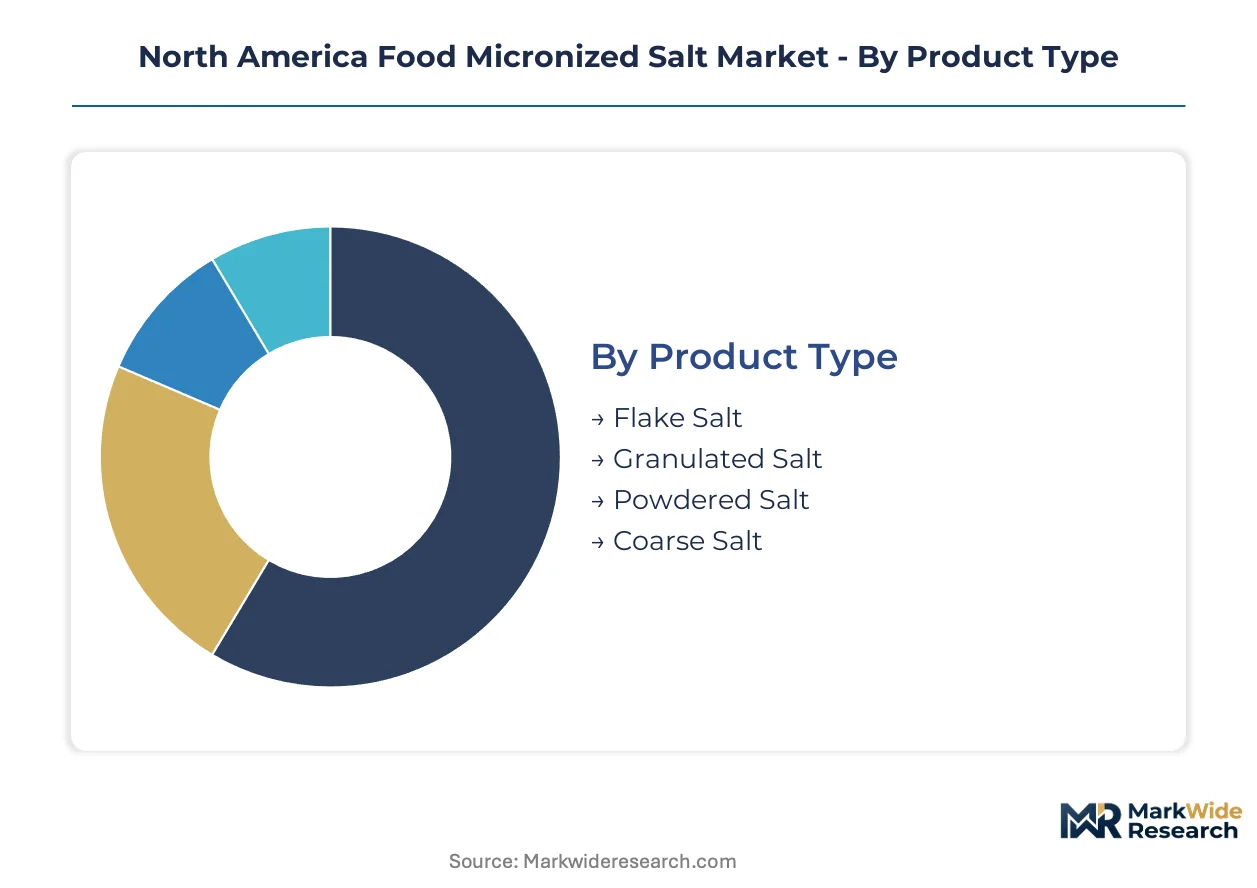
Particle size distribution determines dissolution kinetics and regulatory compliance pathways across North American food manufacturing. Specification tiers align with USDA FSIS cure acceleration requirements and FDA sodium reduction mandates, creating distinct procurement patterns by end-use.
Product Type:
FDA and USDA FSIS specifications differentiate dissolution performance thresholds, with sub-50 micron grades qualifying for accelerated cure protocols in processed meats while coarser fractions serve standard seasoning applications.
- Powdered Salt:Vacuum-evaporated particles below 100 microns achieve rapid dispersion in dry seasoning blends. Snack food manufacturers in the Great Lakes corridor specify these grades for batch consistency at reduced sodium levels mandated by updated FDA guidance.
- Granulated Salt:Controlled crystallization produces 100-300 micron distributions optimized for uniform coating on extruded snacks. Michigan and New York evaporators dominate supply to Chicago-area processors seeking consistent adherence with minimal fines generation.
- Flake Salt:Thin, plate-like crystals provide rapid dissolution with minimal mechanical processing. Bakery applications in Ontario and Quebec favor this morphology for dough systems where crystal integrity affects gluten development.
- Coarse Salt:Larger crystal fractions serve as topping salts and brine preparation feedstock. Limited food-grade demand concentrates in artisanal meat curing operations requiring controlled surface dissolution.
Powdered salt handles the majority of throughput; granulated salt is the fastest mover on share.
Application:
Cost tier stratification separates commodity seasoning from premium cure acceleration, with sodium reduction mandates compressing price spreads between functional grades.
- Processed Meats:Sub-50 micron specifications accelerate cure penetration while maintaining water activity targets. USDA FSIS labeling requirements force processors to document sodium per serving reductions, upgrading specification tiers across sausage and deli meat operations.
- Snack Foods:Dry seasoning applications demand rapid-dispersion salts for uniform coating on extruded and fried products. FDA sodium reduction targets drive reformulation in the Minneapolis-St. Paul and Chicago metropolitan procurement clusters.
- Bakery Products:Controlled particle size ensures even distribution in dough systems without localized salt pockets. Health Canada purity standards create dual-certification requirements for cross-border suppliers serving Ontario and Quebec baking operations.
- Sauces:Liquid and semi-liquid formulations require complete dissolution to prevent sedimentation. Mid-scale processors in Ohio and Pennsylvania leverage membrane filtration pretreatment to compete on food-grade specifications.
Snack foods absorb the largest volume share; processed meats are climbing the fastest.
Distribution Channel:
Customer type concentration determines channel viability, with direct procurement displacing intermediaries among top-20 food manufacturers while smaller accounts sustain distributor networks.
- Wholesale:Bulk rail and truck deliveries to Great Lakes food processing clusters dominate volume movement. Cargill and Morton leverage captive logistics for 25,000-pound minimum orders to major meat and snack manufacturers.
- Online Retail:E-commerce platforms serve artisanal processors and small-batch cure operations requiring sub-pallet quantities. Limited food-grade certification transparency creates qualification friction for cross-border Canadian purchasers.
- Supermarkets:Packaged consumer salt represents minimal micronized grade penetration. Retail channel concentration in private-label table salt leaves limited shelf space for specialized food manufacturing specifications.
- Specialty Stores:Restaurant supply and small-processor focused outlets stock intermediate packaging sizes. Geographic concentration in Chicago and Toronto metropolitan areas aligns with regional food manufacturing density.
Wholesale channels carry the dominant share; online retail is expanding most quickly.
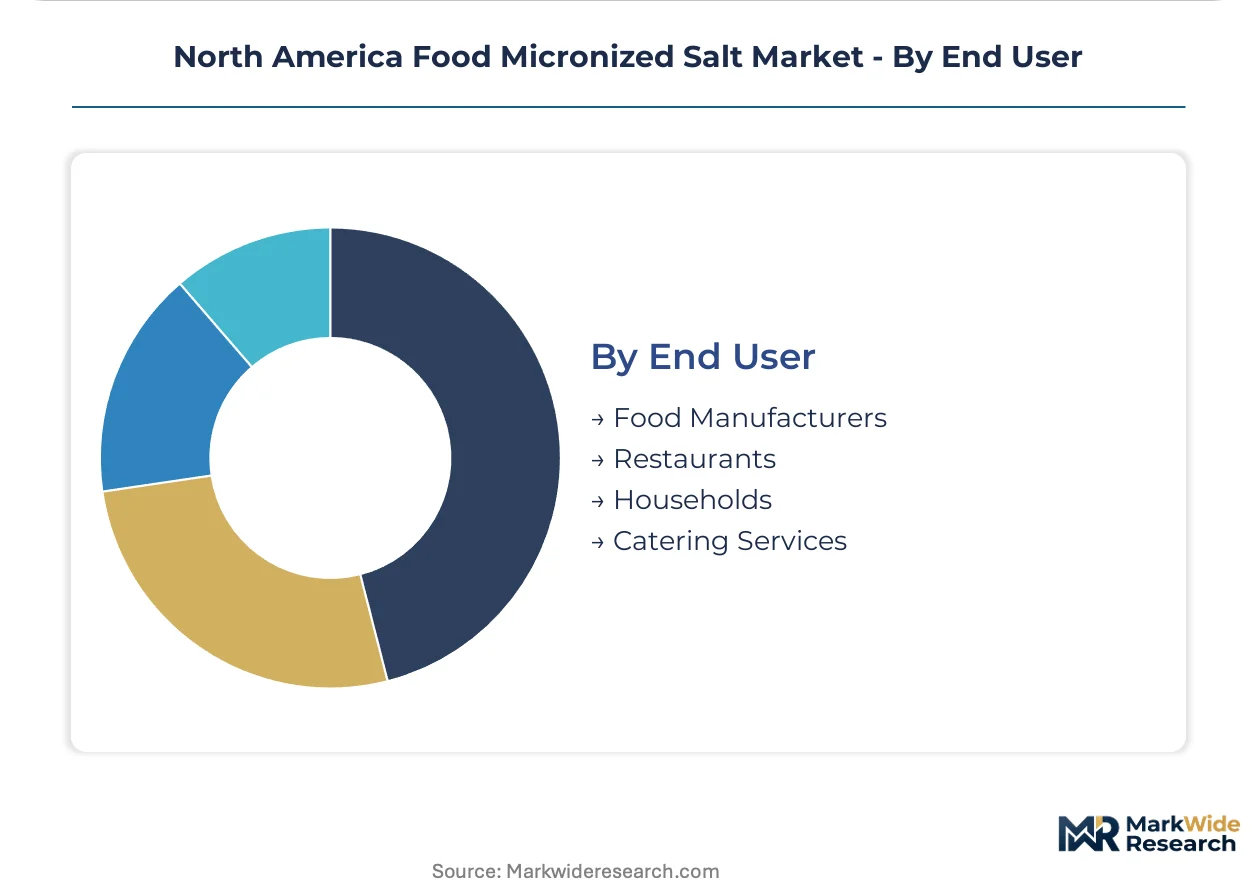
End User:
Volume scale and specification sophistication create distinct service requirements, with food manufacturers demanding certified dissolution curves while foodservice prioritizes cost consistency.
- Food Manufacturers:Master service agreements specify particle size distributions and dissolution curves, bypassing traditional distributors. Direct supplier relationships concentrate among top-20 snack and meat processors in Minneapolis-St. Paul and Chicago procurement offices.
- Restaurants:Chain operators and independent kitchens require consistent salinity without precision specification. Foodservice distribution networks prioritize price stability over particle size validation.
- Catering Services:High-volume event and institutional feeding operations demand reliable supply with minimal quality variation. Seasonal demand spikes stress regional distributor inventory management.
- Households:Consumer packaging represents minimal micronized grade penetration. Standard table salt specifications dominate retail shelf space with limited crossover to food manufacturing grades.
Food manufacturers command the greatest throughput; catering services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the U.S. Great Lakes corridor where captive brine reserves and integrated logistics create cost advantages over Canadian and Mexican supply alternatives. Michigan and New York evaporators command premium positions for sub-50 micron grades demanded by USDA FSIS-regulated meat processors.
United States
Snack food reformulation in the Minneapolis-St. Paul and Chicago metropolitan clusters drives specification upgrades to rapid-dispersion grades. FDA sodium reduction targets issued in 2021 compress batch cycles for cured meat processors seeking cure acceleration without sodium increases. Detroit-area vacuum evaporation facilities supply over 70 percent of domestic food-grade evaporated salt within a 300-mile radius.
Canada
Quebec and Ontario food manufacturing corridors generate cross-border demand for dual-certified production capacity. Health Canada and the Canadian Food Inspection Agency maintain purity standards that parallel USDA FSIS requirements, creating compliance burdens for suppliers serving Montreal-Toronto processors. Membrane filtration adoption in regional mid-scale facilities is challenging traditional brine preparation economics.
Mexico
Processed meat export operations to the United States require FDA-compliant micronized grades for sodium-reduced product lines. Mexican food processors face qualification friction when sourcing sub-20 micron specifications for instant soup base applications. Northern border states concentrate import-dependent supply chains vulnerable to cross-border logistics disruptions.
North America Food Micronized Salt Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America food micronized salt landscape. Integrated evaporators with captive brine reserves and vertical logistics networks dominate bulk food manufacturing accounts through scale economies. Toll processors compete on flexibility and regional proximity for mid-tier seasoning blend manufacturers. Strategic moves concentrate on membrane filtration pretreatment adoption and direct procurement relationship cultivation with top-20 food manufacturers.
Within the integrated evaporator tier, Cargill Incorporated and Morton Salt occupy positions shaped by captive resource control and dense distribution infrastructure respectively. Cargill leverages Great Lakes brine reserves for cost leadership across rail-served bulk accounts. Morton anchors market presence through foodservice and retail network density that supports regional toll processing relationships. Compass Minerals exemplifies the highway-deicing cross-subsidy model that lowers food-grade production overheads through shared evaporation infrastructure.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Morton Salt |
| Compass Minerals |
| K+S Aktiengesellschaft |
| ICL Group |
| DuPont |
| ADM |
| Tate & Lyle |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
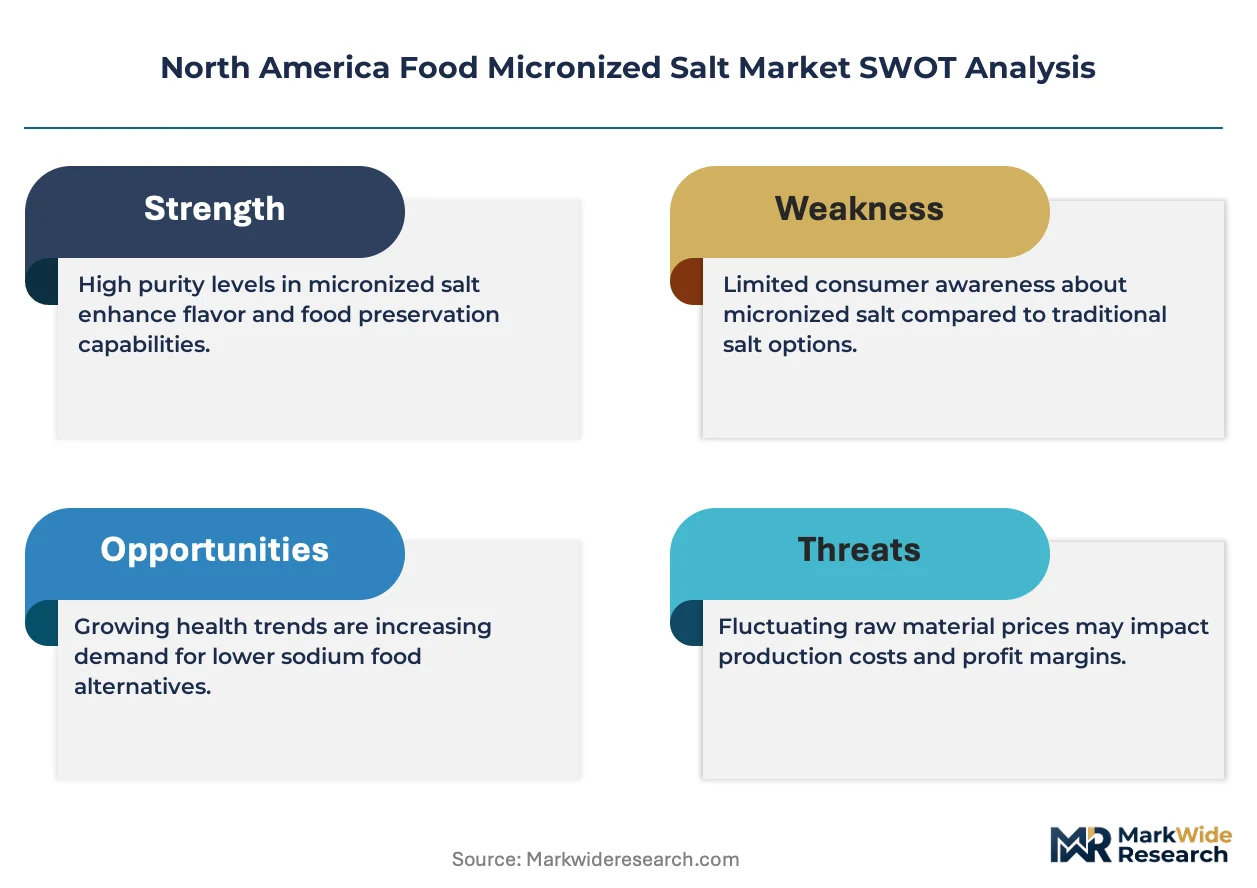
USDA FSIS and Health Canada dual-certification requirements gate supplier qualification and simultaneously stratify price tiers across the North America food micronized salt landscape. Food manufacturers demand documented dissolution curves and particle size validation that only integrated evaporators with captive brine reserves can provision at scale, compressing margins for toll processors unable to finance laser diffraction capex.
Pricing Analysis
Configured-to-order pricing for sub-50 micron cure-acceleration grades commands substantial premiums over standard powdered salt specifications. Contract-based long-term offtake dominates bulk procurement, with price differentiation hinging on certification tier and volume scale. Cost compression in mid-tier granulated salt is intensifying because membrane filtration enables Ohio and Pennsylvania processors to quote food-grade specifications without captive reserves. Small-batch artisanal cure operations exhibit highest price sensitivity; top-20 snack and meat processors prioritize dissolution performance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Detroit-area evaporators to Chicago and Minneapolis-St. Paul procurement clusters concentrate supply vulnerability on winter weather disruptions across Great Lakes rail corridors. Production draws from Michigan, New York, and Ontario brine reserves, with raw material dependencies spanning natural gas feedstock, specialized crystallization equipment, and FDA-compliant packaging materials. Single-source vulnerability pervades sub-20 micron instant soup base specifications where qualified suppliers remain scarce. Distribution runs through direct rail and truck deliveries to food manufacturing clusters, bypassing traditional intermediaries among volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among top-20 North American food manufacturers has shifted bargaining power decisively toward buyers, with direct supplier relationships displacing distributor networks across Chicago and Minneapolis-St. Paul metropolitan clusters.
For Market Incumbents: Consolidate membrane filtration pretreatment capabilities to defend against mid-scale Ohio and Pennsylvania entrants quoting food-grade specifications without captive brine reserves. Add dual-certified production capacity in Quebec and Ontario corridors to capture cross-border USDA-Health Canada demand that outpaces regional supply. Channel control through direct rail-served logistics remains the critical lever against toll processor flexibility.
For New Entrants and Emerging Players: Health Canada fast-track certification for sub-50 micron grades opens white-space in Montreal-Toronto food manufacturing corridors where dual-certified capacity remains underdeveloped. Target freeze-dried broth manufacturers requiring sub-20 micron reconstitution speeds, a specification tier with limited qualified competition. Go-to-market leverage rests on membrane filtration pretreatment adoption that halves energy intensity versus traditional chemical softening.
For Investors and Strategic Acquirers: FDA sodium reduction target enforcement reshapes the acquisition landscape toward suppliers with documented cure-acceleration formulations and existing USDA FSIS approval protocols. Long-term viability favors integrated evaporators with captive Great Lakes brine reserves and vertical logistics networks over toll processing models exposed to natural gas price volatility. Monitor front-of-package sodium warning regulation proliferation in New York and California as the signal for formulation urgency outpacing federal harmonization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Adoption | Ohio and Pennsylvania mid-scale processors bypass bulk chemical softening, cutting pretreatment energy by half. |
| Dual-Certification Capacity Buildout | Quebec and Ontario facilities capture cross-border demand from Montreal-Toronto food manufacturing corridors. |
| Direct Procurement Relationship Cultivation | Master service agreements with top-20 snack and meat processors eliminate distributor intermediaries. |
| Laser Diffraction Equipment Deployment | In-line particle size monitoring systems qualify sub-50 micron grades for USDA FSIS cure acceleration protocols. |
| Natural Gas Hedging Programs | Michigan and New York evaporators protect margins on fixed-price food contracts against feedstock volatility. |
Research Methodology
A spread of perspectives from vacuum evaporation plant managers, procurement leads at major snack and meat processors, distribution channel partners, and technical R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from FDA guidance documents, USDA FSIS labeling requirement filings, Health Canada purity standards, customs and trade data, and SEC 10-K disclosures from integrated salt producers. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Segmentation dimensions modeled include particle size distribution tier, application category, end-user scale, and regional production hub across the analysis window. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment. Forecast inputs incorporated FDA sodium reduction target compliance timelines, membrane filtration adoption curves, and direct procurement relationship penetration rates.
Underlying assumptions cover sustained FDA and Health Canada enforcement of sodium reduction mandates, with deviation risk concentrated in natural gas price volatility and winter logistics disruptions across Great Lakes corridors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market