
 Plant Based Preservatives Market | 2026-2036
Plant Based Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Preservatives Market Analytics
Enzymatic extraction and cold-processing technology is narrowing the efficacy gap between plant-derived and synthetic preservatives in high-moisture applications. Cargill Incorporated leverages its integrated oilseed supply chain to control raw material quality for tocopherol-based antioxidants. Kerry Group plc anchors its position through fermentation-derived vinegar concentrates tailored to clean-label meat applications. Corbion N.V. specializes in propionic acid alternatives from fermented cane sugar for bakery preservation.
Plant based preservatives comprise bioactive compounds extracted from botanical sources that inhibit microbial proliferation and oxidative degradation through phenolic, terpenoid, or organic acid mechanisms; typical specifications require minimum 40% active compound concentration in standardized extracts for commercial food use. Essential oils from rosemary and oregano sources lead value contribution due to high antioxidant potency and dual antimicrobial function. Fermented extracts represent the fastest-growing product category as vinegar-derived solutions displace benzoates in condiment and sauce applications. Powder forms capture expanding share in dry-mix and seasoning applications where liquid carriers introduce formulation constraints.
FDA GRAS determinations and EU Food Additives Regulation (EC) No 1333/2008 govern approval pathways and maximum usage levels for botanical preservatives in packaged foods. EFSA safety evaluations for novel essential oil extracts create compliance timelines that favor established suppliers with existing dossiers. Stakeholders must monitor evolving ECHA REACH registration requirements for concentrated botanical actives and anticipate state-level clean-label legislation in California and New York that could outpace federal standard-setting.
Market Dynamics
Reformulation mandates from major retail chains are compressing supplier qualification timelines and forcing botanical extract standardization investments ahead of regulatory deadlines.
Growth Catalysts
- EU Food Additives Regulation:Updated purity specifications for rosemary and oregano extracts accelerate displacement of synthetic antioxidants in packaged meats across Germany, France, and the Netherlands.
- Fermentation technology:Vinegar-derived propionic acid alternatives achieve cost parity with petroleum-based benzoates in high-volume bakery applications, unlocking clean-label positioning.
- California clean-label legislation:State-level procurement standards for school nutrition and institutional foodservice create mandated demand pull for plant-derived shelf-life solutions.
Market Restraints
- Raw material volatility:Weather-dependent yields for rosemary and oregano in Mediterranean growing regions create input cost instability that synthetic preservatives do not face.
- Supply concentration:Three specialized extract houses control over 60% of standardized carnosic acid supply, creating procurement risk for second-tier formulators.
- Technical limitation:Essential oil emulsification in high-moisture applications requires carrier systems that dilute active compound concentration below efficacy thresholds.
Strategic Opportunities
- Underpenetrated geography:India's FSSAI is streamlining approval pathways for botanical preservatives, opening formulation shifts in processed spice and ready-to-eat segments.
- Technology convergence:Cold-processing and nano-encapsulation convergence enables oil-soluble actives in aqueous beverage systems previously blocked by separation.
- Regulatory tailwind:South Korea's MFDS expanded GRAS-equivalent recognition for fermented rice extracts, creating first-mover positioning in kimchi and fermented vegetable exports.
Industry Challenges
- Specialized talent scarcity:Food microbiologists with dual expertise in botanical chemistry and formulation stability command premium compensation, constraining mid-cap R&D expansion.
- Certification timeline compression:EFSA novel food evaluations for new essential oil sources extend 18-24 months, delaying product launches against faster synthetic registration pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Preservatives Market |
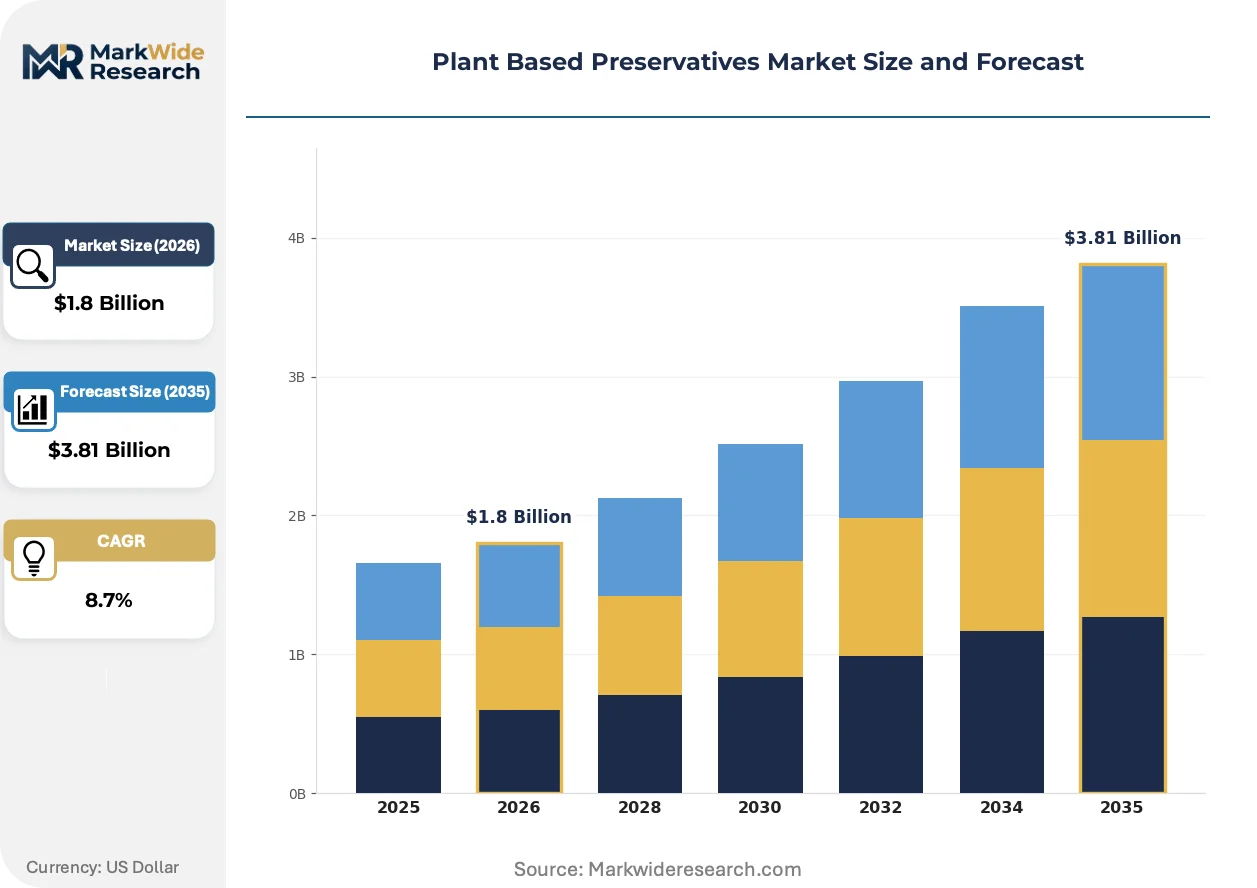
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Antioxidants, Essential Oils, Fermented Extracts, Vinegar Application: Food Preservation, Cosmetic Stabilization, Pharmaceuticals, Dietary Supplements Form: Liquid, Powder, Granular, Emulsified Source: Fruits, Herbs, Vegetables, Spices |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Kemin Industries Inc., Tate & Lyle, Kerry Group plc, Koninklijke DSM N.V., Corbion N.V., DuPont Nutrition & Biosciences, Kalsec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Preservatives Market Evolving Landscape
Digital supply chain mapping and extraction process virtualization are collapsing the development cycle for standardized botanical actives, compressing what required years into months.
Supercritical CO2 extraction with integrated fractionation is virtualizing the traditional solvent-based rosemary extract supply chain. Mid-sized meat processors in the US and Germany are adopting these precision-refined actives to meet retailer specification sheets. The technology is virtualizing quality control costs by embedding spectroscopic verification directly into production lines, eliminating third-party testing bottlenecks.
REACH registration requirements for concentrated botanical actives under ECHA oversight are tightening purity documentation for import into EU member states. Suppliers without existing substance dossiers face 12-18 month qualification delays versus established players. The regulation most affects essential oil concentrates above 80% active compound, forcing reformulators toward lower-concentration standardized extracts.
Direct procurement contracts between preservative suppliers and clean-label retail chains are displacing traditional distributor relationships in North American and European markets. Large-format grocers in Germany and the US now specify approved extract houses by name, removing formulation discretion from contract manufacturers. This channel consolidation concentrates volume with pre-qualified suppliers and marginalizes regional botanical processors lacking certification scale.
Plant Based Preservatives Market Segmentation
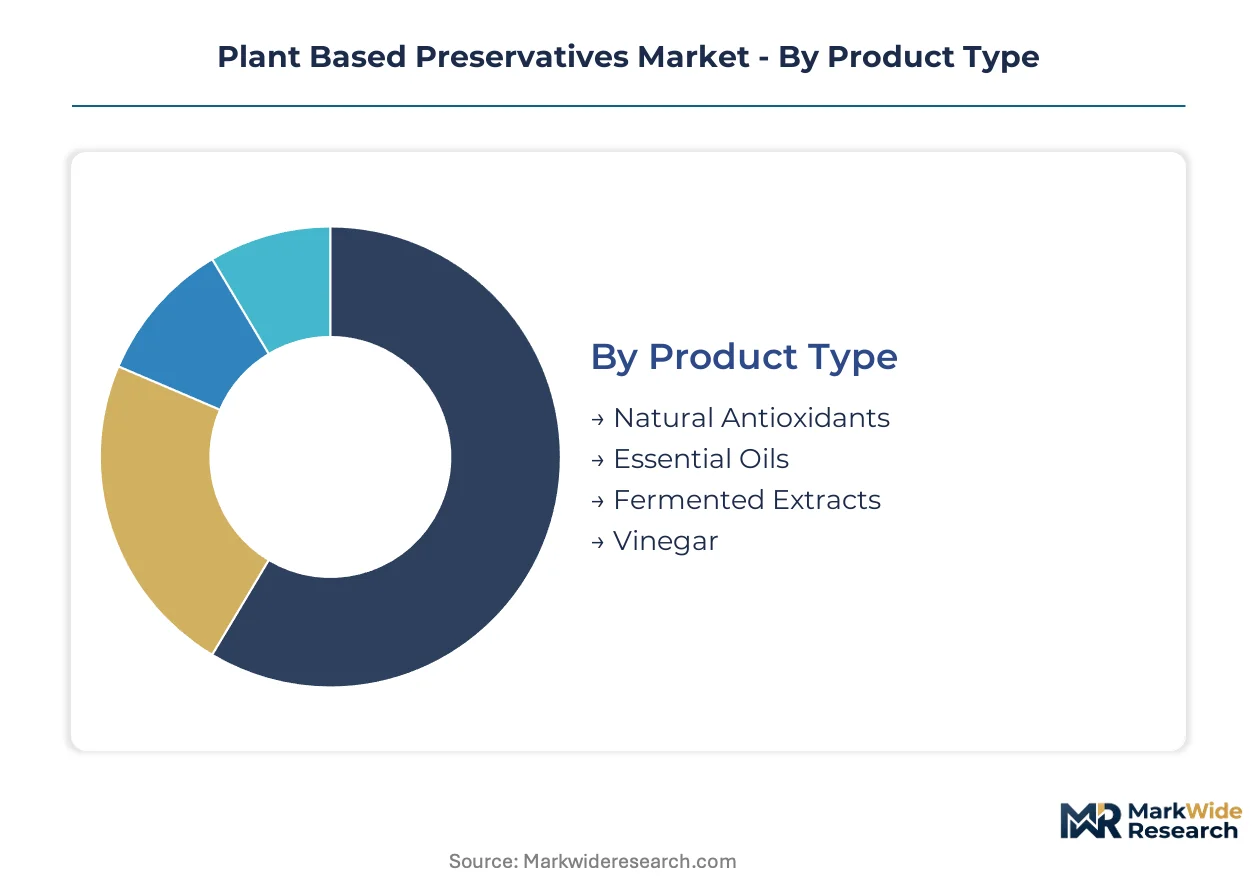
Segmentation in plant-based preservatives reveals how extraction chemistry, formulation physics, and end-use specifications create distinct commercial battlegrounds. Manufacturers configure production assets around these boundaries because cross-segment flexibility demands incompatible processing investments.
Product Type:
The use-case spectrum stretches from high-concentration antioxidant actives in meat processing to dilute fermented acids in condiment preservation, with each product category demanding dedicated extraction infrastructure and regulatory dossiers.
- Natural Antioxidants:Tocopherol concentrates and rosemary-derived carnosic acid formulations inhibit lipid oxidation in packaged meats and oils. Demand concentrates in German meat processing where retailer specifications mandate synthetic-free shelf-life extension for private-label sausages and cured products.
- Essential Oils:Terpenoid-rich extracts from oregano and thyme deliver dual antimicrobial-antioxidant function through phenolic compounds. Technical emulsification challenges in high-moisture sauces constrain penetration in aqueous applications despite superior potency versus synthetic alternatives.
- Fermented Extracts:Propionic acid alternatives from cane sugar fermentation displace benzoates in clean-label bakery applications.
- Vinegar:Acetic acid concentrates derived from grain or fruit fermentation provide pH reduction for condiment preservation.
The dominant share belongs to Natural Antioxidants, while Fermented Extracts is closing the gap fastest.
Application:
Cost tier stratification separates commodity food preservation from premium cosmetic and pharmaceutical grades demanding GMP certification and batch-level traceability.
- Food Preservation:Bakery, meat, dairy, and sauce applications consume standardized extracts at 40-80% active compound concentration. Procurement specifications from German retail chains and California institutional foodservice mandate botanical alternatives ahead of regulatory deadlines.
- Cosmetic Stabilization:Personal care formulations require low-odor, color-stable extracts compatible with emulsion chemistry. ECHA REACH registration for concentrated botanical actives creates 12-18 month qualification delays versus established suppliers with existing dossiers.
- Pharmaceuticals:USP-grade preservatives for oral and topical dosage forms demand validated manufacturing processes.
- Dietary Supplements:Softgel and tablet applications prioritize oxidative stability of omega oils and fat-soluble vitamins.
Food Preservation commands volume leadership, though Cosmetic Stabilization generates the steepest margin expansion.
Form:
Volume concentration in dry-mix applications drives powder capacity investments, while liquid extraction assets serve high-throughput meat and dairy processors.
- Liquid:Solvent-based or supercritical CO2 extracts dissolve directly into oil-phase food matrices without carrier addition.
- Powder:Spray-dried or adsorbed actives on maltodextrin carriers suit seasoning blends and dry bakery premixes where moisture introduction risks caking. Powder forms capture expanding share in dry-mix applications where liquid carriers introduce formulation constraints.
- Granular:Free-flowing particulates with controlled dissolution rates for slow-release preservation in fermented vegetable applications.
- Emulsified:Pre-dispersed oil-in-water systems overcome essential oil separation in beverage and sauce matrices.
Powder maintains the installed base advantage, yet Emulsified formats are gaining share fastest in beverage reformulation.
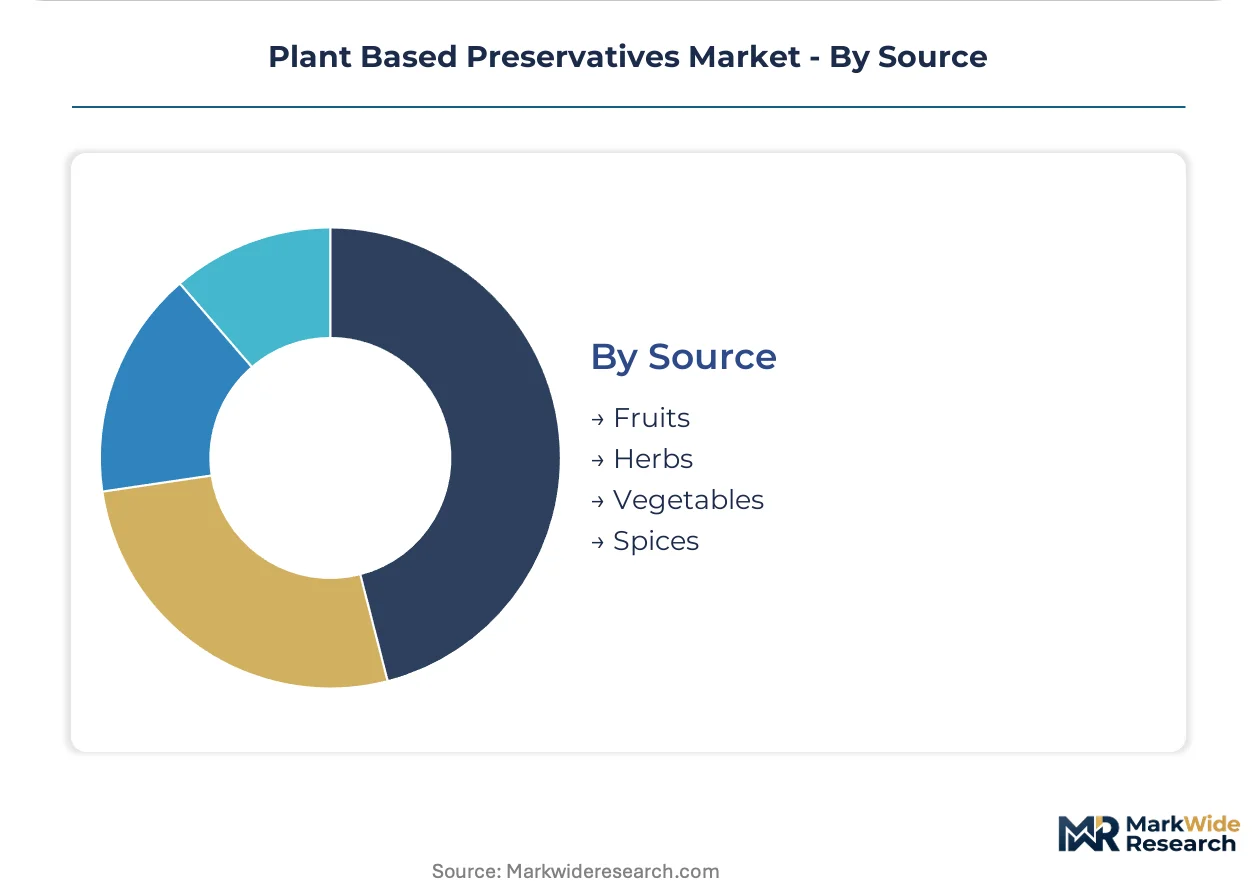
Source:
Supply concentration in Mediterranean herb cultivation creates procurement risk that fruit and vegetable alternatives seek to diversify.
- Fruits:Grape seed and citrus bioflavonoid extracts provide oligomeric proanthocyanidins for cosmetic and nutraceutical stabilization.
- Herbs:Rosemary and oregano cultivation in Spain and Morocco supplies the majority of commercial carnosic acid and carvacrol concentrates. Weather-dependent yields in Mediterranean growing regions create input cost instability unmatched by petroleum-based synthetics.
- Vegetables:Onion and garlic allium extracts deliver sulfur-based antimicrobial compounds for savory food applications.
- Spices:Clove eugenol and cinnamon cinnamaldehyde provide high-potency phenolic preservatives for ethnic sauce formulations.
Herbs anchor current supply security, while Fruits are expanding cultivation acreage fastest to reduce weather dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean-label retail procurement specifications concentrate demand among meat processors in Germany, institutional foodservice operators in California, and bakery manufacturers across Western Europe. These buyer archetypes drive formulation shifts toward standardized botanical extracts with documented regulatory dossiers.
Germany
Private-label sausage and cured meat reformulation dominates extract procurement, with retailers mandating synthetic-free shelf-life extension. EFSA safety evaluations for novel rosemary extracts create compliance timelines favoring established suppliers. The Bavarian meat processing cluster around Munich drives concentrated demand for carnosic acid formulations.
United States
California school nutrition and institutional procurement standards create mandated demand pull for plant-derived solutions. FDA GRAS notification pathways for botanical extracts accelerate formulation shifts away from synthetic alternatives. Midwest meat processors and West Coast sauce manufacturers anchor regional adoption patterns.
France
Clean-label positioning in premium dairy alternatives drives essential oil procurement for oxidative stability. EU Food Additives Regulation (EC) No 1333/2008 governs maximum usage levels for packaged applications. The Île-de-France food manufacturing corridor concentrates reformulation activity among contract processors.
India
Processed spice and ready-to-eat segment expansion creates formulation opportunity for botanical preservatives. FSSAI streamlines approval pathways for standardized extracts, reducing qualification timelines. Maharashtra and Gujarat processed food clusters drive initial procurement volumes for fermented extract alternatives.
South Korea
Kimchi and fermented vegetable export markets demand GRAS-equivalent recognition for rice-derived preservation solutions. MFDS expanded botanical preservative approvals, creating first-mover positioning for clean-label positioning in Asian condiment segments. The Seoul Capital Area food technology corridor anchors domestic formulation expertise.
Plant Based Preservatives Market Competitive Landscape
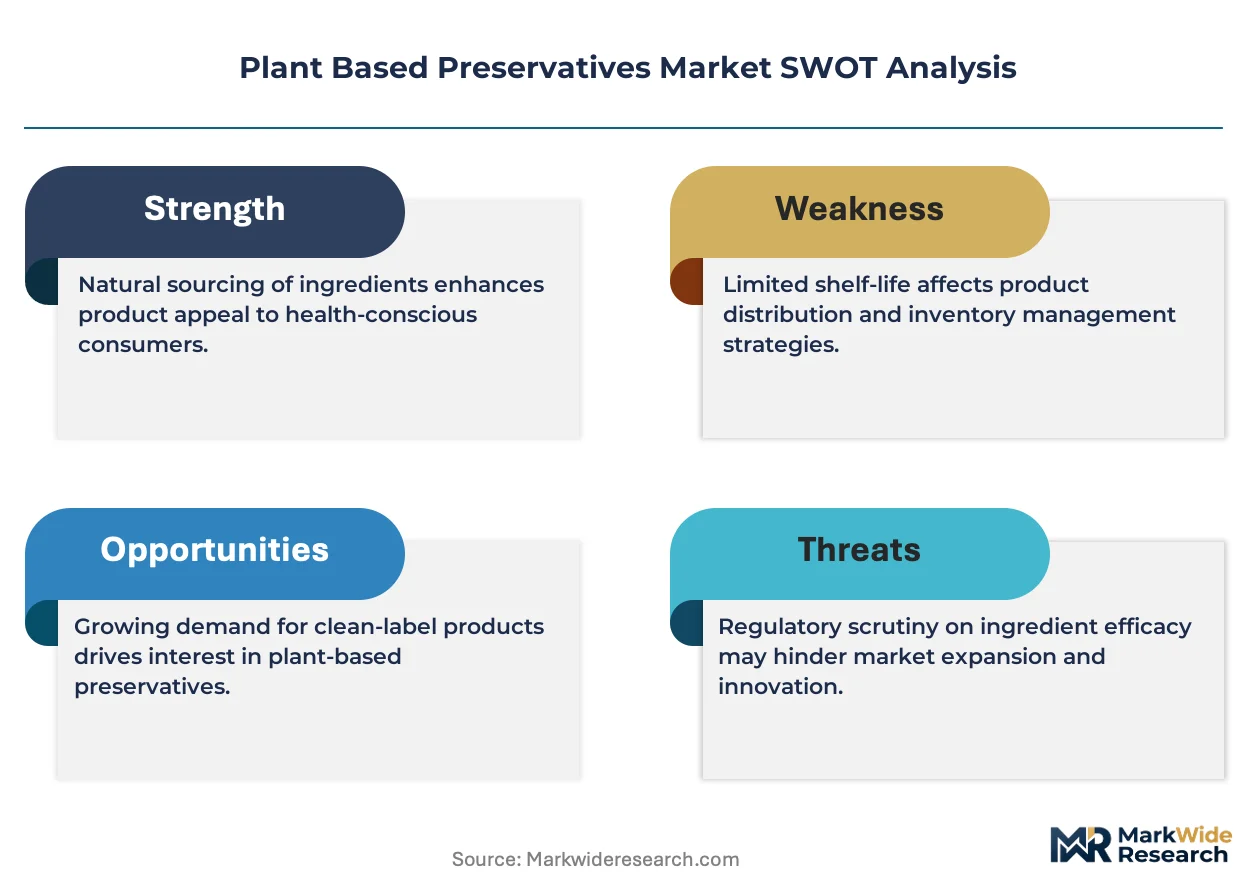
Channel-controlling players compete with product-specialist players across tiered supply positions. Three specialized extract houses dominate standardized carnosic acid supply, while integrated agribusiness operators leverage captive raw material access. Strategic archetypes include oilseed-integrated antioxidant suppliers, fermentation-derived acid specialists, and precision-extraction technology providers. Competitive moves concentrate on backward integration into Mediterranean herb cultivation and supercritical CO2 extraction capacity expansion.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify supply chain control strategies, while Kerry Group plc occupies a position among fermentation-derived solution providers. These entities represent distinct competitive vectors: seed-to-extract vertical coordination versus biotechnology-enabled acid production. Corbion N.V. anchors the specialty fermentation segment with cane sugar-derived propionic acid alternatives.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Kemin Industries Inc. |
| Tate & Lyle |
| Kerry Group plc |
| Koninklijke DSM N.V. |
| Corbion N.V. |
| DuPont Nutrition & Biosciences |
| Kalsec Inc. |
| Others |
Value Network & Pricing Analysis
Raw material volatility in Mediterranean rosemary and oregano cultivation determines both the spread between premium standardized extracts and commodity-grade alternatives and the geographic configuration of extraction capacity investments. Buyers facing procurement concentration risk among three specialized extract houses accept cost-plus contracts with agricultural commodity indexation to secure carnosic acid supply.
Pricing Analysis
Cost-plus contracts with agricultural commodity indexation dominate long-term procurement between German meat processors and Mediterranean extract houses. Price differentiation rests on EFSA dossier completeness and supercritical CO2 extraction certification tiers. Cost compression in mid-tier rosemary extracts is intensifying because of weather-driven yield instability in Spanish and Moroccan growing regions. Institutional foodservice buyers in California exhibit highest price sensitivity, while premium private-label retailers in Germany prioritize supply security over unit cost.
Supply Chain Analysis
Tariff exposure between Morocco and EU member states dominates supply chain risk calculus for carnosic acid procurement. Extraction capacity concentrates in Spain, Morocco, and southern France, drawing from weather-dependent herb cultivation that rests on irrigation infrastructure. Single-source vulnerability persists for standardized extracts above 80% active compound concentration. Distribution runs through direct procurement contracts with large-format retail chains that specify approved extract houses by name.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual expertise in botanical chemistry and food microbiology commands premium compensation that constrains mid-cap R&D expansion, creating a bottleneck that shapes competitive positioning across formulation tiers.
For Market Incumbents: Build regulatory dossier moats through preemptive EFSA novel food submissions for emerging essential oil sources. Backward integration into captive rosemary cultivation in Spain and Morocco secures raw material quality for tocopherol-based antioxidant lines. Capacity expansion in supercritical CO2 extraction addresses technical emulsification limitations that constrain penetration in high-moisture sauce applications. For New Entrants and Emerging Players: India's FSSAI-streamlined approval pathways offer the most penetrable geographic entry point for fermented extract alternatives in processed spice and ready-to-eat segments. South Korea's MFDS-expanded GRAS-equivalent recognition for rice-derived solutions creates white-space positioning in kimchi export markets. Technology licensing partnerships with established extract houses accelerate qualification timelines versus de novo EFSA submissions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-extraction technology providers with existing regulatory dossiers. Long-term viability hinges on backward integration into Mediterranean herb cultivation and nano-encapsulation capability for aqueous beverage applications. Monitor ECHA REACH registration progress for concentrated botanical actives as an inflection indicator for import qualification delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Herb Cultivation | Captive rosemary and oregano supply in Spain and Morocco insulates against weather-driven yield volatility. |
| Supercritical CO2 Capacity Expansion | Precision-refined actives meet German retailer specification sheets for synthetic-free meat preservation. |
| Fermentation Technology Licensing | Vinegar-derived propionic acid alternatives unlock clean-label bakery positioning at cost parity with benzoates. |
| Direct Retail Chain Procurement Contracts | Large-format grocer specification removes formulation discretion from contract manufacturers in North America. |
| Nano-Encapsulation R&D Investment | Oil-soluble actives in aqueous beverage systems overcome essential oil emulsification barriers. |
Research Methodology
Initial hypotheses were tested against primary input from extraction plant managers, procurement leads at German meat processors, regulatory affairs specialists at botanical extract houses, and clean-label retail category buyers, and refined through secondary validation against EFSA safety evaluations, EU Food Additives Regulation (EC) No 1333/2008 documentation, FDA GRAS notification records, and customs trade data for concentrated botanical actives. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, form, and source segmentation dimensions.
Demand-supply balance framing anchored the analytical approach across the projection horizon, modeling natural antioxidants, essential oils, fermented extracts, and vinegar-derived solutions against meat processing, bakery, dairy, and condiment end-use demand. CAGRs were derived from segment-level growth trajectory analysis incorporating raw material yield assumptions, regulatory approval timeline distributions, and formulation shift elasticity in clean-label retail procurement.
Practitioners should monitor EFSA novel food evaluation backlogs, ECHA REACH registration delays for concentrated botanical actives, and state-level clean-label legislation progression in California and New York for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Russia Feed Additives Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Global Oleate Esters Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Gelatin Films Market