
 Non-Alcoholic Drinks Market | 2026-2036
Non-Alcoholic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Drinks Market Outlook
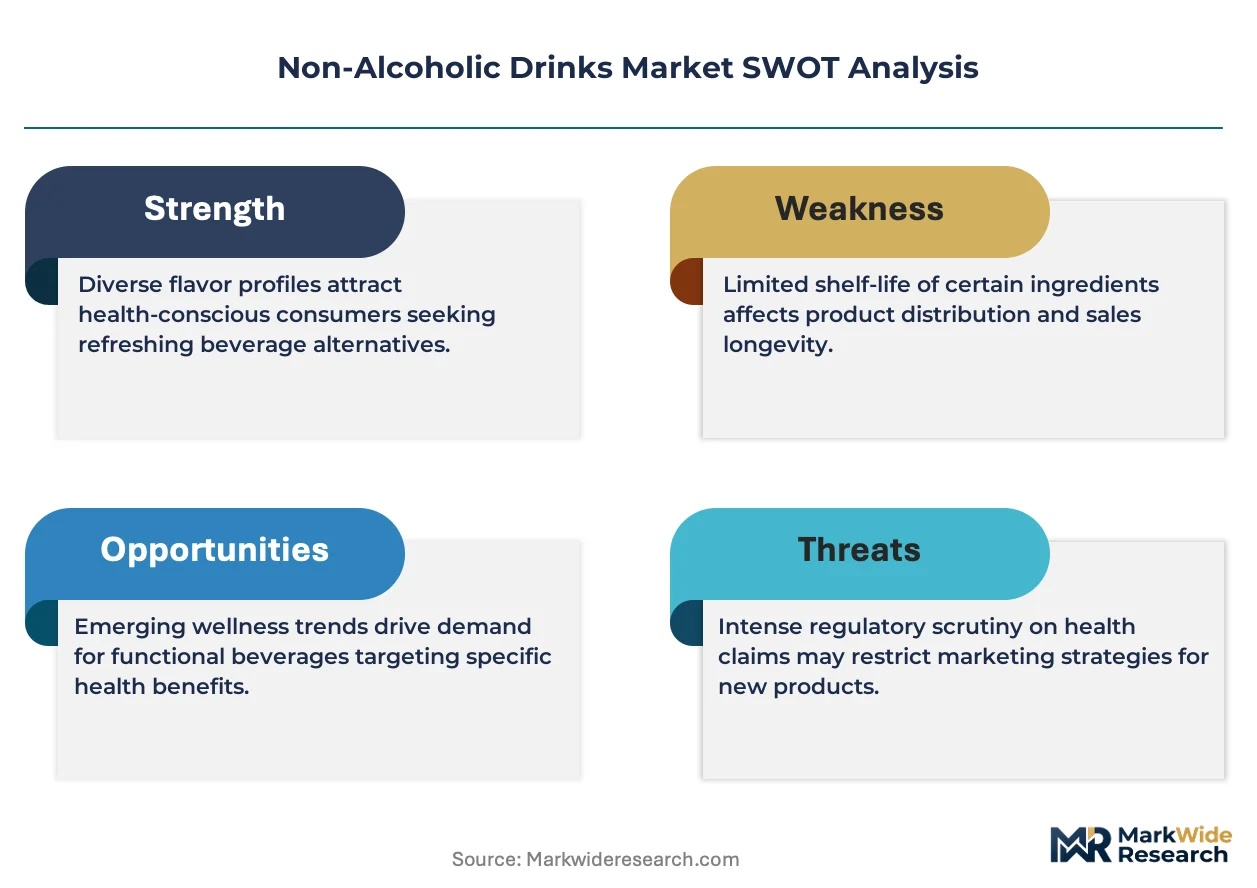
The capital-intensity divergence between bottling infrastructure and digital-native direct-to-consumer platforms is collapsing as scale advantages shift toward flexible manufacturing. PepsiCo leverages its North American bottling network to sustain cost leadership in carbonated soft drinks. Nestlé anchors premium pricing through specialized mineral water sourcing and purification technology. Red Bull GmbH competes through event marketing dominance and controlled distribution in convenience channels.
Non-alcoholic drinks encompass formulated beverages excluding ethanol, typically containing water, sweeteners, acids, flavoring agents, and functional additives processed through blending, carbonation, pasteurization, or aseptic filling to achieve shelf stability and sensory consistency. Their primary commercial purpose is to deliver hydration, refreshment, caffeine, vitamins, or botanical extracts to consumers across retail and foodservice environments. Soft drinks retain the largest revenue pool but face margin compression from sugar taxation, while bottled water commands volume leadership with lower per-unit profitability. Sports drinks represent the fastest-expanding category as fitness culture permeates emerging economies and functional claims attract premium positioning. Online retailers are gaining share rapidly, though supermarkets still control the majority of volume throughput.
The FDA enforces Nutrition Facts labeling and GRAS substance approvals that constrain formulation choices and marketing claims for beverages sold in the United States. EFSA and national regulators across Europe apply parallel standards through the EU Food Information to Consumers Regulation, creating compliance complexity for multinational portfolios. Stakeholders must monitor how front-of-pack labeling schemes and sugar taxation spreads across jurisdictions, as these rules will determine which product formats and sweetness systems retain market access.
Market Dynamics
Sugar taxation cascades across jurisdictions are forcing systemic reformulation of carbonated portfolios, while aseptic cold-fill technology collapses the capital barrier between premium craft and mass-market scale.
Growth Catalysts
- Functional ingredient innovation:Microencapsulation of vitamins and botanicals enables stable shelf-life extension without thermal degradation. Beverage manufacturers in Germany and Japan are deploying this for immunity-positioned waters.
- Front-of-pack labeling mandates:Nutri-Score adoption across France, Belgium, and the Netherlands creates competitive pressure to reformulate for higher grades. Manufacturers achieving A/B ratings gain retail placement advantages.
- China's urban middle-class expansion:Tier-1 and Tier-2 city consumers trade up from boiled tap water to premium bottled and plant-based alternatives. This concentration of purchasing power accelerates category premiumization.
Market Restraints
- Aluminum can supply concentration:Three global packaging conglomerates control 70% of beverage-grade can supply. Any disruption at their smelter or coating facilities ripples through bottling schedules.
- Natural flavor extract volatility:Vanilla, citrus oils, and coffee extracts face harvest-driven price swings. Madagascar vanilla cyclone seasons and Brazilian orange frost events compress margins unpredictably.
- Technical limitation in sugar replication:No approved high-intensity sweetener fully replicates sucrose's mouthfeel and bulking properties. Stevia and monk fruit blends leave lingering aftertastes that limit consumer acceptance.
Strategic Opportunities
- India's underpenetrated functional beverage market:FSSAI's recent clarity on probiotic and vitamin fortification claims opens formulation pathways. Urban millennials in Mumbai and Bangalore show willingness to pay 40% premiums for verified health benefits.
- Direct-to-subscription channel innovation:Customizable flavor profiles and replenishment algorithms bypass traditional retail slotting fees. This model captures consumer data for iterative product development.
- EU Green Deal packaging mandates:The shift to 100% recyclable or reusable containers by 2030 creates first-mover advantages for brands with biodegradable bottle technologies or refill infrastructure.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning microbiology, sensory science, and regulatory compliance commands premium salaries. Smaller brands struggle to staff R&D functions competitively.
- Legacy ERP integration complexity:Real-time traceability requirements for FDA Food Safety Modernization Act compliance clash with decades-old manufacturing execution systems. Retrofit costs strain mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Drinks Market |
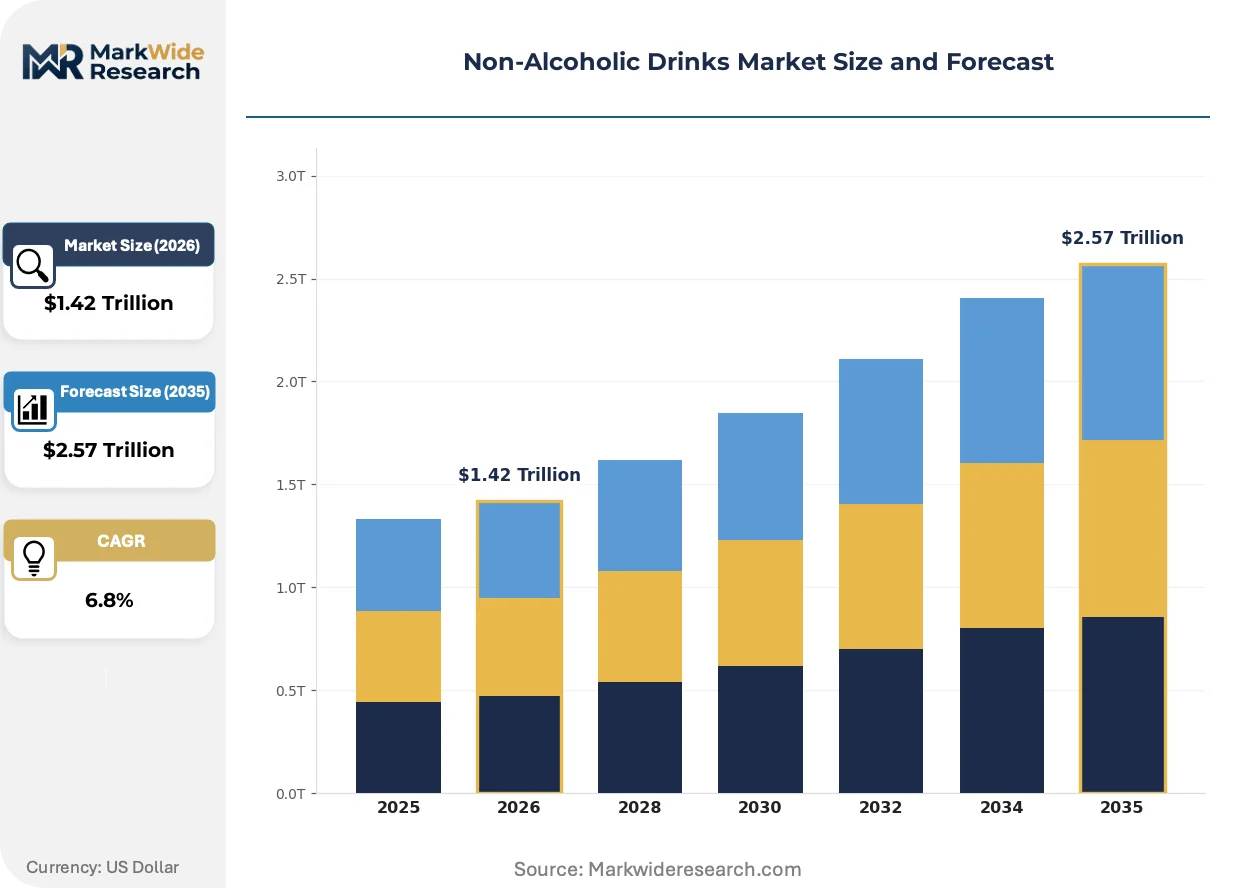
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.57 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Juices, Bottled Water, Sports Drinks Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores End User: Households, Restaurants, Cafes, Events Flavor Type: Citrus, Berry, Herbal, Spicy |
| Companies Covered | Danone, Keurig Dr Pepper, The Coca-Cola Company, The Kraft Heinz Company, Monster Beverage Corporation, PepsiCo, Red Bull GmbH, Suntory Holdings Limited, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Drinks Market Strategic Shifts
Aseptic processing advances and precision fermentation are collapsing traditional boundaries between natural extraction and synthetic production. These shifts reconfigure cost structures and sourcing strategies simultaneously.
Cold-aseptic filling lines are supplanting hot-fill pasteurization for high-acid beverages. Premium juice and functional water brands in California and São Paulo adopt these systems to preserve heat-sensitive vitamins and fresh taste profiles. This technology is supplanting the need for preservative additives and enabling clean-label claims that command retail price premiums.
The FDA's updated Nutrition Facts labeling requirements and added-sugar callouts are compressing permissible serving sizes. Reformulation teams must balance portion reduction against consumer value perception. Carbonated soft drink portfolios face the steepest compliance costs as legacy recipes require systematic sweetener system overhauls.
Subscription-based replenishment models are capturing urban households seeking convenience without store visits. Direct-to-consumer platforms in London, New York, and Singapore bypass traditional supermarket slotting fees while capturing granular consumption data. This channel shift concentrates initially among fitness-oriented consumers who prioritize functional ingredient transparency over impulse purchase accessibility.
Non-Alcoholic Drinks Market Segmentation
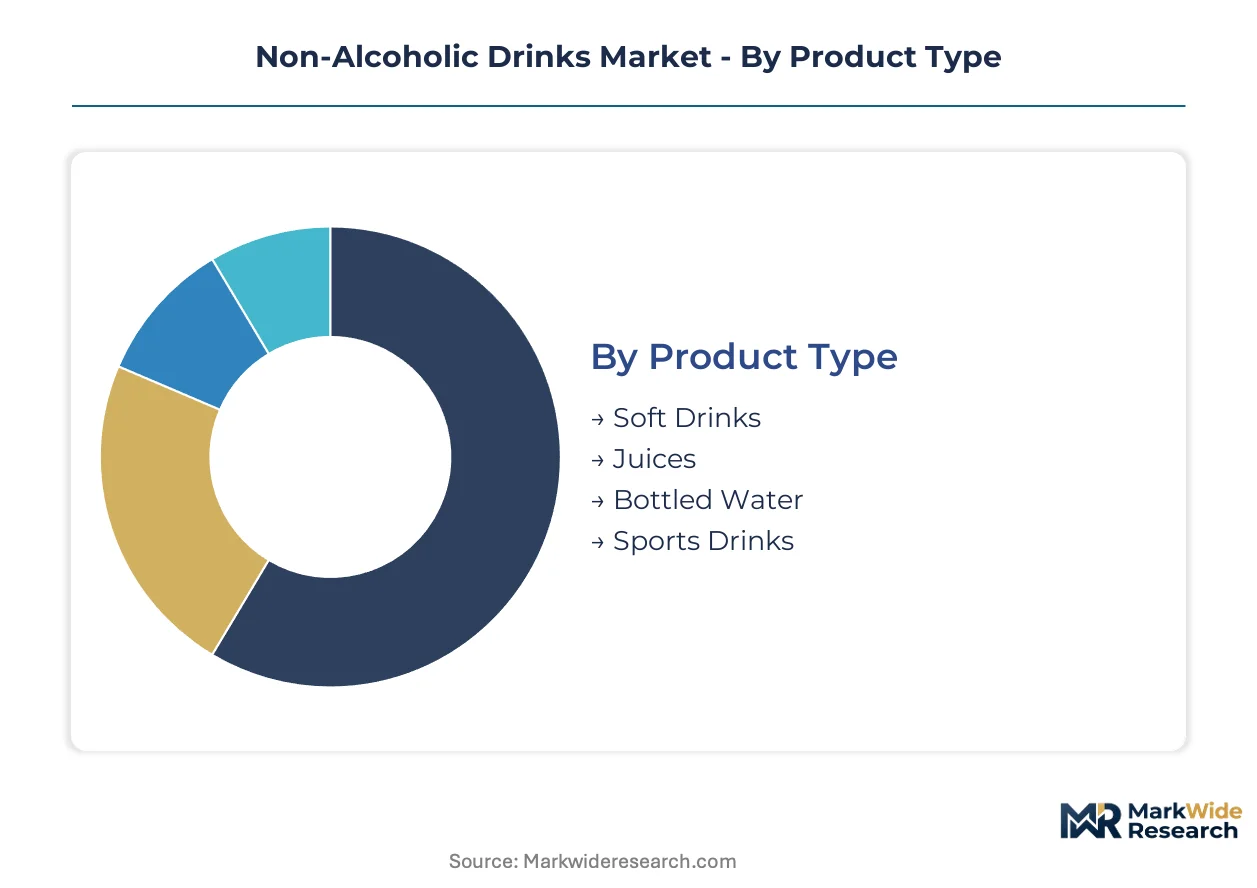
Channel mix dynamics in non-alcoholic beverages determine margin capture and brand positioning. Supermarkets still control volume throughput, yet online retailers are gaining share rapidly through subscription replenishment models.
Product Type:
Supermarkets and convenience stores anchor volume for carbonated and hydration-focused formats, while specialty stores and online channels concentrate premium functional offerings.
- Soft Drinks:Carbonated formulations with sugar or high-intensity sweetener systems face reformulation pressure from FDA added-sugar labeling and cascading sugar taxes. Demand concentrates in the United States among price-sensitive households trading down from premium alternatives, though per-unit margins compress as portion sizes shrink to meet compliance thresholds.
- Sports Drinks:Electrolyte and carbohydrate solutions target fitness-oriented consumers through gyms, marathons, and direct subscription channels. China's urban middle-class in Tier-1 cities drives fastest expansion as gym culture penetrates emerging economies and functional claims justify premium positioning.
- Juices:NFC and concentrate formats compete on cold-aseptic processing claims.
- Bottled Water:Still and sparkling variants command volume leadership with lower profitability per liter.
Soft Drinks dominates installed base. Sports Drinks is where expansion concentrates.
Distribution Channel:
Margin structures diverge sharply between high-frequency convenience formats and data-rich direct channels.
- Supermarkets:Multi-brand shelf space commands slotting fees that privilege scale players with portfolio breadth. Retail buyers in Germany and France increasingly use Nutri-Score ratings as placement criteria, advantaging reformulated products with A/B grades.
- Online Retailers:Customizable flavor profiles and replenishment algorithms bypass traditional retail economics. DTC platforms in London, New York, and Singapore capture granular consumption data that feeds iterative product development cycles.
- Convenience Stores:Impulse-driven single-serve purchases concentrate in urban transit corridors.
- Specialty Stores:Curated premium and craft selections target enthusiast segments with higher willingness to pay.
Supermarkets anchor volume throughput. Online Retailers capture margin expansion.
End User:
Consumption occasion shapes formulation intensity and packaging format selection across the value chain.
- Households:Multi-pack and bulk formats dominate pantry stocking behavior, with subscription models penetrating fitness-oriented segments seeking ingredient transparency.
- Restaurants:Fountain systems and portion-controlled service drive concentrate economics, though sugar taxation in jurisdictions like the United Kingdom and South Africa forces menu reformulation.
- Cafes:Premium ready-to-drink and barista-compatible formats concentrate in urban centers.
- Events:Sponsorship-linked exclusive pouring rights anchor brand visibility for energy and sports drink portfolios.
Households represent the largest addressable base. Restaurants concentrate B2B contract value.
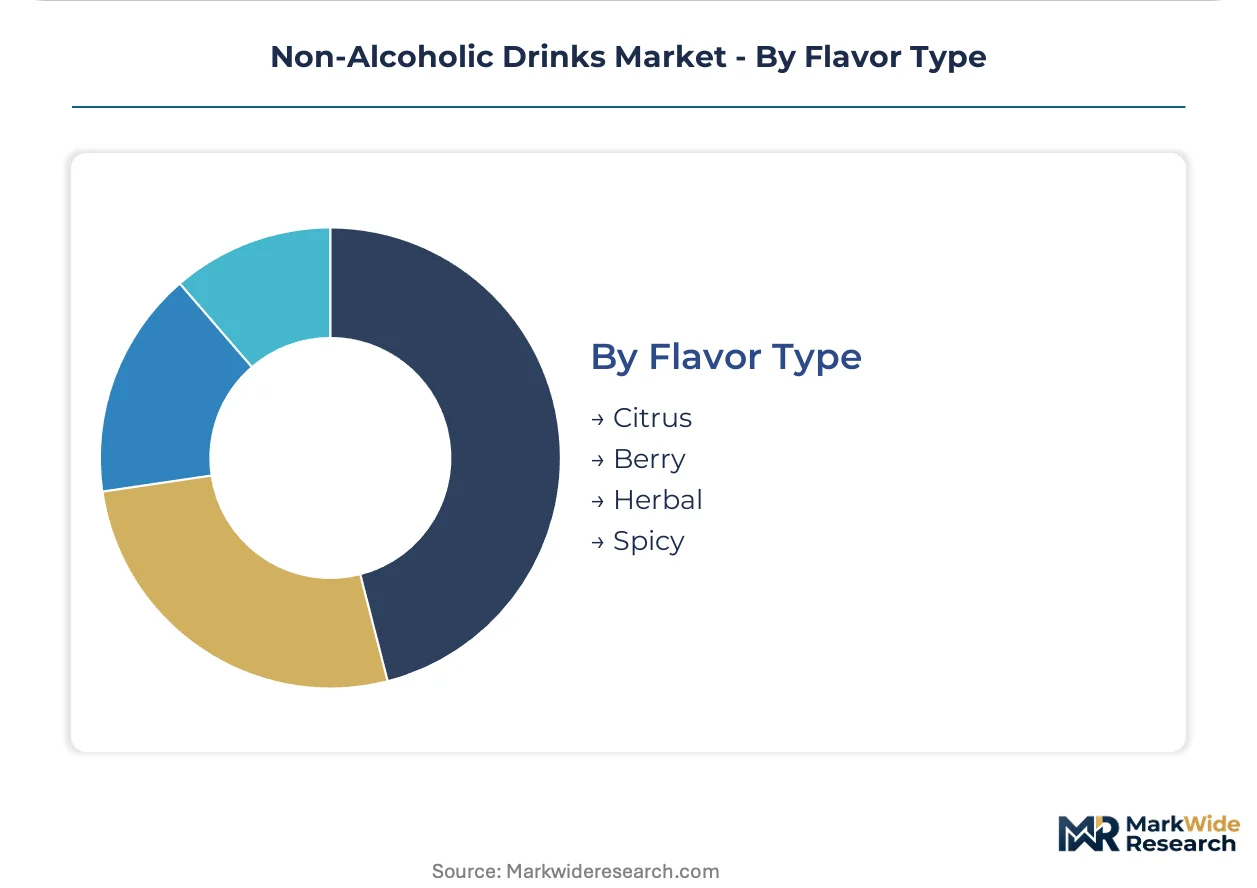
Flavor Type:
Botanical and functional flavor positioning commands price premiums through perceived health associations.
- Citrus:Orange, lemon, and lime oils face harvest-driven volatility from Brazilian frost and Florida hurricane patterns, compressing margins unpredictably for brands without forward-contracted supply.
- Herbal:Botanical extracts including ginger, turmeric, and adaptogenic blends target wellness-positioned consumers in California and Japanese functional beverage markets.
- Berry:Acai, blueberry, and mixed berry profiles dominate antioxidant marketing claims.
- Spicy:Chili, ginger-heat, and cinnamon variants create sensory differentiation in craft and premium tiers.
Citrus dominates volume formulations. Herbal is climbing the fastest on wellness positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Switzerland and Japan where mineral water sourcing commands retail premiums, while volume manufacturing gravitates toward China and the United States where scale economies dominate unit economics.
United States
Health-conscious millennials in metropolitan areas drive functional beverage demand with reduced sugar content. FDA's updated Nutrition Facts labeling requirements pressure systematic reformulation across carbonated portfolios. PepsiCo leverages its North American bottling network to sustain cost leadership in carbonated soft drinks.
China
Urban middle-class consumers in Tier-1 and Tier-2 cities trade up from tap water to premium bottled and plant-based alternatives. SAMR enforces national food safety standards that constrain formulation choices for multinational portfolios. Shanghai and Beijing concentrate purchasing power that accelerates category premiumization.
Germany
Microencapsulation technology for immunity-positioned waters attracts R&D investment from domestic manufacturers. EFSA applies parallel standards through EU Food Information to Consumers Regulation, creating compliance complexity. Bavaria hosts beverage technology clusters deploying aseptic cold-fill systems for premium juice brands.
Japan
Fitness culture penetration drives sports drink expansion among urban consumers seeking functional hydration. METI oversees national standards for food additives and labeling that influence regional formulation decisions. Tokyo and Osaka anchor functional beverage innovation with precision fermentation capabilities.
India
Urban millennials in Mumbai and Bangalore demonstrate willingness to pay premiums for verified health benefits in functional beverages. FSSAI's recent clarity on probiotic and vitamin fortification claims opens formulation pathways for domestic and multinational entrants. Maharashtra and Karnataka concentrate manufacturing investment targeting underpenetrated functional segments.
Non-Alcoholic Drinks Market Competitive Environment
Concentration sits with multinational beverage conglomerates that control bottling infrastructure and brand portfolios spanning multiple categories. Three structural tiers define competitive positioning: scale-driven mass-market operators, premium specialists leveraging sourcing differentiation, and digital-native challengers bypassing traditional retail economics. Dominant competitive moves include strategic partnerships for distribution access and portfolio diversification into functional and plant-based segments.
Among scale-driven multinational operators, The Coca-Cola Company and PepsiCo occupy positions defined by bottling network control and carbonated portfolio breadth. Nestlé represents the premium-tier archetype through specialized mineral water sourcing and purification technology investments. Red Bull GmbH exemplifies event-marketing dominance with controlled distribution strategies in convenience channels.
| Leading Market Players |
|---|
| Danone |
| Keurig Dr Pepper |
| The Coca-Cola Company |
| The Kraft Heinz Company |
| Monster Beverage Corporation |
| PepsiCo |
| Red Bull GmbH |
| Suntory Holdings Limited |
| Nestlé |
| Others |
Value Chain & Pricing Dynamics
Take-or-pay contracts for aluminum can supply lock in both material access and unit cost visibility for beverage manufacturers navigating procurement volatility. These arrangements concentrate pricing power with three global packaging conglomerates while forcing brand owners to absorb volume commitments regardless of demand fluctuations.
Pricing Analysis
The customization-premium spread separates mass-market carbonated formulations from precision-fermented functional waters and personalized subscription offerings. Pricing stratifies across premium, standard, and economy tiers based on ingredient sourcing transparency and clean-label certification status. Cost compression in standard-tier carbonated drinks intensifies because sugar taxation cascades across jurisdictions force reformulation investments. Price-sensitive households trading down from premium alternatives dominate volume demand, while fitness-oriented consumers show lowest sensitivity for verified functional claims.
Supply Chain Analysis
Brazil and Madagascar anchor natural flavor extract production for citrus oils and vanilla respectively, with harvest-driven volatility rippling through formulation costs. Aluminum ingot supply draws from Australian bauxite and Chinese smelting capacity before converging at coating and forming facilities. Single-source vulnerability concentrates in beverage-grade can supply where three conglomerates control majority share. Distribution runs through supermarket slotting-fee structures for mass volume, with direct-to-consumer platforms bypassing traditional retail economics for premium functional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as subscription replenishment algorithms and direct-to-consumer data loops restructure channel access. Interoperability between flavor customization interfaces and manufacturing execution systems determines which brands capture recurring household relationships.
For Market Incumbents: Fortify bottling network control through backward integration into aseptic cold-fill technology and aluminum can capacity reservations. The threat of digital-native challengers bypassing retail slotting fees demands preemptive investment in proprietary subscription platforms. Certification investment in EU Green Deal-compliant packaging formats secures placement advantages as European retail buyers tighten environmental criteria.
For New Entrants and Emerging Players: Anchor in India's underpenetrated functional beverage segment where FSSAI clarity on fortification claims opens formulation pathways. Urban millennials in Mumbai and Bangalore demonstrate willingness to pay substantial premiums for verified health benefits, creating the most penetrable demand pool. A direct-to-subscription go-to-market angle bypasses incumbent-controlled supermarket shelf space while capturing consumption data for iterative product refinement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital-native brands with proprietary subscription algorithms and flavor customization platforms. Long-term viability over the coming decade hinges on data asset accumulation and manufacturing flexibility rather than fixed bottling infrastructure. Acquisition targets should demonstrate precision fermentation capabilities or biodegradable packaging technologies. The signal to watch is front-of-pack labeling mandate expansion beyond Nutri-Score adoption in France, Belgium, and the Netherlands.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Technology Deployment | Preserves heat-sensitive vitamins in functional waters while enabling clean-label claims that command retail premiums. |
| Direct-to-Consumer Platform Launch | Bypasses supermarket slotting fees and captures granular consumption data for iterative formulation development. |
| Biodegradable Packaging Scale-Up | Positions brands for EU Green Deal mandates requiring recyclable or reusable containers by 2030. |
| Precision Fermentation Investment | Collapses cost structures for natural flavor replication while reducing harvest-driven supply volatility. |
| Subscription Replenishment Algorithm Development | Locks in recurring household relationships through customizable flavor profiles and predictive reorder systems. |
Study Parameters
The analysis maps carbonated soft drinks, functional waters, sports drinks, and plant-based alternatives, each validated through beverage brand managers, retail category buyers, and supply chain planners. Primary interviews with formulation scientists, bottling facility operations heads, and regulatory affairs specialists combined with secondary validation against FDA GRAS filings, EFSA scientific opinions, and Nielsen retail audit data. Bottom-up volume modeling and top-down value reconciliation triangulate segment outputs.
Consistency checks against customs records and trade flow databases validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, flavor positioning, and regional regulatory cluster. CAGRs derive from iterative demand elasticity calibration against income growth trajectories and sugar taxation spread patterns. Forecast inputs incorporate aluminum price volatility indices and natural extract harvest projections.
Decision-makers should treat outputs as directional under assumptions of continued sugar taxation cascade and stable aluminum supply concentration; material deviation in either driver would warrant model refresh. Specific risks that could revise trajectories include abrupt FDA sweetener approval reversals, aluminum smelter disruption events, or front-of-pack labeling mandate acceleration. Recalibration cycles align with material shifts in regulatory enforcement intensity and packaging material cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Brazil Energy Drinks Market
Non-Alcoholic Beverages
Africa Energy Drinks Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Vietnam Energy Drinks Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
Pearl Milk Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market