
 Polyglycerol Esters of Fatty Acids Market | 2026-2036
Polyglycerol Esters of Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Polyglycerol Esters of Fatty Acids Market Outlook
Modular emulsifier bundling is shifting buyer choice toward application-specific formulations rather than generic multi-purpose grades. Palsgaard A/S leverages its integrated emulsifier technology platform to sustain formulation leadership across European dairy applications. Cargill, Incorporated anchors its position through backward integration into vegetable oil feedstocks, securing cost-advantaged supply chains. Croda International Plc differentiates via pharmaceutical-grade specialization, occupying high-margin niches in drug delivery systems.
Polyglycerol esters of fatty acids comprise polyglycerol backbones esterified with C8-C22 fatty acids, yielding non-ionic surfactants with hydrophilic-lipophilic balance values typically spanning 3 to 13. These compounds function primarily as emulsifiers, stabilizers, and rheology modifiers across food processing, personal care formulations, and pharmaceutical preparations. Food Grade dominates volume throughput due to entrenched bakery and confectionery demand, though Pharmaceutical Grade commands superior margin pools driven by excipient purity requirements. Personal Care applications are expanding fastest as formulators replace traditional ethoxylated surfactants with plant-derived alternatives.
EFSA maintains stringent food additive safety assessments under Regulation (EC) No 1333/2008, directly influencing emulsifier approval timelines and reformulation costs for European manufacturers. REACH compliance through ECHA mandates extensive chemical substance registration, creating market access barriers for non-European suppliers lacking toxicological dossiers. BASF SE and Evonik Industries AG navigate these frameworks through dedicated regulatory affairs divisions. Stakeholders must monitor evolving EU Green Deal bio-based content thresholds, as these will determine which feedstock strategies remain viable for long-term formulation portfolios.
Market Dynamics
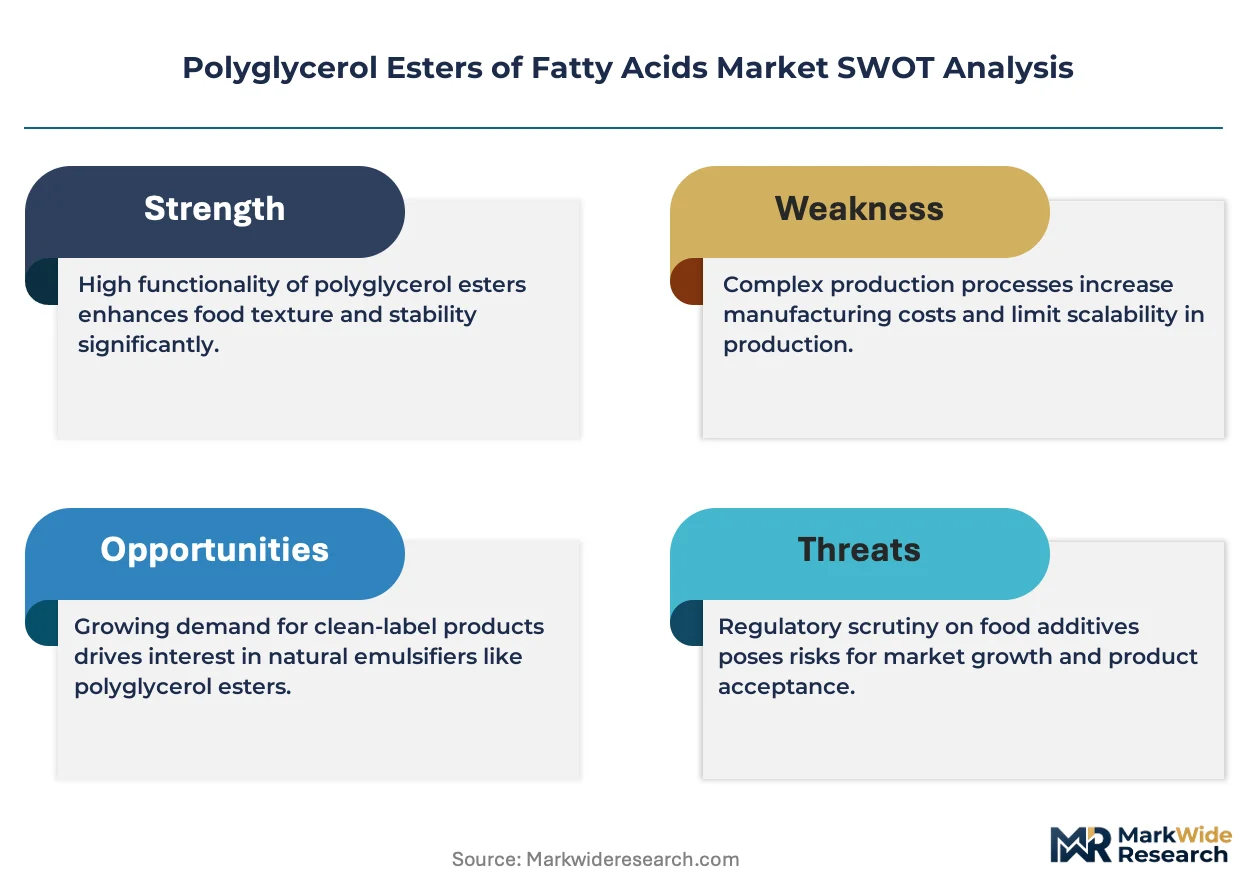
Clean-label formulation mandates from EFSA and EU Green Deal bio-based thresholds are compressing synthetic emulsifier viability, forcing processors to requalify entire ingredient portfolios around plant-derived polyglycerol esters with documented chain-of-custody credentials.
Growth Catalysts
- REACH chemical registration thresholds:ECHA's substance dossier requirements are filtering out non-compliant imports, concentrating procurement among European manufacturers with pre-registered toxicological data.
- Bakery sector reformulation:Artisan and industrial bakeries across Germany and France are replacing synthetic mono- and diglycerides with polyglycerol esters to achieve clean-label positioning.
- Personal care ethoxylate phase-out:Formulators are eliminating polyethylene glycol-based surfactants in favor of plant-derived alternatives with comparable HLB performance profiles.
Market Restraints
- Palm and coconut oil feedstock volatility:Tropical oil price swings directly compress margin structures for ester manufacturers lacking long-term supply contracts.
- EFSA additive re-evaluation timelines:Extended safety assessment windows for existing food emulsifiers create regulatory uncertainty that delays customer commitment.
- Enzymatic esterification yield limitations:Lipase-catalyzed production routes remain constrained by batch-to-batch consistency issues at commercial scale.
Strategic Opportunities
- Pharmaceutical excipient certification:USP-NF and EP compliance for high-purity grades opens formulation partnerships with generic drug manufacturers seeking cost-advantaged alternatives to polysorbates.
- EU Green Deal bio-based content mandates:Renewable carbon thresholds in packaging and personal care are accelerating demand for certified-sustainable emulsifier feedstocks.
- Direct-to-manufacturer digital procurement:Specialty chemical platforms are disintermediating traditional distributor networks for mid-volume bakery and dairy processors.
Industry Challenges
- Multi-jurisdiction dossier maintenance:Parallel compliance with EFSA food additive specifications, REACH substance registrations, and US FDA GRAS self-affirmation requirements strains regulatory affairs capacity.
- Legacy equipment retrofit costs:Confectionery manufacturers with established mono-glyceride handling infrastructure face capital expenditure barriers to process higher-viscosity polyglycerol formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyglycerol Esters of Fatty Acids Market |
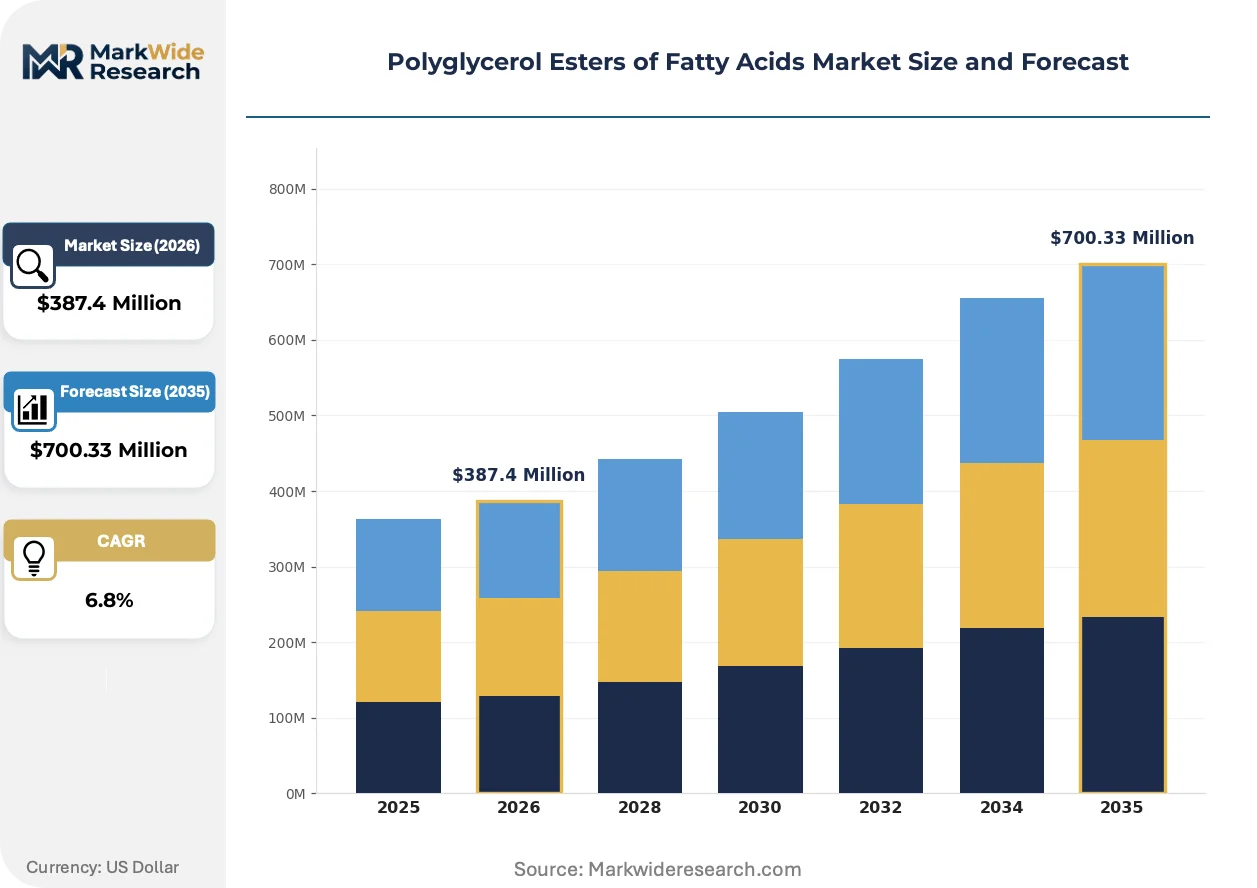
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Cosmetic Grade, Pharmaceutical Grade, Industrial Grade Application: Baking, Dairy Products, Confectionery, Personal Care Formulation Type: Emulsifier, Stabilizer, Thickener, Lubricant End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals |
| Companies Covered | Evonik Industries AG, Lonza Group AG, Palsgaard A/S, Cargill, Incorporated, Mitsubishi Chemical Corporation, BASF SE, Clariant AG, AAK AB, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyglycerol Esters of Fatty Acids Market Strategic Shifts
Enzymatic synthesis routes and precision fermentation-derived fatty acid feedstocks are converging to reshape emulsifier manufacturing economics, while regulatory bio-based mandates are locking in structural preference for plant-derived chemistry over petrochemical alternatives.
Enzymatic esterification using immobilized lipases is absorbing capital allocation from traditional chemical catalysis in European manufacturing facilities. Specialty chemical producers in Germany and the Netherlands are scaling solvent-free production lines that reduce energy intensity and enable broader fatty acid chain-length flexibility. This technology is absorbing market share from conventional alkaline-catalyzed processes by delivering color-stable, low-odor grades preferred by premium cosmetic formulators.
EFSA's systematic re-evaluation of food additives under Regulation (EC) No 1333/2008 is compressing approval timelines for novel emulsifier variants. Manufacturers must now submit extended toxicological packages including reproductive and developmental studies that earlier generations of additives never required. Food-grade polyglycerol esters with established safety histories are benefiting as customers retreat from additives facing data gaps or temporary usage restrictions.
Specification-driven procurement contracts are replacing commodity spot purchasing for mid-sized dairy processors. Buyers in France and Italy now require chain-of-custody documentation linking emulsifier batches to certified-sustainable palm or coconut sources, with penalties for documentation failures. This pattern is most visible in organic dairy applications where clean-label positioning commands shelf price premiums sufficient to absorb ingredient cost differentials.
Polyglycerol Esters of Fatty Acids Market Segmentation
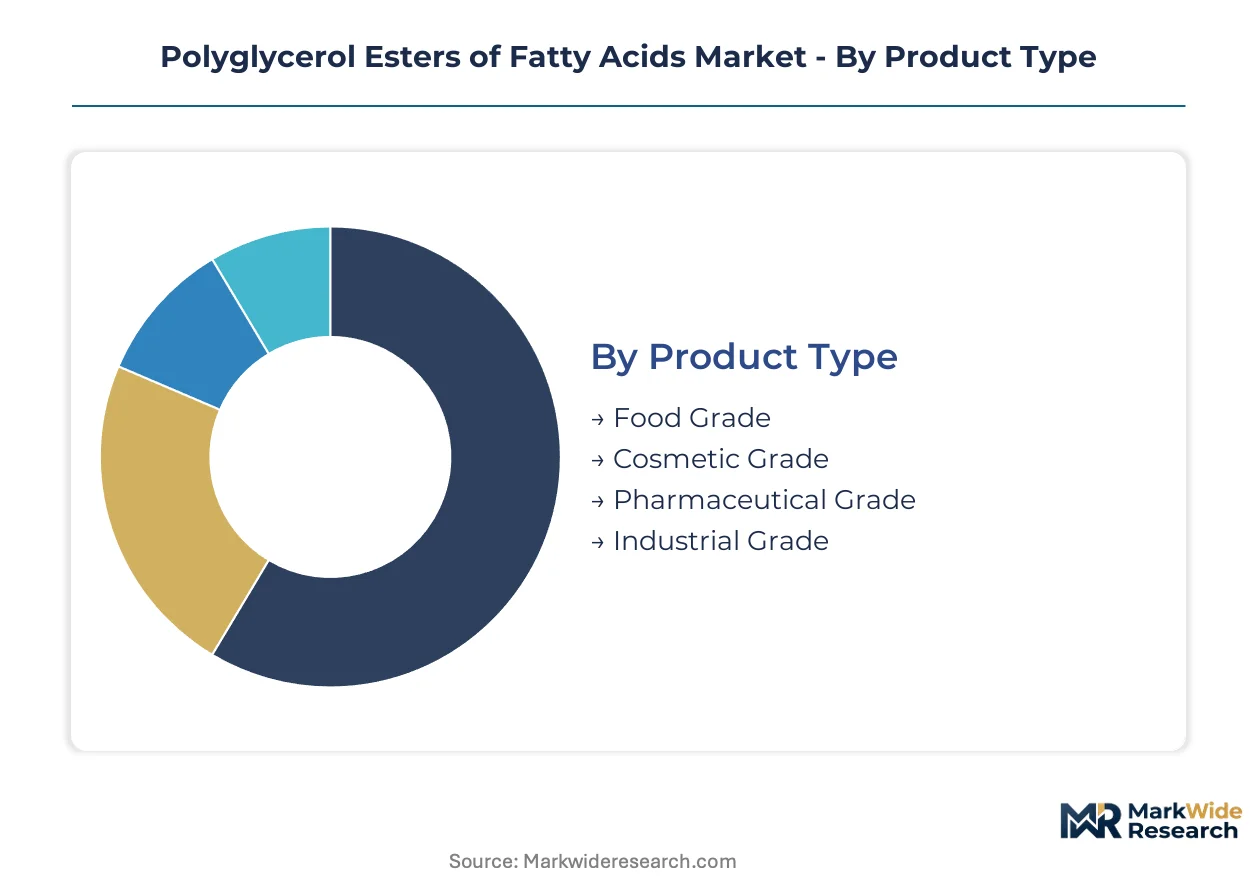
Polyglycerol esters of fatty acids serve divergent performance requirements across food safety, cosmetic elegance, and pharmaceutical purity standards. Segmentation reveals how formulation specifications, regulatory thresholds, and end-use functionality create distinct margin architectures within the emulsifier value chain.
Product Type:
Volume throughput concentrates in mass-market food applications, while premium pricing accrues to grades meeting pharmaceutical purity benchmarks.
- Food Grade:Comprises polyglycerol backbones esterified with C8-C18 fatty acids under alkaline catalysis, delivering HLB values optimized for water-in-oil emulsions. German and French bakery processors dominate procurement, driven by EFSA clean-label mandates displacing synthetic mono- and diglycerides.
- Pharmaceutical Grade:Requires USP-NF and EP compliance with residual glycerol limits below 0.5% and heavy metal specifications stricter than food counterparts. Demand clusters around generic drug manufacturers in Switzerland and the Netherlands seeking polysorbate alternatives for parenteral formulations.
- Cosmetic Grade:Balances color stability and low-odor profiles for premium skincare, with enzymatic esterification routes gaining preference among Dutch and German formulators.
- Industrial Grade:Serves lubricant and metalworking fluid applications with less stringent purity requirements, primarily sourced through spot purchasing.
Today's leader: Food Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
Reformulation cycles across European processed food sectors are redrawing demand concentration patterns.
- Baking:Artisan and industrial bakeries leverage polyglycerol esters for dough conditioning and crumb softening, with Germany's precision manufacturing clusters driving premium-grade procurement.
- Dairy Products:UHT milk and whipping cream stabilization represent high-volume consumption, particularly among French and Italian organic dairy processors requiring chain-of-custody documentation.
- Confectionery:Chocolate and coating applications demand precise tempering control, though legacy mono-glyceride handling infrastructure creates retrofit barriers for manufacturers.
- Personal Care:Ethoxylate phase-out initiatives are accelerating plant-derived surfactant substitution, with this segment climbing the fastest among application categories.
Volume anchors in baking and dairy. Margin expansion concentrates in personal care reformulation.
Formulation Type:
Functional role determines specification stringency and customer switching costs within processor supply chains.
- Emulsifier:Dominates volume as the primary functional designation, spanning water-in-oil and oil-in-water systems across food and cosmetic matrices.
- Stabilizer:Critical for freeze-thaw resistance in dairy desserts and extended shelf-life bakery goods, commanding formulation premiums.
- Thickener:Rheology modification for sauces and personal care gels, with HLB tuning determining performance in specific viscosity ranges.
- Lubricant:Industrial applications including food machinery release agents, representing lower-margin, higher-volume offtake.
Emulsification remains the core value proposition. Stabilization functions deliver superior price realization.
End Use Industry:
Regulatory jurisdiction and certification requirements fragment procurement behavior across customer verticals.
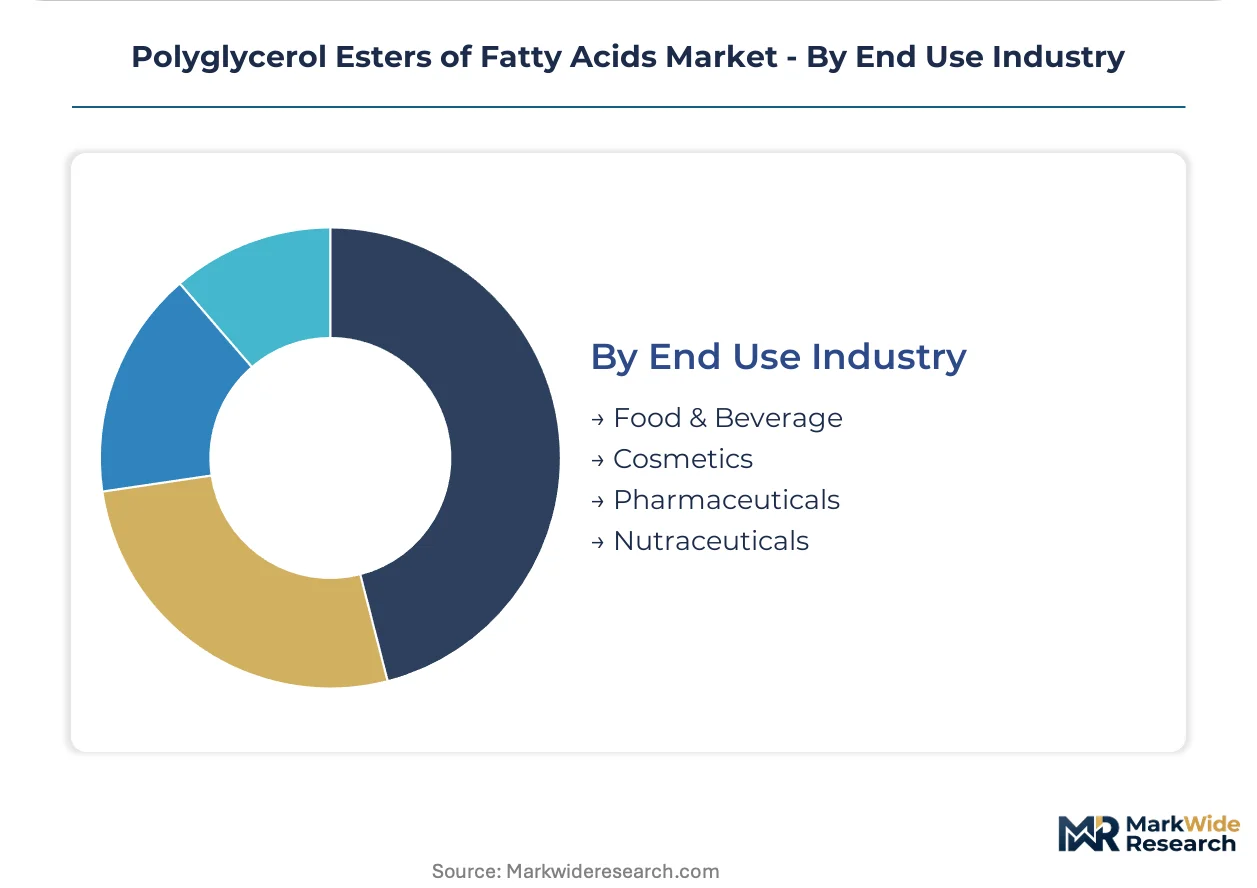
- Food & Beverage:EFSA additive evaluations under Regulation (EC) No 1333/2008 govern approval timelines, with established safety histories conferring competitive advantage.
- Cosmetics:EU Green Deal bio-based thresholds and REACH substance registrations create compliance barriers favoring European manufacturers with pre-registered toxicological dossiers.
- Pharmaceuticals:Excipient qualification protocols including ICH Q3D elemental impurity guidelines drive specification differentiation and customer lock-in.
- Nutraceuticals:Positioned between food and pharmaceutical standards, with demand emerging for delivery system applications in softgel and liquid formulations.
Food & Beverage commands current volume. Pharmaceuticals and nutraceuticals represent the steepest expansion trajectory for value-added grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyglycerol esters of fatty acids manufacturing first achieved industrial scale in European chemical clusters during the mid-20th century, with German and Dutch facilities establishing the process chemistry foundations that persist today. Regional demand patterns now reflect divergent regulatory maturity and end-use specialization across major consuming markets.
Germany
Precision food manufacturing clusters in Bavaria and North Rhine-Westphalia drive premium-grade procurement for bakery and dairy applications. EFSA's additive evaluations under Regulation (EC) No 1333/2008 compress approval timelines, favoring established emulsifiers with documented safety histories. The Cologne-Düsseldorf industrial corridor hosts concentrated formulation R&D activity serving continental European processors.
France
Artisan bakery sector reformulation and organic dairy expansion in Brittany and Normandy accelerate clean-label emulsifier substitution. REACH compliance through ECHA mandates toxicological dossiers that filter non-European imports. The Paris basin concentration of confectionery manufacturers generates specialized demand for tempering-control emulsifiers in chocolate applications.
United States
FDA GRAS self-affirmation pathways enable faster market entry for novel polyglycerol ester variants compared to European pre-approval requirements. Midwest dairy processors and Northeast bakery conglomerates represent high-volume consumption anchors. California-based personal care formulators drive demand for plant-derived surfactants replacing ethoxylated alternatives.
China
SAMR food additive registration requirements and GB standards compliance create market access barriers for imported emulsifiers. Yangtze River Delta food processing clusters scale domestic manufacturing to serve bakery and confectionery sector expansion. Dual carbon policy targets accelerate bio-based feedstock qualification for sustainable emulsifier production.
India
FSSAI food safety standards and rising processed food consumption in Maharashtra and Gujarat expand emulsifier demand from domestic bakery and dairy sectors. The country's pharmaceutical excipient sector in Telangana and Karnataka explores polyglycerol esters as polysorbate alternatives for generic drug formulations.
Polyglycerol Esters of Fatty Acids Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical and cosmetic purity specifications commanding substantial price premiums over standard food-grade offerings. Market structure consolidates around integrated chemical conglomerates with captive fatty acid supply and specialized emulsifier houses with formulation expertise. Three archetypes dominate: diversified chemical majors with backward integration into vegetable oil feedstocks, precision fermentation and enzymatic technology specialists, and regional compounders serving niche application requirements. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure certified-sustainable feedstock access and pharmaceutical excipient qualification.
Among European chemical majors, BASF SE and Evonik Industries AG occupy positions spanning multiple grade tiers through integrated manufacturing platforms. Palsgaard A/S exemplifies the specialized emulsifier archetype with concentrated expertise in food application formulation. Croda International Plc represents the high-margin pharmaceutical and personal care specialization vector, leveraging purity-focused positioning to serve drug delivery and cosmetic elegance requirements.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Lonza Group AG |
| Palsgaard A/S |
| Cargill, Incorporated |
| Mitsubishi Chemical Corporation |
| BASF SE |
| Clariant AG |
| AAK AB |
| Croda International Plc |
| Others |
Value Chain & Pricing Dynamics
EFSA's clean-label mandates and chain-of-custody documentation requirements from French and Italian organic dairy processors are forcing suppliers to requalify feedstock sourcing and absorb certification costs, compressing margins on standard grades while amplifying premiums for credentialed supply.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food, and industrial grades dominates the market, with USP-NF and EP compliance commanding substantial premiums over standard food-grade offerings. Price differentiation centers on certification stringency and volume scale, with pharmaceutical excipient qualification driving the widest spreads. Cost compression in standard food grades is intensifying because enzymatic esterification investments raise fixed-cost absorption pressures. Artisan bakery processors in Germany show highest price sensitivity, while Swiss generic drug manufacturers accept premium pricing for validated excipient supply.
Supply Chain Analysis
Direct-to-manufacturer digital procurement channels are disintermediating traditional distributor networks for mid-volume European processors. Manufacturing concentrates in Germany, the Netherlands, and France, with raw material sourcing drawing from Malaysian and Indonesian palm oil plantations and Philippine coconut oil processors. Supply chain risk centers on tropical oil price volatility and EU Green Deal bio-based threshold compliance. Distribution runs through specialty chemical platforms and regional compounders serving niche application requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-registered European supply and faster FDA GRAS pathways in the United States, with regulatory compliance cost differentials creating structural margin advantages for multi-jurisdiction dossier holders.
For Market Incumbents: Lock in certified-sustainable feedstock contracts before EU Green Deal thresholds harden, and accelerate pharmaceutical excipient qualification to defend against precision fermentation entrants. Backward integration into vegetable oil processing and captive enzymatic production capacity represent critical defensive levers against margin erosion from tropical oil volatility. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical grades offers white-space entry for USP-NF compliant producers, while Indian generic drug manufacturers present the most penetrable demand cluster. Target nutraceutical delivery system applications with simplified qualification protocols, and pursue direct digital procurement partnerships with mid-sized dairy processors seeking supply chain transparency. For Investors and Strategic Acquirers: Asymmetric upside sits with enzymatic technology specialists holding solvent-free production platforms and pre-registered REACH dossiers. Long-term viability favors acquisition targets with dual food-pharma certification capabilities and established chain-of-custody documentation systems. Watch EFSA additive re-evaluation timelines as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Feedstocks | Captive supply of certified-sustainable palm and coconut oils insulates margin structures from tropical commodity volatility. |
| Pharmaceutical Excipient Certification | USP-NF and EP compliance unlocks formulation partnerships with Swiss and Dutch generic drug manufacturers. |
| Enzymatic Esterification Scale-Up | Solvent-free production lines in Germany and the Netherlands reduce energy intensity and enable premium cosmetic grade output. |
| Direct-to-Manufacturer Digital Procurement | Specialty chemical platforms disintermediate distributors for French and Italian mid-volume dairy processors. |
| Joint Venture for Precision Fermentation Feedstocks | Partnerships with biotechnology firms secure bio-based fatty acid supply meeting EU Green Deal renewable carbon thresholds. |
Study Parameters
Bottom-up bakery and dairy processor demand modeling reconciled against top-down vegetable oil feedstock supply tracking forms the analytical core. Primary interviews with plant managers at German and Dutch esterification facilities, procurement leads at French dairy cooperatives, and regulatory affairs directors at specialty chemical firms combined with secondary validation through EFSA additive evaluation databases, REACH registration dossiers, and customs trade flow records. Triangulation across these sources ensures convergence between consumption estimates and production capacity assessments.
Historical trendline analysis of emulsifier substitution patterns in European processed food sectors informed projection framework development across the analysis window. Segmentation dimensions modeled include grade tier, end-use industry, formulation function, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating EFSA regulatory timeline assumptions and enzymatic technology adoption curves. Industry-specific forecast inputs include palm oil futures price volatility indices and pharmaceutical excipient qualification pipeline data.
Caveats apply where EFSA additive re-evaluation outcomes, REACH substance registration amendments, or tropical oil supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory trajectory and feedstock availability. Periodic stress-testing of base assumptions against evolving EU Green Deal implementation schedules is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Brazil Food Additives Market