
 United Kingdom Food Colorants Market | 2026-2036
United Kingdom Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Food Colorants Market Analytics
Artisan bakery and premium confectionery buyers is collapsing share away from mass-market beverage formulators as clean-label expectations harden across British retail channels. Sensient Technologies anchors its position through deep backward integration into natural pigment sourcing. Givaudan (Naturex) differentiates via concentrated R&D spending on plant-derived color stability. Chr. Hansen A/S dominates the dairy application niche with specialized carotenoid strains.
Food colorants comprise chromatic additives—synthetic dyes, natural extracts, lake pigments, and plant-based concentrates—typically specified by hue intensity, light stability, and pH tolerance between 2.5 and 8.0, deployed to standardize visual appeal across processed food matrices. Natural extracts lead type-level value contribution as British retailers enforce additive disclosure policies. Beverage applications remain structurally mature with compressed margin pools, while confectionery and bakery segments capture expanding premium positioning through gel and paste form factors.
The Food Standards Agency enforces E-number labeling and novel food authorization under retained EU Regulation 2015/2283, while BSI standards and the UK REACH framework govern chemical purity thresholds for imported dye intermediates. These layered requirements elevate compliance costs for synthetic dye portfolios and redirect investment toward botanical extraction capabilities. Stakeholders must monitor divergence between UK and retained EU additive approvals as Westminster considers independent positive-list reforms.
Market Dynamics
The Food Standards Agency's additive transparency mandates are compressing synthetic dye portfolios while redirecting capital toward botanical extraction infrastructure across British manufacturing clusters.
Growth Catalysts
- Retained EU Regulation 2015/2283:The novel food authorization framework accelerates natural extract validation timelines, compelling reformulation investments from Greater London confectionery producers seeking clean-label positioning.
- West Midlands bakery concentration:Artisan sourdough and patisserie segments in Birmingham and Coventry are specifying carmine and anthocyanin concentrates for premium visual differentiation.
- Supermarket disclosure policies:Tesco and Sainsbury's front-of-pack additive labeling requirements are forcing contract manufacturers to eliminate azo dyes from private-label lines.
Market Restraints
- Beetroot and spirulina input volatility:Weather-driven harvest fluctuations in East Anglia and Lincolnshire inflate natural pigment spot prices unpredictably.
- Single-source botanical dependency:Cochineal carmine supply concentrates with Peruvian and Canary Islands processors, exposing British formulators to shipping disruption.
- pH stability ceiling:Anthocyanin extracts degrade above pH 4.0, blocking deployment in alkaline beverage matrices where synthetic alternatives dominate.
Strategic Opportunities
- Scottish dairy innovation corridor:Aberdeenshire and Ayrshire creameries are piloting beta-carotene strains for butter and cheese color standardization.
- Encapsulation-fermentation convergence:Microencapsulation technology paired with microbial pigment production extends light stability for natural colorants in transparent packaging.
- Direct-to-brand digital platforms:Online procurement portals are collapsing traditional distributor margins for small-batch Yorkshire and Cumbria food producers.
Industry Challenges
- Extraction technician scarcity:British universities produce insufficient graduates with combined phytochemistry and food engineering credentials for scale-up facilities.
- UK REACH re-registration timelines:Synthetic dye dossier resubmission under the independent chemicals regime consumes eighteen-month compliance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Food Colorants Market |
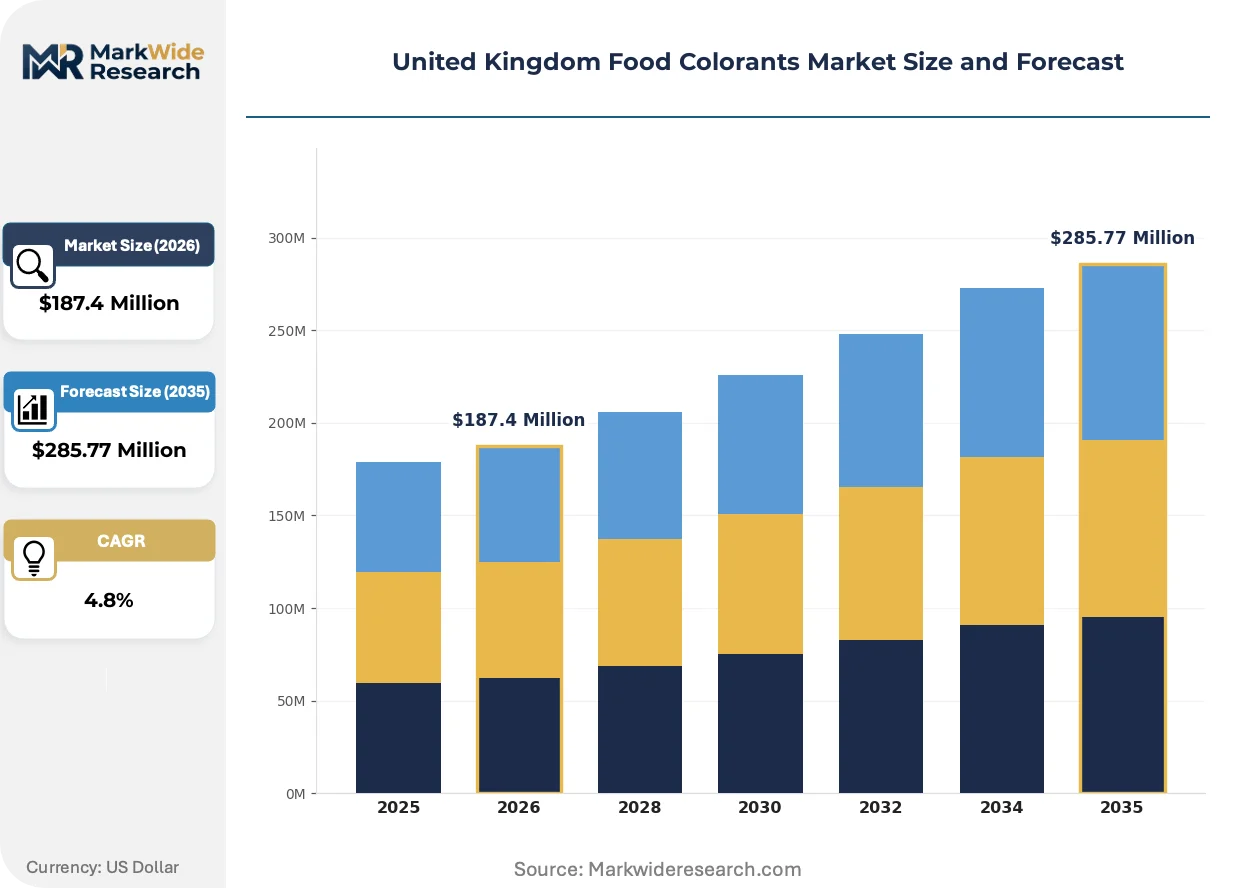
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Synthetic Dyes, Natural Extracts, Plant-Based Colors, Lake Colors Application: Beverages, Confectionery, Bakery Products, Dairy Form: Liquid, Powder, Gel, Paste End User: Food Manufacturers, Retailers, Restaurants, Catering Services |
| Companies Covered | Sensient Technologies, Givaudan (Naturex), Dohler Group, Koninklijke DSM N.V., BASF SE, Chr. Hansen A/S, ADM (Archer Daniels Midland), D.D. Williamson & Co, Tate & Lyle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Food Colorants Market Evolving Landscape
Microencapsulation and fermentation-derived pigments are displacing conventional extraction methods while regulatory divergence between Westminster and Brussels creates formulation complexity for cross-border suppliers.
Encapsulation technology is miniaturizing lipid-shell architectures around carotenoid and curcumin cores, enabling water-dispersible formats without synthetic emulsifiers. Yorkshire-based sauce manufacturers and Manchester beverage startups are adopting these concentrates at pilot scale. The technology is compressing stability gaps between natural and synthetic alternatives in ambient retail distribution.
UK REACH divergence from EU CLP classification is creating parallel compliance obligations for imported dye intermediates. British manufacturers must now maintain separate safety data sheet portfolios for domestic versus continental European shipments. Confectionery exporters in Slough and Reading logistics corridors face the highest documentation burden.
Buyer consolidation among British supermarket chains is compressing supplier negotiation cycles from annual to quarterly reviews. Own-label procurement teams at Aldi UK and Lidl GB now mandate real-time formulation disclosure through vendor portals. The shift is most visible in biscuit and cake mix categories where private-label volume concentrates with three national retailers.
United Kingdom Food Colorants Market Segmentation
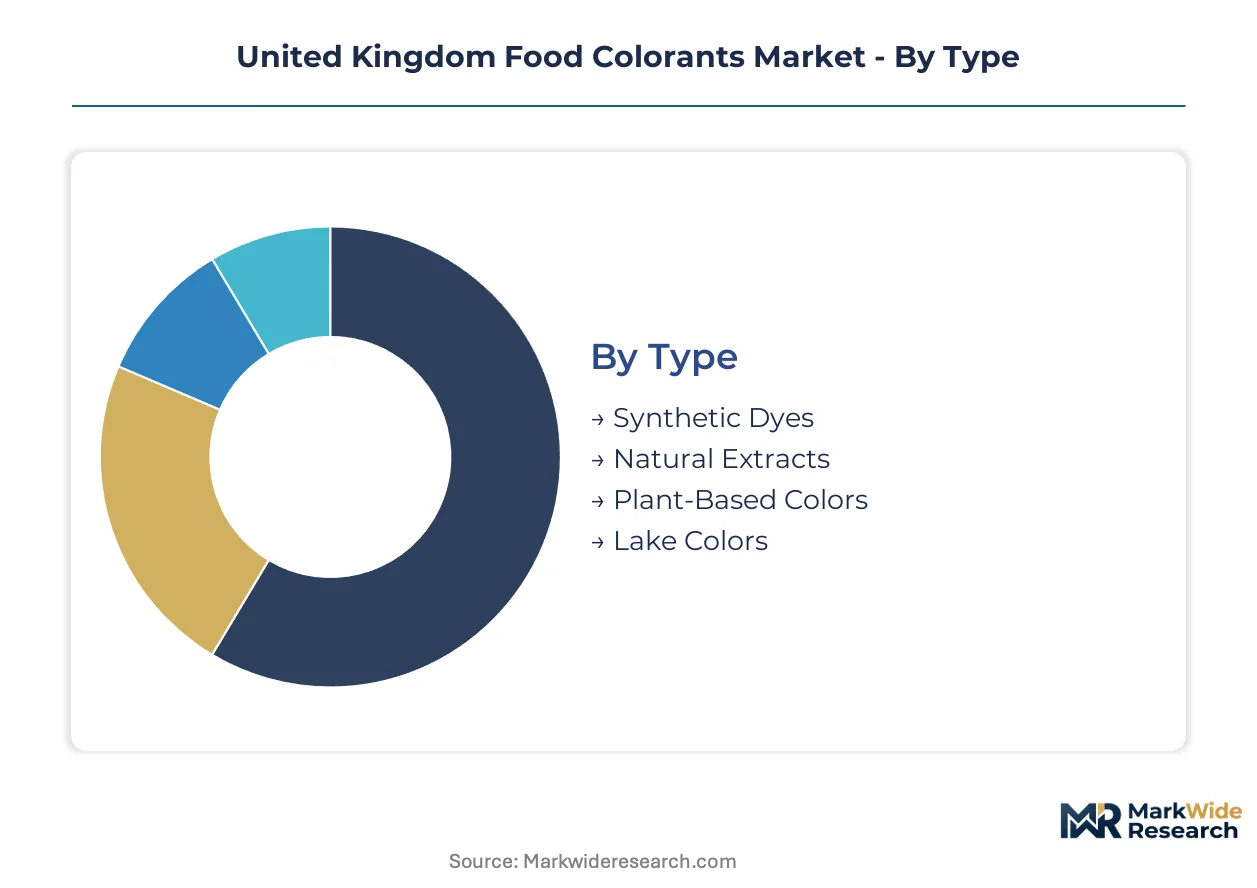
British formulators face divergent substitution pressures across colorant categories as clean-label mandates reshape procurement priorities. Segment-level performance varies sharply between premium-positioned natural extracts and cost-optimized synthetic portfolios.
Type:
Synthetic dyes confront the steepest substitution threat as retailer disclosure policies and Food Standards Agency mandates accelerate natural extract adoption across Greater London and West Midlands manufacturing clusters.
- Natural Extracts:Anthocyanin, carotenoid, and chlorophyll concentrates derived from beetroot, spirulina, and paprika sources. Demand concentrates among artisan confectionery producers in Birmingham and Coventry seeking premium visual differentiation through clean-label positioning.
- Synthetic Dyes:Azo and triphenylmethane compounds including tartrazine and sunset yellow. Compressed margin pools in mass-market beverage applications are forcing reformulation investments as Tesco and Sainsbury's eliminate these additives from private-label lines.
- Plant-Based Colors:Concentrated pigments from turmeric, annatto, and red cabbage with standardized hue intensity.
- Lake Colors:Insoluble pigment complexes formed by precipitating dyes onto aluminum hydrate substrates for fat-based applications.
Synthetic dyes anchor the volume base while natural extracts gain share at the steepest rate.
Application:
Cost tier stratification separates premium-positioned segments from commodity categories, with bakery and confectionery commanding formulation premiums unavailable to mature beverage channels.
- Confectionery:Gel and paste colorants for hard candies, gummies, and chocolate coatings requiring precise hue control and thermal stability. West Midlands artisan producers specify carmine and anthocyanin concentrates for visual differentiation in premium retail channels.
- Bakery:Heat-stable pigments for fondants, icings, and decorative elements in sourdough and patisserie segments. Yorkshire and Cumbria small-batch producers drive spot demand for encapsulated formats that withstand oven temperatures.
- Beverages:Water-dispersible liquid and powder formats for carbonated and still drinks with compressed margin structures.
- Dairy:Beta-carotene and annatto strains for butter and cheese color standardization in Scottish creameries.
Beverage applications retain the largest volume footprint while confectionery climbs the fastest on premiumization.
Form:
Supply concentration in encapsulation technology favors gel and paste formats, while powder and liquid categories face input volatility from East Anglia and Lincolnshire harvest fluctuations.
- Gel:Viscous suspensions with optimized dispersibility for precise dosing in confectionery and bakery matrices. Manchester-based sauce manufacturers pilot these formats for ambient retail distribution.
- Paste:High-concentration semi-solid formats for decorative applications requiring minimal moisture addition. Premium patisserie segments in Greater London specify these for intricate visual effects.
- Liquid:Ready-to-use aqueous solutions for high-volume beverage manufacturing with streamlined handling.
- Powder:Spray-dried concentrates with extended shelf stability for dry mix and seasoning applications.
Powder formats dominate current volume while gel applications expand most quickly through encapsulation adoption.
End User:
Procurement authority is shifting toward consolidated retail buyers, collapsing traditional distributor margins and forcing real-time formulation disclosure through vendor portals.
- Food Manufacturers:Contract producers and branded goods companies across Greater London, West Midlands, and Yorkshire specifying colorants by application matrix and regulatory compliance tier.
- Retailers:Tesco, Sainsbury's, Aldi UK, and Lidl GB own-label procurement teams mandating quarterly supplier reviews and additive transparency through digital platforms.
- Restaurants:Independent and chain operators requiring small-batch colorant procurement for in-house dessert and beverage preparation.
- Catering Services:Institutional foodservice providers with standardized procurement specifications and volume-based pricing structures.
Food manufacturers anchor procurement volume while retailers gain negotiating leverage fastest through consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peruvian and Canary Islands processors export carmine concentrates to British formulators through Rotterdam and Hamburg logistics corridors. Dutch and German port infrastructure handles the majority of natural pigment transshipment before final distribution to Greater London and West Midlands manufacturing clusters.
Greater London
Artisan confectionery producers in Camden and Hackney specify anthocyanin concentrates for premium gummy and chocolate coating applications. The Food Standards Agency enforces retained EU Regulation 2015/2283 novel food authorizations for new botanical extracts entering British formulations. Contract manufacturers along the Thames Gateway corridor are eliminating azo dyes from private-label lines to meet Tesco disclosure mandates.
West Midlands
Birmingham and Coventry sourdough and patisserie segments drive spot demand for carmine and beetroot-derived pigments in decorative fondants and icings. UK REACH re-registration timelines for imported dye intermediates compress eighteen-month compliance windows for local formulators. Encapsulation technology pilots in Wolverhampton manufacturing parks extend light stability for natural colorants in ambient retail distribution.
Yorkshire and Cumbria
Small-batch sauce manufacturers and dry mix producers in Leeds and Carlisle procure gel-format colorants through direct-to-brand digital platforms. Supermarket disclosure policies at Aldi UK and Lidl GB mandate real-time formulation disclosure through vendor portals. Yorkshire-based producers are adopting microencapsulated carotenoid concentrates for heat-stable bakery applications.
Scotland
Aberdeenshire and Ayrshire creameries pilot beta-carotene strains for butter and cheese color standardization. The Scottish Government's food and drink export strategy supports dairy innovation corridor development for premium positioning in continental European markets. Highland extraction facilities face technician scarcity for combined phytochemistry and food engineering scale-up operations.
United Kingdom Food Colorants Market Competitive Landscape
Listed leaders compete with private specialists across backward integration depth and botanical extraction capabilities. The vendor base concentrates around three tiers: multinational pigment houses with captive agricultural supply chains, mid-cap natural extract specialists with regional sourcing networks, and commodity distributors facing margin compression from retailer consolidation. Strategic differentiation runs through M&A activity targeting fermentation-derived pigment platforms and capacity expansion into microencapsulation infrastructure.
Within the multinational tier, Sensient Technologies, Givaudan (Naturex), and Chr. Hansen A/S occupy positions defined by upstream control over natural pigment sourcing. Sensient exemplifies the agricultural integration archetype through deep backward linkages into botanical raw material procurement. Givaudan (Naturex) represents the R&D-intensive specialist model with concentrated investment in plant-derived color stability. Chr. Hansen A/S anchors the microbial fermentation segment with specialized carotenoid strain development for dairy applications.
| Leading Market Players |
|---|
| Sensient Technologies |
| Givaudan (Naturex) |
| Dohler Group |
| Koninklijke DSM N.V. |
| BASF SE |
| Chr. Hansen A/S |
| ADM (Archer Daniels Midland) |
| D.D. Williamson & Co |
| Tate & Lyle |
| Others |
Value Network & Pricing Analysis
UK REACH re-registration requirements gate both supply qualification and price differentiation simultaneously, elevating compliance costs for synthetic dye portfolios while compressing margins on commodity natural extracts that fail to achieve encapsulation premium positioning.
Pricing Analysis
Prior-generation synthetic azo dyes trade at commodity spot rates, current-generation natural concentrates command formulation premiums, and next-generation fermentation-derived pigments justify project-based licensing structures. Three-tier pricing structure across premium encapsulated, standard extracted, and economy synthetic levels separates botanical extraction capabilities from commodity dye imports. Cost compression in mass-market beverage tiers is intensifying because supermarket disclosure policies eliminate azo dye offtake. Food manufacturers in Greater London exhibit lowest price sensitivity for clean-label certification, while contract beverage bottlers in Yorkshire face acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of carmine and cochineal concentrates dominates inventory strategy, with just-in-time procurement reserved for synthetic dye intermediates where UK REACH documentation creates predictable lead times. Raw material sourcing draws from Peru and the Canary Islands for carmine, East Anglia and Lincolnshire for beetroot and spirulina, and India for annatto and turmeric. Single-source botanical dependency on Peruvian processors exposes British formulators to shipping disruption through Rotterdam and Hamburg corridors. Distribution runs through Dutch and German port infrastructure before final delivery to West Midlands and Greater London manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment, where Food Standards Agency additive transparency mandates and UK REACH divergence from EU frameworks create switching costs that protect validated natural extract suppliers.
For Market Incumbents: Compound backward integration into botanical raw material procurement to defend against emerging fermentation-derived pigment platforms. Expand microencapsulation capacity in Yorkshire manufacturing corridors to capture premium positioning as Tesco and Sainsbury's disclosure policies accelerate. Lock long-term supply agreements with East Anglia beetroot growers to hedge input volatility. For New Entrants and Emerging Players: Differentiate on Scottish dairy corridor specialization, where Aberdeenshire and Ayrshire creameries pilot beta-carotene strains with limited incumbent coverage. Target white-space in direct-to-brand digital procurement for Cumbria small-batch producers. Pursue go-to-market partnerships with Manchester beverage startups seeking encapsulated carotenoid stability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-derived pigment platforms, favoring acquisition of microbial strain developers over greenfield extraction facilities. Long-term viability over the coming decade rests on regulatory divergence persistence between Westminster and Brussels. Watch for UK REACH positive-list reform announcements as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Sourcing | Sensient Technologies anchors position through captive agricultural supply chains in key growing regions. |
| Microencapsulation Capacity Expansion | Yorkshire-based manufacturers pilot lipid-shell architectures to close stability gaps with synthetic alternatives. |
| Fermentation-Derived Pigment Development | Chr. Hansen A/S leverages microbial strain libraries to bypass weather-driven harvest volatility. |
| Direct-to-Brand Digital Platform Launch | Online procurement portals collapse traditional distributor margins for small-batch Cumbria producers. |
| UK REACH Compliance Dossier Investment | Eighteen-month re-registration timelines protect validated suppliers from commodity import competition. |
Research Methodology
A standing panel of food formulation chemists, procurement directors at British supermarket chains, botanical extraction facility managers, and Food Standards Agency compliance officers provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews combined with customs records from Dutch and German port authorities, British Retail Consortium disclosure policy documents, and UK REACH registration databases. Bottom-up volume modeling triangulated against top-down value estimates from food manufacturer capex disclosures.
Consistency checks validated outputs against external benchmarks including British food and drink federation production statistics and continental European trade flow data. Segmentation dimensions spanned colorant type, application matrix, form factor, and end-user procurement authority across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating retailer consolidation timelines and natural extract substitution rates. Forecast inputs included East Anglia harvest yield variance and Scottish dairy export corridor development.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory divergence and clean-label premium persistence; material deviation would warrant model refresh. Forecasts reflect these documented assumptions without certainty guarantees. Revision becomes warranted when UK REACH positive-list reform or EU regulatory alignment crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Germany Food Emulsifiers Market