
 Beverage Acidulants Market | 2026-2036
Beverage Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Acidulants Market Analysis
Asset-light toll manufacturing and third-party fermentation contracts is reconfiguring capital barriers for new acidulant suppliers. Cargill Incorporated leverages backward integration into corn dextrose feedstock to sustain cost advantages in citric acid production. Corbion N.V. specializes in bio-based malic acid through proprietary fermentation pathways, positioning its portfolio toward premium beverage formulations.
Beverage acidulants comprise organic acids—principally citric, malic, tartaric, and lactic—introduced at concentrations typically ranging from 0.05% to 0.3% by weight to regulate pH, enhance flavor profiles, and extend microbial stability in finished drinks. These compounds function as taste modulators, preservative synergists, and mineral absorption facilitators across carbonated and non-carbonated beverage systems. Citric acid dominates product type volumes due to its universal compatibility with fruit-flavored applications, while malic acid captures faster growth in energy beverages where its slower dissociation rate prolongs tartness perception. Powder and granular forms anchor manufacturing demand for precise dosing control, though liquid acidulants gain traction in continuous-processing bottling lines.
FDA food additive regulations under 21 CFR govern acidulant purity specifications and GRAS affirmation pathways in the United States, while EFSA and REACH frameworks in Europe enforce residual solvent limits and supply chain chemical safety documentation. China's SAMR and GB standards mandate contaminant thresholds for domestically produced and imported acidulants, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor evolving biobased certification requirements and carbon intensity disclosures as beverage manufacturers tie acidulant procurement to scope-three emissions targets.
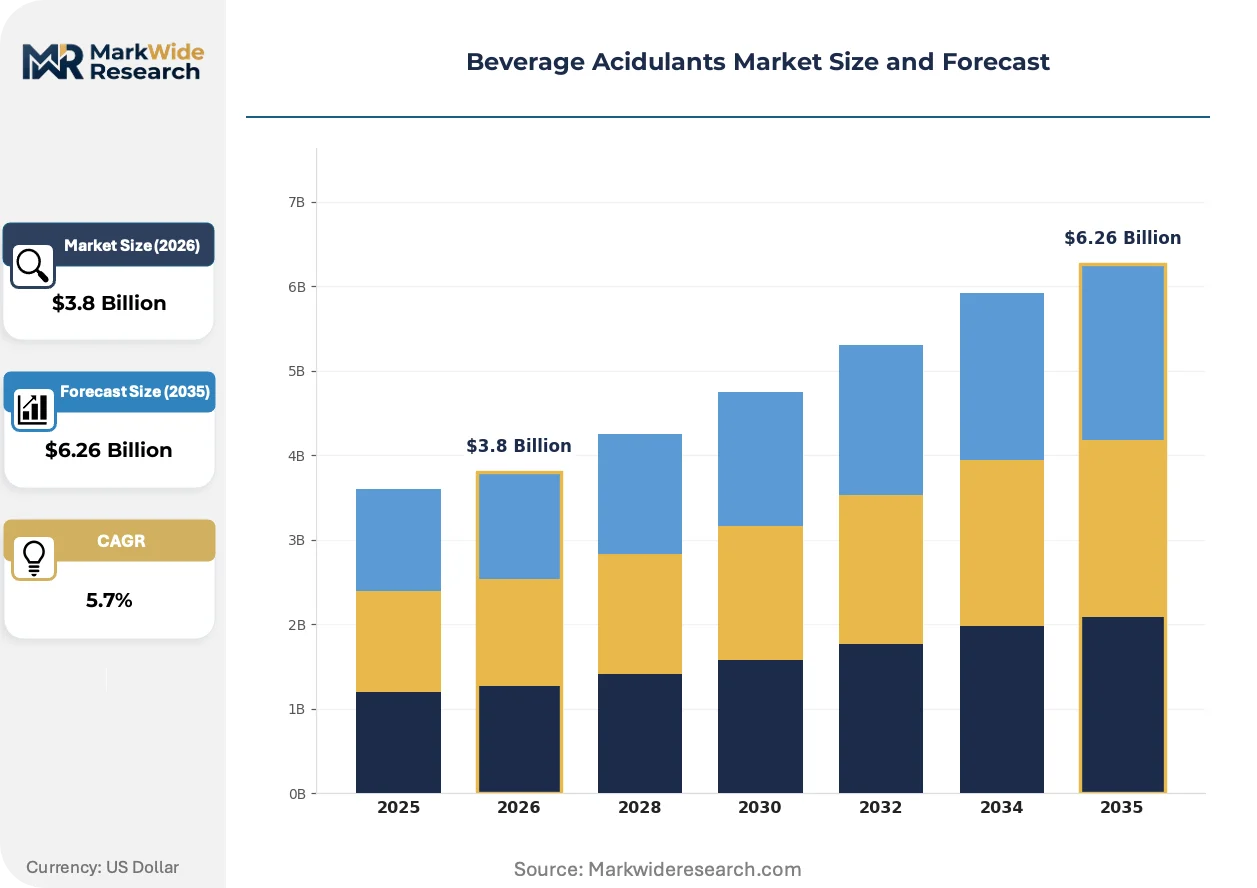
Market Dynamics
Fermentation-based manufacturing economics is compressing synthetic acidulant margins as Chinese producers scale biotechnological capacity and European regulators tighten carbon intensity disclosure requirements for imported feedstocks.
Growth Catalysts
- Clean-label formulation mandates:Beverage manufacturers are reformulating with naturally-derived acidulants to meet retailer clean-label specifications and EFSA guidance on artificial additive reduction.
- China:Domestic fermentation infrastructure expansion is lowering citric acid production costs and redirecting export volumes toward Southeast Asian beverage processing clusters.
- Sports and energy drink proliferation:Functional beverage categories require precise pH modulation and extended tartness profiles that malic and citric acid systems deliver.
Market Restraints
- Corn dextrose feedstock volatility:Citric acid fermentation depends on agricultural commodity pricing subject to climate disruption and biofuel diversion pressures.
- Supply concentration in Shandong Province:Over half of global citric acid fermentation capacity clusters in eastern China, creating single-point vulnerability to regional energy rationing or environmental enforcement.
- REACH residual solvent documentation:European chemical safety frameworks impose testing burdens on imported acidulants that synthetic producers struggle to satisfy without capital-intensive purification retrofits.
Strategic Opportunities
- Biobased certification premiums:USDA BioPreferred and EU Ecolabel pathways enable price differentiation for fermentation-derived acidulants with verified renewable carbon content.
- India beverage manufacturing expansion:FSSAI modernization and multinational bottler investments in Gujarat and Maharashtra are opening acidulant procurement channels previously dominated by Chinese supply.
- Carbonated water and seltzer segments:Zero-calorie flavored sparkling categories require acidulant systems for taste modulation without caloric sweeteners, creating formulation specification demand.
Industry Challenges
- Fermentation process engineering talent scarcity:Industrial microbiology and bioprocess optimization expertise concentrates in legacy pharmaceutical and enzyme manufacturing regions, complicating new facility staffing.
- GRAS self-affirmation documentation timelines:Novel acidulant blends or fermentation-derived variants require extensive toxicological dossiers under 21 CFR pathways that delay commercialization by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Acidulants Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Malic Acid, Tartaric Acid, Lactic Acid Application: Sodas, Sports Drinks, Fruit Juices, Energy Beverages Form: Liquid, Powder, Granular, Crystalline End User: Manufacturers, Distributors, Retailers, Food Service |
| Companies Covered | Tate & Lyle, Cargill Incorporated, Archer Daniels Midland Company, Corbion N.V., Parry Enterprises India Ltd., Northeast Pharmaceutical Group Co., Ltd., FBC Industries, Inc., Batory Foods, DairyChem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Acidulants Market Emerging Trajectories
Biotechnological process innovation and regulatory carbon accounting are converging to redefine acidulant manufacturing economics and procurement criteria across beverage value chains.
Precision fermentation for organic acid production is hybridizing with conventional chemical synthesis as equipment suppliers integrate continuous bioreactor designs with downstream crystallization systems. Mid-scale beverage ingredient processors are adopting these hybrid platforms to escape commodity pricing traps. The technology is compressing minimum efficient scale thresholds and enabling regional distributed production models.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-dependent purification technology obsolescence across acidulant processing facilities. Manufacturers face capital allocation decisions between cryogenic retrofit and alternative separation technologies. European citric acid importers are demanding supplier documentation of low-global-warming-potential process cooling systems.
Scope-three emissions auditing is penetrating beverage acidulant procurement specifications as multinational bottlers face CSRD-mandated supply chain disclosure requirements. Category managers are substituting traditional price-per-kilogram metrics with carbon-adjusted total cost models. This recalibration is most visible in German and Dutch beverage manufacturing clusters where retailer sustainability scorecards influence ingredient sourcing decisions.
Beverage Acidulants Market Segmentation
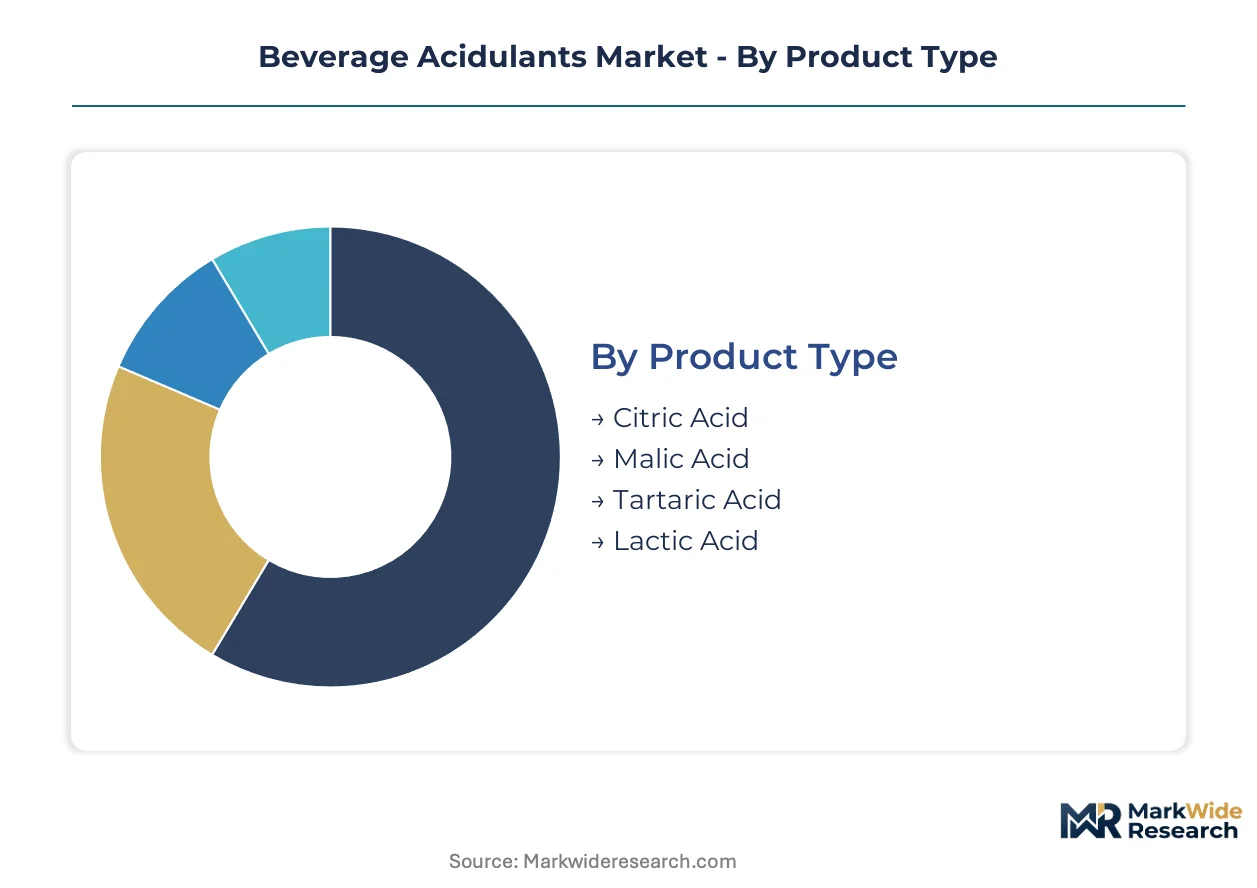
Beverage acidulant procurement varies sharply across product chemistry, formulation requirements, and supply chain position. Manufacturers configure acidulant portfolios around pH modulation precision, dissolution kinetics, and clean-label positioning rather than commodity sourcing alone.
Product Type:
Cost tier stratification separates fermentation-scale commodities from specialty organic acids commanding formulation premiums.
- Citric Acid:Fermentation-derived from Aspergillus niger on corn dextrose substrate, this acid delivers universal compatibility with fruit-flavored systems and rapid pH depression. Chinese Shandong Province producers dominate volume supply, though EU F-Gas Regulation compliance costs are compressing margins on imported material. Manufacturers seeking carbon-adjusted sourcing increasingly demand documentation of renewable feedstock ratios.
- Malic Acid:Slower dissociation kinetics prolong tartness perception in energy beverages where sustained flavor release differentiates brand experience. Corbion N.V. and select fermentation specialists command premium positioning through bio-based certification pathways, with demand concentrating in German and Dutch beverage manufacturing clusters facing scope-three disclosure mandates.
- Tartaric Acid:Grape-derived stereoisomer configurations serve wine-based coolers and premium cocktail mixers requiring specific optical rotation properties.
- Lactic Acid:Dairy fermentation heritage supports probiotic-positioned functional beverages, with PURAC and comparable suppliers targeting gut-health formulation trends.
Citric acid commands the established base. The steepest expansion runs through malic acid.
Application:
End-use formulation requirements dictate acidulant selection through pH targets, microbial stability windows, and flavor modulation intensity.
- Sodas:Carbonated soft drinks rely on citric acid for sharp, clean tartness that cuts through high-sugar matrices without residual aftertaste. Coca-Cola and PepsiCo procurement specifications emphasize consistent hydration-grade purity and supply security over unit cost minimization.
- Sports Drinks:Isotonic formulations require precise pH buffering to maintain electrolyte bioavailability and palatability during exertion. Gatorade and Powerade supply chains specify malic-citric blends that sustain tartness perception through consumption duration.
- Fruit Juices:Natural acidity supplementation preserves shelf stability in pasteurized concentrates without synthetic preservative declarations.
- Energy Beverages:Caffeine-acidulant synergy demands rapid gastric emptying rates that malic acid systems facilitate.
Sports drinks anchor volume procurement. Energy beverages are climbing the fastest.
Form:
Physical state determines handling economics, dosing precision, and integration compatibility with existing processing infrastructure.
- Powder:Spray-dried or milled crystalline material enables precise gravimetric dosing in batch-compounding operations. Powder dominates contract manufacturing facilities serving mid-tier beverage brands without continuous liquid injection capabilities.
- Liquid:Pre-dissolved acid solutions integrate directly into continuous-flow bottling lines, eliminating dissolution tanks and reducing cleaning cycle frequency. Coca-Cola FEMSA and comparable bottlers in Mexico and Brazil specify liquid citric acid for high-speed carbonated production.
- Granular:Intermediate particle size balances flowability with dissolution rate for hybrid processing environments.
- Crystalline:High-purity anhydrous or monohydrate crystals serve pharmaceutical-adjacent beverage applications demanding USP-grade documentation.
Powder formulations retain the installed base. Liquid systems are gaining share fastest.
End User:
Supply chain position shapes procurement sophistication, with direct manufacturers exercising specification authority that downstream intermediaries cannot replicate.
- Manufacturers:PepsiCo, Nestlé Waters, and Keurig Dr Pepper maintain dedicated acidulant procurement teams that audit fermentation source, carbon intensity, and GRAS documentation. These stakeholders negotiate multi-year supply agreements with fermentation specialists.
- Distributors:Univar Solutions and Brenntag aggregate fragmented regional demand from smaller bottlers, carrying inventory risk and blending services that justify margin capture.
- Retailers:Private-label beverage programs at Walmart and Costco specify acidulant systems through co-manufacturer contracts rather than direct chemical procurement.
- Food Service:Fountain syrup compounding for quick-service restaurants demands acidulant stability in concentrated form under ambient storage.
Manufacturers control specification authority. Distributor channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping acidulant trade flows as Chinese fermentation capacity saturates domestic demand and European carbon disclosure rules redirect procurement patterns. Shandong Province suppliers now compete with Southeast Asian toll manufacturers for regional beverage processing contracts.
China
Domestic fermentation infrastructure in Shandong Province supplies over half of global citric acid volume, with producers scaling continuous bioreactor platforms to capture carbonated beverage demand across Southeast Asia. SAMR's GB standards mandate stricter contaminant thresholds for acidulants used in infant formula-adjacent beverages. Qingdao and Jinan industrial clusters host integrated dextrose-to-acid facilities that bypass import tariff exposure.
United States
Midwest corn belt proximity sustains dextrose feedstock cost advantages for domestic citric acid fermentation, though beverage manufacturers increasingly audit scope-three emissions from agricultural inputs. FDA's 21 CFR GRAS pathways govern novel acidulant blend approvals, with self-affirmation timelines stretching commercialization schedules. Chicago and Minneapolis distribution hubs consolidate procurement for Coca-Cola and PepsiCo bottling networks.
Germany
Carbon-adjusted total cost models now dominate acidulant procurement at beverage manufacturing clusters in Bavaria and North Rhine-Westphalia, driven by CSRD-mandated supply chain disclosures. ECHA's REACH residual solvent documentation requirements filter synthetic acidulant imports toward fermentation-verified suppliers. Hamburg port infrastructure handles redirected volumes as buyers bypass Chinese supply concentration.
India
FSSAI modernization and multinational bottler investments in Gujarat and Maharashtra are opening acidulant procurement channels previously captured by Chinese exporters. Domestic fermentation specialists scale malic acid capacity to serve energy beverage formulation demand. Mumbai and Ahmedabad industrial corridors attract toll manufacturing contracts from European acidulant traders seeking tariff diversification.
Brazil
São Paulo and Rio de Janeiro beverage manufacturing clusters specify liquid citric acid for high-speed carbonated production lines, with Coca-Cola FEMSA procurement teams prioritizing continuous-flow integration over batch processing economics. ANVISA's food additive purity frameworks align with FDA specifications, reducing documentation burden for US-sourced acidulants. Regional distributors aggregate fragmented demand from mid-tier juice processors in Minas Gerais.
Beverage Acidulants Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying fermentation-derived acids to formulation houses. The market structures around three concentration nodes: agricultural commodity processors with captive dextrose supply, dedicated organic acid fermentation specialists, and toll manufacturers operating asset-light bioreactor networks. Two competitive moves dominate capital allocation—backward integration into corn processing and geographic diversification of fermentation capacity to escape Shandong supply concentration.
Among agricultural-commodity-based processors, Cargill Incorporated and Archer Daniels Midland Company exemplify feedstock-integrated archetypes that convert corn dextrose into acidulant output. Tate & Lyle occupies a position within the European fermentation-specialist tier, while Corbion N.V. represents bio-based malic acid positioning toward premium beverage formulations. These three names anchor the competitive map without exhausting its topography.
| Leading Market Players |
|---|
| Tate & Lyle |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Corbion N.V. |
| Parry Enterprises India Ltd. |
| Northeast Pharmaceutical Group Co., Ltd. |
| FBC Industries, Inc. |
| Batory Foods |
| DairyChem |
| Others |
Supply Flow & Price Mechanics
Shandong Province supply concentration determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic shape of acidulant procurement networks. Corn dextrose feedstock volatility feeds directly into fermentation cost curves, compressing margins on commodity citric acid while bio-based certification premiums expand spreads at the specialty tier.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments against price volatility. Price differentiation rests on fermentation source verification and EU Ecolabel certification tier, with carbon-adjusted total cost models gaining traction among German beverage manufacturers. Cost compression in standard-grade citric acid is intensifying because Chinese capacity expansion outpaces demand absorption. Mid-tier contract manufacturers exhibit highest price sensitivity, while multinational bottlers prioritize supply security over unit cost minimization.
Supply Chain Analysis
REACH residual solvent documentation functions as de facto export controls limiting synthetic acidulant flows into European markets. Manufacturing gravity centers on China, the United States, and Germany, with raw material dependencies spanning corn dextrose, Aspergillus niger cultures, and downstream crystallization equipment. Single-source vulnerability concentrates in Shandong fermentation clusters exposed to regional energy rationing. Distribution runs through Univar Solutions and Brenntag regional hubs that aggregate fragmented bottler demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—GRAS self-affirmation timelines stretching 18-36 months—protects incumbent positions against rapid competitive entry. Switching costs lock beverage manufacturers into validated acidulant supply relationships.
For Market Incumbents: Harden backward integration into corn dextrose feedstock to escape agricultural commodity volatility, while expanding fermentation capacity in Gujarat and Maharashtra to diversify beyond Shandong concentration risk. Invest in USDA BioPreferred certification infrastructure to capture premium pricing from scope-three disclosure mandates at Dutch and German bottlers. For New Entrants and Emerging Players: Pursue toll manufacturing contracts with European acidulant traders seeking tariff diversification through Mumbai and Ahmedabad industrial corridors. Energy beverage malic acid formulations represent the most penetrable segment, given Corbion N.V. premium positioning leaves mid-tier price points exposed. Lead with liquid acidulant systems for continuous-flow bottling lines where installed powder infrastructure creates conversion friction. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-specialist acquisition targets with verified renewable carbon content documentation. Long-term viability hinges on bioprocess engineering talent scarcity creating sustainable competitive differentiation. Watch for FSSAI enforcement modernization in India as inflection indicator for procurement channel redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Dextrose | Cargill Incorporated leverages captive feedstock supply to sustain cost advantages against Chinese fermentation exports. |
| Bio-based Certification Investment | USDA BioPreferred and EU Ecolabel pathways enable price differentiation for verified renewable carbon content acidulants. |
| Geographic Capacity Diversification | Gujarat and Maharashtra fermentation facilities reduce tariff exposure and capture FSSAI modernization procurement shifts. |
| Liquid Acidulant System Expansion | Coca-Cola FEMSA procurement specifications favor continuous-flow integration over batch processing economics. |
| Scope-three Emissions Documentation | CSRD-mandated supply chain disclosures at German bottlers recalibrate procurement toward carbon-adjusted total cost models. |
Methodological Framework
Desk research of customs trade databases, SEC 10-K filings, and ECHA REACH registration dossiers preceded structured interviews with beverage formulation chemists, acidulant procurement managers at multinational bottlers, fermentation plant engineers, and distribution channel partners. Bottom-up volume estimates triangulated against top-down market sizing from corn dextrose consumption patterns and beverage production statistics.
Assumptions held fixed include EFSA guidance trajectory on artificial additive reduction and EU F-Gas Regulation phase-down schedules, while corn dextrose pricing and Shandong environmental enforcement intensity were modeled as variable inputs. Segmentation dimensions covered acidulant chemistry type, beverage application category, physical form factor, and end-user supply chain position. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window.
Sensitivities concentrate around SAMR contaminant threshold revisions and CSRD enforcement intensity at German manufacturing clusters. Forecasts reflect documented assumptions on fermentation yield improvements and carbon accounting methodology standardization. Material shifts in REACH residual solvent documentation requirements or Shandong energy rationing severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Oxygen Absorbers Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Italy Food Enzymes Market