
 Flavor Encapsulation Market | 2026-2036
Flavor Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor Encapsulation Market Foresight
Buyer concentration among multinational beverage producers is hardening as procurement teams consolidate supplier rosters around full-service encapsulation partners. Givaudan leverages integrated flavor creation and delivery systems to lock in multi-year supply agreements with top-tier drink manufacturers. Kerry Group anchors its position through captive spray-drying infrastructure across three continents. Firmenich competes on proprietary coacervation IP that protects volatile top-notes in low-pH functional beverages.
Flavor encapsulation encloses volatile aromatic compounds within protective matrices—typically gum arabic, modified starches, or lipid shells—to prevent oxidation, evaporation, and premature release during thermal processing or storage. Spray drying dominates commercial output due to its cost efficiency and throughput scale, though liposomal encapsulation commands premium positioning in nutritional supplements where bioavailability drives formulation value. Coacervation occupies the fastest-growing segment as clean-label confectionery brands reject synthetic fixatives. Fruit concentrates and botanical essences represent the core material categories where margin pools deepen, particularly for organic-certified inputs facing supply scarcity.
FDA oversight of Generally Recognized As Safe determinations and EFSA enforcement of novel food regulations shape which encapsulation carriers gain market access in the United States and European Union. REACH compliance for wall-material chemistries and FSSAI labeling mandates in India add compliance layers that favor suppliers with established regulatory dossiers. Stakeholders must monitor evolving natural-flavor definitions across jurisdictions, as reclassification risk threatens existing product registrations and opens displacement opportunities for compliant alternatives.
Market Dynamics
Clean-label regulatory pressure from FDA and EFSA is forcing beverage and confectionery manufacturers to abandon synthetic preservatives, creating urgent demand for natural encapsulation carriers that protect volatile flavors without chemical additives. This structural shift concentrates procurement power among multinational brands seeking full-service partners with proven regulatory dossiers.
Growth Catalysts
- Spray-drying infrastructure expansion:Captive production facilities across three continents enable just-in-time delivery to beverage manufacturers, reducing working capital requirements for volatile flavor inputs.
- EFSA novel food regulations:Accelerated approval pathways for natural extract carriers in the European Union open displacement opportunities against synthetic alternatives facing reclassification risk.
- Functional beverage proliferation:Low-pH vitamin waters and probiotic drinks require advanced coacervation systems to shield citrus and botanical top-notes from acidic degradation during shelf life.
Market Restraints
- Organic-certified input scarcity:Supply concentration for gum arabic in Sudan and Chad creates price volatility and ethical sourcing risks for clean-label formulations.
- REACH compliance burden:Wall-material chemistries face extended registration timelines and testing costs that disadvantage smaller encapsulation specialists without dedicated regulatory teams.
- Lipid shell oxidation sensitivity:Technical limitations in high-temperature processing environments restrict lipid-based encapsulation to ambient or chilled applications, excluding hot-fill beverage segments.
Strategic Opportunities
- India FSSAI labeling mandates:New disclosure requirements for artificial flavoring create immediate replacement demand for encapsulated natural extracts in domestic confectionery and beverage markets.
- Coacervation-confectionery convergence:Premium chocolate brands in Germany and Switzerland reject synthetic fixatives, opening formulation partnerships for heat-stable encapsulated fruit essences.
- Direct-to-brand digital sampling:Online platforms enable mid-sized beverage startups to test encapsulated prototypes without minimum order commitments, democratizing access to advanced delivery technologies.
Industry Challenges
- Spray-drying operator scarcity:Specialized knowledge of atomization parameters and matrix optimization commands premium wages, constraining capacity expansion timelines for contract manufacturers.
- Coacervation IP fragmentation:Proprietary complexation methods face licensing disputes across multiple jurisdictions, complicating technology transfer and joint development agreements.
- Legacy thermal processing integration:Encapsulated flavors require recalibration of UHT and retort lines originally designed for synthetic stabilizers, demanding capital investment and line downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor Encapsulation Market |
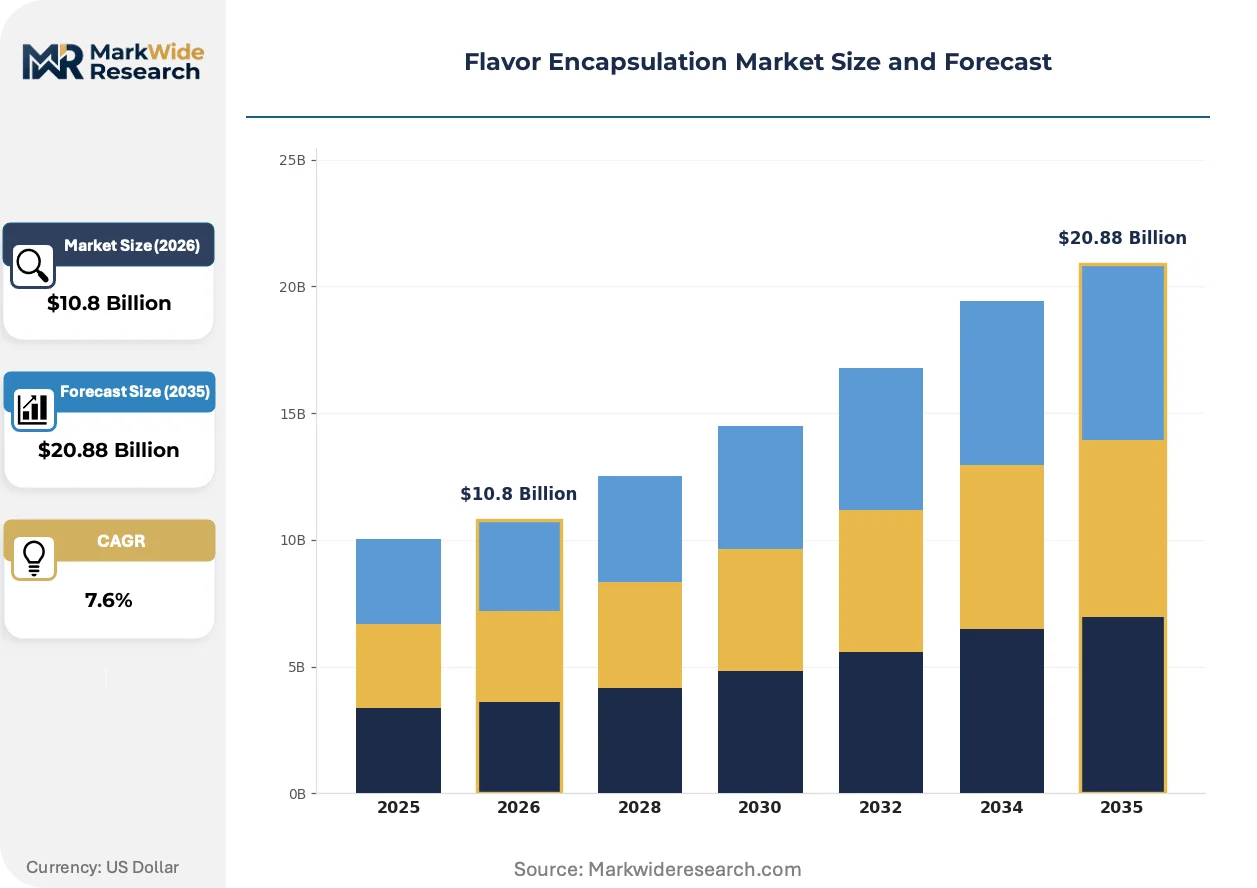
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $20.88 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Encapsulation Technique: Spray Drying, Coacervation, Freeze Drying, Extrusion, Fluidized Bed, Liposomal Encapsulation Core Material Type: Essential Oils, Natural Extracts, Artificial Flavors, Fruit Concentrates, Spice Extracts, Botanical Essences Application Area: Beverages, Confectionery, Sauces & Dressings, Bakery Products, Dairy Alternatives, Nutritional Supplements End User Industry: Food Manufacturers, Flavor Houses, Nutraceutical Companies, Beverage Producers, Ingredient Suppliers, Food Service Providers |
| Companies Covered | Firmenich, Kerry Group, Givaudan, Takasago International Corporation, Cargill, International Flavors & Fragrances, Sensient Technologies Corporation, Ingredion Incorporated, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor Encapsulation Market Shifts & Advancements
Liposomal encapsulation is advancing from nutritional supplements into mainstream beverage applications, driven by bioavailability claims and clean-label positioning. Three interconnected developments are restructuring competitive advantage in flavor delivery systems.
Microfluidic manufacturing is decentralizing production economics for liposomal flavor carriers. Equipment costs below $500,000 enable regional contract manufacturers to enter premium encapsulation services previously dominated by capital-intensive spray-drying operations. Functional drink brands in Japan and South Korea now source liposomal citrus matrices from domestic microfluidic specialists rather than importing spray-dried alternatives.
REACH authorization requirements for novel wall-material chemistries are compressing innovation cycles in the European Union. Suppliers must submit comprehensive toxicological dossiers to ECHA before commercializing modified starch derivatives or protein-based carriers. German and Dutch encapsulation houses are responding by pre-submitting regulatory packages for next-generation coacervation systems, securing multi-year approval advantages over competitors awaiting authorization.
Certification-driven procurement is restructuring supplier selection criteria for multinational beverage brands. Buyers now mandate organic certification, carbon footprint disclosure, and ethical sourcing verification alongside technical performance specifications. United States-based functional drink manufacturers prioritize suppliers with USDA Organic and B Corp certifications, compressing margins for conventional encapsulation houses lacking sustainability credentials.
Flavor Encapsulation Market Segmentation
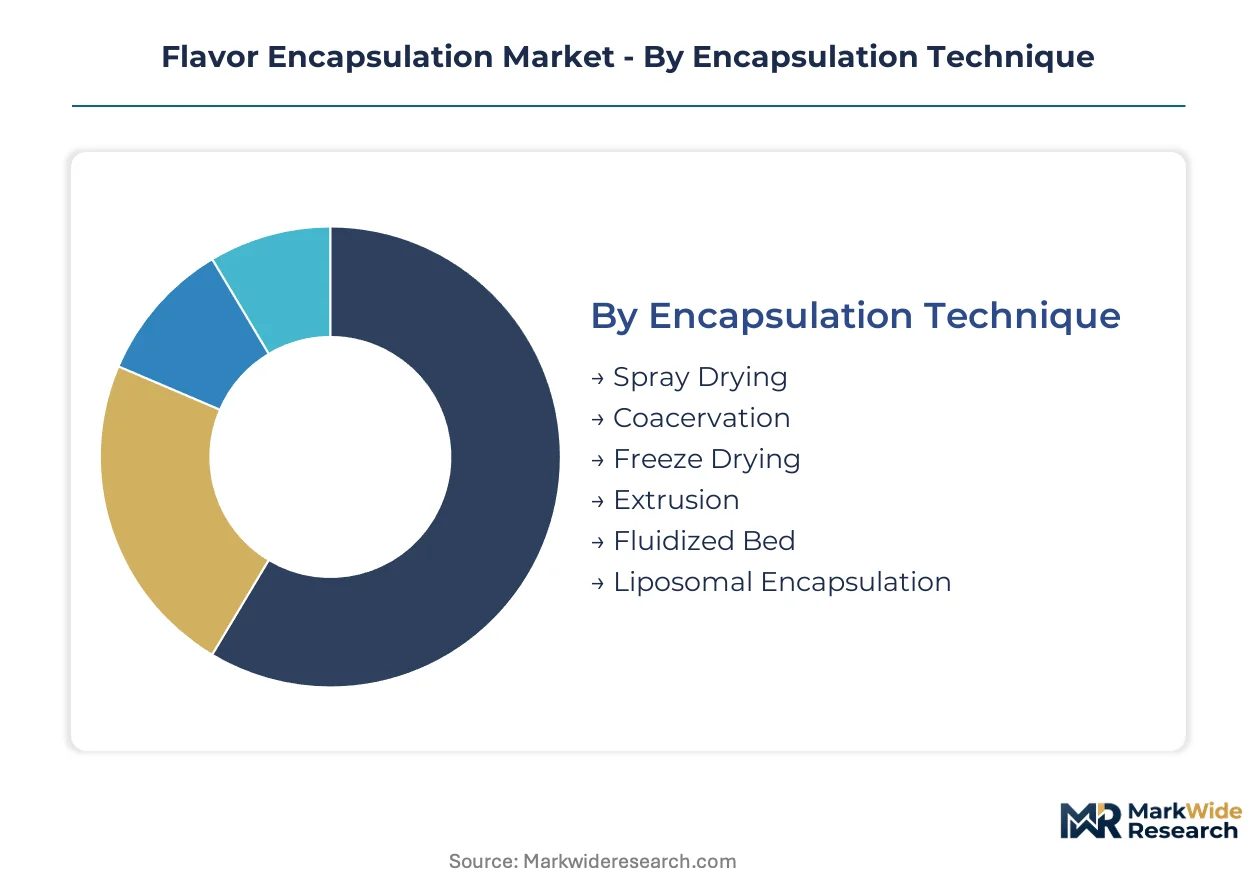
Segmentation in flavor encapsulation determines which carriers gain regulatory clearance and which technologies command formulation premiums. Certification requirements vary sharply across encapsulation methods and core materials, reshaping supplier selection criteria for multinational brands.
Encapsulation Technique:
FDA Generally Recognized As Safe determinations and EFSA novel food regulations apply differentially across these methods, with spray drying holding the broadest pre-approved status while liposomal systems face extended toxicological review.
- Spray Drying:Atomization of flavor emulsions into heated chambers deposits volatile compounds within carbohydrate or protein matrices. Dominates commercial output due to established GRAS status and throughput economics. Demand concentrates among United States beverage producers seeking cost-efficient citrus protection for high-volume functional drinks.
- Coacervation:Phase separation of hydrocolloid complexes around flavor oil cores creates multi-layered shells with superior oxidative barrier properties. German and Swiss confectionery brands specify coacervated botanical essences for premium chocolate applications where synthetic fixatives are rejected.
- Freeze Drying:Sublimation-based dehydration preserves heat-sensitive aromatic profiles in low-temperature conditions. Specialty coffee and tea extract houses in Japan employ this method for volatile top-note retention.
- Extrusion:High-pressure mechanical forcing of flavor-carrier mixtures through dies produces glassy matrices. Limited adoption due to thermal degradation risks during processing.
- Fluidized Bed:Suspension coating of core particles within upward air streams enables layered shell construction. Niche positioning in spice extract encapsulation for ambient-stable seasoning blends.
- Liposomal Encapsulation:Phospholipid bilayer vesicles enclose hydrophobic flavor compounds for enhanced bioavailability claims. Nutraceutical companies in South Korea and Japan source liposomal citrus matrices for premium positioning.
Leading the category by volume: Spray Drying. Growing fastest: Coacervation.
Core Material Type:
Cost tiers separate commodity artificial flavors from certified-natural inputs where organic scarcity commands substantial premiums.
- Essential Oils:Highly concentrated volatile compounds distilled from plant sources require robust oxidative protection. Citrus oil encapsulation dominates functional beverage formulations in the United States and Germany.
- Natural Extracts:Solvent or water-derived flavoring substances from botanical sources face EFSA novel food classification if extraction methods deviate from traditional processes. Clean-label beverage brands mandate natural extract carriers to satisfy FDA and EFSA preservative-free positioning.
- Artificial Flavors:Synthetic aromatic compounds produced through chemical synthesis occupy economy-tier applications. Contraction trajectory as regulatory pressure and consumer preference shift procurement toward natural alternatives.
- Fruit Concentrates:Reduced water-content fruit preparations encapsulate for extended shelf stability. Premium confectionery applications in Switzerland and Germany specify organic-certified concentrates facing supply scarcity from Sudanese and Chadian gum arabic dependencies.
- Spice Extracts:Oleoresins and essential oil fractions from pepper, cinnamon, and cardamom. Fluidized bed encapsulation serves ambient-stable sauce and dressing segments.
- Botanical Essences:Complex aromatic profiles from herbs, flowers, and plant resins. Coacervation protects volatile top-notes in low-pH probiotic beverages where acidic degradation threatens sensory performance.
Highest margin concentration: Botanical Essences. Steepest expansion trajectory: Natural Extracts.
Application Area:
Customer type determines performance specifications, with beverage producers demanding acid stability and confectionery brands prioritizing heat resistance.
- Beverages:Functional drink manufacturers in the United States and Japan require coacervation systems for citrus and botanical protection in low-pH vitamin waters. Shelf-life extension without synthetic preservatives drives specification.
- Confectionery:Premium chocolate brands in Germany and Switzerland reject synthetic fixatives, creating formulation partnerships for heat-stable encapsulated fruit essences.
- Sauces & Dressings:Acidic emulsion systems require lipid-shell or modified starch encapsulation for volatile spice and herb retention. Food service procurement emphasizes cost efficiency over premium carrier technologies.
- Bakery Products:Thermal processing during baking demands heat-stable encapsulation matrices. Marginal segment due to flavor volatilization at oven temperatures exceeding carrier protection thresholds.
- Dairy Alternatives:Plant-based milk and yogurt applications require neutral-pH compatible carriers. Emerging segment as oat and almond base formulations proliferate.
- Nutritional Supplements:Bioavailability claims drive liposomal encapsulation adoption. South Korean and Japanese nutraceutical companies specify phospholipid carriers for premium positioning.
Dominant volume share: Beverages. Gaining share fastest: Nutritional Supplements.
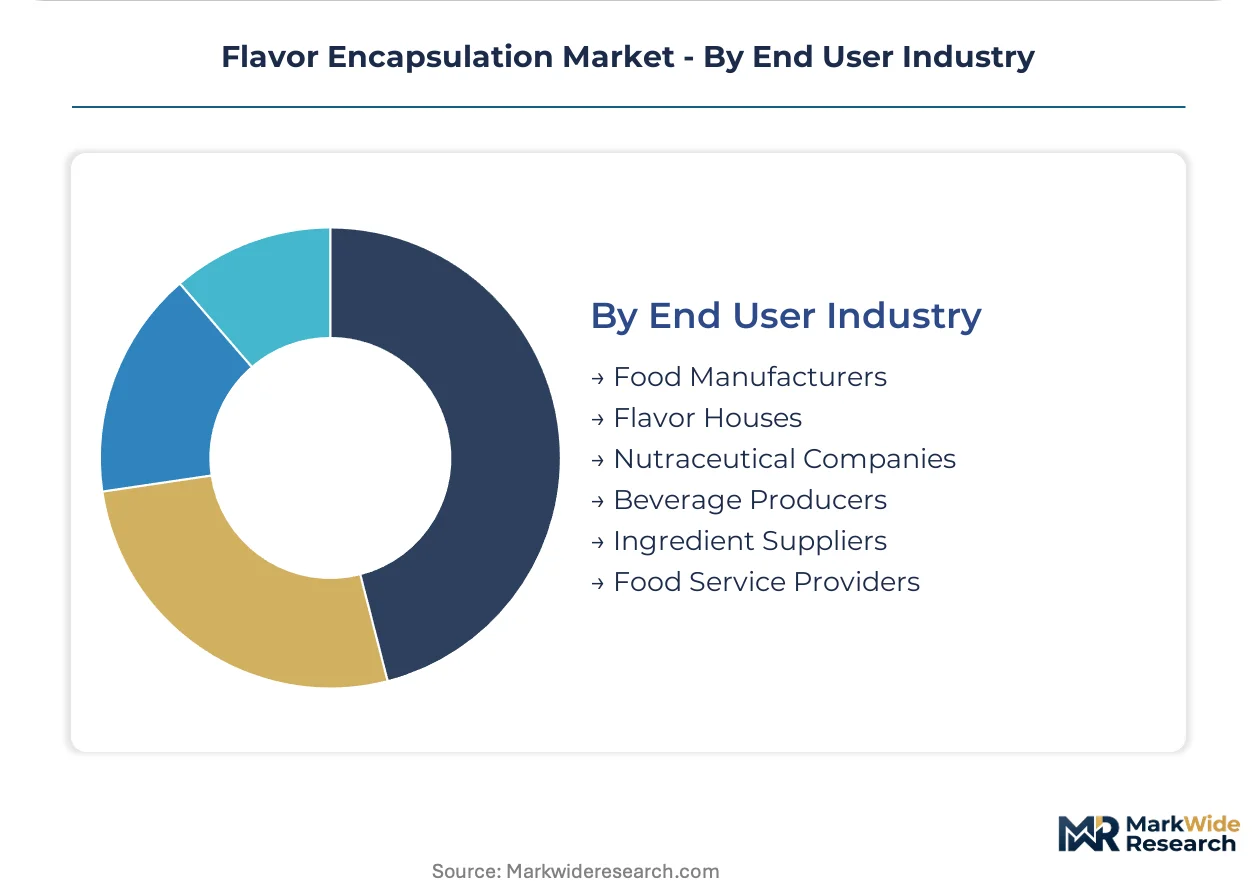
End User Industry:
Supply concentration favors full-service encapsulation partners with captive infrastructure and established regulatory dossiers.
- Food Manufacturers:Integrated procurement of encapsulated flavors for multiple product lines. Consolidating supplier rosters around partners with spray-drying capacity across three continents.
- Flavor Houses:Integrated creation and delivery systems lock in multi-year supply agreements. Givaudan and Firmenich compete on proprietary coacervation IP for volatile top-note protection.
- Nutraceutical Companies:Bioavailability-driven specification of liposomal carriers. South Korean and Japanese buyers prioritize domestic microfluidic specialists over imported spray-dried alternatives.
- Beverage Producers:Direct formulation partnerships with encapsulation houses for proprietary delivery systems. Procurement teams mandate carbon footprint disclosure and ethical sourcing verification alongside technical performance.
- Ingredient Suppliers:Intermediate positioning between raw material producers and finished goods manufacturers. Margin compression from certification-driven procurement requirements.
- Food Service Providers:Cost-sensitive bulk purchasing of economy-tier encapsulated flavors. Limited specification influence compared to branded goods manufacturers.
Concentrating procurement power: Beverage Producers. Expanding most quickly: Nutraceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sudanese and Chadian gum arabic belts anchor raw-material supply for hydrocolloid carriers, while formulation demand clusters in beverage manufacturing hubs across three continents.
United States
Functional drink manufacturers in California and New York State specify coacervation systems for citrus protection in low-pH vitamin waters. FDA Generally Recognized As Safe determinations favor spray-dried carriers with established dossiers. Chicago-area procurement teams consolidate supplier rosters around partners with captive infrastructure.
Germany
Premium chocolate brands in Bavaria and Baden-Württemberg reject synthetic fixatives, creating formulation partnerships for heat-stable encapsulated fruit essences. EFSA novel food regulations accelerate approval pathways for natural extract carriers. Cologne and Hamburg host flavor houses competing on proprietary coacervation IP.
Japan
Nutraceutical companies in Tokyo and Osaka source liposomal citrus matrices from domestic microfluidic specialists. METI standards shape phospholipid carrier specifications for bioavailability claims. Kanto region beverage startups test encapsulated prototypes through direct-to-brand digital sampling platforms.
India
FSSAI labeling mandates for artificial flavoring create replacement demand in Maharashtra and Gujarat confectionery markets. Mumbai-based procurement teams prioritize suppliers with carbon footprint disclosure. Bangalore functional beverage brands require acid-stable encapsulation for probiotic drink formulations.
Switzerland
Swissmedic oversight of novel food additives shapes carrier approval timelines for Zurich and Geneva flavor houses. Premium confectionery manufacturers specify organic-certified botanical essences facing supply scarcity. Basel-area encapsulation specialists pre-submit regulatory packages for next-generation coacervation systems.
Flavor Encapsulation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microfluidic manufacturing and regional contract services. The supplier base concentrates around full-service encapsulation partners with captive spray-drying infrastructure across multiple continents. Three archetypes dominate: integrated flavor houses with proprietary delivery IP, ingredient suppliers with backward control over hydrocolloid sources, and regional specialists leveraging microfluidic equipment economics. Competitive moves center on multi-year supply agreement lock-ins and pre-submission of regulatory dossiers for novel carrier chemistries.
Among Swiss and Irish flavor houses, Firmenich, Kerry Group, and Givaudan exemplify the integrated archetype combining flavor creation with encapsulation delivery systems. These entities occupy positions where proprietary coacervation methods and captive production infrastructure anchor multi-continental supply relationships. Their market presence reflects the premium-tier concentration around full-service partners capable of meeting certification-driven procurement criteria from multinational beverage brands.
| Leading Market Players |
|---|
| Firmenich |
| Kerry Group |
| Givaudan |
| Takasago International Corporation |
| Cargill |
| International Flavors & Fragrances |
| Sensient Technologies Corporation |
| Ingredion Incorporated |
| Symrise AG |
| Others |
Supply & Pricing Matrix
Multinational beverage procurement teams consolidate supplier rosters around full-service encapsulation partners, compressing margins for single-technology houses and rewarding integrated players with captive spray-drying infrastructure across three continents. This buyer concentration enforces three-tier pricing structure across premium, standard, and economy levels based on certification grade and volume scale.
Pricing Analysis
High-volume spray-dried citrus carriers for functional beverages occupy the economy tier with thin margins, while liposomal encapsulation for Japanese nutraceuticals commands premium positioning through bioavailability claims. Price differentiation separates organic-certified botanical essences from conventional alternatives, with Sudanese gum arabic scarcity driving cost premiums for clean-label formulations. Pricing pressure stems from REACH compliance burdens that disadvantage smaller specialists without dedicated regulatory teams. Contract manufacturers face acute price sensitivity, whereas premium chocolate brands in Germany and Switzerland absorb higher costs for heat-stable coacervated fruit essences.
Supply Chain Analysis
Ocean freight volatility from Sudan and Chad through European ports elevates landed costs for gum arabic hydrocolloids, the dominant wall-material for spray-dried and coacervated carriers. Raw material sourcing draws from Sudanese acacia belts, Indian modified starch processors, and German phospholipid suppliers for liposomal systems. Single-source vulnerability concentrates in gum arabic supply from conflict-affected regions, with ethical sourcing verification now mandatory for multinational brand procurement. Distribution runs through regional contract manufacturers with captive spray-drying capacity, bypassing import dependencies for time-sensitive beverage formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flavor encapsulation market is becoming a vertical-integration race as players pursue backward control over Sudanese gum arabic supply and captive spray-drying capacity to defend margin position against procurement consolidation.
For Market Incumbents: Anticipate displacement from microfluidic regional specialists in Japan and South Korea by pre-submitting ECHA regulatory dossiers for next-generation coacervation systems before competitors secure approval advantages. Deepen backward integration into Sudanese and Chadian gum arabic sourcing through direct farm-gate partnerships, reducing exposure to commodity volatility and ethical sourcing audit failures.
For New Entrants and Emerging Players: Capture white-space in Indian domestic confectionery markets where FSSAI labeling mandates for artificial flavoring create immediate replacement demand for encapsulated natural extracts. Target Bangalore functional beverage startups through direct-to-brand digital sampling platforms that eliminate minimum order barriers, then scale to Mumbai-based procurement teams demanding carbon footprint disclosure.
For Investors and Strategic Acquirers: The window for entry favors regional microfluidic specialists with equipment costs below $500,000 and established relationships with South Korean nutraceutical companies. Acquisition candidates should demonstrate EFSA novel food approval progress or USDA Organic certification pipelines. Watch for ECHA authorization timelines as inflection indicators that will separate multi-year approval leaders from stranded technology portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gum Arabic Sourcing | Direct farm-gate partnerships in Sudan reduce ethical sourcing audit failures and price volatility exposure. |
| Pre-Submission of ECHA Regulatory Dossiers | Early REACH authorization for protein-based carriers secures multi-year advantage over awaiting competitors. |
| Microfluidic Manufacturing Scale-Up | Equipment costs below $500,000 enable regional contract services previously dominated by spray-drying operations. |
| Direct-to-Brand Digital Sampling Platforms | Online prototype testing eliminates minimum order commitments for mid-sized beverage startups in Japan. |
| Carbon Footprint Disclosure Certification | USDA Organic and B Corp credentials satisfy multinational beverage procurement mandates compressing conventional margins. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with spray-drying plant managers, beverage procurement leads, flavor house R&D directors, and FSSAI regulatory consultants. Secondary sources included FDA GRAS determination databases, EFSA novel food registers, ECHA authorization timelines, and Indian customs import records for gum arabic derivatives. Bottom-up capacity modeling across encapsulation techniques triangulated against top-down demand projections from functional beverage production data.
Granularity-level modeling operated at the intersection of encapsulation method, core material certification grade, and end-use application performance specifications. Segmentation dimensions included carrier technology, organic certification status, pH stability requirements, and regional regulatory cluster. CAGRs were derived through trend extrapolation of procurement consolidation patterns and approval pathway timelines. Forecast inputs incorporated spray-drying operator wage inflation and gum arabic supply concentration metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA reclassification of natural flavor definitions and Sudanese supply disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Food Stabilizer Systems Market