
 Asia Pacific Fruits and Vegetables Juice Market | 2026-2036
Asia Pacific Fruits and Vegetables Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Fruits and Vegetables Juice Market Outlook
Skilled cold-press technicians is rotating from boutique startups into scaled manufacturing facilities across the region. PepsiCo Inc leverages its bottling infrastructure to anchor distribution in Southeast Asian convenience channels. Dabur India Ltd sustains Ayurvedic ingredient differentiation through in-house herb sourcing networks. The Coca-Cola Company competes via fortified juice portfolios targeting India's pharmacy retail segment.
Asia Pacific fruits and vegetables juice comprises unconcentrated or reconstituted liquid extracts from raw produce, typically processed through mechanical pressing, enzymatic treatment, or high-pressure processing to retain bioactive compounds such as ascorbic acid and polyphenols, serving refreshment, nutrition supplementation, and functional health applications. Juice blends lead volume due to flavor customization and cost flexibility in tropical formulations. 100% juice segments command premium shelf positioning in China's tier-one supermarkets. Pouch packaging is capturing fastest growth in India's price-sensitive rural markets through unit-dose affordability.
India's FSSAI mandates preservative labeling and maximum microbial limits that reshape product formulation roadmaps for domestic manufacturers. China's SAMR enforces GB standards for juice content declarations, restricting dilution practices in concentrate-to-ready-to-drink conversions. Australia's FSANZ nutrient profiling criteria influence export eligibility for regional suppliers targeting premium channels. Stakeholders must monitor evolving shelf-life extension claims against tightening additive regulations before committing to new production lines.
Market Dynamics
Cold-pressed extraction technology is compressing nutrient degradation timelines across Asia Pacific manufacturing facilities, forcing legacy thermal processors to retool or exit premium segments entirely.
Growth Catalysts
- Urban millennial demand clusters:Health-conscious consumers in Shanghai, Mumbai, and Jakarta are pulling functional beverages into daily consumption routines, expanding addressable volume beyond traditional refreshment occasions.
- FSSAI preservative labeling mandates:India's tightening disclosure requirements are accelerating clean-label reformulation investments, advantaging domestic manufacturers with captive herb sourcing infrastructure.
- High-pressure processing adoption:This non-thermal pasteurization method is extending refrigerated shelf life without chemical additives, unlocking modern trade distribution for regional juice brands.
Market Restraints
- Tropical fruit input volatility:Mango, pineapple, and passion fruit harvests across Thailand and Vietnam face climate-induced yield compression, squeezing margin structures for blend-dependent producers.
- GB standards compliance costs:China's juice content declaration requirements impose analytical testing burdens that disproportionately burden small and mid-scale manufacturers in inland provinces.
- Refrigerated logistics fragmentation:Cold chain gaps between processing centers and tier-three Chinese cities limit penetration of premium chilled juices outside eastern seaboard clusters.
Strategic Opportunities
- Rural India pouch expansion:Unit-dose affordability at price points below bottled alternatives is capturing first-time juice consumers in Maharashtra and Uttar Pradesh village retail.
- Ayurvedic functional positioning:Ashwagandha, turmeric, and amla fortification aligns with wellness trends while leveraging India's traditional medicine regulatory familiarity under FSSAI.
- Pharmacy channel anchoring:India's chemist retail networks offer validated health positioning for fortified portfolios, accessing consumers seeking nutrition supplementation alongside medication purchases.
Industry Challenges
- Cold-press technician scarcity:Skilled operators trained in boutique startup environments command premium wages, constraining scaled facility staffing across Southeast Asian manufacturing hubs.
- Shelf-life extension claim validation:Tightening additive regulations in Australia and New Zealand require clinical substantiation timelines that delay new product launches by 12-18 months.
- Legacy thermal asset stranding:Existing pasteurization infrastructure faces accelerated obsolescence as retail buyers prioritize HPP-processed inventory, forcing write-down decisions for mid-cap processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Fruits and Vegetables Juice Market |
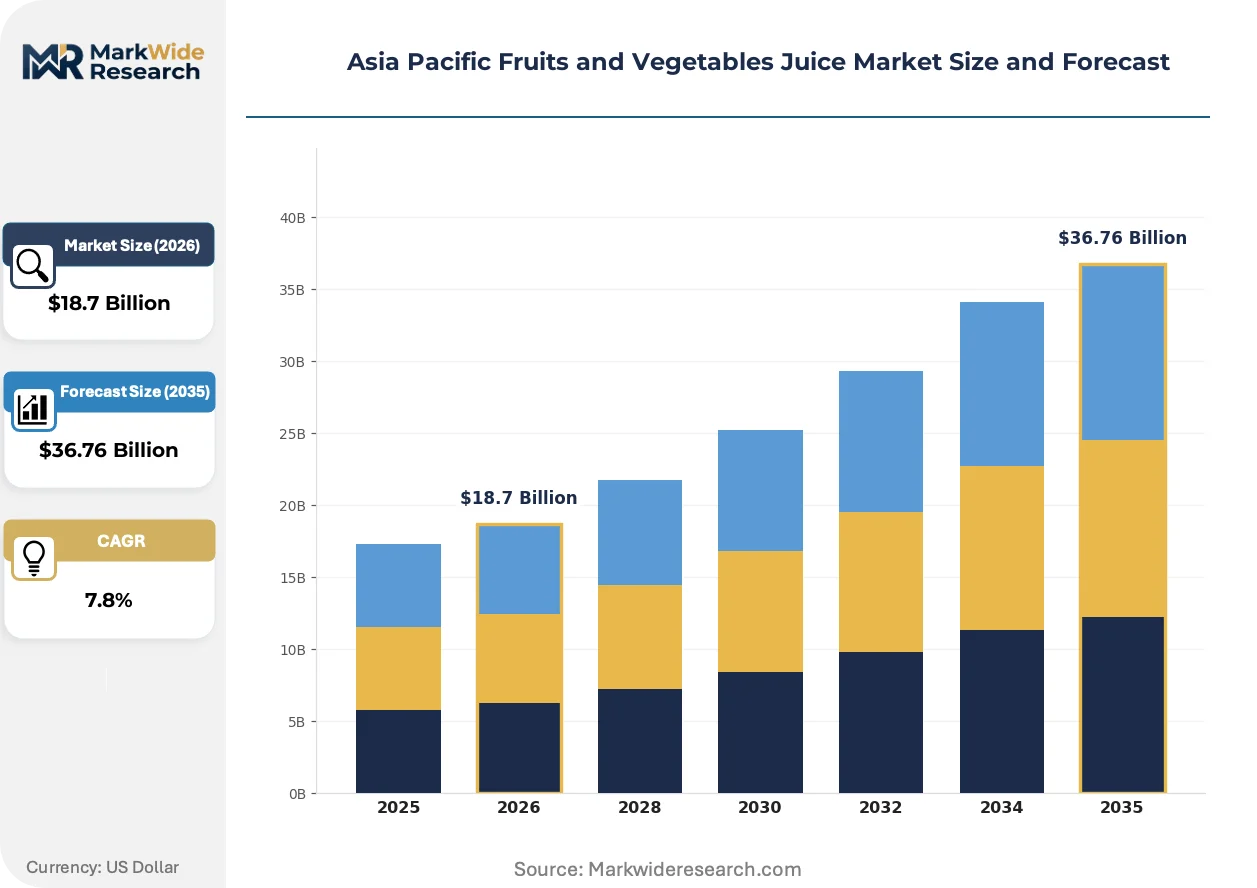
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 100% Juice, Juice Blend, Concentrate, Nectars Ingredient Type: Citrus, Berries, Roots, Vegetables Packaging Type: Bottles, Cartons, Pouches, Cans Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | Dabur India Ltd, Fresh Del Monte Produce Incorporated, PepsiCo Inc, Patanjali Ayurved Limited, Raw Pressery Private Limited, The Coca-Cola Company, ITC Limited, Citropak Limited, Huiyuan Group Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Fruits and Vegetables Juice Market Strategic Shifts
Processing technology convergence and regulatory disclosure tightening are rewriting competitive rules across Asia Pacific juice manufacturing, compressing timelines between innovation and commoditization.
High-pressure processing equipment is displacing conventional thermal pasteurization lines in premium manufacturing facilities. Tier-one Chinese supermarkets and Indian modern trade chains are specifying HPP certification for shelf placement. This displacement is collapsing the premium shelf-life gap between chilled and ambient-stable products.
China's SAMR enforcement of GB standards for juice content declarations is eliminating dilution practices in concentrate-to-ready-to-drink conversions. Manufacturers must now maintain minimum fruit content thresholds that raise input costs. Domestic brands with backward integration into orchard operations are absorbing this compression better than import-reliant competitors.
Urban Indian consumers are unbundling juice purchases from grocery trips, adopting subscription direct-to-home models for cold-pressed deliveries. Metro corridor households in Bangalore and Hyderabad prioritize convenience and freshness verification over retail browsing. This channel rotation is forcing traditional distributors to develop last-mile chilled capabilities or cede premium volume to platform-native brands.
Asia Pacific Fruits and Vegetables Juice Market Segmentation
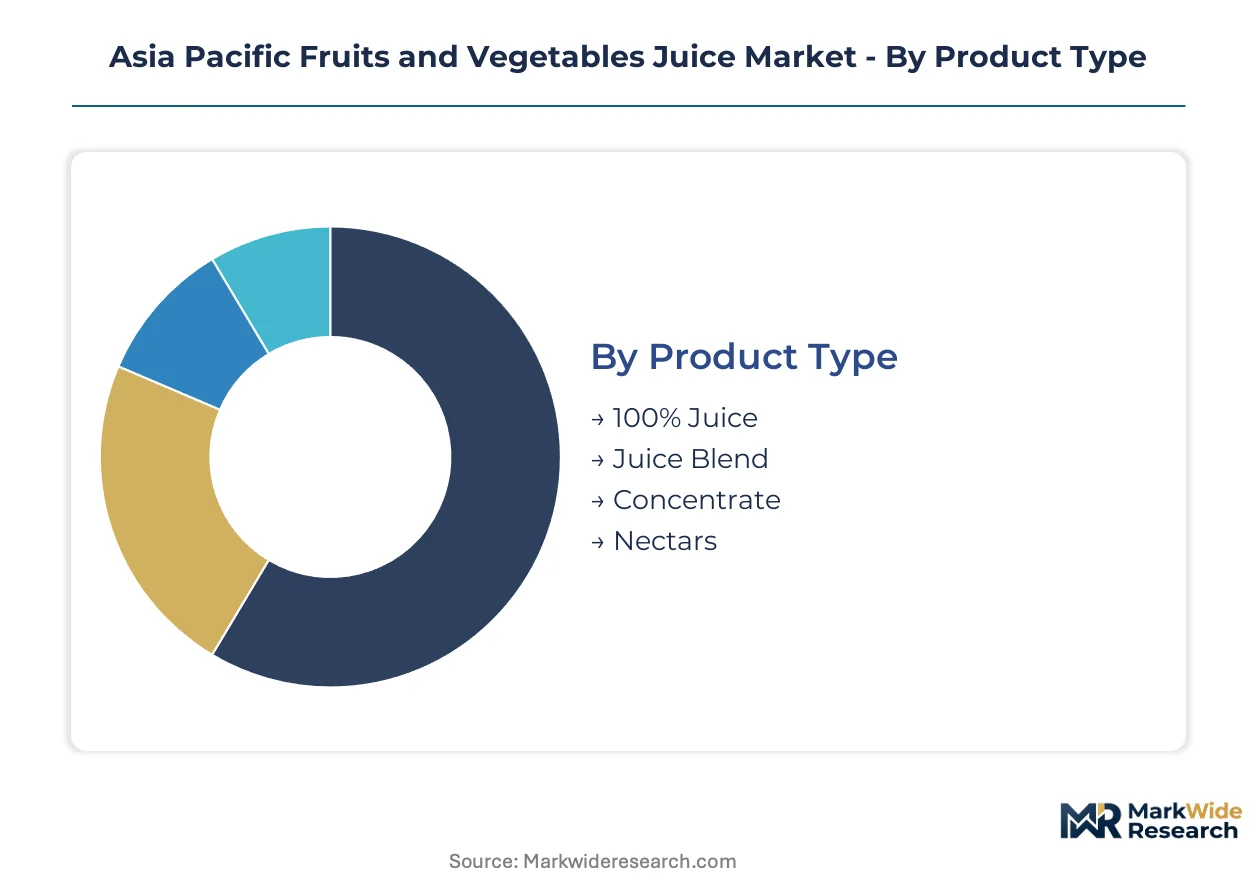
Asia Pacific juice manufacturers configure product portfolios around four intersecting dimensions that determine margin capture, regulatory exposure, and channel access. Each segmentation layer carries distinct compliance burdens and pricing power dynamics shaped by local enforcement patterns.
Product Type:
China's SAMR enforces GB standards that differentiate juice categories by minimum fruit content thresholds, creating compliance cost stratification across manufacturing footprints.
- Juice Blend:Formulations combining multiple fruit sources with water and permitted additives dominate volume throughput across Southeast Asian manufacturing. Demand concentrates in Indonesia and Vietnam where tropical flavor customization supports local palate preferences and cost flexibility in procurement.
- 100% Juice:Pure fruit extracts without added water or preservatives command premium shelf positioning in Shanghai and Beijing tier-one supermarkets. China's GB standards mandate stricter labeling and content verification, advantaging domestic producers with captive orchard supply.
- Concentrate:Reduced-water extracts for reconstitution face tightening dilution restrictions under SAMR enforcement.
- Nectars:Lower fruit-content beverages with added sweeteners serve price-sensitive segments in India's rural markets.
Juice Blend handles the majority of throughput; 100% Juice is expanding most quickly on share.
Ingredient Type:
Input sourcing geography determines margin volatility, with climate-exposed harvests in Thailand and Vietnam squeezing blend-dependent producers.
- Citrus:Orange and lemon derivatives anchor fortification portfolios targeting pharmacy retail channels in India. FSSAI microbial limit enforcement shapes pasteurization requirements for citrus-based products entering modern trade.
- Berries:Acai, blueberry, and cranberry extracts command antioxidant positioning premiums in Australian and New Zealand premium channels. TGA-influenced nutrient profiling criteria constrain health claim substantiation for berry-fortified lines.
- Roots:Carrot, beet, and turmeric extracts align with Ayurvedic functional positioning under India's FSSAI traditional medicine familiarity.
- Vegetables:Tomato, spinach, and mixed green formulations serve savory juice niches in Japan's health-conscious urban corridors.
Citrus handles the majority of throughput; Berries are gaining share fastest.
Packaging Type:
Cold chain infrastructure maturity dictates viable formats, with refrigerated logistics gaps limiting premium chilled formats outside eastern seaboard clusters.
- Pouches:Flexible unit-dose packaging captures first-time juice consumers in Maharashtra and Uttar Pradesh village retail through price points below bottled alternatives. India's fragmented rural distribution favors lightweight, break-resistant formats.
- Bottles:PET and glass containers dominate modern trade shelf presence in China's tier-one supermarkets. HPP-processed chilled juices require bottle formats that maintain seal integrity through high-pressure pasteurization cycles.
- Cartons:Aseptic brick packs serve ambient-stable juice distribution in Southeast Asian convenience channels with limited refrigeration.
- Cans:Aluminum formats capture on-the-go consumption in Japan's vending machine infrastructure and Australia's outdoor recreation segments.
Bottles handle the majority of throughput; Pouches show the steepest expansion trajectory.
Distribution Channel:
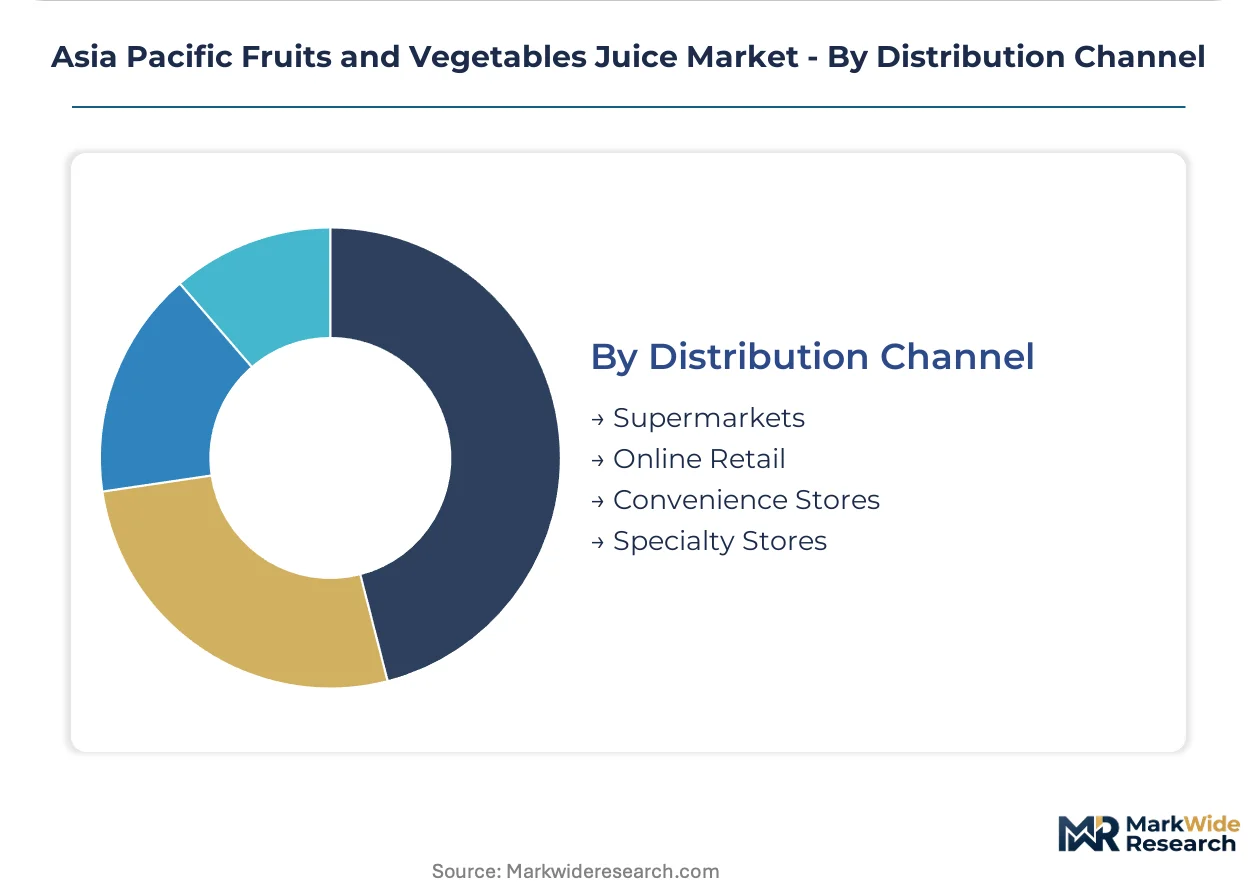
Channel selection determines regulatory exposure and margin structure, with pharmacy retail requiring distinct FSSAI compliance pathways in India.
- Supermarkets:Tier-one Chinese chains and Indian modern trade specify HPP certification and clean-label positioning for shelf placement. SAMR and FSSAI labeling mandates reshape supplier qualification requirements.
- Online Retail:Direct-to-home subscription models for cold-pressed deliveries are unbundling juice purchases from grocery trips in Bangalore and Hyderabad metro corridors. Last-mile chilled capabilities separate platform-native brands from traditional distributors.
- Convenience Stores:7-Eleven and FamilyMart networks across Thailand, Philippines, and Indonesia prioritize ambient-stable, long-shelf-life formats.
- Specialty Stores:Organic and health-focused retailers in Australia and New Zealand enforce additive-free standards aligned with FSANZ nutrient profiling.
Supermarkets handle the majority of throughput; Online Retail is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards enforcement creates the regulatory anchor for Asia Pacific juice manufacturing, with China's eastern seaboard cities generating the dominant demand concentration across the forecast window.
China
Shanghai and Beijing tier-one supermarkets pull HPP-certified chilled juices into daily consumption routines. SAMR's juice content declaration mandates eliminate dilution practices in concentrate conversions. Yangtze River Delta manufacturing clusters absorb input cost compression through captive orchard backward integration.
India
Mumbai and Bangalore metro corridors drive subscription direct-to-home models for cold-pressed deliveries. FSSAI preservative labeling mandates accelerate clean-label reformulation investments. Maharashtra and Uttar Pradesh village retail channels capture first-time consumers through unit-dose pouch affordability.
Japan
Tokyo and Osaka urban corridors sustain savory vegetable juice niches in health-conscious consumption patterns. METI efficiency standards shape processing equipment procurement decisions. Kanto region vending machine infrastructure anchors aluminum can format penetration for on-the-go consumption.
Australia
Sydney and Melbourne premium channels enforce additive-free standards aligned with FSANZ nutrient profiling criteria. TGA-influenced health claim substantiation requirements constrain berry-fortified line launches. New South Wales and Victoria distribution networks prioritize clinical validation timelines for shelf-life extension claims.
Indonesia
Jakarta and Surabaya urban millennial clusters expand functional beverage adoption beyond traditional refreshment occasions. Convenience channel dominance through 7-Eleven and FamilyMart networks prioritizes ambient-stable formats. Java Island manufacturing hubs face tropical fruit input volatility from climate-exposed Thai and Vietnamese harvests.
Asia Pacific Fruits and Vegetables Juice Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates leveraging bottling infrastructure against Ayurvedic-rooted domestic manufacturers. The structure stratifies around three archetypes: global FMCG majors with distribution scale, traditional medicine heritage players with herb sourcing networks, and platform-native cold-press specialists with direct-to-home capabilities. Competitive moves concentrate on pharmacy channel anchoring for fortified portfolios and rural pouch expansion for price-sensitive penetration.
Among India-based heritage manufacturers, Dabur India Ltd and Patanjali Ayurved Limited occupy positions anchored by traditional medicine familiarity under FSSAI frameworks. PepsiCo Inc and The Coca-Cola Company represent the multinational FMCG tier, with their scale-driven infrastructure shaping Southeast Asian convenience channel dynamics. Raw Pressery Private Limited exemplifies the platform-native specialist archetype, sitting within the subscription direct-to-home vector that is unbundling juice purchases from grocery trips in Bangalore and Hyderabad metro corridors.
| Leading Market Players |
|---|
| Dabur India Ltd |
| Fresh Del Monte Produce Incorporated |
| PepsiCo Inc |
| Patanjali Ayurved Limited |
| Raw Pressery Private Limited |
| The Coca-Cola Company |
| ITC Limited |
| Citropak Limited |
| Huiyuan Group Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Scale economies in HPP equipment deployment across Yangtze River Delta manufacturing clusters compress per-unit processing costs for certified chilled juices while simultaneously raising price floors for thermal-processed alternatives locked out of tier-one supermarket placement. This capacity-utilization dynamic concentrates margin capture among operators with backward integration into orchard supply, forcing import-reliant competitors into lower-price nectars and juice blends.
Pricing Analysis
Price spreads between Shanghai tier-one supermarkets and Maharashtra village retail exceed threefold across equivalent juice categories, with HPP certification, cold-chain integrity, and brand positioning as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels separates subscription cold-pressed deliveries from modern trade bottled formats and rural pouch units. Pricing pressure stems from climate-induced tropical fruit input volatility squeezing blend-dependent producers. Pharmacy channel buyers show lowest price sensitivity; rural first-time consumers exhibit highest elasticity.
Supply Chain Analysis
Strategic stockpiling of mango, pineapple, and passion fruit concentrates during harvest windows dominates procurement strategy, with just-in-time fresh-fruit processing limited to HPP-certified facilities with verified cold-chain throughput. Thailand, Vietnam, and India's Maharashtra orchards anchor raw material sourcing for tropical formulations. Supply chain risk centers on single-source vulnerability for cold-press technician talent pools across Southeast Asian manufacturing hubs. Distribution runs through PepsiCo and Coca-Cola bottling infrastructure for convenience channel penetration, with platform-native brands building captive last-mile chilled capabilities for direct-to-home subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from functional beverage categories—kombucha, probiotic drinks, and plant-based milks—pulling health-conscious millennial spend away from traditional juice occasions. Defense requires anchoring in validated health positioning and channel control.
For Market Incumbents: Secure pharmacy retail anchoring for fortified portfolios under FSSAI traditional medicine frameworks, locking in validated health positioning that functional substitutes cannot replicate. Capture rural pouch expansion in Maharashtra and Uttar Pradesh through unit-dose affordability below bottled alternatives, preempting price-war erosion from regional blend manufacturers. Cold-press technician scarcity across Southeast Asian hubs demands accelerated training program investment or wage-premium absorption to maintain HPP throughput. For New Entrants and Emerging Players: Differentiate on Ayurvedic functional fortification—ashwagandha, turmeric, amla—leveraging FSSAI regulatory familiarity that foreign competitors lack. Target subscription direct-to-home models in Bangalore and Hyderabad metro corridors, where platform-native brands unbundle juice purchases from grocery trips. Penetrate specialty store channels in Australia and New Zealand through additive-free positioning aligned with FSANZ nutrient profiling criteria. For Investors and Strategic Acquirers: Platform-native cold-press specialists with direct-to-home capabilities and captive last-mile chilled infrastructure represent the highest-conviction acquisition archetype, capturing channel rotation away from traditional distributors. Long-term viability hinges on substitution defense through health-claim substantiation and regulatory moat maintenance. Watch for FSSAI enforcement intensity against shelf-life extension claims as the inflection signal—tightening validation timelines would accelerate consolidation toward scaled manufacturers with clinical substantiation resources.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Certification Investment | SAMR and tier-one supermarket specifications lock in premium shelf placement for certified operators. |
| Backward Integration into Orchard Supply | Captive mango and pineapple sourcing absorbs GB standards input cost compression better than import-reliant competitors. |
| Pharmacy Channel Partnership | India's chemist retail networks offer validated health positioning inaccessible to convenience-store functional beverages. |
| Rural Pouch Distribution Buildout | Unit-dose affordability below bottled alternatives captures first-time consumers in Maharashtra and Uttar Pradesh village retail. |
| Cold-Press Technician Training Program | Scarcity of skilled HPP operators across Southeast Asian manufacturing hubs constrains scaled facility staffing. |
Study Parameters
Cross-validation between executive interviews and customs-derived trade data anchors the qualitative findings. Primary fieldwork engaged cold-press facility operators, FSSAI compliance officers, modern trade category buyers, Ayurvedic ingredient sourcing managers, and pharmacy retail procurement heads. Secondary sources included SAMR GB standards filings, FSSAI preservative labeling directives, FSANZ nutrient profiling criteria, Nielsen retail audit data for tier-one Chinese supermarkets, and India customs records for tropical fruit concentrate imports. Bottom-up volume triangulation against top-down macroeconomic drivers tested forecast robustness.
Sensitivity analysis across input cost scenarios and regulatory enforcement intensity brackets shaped the projection framework. Segmentation dimensions modeled include product type, ingredient source, packaging format, distribution channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical penetration patterns and policy announcement timelines. Forecast inputs incorporated HPP equipment installation rates, cold-chain infrastructure buildout in tier-three Chinese cities, and FSSAI clean-label reformulation investment cycles.
The analysis sits within stated boundaries; outcomes outside sustained urban millennial health-consciousness, intact cold-chain integrity, and stable tropical fruit harvest conditions would require recalibration. Forecasts reflect documented assumptions about SAMR enforcement consistency and FSSAI traditional medicine regulatory familiarity. Revision becomes warranted when climate-induced yield compression crosses thresholds that force widespread input substitution or when HPP technician wage premiums exceed facility-level absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
India Bottled Water Market
Beverages
Bottled Deep Ocean Water Market
Beverages
United States Recovery Drinks Market
Beverages
Powdered Beverages Market
Beverages
Japan Energy Drink Market
Beverages
Recovery Drinks Market
Beverages
Water Bottle Market
Beverages
Adaptogenic Beverages Market
Beverages
Global Soda Maker Market
Beverages
Nitro-Infused Cola Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Aloe Vera Juice Market
Beverages
Global Squash Drinks Market
Beverages
Yerba Mate Market
Beverages
Crystal Boba Market
Beverages
Italy Bottled Water Market