
 Neohesperidine DC Market | 2026-2036
Neohesperidine DC Market Size, Share, and Industry Trends Forecast 2026-2036
Neohesperidine DC Market Foresight
Direct procurement channels between citrus extract refiners and flavor houses is reconfiguring how Neohesperidine DC reaches end-formulators. Merck KGaA leverages its pharmaceutical-grade purification infrastructure to supply high-purity isolates into European nutraceutical pipelines. Layn Corp anchors Asian supply through backward integration into citrus peel sourcing networks. Bordas Distillations Chinchurreta competes from Spain with specialized extraction expertise honed across decades of botanical processing.
Neohesperidine DC is a flavanone glycoside derived from bitter orange peel, typically refined to purity thresholds exceeding ninety percent for food-grade commercial use; it functions primarily as a sweetness enhancer and flavor modifier in reduced-sugar formulations. Concentrates dominate current volume flows due to their compatibility with industrial beverage batching systems, while liquid extracts represent the fastest-growing format as pharmaceutical tablet coating applications expand. The Food & Beverage end-use segment commands the largest margin pool, though Nutraceuticals is displacing traditional channels as dietary supplement brands seek GRAS-affirmed sweetening alternatives.
EFSA novel food evaluations and REACH chemical safety registrations govern European market access, with FDA GRAS self-affirmation pathways shaping United States commercialization timelines. EMA pharmaceutical excipient standards and USP-NF monograph compliance create dual certification burdens for suppliers targeting drug applications. Stakeholders must monitor pending EFSA re-evaluations of neohesperidin-derived additives and pre-position supply chain documentation for potential purity threshold adjustments.
Market Dynamics
REACH chemical safety registrations and EFSA novel food evaluations are compressing supplier margins while concentrating procurement among vertically integrated citrus extract refiners capable of pharmaceutical-grade purification.
Growth Catalysts
- Clean-label beverage reformulation:Food-grade Neohesperidine DC isolates enable 30-50% sugar reduction in carbonated soft drinks without synthetic aftertaste, pulling demand from Germany and Spain.
- REACH compliance infrastructure:Suppliers with pre-registered dossiers and toxicology data packages secure preferred-supplier status with European flavor houses accelerating formulation timelines.
- Pharmaceutical excipient qualification:USP-NF monograph compliance opens tablet coating and oral disintegrating film applications previously served by artificial sweeteners.
Market Restraints
- Bitter orange peel supply concentration:Spanish and Italian citrus processors control 60%+ of raw material flows, creating price volatility during adverse harvests.
- Dual certification burden:EMA pharmaceutical excipient standards layered atop food-grade purity requirements extend qualification timelines for cross-segment suppliers.
- Stevia glycoside substitution:Reb M and Reb D isolates from fermentation-derived sources capture share in mid-intensity sweetening applications.
Strategic Opportunities
- Nutraceutical pipeline expansion:GRAS self-affirmation pathways in the United States enable rapid entry into protein powder and gummy supplement formats.
- Liquid extract format growth:Pharmaceutical tablet coating applications favor liquid concentrates over powder isolates, rewarding suppliers with spray-drying capabilities.
- Asian backward integration:Citrus peel sourcing networks in China and Southeast Asia remain underdeveloped relative to extraction capacity, creating acquisition targets.
Industry Challenges
- Analytical chemistry talent scarcity:Flavanone glycoside quantification and chiral purity verification require specialized HPLC-MS expertise concentrated in pharmaceutical hubs.
- Legacy batch system integration:Beverage manufacturers running continuous liquid processing lines face reformulation complexity when incorporating high-intensity sweetener micro-dosing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neohesperidine DC Market |
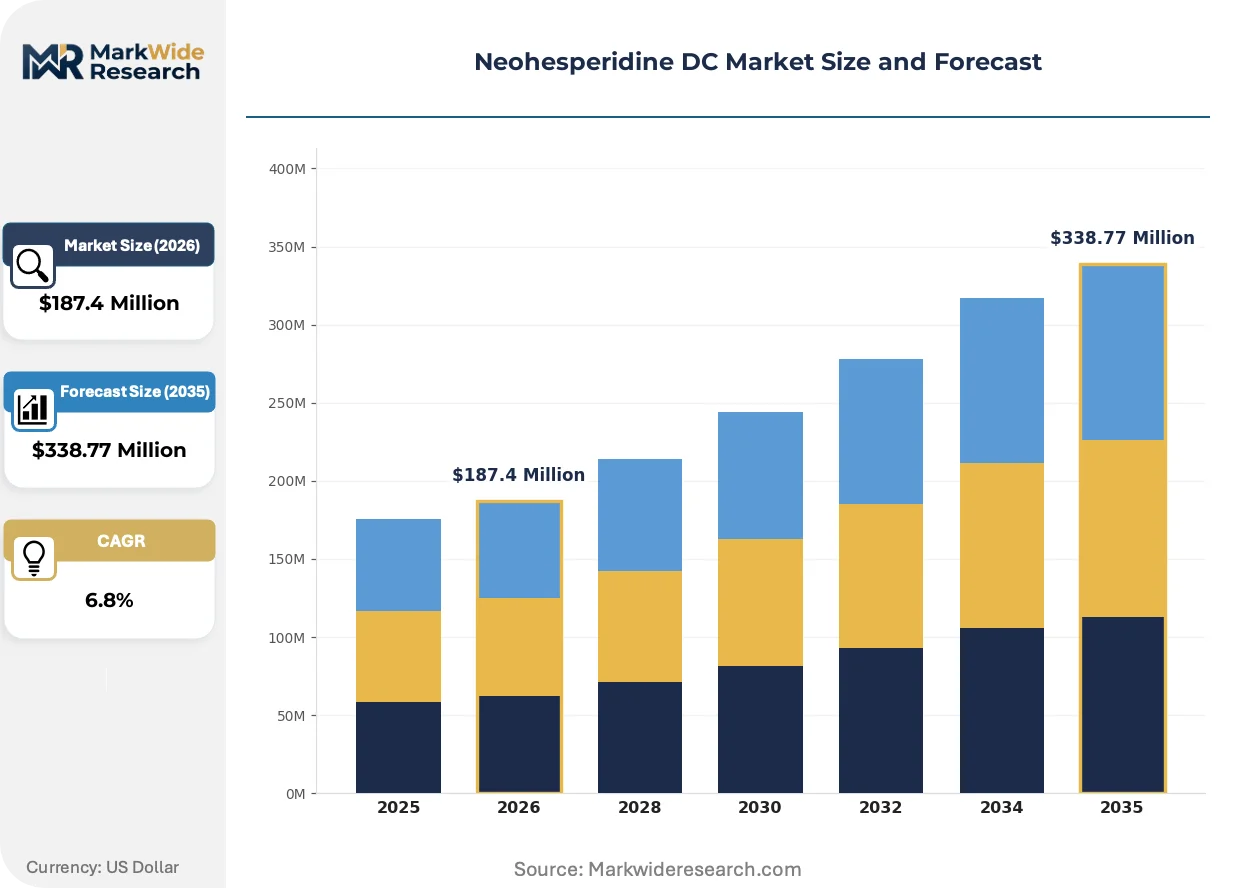
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Powders, Liquid Extracts, Granules End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Natural, Synthetic, Blended, Isolated Application: Flavoring Agents, Sweeteners, Food Preservatives, Dietary Supplements |
| Companies Covered | Changsha Sunnycare, Gelfix, Kang Biotech, Bordas Distillations Chinchurreta, Nutrafur S.A., Okay Pharmaceutical, Layn Corp, Golden Health, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neohesperidine DC Market Shifts & Advancements
Membrane filtration and simulated moving bed chromatography are replacing solvent-intensive extraction methods, compressing capital recovery periods for citrus refiners while tightening purity thresholds.
Continuous counter-current chromatography systems are rendering obsolete traditional solvent extraction trains dependent on ethyl acetate and hexane partitioning. Spanish botanical processors deploy these systems to achieve 95%+ purity in single-pass operations. The technology is rendering obsolete multi-stage crystallization steps that previously dominated capex allocation.
EFSA's pending re-evaluation of neohesperidin-derived food additives is forcing suppliers to pre-position enhanced toxicology dossiers. The industrial consequence is a bifurcation between dossier-ready incumbents and second-tier suppliers facing 18-24 month qualification gaps. Nutraceutical brands sourcing from European flavor houses are most affected, accelerating dual-sourcing strategies.
Direct procurement contracts between citrus refiners and end-formulators are compressing traditional distribution through regional ingredient distributors. Beverage manufacturers in Germany and the United States now negotiate multi-year offtake agreements specifying harvest-origin traceability. This channel disintermediation is most visible in reduced-sugar carbonated soft drink launches where formulation stability requires supplier-facilitated technical service.
Neohesperidine DC Market Segmentation
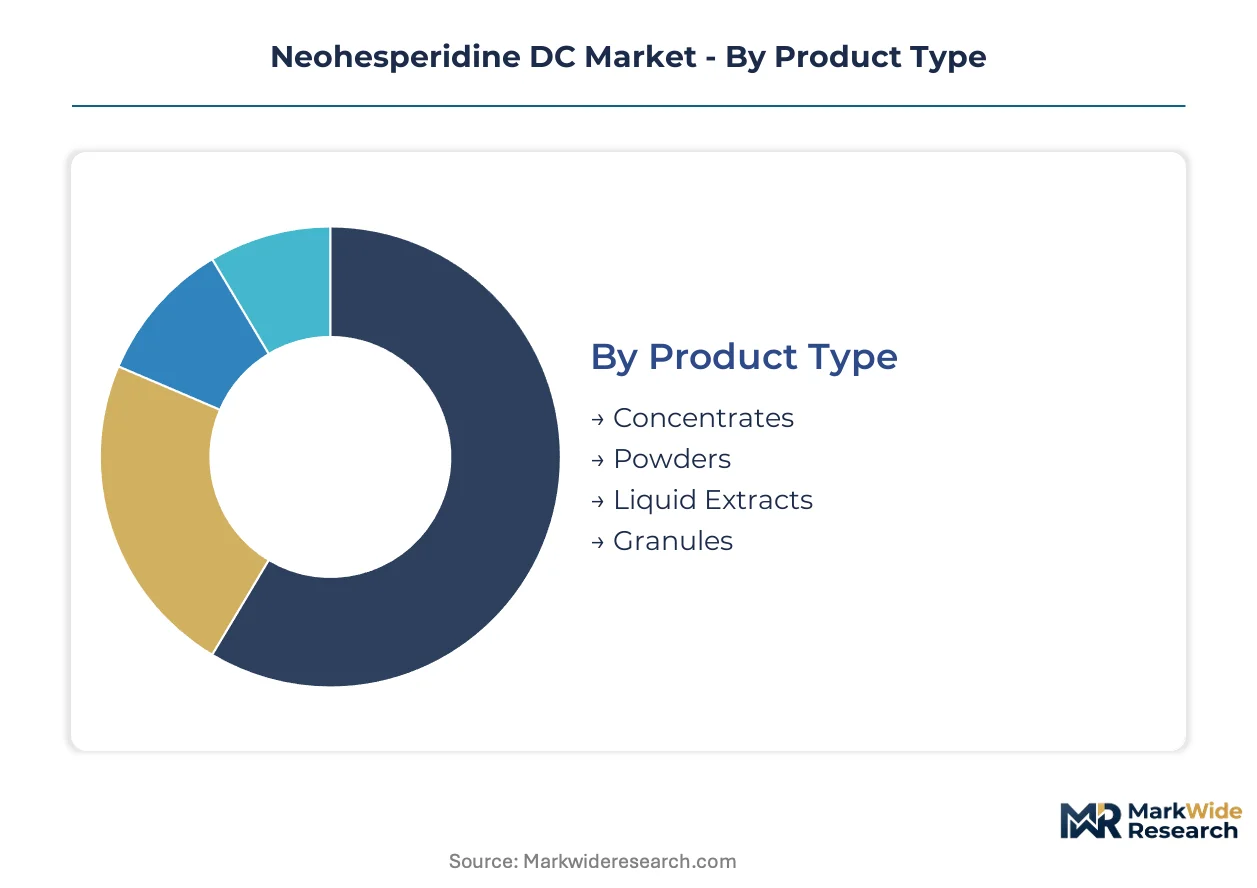
Neohesperidine DC procurement patterns diverge sharply across product formats and end-use specifications, with pharmaceutical-grade isolates demanding intensive technical service support while beverage concentrates prioritize logistics reliability. Suppliers must calibrate after-sales infrastructure to match the qualification complexity inherent in each segment tier.
Product Type:
After-sales-service intensity escalates with purity thresholds, as pharmaceutical-grade concentrates require ongoing analytical support and reformulation troubleshooting that commodity powders do not.
- Concentrates:Standardized flavanone glycoside solutions at 90-95% purity serve industrial beverage batching systems in Germany and Spain. European flavor houses demand supplier-facilitated technical service for formulation stability in reduced-sugar carbonated soft drinks.
- Liquid Extracts:Spray-dried or solvent-based solutions enable precise micro-dosing in pharmaceutical tablet coatings. USP-NF monograph compliance opens oral disintegrating film applications previously served by artificial sweeteners, with EMA excipient standards creating dual certification burdens.
- Powders:Crystalline isolates suit dry-blend nutraceutical applications.
- Granules:Agglomerated formats improve flowability for high-speed packaging lines.
By volume, Concentrates leads. By growth pace, Liquid Extracts is ahead.
End Use Industry:
Cost-tier stratification separates commodity food-grade supply from premium pharmaceutical and nutraceutical channels where certification investments command price premiums.
- Food & Beverage:Clean-label reformulation in carbonated soft drinks and reduced-sugar beverages drives procurement from German and Spanish manufacturers. REACH-registered suppliers secure preferred status with flavor houses accelerating launch timelines.
- Nutraceuticals:Dietary supplement brands in the United States leverage FDA GRAS self-affirmation pathways for rapid entry into protein powders and gummy formats. GRAS-affirmed sweetening alternatives displace traditional channels as brands seek regulatory certainty.
- Pharmaceuticals:Tablet coating and excipient applications require USP-NF and EMA compliance.
- Cosmetics:Flavor masking in oral care and personal care products represents niche demand.
Food & Beverage captures the largest margin pool. Nutraceuticals climbs fastest as supplement brands diversify sweetening portfolios.
Form:
Application specificity determines sourcing strategy, with natural isolates commanding harvest-origin traceability that synthetic alternatives bypass.
- Natural:Bitter orange peel-derived flavanone glycosides refined to 90%+ purity dominate European clean-label procurement. Spanish and Italian citrus processors control raw material flows, creating price volatility during adverse harvests.
- Isolated:Single-compound specifications enable precise dosing in pharmaceutical applications. EFSA novel food evaluations and REACH registrations compress margins while concentrating supply among dossier-ready incumbents.
- Synthetic:Fermentation-derived or chemically synthesized alternatives offer supply security.
- Blended:Multi-component formulations balance cost and performance in mid-tier applications.
Natural isolates dominate volume. Isolated forms expand most quickly in pharmaceutical qualification pipelines.
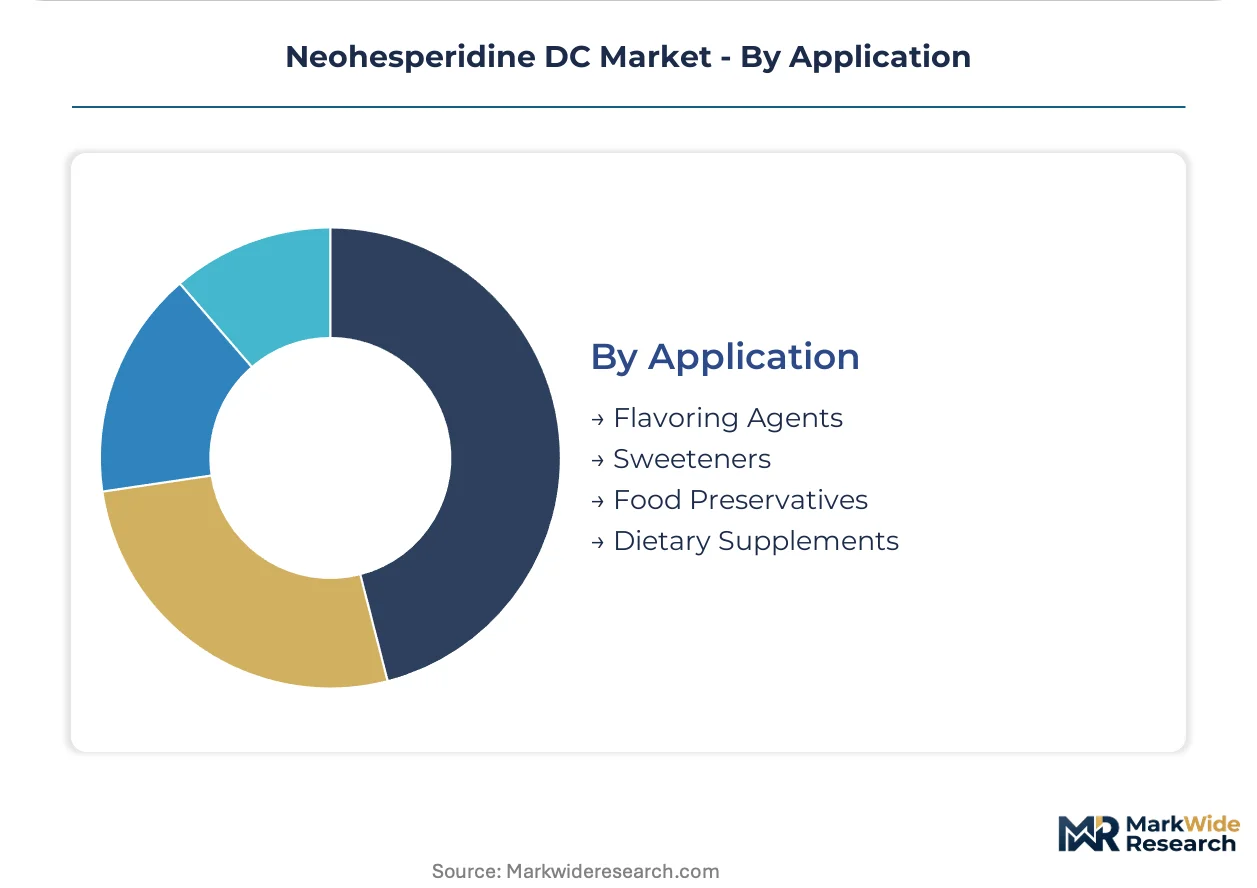
Application:
Customer-type differentiation separates industrial flavor houses seeking sweetness enhancement from finished goods manufacturers requiring end-label sweetener positioning.
- Sweeteners:High-intensity sweetness enhancement enables 30-50% sugar reduction without synthetic aftertaste. Beverage manufacturers in Germany and the United States negotiate multi-year offtake agreements specifying harvest-origin traceability.
- Flavoring Agents:Bitter taste masking and flavor modulation support reduced-sodium and reduced-sugar formulations. Direct procurement contracts between citrus refiners and end-formulators compress traditional distribution channels.
- Dietary Supplements:Palatability improvement in protein powders and gummies.
- Food Preservatives:Antimicrobial synergy in select applications remains underdeveloped.
Sweeteners leads by volume. Flavoring Agents gains share fastest as sodium reduction trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registrations and FDA GRAS pathways are redrawing procurement geography for high-intensity sweeteners. Suppliers now cluster near regulatory hubs where dossier preparation accelerates market access timelines.
Germany
Clean-label beverage reformulation budgets in Cologne and Hamburg are pulling pharmaceutical-grade Neohesperidine DC through flavor houses. ECHA REACH compliance infrastructure favors dossier-ready suppliers with pre-registered toxicology packages. The Rhine-Ruhr industrial corridor hosts concentrated technical service teams supporting reduced-sugar carbonated soft drink launches.
United States
GRAS self-affirmation pathways enable rapid nutraceutical entry for protein powders and gummy supplements. FDA guidance on novel food additives shapes commercialization timelines for dietary supplement brands. Chicago and New Jersey flavor clusters negotiate multi-year offtake agreements specifying harvest-origin traceability from Spanish citrus processors.
Spain
Seville and Valencia control bitter orange peel supply networks supplying 60% of European raw material flows. EFSA novel food evaluations compress margins while concentrating procurement among vertically integrated extract refiners. Andalusian botanical processors deploy continuous counter-current chromatography achieving 95% purity in single-pass operations.
China
Layn Corp anchors Asian supply through backward integration into citrus peel sourcing networks in Hunan and Sichuan provinces. SAMR food additive standards and GB compliance requirements shape import substitution strategies. Shanghai and Guangzhou extraction capacity outpaces domestic raw material development, creating acquisition targets in Southeast Asian peel supply.
India
FSSAI food safety regulations and emerging clean-label demand in Mumbai and Bangalore are opening formulation trials for natural high-intensity sweeteners. CDSCO pharmaceutical excipient standards create dual certification pathways for suppliers targeting tablet coating applications. Maharashtra and Gujarat nutraceutical manufacturers seek GRAS-affirmed alternatives to synthetic sweeteners.
Neohesperidine DC Market Competitive Landscape
On the supply side, the industry is bifurcating between pharmaceutical-grade purification specialists and commodity citrus extract processors. Tier-one suppliers command preferred status with European flavor houses through REACH-registered dossiers and toxicology data packages. Three strategic archetypes dominate: vertically integrated botanical processors with captive peel supply, pharmaceutical-grade refiners leveraging existing purification infrastructure, and Asian extract houses scaling through backward integration. Capacity expansion and direct procurement contracting represent the dominant competitive vectors as beverage manufacturers seek harvest-origin traceability.
Among European pharmaceutical-grade suppliers, Merck KGaA exemplifies the infrastructure-leveraging archetype through its existing purification capabilities. Bordas Distillations Chinchurreta occupies a position within the specialized botanical processing tier rooted in decades of Spanish extraction expertise. Layn Corp represents the Asian scale-driven model, anchoring regional supply through upstream control over citrus peel sourcing networks.
| Leading Market Players |
|---|
| Changsha Sunnycare |
| Gelfix |
| Kang Biotech |
| Bordas Distillations Chinchurreta |
| Nutrafur S.A. |
| Okay Pharmaceutical |
| Layn Corp |
| Golden Health |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Spanish and Italian citrus processors command 60% of bitter orange peel flows, anchoring margin capture in pharmaceutical-grade purification tiers where REACH-registered dossiers command premium positioning. Downstream pricing power concentrates among flavor houses and nutraceutical brands seeking harvest-origin traceability, while commodity-grade concentrates face cost compression from fermentation-derived substitutes.
Pricing Analysis
Volume-discount tiering structures separate multi-year offtake agreements from spot-market transactions. Three-tier pricing stratifies across pharmaceutical-grade isolates, food-grade concentrates, and commodity powders, with EMA and USP-NF certification premiums widening spreads. Cost compression in standard-grade concentrates intensifies as Reb M and Reb D stevia glycosides capture mid-intensity applications. Beverage manufacturers running continuous processing lines exhibit highest price sensitivity; pharmaceutical excipient buyers prioritize purity guarantees over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure procurement between Spanish citrus refiners and German flavor houses. Raw material flows draw from Seville, Valencia, and Hunan province networks, with extraction capacity anchored in Andalusia and Sichuan. Single-source vulnerability concentrates in Spanish peel supply during adverse harvests. Distribution runs through direct procurement contracts that disintermediate regional ingredient distributors, particularly for reduced-sugar carbonated soft drink formulations requiring supplier-facilitated technical service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where REACH-registered dossiers and EFSA toxicology packages create 18-24 month qualification gaps that shield incumbents from rapid competitive entry.
For Market Incumbents: Insulate market position by deepening backward integration into Southeast Asian citrus peel networks and pre-positioning enhanced toxicology dossiers ahead of pending EFSA re-evaluations. Stevia glycoside substitution threats demand counter-positioning through sweetness-enhancer technical service capabilities that fermentation-derived alternatives cannot replicate. Capacity expansion in pharmaceutical-grade liquid extract formats captures tablet coating application growth. For New Entrants and Emerging Players: Build out presence in Indian nutraceutical channels where FSSAI regulations and emerging clean-label demand create lower entry barriers than REACH-governed European markets. Protein powder and gummy supplement formats offer the most penetrable white space, with GRAS self-affirmation pathways enabling rapid commercialization. Partner with established flavor houses for technical service coverage rather than building independent reformulation support infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade purification segments as continuous counter-current chromatography systems replace solvent extraction trains. Long-term viability favors dossier-ready incumbents with captive peel supply and multi-regional certification infrastructure. Acquisition targets include Asian extract houses with underdeveloped upstream citrus sourcing. Monitor EFSA re-evaluation timelines as the critical inflection signal for qualification-gap widening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Peel Supply | Captive raw material access insulates Spanish and Italian processors from harvest volatility and price spikes. |
| Continuous Counter-Current Chromatography Deployment | Single-pass 95% purity achievement compresses capital recovery periods for Andalusian botanical processors. |
| Dual Certification Investment (USP-NF and EMA) | Pharmaceutical excipient qualification opens tablet coating applications previously served by artificial sweeteners. |
| Direct Procurement Contracting | Multi-year offtake agreements with harvest-origin traceability compress traditional distribution margins. |
| Liquid Extract Format Expansion | Spray-drying capabilities capture pharmaceutical tablet coating demand displacing powder isolates. |
Research Methodology
A standing panel of citrus extract refinery technical directors, European flavor house procurement leads, pharmaceutical excipient qualification managers, and dietary supplement brand formulators provided ongoing calibration across the research cycle. Primary interview insights combined with secondary validation from EFSA novel food evaluation databases, REACH registration dossiers, FDA GRAS notification filings, and customs trade flow records. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing applied to regulatory approval timelines and raw material supply disruptions. Segmentation dimensions modeled include product format tier, end-use industry vertical, certification grade level, and regional regulatory cluster. CAGRs derived from historical volume trajectories and application penetration curves, with specific inputs from beverage reformulation intensity indices and pharmaceutical excipient qualification pipeline data.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian extract houses or accelerated EFSA purity threshold adjustments would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Potassium Lactate Market
Food Additives and Ingredients
Powdered Fats Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Lactoperoxidase Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
United States Anti-Caking Market